
 Platelet Shaker Market | 2026-2036
Platelet Shaker Market Size, Share, and Industry Trends Forecast 2026-2036
Platelet Shaker Market Outlook
The capital-intensity divergence between automated digital-control specialists and mechanical-only fabricators is rotating competitive investment toward temperature-regulated platforms. Thermo Fisher Scientific leverages its life-sciences instrumentation ecosystem to sustain premium positioning across hospital laboratories. Greiner Bio-One International GmbH anchors European demand through blood-banking consumables integration. Haemonetics Corporation dominates transfusion workflow systems, extending its reach into agitation equipment through channel control.
Platelet shakers are electromechanical devices that maintain viable platelet concentrates through continuous gentle agitation at controlled speeds, typically operating between 60 and 70 revolutions per minute to prevent aggregation while preserving functional integrity. Their primary commercial purpose centers on blood-bank inventory management and cellular therapy manufacturing, where thermal stability and motion uniformity directly determine shelf-life extension and clinical utility. Benchtop shakers lead hospital laboratory procurement due to space constraints and moderate throughput requirements, while multiple-plate configurations capture the fastest growth trajectory as large-scale blood processors consolidate processing lines. Floor-model shakers occupy mature replacement cycles in established regional blood centers, with margin pools concentrating in digital-control and temperature-regulation technology modules.
The US FDA enforces platelet storage and agitation standards through blood-banking regulations, while the European MDR and EMA guidelines impose design-validation requirements on therapeutic-device classifications. ISO 13485 quality-management frameworks shape supplier qualification protocols across regulated procurement channels. Stakeholders must monitor evolving harmonization between FDA 21 CFR Part 606 and EU MDR technical documentation expectations to anticipate compliance-driven equipment refresh cycles.
Market Dynamics
Automated processing protocols in blood banking are compressing replacement cycles and forcing equipment upgrades that satisfy tightening FDA and EMA agitation consistency standards. This regulatory pressure is accelerating capital redeployment toward digitally controlled, temperature-regulated platforms.
Growth Catalysts
- EMA MDR design-validation mandates:Blood processors across Germany, France, and Italy must replace legacy mechanical shakers with validated therapeutic-device classifications, creating equipment refresh demand.
- Cellular therapy manufacturing expansion:CAR-T and stem-cell production facilities require precision agitation for platelet-derived growth media, extending addressable demand beyond traditional transfusion medicine.
- Centralized transfusion network consolidation:Germany's unified blood supply architecture concentrates procurement authority, enabling volume commitments that justify premium platform investments.
Market Restraints
- Stainless steel and electronic component cost volatility:Precision motor drives and corrosion-resistant chamber materials expose fabricators to commodity price swings that compress margin buffers.
- ISO 13485 certification timeline friction:Quality-management documentation requirements extend supplier qualification periods, delaying market entry for emerging equipment vendors.
- Passive storage alternatives:Additive solutions that extend platelet shelf life without continuous agitation threaten displacement of mechanical shaker demand in specific clinical settings.
Strategic Opportunities
- India CDSCO pathway acceleration:The country's national pharmaceutical regulator is streamlining medical device approvals, opening procurement channels for compliant shaker platforms in emerging transfusion networks.
- IoT-enabled predictive maintenance convergence:Integration of vibration sensors and cloud analytics allows remote monitoring contracts that transform capital sales into recurring revenue streams.
- Direct hospital procurement platforms:Group purchasing organizations and digital tender marketplaces are disintermediating traditional distributor relationships, enabling manufacturer-direct relationships with mid-sized blood banks.
Industry Challenges
- Mechatronics engineering scarcity:The specialized skill set combining precision motion control, thermal management, and medical device compliance commands premium compensation that strains R&D budgets.
- Legacy equipment integration complexity:Blood bank information systems and existing cold chain infrastructure require custom interfacing that prolongs deployment timelines and inflates implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platelet Shaker Market |
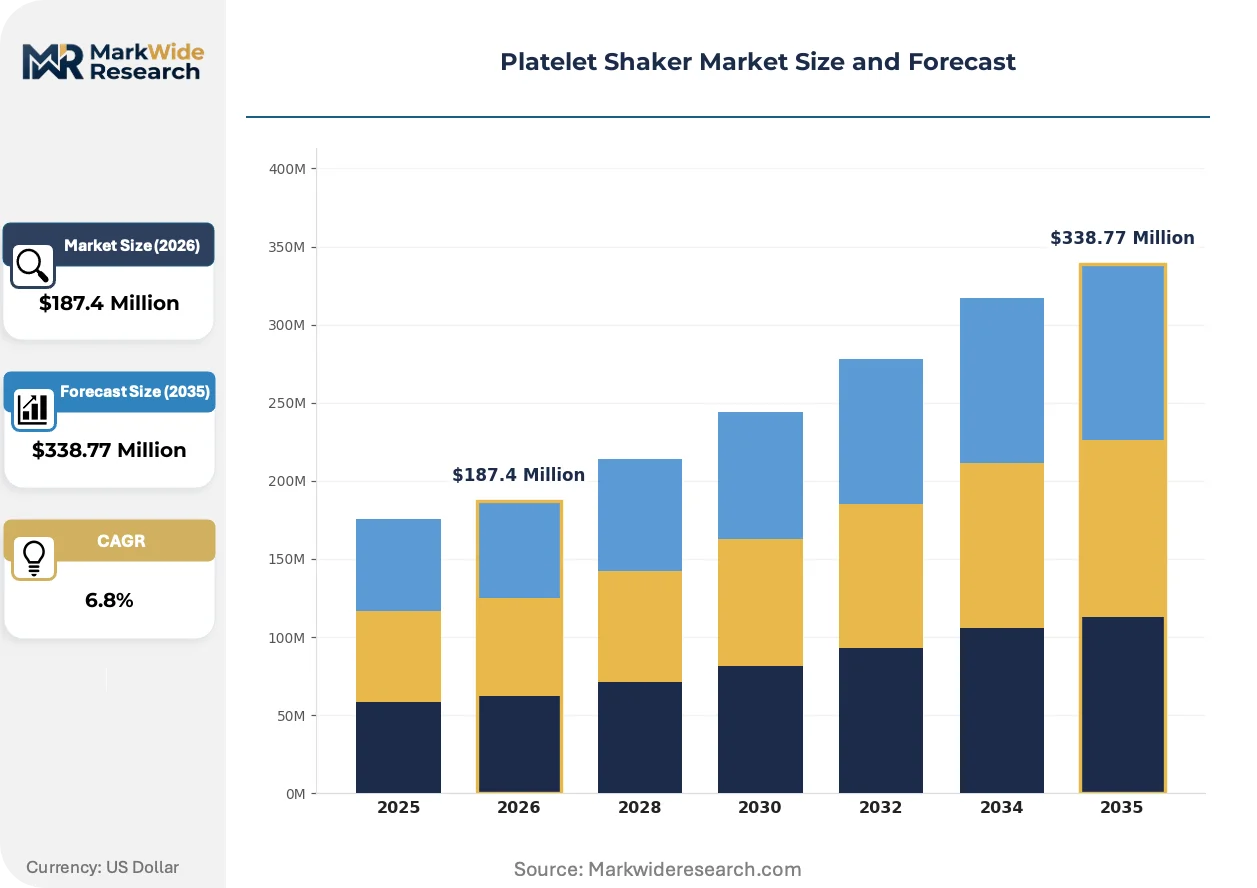
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Shakers, Floor Model Shakers, Portable Shakers, Multiple Plate Shakers Application: Blood Component Separation, Cell Culture, Cellular Therapy, Research Applications End User: Hospital Laboratories, Blood Banks, Research Institutions, Diagnostic Centers Technology: Mechanical Agitation, Magnetic Stirring, Digital Control, Temperature Regulation |
| Companies Covered | Thermo Fisher Scientific Inc., Haemonetics Corporation, Greiner Bio-One International GmbH, Helmer Scientific Inc., Terumo Corporation, Boekel Scientific, Biolab Scientific, Meditech Technologies India Private Limited, Fanem Ltda., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platelet Shaker Market Strategic Shifts
Digital control architectures are supplanting analog mechanical systems across blood banking infrastructure, with sensor feedback loops and programmable motion profiles becoming baseline expectations rather than premium differentiators.
Brushless DC motor platforms with integrated encoder feedback are displacing traditional AC induction drives in high-throughput processing environments. Large-scale blood centers in Germany and the United States are specifying these platforms for new installations. The shift is compressing maintenance intervals while enabling closed-loop speed regulation that satisfies FDA agitation variance limits.
EU MDR technical documentation requirements are forcing design-history file investments that smaller mechanical fabricators cannot absorb. The regulation mandates clinical evidence for therapeutic-device classifications previously governed by self-certification. Blood bank procurement committees in France and Italy are now requiring MDR-compliant declarations of conformity, filtering supplier pools toward quality-system-mature platforms.
Service contract unbundling is fragmenting traditional equipment-plus-maintenance bundles into separately negotiated monitoring, calibration, and parts-replacement agreements. Hospital laboratories in the United States are driving this shift through capital-expense constraints that favor operational-expense treatment of aftermarket services. The pattern concentrates margin pressure on original equipment manufacturers while creating openings for independent service organizations.
Platelet Shaker Market Segmentation
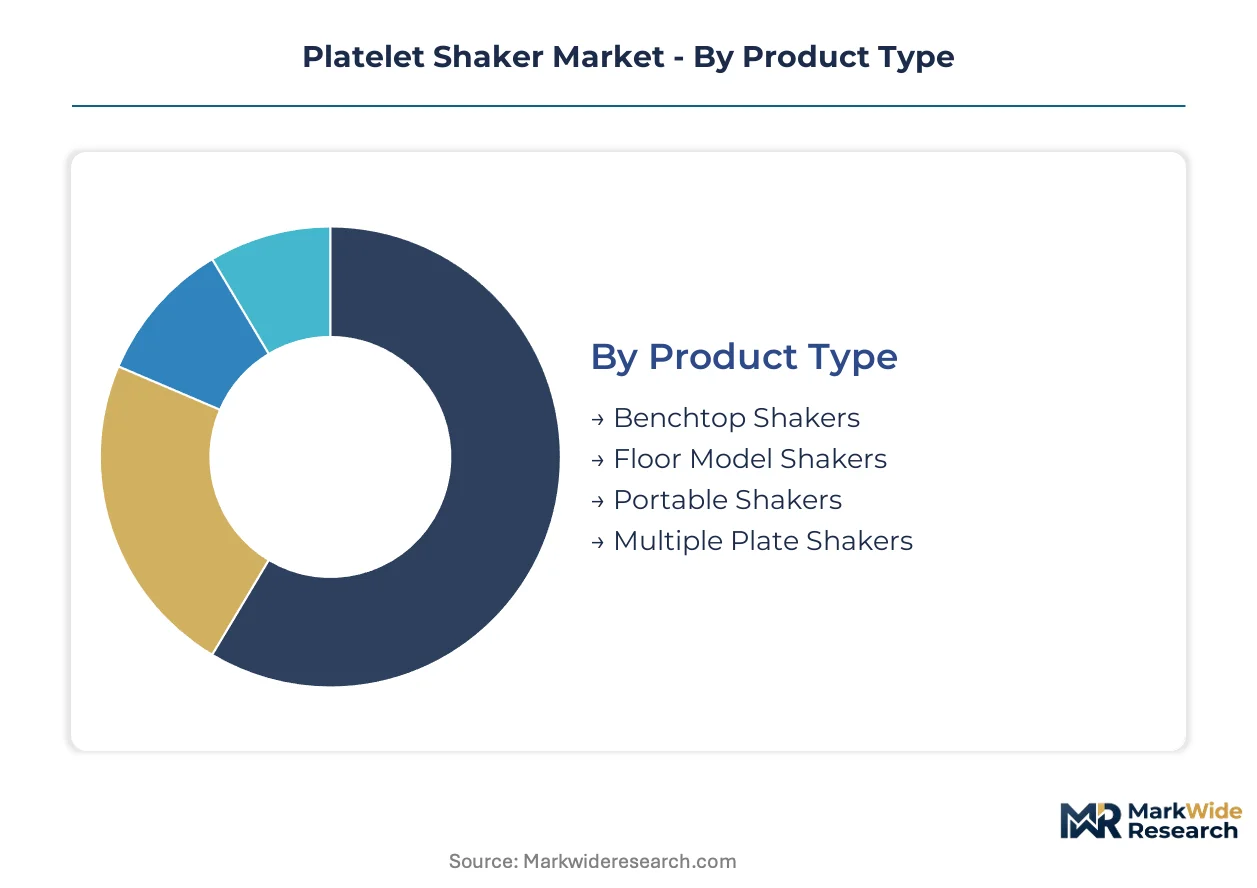
Platelet shaker procurement patterns diverge sharply across equipment formats and control architectures. Substitution threats from additive storage solutions and passive agitation technologies reshape competitive intensity differently within each segment cluster.
Product Type:
Benchtop configurations face intensifying displacement pressure from compact thermal incubators with integrated motion systems, while floor models confront longer replacement cycles and refurbishment alternatives.
- Benchtop Shakers:Compact electromechanical units occupy limited laboratory real estate with single or dual plate capacity. Hospital laboratories in Germany and the United States concentrate procurement here due to space constraints and moderate throughput requirements. These systems face margin compression as multi-functional incubated shakers capture preference.
- Multiple Plate Shakers:High-capacity platforms process six to twelve plate units simultaneously for large-scale blood centers. Germany's centralized transfusion networks drive the steepest demand acceleration as regional processors consolidate processing lines onto unified platforms.
- Floor Model Shakers:Heavy-duty industrial units serve established regional blood centers with mature replacement cycles and extended service intervals.
- Portable Shakers:Battery-powered mobile units support field transfusion services and emergency medical deployments with limited temperature control capabilities.
Benchtop shakers retain volume leadership across installed base; multiple plate configurations hold the steepest expansion curve.
Application:
Cost tier stratification separates regulated therapeutic applications from research-grade deployments, with certification requirements driving price spreads between segments.
- Blood Component Separation:FDA 21 CFR Part 606 and EMA MDR regulated processes demand validated agitation consistency for platelet concentrate viability. Blood banks in France and Italy require MDR-compliant declarations of conformity, filtering procurement toward quality-system-mature platforms.
- Cellular Therapy:CAR-T and stem-cell manufacturing facilities require precision agitation for platelet-derived growth media with closed-system aseptic processing requirements. This application extends addressable demand beyond traditional transfusion medicine into bioproduction workflows.
- Cell Culture:Research and bioproduction environments utilize shakers for suspension cell maintenance with less stringent regulatory documentation requirements.
- Research Applications:Academic and pharmaceutical discovery settings prioritize flexibility and programmability over validation packages.
Blood component separation commands premium pricing tiers; cellular therapy applications are climbing the fastest.
End User:
Customer type determines procurement authority concentration and service contract structures, with centralized purchasing entities altering competitive dynamics.
- Blood Banks:Automated processing protocol adoption compresses replacement cycles and forces equipment upgrades satisfying tightening FDA and EMA agitation consistency standards. These facilities specify brushless DC motor platforms with integrated encoder feedback for closed-loop speed regulation.
- Hospital Laboratories:Capital-expense constraints drive operational-expense treatment of aftermarket services through unbundled service contracts. Mid-sized facilities increasingly utilize group purchasing organizations and digital tender marketplaces for direct manufacturer relationships.
- Research Institutions:Academic procurement prioritizes grant-funded equipment with extended warranty and calibration support requirements.
- Diagnostic Centers:High-throughput testing environments require rapid platelet processing with minimal quality control overhead.
Hospital laboratories retain the broadest installed base; blood banks hold the steepest expansion trajectory.
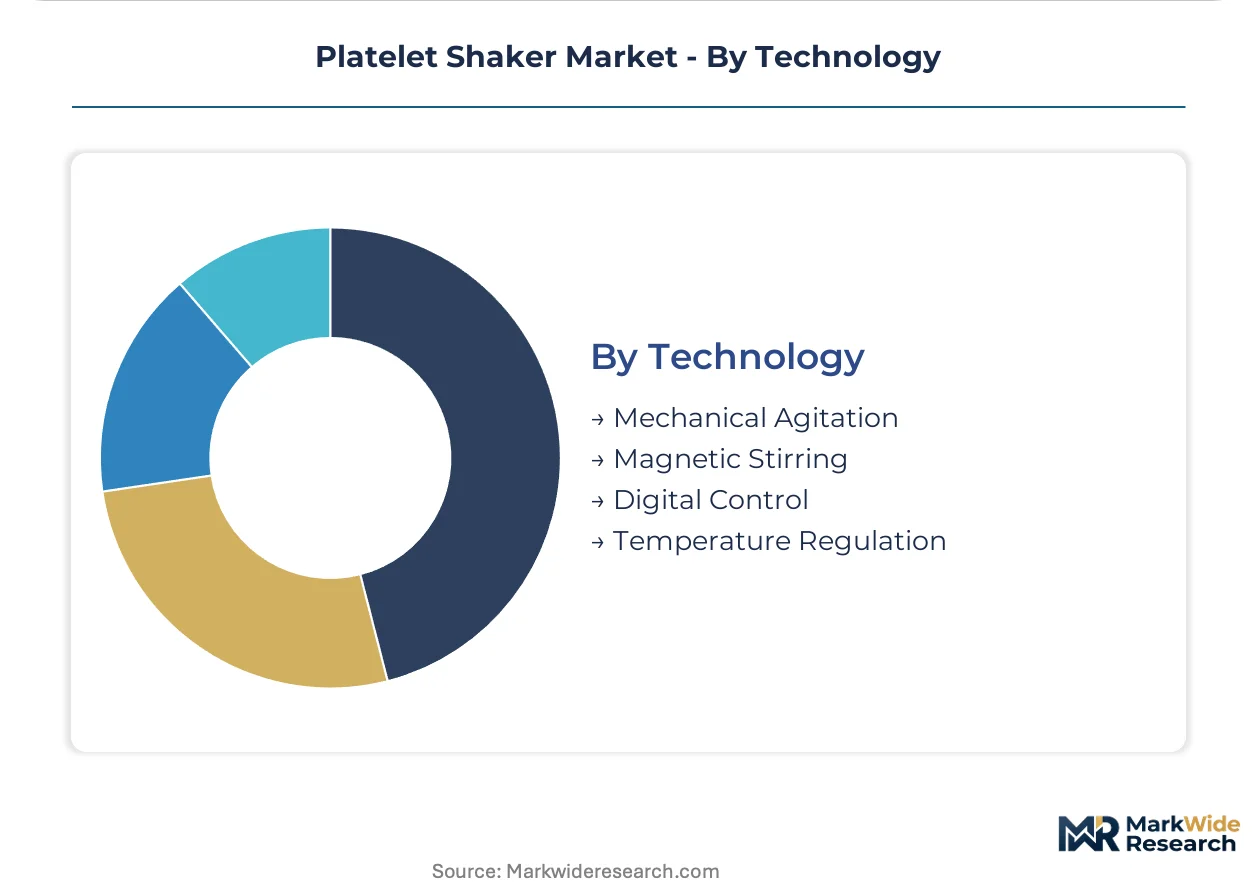
Technology:
Supply concentration among mechatronics engineering specialists favors integrated digital-temperature platforms over discrete mechanical systems.
- Digital Control:Sensor feedback loops and programmable motion profiles enable closed-loop speed regulation that satisfies FDA agitation variance limits. These architectures are supplanting analog mechanical systems as baseline expectations rather than premium differentiators.
- Temperature Regulation:Combined thermal and motion management platforms capture margin concentration as large-scale blood processors consolidate processing lines. Thermo Fisher Scientific leverages life-sciences instrumentation ecosystems to sustain premium positioning through integrated platform sales.
- Mechanical Agitation:Traditional cam-driven and eccentric rotation systems serve cost-sensitive replacement markets with limited feature requirements.
- Magnetic Stirring:Stir-bar based agitation alternatives address specific cell culture applications with lower shear stress requirements.
Mechanical agitation retains legacy installed base dominance; temperature regulation platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature transfusion networks and emerging procurement systems. Germany deploys centralized blood-banking infrastructure with precision-agitation specifications, while India and Brazil rely on fragmented hospital-laboratory procurement with cost-sensitive mechanical platforms.
United States
FDA 21 CFR Part 606 enforcement compresses replacement cycles for blood centers seeking agitation variance compliance. Hospital laboratories in the Northeast Corridor drive unbundled service contract adoption. Thermo Fisher Scientific leverages its life-sciences instrumentation ecosystem to sustain premium positioning across Boston and New York Metro clusters.
Germany
Centralized transfusion networks concentrate procurement authority for validated therapeutic-device classifications. EMA MDR design-validation mandates force equipment refreshes in Bavaria and North Rhine-Westphalia. Regional blood processors specify brushless DC motor platforms with integrated encoder feedback for closed-loop speed regulation.
France
Blood bank procurement committees require MDR-compliant declarations of conformity, filtering supplier pools toward quality-system-mature platforms. The Île-de-France region anchors demand for digitally controlled temperature-regulated shakers. ANSM oversight tightens documentation requirements for platelet storage equipment validation.
India
CDSCO pathway acceleration streamlines medical device approvals for emerging transfusion networks. Maharashtra and Gujarat host hospital laboratories prioritizing capital-expense constraints over feature expansion. Domestic fabricators compete on cost-sensitive mechanical platforms for mid-sized blood bank procurement.
Japan
PMDA therapeutic-device classifications impose design-history file investments that favor established quality-system-mature suppliers. The Kanto region around Tokyo concentrates cellular therapy manufacturing demand for precision agitation in platelet-derived growth media. METI industrial policy supports domestic mechatronics engineering capabilities.
Platelet Shaker Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier with divergent investment capabilities. Thermo Fisher Scientific and Haemonetics Corporation anchor the upper tier through life-sciences instrumentation ecosystems and transfusion workflow control. Mid-cap specialists concentrate on regional blood-banking relationships and cost-optimized mechanical platforms. Competitive moves center on portfolio diversification into temperature-regulation modules and geographic expansion through distributor network consolidation.
Among North American and European integrated leaders, Thermo Fisher Scientific Inc., Haemonetics Corporation, and Greiner Bio-One International GmbH exemplify contrasting strategic positions. Thermo Fisher Scientific occupies the diversified life-sciences instrumentation archetype with cross-selling leverage into hospital laboratories. Haemonetics Corporation represents the transfusion workflow specialist archetype extending channel control into adjacent agitation equipment. Greiner Bio-One International GmbH anchors the European blood-banking consumables integration archetype, leveraging regional procurement relationships in Germany and France. These three fabricators illustrate how scale, specialization, and geographic focus segment competitive positioning in regulated medical device procurement.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Haemonetics Corporation |
| Greiner Bio-One International GmbH |
| Helmer Scientific Inc. |
| Terumo Corporation |
| Boekel Scientific |
| Biolab Scientific |
| Meditech Technologies India Private Limited |
| Fanem Ltda. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German blood processors and precision-motor suppliers lock in both corrosion-resistant chamber materials and price visibility, insulating procurement committees from stainless steel volatility while compressing margin buffers for mechanical fabricators.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement between large-scale blood centers and platform manufacturers, with three-tier pricing structure across premium, standard, and economy levels separating MDR-validated digital-control systems from mechanical-only units. Price differentiation rests on ISO 13485 certification tier and after-sales service bundling, with hospital laboratories in the United States driving unbundled operational-expense treatment. Cost compression in economy mechanical tiers is intensifying because domestic fabricators in India compete on capital-expense constraints. Blood banks remain least price-sensitive due to regulatory compliance mandates, while research institutions exhibit highest elasticity.
Supply Chain Analysis
Brushless DC motor encoder production concentrates in Germany, Japan, and the United States, creating single-source vulnerability for precision motion-control components. Raw material dependencies span corrosion-resistant stainless steel alloys, rare-earth magnet composites, and medical-grade polymer housings. Tariff exposure on precision motor drives imported into the European Union threatens margin stability for equipment assemblers. Distribution runs through group purchasing organizations and digital tender marketplaces that disintermediate traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA 21 CFR Part 606 and EMA MDR validation requirements creates formidable switching costs that incumbents can exploit to deepen hospital laboratory relationships and blood-bank channel control.
For Market Incumbents: Secure MDR-compliant design-history file investments to filter competitor pools from French and Italian procurement committees. Anchor channel control through integrated temperature-regulation platform sales that compress replacement cycles for legacy mechanical shakers. Passive storage additive solutions threaten displacement in specific clinical settings; counter through closed-loop speed regulation capabilities that satisfy FDA agitation variance limits. For New Entrants and Emerging Players: Unbundled calibration and predictive maintenance service contracts represent a service-layer gap where incumbents under-serve mid-sized blood banks. Target India's CDSCO-accelerated approval pathway for cost-sensitive mechanical platform penetration. Pursue direct manufacturer relationships through digital tender marketplaces rather than distributor network replication. For Investors and Strategic Acquirers: Quality-system-mature specialists with embedded brushless DC motor capabilities offer the strongest acquisition target archetype for portfolio consolidation. Long-term viability centers on therapeutic-device classification breadth rather than research-grade equipment exposure. Monitor EMA-FDA harmonization progress on agitation consistency standards as the inflection indicator for compliance-driven equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Design-Validation Investment | EMA technical documentation mandates filter supplier pools toward quality-system-mature platforms in France and Italy. |
| Brushless DC Motor Platform Transition | German blood processors specify integrated encoder feedback for closed-loop speed regulation compliance. |
| IoT Predictive Maintenance Convergence | Cloud analytics integration transforms capital sales into recurring revenue streams for hospital laboratories. |
| CDSCO Pathway Market Entry | Streamlined medical device approvals open procurement channels in Maharashtra and Gujarat transfusion networks. |
| Direct Hospital Procurement Platform | Digital tender marketplaces disintermediate distributor relationships for mid-sized blood bank access. |
Study Parameters
A spread of perspectives from blood-bank procurement managers, biomedical engineers, GPO contracts managers, and aftermarket service heads converged on the working assumptions. Primary interview insights combined with secondary validation from FDA 21 CFR Part 606 filings, EMA MDR technical documentation databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up equipment shipment analysis and top-down transfusion network spend estimates were triangulated for coherence.
Segmentation dimensions modeled include product format, control architecture, end-user facility type, and regional regulatory cluster across the analysis window. CAGRs were derived from installed base replacement cycle compression and cellular therapy manufacturing expansion trajectories. Forecast inputs incorporated EMA MDR enforcement timelines and brushless DC motor adoption curves in large-scale processing environments.
Underlying assumptions cover sustained FDA agitation variance enforcement and EMA design-validation mandate adherence, with deviation risk concentrated in passive storage additive solution efficacy and stainless steel commodity price volatility. Practitioners should keep alternative scenarios live as harmonization between FDA and EU MDR technical documentation expectations evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Global Microplate System Market
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Blood Bank Analyzers Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Pipettes and Accessories Market