
 Longevity Clinic Chain Infrastructure Market | 2026-2036
Longevity Clinic Chain Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Longevity Clinic Chain Infrastructure Market Insights
Corporate wellness groups and longevity researchers is bifurcating the buyer base that legacy operators built around individual affluent patients. Fountain Life leverages vertical integration across diagnostic labs and regenerative therapy suites to control patient throughput. Cenegenics anchors its position through R&D intensity in hormone optimization protocols. Clinique La Prairie differentiates via geographic dominance across European wellness hubs.
Longevity clinic chain infrastructure encompasses the physical facilities, medical equipment networks, and integrated technology systems that enable standardized delivery of preventive, regenerative, and diagnostic services across multi-location operators, typically requiring ISO 13485-compliant device calibration and controlled-environment specifications for cell therapy processing. These installations serve commercial purposes by capturing recurring revenue from subscription-based health optimization programs while reducing per-unit service costs through centralized procurement. Outpatient centers lead facility type deployment due to lower capital intensity and faster regulatory licensing timelines. Regenerative therapies command the deepest margin pools within service offerings, though preventive care scales more rapidly across new market entrants. AI diagnostics within technology utilization represents the fastest-expanding segment as chains seek to reduce specialist labor dependency.
The US FDA and EMA jointly shape market access through divergent pathways for cell-based interventions, with FDA 351/361 distinctions determining whether chains must pursue biologics licensing or remain under physician practice exemptions. HIPAA in the US and GDPR in Europe impose data architecture requirements that increase technology infrastructure costs but create compliance barriers for new entrants. Stakeholders must monitor how evolving regenerative medicine frameworks in Switzerland and the UAE reshape permissible service menus and capital allocation priorities.
Market Dynamics
AI diagnostic platforms are compressing specialist labor requirements across outpatient chains, forcing capital reallocation toward automated imaging suites and algorithmic patient triage systems that reduce per-visit operational costs.
Growth Catalysts
- FDA 351/361 Pathway Clarity:The US FDA's regenerative medicine framework distinguishes between biologics licensing and physician practice exemptions, enabling chains to scale cell therapy services without full drug approval timelines.
- Corporate Wellness Mandates:Fortune 500 employers in Dubai and Miami are embedding longevity screening into executive health benefits, creating institutional demand beyond individual affluent patients.
- ISO 13485 Device Standardization:Unified calibration protocols for diagnostic equipment allow chains to centralize procurement and reduce per-facility technology deployment costs.
Market Restraints
- Cell Processing Facility Costs:Controlled-environment specifications for regenerative therapy suites require cleanroom infrastructure that quadruples capital intensity versus standard outpatient buildouts.
- GDP Data Architecture Requirements:European chains face mandatory compliance investments for patient data handling under GDPR, creating fixed cost barriers for new market entrants.
- Biologics Cold Chain Fragility:Temperature-sensitive regenerative materials concentrate supply risk with specialized logistics providers operating limited geographic footprints.
Strategic Opportunities
- Switzerland Regulatory Arbitrage:Swissmedic's evolving framework for cell-based interventions permits service menus unavailable under stricter FDA or EMA jurisdictions, attracting capital to Zurich and Geneva clusters.
- Subscription Model Penetration:Annual health optimization programs lock in recurring revenue streams that smooth facility utilization and reduce patient acquisition cost volatility.
- AI-Wearable Convergence:Integration of continuous glucose monitors and sleep trackers with clinic diagnostic platforms enables remote patient monitoring between physical visits.
Industry Challenges
- Regenerative Medicine Specialist Scarcity:Trained cell therapy technicians and hormone optimization physicians command premium compensation that strains labor cost structures.
- HIPAA-GDPR Dual Compliance:Chains operating across US and European jurisdictions must architect separate data systems, doubling technology infrastructure overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Longevity Clinic Chain Infrastructure Market |
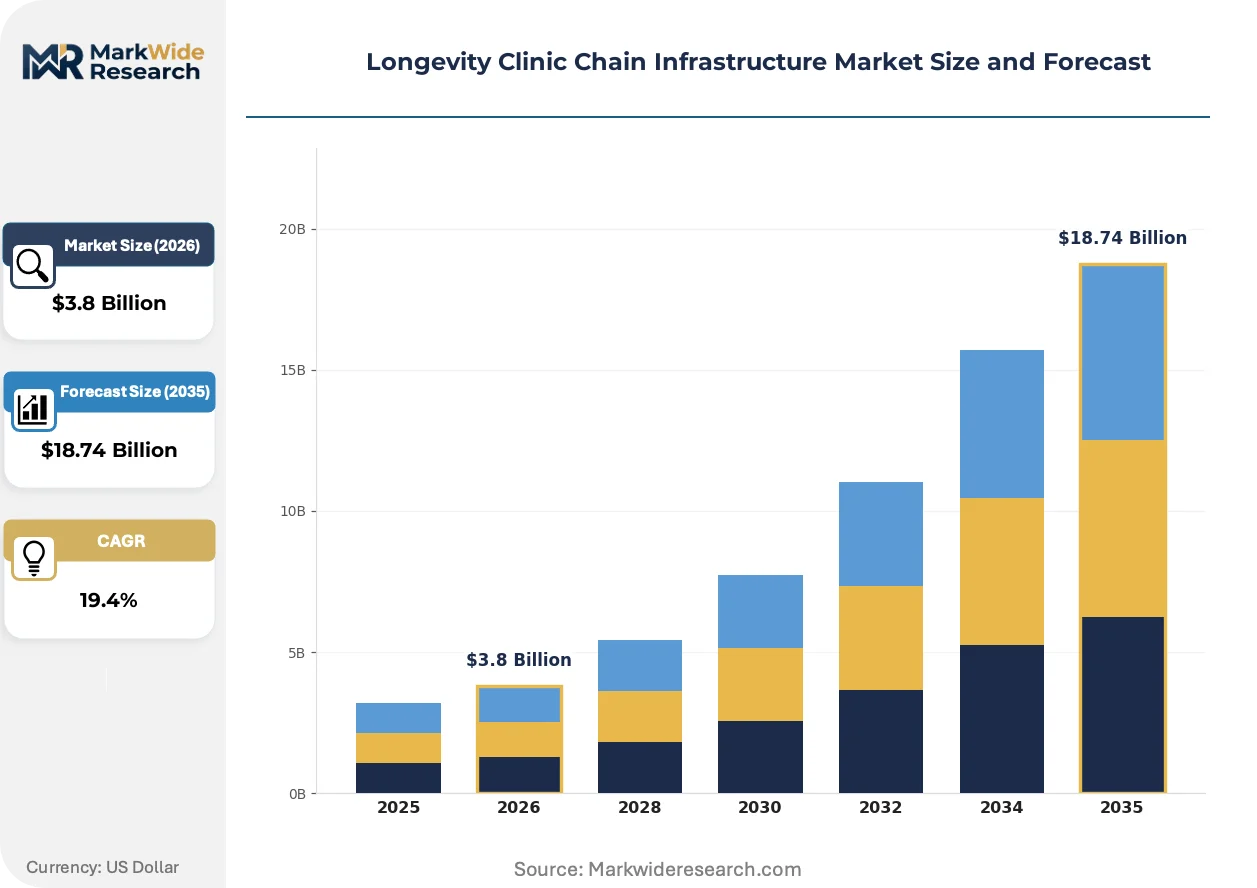
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Outpatient Centers, Wellness Hubs, Diagnostic Labs, Rehabilitation Units, Health Spas Service Offering: Preventive Care, Regenerative Therapies, Nutritional Counseling, Genetic Testing, Physical Therapy End User: Senior Wellness Programs, Corporate Wellness Groups, Chronic Condition Patients, Longevity Researchers Technology Utilization: Telehealth Platforms, AI Diagnostics, Wearable Health Devices, Virtual Reality Therapy, Data Analytics |
| Companies Covered | Fountain Life, Cenegenics, Clinique La Prairie, SHA Wellness Clinic, VIVAMAYR Medical Center, Paracelsus Clinic, Lanserhof, Six Senses, Healthspan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Longevity Clinic Chain Infrastructure Market Trends and Innovations
Technology deployment patterns across longevity clinic chains are splitting between capital-heavy regenerative therapy suites and lean AI-powered diagnostic nodes, reshaping facility design standards and equipment vendor relationships.
Multi-omics screening platforms are bifurcating patient intake protocols across high-end chains. Ultra-high-net-worth individuals in Zurich and Miami demand whole-genome sequencing and metabolomic profiling as baseline services. Mid-market outpatient centers respond with targeted biomarker panels that compress initial consultation costs while maintaining perceived value differentiation.
The EU AI Act's risk classification system for medical decision-support algorithms is forcing European chains to revalidate diagnostic software workflows. Operators must document human oversight protocols for AI-generated treatment recommendations. Swiss and German facilities face the steepest compliance timelines given their earlier adoption of automated imaging interpretation.
Employer-sponsored longevity benefits are displacing individual direct-pay models in Dubai and Miami corporate corridors. Health optimization programs now flow through benefits administrators rather than concierge medicine brokers. This channel shift compresses pricing power but accelerates patient volume scaling for chains with standardized service menus.
Longevity Clinic Chain Infrastructure Market Segmentation
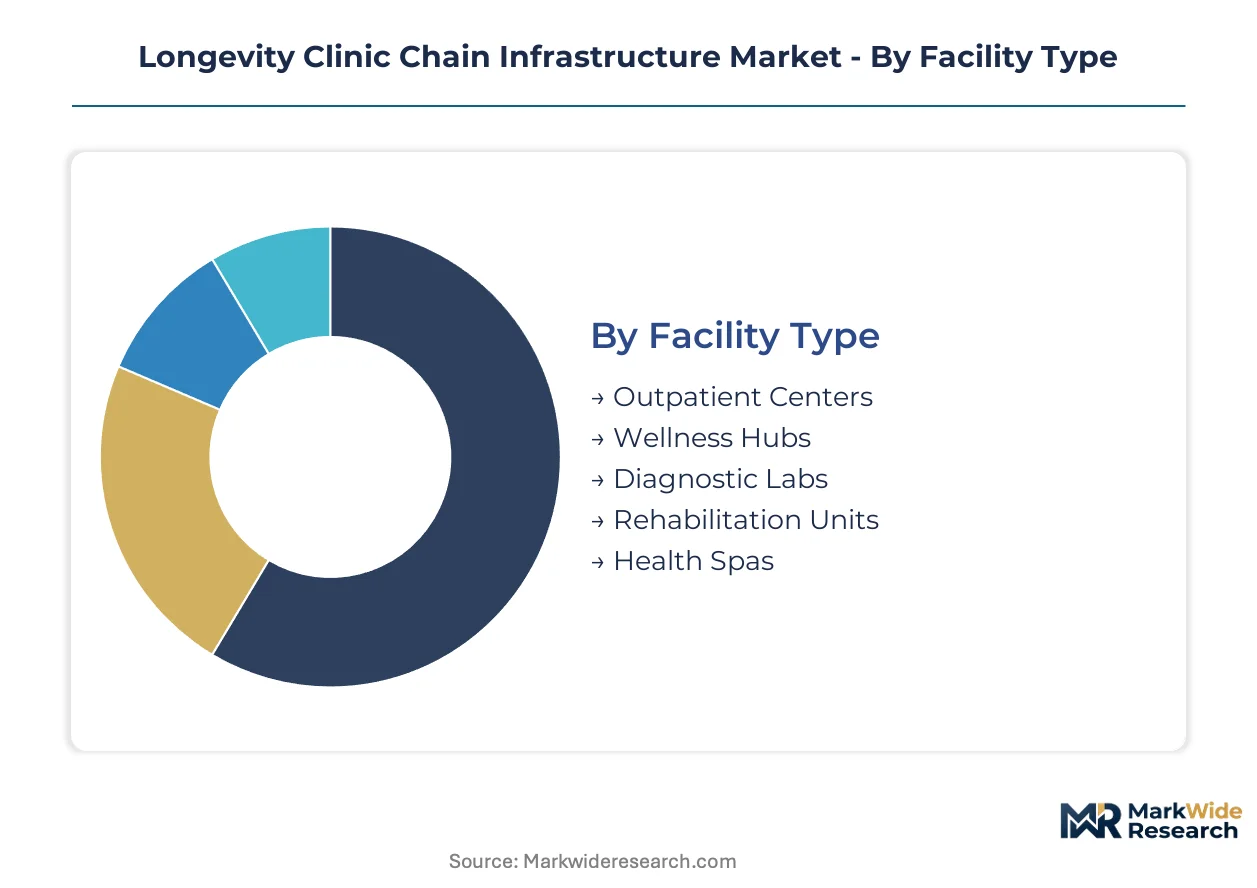
Longevity clinic chains deploy heterogeneous facility configurations and service menus to capture distinct patient cohorts. Channel economics vary sharply across outpatient centers versus wellness hubs, while technology utilization determines labor cost structures and regulatory compliance burdens.
Facility Type:
Outpatient centers and wellness hubs flow through contrasting channels—corporate benefits administrators versus direct-to-consumer concierge brokers—creating divergent pricing power and patient acquisition economics.
- Outpatient Centers:These facilities integrate diagnostic imaging suites with physician consultation pods under streamlined licensing frameworks. Demand concentrates in Dubai and Miami corporate corridors where Fortune 500 employers embed longevity screening into executive health benefits, though per-visit revenue sits below regenerative therapy suites.
- Wellness Hubs:Multi-service campuses combine preventive care, spa amenities, and lifestyle coaching under single-roof experiences. Ultra-high-net-worth individuals in Zurich and Geneva drive capacity expansion here, attracted by Swissmedic's permissive cell-based intervention frameworks unavailable in stricter jurisdictions.
- Diagnostic Labs:Centralized processing nodes handle biomarker analysis and multi-omics screening for network affiliates.
- Rehabilitation Units:Post-therapy recovery facilities support regenerative procedure outcomes with controlled-environment monitoring.
- Health Spas:Lifestyle-oriented properties emphasize sleep optimization and stress reduction protocols with lighter medical oversight.
By volume, Outpatient Centers lead. By growth pace, Wellness Hubs are expanding most quickly.
Service Offering:
Margin profiles stratify sharply across this dimension, with regenerative therapies commanding premium pricing while preventive care scales through subscription models.
- Regenerative Therapies:Cell-based interventions and hormone optimization protocols require ISO 13485-compliant cleanroom infrastructure. FDA 351/361 pathway clarity in the US enables chains to scale these services without full biologics licensing timelines, though specialist scarcity strains labor costs.
- Preventive Care:Annual health optimization programs and risk-factor monitoring lock in recurring revenue streams. Corporate wellness mandates in Dubai and Miami accelerate patient volume scaling, compressing per-unit margins but smoothing facility utilization.
- Nutritional Counseling:Metabolic profiling and personalized diet protocols support longevity outcomes with moderate capital requirements.
- Genetic Testing:Whole-genome sequencing and pharmacogenomic analysis anchor premium tier differentiation.
- Physical Therapy:Movement optimization and musculoskeletal rehabilitation serve post-procedure recovery pathways.
Regenerative Therapies generate the deepest margin pools. Preventive Care is climbing the fastest as employer-sponsored benefits displace direct-pay models.
End User:
Customer acquisition channels bifurcate between institutional contracts and individual concierge relationships, reshaping sales force deployment and service standardization requirements.
- Corporate Wellness Groups:Fortune 500 employers and family offices negotiate population-level contracts with standardized service menus. Benefits administrators in Miami and Dubai corridors now channel substantial volume, accelerating patient throughput for chains with compliant data architectures.
- Senior Wellness Programs:Affluent aging cohorts seek proactive intervention before chronic condition onset. Zurich clusters attract this segment through Swissmedic's evolving regulatory framework permitting broader service menus than FDA or EMA jurisdictions.
- Chronic Condition Patients:Disease management integration with longevity optimization creates cross-sell opportunities.
- Longevity Researchers:Academic and clinical trial participants generate data assets and publication credibility for chain operators.
Corporate Wellness Groups dominate current volume. Longevity Researchers represent the steepest expansion trajectory as real-world evidence requirements intensify.
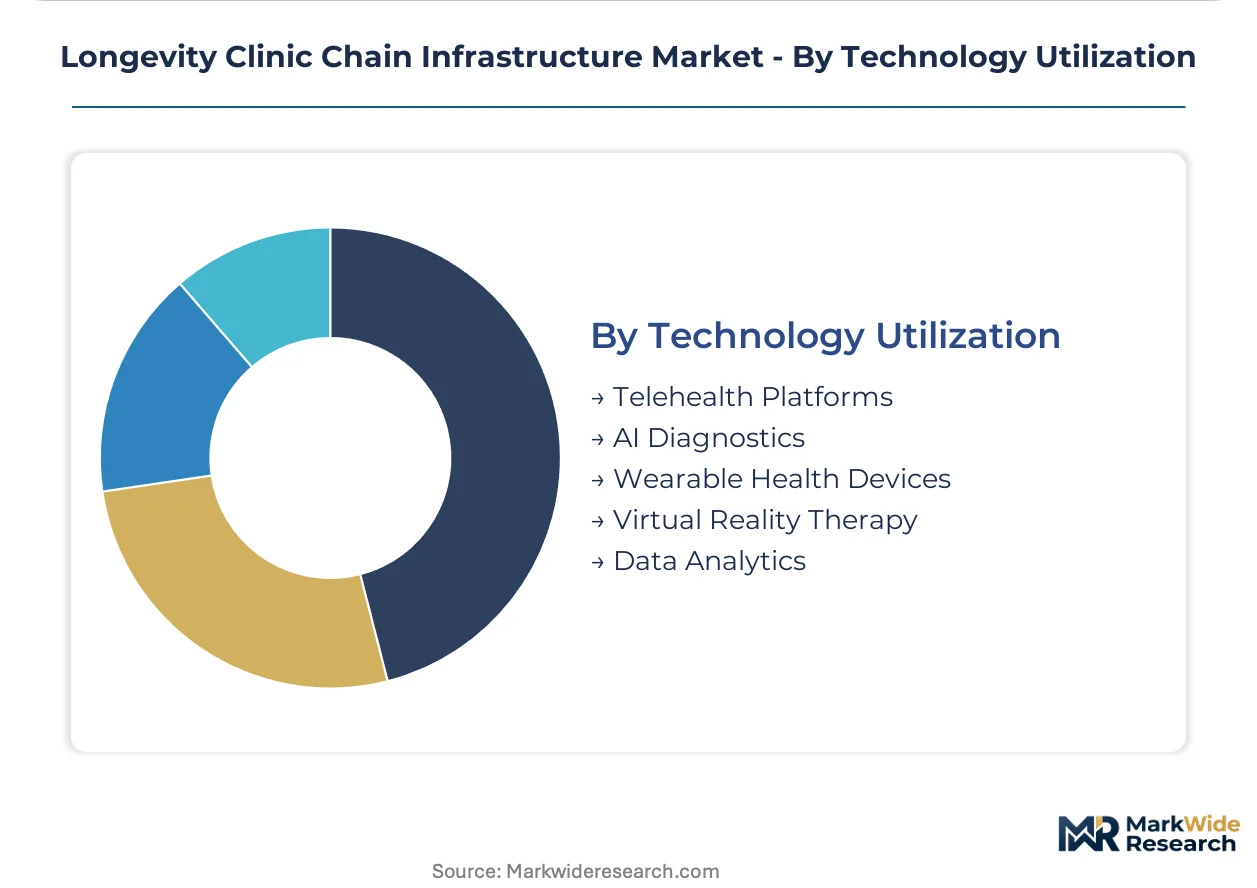
Technology Utilization:
Capital allocation splits between labor-displacing automation and patient-engagement platforms, with regulatory validation timelines varying by jurisdiction.
- AI Diagnostics:Automated imaging interpretation and algorithmic patient triage reduce specialist labor dependency. EU AI Act risk classification requirements force European chains to revalidate software workflows and document human oversight protocols, with Swiss and German facilities facing the steepest compliance timelines.
- Wearable Health Devices:Continuous glucose monitors, sleep trackers, and activity sensors enable remote patient monitoring between physical visits. Integration with clinic diagnostic platforms creates subscription stickiness and real-time intervention triggers.
- Telehealth Platforms:Virtual consultation infrastructure extends geographic reach with lower capital intensity than physical buildouts.
- Virtual Reality Therapy:Immersive environments support pain management and cognitive training protocols.
- Data Analytics:Population health insights and predictive risk modeling inform service menu optimization.
AI Diagnostics absorbs the largest capital share. Wearable Health Devices are gaining share fastest as patient monitoring extends beyond facility walls.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dubai International Airport cargo corridor underwrites the UAE's role as the primary Gulf hub for temperature-sensitive biologics distribution, connecting Swiss and US cell therapy supply chains to Middle Eastern patient populations.
United States
Fortune 500 employers in Miami and Manhattan drive corporate wellness contract volume through benefits administrators. FDA 351/361 pathway distinctions enable chains to scale cell therapies without full biologics licensing. The Miami health corridor concentrates outpatient center buildouts targeting executive screening programs.
Switzerland
Swissmedic's evolving framework for cell-based interventions permits service menus unavailable under stricter FDA or EMA jurisdictions. Zurich and Geneva clusters attract ultra-high-net-worth individuals seeking hormone optimization protocols. The Lake Geneva wellness belt anchors European premium-tier facility expansion.
United Arab Emirates
Dubai's free zone infrastructure and MOHAP regulatory flexibility position the emirate as a Gulf longevity hub. Family offices and sovereign wealth capital fund multi-service wellness campuses. The Dubai Healthcare City cluster integrates diagnostic labs with regenerative therapy suites under streamlined licensing.
Germany
EU AI Act risk classification requirements force German chains to revalidate diagnostic software workflows with documented human oversight. Berlin and Munich house the steepest compliance timelines given earlier automated imaging adoption. GDPR data architecture investments create fixed cost barriers for new market entrants.
United Kingdom
London's Harley Street medical district attracts preventive care outpatient models targeting affluent aging cohorts. MHRA alignment with EMA frameworks shapes permissible regenerative service menus. The Thames Valley corridor concentrates AI diagnostic platform development for network affiliate deployment.
Longevity Clinic Chain Infrastructure Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory navigation capabilities. The vendor base splits between vertically integrated multi-location operators and single-site wellness hubs with spa-hotel hybrid models. Three archetypes dominate: R&D-intensive protocol developers, geographic cluster specialists, and corporate benefits channel aggregators. Capacity expansion and AI diagnostic platform licensing constitute the dominant competitive moves.
Within the R&D-intensive tier, Cenegenics exemplifies hormone optimization protocol developers with laboratory-backed service standardization. Clinique La Prairie occupies a position among geographic cluster specialists leveraging Swiss regulatory arbitrage. Fountain Life represents the vertically integrated archetype controlling diagnostic throughput across multi-state networks.
| Leading Market Players |
|---|
| Fountain Life |
| Cenegenics |
| Clinique La Prairie |
| SHA Wellness Clinic |
| VIVAMAYR Medical Center |
| Paracelsus Clinic |
| Lanserhof |
| Six Senses |
| Healthspan |
| Others |
Pricing and Supply Chain Analysis
ISO 13485 certification gates both supplier qualification and price differentiation simultaneously, as chains without compliant device calibration cannot access regenerative therapy revenue pools regardless of pricing flexibility. This regulatory threshold stratifies procurement power across centralized multi-location operators versus fragmented single-site wellness hubs.
Pricing Analysis
Volume-discount tiering structures dominate corporate wellness contracts, with Fortune 500 employers negotiating population-level rates that compress per-unit margins against direct-to-consumer concierge premiums. Pricing stratifies across premium, standard, and economy tiers based on service intensity and geographic cluster prestige. Cost compression in mid-market outpatient centers is intensifying because employer benefits administrators standardize service menus across competing chains. Corporate wellness groups exhibit highest price sensitivity, while ultra-high-net-worth individuals in Swiss clusters demonstrate lowest elasticity.
Supply Chain Analysis
Switzerland and the United States anchor cleanroom infrastructure fabrication and biologics cold chain logistics respectively. Regenerative therapy suites draw from temperature-controlled cryogenic storage systems, specialized cell culture media, and ISO-compliant diagnostic device networks. Single-source vulnerability concentrates with limited qualified logistics providers handling temperature-sensitive materials. Distribution runs through Dubai's free zone corridor connecting Swiss cell therapy supply chains to Gulf patient populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from capital-intensity cyclicality, with facility buildout pauses during rate tightening now reversing as sovereign wealth and family office deployment accelerates into Zurich and Miami clusters.
For Market Incumbents: Fortify diagnostic throughput control through captive laboratory networks, reducing per-patient reliance on third-party biomarker processing. Secure hormone optimization protocol IP against emerging R&D-intensive entrants. Expand ISO 13485-certified device calibration capacity in Dubai to preempt supply bottlenecks for regenerative therapy suite rollouts.
For New Entrants and Emerging Players: Swissmedic's expedited cell-based intervention pathway offers fastest regulatory clearance for regenerative service menus unavailable under FDA or EMA frameworks. Target corporate wellness benefits administrators in Miami corridors with standardized AI diagnostic packages priced below incumbent concierge premiums. Lead with wearable health device integration to demonstrate remote monitoring capabilities during pilot contracts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-powered diagnostic nodes versus regenerative therapy suites, favoring technology-light outpatient models over cleanroom-heavy wellness hubs. Long-term viability centers on chains with recurring subscription revenue smoothing facility utilization volatility. Watch FDA 351/361 pathway enforcement discretion as inflection signal for regenerative therapy margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Expansion | Enables regenerative therapy suite licensing across Dubai and Zurich clusters under unified device standards. |
| AI Diagnostic Platform Licensing | Reduces specialist labor dependency while triggering EU AI Act compliance investments in German facilities. |
| Corporate Benefits Channel Partnership | Locks recurring revenue through Fortune 500 executive health programs in Miami corridors. |
| Cold Chain Logistics Integration | Secures temperature-sensitive biologics distribution via Dubai International Airport cargo infrastructure. |
| Swissmedic Regulatory Arbitrage Positioning | Captures ultra-high-net-worth patient flows seeking cell-based interventions unavailable under stricter FDA frameworks. |
Research Methodology
Cross-validation between primary interviews with longevity clinic operators and secondary regulatory filing analysis anchors the qualitative findings. Stakeholder consultations spanned facility development executives, cell therapy laboratory directors, corporate benefits administrators, and biomedical equipment procurement managers. Secondary sources included FDA 351/361 pathway guidance documents, Swissmedic cell-based intervention frameworks, MOHAP licensing protocols, EU AI Act risk classification schedules, and ISO 13485 certification databases. Bottom-up facility deployment tracking and top-down market sizing triangulated volume estimates.
Sensitivity analysis tested capital intensity assumptions across cleanroom infrastructure versus lean diagnostic node configurations. Segmentation dimensions modeled facility type, service offering intensity, end-user channel structure, and technology utilization tier. CAGRs were derived from facility rollout pipelines, patient throughput assumptions, and subscription pricing trajectories. Forecast inputs incorporated regenerative medicine specialist wage inflation, biologics cold chain cost curves, and AI diagnostic platform adoption rates.
Underlying assumptions cover regulatory pathway stability and sovereign wealth capital commitment continuity, with deviation risk concentrated in FDA enforcement discretion shifts and GDPR compliance cost escalations. Recalibration cycles align with material shifts in regenerative medicine framework updates across Swissmedic, FDA, and EMA jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market
Healthcare Facilities
Global Healthcare Architecture Market
Healthcare Facilities
Confinement Center Market