
 Bedless Hospitals Market | 2026-2036
Bedless Hospitals Market Size, Share, and Industry Trends Forecast 2026-2036
Bedless Hospitals Market Outlook
Acute-care certification tiers is bifurcating the competitive landscape into high-complexity outpatient operators and volume-focused same-day facilities. HCA Healthcare anchors its position through captive surgery center networks in metropolitan corridors. Fresenius SE & Co. KGaA leverages nephrology specialization to dominate renal ambulatory settings. Surgery Partners competes on price-transparent bundled procedures across multi-specialty platforms.
Bedless hospitals are healthcare delivery organizations engineered for zero overnight stays, relying on minimally invasive surgical protocols, enhanced recovery after surgery pathways, and real-time remote physiologic monitoring to discharge patients within four to twenty-three hours. Their commercial purpose centers on reducing facility costs, eliminating hospital-acquired infection vectors, and aligning reimbursement with value-based episode pricing. Telemedicine and remote monitoring represent the structural backbone of clinical continuity, while AI diagnostics commands premium positioning by enabling pre-operative risk stratification and post-discharge anomaly detection. Wearable devices within the technology segment occupy the fastest-expanding margin pool as payers mandate objective recovery metrics for reimbursement authorization.
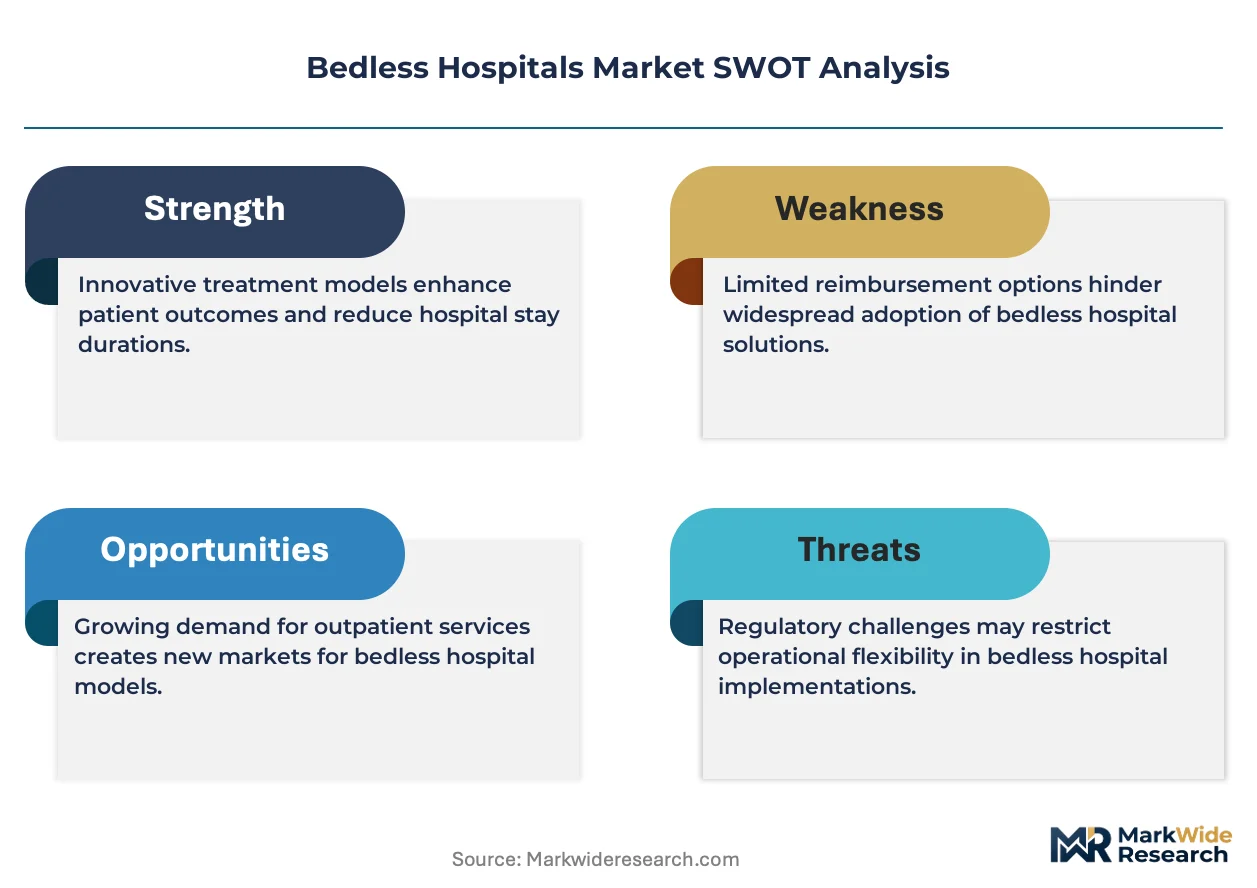
FDA 510(k) clearance pathways for software-as-medical-device platforms govern AI diagnostic deployment, while CMS outpatient prospective payment system revisions directly shape site-of-service economics and capital allocation. HIPAA interoperability mandates and state-level certificate-of-need regulations create divergent compliance burdens that filter market entry by geography. Stakeholders must weigh ambulatory footprint expansion against regulatory exposure from pending site-neutral payment legislation.
Market Dynamics
CMS outpatient prospective payment system revisions are forcing capital reallocation toward ambulatory surgical capacity, compressing the traditional inpatient revenue model while rewarding same-day procedural throughput.
Growth Catalysts
- CMS Site-of-Service Price Parity:Medicare reimbursement differentials now favor ambulatory settings, pulling orthopedic and cardiovascular procedures out of inpatient towers.
- AI Pre-Operative Risk Stratification:Machine learning platforms reduce same-day surgery cancellation rates by identifying high-risk patients before facility scheduling.
- Japan's METI Digital Health Infrastructure:Government-backed telemedicine networks enable real-time post-discharge monitoring for urban ambulatory clusters.
Market Restraints
- Certificate-of-Need State Variability:CON moratoriums in 35 US states block ambulatory facility entry, protecting incumbent hospital systems from price competition.
- Anesthesiologist Labor Concentration:CRNA supervision requirements and anesthesiology group consolidation in metropolitan corridors limit same-day surgical throughput expansion.
- Implant Supply Oligopoly:Orthopedic device sourcing concentrates among three multinational suppliers, compressing ambulatory surgery center margin capture on bundled episodes.
Strategic Opportunities
- Rural Health Clinic Conversion:Underutilized primary care infrastructure in the US Southeast offers retrofit potential for micro-ambulatory surgical units serving Medicare Advantage populations.
- EU MDR Software-as-Medical-Device Pathway:Streamlined 510(k)-equivalent clearance for AI diagnostic platforms accelerates European ambulatory network deployment.
- Wearable-Enabled Episode Pricing:Objective recovery metrics from continuous glucose monitors and pulse oximetry validate value-based reimbursement for diabetic foot procedures.
Industry Challenges
- Perioperative Nursing Shortage:Same-day surgical facilities compete with inpatient systems for PACU-trained RNs, extending case start delays.
- EHR Interoperability Fragmentation:Ambulatory networks struggle to integrate proprietary anesthesia information systems with hospital-based electronic records for seamless care transitions.
- Medical Malpractice Carrier Reticence:Insurers apply higher loss-cost multipliers to freestanding surgical facilities, elevating fixed cost burdens relative to hospital-affiliated centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bedless Hospitals Market |
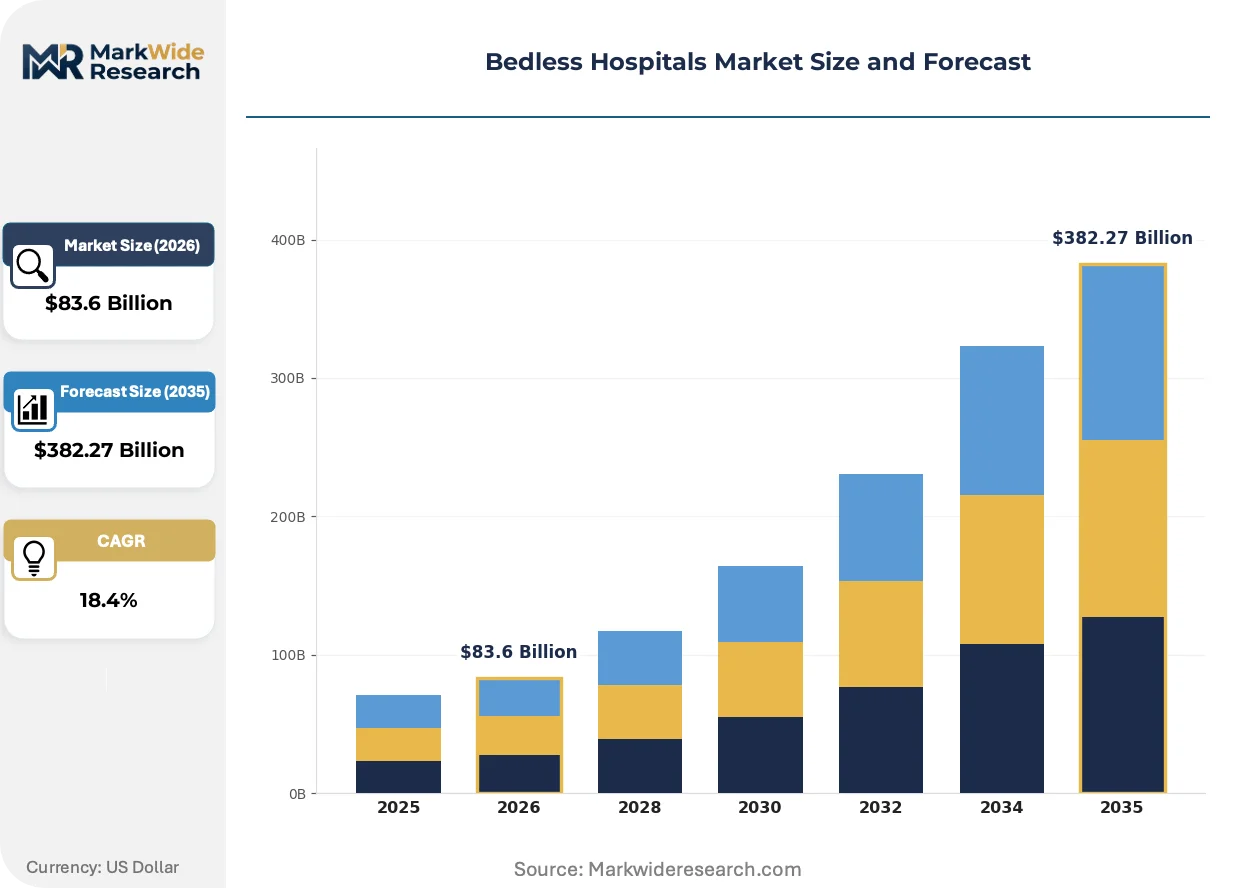
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $382.27 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Telemedicine, Outpatient Services, Remote Monitoring, Virtual Care Technology: Mobile Health, Wearable Devices, Online Portals, AI Diagnostics End User: Clinics, Healthcare Providers, Insurance Companies, Patients Delivery Mode: Home Care, Digital Platforms, Mobile Units, Consultation Services |
| Companies Covered | HCA Healthcare, Tenet Healthcare, Community Health Systems, Surgery Partners, AmSurg, UnitedHealth Group, Fresenius SE & Co. KGaA, Universal Health Services, Medical Facilities Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bedless Hospitals Market Strategic Shifts
Digital infrastructure is compressing the traditional inpatient episode into algorithmically managed ambulatory encounters, with three distinct vectors reshaping facility design and clinical workflow.
Ultrasound-guided regional anesthesia is supplanting general anesthesia protocols in orthopedic and gynecologic same-day procedures. Ambulatory surgery centers in Germany and Japan report 40% faster PACU discharge times using continuous catheter-based nerve blocks. This modality is supplanting volatile anesthetic consumption while reducing post-operative nausea rates that previously extended observation windows.
The EU AI Act's risk classification framework for medical device software is recalibrating development roadmaps for diagnostic algorithms. Developers must now document clinical validation datasets and post-market surveillance protocols before CE marking. German and French ambulatory networks are prioritizing lower-risk triage tools over diagnostic AI to accelerate deployment timelines.
Self-funded employers and Medicare Advantage plans are unbundling facility fees from professional fees in orthopedic bundled payments. Direct contracting between regional employers and multi-specialty ambulatory platforms is displacing traditional payer intermediation in Texas and Florida markets. This procurement evolution concentrates surgical volume in price-transparent networks that report outcomes to purchasing coalitions.
Bedless Hospitals Market Segmentation
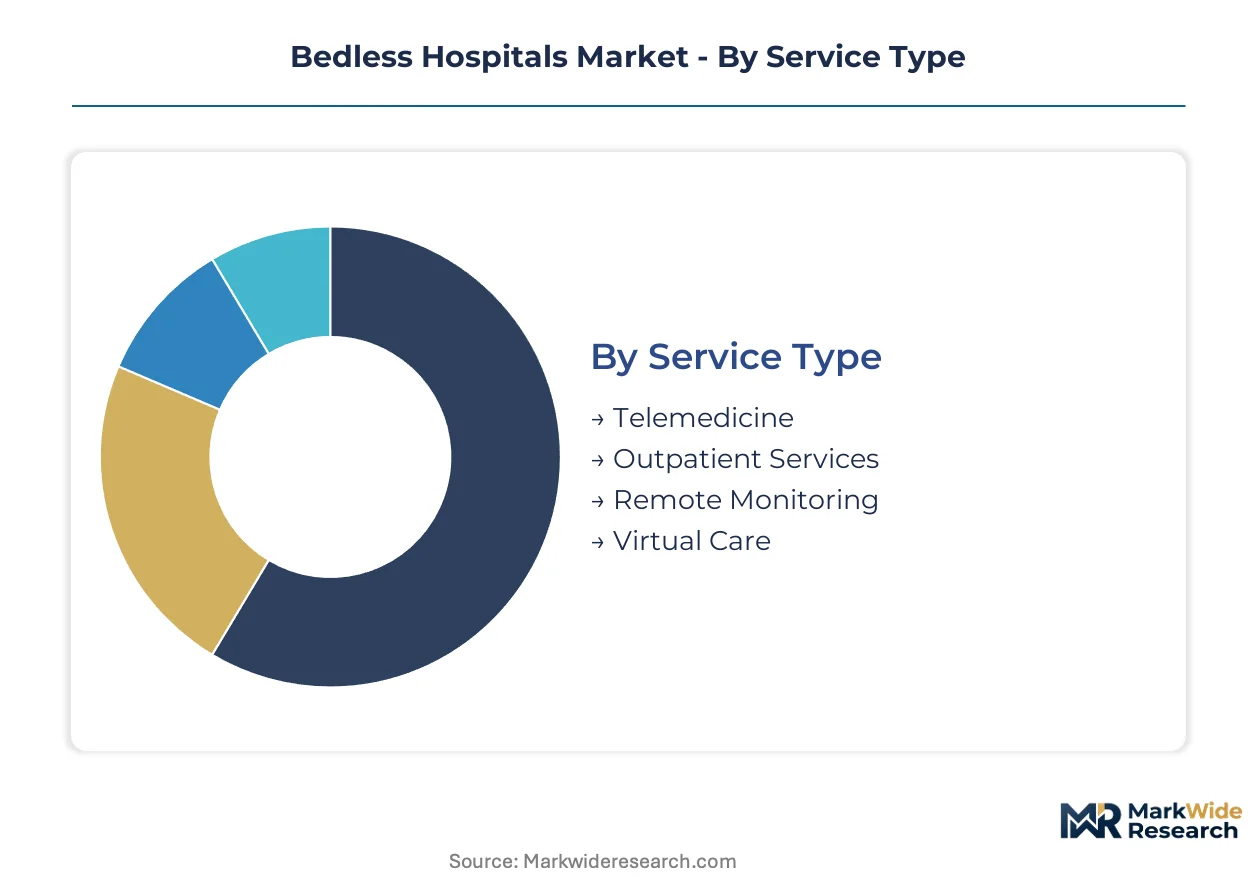
Bedless hospital operators configure service portfolios around reimbursement pathways and patient acuity thresholds. Segment selection determines capital allocation between physical ambulatory infrastructure and digital delivery platforms.
Service Type:
Substitution pressure from inpatient alternatives weighs most heavily on service categories with established hospital-based analogs, forcing ambulatory operators to differentiate on throughput efficiency and episode pricing.
- Telemedicine:Real-time video consultation platforms with asynchronous messaging integration. CMS reimbursement expansion for virtual visits concentrates demand in Medicare Advantage networks across Florida and Texas, though state-level parity laws create payment fragmentation.
- Outpatient Services:Same-day surgical and procedural encounters including arthroscopy, cataract extraction, and colonoscopy. HCA Healthcare and Surgery Partners compete on bundled episode pricing for orthopedic procedures in metropolitan corridors.
- Remote Monitoring:Continuous physiologic surveillance using cellular-enabled devices. Post-discharge cardiac monitoring contracts with Medicare Advantage plans drive volume in Arizona and Nevada retirement clusters.
- Virtual Care:Comprehensive digital-first primary care with integrated pharmacy and behavioral health. Employer direct contracting in California and Washington displaces traditional payer intermediation.
Outpatient Services anchors the volume base while Virtual Care gains share at the steepest rate.
Technology:
Technology segmentation stratifies by development maturity and regulatory clearance burden, with FDA 510(k) pathways filtering deployment timelines.
- Mobile Health:Smartphone-native applications for medication adherence and symptom tracking. Chronic disease management programs in Germany's statutory health insurance system drive adoption.
- Wearable Devices:Continuous glucose monitors, pulse oximeters, and ECG patches with cloud connectivity. Objective recovery metrics validate value-based reimbursement authorization from UnitedHealthcare and Aetna.
- Online Portals:Patient-facing platforms for scheduling, results access, and billing transparency. Required under HIPAA interoperability mandates, these systems struggle with EHR integration fragmentation.
- AI Diagnostics:Machine learning algorithms for pre-operative risk stratification and post-discharge anomaly detection. EU AI Act risk classification frameworks recalibrate development roadmaps for CE marking in France and Germany.
Wearable Devices anchors the volume base while AI Diagnostics climbs the fastest amid payer mandates for objective outcome metrics.
End User:
End user segmentation reflects procurement authority concentration and reimbursement risk allocation across the care continuum.
- Clinics:Independent and health system-affiliated ambulatory facilities performing same-day procedures. Rural Health Clinic conversion programs in the US Southeast offer retrofit potential for micro-surgical units.
- Healthcare Providers:Integrated delivery networks and physician groups managing episode-based contracts. Kaiser Permanente and Intermountain Healthcare deploy captive bedless capacity for total joint replacement bundles.
- Insurance Companies:Payers designing narrow networks and prior authorization protocols. Site-of-service policies at Cigna and Anthem steer cardiovascular procedures toward ambulatory settings.
- Patients:Direct-pay consumers seeking transparent pricing and convenience. Self-funded employer coalitions in Texas and Florida concentrate surgical volume in price-transparent networks.
Healthcare Providers anchors the volume base while Insurance Companies expand procurement influence through narrow network design.
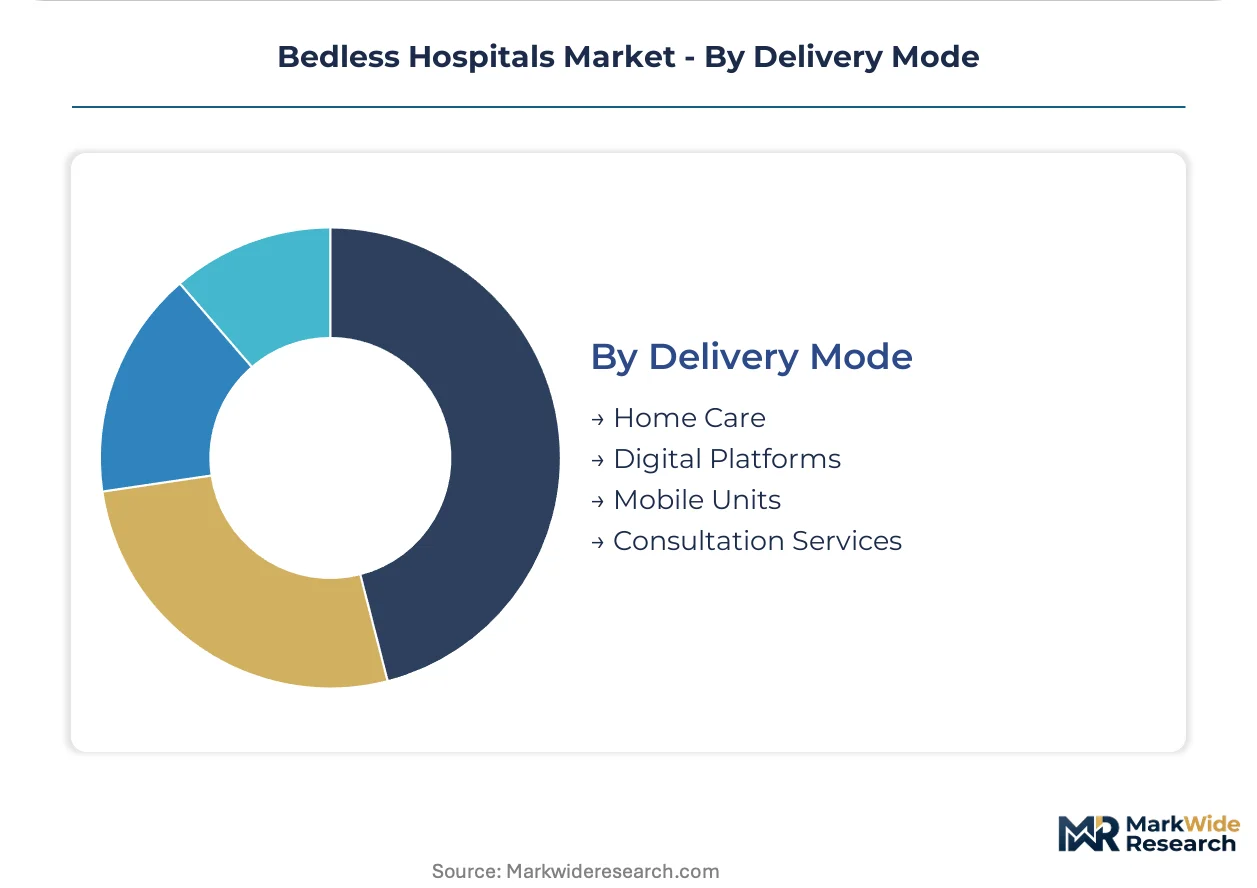
Delivery Mode:
Delivery mode segmentation tracks physical asset intensity and geographic reach, with capital-light models gaining favor amid labor shortages.
- Home Care:Infusion therapy, wound care, and post-surgical monitoring in residential settings. Hospital-at-home waivers from CMS during public health emergencies established reimbursement precedent.
- Digital Platforms:Cloud-native infrastructure enabling virtual consultation and asynchronous care. Japan's METI digital health infrastructure supports real-time post-discharge monitoring for urban ambulatory clusters.
- Mobile Units:Retrofitted vehicles delivering surgical and diagnostic services to underserved areas. Certificate-of-Need moratoriums in 35 US states limit expansion of fixed facilities, creating demand for deployable alternatives.
- Consultation Services:Specialist access programs connecting primary care with remote expertise. Telestroke and telepsychiatry networks in North Dakota and Alaska overcome specialist geographic concentration.
Digital Platforms anchors the volume base while Home Care shows the steepest expansion trajectory amid hospital-at-home reimbursement maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in healthcare services remain minimal given the non-tradable nature of clinical delivery, though capital equipment and digital health platforms flow from manufacturing hubs to installation sites across major ambulatory networks.
United States
CMS outpatient prospective payment system revisions pull orthopedic and cardiovascular procedures into ambulatory settings, compressing traditional inpatient revenue models. Certificate-of-Need moratoriums in 35 states block facility entry, protecting incumbent systems. Metropolitan corridors in Texas and Florida concentrate same-day surgical capacity under price-transparent bundled contracts with self-funded employers.
Germany
Statutory health insurance digitization mandates accelerate ambulatory network modernization across urban clusters. The EU AI Act's risk classification framework recalibrates development roadmaps for diagnostic algorithms seeking CE marking. Bavaria and Baden-Württemberg anchor surgical capacity expansion, with ultrasound-guided regional anesthesia protocols reducing PACU discharge times in orthopedic same-day procedures.
Japan
Aging demographics and hospital bed reduction targets concentrate demand in metropolitan ambulatory networks. METI digital health infrastructure investments enable real-time post-discharge monitoring for urban surgical clusters. Tokyo and Osaka prefectures deploy wearable-enabled recovery validation systems under revised long-term care insurance reimbursement schedules.
United Kingdom
NHS elective recovery targets accelerate independent sector capacity procurement for same-day surgical backlogs. Care Quality Commission registration pathways for standalone surgical facilities filter market entry by clinical governance standards. London and the Southeast concentrate private ambulatory investment, while Midlands networks retrofit underutilized primary care infrastructure.
India
Medical tourism corridors in Chennai and Hyderabad expand day-care surgical capacity for international patient flows. Ayushman Bharat digital health mission infrastructure supports telemedicine-enabled pre-operative assessment and post-discharge follow-up. Maharashtra and Karnataka dominate private ambulatory network formation, with corporate hospital chains franchising micro-surgical units to tier-2 cities.
Bedless Hospitals Market Competitive Environment
Concentration sits with multi-facility ambulatory operators and integrated delivery networks that command scale advantages in payer contracting. The competitive structure bifurcates between high-complexity outpatient operators pursuing acute-care certification and volume-focused same-day facilities competing on throughput efficiency. Strategic archetypes include captive surgery center networks, nephrology-specialized ambulatory platforms, and price-transparent multi-specialty operators. Dominant competitive moves encompass ambulatory footprint expansion through de novo development and strategic partnerships with physician groups for case volume capture.
Among US-based multi-facility operators, HCA Healthcare and Surgery Partners exemplify divergent positioning archetypes within the ambulatory surgical center segment. HCA Healthcare anchors metropolitan corridor concentration through captive facility networks, while Surgery Partners occupies a position emphasizing bundled episode pricing transparency across multi-specialty platforms. Fresenius SE & Co. KGaA represents the specialization-driven archetype, with its corporate structure reflecting European capital market access for healthcare infrastructure deployment.
| Leading Market Players |
|---|
| HCA Healthcare |
| Tenet Healthcare |
| Community Health Systems |
| Surgery Partners |
| AmSurg |
| UnitedHealth Group |
| Fresenius SE & Co. KGaA |
| Universal Health Services |
| Medical Facilities Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day procurement cycles for surgical robotics and AI diagnostic platforms concentrate vendor pricing power among three multinational suppliers, while ambulatory operators absorb cost pass-throughs through bundled episode contracts. This lead-time compression favors incumbent hospital-affiliated networks with captive purchasing scale over independent surgery centers negotiating spot terms.
Pricing Analysis
Healthcare providers anchor pricing structures around value-based episode bundles that consolidate facility, professional, and implant fees into single prospective payments. Three-tier pricing stratifies across academic medical center premiums, metropolitan corridor standards, and rural discount tiers, with CMS site-of-service parity narrowing spreads between inpatient and ambulatory rates. Cost compression in orthopedic device sourcing intensifies as implant oligopolists leverage sole-source agreements, while Medicare Advantage plans exhibit highest price sensitivity through narrow network exclusions and prior authorization density.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes extending inbound logistics for wearable monitors and telemedicine hardware creates inventory carrying cost pressure for US-based ambulatory networks. Manufacturing concentrates in China for consumer-grade biosensors, Germany for precision surgical instruments, and Ireland for pharmaceutical compounding, with component sourcing drawing from Taiwanese semiconductor foundries and South Korean battery cell producers. Single-source vulnerability in orthopedic implant supply elevates risk exposure, while distribution runs through group purchasing organizations consolidating procurement leverage for multi-facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perioperative nursing scarcity and anesthesiologist labor concentration in metropolitan corridors constrain same-day surgical throughput expansion, creating competitive advantage for operators that secure captive clinical workforce pipelines.
For Market Incumbents: Shield market position through backward integration into anesthesia staffing and PACU-trained nursing pipelines, while accelerating captive surgery center development in Certificate-of-Need moratorium states where regulatory barriers protect incumbent footprints from price competition. Investment in AI pre-operative risk stratification platforms reduces cancellation rates and optimizes block utilization against emerging volume-focused competitors. For New Entrants and Emerging Players: Lead with rural Health Clinic conversion programs in the US Southeast, where underutilized primary care infrastructure offers retrofit potential for micro-ambulatory surgical units serving Medicare Advantage populations with lower competitive density. Direct employer contracting in Texas and Florida bypasses traditional payer intermediation and concentrates surgical volume in price-transparent networks reporting outcomes to purchasing coalitions. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ambulatory network scale advantages in payer contracting favor multi-facility operators over standalone centers, with acquisition premiums flowing to platforms demonstrating proven episode cost reduction and quality metric validation. Watch for CMS site-neutral payment legislation advancement as the critical inflection signal compressing reimbursement differentials between hospital-affiliated and freestanding facilities.| Strategic Initiative | Industry Significance |
|---|---|
| CMS Reimbursement Strategy | Site-of-service policy alignment with outpatient prospective payment system revisions secures procedure volume migration from inpatient towers. |
| Hospital System Partnership | Captive referral agreements with integrated delivery networks anchor case volume and reduce patient acquisition cost. |
| Software Companion Development | FDA 510(k) clearance for AI diagnostic platforms enables pre-operative risk stratification and post-discharge anomaly detection services. |
| CE Marking Pathway | EU MDR software-as-medical-device compliance accelerates European ambulatory network deployment for diagnostic algorithms. |
| Wearable Integration Program | Objective recovery metrics from continuous monitoring devices validate value-based reimbursement authorization from UnitedHealthcare and Aetna. |
Study Parameters
Desk research of CMS reimbursement databases, FDA 510(k) clearance records, and state-level Certificate-of-Need filings preceded structured interviews with ambulatory surgery center executives, anesthesiology group administrators, GPO contracts managers, and Medicare Advantage plan network directors. Secondary validation drew from hospital procurement databases, SEC healthcare facility filings, and EU MDR regulatory submissions, with bottom-up facility capacity modeling triangulated against top-down payer expenditure analysis.
Variance decomposition across service type, technology platform, and delivery mode segments structured the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves modeling ambulatory procedure migration rates, with inputs including CMS outpatient claims data, wearable device adoption curves, and AI diagnostic regulatory clearance timelines by FDA and notified bodies.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement parity, anesthesiologist labor supply stability, or implant vendor pricing discipline would require recalibration. Forecasts reflect documented assumptions around site-of-service policy continuity and value-based contracting penetration rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
Global Healthcare Architecture Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market
Healthcare Facilities
Private Office-Based Clinics Market