
 US Hospital Facilities Market | 2026-2036
US Hospital Facilities Market Size, Share, and Industry Trends Forecast 2026-2036
US Hospital Facilities Market Intelligence
Tax-exempt municipal bond financing is reshaping how nonprofit hospital systems fund campus expansions without diluting equity. HCA Healthcare leverages its investment-grade balance sheet to sustain aggressive bed-count growth across Sun Belt markets. Kaiser Permanente anchors its competitive position through integrated insurance-hospital operations that control patient flow from premium collection to procedure.
US hospital facilities encompass inpatient and outpatient physical infrastructure designed for acute care delivery, typically incorporating HVAC systems maintaining 15-20 air changes per hour in operating suites, specialized power redundancy for life-support equipment, and modular wall systems supporting rapid room reconfiguration. Patient rooms and intensive care units occupy the largest share of construction spending as aging infrastructure requires seismic retrofitting and private-room conversion. Operating rooms represent the fastest-growing segment as robotic-assisted surgery demands larger footprints, integrated imaging suites, and advanced sterilization infrastructure.
FDA device clearance pathways shape capital equipment procurement timelines, while CMS Conditions of Participation dictate minimum physical plant standards for Medicare reimbursement eligibility. Joint Commission accreditation requirements further constrain facility design choices, particularly around infection control and patient safety systems. Stakeholders must monitor how CMS site-neutral payment policies redirect capital toward outpatient surgical centers rather than traditional inpatient towers.
Market Dynamics
CMS site-neutral payment policies are redirecting capital away from inpatient towers toward outpatient surgical centers, compressing traditional hospital construction timelines while accelerating ambulatory facility deployment across Sun Belt metropolitan corridors.
Growth Catalysts
- Specialty surgical migration:Ambulatory surgery centers are capturing complex orthopedic and cardiovascular procedures previously requiring overnight stays, drawing institutional investment into freestanding facilities equipped for same-day discharge protocols.
- IRA capital incentives:The Inflation Reduction Act's clean energy tax credits are subsidizing geothermal HVAC retrofits and solar microgrids for hospital campuses seeking operational cost reduction alongside carbon compliance.
- Sun Belt demographic pressure:Texas, Florida, and Arizona are absorbing disproportionate Medicare-eligible population inflows, forcing health systems to accelerate bed-count expansion ahead of infrastructure capacity thresholds.
Market Restraints
- Construction cost volatility:Steel and copper price fluctuations are squeezing project margins for seismic retrofitting and private-room conversion programs, particularly in California and Pacific Northwest markets with stringent building codes.
- Skilled labor scarcity:Certified healthcare construction specialists—particularly those qualified for operating suite HVAC and medical gas installation—are concentrating in Dallas-Fort Worth and Phoenix, leaving secondary markets exposed to 18-24 month contractor backlogs.
- CMS reimbursement compression:Site-neutral payment parity between hospital outpatient departments and independent surgery centers is eroding the revenue premium that historically justified inpatient facility investment.
Strategic Opportunities
- Microhospital penetration:Eight-to-ten bed acute care satellites are opening in Texas exurbs and Arizona retirement corridors, capturing emergency volume without full-scale hospital capital deployment.
- Modular construction adoption:Prefabricated patient room pods and operating suite cores are compressing construction schedules by 30-40% for systems facing compressed certificate-of-need windows.
- Medicare Advantage channel capture:Integrated delivery networks are securing exclusive or preferred facility access through risk-based contracting with MA plans, locking in patient flow before competitors complete comparable infrastructure.
Industry Challenges
- Interoperability friction:Legacy building management systems are resisting integration with new IoT-enabled HVAC and power monitoring platforms, forcing parallel infrastructure runs during phased campus renovation.
- Joint Commission compliance lag:Infection control ventilation standards for operating suites are outpacing installed base capabilities, requiring costly ductwork and air handling unit replacements mid-construction cycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hospital Facilities Market |
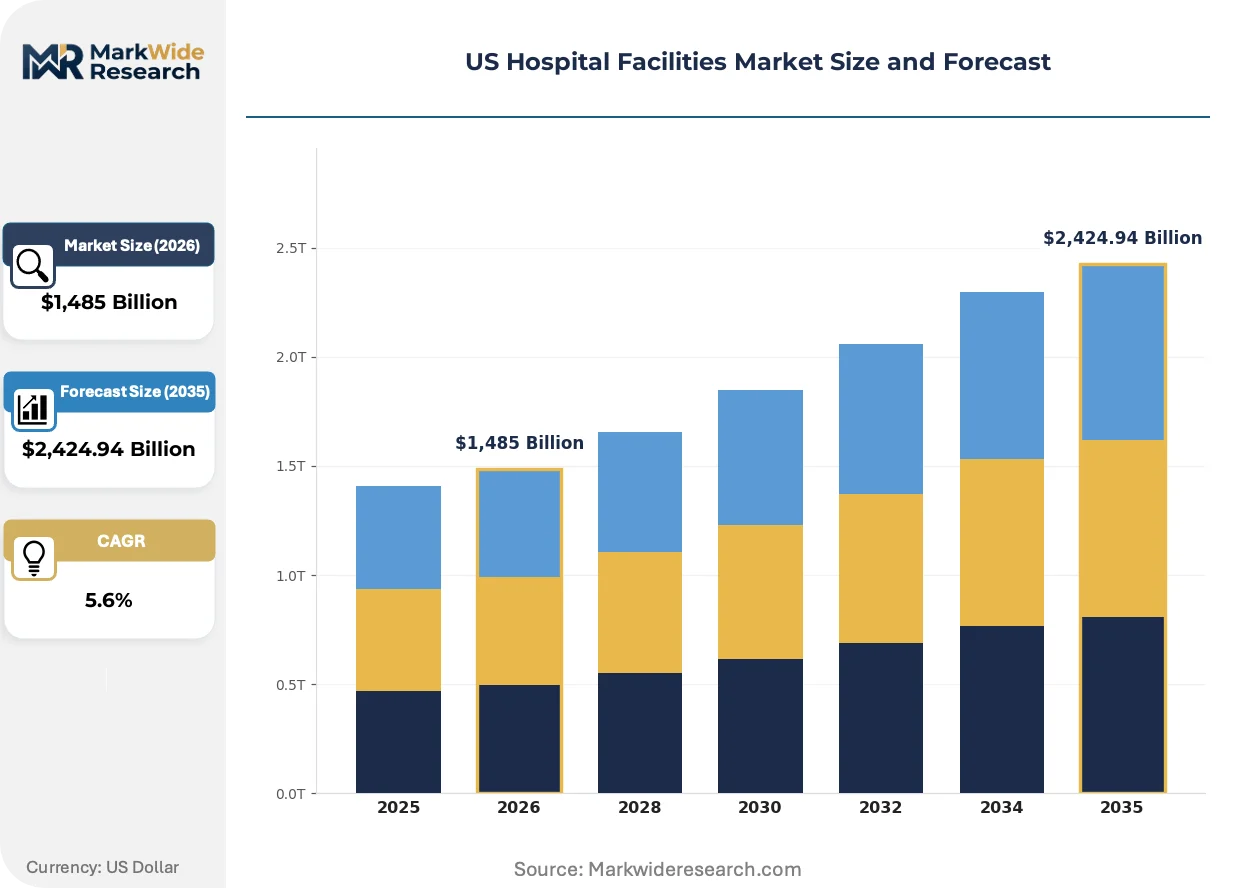
| Market Size in 2026 | $1,485 Billion |
| Market Size in 2035 | $2,424.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Rooms, Operating Rooms, Emergency Departments, Intensive Care Units Technology: Telemedicine, Robotics, Electronic Health Records, Medical Imaging End User: Public Hospitals, Private Hospitals, Specialty Clinics, Rehabilitation Centers Facility Size: Small, Medium, Large, Academic Medical Centers |
| Companies Covered | Ascension Health, Kaiser Permanente, HCA Healthcare, Advocate Health, Providence, Universal Health Services, Trinity Health, Tenet Healthcare, CommonSpirit Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hospital Facilities Market Strategic Shifts & Innovations
Digital infrastructure is penetrating physical plant operations, converting hospitals from static concrete assets into adaptive environments responsive to real-time patient flow, energy pricing, and clinical protocol demands.
Building information modeling combined with digital twin platforms is digitizing facility lifecycle management from design through decommissioning. Health systems including Kaiser Permanente and HCA Healthcare are deploying these tools across Sun Belt expansion projects, compressing change-order cycles and enabling predictive maintenance scheduling that extends mechanical system replacement intervals by 15-20%.
FDA 510(k) clearance pathways for surgical robotics are pressuring operating room footprint standards, as da Vinci and competing platforms demand 600-800 square foot suites with integrated imaging booms and specialized power conditioning. CMS Conditions of Participation have not kept pace, creating jurisdictional friction between federal equipment regulation and facility licensing requirements that delays project completion in multiple states.
Certificate-of-need program suspension in Florida and Texas is accelerating competitor entry, fragmenting patient volume across more facilities than historical utilization models projected. Health systems are responding with smaller, more numerous microhospitals rather than centralized campus expansion, betting on convenience-driven site selection over traditional referral network density.
US Hospital Facilities Market Segmentation
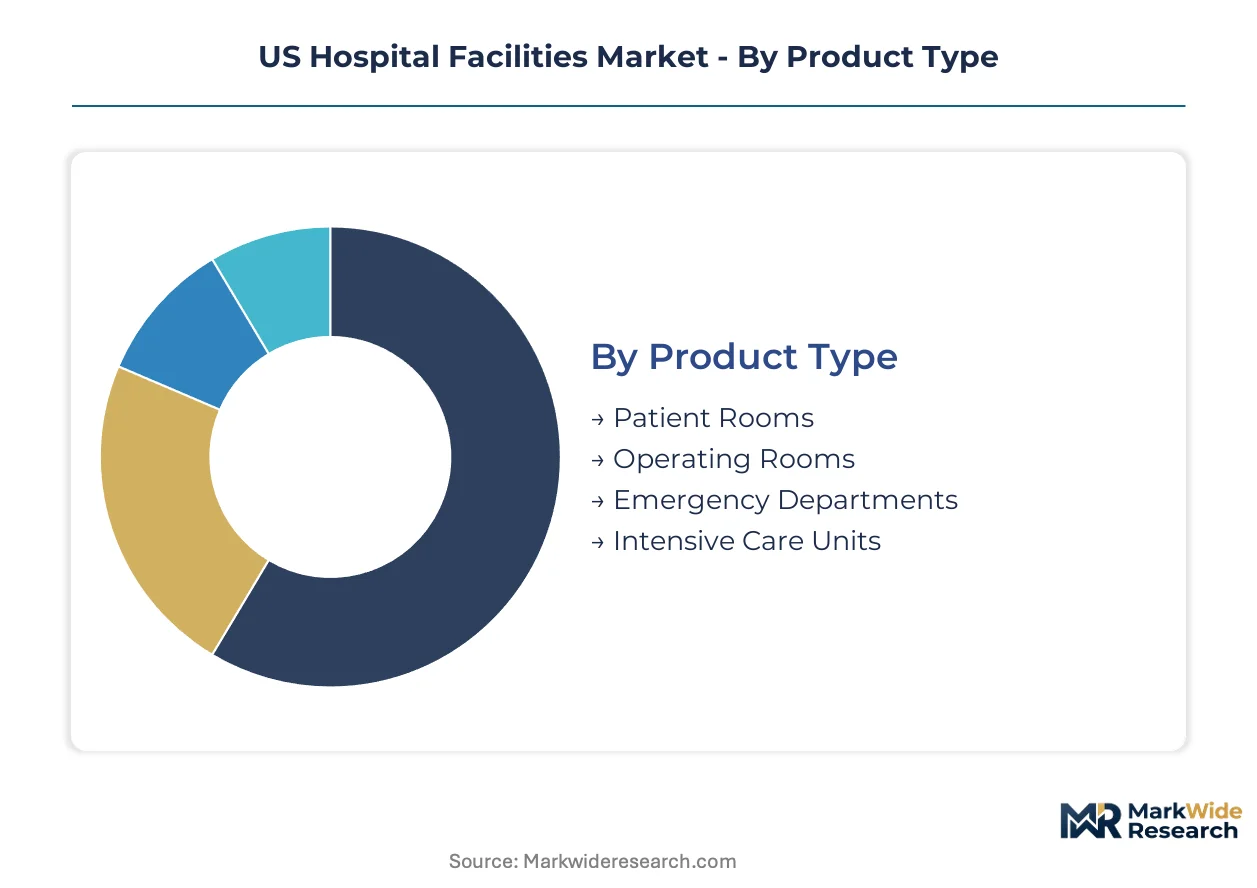
Facility segmentation reveals divergent capital deployment cycles across the US hospital infrastructure base. Construction timelines, technology refresh rates, and reimbursement exposure vary dramatically by segment, forcing health systems to sequence investments strategically rather than uniformly.
Product Type:
Operating rooms turn over fastest at 10-15 year cycles as surgical technology evolves, while patient rooms and emergency departments operate on 25-40 year replacement horizons driven by seismic codes and demographic pressure.
- Patient Rooms:Private-room configurations now dominate new construction, requiring 35-40% larger footprints than legacy semi-private layouts to accommodate family zones and bariatric capacity. Demand concentrates in Texas and Florida health systems converting aging stock as Medicare Advantage penetration shifts length-of-stay expectations.
- Operating Rooms:Robotic-assisted surgery platforms demand 600-800 square foot suites with integrated imaging booms, specialized power conditioning, and HVAC systems maintaining 20+ air changes per hour. Sun Belt systems including HCA Healthcare are expanding these at twice the rate of other infrastructure categories.
- Emergency Departments:Behavioral health integration and surge capacity protocols are driving 40% footprint expansion in new builds.
- Intensive Care Units:Negative pressure isolation capability and tele-ICU infrastructure are becoming standard in ICU renovations.
Patient rooms anchor the volume base while operating rooms gain share at the steepest rate.
Technology:
Capital intensity stratifies sharply across technology categories, with medical imaging and robotics requiring dedicated structural support while telemedicine and EHR deployments leverage existing network infrastructure.
- Telemedicine:Virtual care platforms are compressing physical facility requirements for routine consultations, enabling microhospital formats with reduced square footage per encounter. Arizona and Texas systems deploy these most aggressively in retirement corridor locations.
- Robotics:Surgical robotics demand reinforced flooring, expanded electrical service, and sterile supply workflows that extend construction timelines by 6-12 months compared to conventional OR builds.
- Electronic Health Records:EHR integration now dictates building management system architecture for new construction.
- Medical Imaging:MRI and CT suites require specialized shielding and cryogenic infrastructure with 30-year depreciation schedules.
Medical imaging carries the heaviest capital burden per square foot while telemedicine expands most quickly into existing facility footprints.
End User:
Ownership structure determines financing flexibility and reimbursement exposure, with private systems accessing tax-exempt municipal bonds and public hospitals navigating certificate-of-need constraints.
- Private Hospitals:Investment-grade balance sheets enable aggressive Sun Belt expansion through taxable and tax-exempt debt issuance without equity dilution. HCA Healthcare and Kaiser Permanente anchor this segment with integrated insurance operations that control patient flow from premium collection through procedure.
- Public Hospitals:County and state-owned facilities face political budget cycles and CON program requirements that compress construction windows and limit technology refresh frequency.
- Specialty Clinics:Ambulatory surgery centers and orthopedic specialty facilities are capturing complex procedures previously requiring inpatient admission.
- Rehabilitation Centers:Post-acute facilities face site-neutral payment compression that constrains new construction despite demographic tailwinds.
Private hospitals command the capital access advantage while specialty clinics climb the fastest as CMS reimbursement shifts toward outpatient settings.
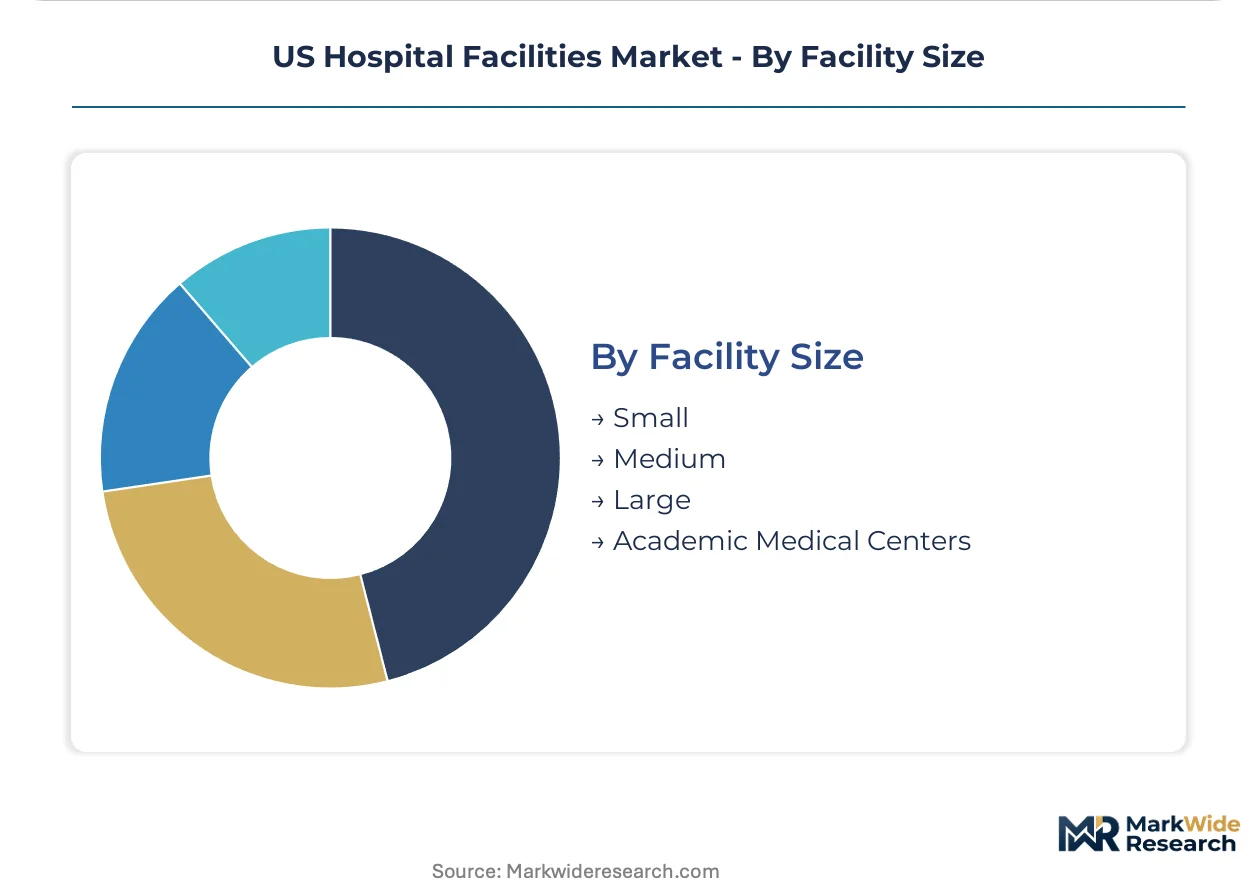
Facility Size:
Scale determines regulatory scrutiny intensity and technology deployment feasibility, with academic medical centers navigating the most complex Joint Commission and CMS Conditions of Participation requirements.
- Academic Medical Centers:Research integration, residency programs, and Level I trauma designation demand specialized infrastructure including biosafety labs, simulation centers, and helicopter landing facilities that extend construction timelines and cost profiles substantially beyond community hospital benchmarks.
- Large Hospitals:Systems with 400+ beds are consolidating service lines and repurposing inpatient towers as outpatient volume migrates to ambulatory settings.
- Medium Hospitals:150-400 bed facilities face the most acute competitive pressure from microhospital entrants.
- Small Hospitals:Rural and critical access hospitals are converting to emergency-only or microhospital formats as inpatient volume erodes.
Academic medical centers anchor the high-complexity referral base while microhospital formats within the small category are expanding most quickly across Texas exurbs and Arizona retirement corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks concentrate capital deployment in states where Medicare Advantage penetration and population growth create simultaneous demand pressure. Texas, Florida, and Arizona absorb disproportionate infrastructure investment as health systems race to capture migrating patient volume.
Texas
Texas health systems face acute bed-count shortages as Dallas-Fort Worth and Houston metro areas absorb net migration exceeding national averages. Certificate-of-need program suspension under state law accelerates competitor entry, fragmenting projected utilization across more facilities than historical models assumed. HCA Healthcare anchors aggressive expansion in San Antonio and Austin exurbs with microhospital formats.
Florida
Florida's retirement corridor demographics drive emergency department volume growth that outpaces national benchmarks. CMS site-neutral payment policies redirect capital toward ambulatory surgery centers in Tampa and Orlando metropolitan statistical areas. Tenet Healthcare and Universal Health Services concentrate freestanding facility deployment along I-4 and I-75 corridors.
Arizona
Arizona's Phoenix-Tucson corridor experiences construction backlog compression as certified healthcare contractors concentrate in competing Sun Belt markets. IRA clean energy tax credits subsidize geothermal HVAC retrofits for Banner Health and HonorHealth campus expansions. Modular construction adoption accelerates to circumvent 18-month contractor wait times.
California
California seismic retrofitting mandates and stringent building codes extend construction timelines for Kaiser Permanente and Sutter Health campus renovations. Skilled labor scarcity concentrates certified specialists in Los Angeles and San Francisco Bay Area markets, leaving Central Valley and Inland Empire projects exposed to cost volatility. Joint Commission infection control standards outpace installed base capabilities.
Illinois
Illinois health systems navigate Cook County certificate-of-need constraints while Advocate Health and CommonSpirit Health repurpose inpatient towers for outpatient service line consolidation. Chicago metropolitan area academic medical centers absorb disproportionate Medicaid and uninsured volume, compressing capital flexibility for facility modernization.
US Hospital Facilities Market Key Industry Players
Channel-controlling players compete with product-specialist players across distinct strategic vectors. The market structure consolidates around integrated delivery networks with insurance operations and fragments among standalone hospital operators and ambulatory surgery center chains. Three archetypes dominate: vertically integrated payer-provider systems, investment-grade for-profit chains, and faith-based nonprofit consortia. M&A activity accelerates as systems seek geographic density, while modular construction partnerships compress facility deployment timelines.
Among investment-grade for-profit operators, HCA Healthcare and Universal Health Services occupy positions emphasizing scale-driven Sun Belt expansion. Kaiser Permanente exemplifies the integrated payer-provider archetype with captive patient flow from premium collection through procedure. Faith-based nonprofit systems including Ascension Health and Trinity Health represent consolidation-focused operators navigating municipal bond financing for campus modernization without equity dilution.
| Leading Market Players |
|---|
| Ascension Health |
| Kaiser Permanente |
| HCA Healthcare |
| Advocate Health |
| Providence |
| Universal Health Services |
| Trinity Health |
| Tenet Healthcare |
| CommonSpirit Health |
| Others |
Cost & Logistics Intelligence
Steel and copper price volatility functions as the primary risk vector, compressing project margins for seismic retrofitting and private-room conversions while simultaneously forcing health systems toward modular construction alternatives that reshape traditional procurement relationships.
Pricing Analysis
Cost-plus contracts with producer price indexation dominate hospital construction procurement, embedding raw material escalators that transfer commodity risk from contractors to health systems. Price differentiation separates integrated delivery networks with captive insurance operations from standalone hospital operators lacking volume leverage. CMS site-neutral payment parity is intensifying cost compression across inpatient facility tiers. Standalone rural hospitals exhibit the highest price sensitivity, while Kaiser Permanente and HCA Healthcare anchor the least sensitive segment through captive patient flow control.
Supply Chain Analysis
Healthcare construction specialty contractors concentrate capacity in Dallas-Fort Worth and Phoenix, leaving secondary Sun Belt markets exposed to 18-24 month backlogs. Steel fabrication draws from domestic mills in Indiana and Ohio, while HVAC equipment sources from Mexico and China. Single-source vulnerability concentrates in certified medical gas installation crews. Distribution runs through regional healthcare construction consortiums that pre-qualify contractors for Joint Commission-compliant work.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility lifecycle services represent the fastest-expanding revenue layer, with predictive maintenance contracts and digital twin subscriptions outpacing hardware deployment growth as health systems prioritize operational cost reduction over capital expansion.
For Market Incumbents: Entrench Sun Belt market position through exclusive Medicare Advantage risk contracting that locks patient volume before competitor microhospital completion. Accelerate modular construction partnerships to compress deployment timelines against certificate-of-need windows. Defensive consolidation of ambulatory surgery center networks counters reimbursement migration threats. For New Entrants and Emerging Players: Texas exurbs and Arizona retirement corridors with suspended CON programs represent the most penetrable entry points for eight-to-ten bed microhospital formats. Specialty surgical migration toward outpatient settings creates white-space in freestanding cardiovascular and orthopedic facilities. Go-to-market positioning through risk-based MA plan partnerships secures volume commitment ahead of construction completion. For Investors and Strategic Acquirers: IRA clean energy tax credit expiration reshapes the acquisition landscape toward health systems with completed geothermal HVAC retrofits and solar microgrid deployment. Long-term viability centers on integrated payer-provider architectures controlling patient flow from premium collection through procedure. Monitor CMS site-neutral payment expansion as the critical inflection signal for inpatient facility valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Medicare Advantage Risk Contracting | Exclusive MA plan partnerships lock patient volume before competitor facility completion. |
| Modular Construction Adoption | Prefabricated patient pods compress schedules by 30-40% for CON-constrained systems. |
| Digital Twin Platform Deployment | Kaiser Permanente and HCA Healthcare extend mechanical system replacement intervals through predictive maintenance. |
| IRA Clean Energy Retrofit | Geothermal HVAC and solar microgrids reduce operational costs while securing carbon compliance. |
| Ambulatory Surgery Center Acquisition | Freestanding facility networks capture complex procedures migrating from inpatient settings. |
Research Approach
Findings reconcile primary fieldwork against secondary review of CMS reimbursement databases, hospital procurement records, and municipal bond issuance filings. Interviews with health system capital planning executives, healthcare construction contractors, biomedical engineers, and GPO contracts managers informed demand-side validation. SEC 10-K disclosures from publicly traded hospital operators and trade data from the Associated General Contractors supplemented supply-side characterization. Bottom-up project pipeline analysis triangulates against top-down Medicare expenditure forecasting.
Forecast inputs incorporate bed-count expansion plans, certificate-of-need program status by state, and Medicare Advantage penetration trajectories across the projection horizon. Segmentation modeling spans facility type, technology deployment, ownership structure, and scale tier. CAGRs derive from facility construction spend velocity indexed to demographic migration patterns and reimbursement policy shifts. IRA tax credit utilization rates and modular construction adoption curves inform cost trajectory assumptions.
Macroeconomic conditions sit as an overlay; deviation in construction labor availability, steel and copper pricing, or interest rate movements would shift the trajectory. Forecasts embed assumptions regarding CMS site-neutral payment expansion pace and CON program continuity. Quarterly review of hospital construction backlog indices, contractor capacity utilization, and MA plan risk contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market
Healthcare Facilities
Global Healthcare Architecture Market
Healthcare Facilities
Bedless Hospitals Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
US and Europe Ambulatory Surgery Centers Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
Qatar Senior Living Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
US Ambulatory Surgery Centers Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market