
 India Anesthesia Devices Market | 2026-2036
India Anesthesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Anesthesia Devices Market Foresight
Anesthesiologist workforce expansion in secondary cities is unwinding capacity bottlenecks that previously limited surgical throughput. Medion Healthcare Pvt. Ltd leverages its domestic manufacturing footprint to compete on cost in government tenders across northern and central India. B. Braun Medical anchors premium segment positioning through specialized anesthesia workstation configurations for cardiac and neurosurgical suites. Shenzhen Mindray Bio-Medical Electronics extends its presence by controlling distribution networks in tier-II hospital markets where price sensitivity shapes procurement decisions.
Anesthesia devices encompass mechanical and electronic systems designed to deliver precise mixtures of anesthetic gases and vapors while monitoring patient vital parameters including oxygen saturation, end-tidal carbon dioxide, and inhalational agent concentrations during surgical procedures. These systems integrate vaporizers, breathing circuits, and monitoring modules to maintain controlled unconsciousness and analgesia across operative settings. Anesthesia machines dominate capital expenditure budgets due to replacement cycles tied to technology upgrades and safety standard revisions. Disposable devices within the product offering dimension capture recurring revenue streams as infection control protocols intensify single-use preferences in hospitals and surgery centers. Integrated systems technology is gaining fastest as clinicians seek unified platforms combining gas delivery, ventilation, and hemodynamic monitoring.
CDSCO enforces the Medical Devices Rules requiring registration and quality management system certification for anesthesia equipment marketed in India, while BIS standards specify electrical safety and performance parameters for electromedical devices. The PLI scheme for medical devices creates fiscal incentives that shape domestic manufacturing investment decisions among both established players and emerging competitors. Stakeholders must monitor how state-level public health mission expansions alter procurement specifications and tender structures for anesthesia infrastructure.
Market Dynamics
Surgical capacity expansion across Tier-II and Tier-III Indian cities is restructuring demand patterns for anesthesia infrastructure, as secondary hospitals upgrade from basic delivery systems to integrated workstation platforms.
Growth Catalysts
- CDSCO Medical Devices Rules:Mandatory quality certification for imported and domestically manufactured equipment is elevating baseline safety standards and accelerating replacement cycles in tertiary care centers.
- Cardiac and neurosurgical suites:Specialized anesthesia workstation configurations are penetrating corporate hospital chains in Maharashtra, Karnataka, and Tamil Nadu where complex procedures concentrate.
- PLI scheme for medical devices:Fiscal incentives under India's production-linked incentive framework are redirecting capital toward domestic manufacturing footprints for anesthesia equipment.
Market Restraints
- Critical component import dependency:Precision vaporizers and advanced monitoring sensors rely on concentrated East Asian supply sources, exposing procurement timelines to geopolitical friction.
- Anesthesiologist workforce scarcity:Specialist training pipeline limitations in secondary cities constrain surgical throughput regardless of equipment availability.
- Capital intensity of integrated systems:Unified platform upgrades require substantial upfront expenditure that strains district hospital budgets under state public health missions.
Strategic Opportunities
- Uttar Pradesh and Bihar expansion corridors:Underpenetrated northern and eastern state hospital networks present whitespace for mid-range workstation deployment as surgical infrastructure scales.
- Remote monitoring convergence:Integration of anesthesia delivery platforms with tele-ICU networks enables specialist oversight across distributed surgical sites.
- State-level public health mission tenders:Evolving procurement specifications under Ayushman Bharat and similar programs create entry points for domestic manufacturers meeting BIS electrical safety standards.
Industry Challenges
- Bio-medical engineer staffing gaps:Preventive maintenance and calibration of complex vaporizer and ventilation modules outpaces available technical workforce in Tier-III facilities.
- CDSCO registration timelines:Extended quality management system certification cycles delay market entry for novel anesthesia monitoring technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Anesthesia Devices Market |
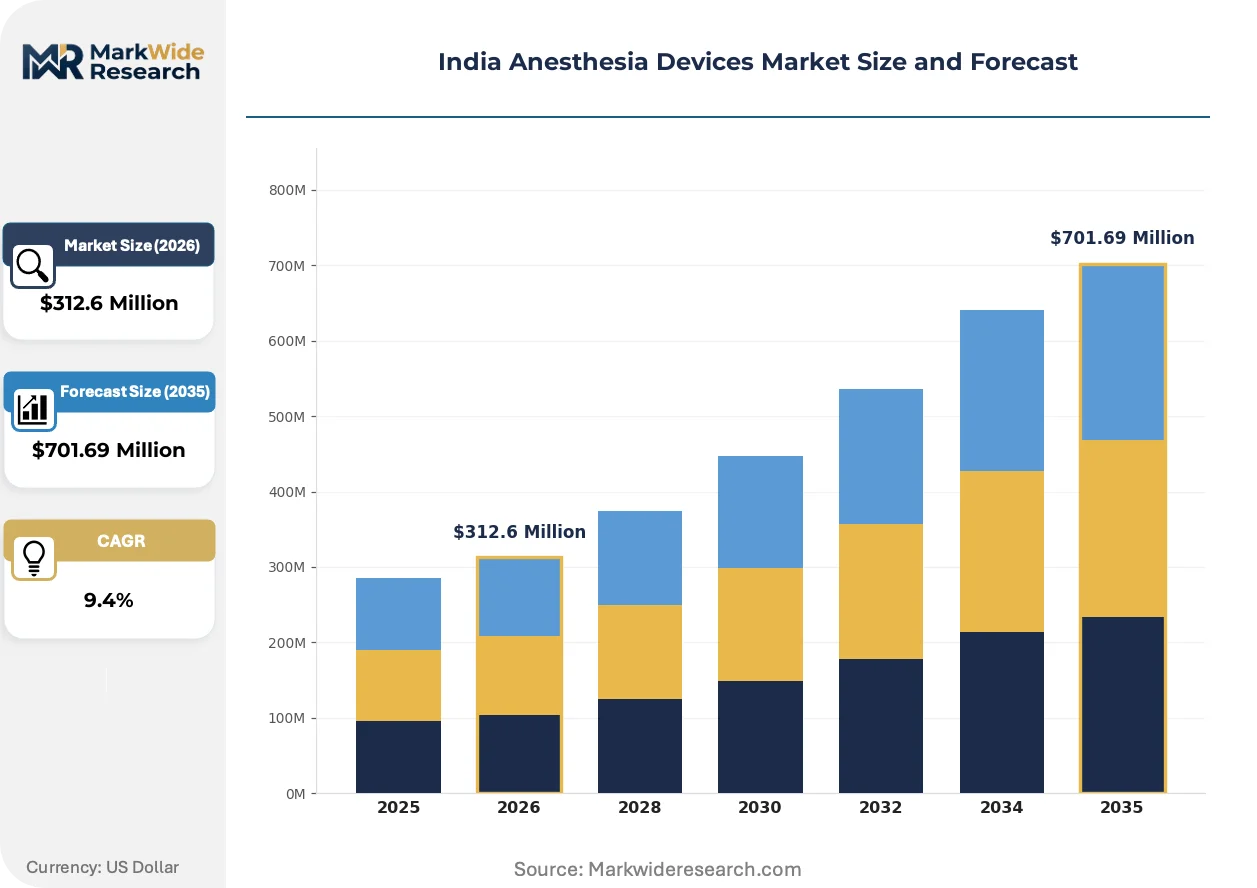
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $701.69 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Anesthesia Machines, Vaporizers, Monitoring Devices, Breathing Circuits End User: Hospitals, Surgery Centers, Physician Offices, Emergency Departments Product Offering: Disposable Devices, Reusable Devices, Accessories, Software Solutions Technology: Electronic, Mechanical, Integrated Systems, Others |
| Companies Covered | Medion Healthcare Pvt. Ltd, Terumo Corporation, Becton, Dickinson and Company, Baxter International Inc., Nihon Kohden Corporation, B. Braun Medical, Ontex Medical Devices Manufacturing Pvt. Ltd, Shenzhen Mindray Bio-Medical Electronics, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Anesthesia Devices Market Shifts & Advancements
Technology trajectories in Indian anesthesia devices are compressing the functional gap between premium cardiac-suite configurations and standard operating theater platforms, while regulatory pressure and procurement evolution reshape competitive positioning.
Integrated anesthesia workstations combining gas delivery, mechanical ventilation, and multi-parameter hemodynamic monitoring are bifurcating the installed base. Corporate hospital chains in Mumbai, Bangalore, and Chennai are adopting these unified platforms at accelerated replacement cycles. The technology is bifurcating procurement patterns into high-complexity integrated suites versus modular upgrade paths for budget-constrained facilities.
CDSCO enforcement of Medical Devices Rules registration requirements is tightening quality management system mandates for both imported and domestically manufactured anesthesia equipment. Manufacturers must now demonstrate compliance with specified electrical safety and performance parameters before market authorization. Imported workstation configurations face extended documentation scrutiny while domestic producers leverage PLI scheme incentives to accelerate certification readiness.
State-level tender structures under public health mission expansions are consolidating purchase authority away from individual hospital procurement committees. Bulk anesthesia equipment acquisition through centralized medical services corporations in Maharashtra, Karnataka, and Tamil Nadu is displacing fragmented purchasing. District hospitals in these states now access standardized workstation specifications through framework contracts rather than independent vendor negotiations.
India Anesthesia Devices Market Segmentation
Anesthesia device procurement in India fragments across clinical settings and technology tiers, with substitution dynamics between disposable and reusable formats reshaping vendor strategies. Understanding segment boundaries clarifies where CDSCO certification requirements and PLI scheme incentives create divergent margin structures for domestic versus imported equipment.
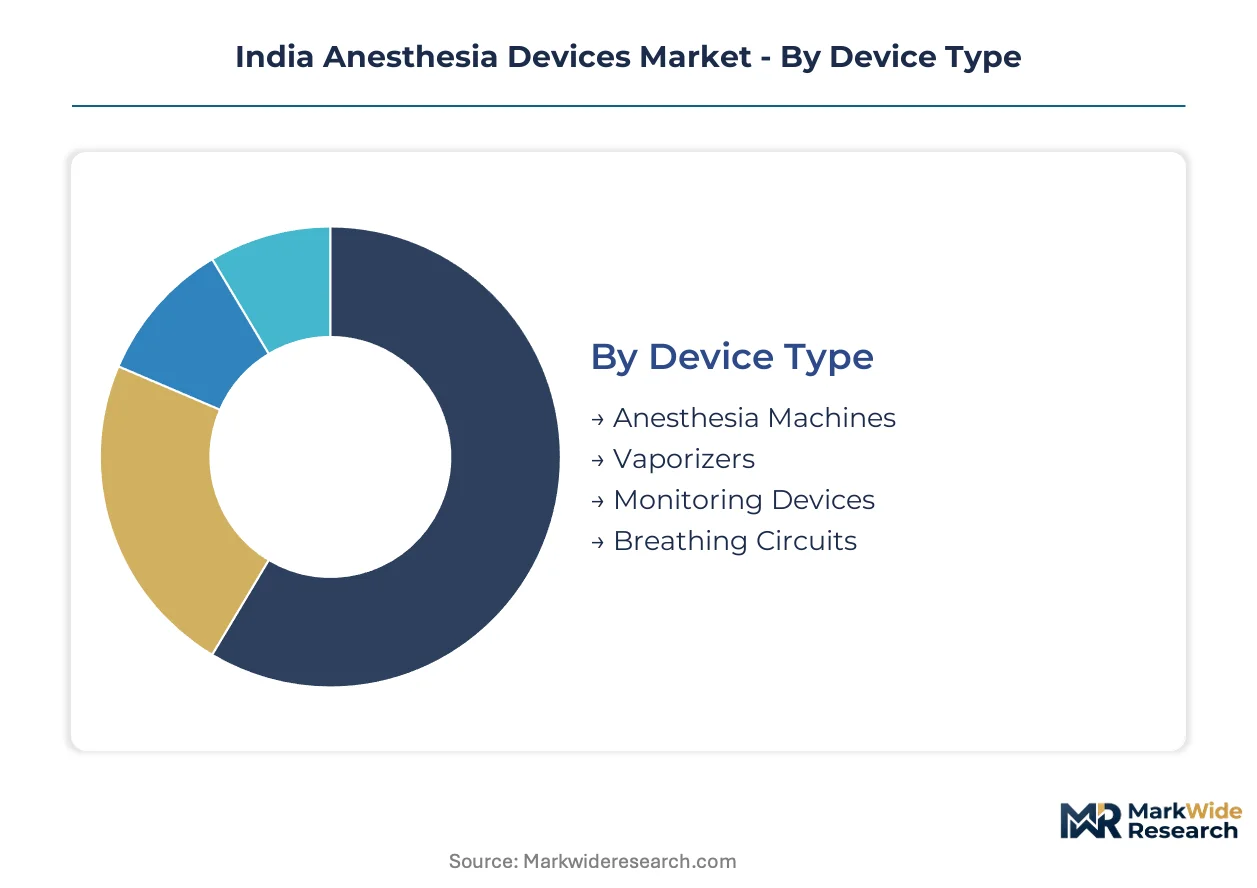
Device Type:
Substitution pressure runs strongest against standalone vaporizers and basic breathing circuits as integrated workstation platforms absorb their discrete functions into unified delivery systems.
- Anesthesia Machines:These systems integrate gas delivery, ventilation, and agent vaporization into centralized platforms with touchscreen interfaces and automated record-keeping. Corporate hospital chains in Maharashtra and Karnataka are consolidating procurement around these units as CDSCO mandates elevate baseline safety specifications and accelerate replacement cycles in tertiary care centers.
- Vaporizers:Precision temperature-compensated units deliver calibrated concentrations of volatile anesthetic agents. Demand concentrates in standalone configurations for budget-constrained district hospitals in Uttar Pradesh and Bihar where modular upgrade paths postpone full workstation investments.
- Monitoring Devices:Multi-parameter modules track oxygen saturation, end-tidal carbon dioxide, and inhalational agent concentrations.
- Breathing Circuits:Disposable and reusable configurations connect patients to anesthesia delivery systems.
Anesthesia machines retain volume leadership; integrated systems technology holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive hospital procurement from the lean equipment profiles dominating physician office settings.
- Hospitals:Tertiary and secondary facilities drive capital expenditure through technology upgrade cycles tied to CDSCO safety standard revisions. Tier-II city hospitals in Tamil Nadu are expanding surgical capacity and driving procurement of anesthesia workstations as anesthesiologist workforce expansion unwinds previous throughput bottlenecks.
- Surgery Centers:Ambulatory facilities prioritize compact, portable anesthesia delivery systems with rapid turnaround capabilities. These settings in Karnataka favor modular platforms that balance infection control protocols against capital constraints under state public health mission frameworks.
- Physician Offices:Limited procedure volumes restrict equipment sophistication to basic sedation delivery systems.
- Emergency Departments:Trauma-focused settings demand rapid-deployment anesthesia capabilities with ruggedized construction.
Hospitals dominate absolute unit demand; surgery centers are climbing the fastest as ambulatory surgical infrastructure scales.
Product Offering:
Volume concentration in disposable formats intensifies as infection control protocols harden against reusable alternatives across corporate hospital chains.
- Disposable Devices:Single-use breathing circuits, filters, and masks eliminate cross-contamination risks while generating recurring revenue streams. These products capture procurement preference in Maharashtra and Tamil Nadu where corporate hospital chains enforce strict single-use protocols across cardiac and neurosurgical suites.
- Reusable Devices:Autoclavable circuits and silicone masks target cost-sensitive government tenders in northern and central India where sterilization infrastructure supports repeated-use economics.
- Accessories:Masks, tubing connectors, and gas sampling lines complete system configurations.
- Software Solutions:Anesthesia information management systems automate documentation and quality reporting.
Disposable devices command the largest revenue base; software solutions are gaining share fastest as digital integration requirements harden.
Technology:
Supply concentration in electronic monitoring modules and integrated platforms contrasts with fragmented mechanical component sourcing.
- Electronic:Microprocessor-controlled systems enable precise agent delivery with automated feedback loops and alarm networks. CDSCO registration timelines for these configurations extend due to quality management system certification requirements for software-enabled medical devices.
- Integrated Systems:Unified platforms combining gas delivery, mechanical ventilation, and hemodynamic monitoring are penetrating corporate hospital chains in Mumbai, Bangalore, and Chennai at accelerated replacement cycles.
- Mechanical:Pneumatic flowmeters and manual vaporizers persist in resource-constrained settings.
- Others:Hybrid configurations and emerging delivery modalities occupy niche applications.
Electronic platforms anchor current revenue; integrated systems are expanding most quickly as clinicians seek unified control interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO anchors anesthesia device quality standards across India's hospital network, with state-level procurement corporations channeling equipment through Maharashtra, Karnataka, and Tamil Nadu. Tier-II and Tier-III city hospitals in these states are expanding surgical capacity and driving procurement of anesthesia workstations as anesthesiologist workforce expansion unwinds previous throughput bottlenecks.
Maharashtra
Mumbai's corporate hospital chains are consolidating procurement around integrated anesthesia workstation platforms with specialized configurations for cardiac and neurosurgical suites. CDSCO Medical Devices Rules mandate quality certification for imported and domestically manufactured equipment, elevating baseline safety specifications in tertiary care centers. The Maharashtra Medical Services Corporation channels bulk anesthesia equipment acquisition through centralized framework contracts, displacing fragmented hospital-level purchasing.
Karnataka
Bangalore's medical device clusters and corporate hospital chains are driving demand for unified platforms combining gas delivery, ventilation, and hemodynamic monitoring. The state's public health mission frameworks prioritize compact, portable anesthesia delivery systems for ambulatory surgery centers with rapid turnaround capabilities. Karnataka's tender structures under Ayushman Bharat create entry points for domestic manufacturers meeting BIS electrical safety standards.
Tamil Nadu
Chennai's tertiary facilities are accelerating replacement cycles for anesthesia machines as CDSCO safety standard revisions tie technology upgrades to capital expenditure budgets. Tier-II city hospitals in Coimbatore and Madurai are expanding surgical capacity and driving procurement of mid-range workstation platforms. The Tamil Nadu Medical Services Corporation consolidates purchase authority through standardized specifications in framework contracts.
Uttar Pradesh
Lucknow and Kanpur's underpenetrated hospital networks present whitespace for mid-range workstation deployment as surgical infrastructure scales under state public health missions. District hospital budgets strain under the capital intensity of integrated systems, favoring modular upgrade paths with standalone vaporizers and basic breathing circuits. Northern India's government tenders concentrate procurement preference for cost-sensitive reusable device configurations.
Bihar
Patna's secondary hospitals are upgrading from basic delivery systems to modular anesthesia platforms as anesthesiologist workforce expansion progresses. The state's procurement specifications under evolving tender structures create opportunities for domestic manufacturers competing on cost in government contracts. Eastern India's surgical capacity expansion lags western and southern states, extending replacement cycles for legacy mechanical vaporizer configurations.
India Anesthesia Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in India's anesthesia devices market, with domestic manufacturers competing on cost against multinational equipment suppliers. The structure bifurcates between premium integrated workstation platforms for corporate hospital chains and modular configurations for budget-constrained government facilities. Three archetypes dominate: multinational technology leaders with specialized cardiac-suite configurations, domestic cost competitors leveraging PLI scheme incentives, and mid-range specialists targeting tier-II hospital markets. Competitive moves center on CDSCO registration readiness for quality certification and state-level tender participation through centralized medical services corporations.
Among multinational suppliers, B. Braun Medical and GE Healthcare exemplify the premium-tier archetype with integrated platform positioning for complex surgical suites. Shenzhen Mindray Bio-Medical Electronics anchors the mid-range specialist tier through distribution network control in price-sensitive tier-II markets. Medion Healthcare Pvt. Ltd represents the domestic cost-competitor archetype, leveraging northern and central India manufacturing footprints for government tender participation.
| Leading Market Players |
|---|
| Medion Healthcare Pvt. Ltd |
| Terumo Corporation |
| Becton, Dickinson and Company |
| Baxter International Inc. |
| Nihon Kohden Corporation |
| B. Braun Medical |
| Ontex Medical Devices Manufacturing Pvt. Ltd |
| Shenzhen Mindray Bio-Medical Electronics |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
CDSCO Medical Devices Rules registration requirements gate both supply qualification and price differentiation in India's anesthesia equipment market. Manufacturers must secure quality management system certification before market authorization, creating a compliance cost barrier that separates premium-tier integrated workstation suppliers from modular equipment vendors competing on upfront capital expenditure.
Pricing Analysis
Maharashtra commands the widest price spreads, with Mumbai's corporate hospital chains absorbing premium integrated platform costs while Uttar Pradesh government tenders drive mid-range workstation pricing downward. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the economy tier intensifies as domestic manufacturers leverage PLI scheme incentives to undercut imported equipment margins. Government hospital procurement committees exhibit highest price sensitivity; cardiac-suite configurations in tertiary care centers show least.
Supply Chain Analysis
China and Taiwan anchor precision vaporizer and advanced monitoring sensor production for Indian anesthesia device assemblers. Domestic manufacturing draws from East Asian semiconductor inputs, German pneumatic components, and domestic steel fabrication for chassis and breathing circuit housings. Single-source vulnerability concentrates in specialized sensor modules, exposing procurement timelines to geopolitical friction. Distribution runs through Maharashtra and Karnataka medical device clusters, with state-level medical services corporations consolidating downstream channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's anesthesia devices market sits in early-cycle expansion as Tier-II and Tier-III city surgical capacity builds out from historically constrained baselines. State public health mission tender evolution creates predictable demand visibility for equipment vendors positioned at appropriate price-performance tiers.
For Market Incumbents: Secure CDSCO registration readiness for next-generation integrated monitoring modules before safety standard revisions accelerate replacement cycles. Deepen backward integration into vaporizer component sourcing to reduce East Asian supply exposure. Channel control through exclusive service contracts with Maharashtra and Karnataka medical services corporations defends position against emerging domestic cost competitors.
For New Entrants and Emerging Players: Anchor in Uttar Pradesh and Bihar government tender corridors where surgical infrastructure scaling outpaces established vendor penetration. Mid-range workstation configurations with modular upgrade paths address district hospital budget constraints under state public health missions. Direct technical training partnerships with state biomedical engineering cadres differentiate service offerings against multinational incumbents.
For Investors and Strategic Acquirers: CDSCO's tightening quality management system certification timelines reshapes the acquisition landscape toward targets with demonstrated regulatory navigation capabilities. Domestic manufacturers with PLI scheme qualification and northern India manufacturing footprints offer viable entry vehicles. Watch state-level medical services corporation tender award patterns as inflection indicators for procurement centralization momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Pathway | Quality certification accelerates market access for integrated workstation platforms in tertiary care centers. |
| State Medical Services Partnership | Framework contracts with Maharashtra and Karnataka corporations consolidate procurement volume and reduce customer acquisition cost. |
| PLI Scheme Qualification | Fiscal incentives redirect capital toward domestic manufacturing footprints for anesthesia equipment assembly. |
| Biomedical Engineer Training Program | Technical workforce development addresses Tier-III facility maintenance gaps and differentiates service offerings. |
| Tele-ICU Integration Development | Remote monitoring convergence enables specialist oversight across distributed surgical sites in secondary cities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with anesthesia device industry stakeholders and systematic secondary validation across regulatory and procurement databases. Interview targets included hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and CDSCO regulatory affairs specialists. Secondary sources encompassed CDSCO Medical Devices Rules filings, state medical services corporation tender documentation, hospital procurement databases, and BIS electrical safety standard revisions. Bottom-up equipment unit demand estimates triangulated against top-down healthcare infrastructure spending allocations.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented demand build-up. Segmentation dimensions included device type tier, end-user facility class, product offering format, and technology platform complexity. CAGRs derived from replacement cycle analysis tied to CDSCO safety standard revision schedules and state public health mission expenditure patterns. Industry-specific inputs incorporated anesthesiologist workforce expansion rates and surgical procedure volume elasticity estimates.
Underlying assumptions cover regulatory enforcement continuity, PLI scheme incentive stability, and state tender centralization progression, with deviation risk concentrated in geopolitical supply disruptions and specialist training pipeline constraints. Recalibration cycles align with material shifts in CDSCO certification timelines and state medical services corporation procurement award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Band Ligators Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Vaginal Applicators Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
Global Embolization Particle Market