
 Global Healthcare Architecture Market | 2026-2036
Global Healthcare Architecture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Architecture Market Foresight
North American hospital infrastructure investment is reconfiguring procurement patterns for architectural services across the United States and Canada. HDR leverages evidence-based design methodologies to sustain competitive positioning in academic medical center projects. HKS anchors its portfolio through deep specialization in cancer center and pediatric facility typologies. Perkins+Will differentiates via integrated sustainable architecture protocols that command premium engagement terms.
Healthcare architecture encompasses the planning, design, and construction of facilities for medical treatment, diagnostics, and patient recovery, requiring compliance with infection control protocols, seismic resilience ratings, and 24/7 operational continuity parameters. Its primary purpose is to optimize clinical workflows while reducing patient stress and energy consumption. Hospital building projects command the largest fee pools given their structural complexity and multi-year delivery timelines, while modular construction represents the fastest-expanding design approach as owners seek schedule compression and waste reduction. Evidence-based design maintains mature penetration in the United States but spreads gradually into Asian and Middle Eastern markets.
FDA facility guidelines, EPA energy efficiency mandates, and the EU Green Deal's building performance standards collectively shape material specifications, MEP system selections, and documentation burdens for architectural practices. The EU AI Act introduces emerging compliance dimensions for smart building integration and automated clinical environment controls. Stakeholders must monitor regulatory divergence between jurisdictions to avoid costly redesign cycles and qualification gaps.
Market Dynamics
Hospital modernization mandates across Germany, the United States, and Japan are compressing traditional design timelines while forcing integration of modular construction with smart building infrastructure. This structural pressure is redistributing fee pools toward firms capable of delivering evidence-based design at accelerated schedules.
Growth Catalysts
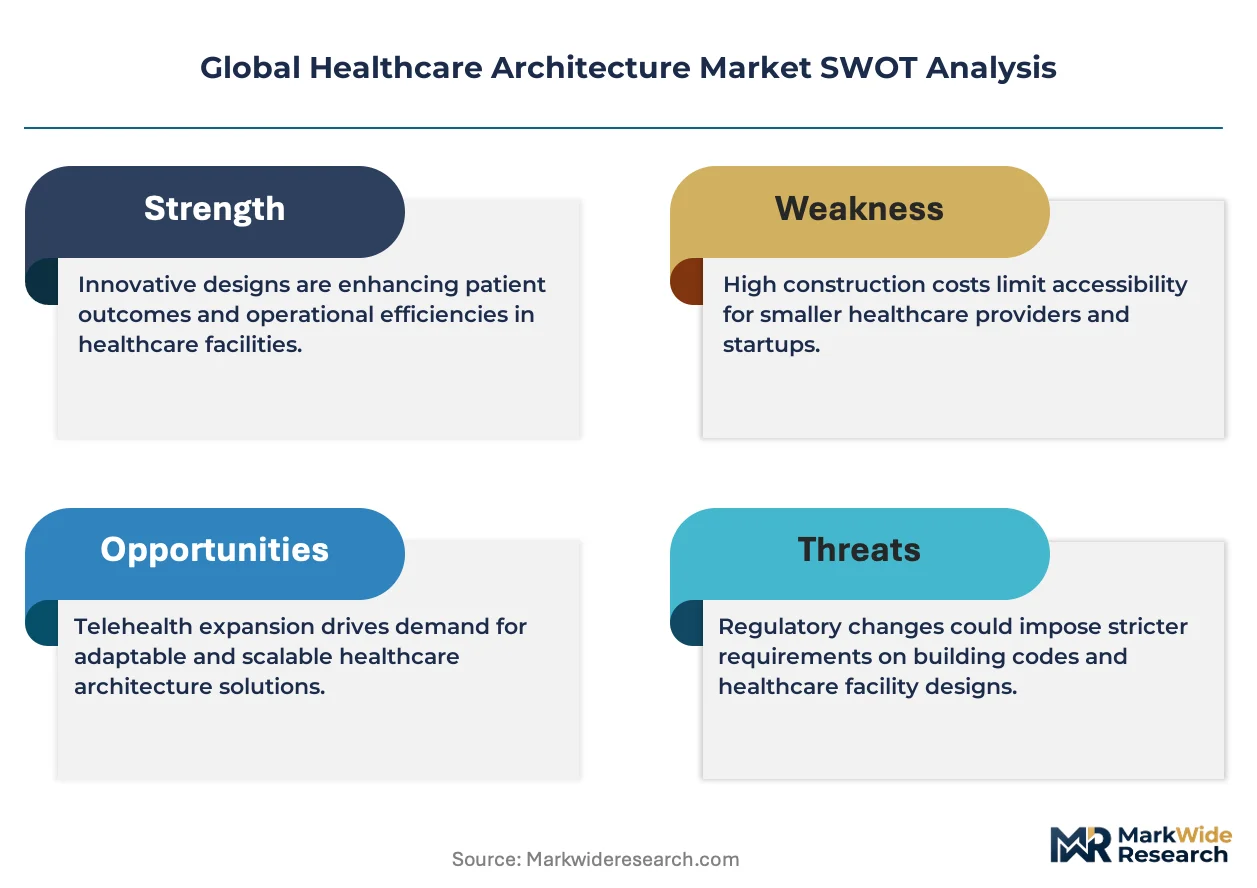
- EU Green Deal building performance standards:Mandatory decarbonization targets for healthcare facilities in Germany, France, and Italy are accelerating sustainable material specifications and energy-positive design contracts.
- Modular construction methodologies:Prefabricated clinical unit systems are compressing project schedules by 30-40% while reducing on-site waste generation for hospital expansions in Canada and Australia.
- Specialized care facility expansion:Cancer centers and pediatric hospitals in Texas, California, and Ontario are driving purpose-built typology demand with premium fee structures.
Market Restraints
- Steel and copper price volatility:MEP system material costs fluctuate unpredictably, squeezing contingency budgets for hospital projects in the United States and United Kingdom.
- Specialized healthcare architect concentration:Deep expertise in infection control protocols and seismic resilience remains concentrated among fewer than two dozen global practices, creating qualification bottlenecks.
- FDA facility guideline complexity:Pharmaceutical manufacturing facility requirements impose documentation burdens that extend schematic design phases by 4-6 months.
Strategic Opportunities
- India hospital infrastructure gap:Tier-2 and Tier-3 cities lack modern healthcare facilities, creating entry points for modular design specialists targeting 500+ bed greenfield projects.
- EU AI Act smart building compliance:Automated clinical environment controls and AI-integrated building management systems represent unclaimed service territory for architecture-engineering hybrids.
- Retrofit-to-net-zero conversion:Existing hospital stock in the United Kingdom and Germany requires deep energy retrofits, opening performance-contracting revenue streams tied to guaranteed energy savings.
Industry Challenges
- Healthcare-specific BIM expertise scarcity:Building information modeling specialists with clinical workflow knowledge command premium compensation that mid-size practices struggle to absorb.
- Seismic resilience certification timelines:California OSHPD and Japan's MLIT approval processes for acute care facilities extend design development by 8-12 months.
- Legacy MEP integration complexity:Smart building sensor networks must interface with 20-30 year old hospital infrastructure without disrupting 24/7 operations.
Report Scope
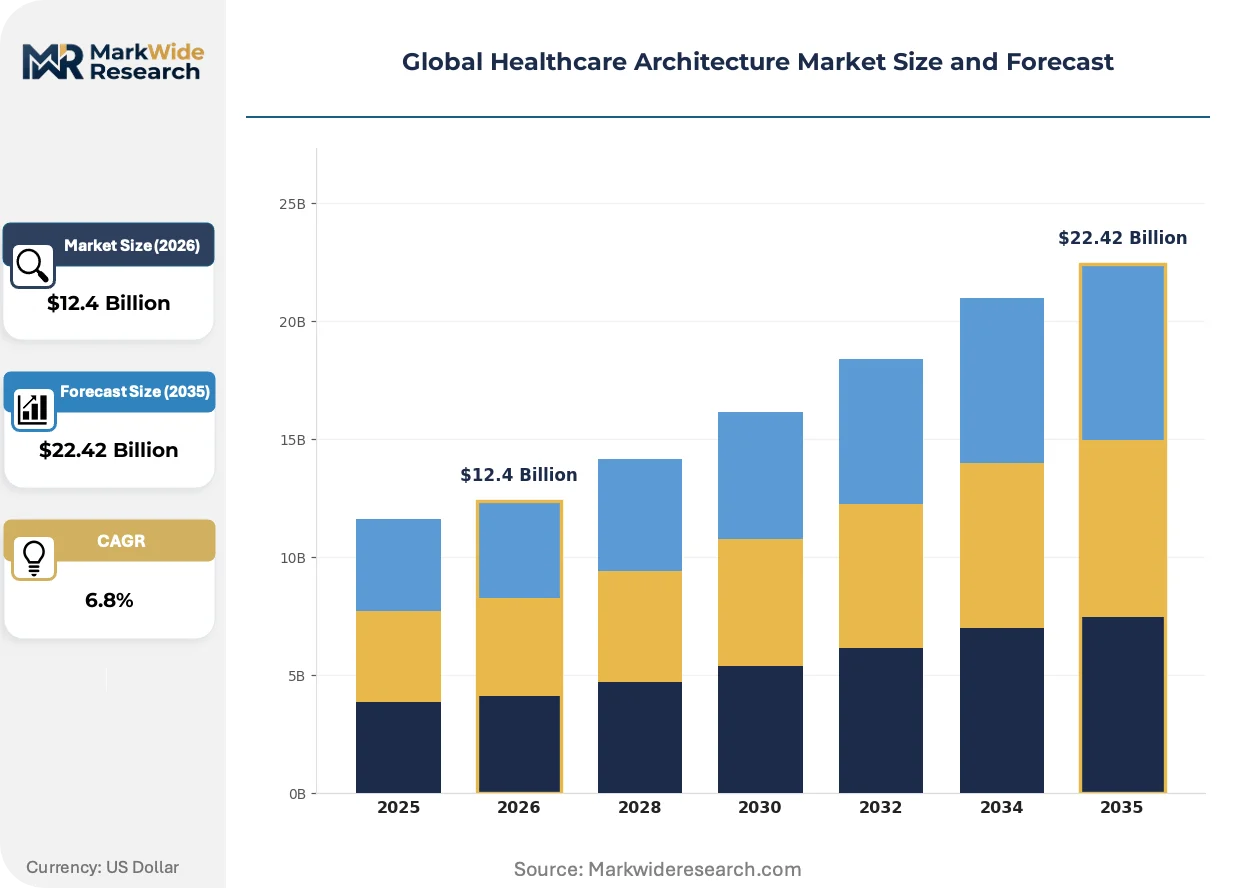
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Architecture Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Hospital Building, Medical Campus, Outpatient Clinic, Diagnostic Center, Rehabilitation Facility Design Approach: Evidence-Based Design, Sustainable Architecture, Modular Construction, Smart Building Integration, Patient-Centered Design Service Offering: Planning & Consultation, Interior Design, Landscape Architecture, Project Management, Engineering Services End User: Public Health Institutions, Private Medical Centers, Research Institutes, Specialized Care Providers, Emergency Services |
| Companies Covered | HDR, HKS, Perkins+Will, Stantec, CannonDesign, NBBJ, Perkins Eastman, SmithGroup, HOK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Architecture Market Shifts & Advancements
Digital twin technology is compressing the gap between design intent and operational performance. Regulatory frameworks are hardening around embodied carbon disclosure. Procurement patterns are fragmenting as health systems diversify their architectural vendor bases.
Digital twin platforms are digitizing the entire building lifecycle from schematic design through operational handover. Academic medical centers in Massachusetts and California are deploying these systems to simulate patient flow and energy performance before construction begins. This capability is digitizing traditional fee structures by tying architect compensation to post-occupancy performance metrics rather than deliverable milestones.
The EU AI Act's risk classification framework for automated clinical environment controls is mandating algorithmic transparency documentation for smart building integrations. Hospital projects in Germany and France must now submit AI system impact assessments alongside traditional building permits. Oncology and surgical suites with integrated environmental automation face the heaviest compliance burdens, driving architecture firms to embed regulatory specialists within design teams.
Health system purchasing departments are unbundling master planning, clinical design, and MEP engineering into separate contracts rather than single-source A/E agreements. This fragmentation is most visible in Texas and Florida, where massive hospital expansion programs are distributing work among 8-12 specialized vendors per project. The disintermediation of traditional full-service relationships is compressing margins while demanding new coordination capabilities from winning firms.
Global Healthcare Architecture Market Segmentation
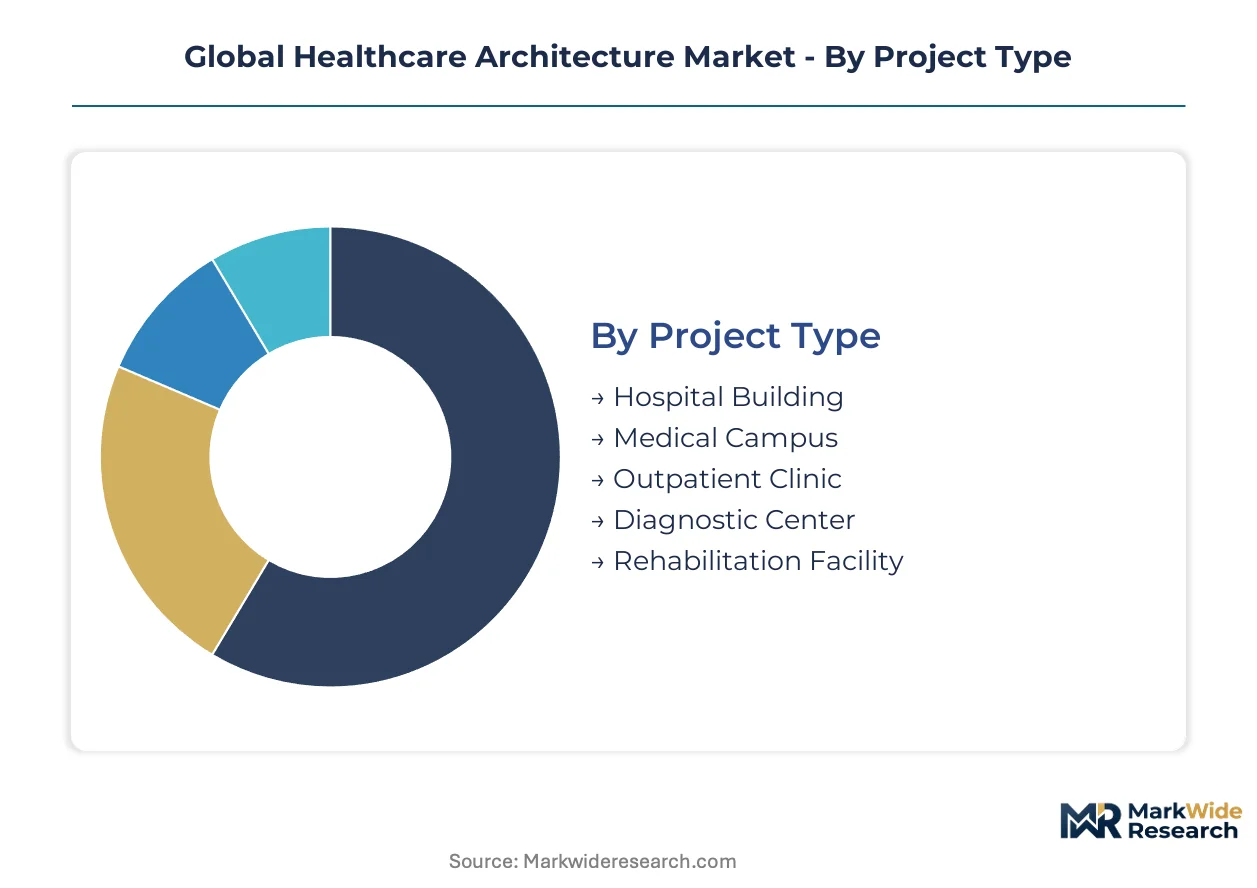
Healthcare architecture segmentation reveals how project complexity, regulatory intensity, and stakeholder specialization fragment fee structures and delivery timelines. Understanding these dimensions clarifies where capital concentrates and which service lines command premium positioning.
Project Type:
Hospital building projects stretch across multi-year cycles with the heaviest documentation burdens, while outpatient clinics compress from schematic to occupancy in under eighteen months.
- Hospital Building:Structural complexity demands seismic resilience certification and 24/7 operational continuity planning. Germany's hospital modernization programs and Texas medical center expansions anchor global demand for acute care facility expertise.
- Medical Campus:Multi-building master plans integrate research, clinical, and administrative functions across phased development timelines. Academic medical centers in Massachusetts and California drive purpose-built campus demand with integrated digital twin specifications.
- Outpatient Clinic:Rapid deployment models serve retail health and ambulatory surgery markets.
- Diagnostic Center:Imaging-intensive facilities require specialized MEP and radiation shielding expertise.
- Rehabilitation Facility:Long-term care integration shapes therapeutic environment design protocols.
Hospital building anchors the volume base while outpatient clinic gains share at the steepest rate.
Design Approach:
Cost stratification separates legacy methodology from premium-positioned innovation, with sustainable architecture and smart building integration commanding fee premiums of 40-60% over conventional practice.
- Evidence-Based Design:Clinical outcome metrics drive spatial planning decisions for infection control and patient stress reduction. The United States maintains mature penetration while Japan and Saudi Arabia expand adoption for academic medical center projects.
- Sustainable Architecture:EU Green Deal mandates and EPA energy efficiency requirements shape material specifications and MEP system selections. Germany's national decarbonization targets accelerate energy-positive design contracts with performance guarantees.
- Modular Construction:Prefabricated clinical units compress schedules by 30-40% for Canadian and Australian hospital expansions.
- Smart Building Integration:AI-integrated environmental controls face emerging EU AI Act compliance dimensions.
- Patient-Centered Design:Biophilic elements and wayfinding psychology reduce clinical anxiety metrics.
Evidence-based design commands the widest geographic penetration while smart building integration climbs the fastest as regulatory frameworks harden around automated clinical controls.
Service Offering:
Procurement fragmentation is unbundling traditional full-service relationships, with health systems in Texas and Florida distributing contracts across 8-12 specialized vendors per project.
- Planning & Consultation:Master planning and feasibility studies establish clinical workflow frameworks and capital allocation priorities. Public health institutions in India and Brazil commission 500+ bed greenfield site assessments with modular deployment roadmaps.
- Engineering Services:MEP system design integrates legacy infrastructure with smart sensor networks without disrupting 24/7 operations. Seismic resilience ratings and FDA facility guidelines impose 8-12 month approval extensions for California and pharmaceutical manufacturing projects.
- Interior Design:Infection control protocols and material specifications shape therapeutic environments.
- Landscape Architecture:Healing gardens and biophilic integration support patient recovery metrics.
- Project Management:Schedule compression and contingency oversight coordinate multi-vendor delivery.
Planning and consultation anchors the front-end revenue base while engineering services expands most quickly as MEP complexity and regulatory documentation burdens intensify.
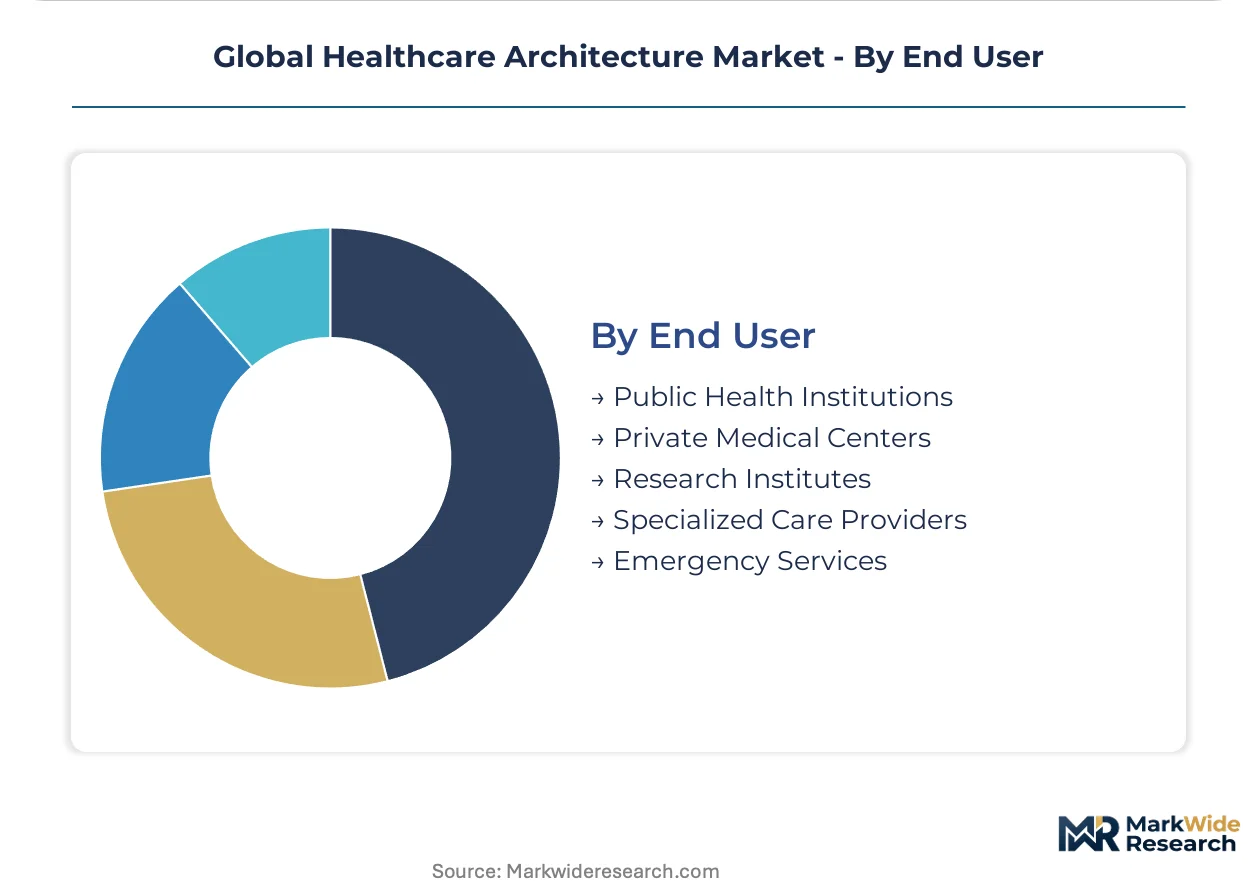
End User:
Customer type determines procurement autonomy, with private medical centers accelerating decision velocity while public health institutions navigate extended approval hierarchies and political oversight.
- Public Health Institutions:Government-funded hospital systems in Germany, the United Kingdom, and Canada navigate budget cycles and political approval for modernization programs. EU Green Deal building performance standards mandate decarbonization timelines that reshape capital planning priorities.
- Specialized Care Providers:Cancer centers and pediatric hospitals in Texas, California, and Ontario commission purpose-built typologies with premium fee structures. Deep expertise in clinical workflow integration commands engagement terms 25-35% above general hospital benchmarks.
- Private Medical Centers:Investor-backed systems in Florida and the UAE pursue schedule compression through modular methodologies.
- Research Institutes:NIH and EU-funded facilities require BSL-3/4 containment and specialized laboratory planning.
- Emergency Services:Trauma center designation requirements and helicopter access protocols shape site selection.
Public health institutions anchor the contract volume base while specialized care providers gains share at the steepest rate as purpose-built typologies command premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Architectural expertise concentrates among fewer than two dozen global practices capable of delivering complex healthcare facilities. Specialized capability clusters have formed around academic medical centers in the United States, hospital modernization programs in Germany, and modular construction adoption in Canada and Australia.
United States
Academic medical centers in Massachusetts and California drive demand for digital twin-integrated facilities. FDA facility guidelines and EPA energy efficiency mandates shape material specifications and documentation burdens. The Texas Medical Center in Houston anchors specialized cancer center and pediatric hospital construction with premium fee structures.
Germany
Hospital modernization programs integrate modular construction with smart building systems across federal states. EU Green Deal building performance standards and national decarbonization targets mandate energy-positive design contracts. The Rhine-Ruhr metropolitan region concentrates retrofit-to-net-zero conversion projects tied to guaranteed energy savings.
Canada
Prefabricated clinical unit systems compress project schedules for hospital expansions in Ontario and British Columbia. Health Canada regulations govern infection control protocols and seismic resilience ratings. Toronto and Vancouver anchor ambulatory surgery and retail health facility deployment with rapid occupancy timelines.
Japan
MLIT approval processes for acute care facilities extend design development timelines while mandating seismic resilience certification. METI guidelines influence smart building integration and automated clinical environment controls. The Kanto region around Tokyo concentrates academic medical center projects adopting evidence-based design methodologies.
India
Tier-2 and Tier-3 cities lack modern healthcare facilities, creating entry points for modular design specialists. CDSCO and national hospital accreditation standards govern clinical workflow planning. Maharashtra and Karnataka anchor 500+ bed greenfield projects targeting public health infrastructure gaps.
Global Healthcare Architecture Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base fragments across evidence-based design practitioners, sustainable architecture specialists, and modular construction technologists. Three archetypes dominate: full-service healthcare architects with multi-decade hospital portfolios, boutique typology specialists in cancer and pediatric facilities, and engineering-forward hybrids integrating MEP with smart building systems. Competitive moves concentrate on strategic partnerships for AI-integrated environmental controls and geographic expansion into underpenetrated hospital infrastructure markets.
Within the full-service tier, HDR, HKS, and Perkins+Will occupy positions defined by methodological differentiation rather than scale alone. HDR represents the evidence-based design archetype with academic medical center concentration. HKS exemplifies typology specialization through cancer center and pediatric facility expertise. Perkins+Will anchors sustainable architecture positioning with integrated protocols commanding premium engagement terms. These three practices illustrate how competitive advantage in healthcare architecture derives from repeatable methodological IP rather than generic capacity.
| Leading Market Players |
|---|
| HDR |
| HKS |
| Perkins+Will |
| Stantec |
| CannonDesign |
| NBBJ |
| Perkins Eastman |
| SmithGroup |
| HOK |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr metropolitan region anchors European healthcare architecture capacity, where hospital modernization programs concentrate design expertise and compress procurement timelines for energy-positive contracts. This geographic clustering of modular construction specialists and sustainable materials suppliers feeds downstream pricing power toward firms with integrated smart building capabilities.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across German, French, and Italian healthcare projects, separating energy-positive design contracts with performance guarantees from conventional fee arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth: EU AI Act compliance documentation and digital twin integration command 40-60% fee premiums over baseline architectural services. Cost compression in standard-tier hospital building segments is intensifying as procurement fragmentation distributes contracts across 8-12 specialized vendors per project. Public health institutions in Germany and Canada exhibit highest price sensitivity due to budget cycle constraints, while specialized cancer centers in Texas and California demonstrate lowest sensitivity given premium positioning requirements.
Supply Chain Analysis
Steel and copper feedstock volatility from German, Chinese, and Australian suppliers anchors MEP system cost unpredictability for hospital projects across North America and Europe. Prefabricated clinical unit production draws from Canadian, Australian, and emerging Indian manufacturing bases, with schedule compression capabilities resting on just-in-time delivery coordination. Single-source vulnerability concentrates in seismic resilience certification expertise, where fewer than two dozen global practices hold California OSHPD and Japan MLIT approval credentials. Distribution runs through health system purchasing departments unbundling master planning, clinical design, and MEP engineering into separate contract streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare architecture sits in early-cycle expansion as EU AI Act compliance mandates and modular construction adoption create unclaimed service territory for architecture-engineering hybrids. Evidence-based design penetration in Asian and Middle Eastern markets remains below 15%, indicating substantial runway for methodological exporters.
For Market Incumbents: Build regulatory specialist moats by embedding EU AI Act impact assessment capabilities within design teams before competitor replication. Consolidate digital twin platform partnerships with Massachusetts and California academic medical centers to lock in post-occupancy performance contracting revenue. Vertical integration into prefabricated clinical unit manufacturing in Ontario and British Columbia defends against schedule compression demands from Canadian health systems. For New Entrants and Emerging Players: Pursue modular design specialization targeting Tier-2 and Tier-3 Indian cities where 500+ bed greenfield projects lack qualified local architects. Enter through performance-based fee structures tied to energy savings guarantees rather than traditional deliverable milestones. White-space concentration in EU AI Act smart building compliance for automated clinical environment controls offers fastest penetration path. For Investors and Strategic Acquirers: Long-term, this sits as a capability scarcity play because deep expertise in infection control protocols and seismic resilience certification remains concentrated among fewer than two dozen global practices with 8-12 month approval timelines. Target acquisition archetype: boutique typology specialists in cancer and pediatric facilities with 25-35% fee premiums over general hospital benchmarks. Signal to watch: health system procurement fragmentation accelerating toward 10+ vendors per project, indicating coordination platform opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Massachusetts academic medical centers deploy simulation capabilities tying architect compensation to post-occupancy metrics. |
| EU AI Act Compliance Specialization | German and French oncology suites now require algorithmic transparency documentation alongside traditional building permits. |
| Modular Construction Scale-Up | Canadian prefabricated clinical units compress hospital expansion schedules by 30-40% while reducing on-site waste. |
| Retrofit-to-Net-Zero Conversion | United Kingdom and German existing hospital stock opens performance-contracting revenue streams tied to guaranteed energy savings. |
| Geographic Expansion into India | Maharashtra and Karnataka anchor 500+ bed greenfield projects targeting public health infrastructure gaps in Tier-2 cities. |
Research Methodology
Initial hypotheses were tested against primary input from healthcare facility planners, hospital procurement committee chairs, biomedical engineers, and modular construction technologists and refined through secondary validation against hospital procurement databases, GPO contracts, CMS Medicare facility cost data, and EU Green Deal implementation reports. Bottom-up project pipeline analysis across Germany, the United States, Japan, Canada, and India triangulated with top-down capital expenditure forecasts from public health institutions.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation by project type, design approach, service offering, and end user archetype. CAGRs derived from weighted capacity expansion schedules and regulatory mandate implementation timelines incorporated MEP system complexity indices and seismic resilience certification backlog data as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in steel and copper price volatility, health system capital allocation priorities, or EU AI Act enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding modular construction adoption rates and digital twin platform penetration. Cross-checking against hospital construction permit filings and health system annual capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
Ambulatory Surgical Centers Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
Confinement Center Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
Mobile Hospitals Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
Bedless Hospitals Market
Healthcare Facilities
US Hospital Facilities Market
Healthcare Facilities
Sauna and Spa Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
Trauma Care Centers Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market