
 Vascular Testing Devices Market | 2026-2036
Vascular Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Testing Devices Market Analytics
Modular platform configurations is decoupling hardware from software purchasing decisions across hospital procurement teams. Siemens Healthineers leverages this shift by offering upgradeable ultrasound cart systems that sustain recurring service revenue. Philips Healthcare anchors its vascular portfolio on integrated PACS connectivity, while GE Healthcare competes through AI-enhanced image reconstruction modules that extend equipment lifecycle value.
Vascular testing devices comprise diagnostic instruments that measure blood flow velocity, vessel patency, and tissue oxygenation using Doppler ultrasound, plethysmography, or transcutaneous sensors with operating frequencies typically ranging from 2 to 15 MHz for deep and superficial vessel assessment. These systems serve clinicians in detecting stenosis, thrombosis, and chronic venous insufficiency before surgical intervention becomes necessary. Ultrasound-based systems occupy the largest installed base due to versatility across anatomical sites, though wearable Doppler patches represent the fastest-expanding technology segment as ambulatory monitoring protocols gain clinical acceptance. Home care settings emerge as a concentrated margin pool where telehealth-integrated devices command premium positioning against traditional clinic-bound equipment.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and clinical evidence standards for manufacturers seeking dual-market access. HIPAA data security rules and GDPR patient privacy frameworks further constrain cloud-connected vascular monitoring architectures, forcing region-specific server deployments. Stakeholders must weigh regulatory compliance investment against the velocity of wearable and AI-augmented product cycles that promise to redefine point-of-care vascular assessment workflows.
Market Dynamics
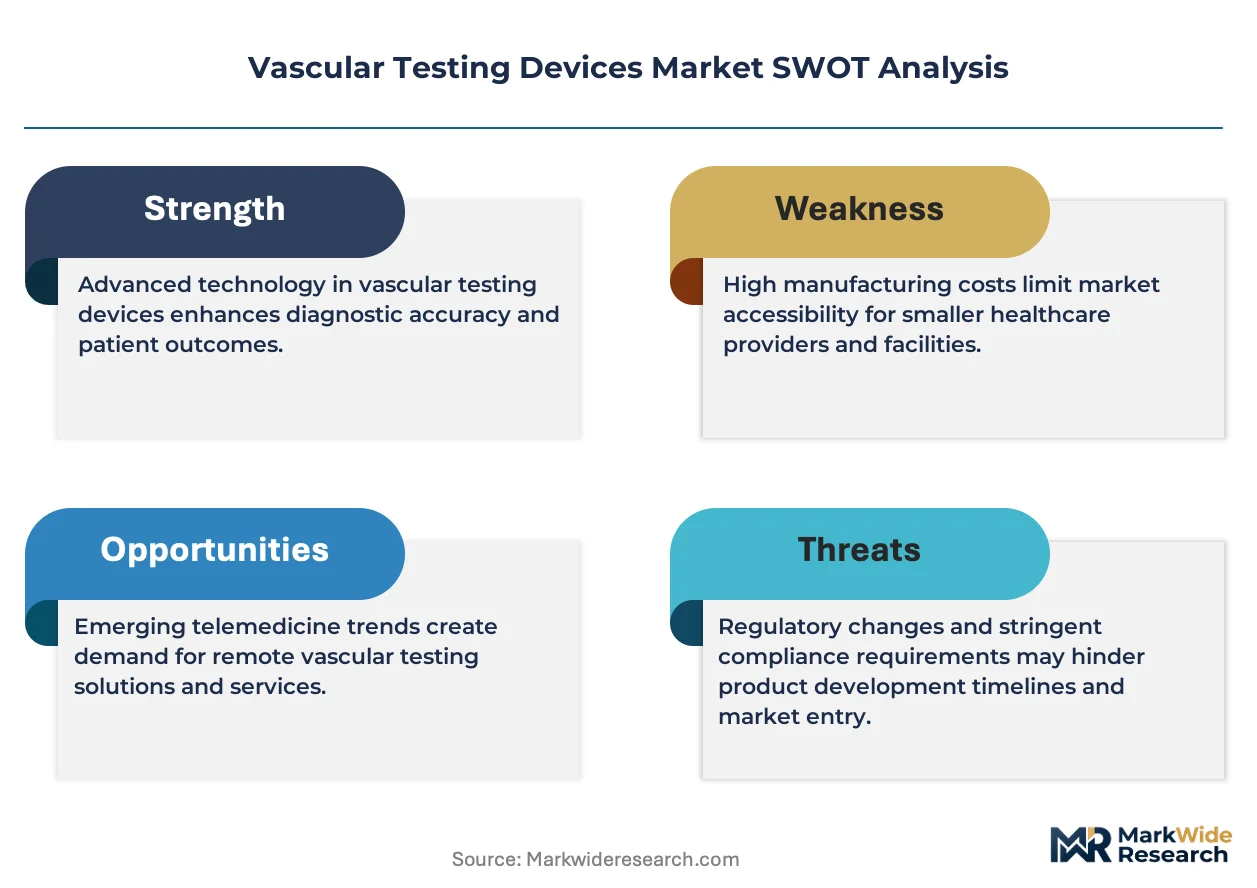
Modular platform architectures are fragmenting procurement decisions across hospital systems, decoupling hardware acquisition from software licensing and service contracts. This structural shift forces vendors to defend recurring revenue streams through upgrade pathways rather than replacement cycles.
Growth Catalysts
- EU MDR Class IIa certification mandates:Tightened quality benchmarks for peripheral artery disease detection systems compel healthcare facilities to modernize non-invasive screening infrastructure.
- Ambulatory monitoring protocols:Wearable Doppler patches gain clinical acceptance as cardiologists integrate continuous blood flow data into chronic venous insufficiency management.
- Telehealth reimbursement expansion:CMS coding updates in the United States legitimize remote vascular assessment, accelerating home care device deployment.
Market Restraints
- Transducer manufacturing concentration:Piezoelectric crystal supply chains cluster in East Asian fabrication facilities, exposing procurement to geopolitical friction.
- GDPR cloud architecture constraints:Patient privacy frameworks force region-specific server deployments that duplicate infrastructure costs for multi-national vendors.
- Optical coherence tomography substitution:High-resolution intravascular imaging platforms capture coronary assessment volumes previously assigned to ultrasound systems.
Strategic Opportunities
- Underpenetrated home care settings:Telehealth-integrated devices command premium positioning against clinic-bound equipment in post-acute monitoring.
- FDA 510(k) predicate pathway optimization:Streamlined clearance mechanisms for iterative Doppler algorithms reduce time-to-market for AI-augmented reconstruction modules.
- Point-of-care convergence:Integration of photoplethysmography with pulse oximetry creates hybrid platforms for emergency department triage protocols.
Industry Challenges
- Sonographer workforce scarcity:Specialized vascular imaging certification programs fail to match hospital expansion of non-invasive screening programs.
- Legacy PACS integration complexity:Hospital information systems require costly middleware development to ingest AI-enhanced ultrasound data streams.
- Dual-market evidence generation:Manufacturers must construct parallel clinical trial architectures to satisfy both FDA substantial equivalence and EU MDR clinical evaluation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Testing Devices Market |
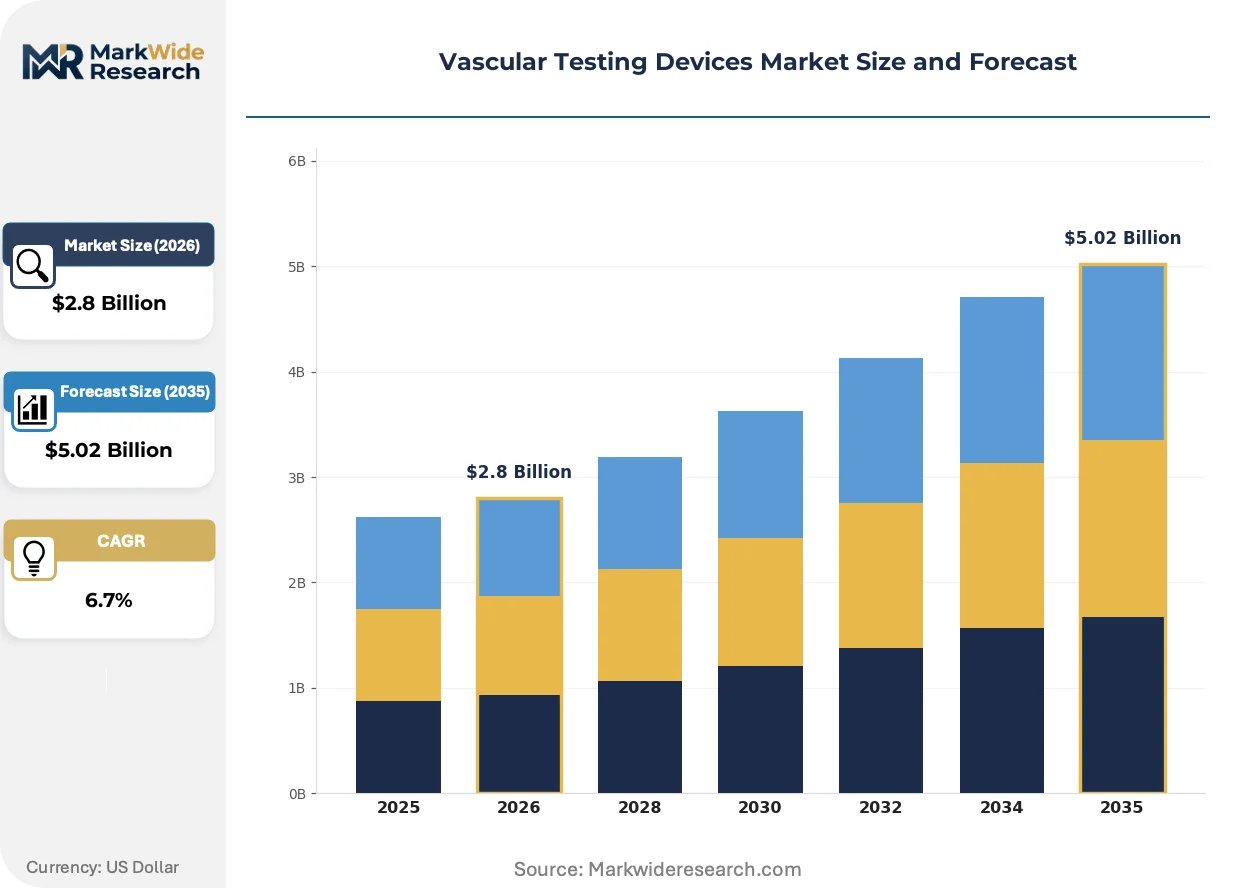
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, Doppler, Ankle-Brachial Index, Transcutaneous Oxygen Tension Technology: Non-Invasive, Invasive, Wearable, Telehealth Solutions End User: Hospitals, Clinics, Diagnostic Laboratories, Home Care Settings Application: Peripheral Artery Disease, Venous Insufficiency, Arterial Occlusion, Diabetes Screening |
| Companies Covered | Medtronic, Boston Scientific Corporation, GE Healthcare, Siemens Healthineers, Philips Healthcare, Unetixs Vascular Inc., Fukuda, Koven Technology Inc., D.E. Hokanson Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Testing Devices Market Evolving Landscape
Artificial intelligence reconstruction algorithms and wearable sensor miniaturization are compressing the boundary between acute diagnostic imaging and longitudinal monitoring. These forces are reconfiguring vendor revenue models and clinical workflow architectures simultaneously.
Machine learning-based spectral Doppler analysis is automating blood flow velocity quantification that previously required manual cursor placement by trained sonographers. Community health systems with limited vascular specialist coverage adopt these tools to extend screening capacity. The technology is automating preliminary stenosis grading, reducing interpretation bottlenecks in high-volume peripheral artery disease detection programs.
EU MDR post-market surveillance requirements now mandate systematic clinical follow-up for Class IIa vascular devices, elevating evidence collection burdens. Manufacturers must maintain active implant registries or equivalent longitudinal tracking systems. Small and mid-size ultrasound vendors face particular pressure, as notified body capacity constraints extend certification timelines beyond historical baselines.
Hospital procurement committees increasingly unbundle service contracts from capital equipment purchases, treating preventive maintenance as separately negotiable spend. Integrated delivery networks in the United States lead this behavior, leveraging purchasing scale to drive aftermarket competition. The shift pressures traditional vendors who historically subsidized hardware margins through captive service agreements.
Vascular Testing Devices Market Segmentation
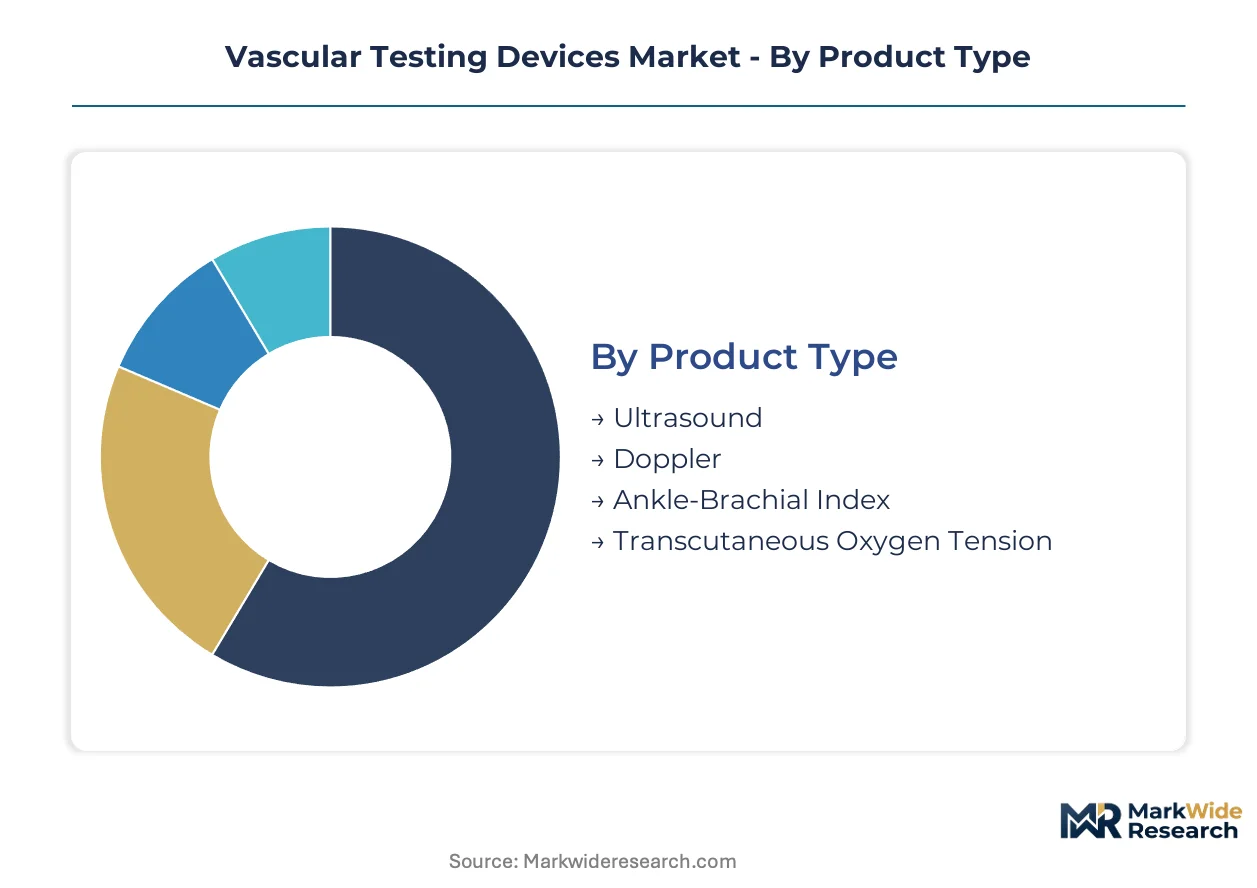
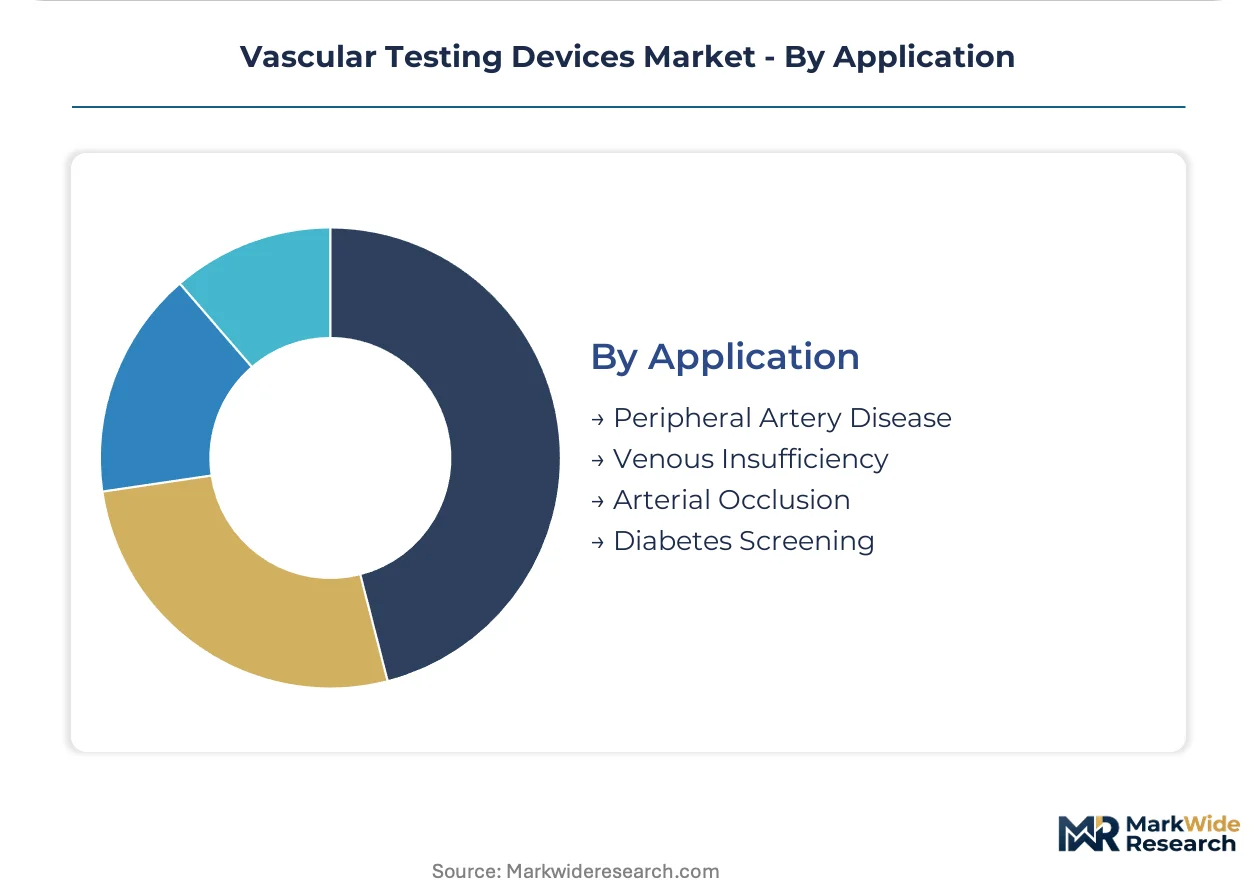
Vascular testing device segmentation reveals how procurement priorities fragment across clinical settings. Technology maturity, reimbursement pathways, and workflow integration requirements create distinct commercial pockets within each category.
Product Type:
Operating frequency ranges and transducer configurations define performance boundaries across anatomical assessment depths.
- Ultrasound:Systems deploy 2-15 MHz transducers for deep and superficial vessel imaging. Hospital systems in the United States prioritize upgradeable cart platforms that extend capital cycles through software module additions.
- Doppler:Continuous and pulsed-wave modalities quantify blood flow velocity without spatial imaging. Wearable Doppler patches gain traction in Germany and France as ambulatory monitoring protocols expand beyond clinic walls.
- Ankle-Brachial Index:Automated cuff systems calculate limb pressure ratios for peripheral artery disease screening. Primary care networks in rural geographies adopt these for point-of-care triage.
- Transcutaneous Oxygen Tension:Electrochemical sensors measure tissue oxygenation at probe-skin interfaces. Wound care centers deploy these for chronic limb ischemia assessment.
Ultrasound leads on scale; Doppler leads on momentum.
Technology:
Connectivity architecture and patient mobility determine reimbursement eligibility and pricing power.
- Non-Invasive:Doppler ultrasound and plethysmography dominate installed bases due to zero procedural risk profiles. EU MDR Class IIa certification requirements compel manufacturers to strengthen clinical evidence packages for these established modalities.
- Invasive:Intravascular pressure wires and flow sensors deliver hemodynamic data during catheterization. Interventional cardiology suites in Japan and South Korea maintain demand despite optical coherence tomography competition.
- Wearable:Miniaturized Doppler patches and photoplethysmography rings enable longitudinal monitoring. FDA 510(k) clearance pathways for iterative algorithm updates accelerate product evolution in this segment.
- Telehealth Solutions:Cloud-connected devices integrate with remote patient monitoring platforms. HIPAA and GDPR compliance constraints force region-specific server deployments that fragment vendor architectures.
Non-invasive systems anchor revenue concentration; wearable platforms show steepest expansion trajectory.
End User:
Capital intensity and technical staffing availability shape device specification requirements across settings.
- Hospitals:Integrated delivery networks negotiate unbundled service contracts for high-volume screening programs. PACS connectivity and AI-enhanced reconstruction modules command premium positioning.
- Clinics:Community vascular practices prioritize portable systems with simplified user interfaces. Sonographer workforce scarcity drives demand for automated measurement tools.
- Diagnostic Laboratories:Centralized testing facilities process high-throughput referrals from dispersed physician networks. Turnaround time requirements favor batch-capable equipment configurations.
- Home Care Settings:Post-acute monitoring protocols create concentrated margin pools where telehealth-integrated devices replace traditional clinic-bound equipment.
Hospitals dominate absolute spend; home care settings expand most quickly.
Application:
Disease prevalence and screening guideline adoption determine addressable population sizes.
- Peripheral Artery Disease:CMS reimbursement codes and EU screening initiatives expand detection program volumes. Ankle-brachial index systems and Doppler ultrasound serve as frontline diagnostic tools.
- Venous Insufficiency:Chronic condition management protocols integrate wearable monitoring for reflux quantification. Compression therapy outcomes validation drives device procurement.
- Arterial Occlusion:Acute limb ischemia triage requires rapid assessment capabilities in emergency departments. Hybrid platforms combining pulse oximetry with photoplethysmography gain protocol inclusion.
- Diabetes Screening:Microvascular complication detection protocols in endocrinology practices drive demand for transcutaneous oxygen tension measurement.
Peripheral artery disease commands largest installed base; diabetes screening climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vascular testing technology first achieved clinical scale in German university hospitals during the 1970s, establishing Doppler ultrasound protocols that spread through European medical education networks before FDA clearance pathways enabled US commercialization in the 1980s.
United States
Integrated delivery networks in Texas and Florida drive procurement volumes for upgradeable cart platforms. CMS reimbursement code expansions for remote patient monitoring legitimize telehealth-integrated vascular assessments. The Minneapolis medical device corridor anchors transducer manufacturing and algorithm development operations.
Germany
Ambulatory monitoring protocols in Bavaria and Baden-Württemberg accelerate wearable Doppler patch deployment. EU MDR notified body capacity constraints extend certification timelines for Class IIa vascular devices. The Erlangen-Nuremberg metropolitan region concentrates ultrasound engineering expertise and clinical trial infrastructure.
Japan
Interventional cardiology suites in Tokyo and Osaka sustain demand for intravascular pressure wire systems. PMDA streamlined review pathways for iterative Doppler algorithms reduce time-to-market for AI-augmented modules. The Kobe medical device cluster hosts manufacturing operations for piezoelectric crystal assemblies.
China
Endocrinology practices in Shanghai and Beijing drive microvascular complication detection protocol expansion. NMPA regulatory harmonization efforts align domestic clinical evidence standards with international benchmarks. The Suzhou industrial park hosts contract manufacturing for transducer probe assemblies serving Asia-Pacific distribution.
United Kingdom
Primary care networks in Greater Manchester and West Midlands adopt automated ankle-brachial index systems for point-of-care triage. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment requirements for EU MDR-certified devices. The Cambridge life sciences cluster supports photoplethysmography algorithm development for hybrid emergency department platforms.
Vascular Testing Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the service-contract unbundling dimension that procurement committees now exploit. The vendor base stratifies into three tiers: diversified imaging conglomerates defending installed bases through PACS integration, mid-size ultrasound specialists competing on algorithm automation, and regional fabricators capturing price-sensitive clinic segments. Consolidation pressure intensifies as notified body capacity constraints favor larger players with dedicated regulatory affairs infrastructure. Strategic moves center on AI module licensing partnerships and backward integration into transducer crystal supply.
Within the diversified imaging conglomerate tier, GE Healthcare, Siemens Healthineers, and Philips Healthcare occupy positions defined by recurring service revenue architectures and upgrade pathway ecosystems. These entities exemplify the shift from replacement-cycle dependence to sustained software licensing models. Unetixs Vascular Inc. and Koven Technology Inc. represent mid-size specialists competing through automated measurement tools that address sonographer workforce scarcity. Fukuda anchors the Asia-Pacific regional fabricator segment with distribution networks calibrated to domestic hospital procurement patterns.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Unetixs Vascular Inc. |
| Fukuda |
| Koven Technology Inc. |
| D.E. Hokanson Inc. |
| Others |
Value Network & Pricing Analysis
Backward integration into piezoelectric crystal fabrication anchors supply security and pricing power for ultrasound transducer manufacturers serving vascular testing markets. Vendors with captive crystal production in Japan and Germany command premium positioning against competitors exposed to East Asian supply concentration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated cart systems from portable units and disposable Doppler patches. FDA 510(k) clearance tier and EU MDR Class IIa certification status drive price differentiation alongside software module bundling. Cost compression in economy-tier wearable segments is intensifying because of contract manufacturing migration to Suzhou industrial facilities. Hospital procurement committees exhibit lowest price sensitivity for PACS-integrated platforms; rural primary care networks show highest sensitivity.
Supply Chain Analysis
Freight cost escalation for temperature-sensitive piezoelectric crystal shipments from Kobe to Minneapolis medical device corridors adds landed cost premiums for North American assembly operations. Manufacturing gravity centers on Japan, Germany, and China for transducer probe assemblies; South Korea supplies specialty semiconductor components for signal processing modules. Single-source vulnerability concentrates in East Asian ceramic substrate fabrication for electrochemical oxygen tension sensors. Distribution runs through hospital GPO contracts in the United States and specialized medical device distributors in European ambulatory care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vascular testing devices function as a stable compounder where chronic disease prevalence and aging demographics generate durable replacement demand across hospital and home care settings.
For Market Incumbents: Lock in recurring revenue through modular upgrade pathways that extend cart system lifecycles beyond traditional replacement cycles. Prioritize backward integration into transducer crystal supply to defend margin position against optical coherence tomography substitution threats in interventional cardiology suites. Invest in FDA 510(k) predicate pathway optimization for AI-augmented reconstruction modules. For New Entrants and Emerging Players: Enter via underpenetrated home care monitoring segments where telehealth reimbursement expansion creates white-space opportunity. Target automated ankle-brachial index systems for rural primary care networks facing sonographer workforce scarcity. Deploy algorithm licensing partnerships with established ultrasound vendors to bypass capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Roll-up economics work for mid-size ultrasound specialists with automated measurement tools because EU MDR notified body capacity constraints favor consolidated regulatory affairs infrastructure. Five-to-ten-year viability hinges on wearable platform convergence with remote patient monitoring reimbursement codes. Watch CMS coding updates for telehealth-integrated vascular assessments as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined clearance for AI-augmented Doppler algorithms accelerates time-to-market velocity. |
| CE Marking Pathway | EU MDR Class IIa certification mandates strengthen clinical evidence packages for European access. |
| Hospital System Partnership | Integrated delivery network contracts secure unbundled service revenue streams. |
| Software Companion Development | AI reconstruction modules extend hardware lifecycle value against replacement pressure. |
| Reimbursement Strategy | CMS remote patient monitoring codes legitimize home care device premium positioning. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Middle East regions, with primary inputs from each combining structured interviews with vascular laboratory directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers alongside secondary validation. FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement schedules, and hospital procurement transaction records anchored data triangulation. Bottom-up equipment shipment analysis and top-down healthcare expenditure allocation models were cross-referenced.
Granularity-level modeling deployed product type, technology architecture, end-user setting, and clinical application dimensions across the projection horizon. CAGRs were derived from installed base evolution and replacement cycle compression patterns. Forecast inputs incorporated sonographer workforce expansion rates, telehealth reimbursement code adoption curves, and EU MDR certification timeline constraints.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time wearable Doppler patch shipment data introduce uncertainty bands around ambulatory monitoring segment projections. Forecasts reflect documented assumptions about reimbursement expansion velocity and certification capacity constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Pathology Instruments Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market