
 Global Biofilms Treatment Market | 2026-2036
Global Biofilms Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biofilms Treatment Market Foresight
Buyer concentration in hospital procurement is recalibrating how biofilm treatment suppliers allocate R&D resources and field sales capacity. Novozymes A/S leverages its enzyme engineering platform to sustain leadership in enzymatic biofilm disruption for chronic infection applications. Ecolab anchors its position through integrated infection prevention programs that bundle surface biofilm control with water treatment protocols. Smith & Nephew competes in surgical settings with specialized wound irrigation formulations designed to penetrate established biofilm matrices.
Biofilms treatment encompasses therapeutic and prophylactic interventions targeting sessile microbial communities encased in extracellular polymeric substances, typically requiring agents that disrupt polysaccharide matrices rather than planktonic organisms alone. These interventions serve primarily to resolve persistent infections in medical devices, chronic wounds, and dental surfaces where conventional antibiotics demonstrate limited efficacy. The antibiotics segment dominates current revenue owing to established reimbursement codes and clinician familiarity, though enzymes represent the fastest-expanding category as hospitals seek alternatives to address antimicrobial resistance. Topical delivery occupies the largest share of administration routes, while intravenous modes command premium pricing in systemic chronic infection management where biofilm burden has disseminated beyond localized sites.
The FDA maintains stringent premarket review pathways for novel anti-biofilm agents, while the EMA's evolving stance on antimicrobial resistance incentives shapes European development priorities and Japan's PMDA accelerates access for breakthrough infection control therapies. These regulatory frameworks collectively elevate clinical evidence requirements and compress timelines for differentiation through superior biofilm eradication data. Stakeholders must monitor evolving antimicrobial stewardship mandates and reimbursement shifts toward outcome-based infection prevention contracts.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously demanding higher clinical evidence thresholds for biofilm-targeting therapies, forcing suppliers to restructure field sales organizations toward value-based account management.
Growth Catalysts
- Antimicrobial stewardship mandates:The FDA's evolving guidance on antimicrobial resistance accelerates hospital adoption of enzymatic and physical biofilm disruption methods as alternatives to conventional antibiotics.
- Chronic wound prevalence:Aging populations in Germany, Japan, and the United States expand addressable patient pools for advanced wound irrigation and debridement protocols targeting established biofilms.
- Medical device infection burden:Catheter-associated and implant-related biofilm infections drive reimbursement expansion for prophylactic anti-biofilm coatings in surgical settings.
Market Restraints
- Clinical validation costs:EMA and FDA requirements for biofilm-specific efficacy endpoints extend development timelines and inflate trial expenditures for novel agents.
- Specialized manufacturing concentration:Production of high-purity therapeutic enzymes clusters among limited European and North American contract manufacturers, creating supply vulnerability.
- Antibiotic substitution pressure:Generic systemic antibiotics remain entrenched in treatment guidelines despite poor biofilm penetration, delaying uptake of targeted alternatives.
Strategic Opportunities
- Japanese regulatory pathway:PMDA's accelerated access framework for breakthrough infection control therapies offers faster commercialization timelines for innovative biofilm disruptors.
- Dental and oral care expansion:Professional dental prophylaxis represents an underpenetrated channel for biofilm-targeting formulations beyond traditional medical device applications.
- Enzyme-antibiotic synergy:Convergence of engineered polysaccharide-degrading enzymes with conventional antibiotics enables combination therapies with differentiated resistance profiles.
Industry Challenges
- Biofilm model standardization:Lack of harmonized in vitro and in vivo testing protocols across ISO and regulatory bodies complicates cross-study comparability and label claims.
- Specialized formulation expertise:Scarce talent pools in extracellular matrix pharmacology and biofilm penetration science constrain R&D throughput for emerging players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biofilms Treatment Market |
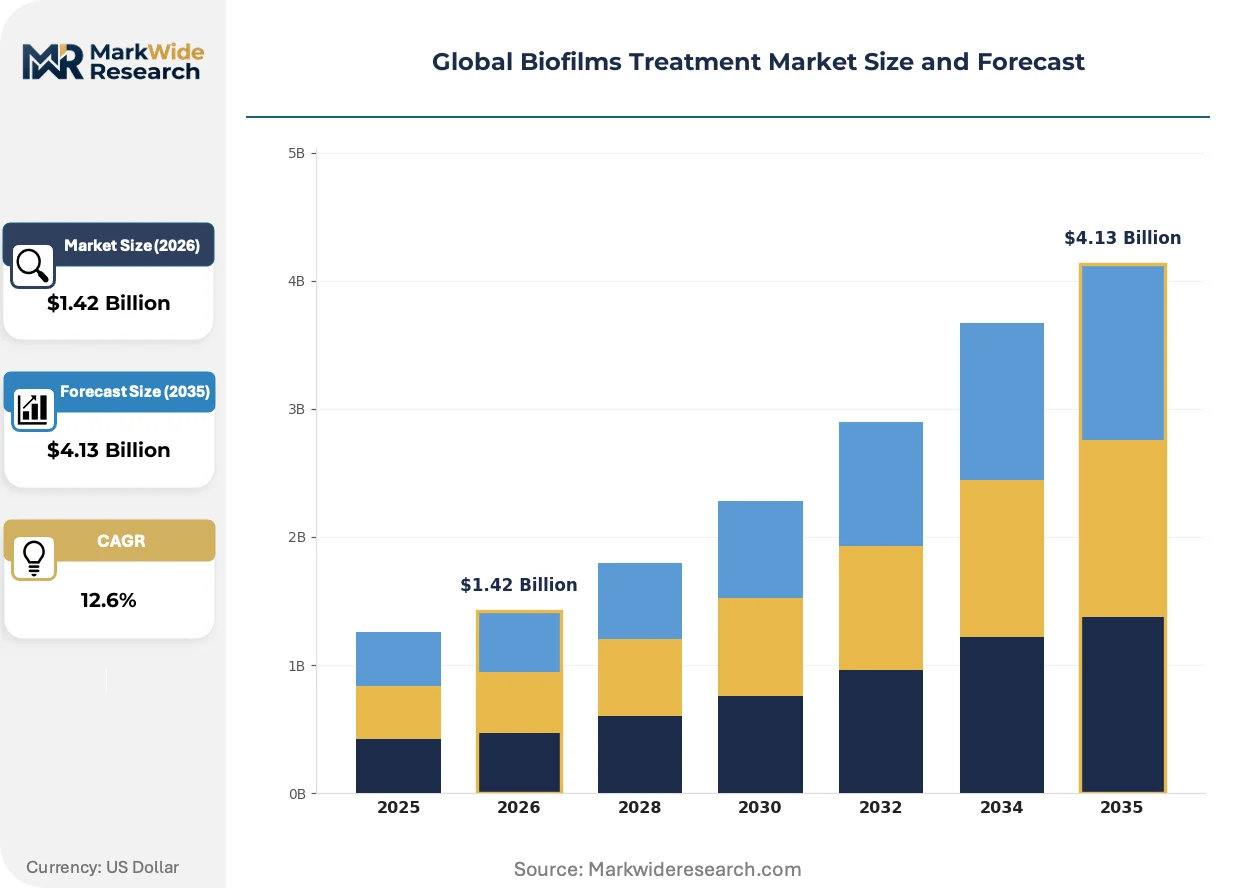
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiseptics, Antifungals, Enzymes Delivery Mode: Topical, Injectable, Oral, Intravenous End User: Hospitals, Clinics, Homecare, Research Laboratories Application: Dental, Surgical, Wound Care, Chronic Infection |
| Companies Covered | Novozymes A/S, 3M Company, Ecolab, Smith & Nephew, ConvaTec Group PLC, Kane Biotech, Pfizer, Merck & Co., Evonik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biofilms Treatment Market Shifts & Advancements
Enzymatic disruption technologies are capturing share from chemical antimicrobials as clinicians prioritize resistance mitigation, while regulatory frameworks increasingly reward biofilm-specific efficacy data over planktonic benchmarks.
Engineered polysaccharide-degrading enzymes now function as precision tools for extracellular matrix dissolution without collateral microbiome damage. Academic medical centers and specialized chronic wound clinics in the United States and Germany are adopting these platforms ahead of community hospitals. This enzymatic approach is overtaking traditional surfactant-based irrigation as the preferred first-line intervention for established device-associated biofilms.
REACH regulation amendments targeting antimicrobial environmental persistence are reshaping formulation chemistry requirements for surface disinfectants and irrigation solutions across European healthcare facilities. Manufacturers must now submit bioaccumulation and ecotoxicity data previously exempted from medical device accessory classifications. Surgical instrument reprocessing and environmental hygiene segments face the steepest compliance burdens, accelerating reformulation investments among established suppliers.
Hospital value analysis committees now mandate outcome-linked contracting for infection prevention bundles, displacing transactional product purchasing. Integrated delivery networks in the United States are consolidating vendor relationships around full-service infection control partnerships rather than discrete product categories. This behavioral shift concentrates procurement influence among three to five national distributors capable of spanning surface, water, and device biofilm management.
Global Biofilms Treatment Market Segmentation
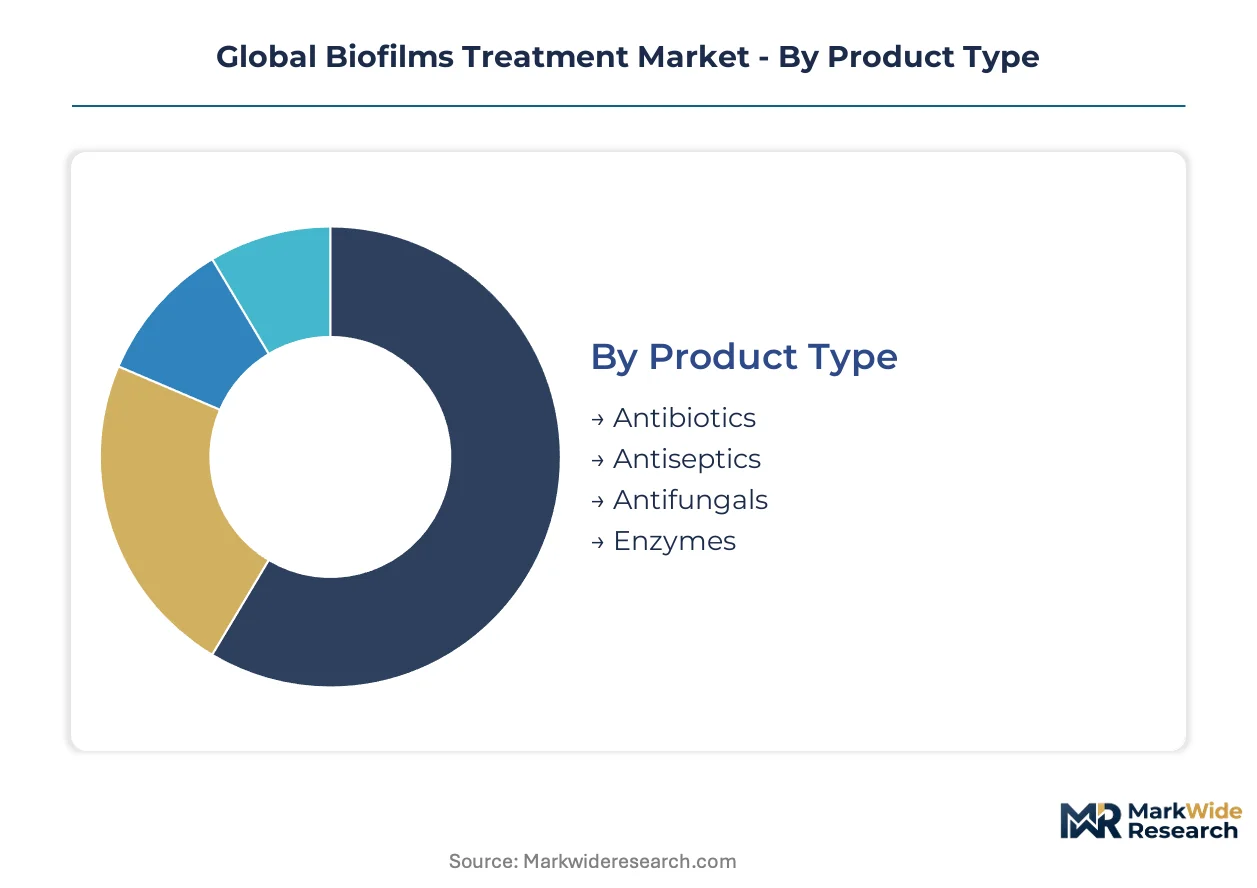
Biofilm treatment procurement diverges sharply across clinical settings, with hospital value analysis committees demanding outcome-linked contracting while homecare channels prioritize ease of administration. Understanding these buyer archetypes shapes how suppliers configure formulation portfolios and field sales organizations.
Product Type:
Hospital formularies differentiate agents based on resistance profiles, reimbursement codes, and compatibility with existing stewardship protocols.
- Antibiotics:Conventional systemic agents dominate current procurement volumes through established reimbursement pathways and clinician familiarity. United States hospital systems anchor demand despite documented limitations in extracellular matrix penetration. Generic substitution pressure compresses margins while delaying uptake of biofilm-targeted alternatives.
- Enzymes:Engineered polysaccharide-degrading proteins disrupt established biofilms without collateral microbiome damage. German academic medical centers and specialized chronic wound clinics in the United States are adopting these platforms ahead of community hospitals. Regulatory incentives for resistance mitigation accelerate formulary placement.
- Antiseptics:Surface-active chemical agents serve prophylactic applications in surgical instrument reprocessing and environmental hygiene.
- Antifungals:Azole and echinocandin formulations address Candida biofilms in catheter-associated and implant-related infections.
Antibiotics lead volumes today; enzymes are gaining share fastest.
Delivery Mode:
Route selection hinges on biofilm penetration depth, systemic burden, and site of infection establishment.
- Topical:Irrigation solutions and wound dressings deliver high local concentrations without systemic exposure. Chronic wound clinics and outpatient surgical centers in Japan and Germany drive demand for advanced formulations with demonstrated extracellular matrix dissolution.
- Intravenous:Systemic administration commands premium pricing in disseminated chronic infections where biofilm burden has escaped localized containment. Hospital procurement consolidation favors suppliers with integrated infection prevention bundles spanning multiple administration routes.
- Injectable:Depot formulations enable sustained release at device insertion sites.
- Oral:Bioavailability challenges limit efficacy against established biofilms; use concentrates in prophylactic dental applications.
Topical administration captures the largest patient volume; intravenous modes generate the highest revenue per course.
End User:
Facility type determines clinical evidence thresholds, contracting mechanisms, and service intensity requirements.
- Hospitals:Integrated delivery networks consolidate vendor relationships around full-service infection control partnerships. Value analysis committees in the United States now mandate outcome-linked contracting for prophylactic device coatings and surgical irrigation protocols.
- Homecare:Long-term wound management and catheter maintenance create recurring demand for simplified administration. Patient adherence limitations favor topical formulations over complex infusion regimens.
- Clinics:Outpatient dental and minor surgical settings concentrate demand for rapid-turnaround prophylaxis.
- Research Laboratories:Academic and contract research organizations drive preclinical validation of novel biofilm disruption mechanisms.
Hospitals dominate absolute spending; homecare channels are expanding most quickly as aging populations shift care settings.
Application:
Disease burden and reimbursement availability vary substantially across anatomical sites and clinical contexts.
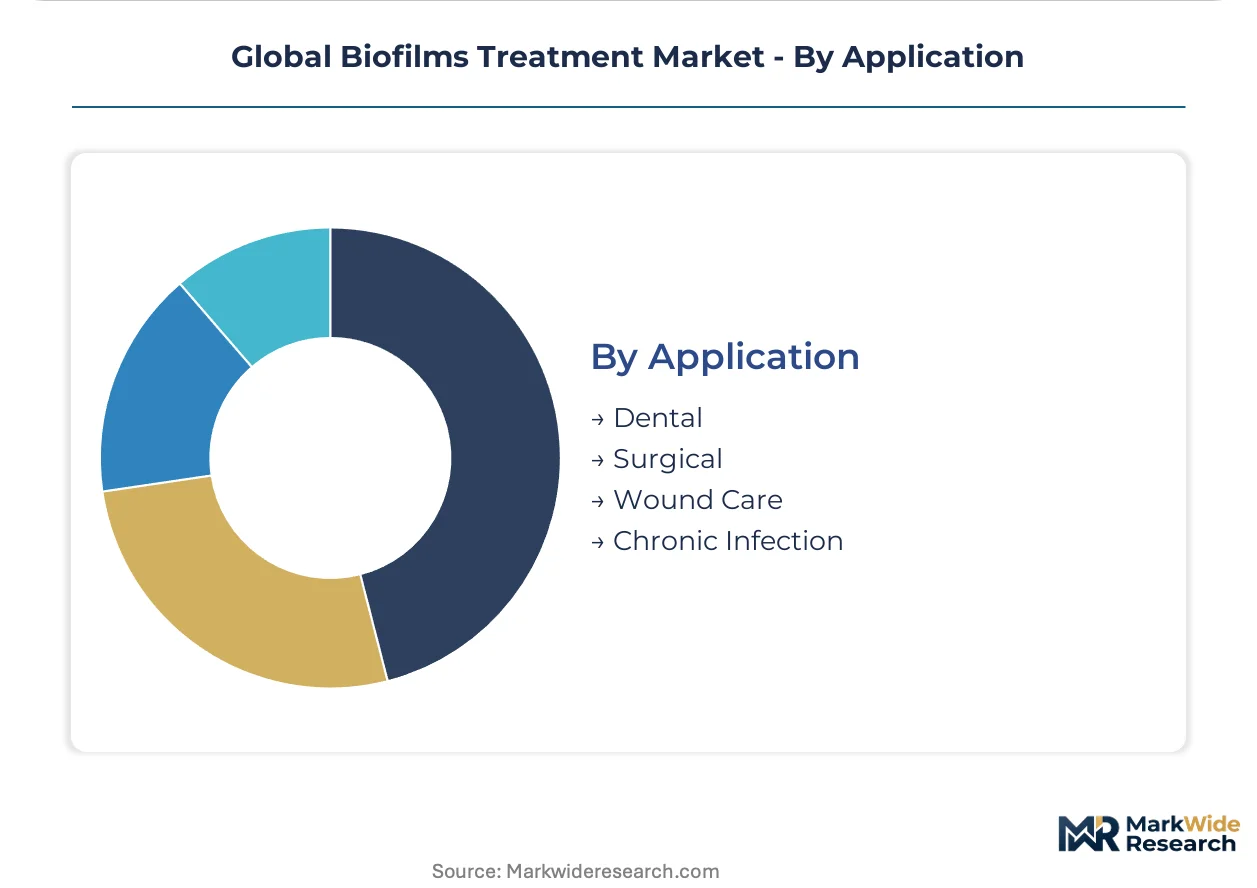
- Wound Care:Chronic diabetic and pressure ulcers represent the largest addressable patient pool. German and Japanese reimbursement expansion for advanced debridement protocols accelerates adoption of enzymatic and surfactant-based irrigation.
- Surgical:Prophylactic anti-biofilm coatings and instrument reprocessing protocols face stringent validation requirements. FDA premarket review pathways and EMA antimicrobial resistance incentives reshape development priorities for device-associated infection prevention.
- Dental:Professional prophylaxis and peri-implantitis management remain underpenetrated relative to medical device applications.
- Chronic Infection:Recurrent catheter-associated and implant-related biofilms drive systemic therapy demand in tertiary care centers.
Wound care leads procedure volumes; surgical applications command the steepest pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biofilm pharmacology talent clusters in Boston, Basel, and Osaka anchor commercial development across three continents. These workforce concentrations shape where enzymatic platforms and device coatings advance from laboratory to market.
United States
Hospital value analysis committees in integrated delivery networks drive procurement consolidation toward full-service infection control partnerships. FDA premarket review pathways for novel anti-biofilm agents elevate clinical evidence requirements for surgical irrigation and device coating submissions. The Boston-Cambridge corridor concentrates therapeutic enzyme engineering and chronic wound clinic adoption of matrix-dissolving platforms.
Germany
Aging demographics expand reimbursement for advanced wound debridement protocols in academic medical centers across Bavaria and North Rhine-Westphalia. REACH regulation amendments targeting antimicrobial environmental persistence reshape formulation chemistry for surface disinfectants and irrigation solutions. The Rhine-Main biotech cluster hosts contract manufacturers specializing in high-purity therapeutic enzymes for biofilm disruption.
Japan
Chronic wound prevalence among elderly populations accelerates demand for topical biofilm-targeting formulations in outpatient surgical settings. PMDA's accelerated access framework for breakthrough infection control therapies compresses commercialization timelines for innovative enzymatic disruptors. The Kansai region around Osaka anchors medical device coating development and hospital procurement of prophylactic anti-biofilm interventions.
United Kingdom
NHS antimicrobial stewardship mandates redirect hospital formulary placement toward enzymatic alternatives with demonstrated resistance mitigation profiles. NICE technology appraisals increasingly require biofilm-specific efficacy endpoints beyond traditional planktonic benchmarks. The Oxford-Cambridge-London golden triangle concentrates R&D talent in extracellular matrix pharmacology and biofilm penetration science.
Switzerland
Specialized chronic wound clinics and tertiary care centers drive premium pricing for intravenous biofilm therapies in systemic infection management. Swissmedic maintains stringent clinical validation requirements that align with EMA antimicrobial resistance incentives shaping European development priorities. The Basel pharmaceutical cluster anchors combination therapy development pairing engineered enzymes with conventional antibiotics.
Global Biofilms Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across enzymatic disruption, surgical irrigation, and integrated infection prevention segments. The vendor base stratifies into three tiers: multinational healthcare conglomerates with bundled service capabilities, mid-cap enzyme engineering specialists, and regional contract manufacturers. Strategic moves concentrate on portfolio diversification into adjacent infection control categories and technology licensing partnerships that accelerate access to biofilm-specific formulation expertise.
Within the enzyme engineering tier, Novozymes A/S and Kane Biotech exemplify pure-play specialists occupying positions anchored to polysaccharide-degrading platform technologies. Among diversified healthcare conglomerates, 3M Company and Smith & Nephew represent archetypal players bundling device coatings with surgical irrigation protocols across hospital procurement channels. Ecolab sits within the integrated service tier, anchoring its competitive position through infection prevention programs that span surface biofilm control and water treatment protocols rather than discrete therapeutic agents.
| Leading Market Players |
|---|
| Novozymes A/S |
| 3M Company |
| Ecolab |
| Smith & Nephew |
| ConvaTec Group PLC |
| Kane Biotech |
| Pfizer |
| Merck & Co. |
| Evonik |
| Others |
Supply & Pricing Matrix
Enzymatic manufacturing scale-up from laboratory to commercial batch sizes simultaneously compresses unit production costs and concentrates supply leverage among European and North American contract manufacturers with validated bioreactor capacity. This dual effect reshapes how biofilm treatment suppliers negotiate procurement terms with hospital systems and integrated delivery networks demanding outcome-linked contracting.
Pricing Analysis
Bundled infection prevention services command premiums over discrete product transactions as hospital value analysis committees prioritize full-service partnerships spanning surface, water, and device biofilm management. Three-tier pricing structure across premium, standard, and economy levels separates matrix-dissolving enzyme formulations from conventional surfactant irrigants and generic antibiotic alternatives. Cost compression in the standard tier intensifies because generic substitution pressure entrenches systemic antibiotics despite poor biofilm penetration. Community hospitals exhibit highest price sensitivity due to constrained formulary budgets, while tertiary care centers in Germany and Japan absorb premium pricing for intravenous systemic therapies.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand, while specialty distributors serve outpatient wound clinics and dental practices with lower volume requirements. High-purity therapeutic enzyme production clusters in Germany, Switzerland, and the United States, creating geographic concentration risk for biofilm-disrupting formulations. Manufacturing draws from recombinant protein expression systems, chromatographic purification resins, and aseptic fill-finish capacity as critical inputs. Single-source vulnerability in contract biomanufacturing capacity constrains supply security as FDA and EMA validation requirements extend facility qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biofilms treatment market functions as a regulatory compounder where FDA antimicrobial resistance guidance and EMA stewardship mandates continuously elevate clinical evidence thresholds, driving sustained R&D investment and consolidation pressure across the vendor base.
For Market Incumbents: Lock in formulary position through outcome-based contracting with integrated delivery networks before enzymatic alternatives achieve broad reimbursement codes. Secure captive supply of high-purity therapeutic enzymes via backward integration into contract manufacturing capacity or exclusive partnerships with Rhine-Main and Basel-based bioreactor facilities. Novozymes A/S and Ecolab demonstrate defensive positioning through platform breadth and service bundling that emerging specialists cannot replicate without decade-long hospital relationship investments. For New Entrants and Emerging Players: Specialty dental distributors represent the most accessible channel partner type for bypassing entrenched hospital procurement consolidation. Dental and oral care prophylaxis remains underpenetrated relative to medical device applications, offering faster formulary placement with lower clinical validation burdens than surgical irrigation protocols. Target professional dental clinics in Japan's Kansai region where PMDA accelerated access frameworks compress commercialization timelines for breakthrough infection control therapies. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap enzyme engineering specialists with validated polysaccharide-degrading platforms but limited commercial infrastructure. Long-term viability hinges on regulatory tailwinds for resistance mitigation and reimbursement expansion for advanced wound debridement across aging populations in Germany and Japan. Watch FDA breakthrough therapy designations for biofilm-specific efficacy endpoints as the signal indicating inflection toward premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts in the United States consolidate vendor relationships around full-service infection control bundles. |
| Reimbursement Strategy | Outcome-linked contracting with CMS and German statutory insurers accelerates formulary placement for enzymatic disruptors. |
| FDA Submission Pathway | Premarket review for novel anti-biofilm agents elevates clinical evidence requirements for surgical irrigation and device coatings. |
| CE Marking Pathway | EMA antimicrobial resistance incentives reshape European development priorities toward biofilm-specific efficacy endpoints. |
| Software Companion Development | Digital adherence tools for homecare wound management differentiate topical formulation suppliers in aging Japanese and German markets. |
Research Methodology
Multiple input streams — primary interviews with hospital procurement managers, formulary directors, and regulatory affairs leads; secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases; plus customs and trade data on therapeutic enzyme imports — were reconciled through bottom-up and top-down triangulation. This approach captured volume and value dynamics across product types, delivery modes, end-user facilities, and anatomical applications.
Historical revenue trajectories were cross-referenced against expert panel inputs from chronic wound clinic directors and biomedical engineers to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include therapeutic agent category, administration route, facility type, and regional regulatory cluster. CAGRs were derived from normalized baseline data and stress-tested against antimicrobial stewardship mandate implementation timelines and reimbursement expansion patterns in the United States, Germany, and Japan.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biofilm model standardization progress, REACH regulation amendment impacts on formulation chemistry, and hospital procurement consolidation velocity. Forecasts reflect documented assumptions on regulatory pathway durations and formulary placement rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Patient Hygiene Aids Market
Infection Control
Infection Control Market
Infection Control
Hand Hygiene Products Market
Infection Control
Surgical Site Infections Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Virus Filtration Market
Infection Control
Alcohol Wipes Market
Infection Control
Intra Abdominal Infection Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Antiseptic Bathing Market
Infection Control
Hand Hygiene Market
Infection Control
Yeast Infection Market