
 Global Brain Implants Market | 2026-2036
Global Brain Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brain Implants Market Foresight
A shortage of fellowship-trained functional neurosurgeons is reorganizing how device companies deploy clinical specialists and training infrastructure. Medtronic leverages its established deep brain stimulation install base across neurological clinics to sustain recurring revenue from implantable pulse generators. Neuralink competes through proprietary electrode array geometries designed for higher channel-count neural signal recording. Boston Scientific anchors its position in movement disorders through cortical stimulation platforms that integrate with existing neurosurgical workflows.
Brain implants comprise chronically implanted devices that interface directly with neural tissue through biocompatible electrode materials such as platinum-iridium alloys or polyimide substrates, transmitting electrical signals to modulate pathological brain activity or restore sensory-motor function. Deep brain stimulation technology dominates current procedure volumes for Parkinson's treatment and epilepsy control, while neural signal recording platforms represent the fastest-expanding margin pool as research institutions and neurosurgical units invest in closed-loop adaptive systems. Implantable chips and microelectrodes capture concentrated R&D investment from firms targeting memory enhancement applications, though electrode arrays retain the largest installed base across existing neurological indications.
FDA breakthrough device pathways and EU MDR conformity requirements are elevating preclinical validation burdens and extending quality management system audits for brain implant manufacturers. Japan's PMDA and South Korea's MFDS maintain distinct biocompatibility testing protocols that fragment regulatory submission strategies across Asia-Pacific markets. Stakeholders must monitor reimbursement coding decisions by CMS and Germany's G-BA, as these determinations directly gate patient access to next-generation cortical stimulation and optogenetic platforms.
Market Dynamics
The functional neurosurgeon shortage is compressing procedure volumes and forcing device manufacturers to restructure clinical training infrastructure around simulation-based credentialing pathways.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for closed-loop adaptive stimulation systems accelerate commercialization timelines for epilepsy control platforms in the United States.
- Platinum-Iridium Alloy Electrodes:Biocompatible materials with demonstrated chronic stability enable longer implant lifecycles and reduce revision surgery rates in movement disorder applications.
- Japan's Reimbursement Maturation:PMDA-established procedure codes for deep brain stimulation now cover Parkinson's treatment in tertiary neurological centers across Tokyo and Osaka prefectures.
Market Restraints
- Polyimide Substrate Supply Concentration:Specialty polymer suppliers in Germany and Switzerland control high-purity medical-grade substrate production, creating input vulnerability for flexible electrode arrays.
- EU MDR Technical Documentation Burden:Extended clinical evaluation report requirements and notified body capacity constraints delay CE marking timelines for novel cortical stimulation devices.
- Non-Invasive Neuromodulation Substitution:Transcranial magnetic stimulation systems for depression and migraine prophylaxis capture patients who would otherwise proceed to implantable interventions.
Strategic Opportunities
- Memory Enhancement Applications:Research institutions in California and Massachusetts are recruiting for hippocampal prosthesis trials targeting cognitive deficit populations outside traditional movement disorder indications.
- South Korea's MFDS Fast-Track:Innovation approval pathways for breakthrough medical devices reduce pre-market review periods for neural signal recording platforms targeting stroke rehabilitation.
- Optogenetics-Convergence:Viral vector delivery systems combined with wireless photostimulation hardware open programmable circuit-specific modulation beyond electrical stimulation limitations.
Industry Challenges
- Fellowship-Trained Functional Neurosurgeon Scarcity:North American academic medical centers graduate fewer than 50 specialists annually capable of deep brain stimulation lead placement, constraining addressable procedure volume.
- Implantable Pulse Generator Battery Replacement Logistics:Surgical resource scheduling for elective generator exchanges competes with de novo implantation capacity in high-volume neurological clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brain Implants Market |
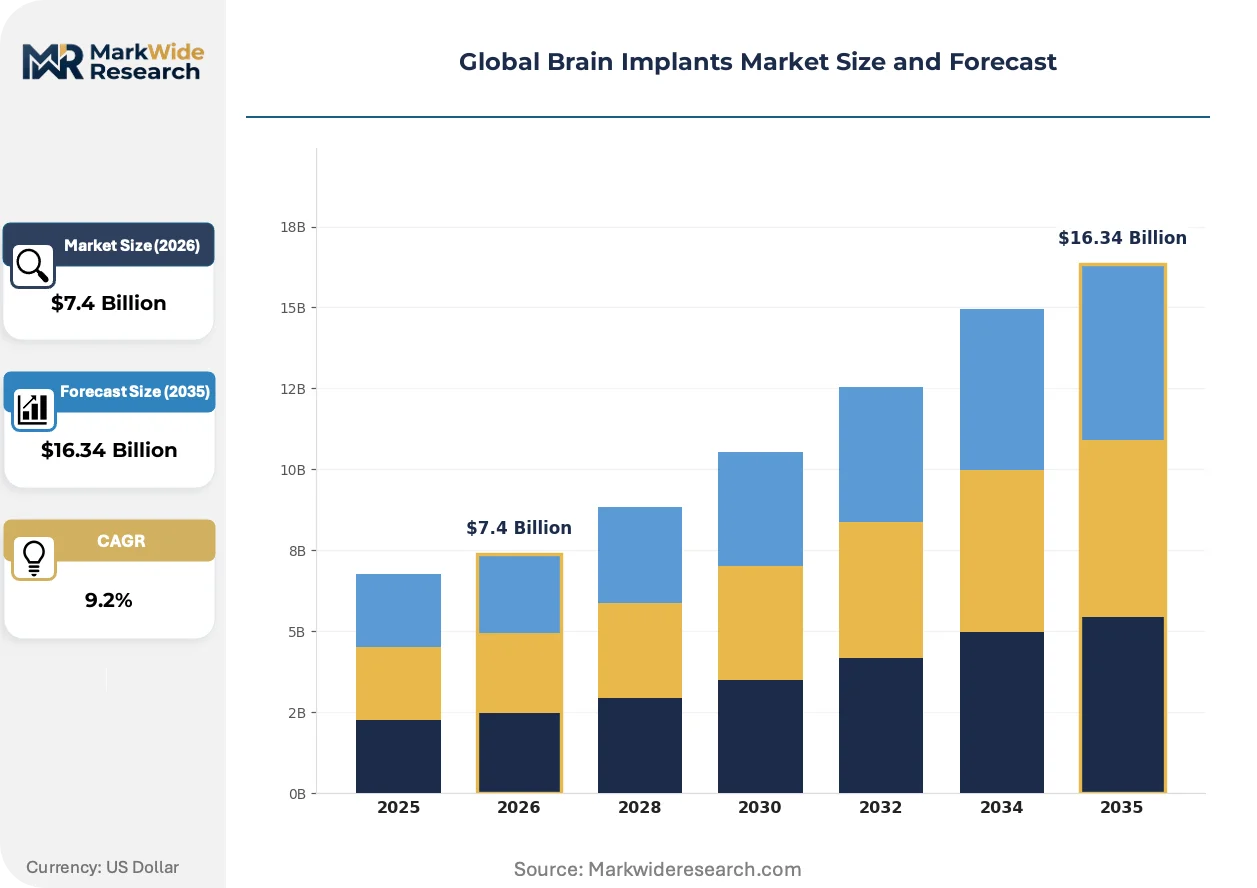
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $16.34 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrode Arrays, Neural Dust, Microelectrodes, Implantable Chips Technology: Deep Brain Stimulation, Cortical Stimulation, Optogenetics, Neural Signal Recording Application: Epilepsy Control, Parkinson’s Treatment, Memory Enhancement, Sleep Disorder Management End User: Neurological Clinics, Research Institutions, Rehabilitation Centers, Neurosurgical Units |
| Companies Covered | Precision Neuroscience, INBRAIN Neuroelectronics, Neuralink, Boston Scientific, Medtronic, Synchron, Paradromics, Cobient, Blackrock Neurotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brain Implants Market Shifts & Advancements
Electrode array architectures are fragmenting into divergent performance tiers as research applications demand higher channel counts while clinical workflows prioritize surgical efficiency and reliability.
High-density neural signal recording is bifurcating the electrode market into research-grade thousand-channel arrays and clinical-grade hundred-channel systems optimized for chronic biocompatibility. Academic neuroengineering laboratories at Stanford and MIT are deploying Utah-style probes with 1,024 active sites for brain-computer interface decoding, while neurological clinics in Cleveland and Munich standardize on 8-contact directional leads for Parkinson's therapy. This technological divergence is compressing R&D budgets as manufacturers maintain parallel development tracks with incompatible validation requirements.
EU MDR Article 117 substance scrutiny is elevating biocompatibility testing burdens for implantable devices containing novel materials or surface modifications. Manufacturers must now demonstrate comprehensive toxicological profiles for electrode coatings and encapsulation polymers through notified body-reviewed chemical characterization studies. Cortical stimulation platforms with polyimide-based flexible substrates face particular documentation intensity, driving consolidation of regulatory affairs functions in Dublin and Brussels hubs.
Neurological clinics are unbundling device procurement from surgical service contracts, creating direct purchasing relationships with manufacturers previously intermediated by hospital procurement consortiums. Large academic medical centers in Texas and Pennsylvania now negotiate implantable pulse generator pricing through centralized supply chain offices rather than physician preference item committees. This purchasing centralization is most pronounced in United States integrated delivery networks managing multiple deep brain stimulation programs across regional hospital systems.
Global Brain Implants Market Segmentation
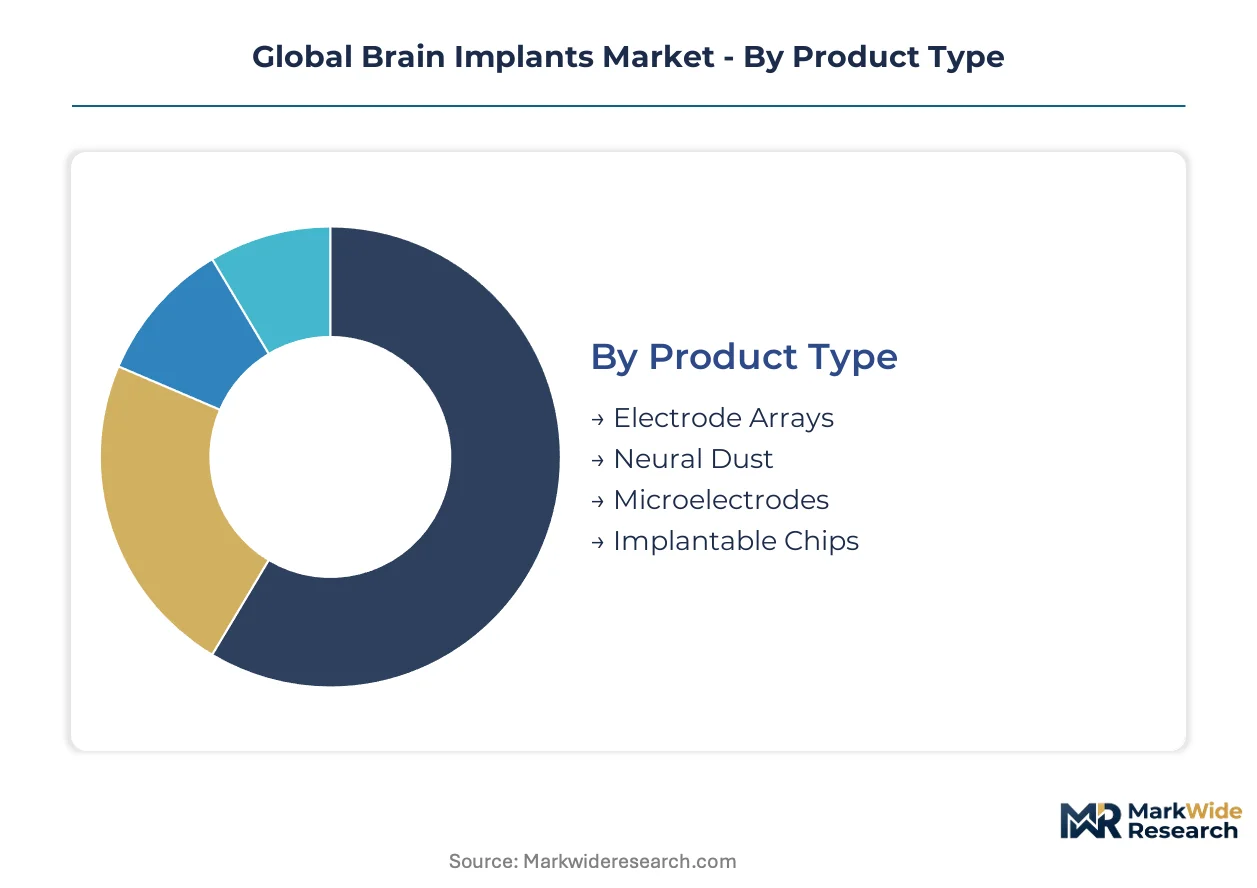
Segmentation in brain implants reveals divergent commercial pathways across research-grade and clinical-grade tiers. Each dimension—product architecture, stimulation modality, therapeutic target, and care setting—carries distinct regulatory burdens and reimbursement profiles that reshape manufacturer resource allocation.
Product Type:
Electrode arrays dominate domestic demand in the United States and Germany where deep brain stimulation procedures concentrate, while neural dust and microelectrodes flow primarily toward export-led research procurement in South Korea and Switzerland.
- Electrode Arrays:Platinum-iridium alloy configurations with 8 to 16 contact sites provide chronic biocompatibility for movement disorder therapy. Demand clusters in Cleveland Clinic and University Hospital Zurich surgical suites where Parkinson's treatment volumes justify dedicated implant inventory.
- Neural Dust:Ultrasonic-powered motes measuring under 100 micrometers enable wireless neural signal recording without transcranial wiring. Research institutions at MIT and Caltech drive procurement for brain-computer interface development despite unresolved encapsulation durability questions.
- Microelectrodes:Silicon-based shank arrays with high-density recording sites serve acute intraoperative mapping in epilepsy control procedures.
- Implantable Chips:Application-specific integrated circuits for closed-loop adaptive stimulation are scaling from prototype to pilot manufacturing in South Korean foundries.
Electrode arrays command the established base. The steepest expansion runs through neural dust architectures.
Technology:
Cost tiering separates mature electrical stimulation platforms from premium optogenetic systems, with neural signal recording occupying a mid-tier position as hardware commoditizes while software analytics retain margin.
- Deep Brain Stimulation:Implantable pulse generators with quadripolar leads deliver targeted electrical modulation to subthalamic nuclei. FDA-cleared indications for Parkinson's treatment and epilepsy control sustain recurring revenue through battery replacement cycles at neurological clinics in Texas and Pennsylvania.
- Neural Signal Recording:High-channel-count acquisition systems capture local field potentials for closed-loop algorithm training. Research institutions in Massachusetts and California absorb capital equipment costs ahead of clinical translation, compressing near-term margins.
- Cortical Stimulation:Epidural or subdural electrode placements address stroke rehabilitation and chronic pain outside basal ganglia targets.
- Optogenetics:Viral vector delivery combined with wireless photostimulation enables cell-type-specific circuit modulation at prototype scale.
Deep brain stimulation captures the revenue concentration. Neural signal recording gains share fastest as adaptive algorithms mature.
Application:
Volume distribution favors movement disorders and seizure control where reimbursement codes exist, while memory enhancement and sleep applications remain investigational with concentrated geography in academic medical centers.
- Parkinson's Treatment:Bilateral subthalamic nucleus stimulation reduces motor fluctuations and dyskinesia in patients with advanced disease. Germany's G-BA and Japan's PMDA have established procedure codes that gate patient access in tertiary neurological centers.
- Epilepsy Control:Responsive neurostimulation systems detect seizure onset and deliver counter-stimulation to hippocampal or neocortical foci. FDA breakthrough device designations have accelerated review timelines for closed-loop platforms targeting drug-resistant populations.
- Memory Enhancement:Hippocampal prosthesis trials for cognitive deficit populations recruit outside traditional movement disorder indications.
- Sleep Disorder Management:Hypoglossal nerve stimulation and thalamic targets for insomnia remain preclinical or early clinical stage.
Parkinson's treatment anchors the installed base. Memory enhancement climbs the fastest trajectory through DARPA-funded research programs.
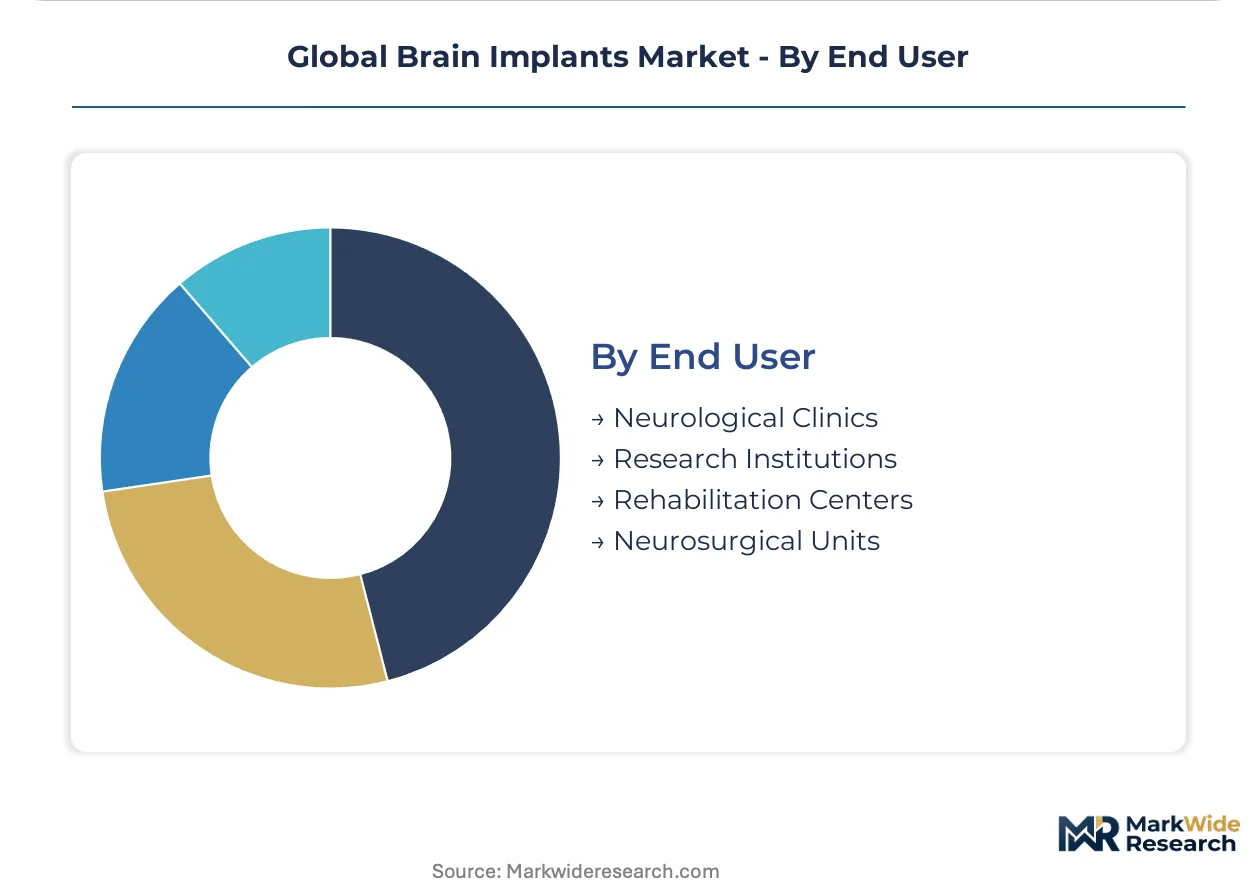
End User:
Customer type stratifies procurement authority, with neurological clinics and neurosurgical units holding capital budgets for implantable systems while research institutions and rehabilitation centers concentrate on consumables and training infrastructure.
- Neurological Clinics:Integrated delivery networks in the United States manage deep brain stimulation programs across regional hospital systems, centralizing implantable pulse generator purchasing through supply chain offices rather than physician preference committees.
- Research Institutions:Academic neuroengineering laboratories at Stanford, MIT, and ETH Zurich deploy thousand-channel recording arrays for brain-computer interface decoding, driving demand for high-density electrode substrates with less stringent chronic biocompatibility requirements.
- Neurosurgical Units:Operating room scheduling constraints and fellowship-trained functional neurosurgeon scarcity limit procedure throughput in high-volume centers.
- Rehabilitation Centers:Post-implant programming and device optimization services capture recurring revenue streams separate from surgical implantation.
Neurological clinics command the established base. Research institutions show the steepest expansion through DARPA and NIH funding cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States prioritizes chronic therapeutic implants for movement disorders, while Switzerland and South Korea concentrate procurement on research-grade neural interfaces for brain-computer interface development.
United States
FDA breakthrough device designations for closed-loop epilepsy systems and established CMS reimbursement codes for Parkinson's treatment drive domestic demand. The agency's expedited review pathways compress commercialization timelines for adaptive neurostimulation platforms. Cleveland Clinic and Massachusetts General Hospital anchor surgical volumes in Ohio and Massachusetts, where integrated delivery networks centralize implantable pulse generator purchasing through supply chain offices.
Germany
G-BA procedure coding for deep brain stimulation in tertiary neurological centers gates patient access to movement disorder therapy. EU MDR conformity requirements and notified body capacity constraints extend CE marking timelines for novel cortical stimulation devices. University Hospital Zurich and Charité Berlin concentrate surgical expertise in Baden-Württemberg and Berlin-Brandenburg, where fellowship-trained functional neurosurgeons manage high-volume implant programs.
Japan
PMDA-established reimbursement codes now cover subthalamic nucleus stimulation for advanced Parkinson's cases in designated tertiary centers. The regulator maintains distinct biocompatibility testing protocols that fragment submission strategies from EU and US pathways. Tokyo and Osaka prefectures host the highest surgical volumes, with Keio University Hospital and Osaka University Hospital standardizing on 8-contact directional leads for chronic therapy.
South Korea
MFDS innovation approval pathways reduce pre-market review periods for neural signal recording platforms targeting stroke rehabilitation. Government-funded brain research initiatives channel procurement toward high-density electrode arrays for academic neuroengineering laboratories. Seoul Capital Area and Daejeon-Sejong clusters concentrate R&D investment, with Korea Advanced Institute of Science and Technology deploying thousand-channel acquisition systems for closed-loop algorithm development.
Switzerland
Swissmedic maintains alignment with EU MDR substance scrutiny requirements while preserving faster notified body engagement for breakthrough device categories. ETH Zurich and University of Geneva drive research-grade procurement for wireless neural dust and optogenetic platforms. The Zurich-Geneva corridor concentrates specialty polymer suppliers controlling high-purity medical-grade polyimide substrate production for flexible electrode arrays.
Global Brain Implants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in brain implant supply. Medtronic and Boston Scientific anchor the upper tier through established deep brain stimulation install bases and recurring revenue from implantable pulse generator replacements. Neuralink and Synchron occupy a distinct archetype focused on high-channel-count neural interfaces for brain-computer interface applications. Blackrock Neurotech and Paradromics represent research-grade specialists supplying academic laboratories. Competitive moves concentrate on simulation-based clinical training infrastructure and regulatory affairs consolidation in Dublin and Brussels hubs.
Among US-based integrated device manufacturers, Medtronic and Boston Scientific occupy positions sustained by chronic therapeutic implant ecosystems. Neuralink exemplifies the venture-backed neural interface archetype pursuing higher-density recording geometries. Precision Neuroscience and INBRAIN Neuroelectronics represent the flexible electrode substrate specialist tier targeting minimally invasive insertion workflows. Synchron anchors the vascular-access approach to neural signal acquisition, diverging from transcranial surgical placement paradigms.
| Leading Market Players |
|---|
| Precision Neuroscience |
| INBRAIN Neuroelectronics |
| Neuralink |
| Boston Scientific |
| Medtronic |
| Synchron |
| Paradromics |
| Cobient |
| Blackrock Neurotech |
| Others |
Supply & Pricing Matrix
Chronic biocompatibility validation at scale concentrates manufacturing among firms with established FDA master files and EU notified body relationships, compressing price floors for platinum-iridium electrode arrays while elevating premiums for novel polyimide substrate configurations. This scale dynamic locks smaller entrants into higher per-unit validation costs across neurological clinic procurement cycles.
Pricing Analysis
Long-term offtake agreements between integrated delivery networks and implantable pulse generator manufacturers dominate procurement, with spot purchasing limited to research-grade microelectrode arrays for academic laboratories. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop adaptive systems from directional leads and basic quadripolar configurations. Cost compression in standard-tier movement disorder therapy is intensifying because non-invasive neuromodulation substitutes capture price-sensitive patients. Research institutions exhibit highest price sensitivity due to grant-funded procurement constraints, while neurological clinics prioritize reliability over unit cost.
Supply Chain Analysis
Specialty polymer production in Germany and Switzerland controls high-purity medical-grade polyimide substrate output, creating a chokepoint for flexible electrode array manufacturers dependent on chronic encapsulation performance. Raw material flows draw from platinum-iridium alloy suppliers in the United States, silicon foundries in South Korea, and biocompatible coating specialists in Japan. Single-source vulnerability concentrates in substrate-grade polymer purification, where two suppliers serve the global medical device tier. Distribution runs through hospital procurement consortiums and direct purchasing relationships with large academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA breakthrough device pathways and established reimbursement codes constructs formidable defensive moats for incumbents, while surgeon training infrastructure creates switching costs that resist displacement.
For Market Incumbents: Consolidate simulation-based credentialing partnerships with fellowship programs to lock in procedural volume against the functional neurosurgeon shortage. Deepen backward integration into platinum-iridium alloy sourcing to offset substrate supply concentration. Priority rests on controlling implantable pulse generator replacement logistics before non-invasive substitutes erode elective surgery scheduling capacity.
For New Entrants and Emerging Players: Lead with vascular-access neural signal acquisition platforms that bypass transcranial surgical placement constraints, targeting stroke rehabilitation applications in South Korea's MFDS fast-track pathway. Memory enhancement trials for hippocampal prosthesis development represent the most penetrable white-space segment outside established movement disorder indications. Go-to-market execution should anchor in research institution partnerships with DARPA funding exposure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among implantable pulse generator manufacturers with established neurological clinic install bases and battery replacement cycles. Long-term viability across the projection horizon favors firms with parallel regulatory submissions in FDA, EU MDR, and Japan PMDA pathways. Acquisition targets should demonstrate closed-loop algorithm capabilities. The signal to monitor is CMS reimbursement coding decisions for next-generation cortical stimulation platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Simulation-Based Training Infrastructure | Addresses functional neurosurgeon scarcity by compressing credentialing timelines for deep brain stimulation lead placement. |
| FDA Breakthrough Device Submission | Expedites commercialization pathways for closed-loop epilepsy control systems in the United States. |
| EU MDR Notified Body Consolidation | Centralizes regulatory affairs functions in Dublin and Brussels to manage Article 117 substance scrutiny. |
| Research Institution Partnership | Captures high-channel-count neural signal recording demand from Stanford, MIT, and ETH Zurich laboratories. |
| Reimbursement Strategy Development | Gates patient access through CMS, Germany's G-BA, and Japan's PMDA procedure code establishment. |
Research Methodology
Cross-validation between primary interviews with functional neurosurgeons, biomedical engineers, and hospital purchasing committee members and secondary sources including FDA 510(k) filings, EU MDR technical documentation, and CMS reimbursement databases anchors the qualitative findings. Bottom-up triangulation across implantable pulse generator shipment data and top-down validation through neurological clinic procedure volume estimates calibrate market sizing. Secondary sources include PMDA approval summaries, MFDS innovation pathway disclosures, and academic neuroengineering laboratory procurement records.
Sensitivity analysis around fellowship-trained surgeon graduation rates, battery replacement cycle frequency, and non-invasive substitution elasticity informs the analytical framework across the modeling period. Segmentation dimensions include product architecture, stimulation modality, therapeutic target, and care setting. CAGRs derive from installed base expansion rates and replacement revenue capture. Industry-specific inputs incorporate EU MDR transition timelines and PMDA reimbursement maturation trajectories.
The analysis sits within stated boundaries; outcomes outside established FDA breakthrough device designations and mature reimbursement pathways would require recalibration. Forecasts reflect assumptions regarding surgeon training pipeline recovery and substrate supply concentration stability. Practitioners should keep alternative scenarios live as non-invasive neuromodulation efficacy data and optogenetics clinical translation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Contact Cast Systems Market
Medical Devices
Germany Anesthesia Devices Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Smart Stairlift Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Brazil Angioplasty Devices Market