
 PP Capacitor Films Market | 2026-2036
PP Capacitor Films Market Size, Share, and Industry Trends Forecast 2026-2036
PP Capacitor Films Market Analytics
Direct procurement from resin compounders to film converters is tilting as capacitor OEMs seek tighter thickness tolerances for high-frequency applications. Toray Industries leverages its biaxial orientation expertise to supply ultra-thin grades for EV power modules. Borealis AG anchors European supply through backward integration into polypropylene resin and captive additives. Cosmo Films competes on cost-optimized cast film output for consumer-grade capacitors across South Asian assembly lines.
PP capacitor films are biaxially oriented or cast polypropylene dielectrics, typically manufactured in thicknesses from 1μm to 10μm, that store electrical energy in metallized-layer configurations for pulse and AC filtering applications. The biaxially oriented segment leads in revenue due to its superior dielectric strength and thermal stability under inverter-grade ripple currents. Cast film occupies the volume-intensive consumer electronics tier where 2μm-5μm specifications balance performance against material cost. Thinner 1μm grades are gaining traction in automotive DC-link capacitors as silicon carbide switching frequencies rise.
Japan's METI enforces JIS standards for film capacitor reliability in industrial equipment, while the EU F-Gas Regulation pressures manufacturers toward dry-type film constructions that eliminate impregnation fluids. China's NMPA and GB standards govern safety certifications for grid-connected renewable energy capacitors, creating compliance layers for imported dielectrics. Stakeholders must monitor how REACH amendments and emerging PFAS restrictions in Europe reshape polypropylene additive formulations and metallization adhesion chemistry.
Market Dynamics
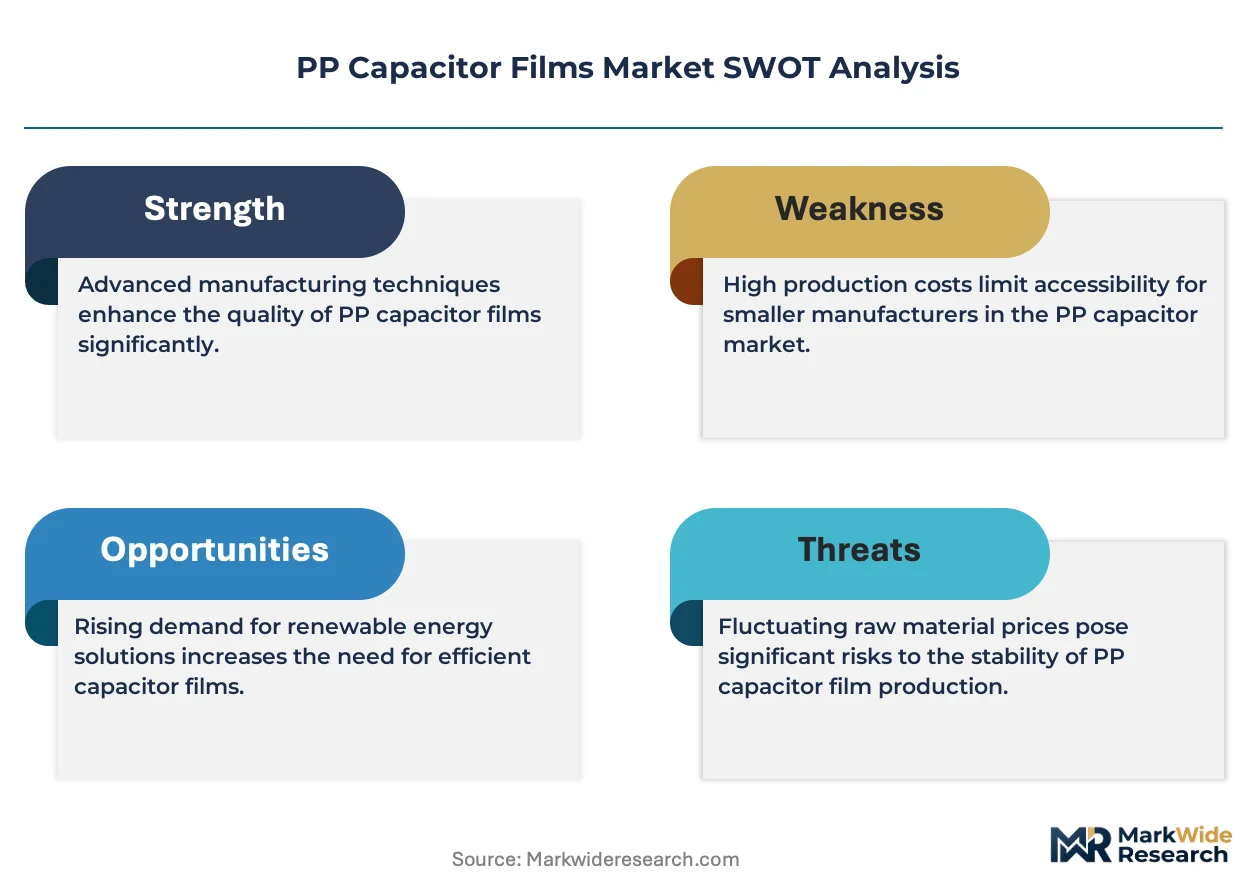
Silicon carbide inverter architectures are compressing dielectric thickness requirements across automotive and renewable energy capacitor supply chains, forcing film converters to recalibrate extrusion and orientation parameters for sub-2μm specifications.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon impregnants in high-voltage capacitors accelerates dry-type metallized film adoption for grid-tied solar inverters and wind turbine converters.
- Electric vehicle powertrain electrification:Automotive OEMs in South Korea and Japan are scaling orders for 1μm-3μm biaxially oriented grades to serve silicon carbide-based DC-link modules operating above 20kHz switching frequencies.
- China's dual carbon policy framework:Provincial renewable energy mandates and carbon intensity targets are expanding domestic demand for high-voltage DC capacitors in utility-scale battery storage and photovoltaic installations.
Market Restraints
- Propylene feedstock volatility:Polypropylene resin prices fluctuate with naphtha and propane cracking economics, compressing margin buffers for film converters without captive polymerization assets.
- Metallization equipment concentration:Vacuum deposition system supply concentrates among German and Japanese capital equipment manufacturers, creating capex bottlenecks for capacity expansion.
- Thickness-tolerance yield limits:Sub-1.5μm biaxial orientation processes exhibit elevated pinhole defect rates, constraining volume output for automotive-grade specifications.
Strategic Opportunities
- India's renewable energy buildout:Central Electricity Authority targets for solar and wind capacity are creating demand for cost-optimized cast film capacitors in domestic inverter manufacturing clusters.
- REACH amendment compliance services:Film converters with in-house additive formulation capabilities can capture premium positioning by pre-certifying metallization adhesion chemistries against emerging PFAS restrictions.
- Solid-state battery buffer integration:Hybrid energy storage architectures combining lithium-ion cells with film capacitor buffers for pulse power smoothing represent an emerging specification channel.
Industry Challenges
- Thin-film process engineering talent scarcity:Biaxial orientation line operators with expertise in sub-2μm gauge control and real-time defect detection are concentrated among Japanese and German engineering cohorts.
- Multi-standard certification complexity:Capacitor OEMs must simultaneously satisfy JIS reliability protocols for industrial equipment, GB safety certifications for Chinese grid connection, and IEC standards for European renewable installations.
- Legacy metallization chemistry requalification:Substituting zinc-aluminum alloy compositions for pure aluminum to meet corrosion resistance specifications requires extensive inverter-grade ripple current testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PP Capacitor Films Market |
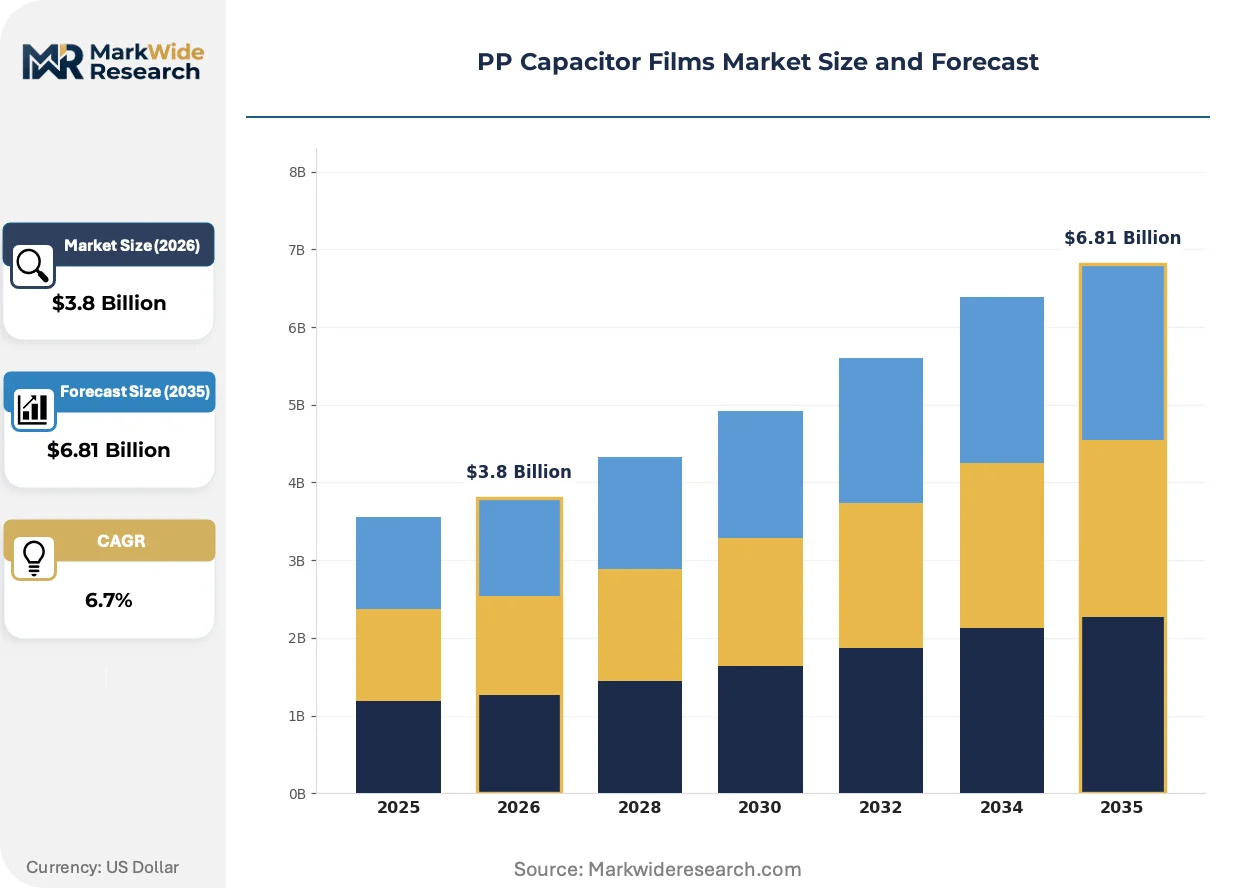
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Biaxially Oriented, Cast, Stretched, Non-Oriented Application: Power Electronics, Automotive, Renewable Energy, Consumer Electronics End User: OEMs, Automotive Manufacturers, Electronics Companies, Renewable Energy Firms Thickness: 1μm, 2μm, 5μm, 10μm |
| Companies Covered | Toray Industries, Shin-Etsu Chemical, Mitsubishi Chemical Corporation, Bolloré Group, JPFL Films, Cosmo Films, DuPont Teijin Films, Treofan Group, Borealis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PP Capacitor Films Market Evolving Landscape
Dielectric film technology is bifurcating between ultra-thin automotive specifications and cost-optimized renewable energy grades, while regulatory chemistry constraints and procurement model compression reshape competitive positioning across the value chain.
Co-extruded multilayer polypropylene architectures are hybridizing discrete dielectric and mechanical functions into single-web constructions. Tier-1 automotive capacitor suppliers in Japan and South Korea are qualifying these structures for 800V platform DC-link modules. This convergence is hybridizing what were previously separate film and separator supply chains, consolidating supplier relationships and compressing qualification timelines for new material entrants.
REACH amendments targeting per- and polyfluoroalkyl substances are forcing reformulation of metallization adhesion promoters and surface treatment chemistries. European film converters are accelerating migration to silicone-based and plasma-activated adhesion systems ahead of enforcement timelines. The dry-type high-voltage segment faces the steepest compliance burden, with German and Austrian capacitor manufacturers front-loading inventory to bridge requalification gaps.
Capacitor OEM procurement is consolidating specification-setting authority at headquarters technical centers, displacing distributed plant-level purchasing. Tier-1 automotive and renewable energy buyers in Germany, Japan, and China are mandating direct film converter relationships with locked thickness tolerance bands and statistical process control documentation. South Korean power electronics manufacturers exhibit the most centralized procurement concentration, with inverter division engineers specifying resin grades and orientation parameters directly.
PP Capacitor Films Market Segmentation
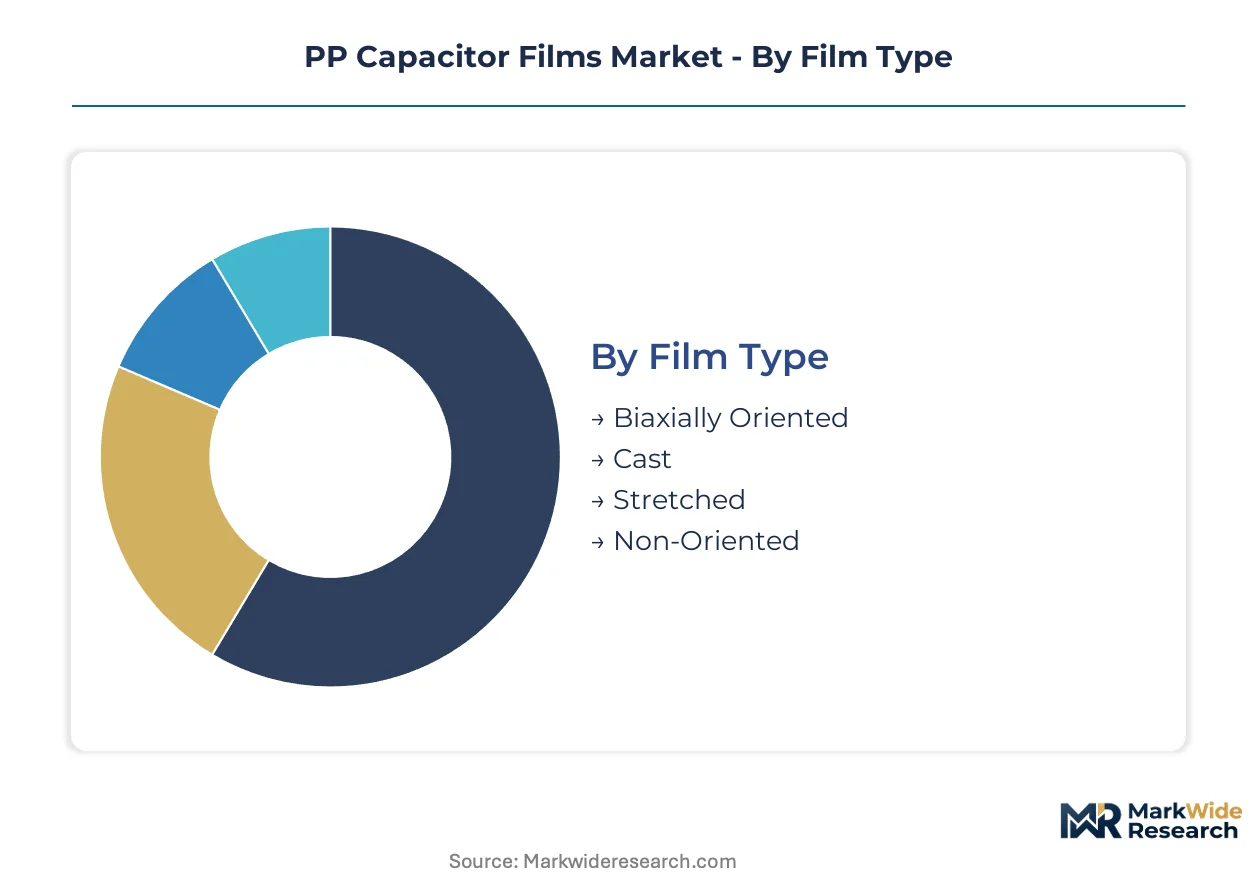
Segmentation in PP capacitor films tracks how dielectric specifications fragment across switching frequency requirements and voltage tolerance bands. Each dimension—film construction, application intensity, procurement channel, and gauge—carries distinct margin profiles and qualification barriers that reshape supplier positioning.
Film Type:
Mature biaxial orientation processes dominate high-reliability tiers, while emerging cast film variants capture cost-sensitive volume applications.
- Biaxially Oriented:Polypropylene films stretched in machine and transverse directions achieve dielectric strengths exceeding 600kV/mm and thermal stability above 105°C. Japanese precision film corridors in Shiga and Gifu prefectures concentrate output for 800V EV inverter modules where silicon carbide switching above 20kHz demands sub-2μm gauge control.
- Cast:Extruded and rapidly cooled films without orientation deliver 2μm-5μm specifications at 15-20% lower unit cost. Indian inverter assembly clusters in Gujarat and Tamil Nadu absorb cast film volumes for utility-scale solar installations where 50Hz grid frequencies tolerate moderate dielectric loss.
- Stretched:Monoaxially oriented variants balance mechanical strength against dielectric uniformity for industrial motor run capacitors.
- Non-Oriented:Unstretched extruded films serve legacy AC motor applications and price-commoditized consumer electronics filtering.
Biaxially oriented grades handle the majority of throughput; cast film is the fastest mover on share.
Application:
Application segmentation follows voltage stress intensity and ripple current density, with cost tiers separating automotive precision from renewable energy scale.
- Power Electronics:Industrial drives, welding equipment, and uninterruptible power supplies require 3μm-5μm biaxially oriented films with metallized self-healing properties. German and Austrian capacitor OEMs specify these grades for 690V industrial bus architectures.
- Automotive:DC-link capacitors for traction inverters and onboard chargers operate at 400V-800V with switching frequencies climbing toward 50kHz. South Korean power electronics divisions at Hyundai and Kia lock thickness tolerances at ±0.1μm for 1μm-2μm specifications.
- Renewable Energy:Grid-tied solar inverters and wind turbine converters prioritize 5μm-10μm films with dry-type construction to satisfy EU F-Gas Regulation phasedown timelines.
- Consumer Electronics:Power supply filtering and ballast applications absorb 2μm-4μm cast film output from South Asian converter lines.
Power electronics maintains the broadest specification range; automotive is expanding most quickly on share.
End User:
End user segmentation reflects procurement centralization intensity, with OEM technical centers displacing distributed plant purchasing.
- OEMs:Tier-1 capacitor manufacturers in Germany, Japan, and China mandate direct film converter relationships with statistical process control documentation locked to thickness tolerance bands.
- Automotive Manufacturers:South Korean and Japanese OEMs specify resin grades and orientation parameters directly, bypassing traditional distributor channels for DC-link module supply.
- Electronics Companies:Consumer-grade capacitor assemblers in South Asia and Southeast Asia rely on spot market procurement for 2μm-5μm cast film volumes.
- Renewable Energy Firms:Utility-scale inverter manufacturers in China and India qualify film converters against GB and BIS standards for grid-connection certification.
OEMs handle the majority of throughput; automotive manufacturers are gaining share fastest.
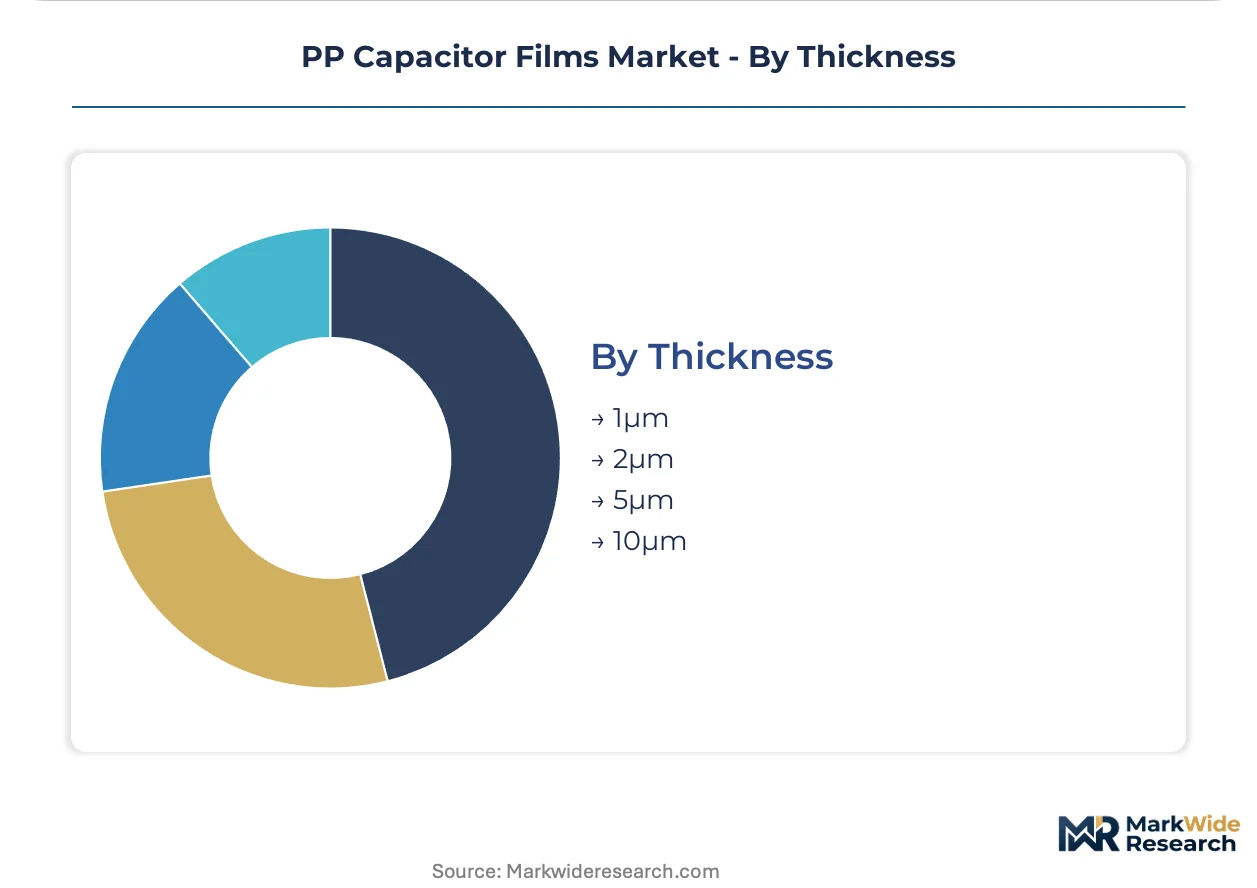
Thickness:
Thickness segmentation tracks the compression trajectory driven by silicon carbide inverter architectures and thermal density constraints.
- 1μm:Ultra-thin biaxially oriented grades for 800V automotive platforms achieve energy density targets but exhibit elevated pinhole defect rates that constrain yield. Japanese film converters in Toray's supply network dominate qualification timelines.
- 2μm:The crossover specification balancing dielectric strength against manufacturability for 400V-800V EV modules and high-frequency industrial drives.
- 5μm:Utility-scale renewable energy capacitors and standard industrial equipment favor this gauge for dry-type high-voltage constructions.
- 10μm:Legacy high-voltage DC and pulse power applications where energy density is secondary to mechanical robustness.
2μm handles the majority of throughput; 1μm is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qinghai-Tibet ultra-high-voltage DC transmission corridor anchors China's renewable energy export capacity, while Japan's precision film belt and South Korea's electronics corridor concentrate dielectric manufacturing for automotive and industrial capacitor supply chains.
China
Provincial renewable energy mandates under the dual carbon policy framework are scaling orders for high-voltage DC capacitors in utility-scale battery storage and photovoltaic installations. GB standards and NMPA safety certifications govern grid-connection requirements for imported dielectrics. Manufacturing clusters in Jiangsu and Zhejiang provinces are absorbing cast and biaxially oriented film volumes for domestic inverter assembly.
Japan
Silicon carbide inverter architectures from automotive OEMs are compressing dielectric thickness requirements toward sub-2μm specifications. METI enforces JIS reliability standards for film capacitor performance in industrial equipment. The precision film belt spanning Shiga and Gifu prefectures concentrates output for 800V EV inverter modules where switching frequencies exceed 20kHz.
South Korea
Hyundai and Kia power electronics divisions are mandating locked thickness tolerances at ±0.1μm for 1μm-2μm biaxially oriented grades. Centralized procurement concentration at inverter division technical centers bypasses traditional distributor channels. The Seoul-Incheon manufacturing corridor houses capacitor OEM qualification facilities for DC-link module supply.
Germany
The EU F-Gas Regulation phasedown of hydrofluorocarbon impregnants is accelerating dry-type metallized film adoption for grid-tied solar inverters and wind turbine converters. ECHA REACH amendments targeting PFAS substances are forcing metallization adhesion chemistry reformulation. Bavarian and Baden-Württemberg capacitor manufacturers are front-loading inventory to bridge requalification gaps.
India
Central Electricity Authority targets for solar and wind capacity expansion are creating demand for cost-optimized cast film capacitors in domestic inverter manufacturing clusters. BIS certification requirements govern grid-connection standards for renewable energy installations. Gujarat and Tamil Nadu assembly clusters are absorbing 2μm-5μm cast film volumes for utility-scale solar where 50Hz grid frequencies tolerate moderate dielectric loss.
PP Capacitor Films Market Competitive Landscape
On the supply side, the industry is consolidating around backward-integrated resin compounders and specialized film converters with captive orientation expertise. Japanese and European players anchor the premium tier through biaxial orientation mastery, while South Asian and Middle Eastern converters compete on cost-optimized cast output. Three archetypes dominate: integrated resin-to-film operators, precision orientation specialists, and scale-driven cast film producers. Capacity expansion and direct OEM technical relationships constitute the dominant competitive moves.
Among integrated chemical conglomerates, Toray Industries and Mitsubishi Chemical Corporation occupy positions exemplifying the precision orientation archetype, leveraging captive polymerization and additives expertise. Borealis AG represents the European backward-integrated model with upstream control over polypropylene resin supply. These three anchors illustrate how supplier positioning fragments across geographic technology corridors and procurement centralization patterns.
| Leading Market Players |
|---|
| Toray Industries |
| Shin-Etsu Chemical |
| Mitsubishi Chemical Corporation |
| Bolloré Group |
| JPFL Films |
| Cosmo Films |
| DuPont Teijin Films |
| Treofan Group |
| Borealis AG |
| Others |
Value Network & Pricing Analysis
Polypropylene resin supply concentrates among naphtha crackers in South Korea, Japan, and Saudi Arabia, anchoring margin capture at the polymerization tier and compressing film converter buffers during feedstock volatility cycles. Biaxially oriented grade premiums reflect captive additive formulation and statistical process control documentation locked to automotive OEM tolerance bands.
Pricing Analysis
Volume-discount tiering separates automotive-grade biaxially oriented specifications from cost-optimized cast film for renewable energy applications. Price differentiation rests on certification grade—JIS-compliant industrial tiers command premiums against consumer-grade output—and locked thickness tolerance bands down to ±0.1μm for 800V EV modules. Pricing pressure stems from propylene feedstock volatility linked to cracking economics, with margin compression running through non-integrated film converters. Automotive manufacturers exhibit the least price sensitivity due to qualification lock-in, while Indian solar inverter assemblers absorb spot-market cast film with elevated cost consciousness.
Supply Chain Analysis
Upstream polypropylene feedstock draws from petrochemical complexes in South Korea, Japan, and Saudi Arabia, with naphtha and propane cracking economics tethering resin cost structures to crude oil benchmarks. Biaxial orientation line equipment sources from German and Japanese capital equipment manufacturers, creating single-source vulnerability for capacity expansion timelines. Distribution runs through direct converter-OEM relationships for automotive and renewable energy tiers, with spot-market channels serving South Asian consumer electronics assembly. Tariff exposure on metallized film imports into China and India compounds supply chain risk for European and Japanese exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PP capacitor films market sits at a platform-economics inflection where silicon carbide inverter standardization across 800V automotive architectures is consolidating specification-setting authority at OEM technical centers and displacing distributed procurement.
For Market Incumbents: Harden qualification timelines for sub-1.5μm biaxial orientation grades to defend against emerging Korean film converters with state-backed capacity expansion. Lock backward integration into polypropylene resin and captive additives to offset propylene feedstock volatility, while pre-certifying metallization adhesion chemistries against ECHA REACH PFAS amendments to capture premium positioning during requalification gaps.
For New Entrants and Emerging Players: Establish a beachhead in India's cost-optimized cast film segment serving Central Electricity Authority renewable energy targets, where BIS certification barriers remain lower than automotive-grade JIS protocols. Target Gujarat and Tamil Nadu inverter assembly clusters with 2μm-5μm specifications, leveraging local toll metallization partnerships to bypass vacuum deposition equipment bottlenecks.
For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated film converters with captive polymerization assets and in-house additive formulation capabilities, as these archetypes capture margin pools upstream of commodity resin volatility. The signal to watch is qualification velocity for 1μm grades among Tier-1 automotive capacitor suppliers, which indicates whether silicon carbide inverter adoption is compressing dielectric specifications faster than incumbent yield curves can adapt.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Resin | Captive polymerization buffers margin compression from naphtha cracking volatility. |
| Sub-2μm Gauge Qualification Acceleration | Toray's biaxial orientation expertise locks automotive DC-link module specifications. |
| REACH PFAS Compliance Pre-Certification | Silicone-based adhesion systems capture premium during German requalification gaps. |
| India Cast Film Capacity Expansion | Gujarat assembly clusters absorb cost-optimized output for utility-scale solar. |
| Direct OEM Technical Center Relationships | Hyundai and Kia inverter divisions bypass distributor channels for locked tolerances. |
Research Methodology
A spread of perspectives from biaxial orientation line engineers, capacitor OEM procurement directors, automotive inverter platform architects, and metallization equipment specialists converged on the working assumptions around silicon carbide switching frequency compression and dielectric thickness trajectories. Primary fieldwork combined with secondary validation from SEC filings of integrated chemical conglomerates, Japanese METI industrial statistics, ECHA REACH amendment drafts, and customs trade data on polypropylene resin and metallized film flows. Bottom-up capacity and utilization estimates from film converter facilities were triangulated against top-down demand modeling from electric vehicle production databases and renewable energy installation trackers.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning film construction type, application intensity tier, end-user procurement centralization pattern, and gauge specification band. CAGRs were derived from elasticity-adjusted volume projections against fixed investment cycles in orientation line capacity. Industry-specific forecast inputs included silicon carbide inverter adoption curves from automotive platform disclosures and provincial renewable energy mandate trajectories under China's dual carbon policy framework.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks, naphtha cracking spreads, or electric vehicle subsidy regimes would shift the trajectory. Forecasts reflect documented assumptions around qualification timelines for sub-1.5μm grades and ECHA enforcement schedules for PFAS restrictions. Cross-checking against IEA renewable energy capacity projections and automotive OEM platform electrification roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
Europium Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
Graphene Oxide (GO) Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Asia-Pacific Silicone Market