
 United States Sapphire Glass Market | 2026-2036
United States Sapphire Glass Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sapphire Glass Market Intelligence
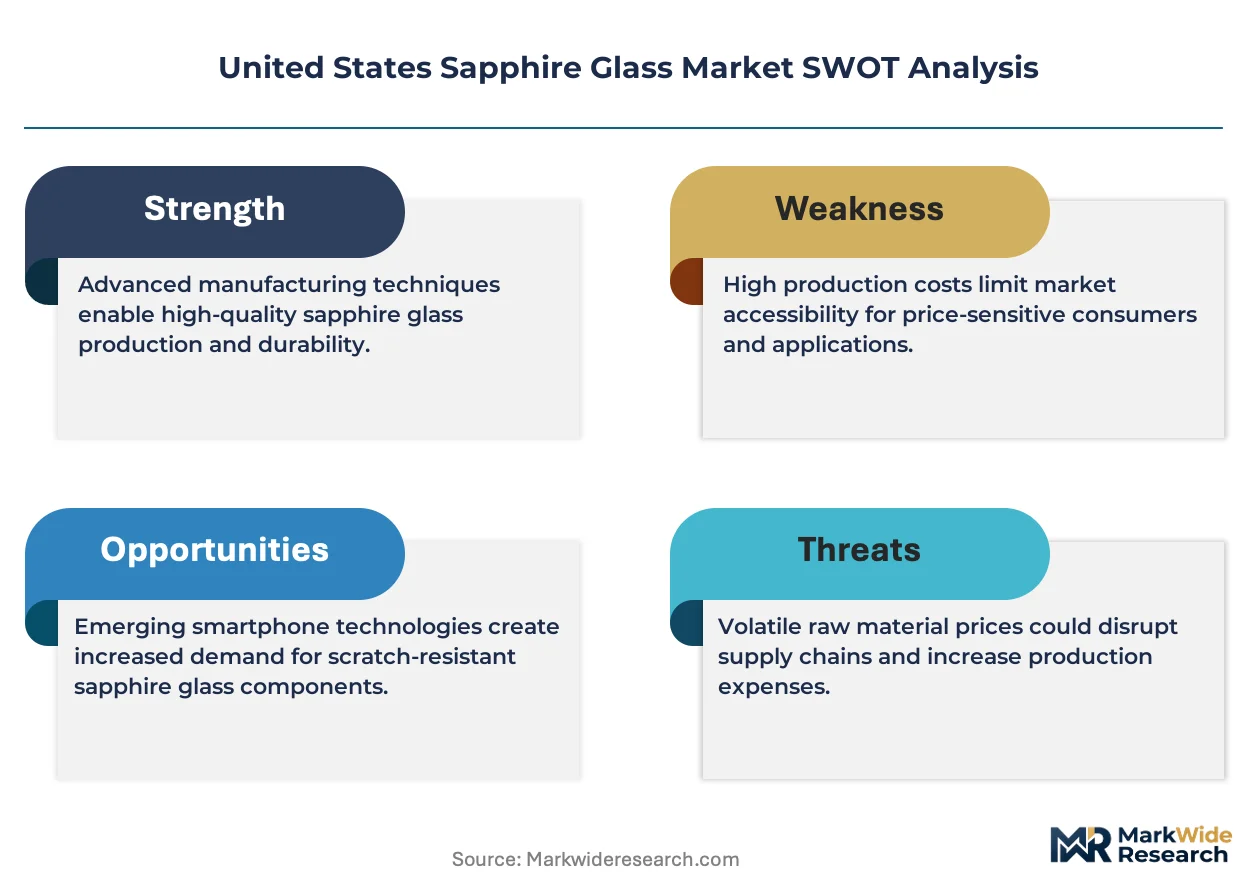
Optical-grade and medical-specification tiers is bifurcating the United States sapphire glass landscape. Rubicon Technology leverages in-house crystal growth to sustain pricing power across defense contracts. Precision Sapphire Technologies, Ltd. anchors its position in custom optical assemblies for laser systems. Kyocera Corporation differentiates through ceramic-to-glass hybrid substrates that extend thermal performance limits.
Sapphire glass consists of single-crystal aluminum oxide (Al₂O₃) manufactured through the Kyropoulos or edge-defined film-fed growth (EFG) methods, achieving Mohs hardness of 9 and transmission wavelengths from ultraviolet through mid-infrared. It serves primarily as a transparent armor, sensor window, and substrate material where mechanical durability and chemical inertness outweigh cost premiums. Substrates dominate volume consumption in semiconductor and LED fabrication, while watch crystals represent a mature margin pool constrained by synthetic quartz alternatives. Aerospace and medical device end-user segments capture the fastest structural expansion, driven by infrared imaging proliferation and implantable device optical monitoring.
FDA medical device standards, DOD MIL-PRF-13830B optical specifications, and OSHA workplace safety mandates collectively shape material certification pathways and procurement eligibility. California's state-level clean manufacturing regulations add compliance layers for crystal growth facilities operating near semiconductor clusters. Stakeholders must monitor evolving defense procurement localization requirements and medical device traceability mandates to secure long-term contract viability.
Market Dynamics
Defense procurement localization mandates and FDA medical device traceability requirements are restructuring supplier qualification pathways, compressing vendor pools while elevating certified domestic crystal growth capacity.
Growth Catalysts
- Aerospace infrared proliferation:Next-generation missile warning systems and reconnaissance platforms require sapphire windows transmitting mid-infrared wavelengths. Pentagon procurement cycles prioritize domestic optical substrate sourcing.
- OSHA workplace safety mandates:Stricter industrial laser enclosure standards accelerate sapphire viewport adoption in manufacturing environments. Facilities retrofitting Class 4 laser systems drive replacement demand.
- California semiconductor clustering:LED and power electronics fabrication expansion concentrates substrate consumption near crystal growth facilities. Proximity reduces logistics costs and lead times for wafer manufacturers.
Market Restraints
- High-purity alumina supply concentration:Feedstock for Kyropoulos growth relies on limited domestic refining capacity. Price volatility in specialty chemical inputs compresses crystal grower margins.
- EFG method technical limitations:Edge-defined film-fed growth struggles with large-diameter boule uniformity above 200mm. Optical-grade yield losses constrain volume scaling for defense windows.
- Synthetic quartz substitution:Watch crystal and consumer electronics cover glass segments face displacement from engineered quartz alternatives. Brand buyers prioritize cost over Mohs hardness in non-critical applications.
Strategic Opportunities
- Texas medical device corridor expansion:Implantable optical sensors for glucose monitoring and cardiac devices represent underpenetrated demand. FDA breakthrough device designation pathways accelerate market entry.
- IRA clean energy manufacturing credits:Incentives for domestic semiconductor and solar supply chains subsidize sapphire substrate production facility construction. Crystal growers capture tax advantages co-locating with wafer fabs.
- Ceramic-to-glass hybrid convergence:Integration of sapphire with aluminum nitride and silicon carbide substrates enables thermal management solutions. Power electronics packaging demands multi-material optical assemblies.
Industry Challenges
- Optical fabrication skill scarcity:Precision polishing and metrology expertise for MIL-PRF-13830B compliance resides in aging workforce cohorts. Training pipelines for double-side polishing technicians remain underdeveloped.
- Defense certification timeline compression:DOD vendor qualification cycles extend 18-24 months for new crystal growth sources. Expedited pathways for existing qualified suppliers disadvantage market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sapphire Glass Market |
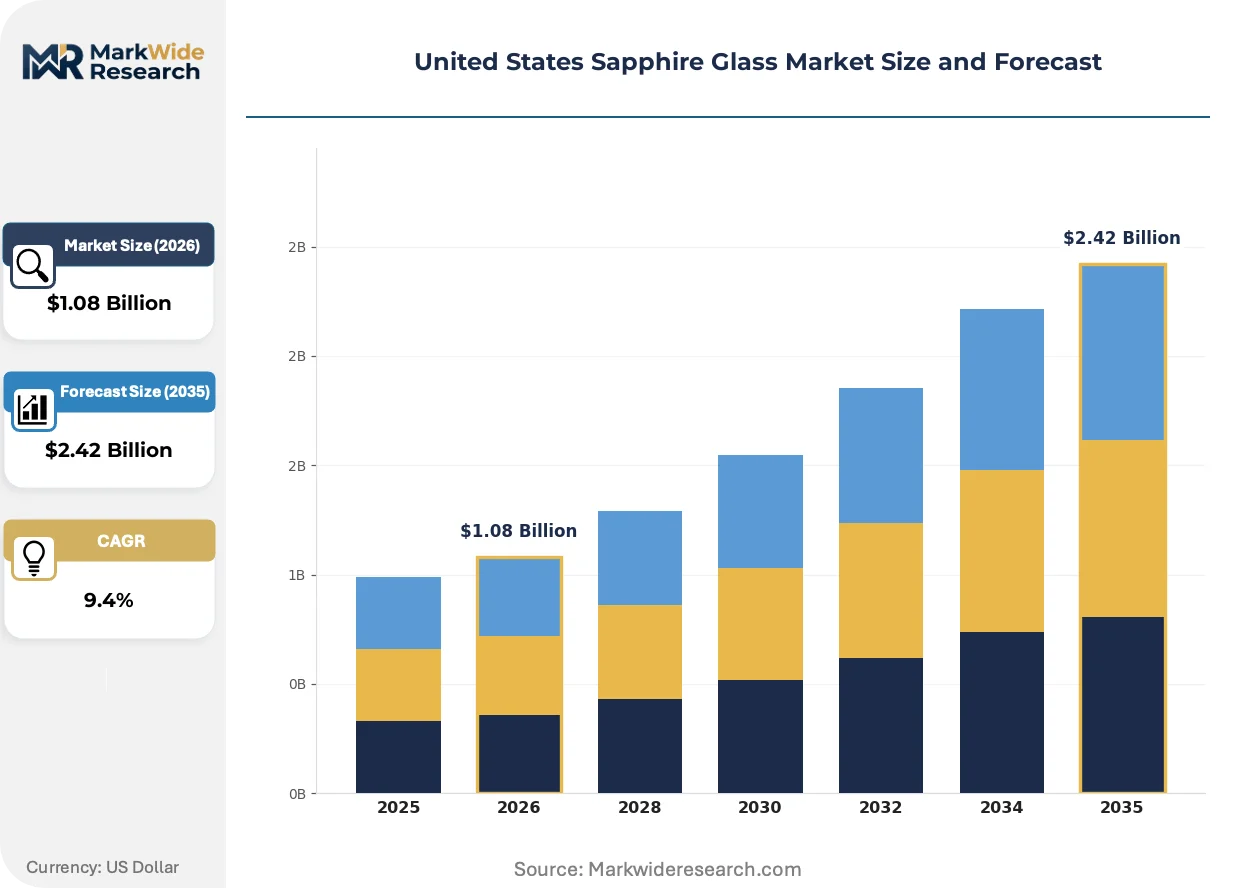
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $2.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Substrates, Windows, Lenses, Watch Crystals End User: Consumer Electronics, Aerospace, Automotive, Medical Devices Thickness: Thin, Medium, Thick, Ultra-Thin Manufacturing Process: Grow Method, Slicing, Polishing, Etching |
| Companies Covered | Rayotek Scientific Inc., Precision Sapphire Technologies, Ltd., Rubicon Technology, II-VI Optical Systems, Swiss Jewel Company, Sapphire Technologies, SCHOTT North America Inc., Kyocera Corporation, Saint-Gobain Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sapphire Glass Market Strategic Shifts & Innovations
Sapphire glass manufacturing is bifurcating between commodity substrate volume and precision optical specialization, with process control technologies determining competitive position across defense and medical verticals.
Advanced edge-defined film-fed growth systems incorporating real-time thermal imaging feedback are miniaturizing defect detection resolution to sub-micron scales. Aerospace prime contractors specify these enhanced boules for infrared window assemblies. The technology is compressing acceptable inclusion density thresholds and disqualifying legacy growth equipment from new defense contracts.
FDA's updated Unique Device Identification requirements for implantable optical components mandate lot-level traceability from crystal seed to finished device. Medical device OEMs now require sapphire suppliers to maintain electronic batch records compatible with FDA's data submission portals. California-based pacemaker and continuous glucose monitor manufacturers are consolidating vendor lists to those with validated quality management systems.
Defense prime contractors are consolidating optical procurement under long-term supply agreements with crystal growers holding active facility security clearances. Traditional spot-market substrate purchasing is yielding to multi-year sole-source contracts with embedded price adjustment mechanisms. This pattern concentrates most visible in Arizona and Florida aerospace manufacturing corridors where missile and aircraft programs dominate sapphire consumption.
United States Sapphire Glass Market Segmentation
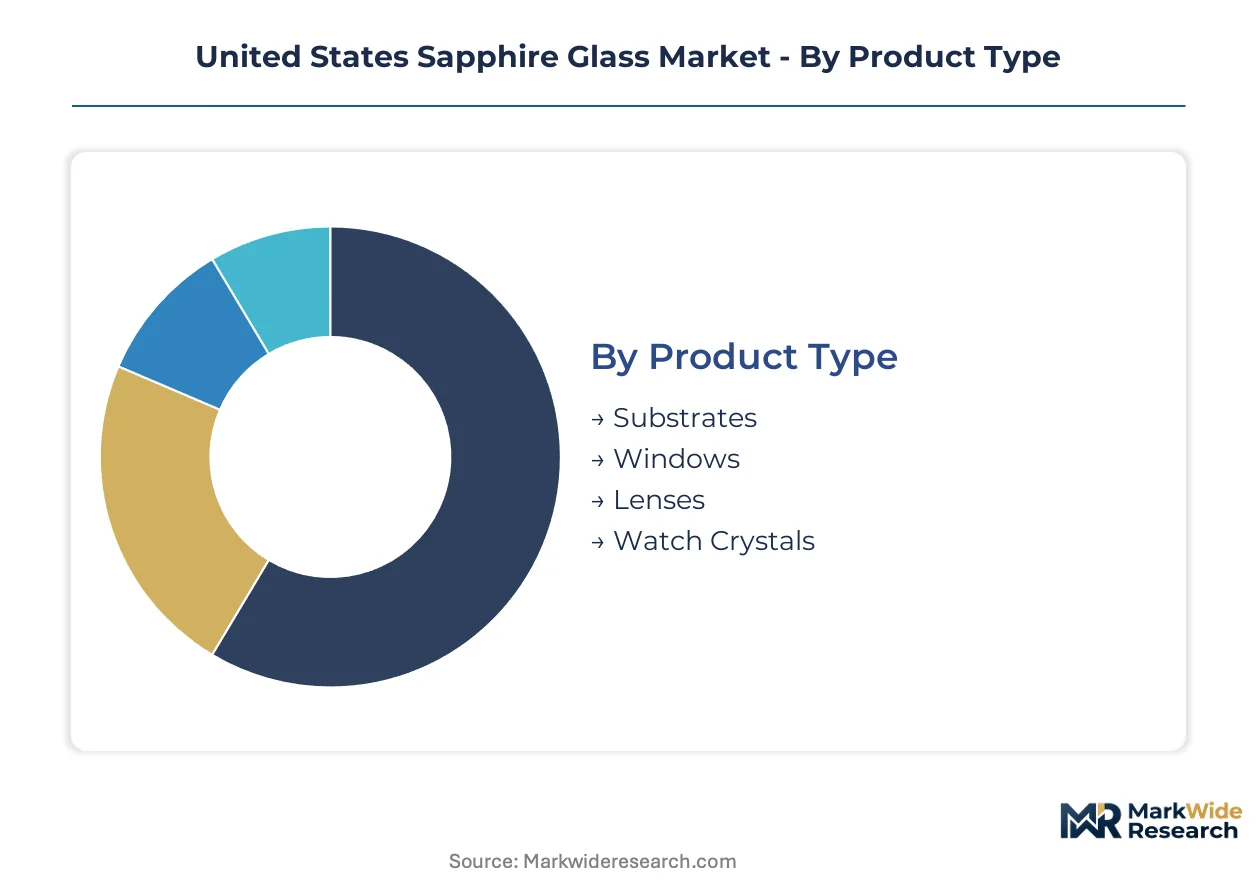
Sapphire glass demand fragments across distinct specification tiers that channel through specialized procurement pathways. Defense contractors, medical device OEMs, and semiconductor fabs each impose unique certification requirements that reshape supplier economics.
Product Type:
Defense procurement offices and semiconductor fabs source through divergent channels—long-term sole-source agreements for optical windows versus spot-market wafer purchasing for LED substrates.
- Substrates:Single-crystal Al₂O₃ wafers sliced from Kyropoulos-grown boules serve as foundational layers for GaN epitaxy in power electronics and solid-state lighting. California's LED fabrication clusters near Rubicon Technology's crystal growth facilities concentrate volume demand. IRA clean energy manufacturing credits subsidize domestic substrate capacity expansion.
- Windows:Precision-polished plates transmitting ultraviolet through mid-infrared wavelengths armor missile warning systems and reconnaissance platforms. Arizona and Florida aerospace corridors absorb the bulk of MIL-PRF-13830B-certified production. Pentagon localization mandates disqualify non-domestic crystal sources from new program awards.
- Lenses:Curved optical elements for laser focusing and imaging assemblies require sub-micron surface figure control.
- Watch Crystals:Synthetic quartz alternatives displace sapphire in cost-sensitive consumer timepieces.
By volume, Substrates leads. By growth pace, Windows is climbing the fastest.
End User:
Margin structures vary dramatically—medical device traceability requirements command premium pricing, while consumer electronics procurement squeezes unit economics.
- Consumer Electronics:Smartphone camera covers and smartwatch faces once drove sapphire demand. Brand buyers now prioritize cost over Mohs hardness 9 durability, shifting volume toward chemically strengthened aluminosilicate alternatives.
- Aerospace:Next-generation infrared imaging platforms require large-aperture sapphire windows with inclusion densities below 100 per cubic centimeter. Prime contractors consolidate procurement under multi-year agreements with security-cleared crystal growers.
- Automotive:Optical sensors for LiDAR enclosures and head-up display combiners represent emerging specification tiers.
- Medical Devices:Implantable glucose monitors and cardiac optical sensors demand lot-level traceability from seed crystal to finished component. FDA's Unique Device Identification rules compress qualified vendor pools to California-based manufacturers with validated quality systems.
Medical Devices captures the steepest expansion trajectory. Aerospace anchors absolute revenue concentration.
Thickness:
Wafer thinning capabilities determine addressable market scope—ultra-thin segments serve emerging flexible electronics applications.
- Thin:Sub-millimeter wafers for LED chip fabrication dominate unit economics.
- Medium:Standard optical window thicknesses balance transmission performance with mechanical durability.
- Thick:Armor-grade plates for transparent protection systems require extended growth cycles and specialized slicing equipment.
- Ultra-Thin:Sub-100-micron foils for flexible electronics and implantable sensors represent the frontier of processing capability.
Medium thickness commands the largest revenue share. Ultra-Thin is gaining share fastest.
Manufacturing Process:
Process control investments separate defense-qualified suppliers from commodity substrate producers.
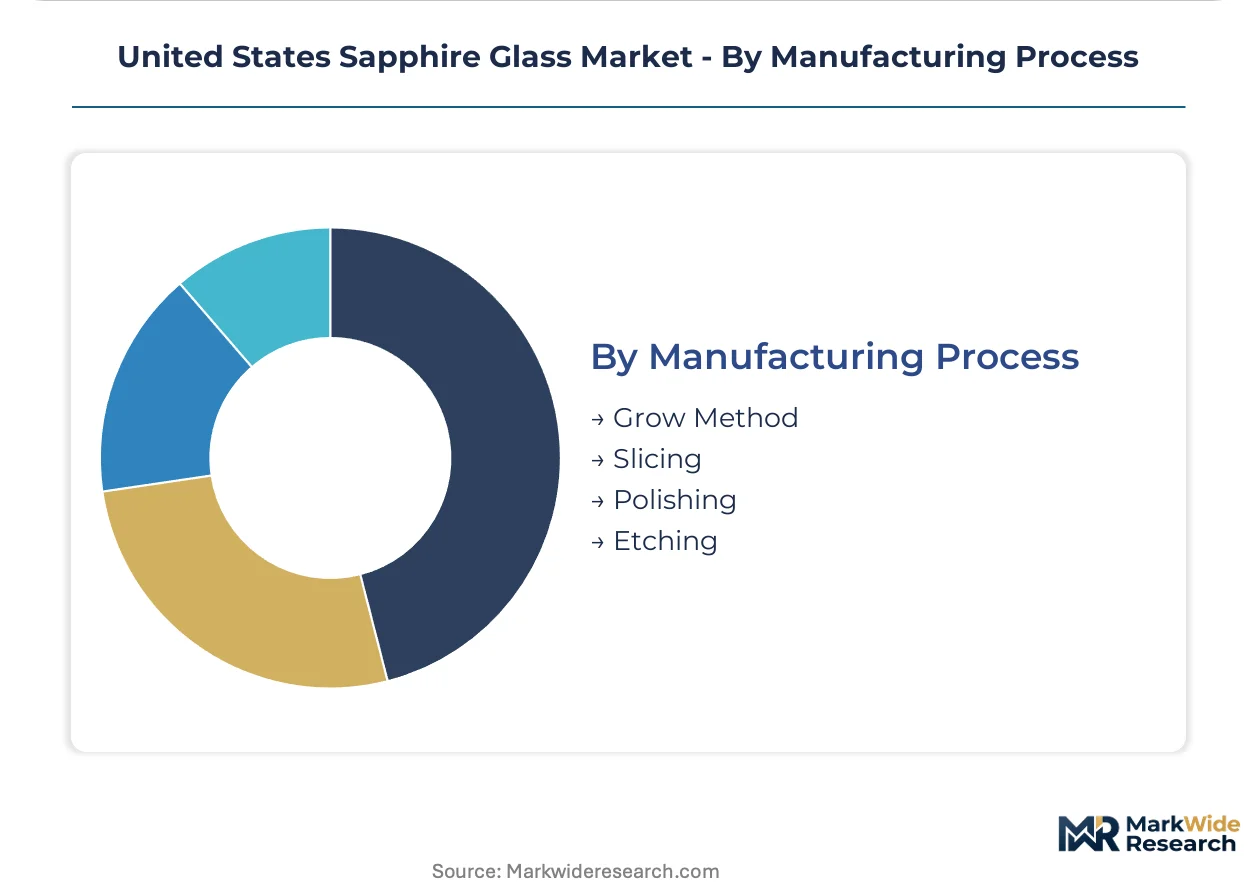
- Grow Method:Kyropoulos and EFG crystal growth techniques determine boule size, optical uniformity, and inclusion density. Real-time thermal imaging feedback systems now miniaturize defect detection to sub-micron resolution.
- Slicing:Multi-wire diamond sawing converts boules into wafers with thickness tolerances critical for epitaxial yield.
- Polishing:Double-side polishing to angstrom-level roughness satisfies MIL-PRF-13830B scratch-dig specifications. Aging technician cohorts constrain capacity expansion.
- Etching:Chemical surface preparation removes subsurface damage prior to epitaxial deposition.
Grow Method operations absorb the greatest capital intensity. Polishing represents the tightest bottleneck.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crystal growth facilities cluster near defense and semiconductor demand centers, concentrating qualified supplier capacity in specific metropolitan corridors. California's clean manufacturing regulations and Texas's medical device expansion are reshaping facility location decisions. Domestic sourcing mandates from the Pentagon and FDA traceability rules further harden these geographic patterns.
California
LED fabrication clusters in Silicon Valley and the Central Valley drive substrate consumption near Rubicon Technology's crystal growth operations. The California Air Resources Board imposes emissions controls on industrial furnaces used in Kyropoulos growth. San Jose and Fresno corridor facilities benefit from proximity to wafer manufacturers seeking reduced logistics costs.
Arizona
Missile warning system production at Raytheon and Northrop Grumman facilities generates demand for large-aperture optical windows. State tax incentives for defense manufacturing support crystal polishing operations in the Phoenix-Tucson corridor. Tucson's aerospace cluster concentrates MIL-PRF-13830B-certified fabrication capacity under long-term sole-source agreements.
Florida
Reconnaissance aircraft programs at Eglin Air Force Base and Patrick Space Force Base anchor infrared window procurement. Florida's defense contractor tax exemptions attract sapphire viewport manufacturers serving laser system retrofits. Orlando's simulation and training industry creates secondary demand for durable optical components.
Texas
Implantable medical device manufacturers in Austin and Dallas-Fort Worth are consolidating vendor lists for optical sensor components. The Texas Enterprise Fund subsidizes quality management system certifications required by FDA Unique Device Identification rules. Houston's cardiac device corridor represents underpenetrated demand for lot-traceable sapphire substrates.
Massachusetts
Precision optics for laser systems and spectroscopy equipment concentrate in Greater Boston's technology corridor. Massachusetts manufacturing extension partnerships support workforce training for double-side polishing technicians. Cambridge and Lowell facilities serve defense research contracts requiring security-cleared crystal sources.
United States Sapphire Glass Market Key Industry Players
Concentration sits with domestic crystal growers holding active defense security clearances and validated FDA quality systems. The vendor pool compresses under DOD localization mandates and medical device traceability requirements, elevating qualified suppliers above commodity substrate producers. Three archetypes dominate: integrated crystal-to-component manufacturers, specialized optical fabricators, and multi-material substrate hybridizers. Competitive moves center on capacity expansion near semiconductor clusters and strategic partnerships with aerospace prime contractors.
Among domestic integrated manufacturers, Rubicon Technology and Rayotek Scientific Inc. exemplify the crystal-to-component archetype, occupying positions that bridge boule growth through precision polishing. Precision Sapphire Technologies, Ltd. represents the specialized optical fabricator tier, anchoring custom assembly capabilities for laser system integrators. Kyocera Corporation sits within the multi-material hybridizer category, leveraging ceramic-to-glass convergence for thermal management applications.
| Leading Market Players |
|---|
| Rayotek Scientific Inc. |
| Precision Sapphire Technologies, Ltd. |
| Rubicon Technology |
| II-VI Optical Systems |
| Swiss Jewel Company |
| Sapphire Technologies |
| SCHOTT North America Inc. |
| Kyocera Corporation |
| Saint-Gobain Group |
| Others |
Cost & Logistics Intelligence
Synthetic quartz displacement in watch crystals and consumer electronics covers simultaneously redraws procurement geography toward Asian engineered-material suppliers and compresses margin pools for commodity-grade sapphire producers. This substitution dynamic redirects domestic crystal growth capacity toward defense and medical specification tiers where certification barriers sustain pricing power.
Pricing Analysis
MIL-PRF-13830B optical specifications dictate the pricing tier structure across defense-qualified sapphire glass, separating premium-certified windows from standard substrate grades. Pricing stratifies across optical-grade, medical-specification, and industrial-economy tiers based on inclusion density thresholds and traceability documentation. Cost compression in consumer-facing segments intensifies as brand buyers prioritize unit economics over Mohs hardness 9 durability. Medical device OEMs exhibit lowest price sensitivity due to FDA lot-traceability mandates that compress qualified vendor pools.
Supply Chain Analysis
Strategic stockpiling of high-purity alumina feedstock dominates inventory strategy given limited domestic refining capacity and Kyropoulos growth method requirements. Crystal growth operations draw from concentrated specialty chemical suppliers in Germany and Japan, with boule slicing and polishing anchored in California, Arizona, and Massachusetts corridors. Single-source vulnerability in feedstock refining exposes margin compression when alumina spot markets tighten. Distribution runs through defense prime contractor sole-source agreements and semiconductor fab spot purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States sapphire glass market functions as a regulatory-moat arena where FDA traceability rules and DOD security clearance requirements erect switching-cost barriers that entrench qualified incumbents.
For Market Incumbents: Shield market position by deepening in-house crystal growth capacity near California semiconductor clusters and securing multi-year sole-source agreements with Arizona aerospace primes. Synthetic quartz substitution in consumer electronics demands accelerated certification investment for medical-device specification tiers to offset volume erosion in watch crystals.
For New Entrants and Emerging Players: Anchor in Texas medical device corridor expansion where implantable optical sensor demand outpaces qualified supplier capacity. FDA breakthrough device designation pathways offer the most penetrable entry angle for glucose monitoring and cardiac sensor substrates requiring lot-level traceability systems.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated crystal-to-component manufacturers with active defense security clearances. Long-term viability hinges on captive supply of optical-grade boules through the projection horizon. Watch DOD vendor qualification timeline compression as the inflection signal for acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Defense Security Clearance Acquisition | Facility clearances unlock sole-source Pentagon procurement channels unavailable to unqualified competitors. |
| FDA Quality System Validation | Electronic batch record compatibility secures implantable medical device vendor list inclusion. |
| Kyropoulos Capacity Expansion | IRA clean energy credits subsidize domestic boule growth facilities co-located with wafer fabs. |
| Real-Time Thermal Imaging Integration | Sub-micron defect detection systems disqualify legacy growth equipment from next-generation defense contracts. |
| Multi-Material Hybrid Substrate Development | Sapphire-aluminum nitride convergence addresses power electronics packaging thermal management requirements. |
Research Approach
The analysis maps optical-grade windows, medical-specification substrates, and industrial-grade components, each validated through crystal growth engineers, defense procurement officers, medical device quality managers, and semiconductor fab materials specialists. Primary fieldwork combined structured interviews with secondary triangulation against SEC 10-K filings, DOD contract award databases, FDA 510(k) submission records, and customs trade data. Bottom-up wafer consumption estimates and top-down defense budget allocations were reconciled across modeling approaches.
Consistency checks validated volume and value outputs against external benchmarks including aerospace prime contractor procurement disclosures and LED fabrication capacity announcements. Segmentation dimensions encompassed product type, end-user vertical, thickness specification, and manufacturing process tier across the projection horizon. CAGRs were derived from trend extrapolation of defense modernization cycles, medical device approval trajectories, and semiconductor capital expenditure patterns.
Decision-makers should treat outputs as directional under assumptions of sustained Pentagon localization mandates and stable FDA traceability requirements; material deviation would warrant model refresh. Revision becomes warranted when defense procurement timeline compression or feedstock supply disruption crosses thresholds that alter qualified supplier economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Gallium Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
EV Capacitor Films Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Global Electronic Materials Market