
 Semiconductor Grade Neon Gas Market | 2026-2036
Semiconductor Grade Neon Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Grade Neon Gas Market Insights
A capital-intensity divergence between cryogenic distillation operators and gas-blending specialists is reorganizing competitive tiers. Linde sustains integrated air-separation dominance from feedstock through purification. Messer leverages regional cylinder networks to anchor European supply security. Air Liquide differentiates through on-site bulk installations at major lithography fabs.
Semiconductor grade neon gas denotes neon purified to 99.999% or higher, with critical limits on helium, hydrogen, and oxygen impurities below single-digit parts per million, produced via fractional distillation of liquid air followed by catalytic gettering and cryogenic adsorption. Ultra-pure neon commands the dominant margin pool in lithography laser mixtures. High-purity neon occupies mature demand in signage and general illumination. Neon mixtures for excimer lasers represent the fastest-growing delivery format as 193nm and emerging 13.5nm lithography tools proliferate.
The EPA regulates neon as a volatile organic compound surrogate in certain industrial emissions contexts, while REACH mandates full substance registration and impurity disclosure for EU-sourced specialty gases. Japan's METI enforces JIS K 1105 purity benchmarks that effectively gate market access for non-compliant foreign suppliers. Stakeholders must weigh captive air-separation investments against long-term offtake contracts as lithography wavelength transitions redefine gas mixture specifications.
Market Dynamics
The transition from 193nm to 13.5nm extreme ultraviolet lithography is compressing neon consumption per wafer while multiplying purity thresholds, forcing gas suppliers to recalibrate purification investments against shrinking unit economics at leading foundries.
Growth Catalysts
- Excimer laser proliferation:Deep ultraviolet lithography systems at Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek cluster consume bulk high-purity supply, anchoring demand concentration.
- EU F-Gas Regulation:Tightening impurity thresholds for excimer laser gas mixtures under REACH compliance frameworks are elevating specification premiums for qualified suppliers.
- 193nm tool refresh cycles:Leading foundries in Taiwan and South Korea are expanding installed base capacity, sustaining neon offtake volumes despite wavelength transition pressures.
Market Restraints
- Cryogenic energy intensity:Fractional distillation of liquid air requires sustained electricity inputs, exposing margins to volatile industrial power tariffs in Germany and Japan.
- Ukrainian feedstock concentration:Pre-conflict cryogenic separation capacity in Eastern Europe supplied substantial crude neon feedstock, creating supply security vulnerabilities now requiring alternative sourcing.
- Helium impurity technical floor:Catalytic gettering and cryogenic adsorption face fundamental limits in stripping helium below single-digit parts per million without prohibitively expensive additional processing stages.
Strategic Opportunities
- Indian semiconductor manufacturing:PLI scheme incentives for domestic fab construction under India's Ministry of Electronics and Information Technology are creating first-mover positions for on-site gas installation specialists.
- 13.5nm EUV gas mixture innovation:Emerging lithography wavelength specifications demand reformulated neon-halogen mixtures, opening formulation IP opportunities for blending specialists.
- On-site bulk installation models:Major lithography fabs in Taiwan and South Korea are transitioning from cylinder delivery to pipeline-connected bulk storage, favoring capital-rich integrated operators.
Industry Challenges
- Cryogenic engineering talent scarcity:Fractional distillation operations require specialized expertise in low-temperature thermodynamics and adsorption system design that outpaces current vocational training pipelines.
- JIS K 1105 certification timelines:Japan's METI-enforced purity benchmarks demand extensive third-party validation cycles that delay market entry for new foreign suppliers by 18-24 months.
- Legacy cylinder fleet integration:Regional gas distributors maintain substantial invested capital in conventional high-pressure cylinder networks that resist rapid conversion to bulk installation economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Grade Neon Gas Market |
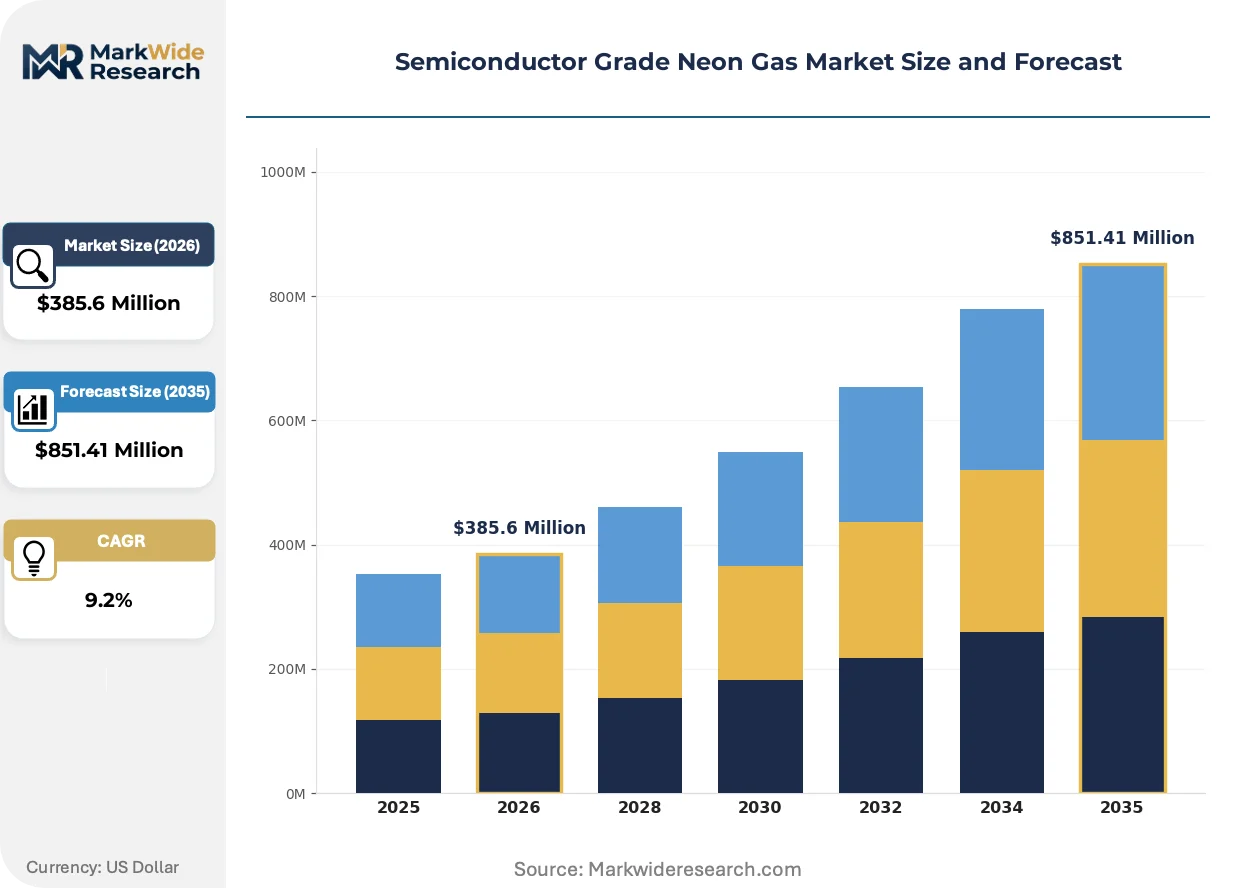
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $851.41 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultra-Pure Neon, High-Purity Neon, Neon Mixtures, Technical Neon End User: Electronics Industry, Laser Manufacturing, Display Technology, Optical Applications Delivery Mode: Cylinders, Bulk Delivery, On-Site Supply, Cryogenic Containers Application: Illumination, Laser Systems, Signage, Etching Processes |
| Companies Covered | Messer, Matheson Tri-Gas, Linde, Ingas, Iceblick, Air Liquide, Taiyo Nippon Sanso, American Gas Products, Air Products and Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Grade Neon Gas Market Trends and Innovations
Purification technology and delivery infrastructure are converging to address wavelength-driven specification compression, with regulatory frameworks simultaneously tightening disclosure requirements and reshaping competitive qualification barriers.
Membrane-assisted cryogenic adsorption is miniaturizing purification train footprints while maintaining 99.999% purity thresholds. Leading foundries in Taiwan are piloting compact skid-mounted systems that reduce facility space requirements by half. This technology is miniaturizing the capital barrier for mid-scale producers seeking to serve secondary lithography tool markets.
REACH mandates full substance registration and impurity disclosure for EU-sourced specialty gases, extending disclosure obligations through the supply chain. Industrial gas blenders must now document contaminant profiles at parts-per-billion resolution. European excimer laser gas mixture suppliers are responding by investing in in-house mass spectrometry capabilities to maintain formulation confidentiality.
Long-term offtake contracting is displacing spot market purchasing at major semiconductor manufacturers. Taiwan's Hsinchu Science Park fabs are locking in five to seven-year supply agreements with fixed purity escalation clauses. This pattern is most visible in Taiwan and South Korea, where lithography tool density concentrates buyer leverage and justifies dedicated pipeline infrastructure.
Semiconductor Grade Neon Gas Market Segmentation
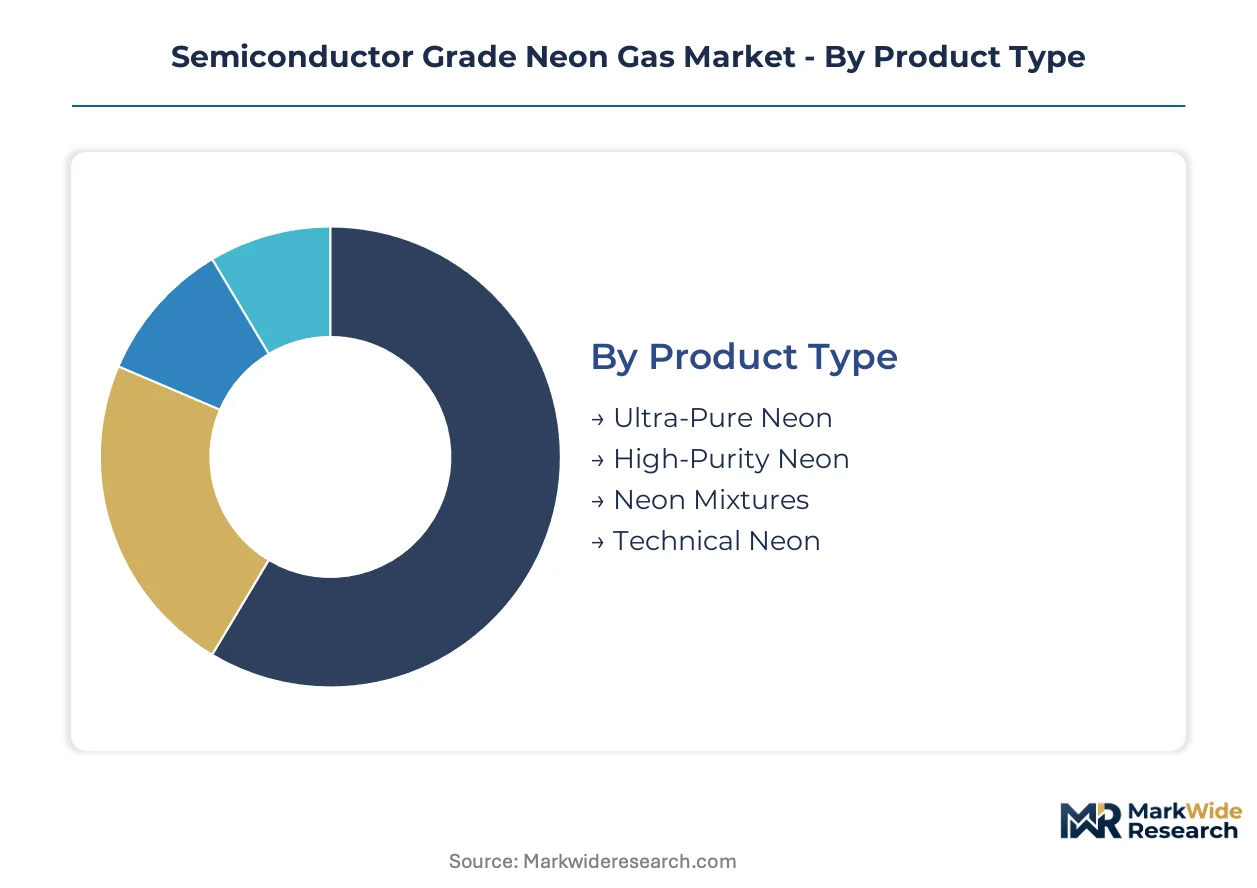
Segmentation in semiconductor grade neon gas reveals how purity thresholds, delivery infrastructure, and end-use specifications fragment supplier economics. Each dimension carries distinct regulatory, capital, and technical barriers that reshape competitive positioning across the value chain.
Product Type:
Regulatory differentiation separates qualification tiers, with EU REACH and Japan's METI JIS K 1105 enforcing divergent impurity disclosure thresholds that elevate certification costs for higher grades.
- Ultra-Pure Neon:Purified to 99.999% or higher with helium, hydrogen, and oxygen impurities held below single-digit parts per million through catalytic gettering and cryogenic adsorption. Taiwan's Hsinchu Science Park fabs consume the dominant share for 193nm and 13.5nm lithography laser mixtures, though EUV wavelength transition is compressing unit consumption per wafer.
- Neon Mixtures:Pre-formulated blends with halogen components for excimer laser operation, requiring precise ppm-level contaminant control. South Korea's Pyeongtaek cluster anchors demand as 193nm tool refresh cycles sustain offtake volumes despite purity escalation costs.
- High-Purity Neon:Serves mature signage and general illumination applications with less stringent impurity ceilings than lithography grades.
- Technical Neon:Standard industrial grade for non-critical applications where fractional distillation outputs require minimal secondary processing.
Ultra-pure neon handles the majority of throughput; neon mixtures are expanding most quickly on share as lithography tool proliferation drives formatted blend demand.
End User:
Cost tier stratification concentrates margin capture at the electronics-laser nexus, where excimer laser gas consumption justifies dedicated purification investments and long-term offtake contracting.
- Electronics Industry:Leading foundries in Taiwan and South Korea lock in five to seven-year supply agreements with fixed purity escalation clauses, displacing spot market purchasing and favoring capital-rich integrated operators with pipeline-connected bulk storage capabilities.
- Laser Manufacturing:Excimer laser OEMs and maintenance providers source neon-halogen mixtures for 193nm DUV and emerging 13.5nm EUV systems, with formulation IP becoming a critical differentiator as wavelength specifications evolve.
- Display Technology:OLED and micro-LED fabrication processes utilize neon in etching and deposition chambers.
- Optical Applications:Scientific instrumentation and specialized lighting systems require consistent purity without lithography-grade certification overhead.
Electronics industry procurement dominates volume commitment; laser manufacturing is climbing the fastest on specification intensity.
Delivery Mode:
Volume concentration at major lithography fabs is driving infrastructure transition from conventional cylinder networks to integrated bulk systems that reduce handling contamination risk.
- On-Site Supply:Pipeline-connected bulk installations at Taiwan and South Korea foundries eliminate cylinder changeout contamination while securing supply continuity for high-volume consumers. Linde and Air Liquide anchor this tier through captive air-separation and purification integration.
- Bulk Delivery:Cryogenic tanker shipments serve mid-scale consumers with dedicated storage infrastructure but insufficient volume for pipeline economics.
- Cylinders:Regional distributors like Messer leverage established high-pressure networks for European supply security, though legacy fleet conversion to bulk economics proceeds slowly.
- Cryogenic Containers:Portable dewar systems address intermittent demand from research facilities and secondary manufacturing.
On-site supply captures the steepest expansion trajectory as lithography tool density justifies dedicated infrastructure; cylinders retain residual share in fragmented regional markets.
Application:
Customer type divergence separates qualified lithography suppliers from commodity players, with REACH and JIS K 1105 certification timelines creating 18-24 month entry barriers for new foreign competitors.
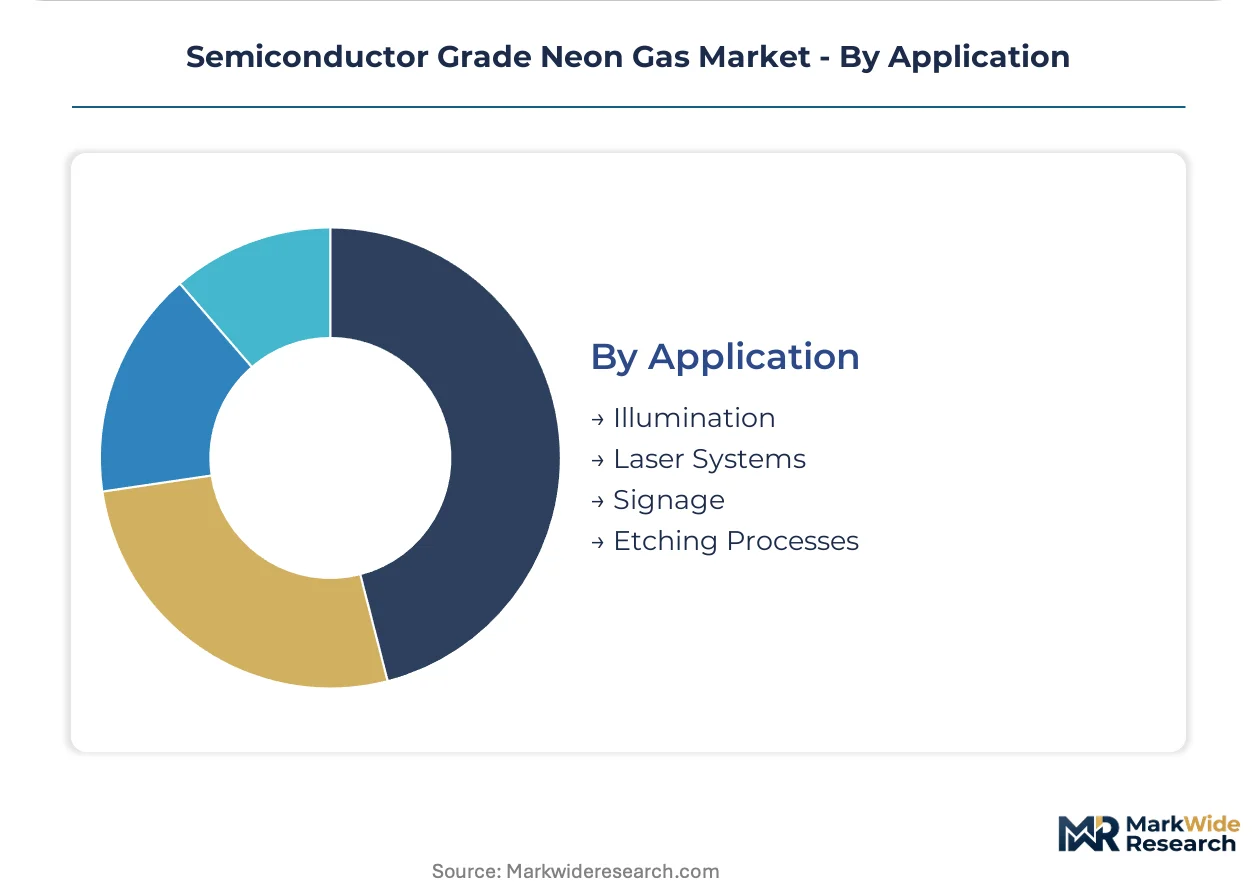
- Laser Systems:Deep ultraviolet and extreme ultraviolet lithography tools at Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek cluster consume the dominant high-purity supply, with EU F-Gas Regulation tightening impurity thresholds and elevating specification premiums.
- Etching Processes:Semiconductor plasma etching utilizes neon as a buffer gas in critical dimension control applications.
- Illumination:General lighting and specialty discharge lamps operate on mature high-purity specifications without lithography-grade certification requirements.
- Signage:Traditional neon tube advertising represents a declining demand pool as LED substitution accelerates.
Laser systems command the dominant margin pool; etching processes are gaining share fastest as advanced node proliferation extends neon consumption beyond lithography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across consuming regions. Taiwan and South Korea fabs absorb premium pricing for ultra-purity with minimal volume contraction, while European signage and illumination buyers exhibit immediate demand response to tariff-adjusted neon costs.
Taiwan
Deep ultraviolet lithography tool density at Hsinchu Science Park sustains the world's highest per-fab neon consumption rates. METI-equivalent purity negotiations through the Industrial Development Bureau shape procurement contract structures. Kaohsiung's emerging packaging cluster is diversifying demand beyond front-end lithography into etching buffer applications.
South Korea
Pyeongtaek's semiconductor mega-cluster anchors excimer laser gas offtake for 193nm and 13.5nm systems. South Korea's Ministry of Trade, Industry and Energy enforces local content ratios that privilege on-site bulk installation contracts. Samsung's Pyeongtaek campuses are transitioning from cylinder delivery to pipeline-connected cryogenic storage systems.
United States
CHIPS Act fab construction in Arizona and Texas is generating first-mover installation opportunities for integrated gas suppliers. EPA volatile organic compound surrogate classifications for neon emissions shape environmental compliance costs at new facilities. Intel's expanding Arizona operations are negotiating five-year supply agreements with fixed purity escalation clauses.
Germany
Industrial gas blending specialists serve European lithography tool maintenance networks from Ruhr Valley cylinder hubs. EU F-Gas Regulation and REACH impurity disclosure mandates elevate certification overhead for excimer laser mixture formulation. Dresden's silicon Saxony cluster maintains captive neon storage for ASML tool servicing requirements.
Japan
Domestic excimer laser OEMs and maintenance providers source neon-halogen mixtures under stringent METI JIS K 1105 purity benchmarks. Japan's Ministry of Economy, Trade and Industry enforces third-party validation cycles that delay foreign supplier market entry. Kyushu's semiconductor materials corridor concentrates specialty gas distribution infrastructure for regional fab networks.
Semiconductor Grade Neon Gas Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital requirements for cryogenic distillation and on-site bulk installation creating structural barriers to tier ascension. Three archetypes populate the competitive map: captive air-separation operators controlling feedstock through purification, regional cylinder network specialists leveraging established distribution density, and formulation-focused blenders capturing IP premiums in excimer laser mixtures. Capacity expansion through long-term offtake contracting and backward integration into crude neon feedstock sourcing represent the dominant competitive vectors.
Within the integrated operator tier, Linde and Air Liquide exemplify capital-rich players with pipeline-connected bulk installation capabilities at major lithography fabs. Among regional specialists, Messer occupies a position anchored in European cylinder network density. Taiyo Nippon Sanso represents the Japan-centric archetype navigating METI certification requirements.
| Leading Market Players |
|---|
| Messer |
| Matheson Tri-Gas |
| Linde |
| Ingas |
| Iceblick |
| Air Liquide |
| Taiyo Nippon Sanso |
| American Gas Products |
| Air Products and Chemicals |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory buffers at Taiwan's Hsinchu Science Park fabs concentrate pricing leverage among cryogenic distillation operators with captive air-separation capacity. Long-term offtake contracting with fixed purity escalation clauses now displaces spot purchasing, anchoring supplier power against volatile electricity tariffs in Germany and Japan.
Pricing Analysis
After-sales service revenue from laser mixture reformulation and on-site purification maintenance drives lifetime value capture. Three-tier pricing structure across ultra-pure, neon mixture, and high-purity grades separates lithography-certified supply from signage commodity tiers. Cost compression in ultra-pure grades intensifies because EU F-Gas Regulation compliance elevates certification overhead. Electronics industry procurement at Taiwan and South Korea fabs exhibits minimal price sensitivity, while European illumination buyers contract volumes immediately when tariff-adjusted costs rise.
Supply Chain Analysis
Ninety-day inventory cycles reflect Ukrainian feedstock disruption and forced diversification into North American and Middle Eastern crude neon sources. Cryogenic separation capacity concentrates in Germany, the United States, and Qatar after Eastern European supply displacement. Fractional distillation operations draw from liquid air feedstock, catalytic gettering catalysts, and specialized adsorption media. Single-source vulnerability persists in helium stripping technology where catalytic gettering faces fundamental technical floors. Distribution runs through pipeline-connected bulk installations at major foundries, supplemented by regional cylinder networks for secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor grade neon gas market sits at a high-growth inflection as 13.5nm EUV lithography wavelength transitions redefine gas mixture specifications and purity thresholds.
For Market Incumbents: Secure backward integration into crude neon feedstock sourcing to offset Ukrainian supply displacement and lock in five to seven-year offtake contracts with Taiwan's Hsinchu Science Park fabs before competitor capacity additions. Deepen on-site bulk installation capabilities at South Korea's Pyeongtaek cluster to defend against regional cylinder network specialists seeking pipeline economics. For New Entrants and Emerging Players: Lead with formulation IP development for neon-halogen mixtures targeting 13.5nm EUV specifications, where established suppliers face recalibration lags. India's PLI scheme semiconductor manufacturing incentives present the most penetrable geography for first-mover on-site gas installation contracts. Pursue joint venture structures with domestic industrial gas distributors to bypass JIS K 1105 certification timeline barriers. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because lithography wavelength transitions concentrate demand among qualified suppliers with METI and REACH certification infrastructure. Target mid-scale cryogenic distillation operators with existing air-separation assets and regional cylinder network density. Watch ASML's 13.5nm tool shipment volumes as the signal indicating gas mixture specification inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crude Neon Feedstock | Captive sourcing from Qatar and North American cryogenic plants secures supply continuity against geopolitical disruption. |
| Long-term Supply Agreement | Five to seven-year offtake contracts with Taiwan's Hsinchu Science Park fabs lock in volume commitments and purity escalation clauses. |
| Capacity Expansion | Membrane-assisted cryogenic adsorption miniaturization enables mid-scale producers to serve secondary lithography tool markets. |
| Joint Venture | Partnerships with Indian domestic gas distributors accelerate PLI scheme fab construction timelines and bypass certification delays. |
| Technology Licensing | Neon-halogen mixture formulation IP licensing to excimer laser OEMs captures recurring revenue from 13.5nm EUV system proliferation. |
Research Methodology
Operator-level perspectives from cryogenic distillation plant managers, procurement leads at Taiwan and South Korea foundries, excimer laser OEM technical directors, and regional gas distribution channel partners anchored the qualitative base. Primary interview insights combined with customs and trade data, SEC filings from integrated industrial gas operators, METI JIS K 1105 certification records, and EU REACH registration databases. Bottom-up volume modeling across purity grades and delivery modes triangulated against top-down semiconductor capital expenditure forecasts.
Sensitivity analysis tested forecast robustness across electricity tariff volatility scenarios, Ukrainian supply recovery assumptions, and EU F-Gas Regulation enforcement intensity variations. Segmentation modeling spanned purity tier, delivery infrastructure type, end-use application, and regional regulatory cluster dimensions. CAGRs derived from installed base projections for 193nm and 13.5nm lithography tools, wafer start forecasts, and gas consumption coefficients per exposure layer.
Forecasts assume regulatory continuity in EU REACH, Japan METI JIS K 1105, and EPA emissions frameworks; material policy shifts would require re-modeling. Lithography wavelength transition timelines and crude neon feedstock sourcing diversification pace represent key uncertainty factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Indium Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Semiconductor PI Film Market