
 North America Silicone Market | 2026-2036
North America Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
North America Silicone Market Analytics
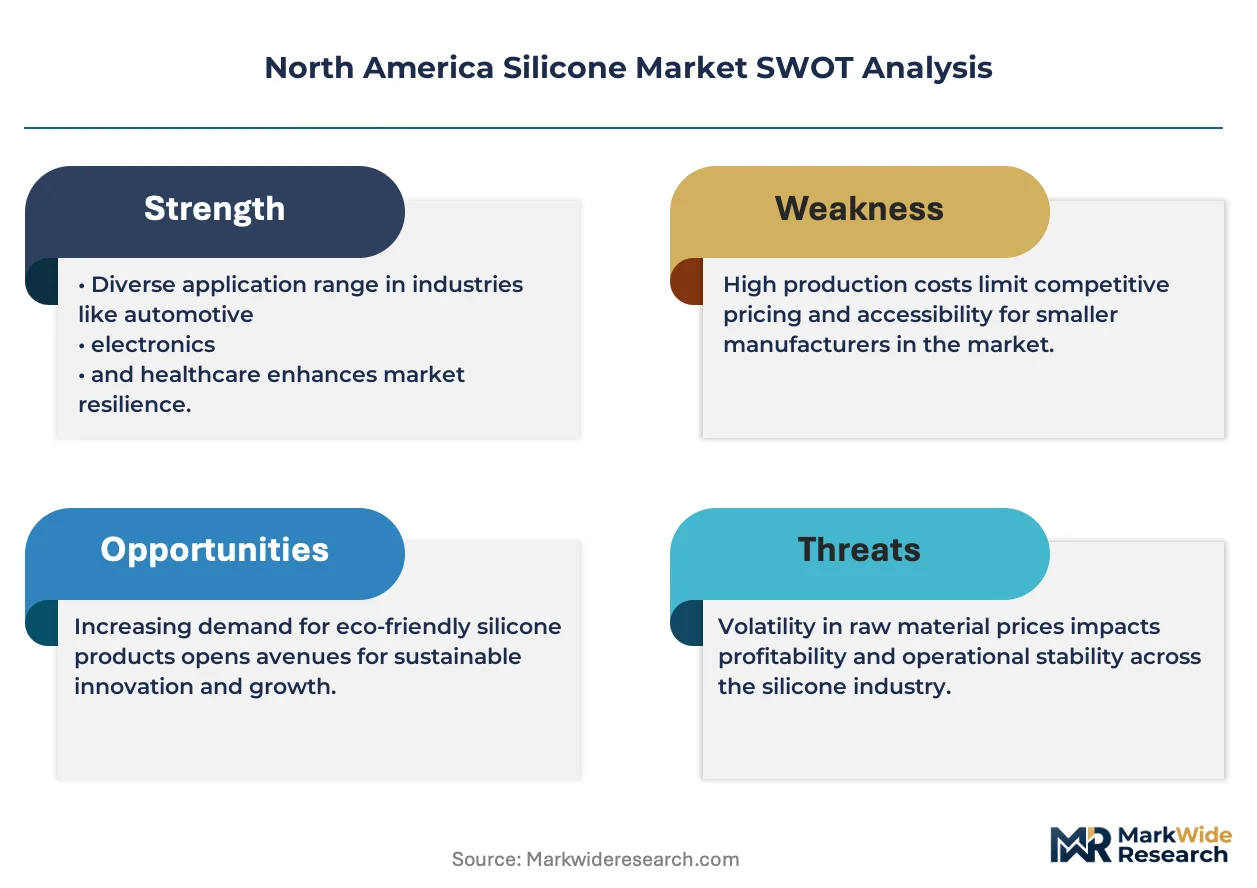
Capital-intensity divergence between integrated siloxane producers and formulation specialists is redrawing competitive boundaries in the North America silicone sector. Dow leverages captive chlorosilane capacity and Gulf Coast cracking assets to sustain margin capture across the elastomer value chain. Momentive competes through specialized healthcare-grade formulations that anchor premium positioning in medical device supply chains. Shin-Etsu Chemical Co., Ltd. extends its position via tight control over ultra-high-purity electronic-grade silicones for semiconductor fabrication customers.
Silicone denotes a family of synthetic polymers built on alternating silicon-oxygen backbones with organic side groups, typically manufactured through hydrolysis of chlorosilanes followed by polycondensation to achieve viscosities ranging from water-thin fluids to high-consistency rubbers. These materials deliver thermal stability from minus sixty degrees Celsius to over two hundred degrees Celsius, electrical insulation, and biocompatibility for applications spanning construction sealing, automotive gasketing, and implantable medical devices. Sealants and elastomers represent the mature volume core where margin pools have compressed amid raw material cyclicality, while healthcare-grade gels command structural premiums driven by FDA master file requirements and validation timelines that deter commoditization. Electronics applications in thermal interface materials and protective coatings are outpacing construction growth as semiconductor packaging complexity intensifies.
The EPA oversees siloxane environmental fate assessments under TSCA Section 5 premanufacture notifications, while FDA regulates medical-grade silicones through device master files and biocompatibility ISO 10993 testing protocols, collectively raising compliance costs for non-integrated entrants. Health Canada and PMRA coordinate with EPA on cross-border chemical evaluations, creating harmonized but stringent North American product registration requirements. Stakeholders must monitor evolving state-level PFAS-analogue scrutiny that could extend to certain silicone formulations, while calibrating capital deployment between commodity elastomer expansion and specialty healthcare or electronics-grade capacity.
Market Dynamics
Integrated chlorosilane-to-elastomer production clusters along the U.S. Gulf Coast are compressing margins for non-captive formulators while concentrating procurement power among medical device and semiconductor OEMs.
Growth Catalysts
- Healthcare-grade certification pipelines:FDA master file requirements for implantable silicones create multi-year validation barriers that protect incumbent suppliers from price erosion.
- Semiconductor packaging thermal management:Advanced node chip fabrication in Arizona and Texas drives demand for ultra-high-purity electronic-grade silicone thermal interface materials.
- REACH-aligned state chemical safety expansions:California and New York are adopting EPA TSCA Section 5 review standards that harmonize compliance costs across the continent.
Market Restraints
- Silicon metal and methanol feedstock volatility:Siloxane producers face margin compression when metallurgical-grade silicon spot prices spike due to Chinese smelter curtailments.
- Gulf Coast production concentration:Hurricane exposure and petrochemical corridor congestion create single-point-of-failure risks for North American siloxane supply.
- Fluoropolymer substitution in high-temperature gasketing:FKM elastomers are capturing aerospace and automotive applications above 250 degrees Celsius where silicones degrade.
Strategic Opportunities
- Mexico medical device manufacturing expansion:Tijuana and Guadalajara clusters offer tariff-advantaged assembly locations for FDA-registered silicone components.
- IRA clean energy manufacturing incentives:Battery and solar equipment production tax credits are pulling silicone encapsulant demand toward domestic supply chains.
- AI-enabled predictive formulation:Machine learning models trained on rheological data are accelerating custom elastomer development cycles for niche automotive applications.
Industry Challenges
- ISO 10993 biocompatibility testing bottlenecks:Limited third-party laboratory capacity extends medical-grade silicone validation timelines to 18-24 months.
- Legacy chlorosilane reactor retrofit requirements:EPA emissions controls mandate capital-intensive cracking furnace upgrades for pre-2015 production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Silicone Market |
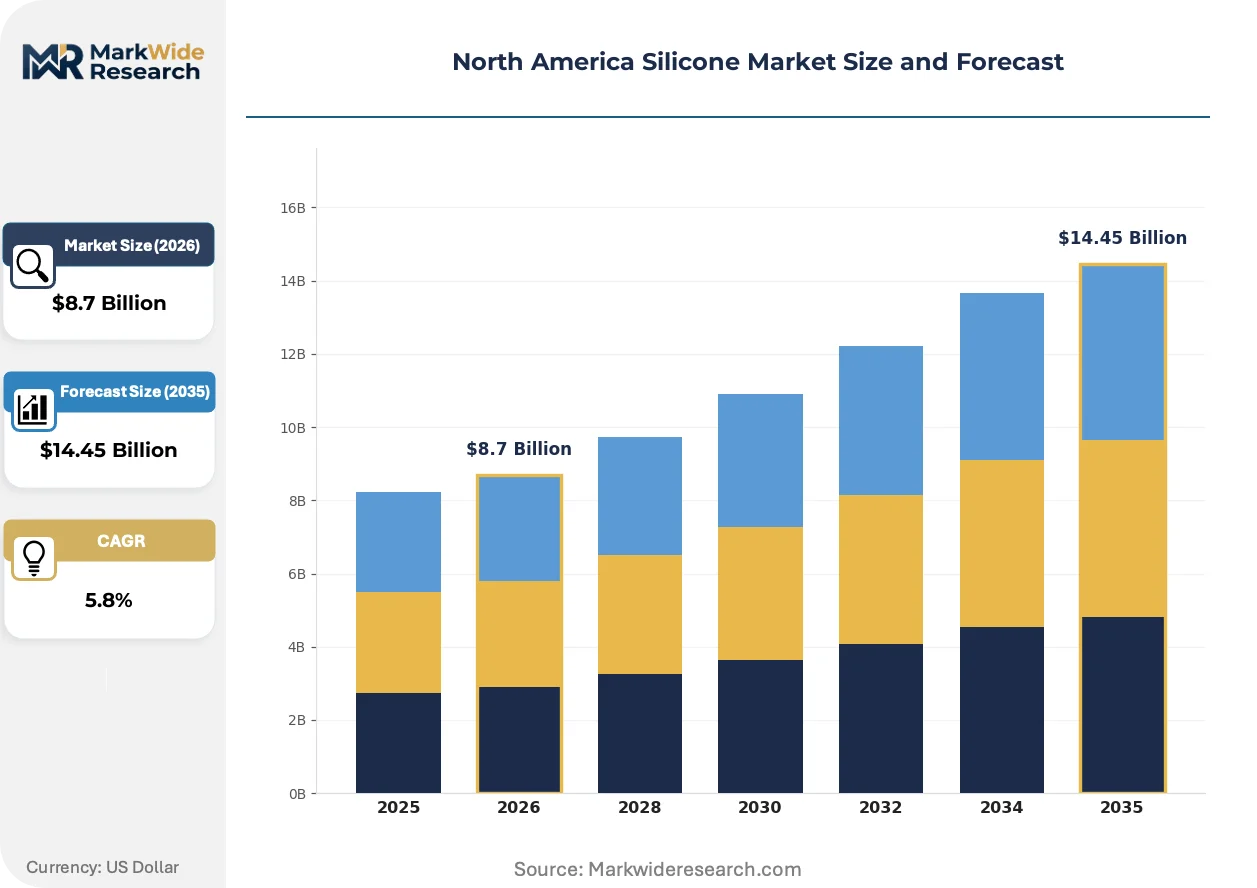
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealants, Adhesives, Elastomers, Gels Application: Construction, Automotive, Electronics, Healthcare Form: Liquid, Solid, Foam, Paste End User: Manufacturers, Distributors, Retailers, Contractors |
| Companies Covered | Dow, Wacker Chemie AG, Elkem ASA, Evonik Industries, Momentive, Shin-Etsu Chemical Co., Ltd., Kaneka Corporation, CHT Group, Gelest, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Silicone Market Evolving Landscape
Digital chemistry platforms and regulatory automation tools are compressing product development cycles while fragmenting traditional formulation value capture.
Liquid silicone rubber injection molding with in-mold monitoring sensors is decomposing the barrier between prototype and production volumes. Medical device OEMs in Minnesota and Massachusetts are adopting these systems for lot sizes under 500 units. The technology is decomposing minimum efficient scale thresholds that previously protected large-volume compounders.
EPA's expanded siloxane environmental fate assessments under TSCA Section 5 are extending premanufacture notification review periods. Formulators must now submit aquatic toxicity data for cyclic siloxanes D4, D5, and D6. Personal care and household product segments are reformulating toward linear siloxane alternatives to avoid regulatory holds.
Direct material qualification between OEMs and raw siloxane producers is bypassing traditional distributor networks. Automotive Tier 1 suppliers in Michigan and Ohio now contract directly with Dow and Momentive for specified viscosity grades. This channel compression is most visible in electric vehicle battery module sealing applications where traceability requirements exceed distributor capabilities.
North America Silicone Market Segmentation
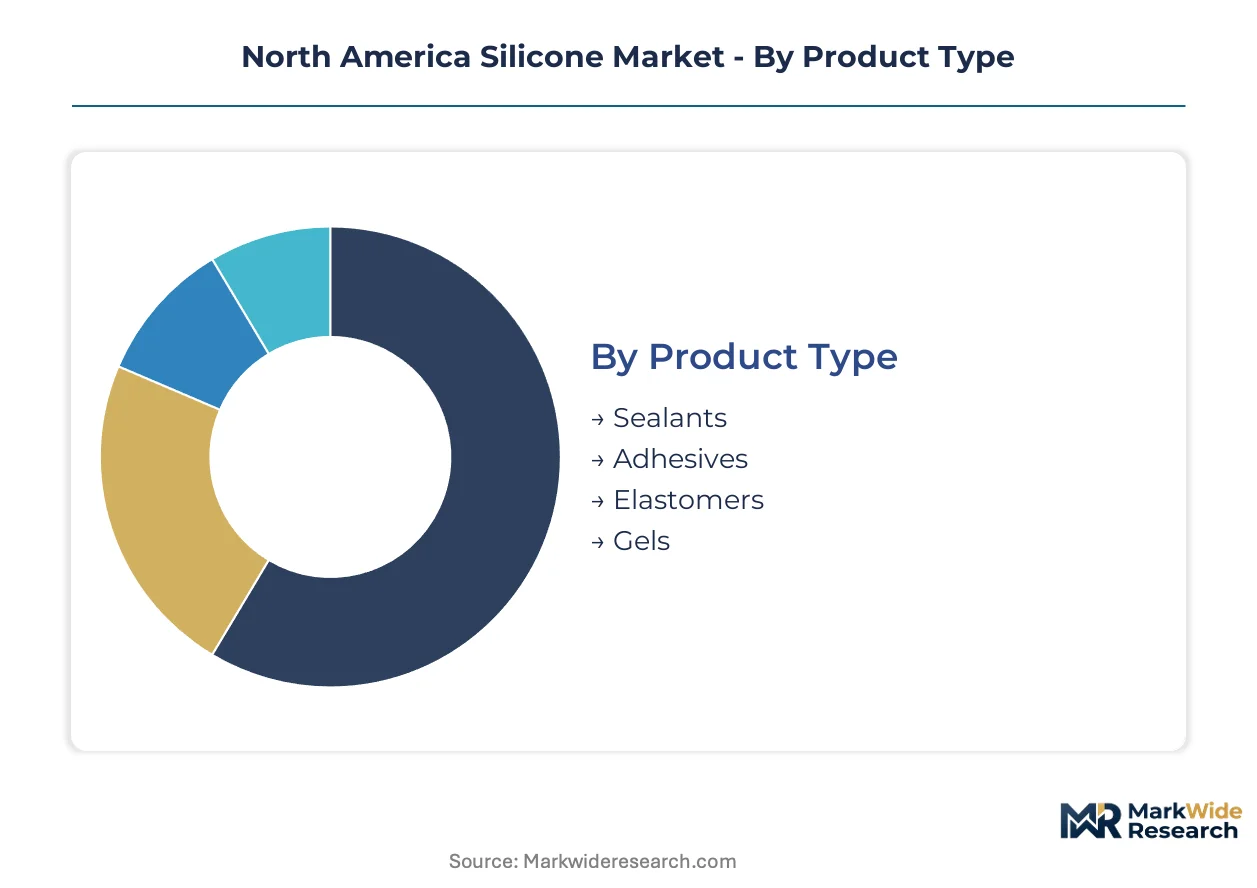
Silicone segmentation in North America reflects divergent margin architectures across product chemistry, application requirements, and supply chain proximity. Category boundaries increasingly blur as medical device OEMs demand formulation customization that spans traditional product-type definitions.
Product Type:
Elastomers and healthcare-grade gels command the widest spreads between input costs and validated selling prices, while sealants face compression from commoditized Asian imports.
- Elastomers:High-consistency rubbers and liquid silicone rubber compounds deliver compression set resistance and temperature stability from minus sixty to two hundred thirty degrees Celsius. Automotive sealing and medical tubing manufacturers in Michigan and Minnesota concentrate procurement here, though fluoropolymer substitution above two hundred fifty degrees Celsius constrains aerospace applications.
- Gels:Soft, conformable materials with Shore 00 durometer ratings provide cushioning and encapsulation for implantable devices and sensitive electronics. FDA master file requirements and eighteen-to-twenty-four-month ISO 10993 validation timelines protect margin pools for incumbent suppliers serving cardiac rhythm management and neurostimulation OEMs.
- Sealants:One-part moisture-cure and two-part addition-cure formulations dominate construction glazing and infrastructure waterproofing. Price pressure from low-cost imports limits domestic producer returns in standard-grade architectural applications.
- Adhesives:Structural bonding grades bond dissimilar substrates in transportation and electronics assembly. Demand from electric vehicle battery module manufacturers in Ohio and Tennessee favors thermally conductive formulations with dielectric properties.
The dominant share belongs to elastomers, while gels are closing the gap fastest through healthcare premiumization.
Application:
Volume concentration diverges sharply from value capture, with construction consuming tonnage while electronics and healthcare generate returns per kilogram.
- Healthcare:Implantable devices, wearable sensors, and drug delivery systems require platinum-cured grades with extractables testing and USP Class VI certification. Validation bottlenecks at limited ISO 10993 testing laboratories extend commercialization timelines, entrenching relationships between device manufacturers and incumbent silicone compounders.
- Electronics:Thermal interface materials, conformal coatings, and encapsulants serve semiconductor packaging and power electronics. Arizona and Texas fabrication facilities drive demand for ultra-high-purity electronic grades with metallic impurity specifications below ten parts per billion.
- Construction:Structural glazing, weathersealing, and infrastructure waterproofing absorb volume production. Cyclicality in non-residential building permits creates demand volatility that integrated Gulf Coast producers manage through captive chlorosilane flexibility.
- Automotive:Gasketing, hoses, and vibration dampers transition toward electric vehicle architectures. Battery module sealing and thermal runaway protection requirements favor addition-cure liquid silicone rubber with flame-retardant additives.
Construction retains volume leadership, though electronics and healthcare together capture disproportionate value through specification intensity.
Form:
Processing economics and equipment specialization create distinct competitive territories across physical states.
- Liquid:Pumpable viscosity grades enable automated dispensing and liquid injection molding. Medical device manufacturers in Massachusetts and Minnesota adopt in-mold monitoring sensors for lot sizes below five hundred units, collapsing minimum efficient scale thresholds.
- Solid:High-consistency rubber requires mill mixing and compression or transfer molding. Automotive and industrial gasket producers favor this form for thick-section parts where liquid grades exhibit cure inhibition.
- Foam:Cellular structures provide cushioning, thermal insulation, and energy absorption. Transportation seating and medical positioning applications specify controlled cell structure and compression-deflection characteristics.
- Paste:Non-sag thixotropic grades suit vertical and overhead applications in construction sealing. Tooling and cure speed requirements differentiate professional-grade from consumer DIY formulations.
Liquid formulations lead in growth velocity, while solids maintain installed base dominance in heavy industrial applications.
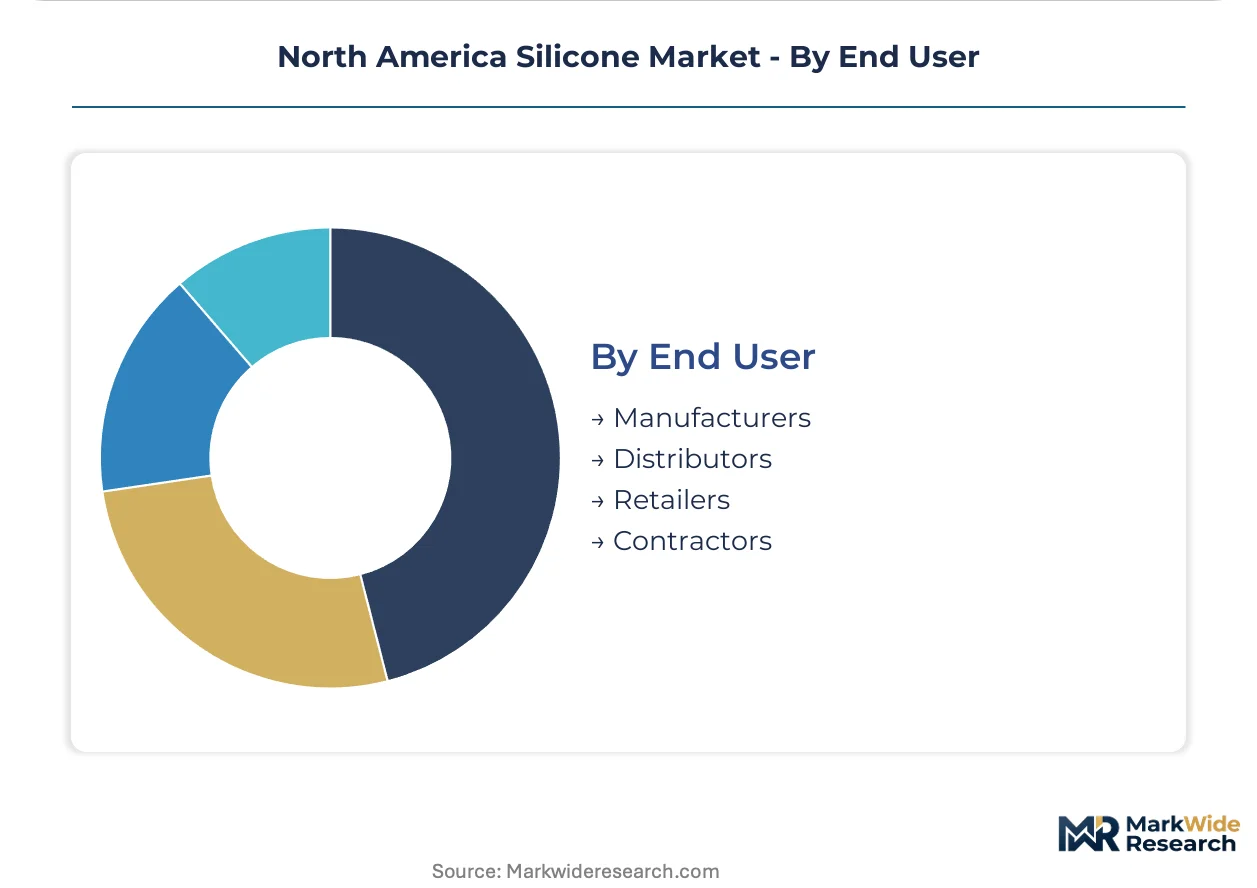
End User:
Channel structure determines technical support intensity and pricing transparency across the value chain.
- Manufacturers:OEMs and Tier 1 suppliers in automotive, electronics, and medical devices contract directly with Dow, Momentive, and Wacker for specified viscosity grades. Traceability requirements for FDA-regulated devices and automotive PPAP documentation exceed distributor capabilities.
- Distributors:Regional and national chemical distributors serve mid-tier formulators and smaller OEMs with inventory positioning and technical service. Value-added blending and repackaging operations concentrate in Chicago, Houston, and Philadelphia logistics corridors.
- Contractors:Professional installers in construction and MRO segments purchase through building material retailers and specialty distributors. Product selection depends on cure speed, tooling characteristics, and warranty support.
- Retailers:Big-box home improvement and e-commerce platforms serve consumer DIY applications with pre-packaged sealants and adhesives. Price transparency and brand recognition drive purchase decisions at this tier.
Direct manufacturer relationships concentrate value capture, while distributor intermediation persists where technical specification complexity remains moderate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates along the U.S. Gulf Coast petrochemical corridor while Canadian and Mexican producers capture value through tariff-advantaged assembly and specialized formulation capabilities.
United States
Semiconductor packaging demand from Arizona and Texas fabrication facilities drives ultra-high-purity electronic-grade silicone consumption. EPA TSCA Section 5 premanufacture notifications extend review timelines for cyclic siloxanes D4, D5, and D6. The Gulf Coast chlorosilane-to-elastomer production clusters near Houston deliver integrated margin capture across the value chain.
Canada
Healthcare-grade silicone component assembly serves U.S. medical device OEMs through tariff-advantaged cross-border supply chains. Health Canada and PMRA coordinate with EPA on harmonized chemical safety evaluations under TSCA-aligned standards. Ontario-based formulators concentrate on FDA-registered implantable device materials for cardiac rhythm management applications.
Mexico
Tijuana and Guadalajara medical device manufacturing clusters absorb silicone procurement for implantable and wearable component assembly. Mexico's proximity to U.S. distribution networks reduces logistics costs for just-in-time delivery to Arizona and California semiconductor facilities. Nuevo León petrochemical infrastructure supports regional siloxane precursor availability.
North America Silicone Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chlorosilane producers commanding upstream margins while formulation specialists capture premium positioning in validated healthcare and electronics segments. The market structure consolidates around Gulf Coast production assets with captive silicon metal and methanol supply. Three archetypes dominate: backward-integrated commodity elastomer producers, healthcare-grade certification specialists, and ultra-high-purity electronic-grade compounders. Competitive moves center on capacity expansion in medical device corridors and strategic partnerships with semiconductor packaging OEMs.
Within the integrated producer tier, Dow and Momentive exemplify divergent strategic positioning—Dow anchors Gulf Coast chlorosilane-to-elastomer production with captive cracking assets, while Momentive occupies the healthcare-grade formulation specialist position. Shin-Etsu Chemical Co., Ltd. represents the ultra-high-purity electronic-grade archetype, serving semiconductor fabrication customers with metallic impurity specifications below ten parts per billion.
| Leading Market Players |
|---|
| Dow |
| Wacker Chemie AG |
| Elkem ASA |
| Evonik Industries |
| Momentive |
| Shin-Etsu Chemical Co., Ltd. |
| Kaneka Corporation |
| CHT Group |
| Gelest, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Gulf Coast chlorosilane producers and automotive Tier 1 suppliers lock in volume commitments and price visibility across cyclical silicon metal markets. These arrangements shield integrated producers from spot volatility while forcing non-captive formulators into margin-squeezing short-term procurement.
Pricing Analysis
The customization-premium spread between configured-to-order healthcare-grade formulations and standard construction sealants exceeds threefold in North American silicone markets. Pricing stratifies across FDA-registered implantable grades, industrial elastomers, and commodity architectural sealants, with certification intensity as the primary differentiation driver. Price erosion runs through construction-grade volumes due to low-cost Asian imports, while medical device OEMs exhibit lowest price sensitivity given validation switching costs. Automotive battery module sealants occupy a mid-tier position where thermal conductivity specifications command moderate premiums over general industrial grades.
Supply Chain Analysis
Just-in-time inventory strategies dominate among Minnesota and Massachusetts medical device manufacturers running liquid silicone rubber injection molding cells with lot sizes below five hundred units. Supply concentrates in the United States Gulf Coast, Germany, and Japan, with chlorosilane cracking capacity anchored near Houston petrochemical infrastructure. Raw material feeds draw from metallurgical-grade silicon smelters, methanol steam crackers, and platinum catalyst suppliers. Single-source vulnerability persists for ultra-high-purity electronic grades with metallic impurity specifications below ten parts per billion. Distribution runs through direct OEM contracts for validated healthcare and automotive applications, with regional distributors serving construction and industrial maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American silicone demand sits in early-cycle expansion driven by semiconductor packaging thermal management requirements and electric vehicle battery module sealing adoption. Penetration headroom remains substantial in Mexico medical device manufacturing corridors and IRA-incentivized clean energy equipment production.
For Market Incumbents: Compound defensive positioning through captive chlorosilane capacity additions along the Gulf Coast and accelerated FDA master file submissions for implantable device grades. Fluoropolymer substitution above two hundred fifty degrees Celsius threatens aerospace gasket applications, demanding R&D investment in hybrid silicone-fluorosilicone formulations. Backward integration into silicon metal procurement through long-term smelter offtakes secures margin capture against Chinese supply curtailments.
For New Entrants and Emerging Players: Differentiate on rapid-turn medical device prototyping services leveraging AI-enabled rheological modeling and in-mold monitoring sensor integration. The most penetrable white-space sits in Tijuana and Guadalajara contract manufacturing clusters serving FDA-registered component assembly with tariff-advantaged logistics. Target electronics thermal interface materials for Arizona and Texas semiconductor fabrication facilities where ultra-high-purity specifications deter commodity competition. Go-to-market execution favors direct OEM qualification partnerships bypassing traditional distributor networks.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained expansion phase that favors backward-integrated producers with healthcare certification pipelines. Long-term viability over the next decade hinges on regulatory moat depth around ISO 10993 validation timelines and EPA TSCA Section 5 compliance infrastructure. Acquisition targets should display captive chlorosilane supply or specialized healthcare-grade formulation capabilities with active FDA master files. The signal to watch is EPA review period extension for cyclic siloxanes D4, D5, and D6, which would accelerate reformulation demand toward linear siloxane alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Production | Gulf Coast cracking assets capture margin across elastomer value chains against feedstock volatility. |
| Healthcare-Grade FDA Master File Expansion | Validation barriers protect premium positioning in cardiac rhythm management and neurostimulation supply chains. |
| AI-Enabled Formulation Development | Machine learning compression of rheological testing cycles accelerates custom elastomer commercialization timelines. |
| Mexico Manufacturing Corridor Partnership | Tijuana and Guadalajara clusters offer tariff-advantaged assembly locations for just-in-time U.S. distribution. |
| Ultra-High-Purity Electronic Grade Capacity | Arizona and Texas semiconductor packaging demand requires metallic impurity specifications below ten parts per billion. |
Research Methodology
A standing panel of silicone plant managers, medical device procurement directors, automotive Tier 1 supplier engineers, and distribution channel partners provided ongoing calibration across primary fieldwork. Secondary validation drew from EPA TSCA Section 5 filing databases, FDA device master file registries, U.S. customs trade data, and ACC industry reports. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, application, and regional production hub dimensions. CAGRs were derived from weighted average growth contributions across elastomer, gel, sealant, and adhesive segments. Forecast inputs incorporated semiconductor fabrication capacity announcements, electric vehicle production tax credit utilization rates, and state-level chemical safety regulatory alignment trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained EPA TSCA review intensity and continued Gulf Coast petrochemical corridor concentration; material deviation would warrant model refresh. Revision becomes warranted when silicon metal spot price volatility or hurricane-related production disruption crosses thresholds that alter integrated producer margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Yttrium Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Europium Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
India Silicon Carbide (Sic) Market