
 US Distributed Acoustic Sensing Market | 2026-2036
US Distributed Acoustic Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
US Distributed Acoustic Sensing Market Insights
Photonic interrogator hardware is fragmenting into modular, software-defined architectures that slash deployment costs and enable edge analytics. Halliburton Company leverages its integrated oilfield services footprint to bundle DAS with completions workflows. Schlumberger Limited anchors its position through fiber-optic sensing R&D tied to reservoir monitoring. Baker Hughes Company competes by extending its industrial IoT platform to pipeline integrity applications.
Distributed acoustic sensing deploys standard or specialty single-mode fiber as a continuous vibration detector, with interrogator units sending coherent laser pulses and analyzing Rayleigh backscatter to detect strain events over distances exceeding fifty kilometers. Its primary purpose spans pipeline leak detection, third-party intrusion alerts, and structural health monitoring for critical infrastructure. Pipeline Monitoring leads application revenue due to PHMSA-mandated leak detection requirements, while Perimeter Security grows fastest as data centers and utilities harden physical boundaries. Fiber Optic Sensors dominate technology revenue given superior spatial resolution and immunity to electromagnetic interference.
PHMSA regulations under 49 CFR Part 195 compel hazardous liquid pipeline operators to deploy continuous monitoring, directly expanding DAS procurement cycles. EPA methane emissions rules and FERC certificate conditions for new gas infrastructure further embed fiber sensing into compliance architecture. Stakeholders must weigh interrogator refresh cycles against software analytics upgrades to preserve capital efficiency.
Market Dynamics
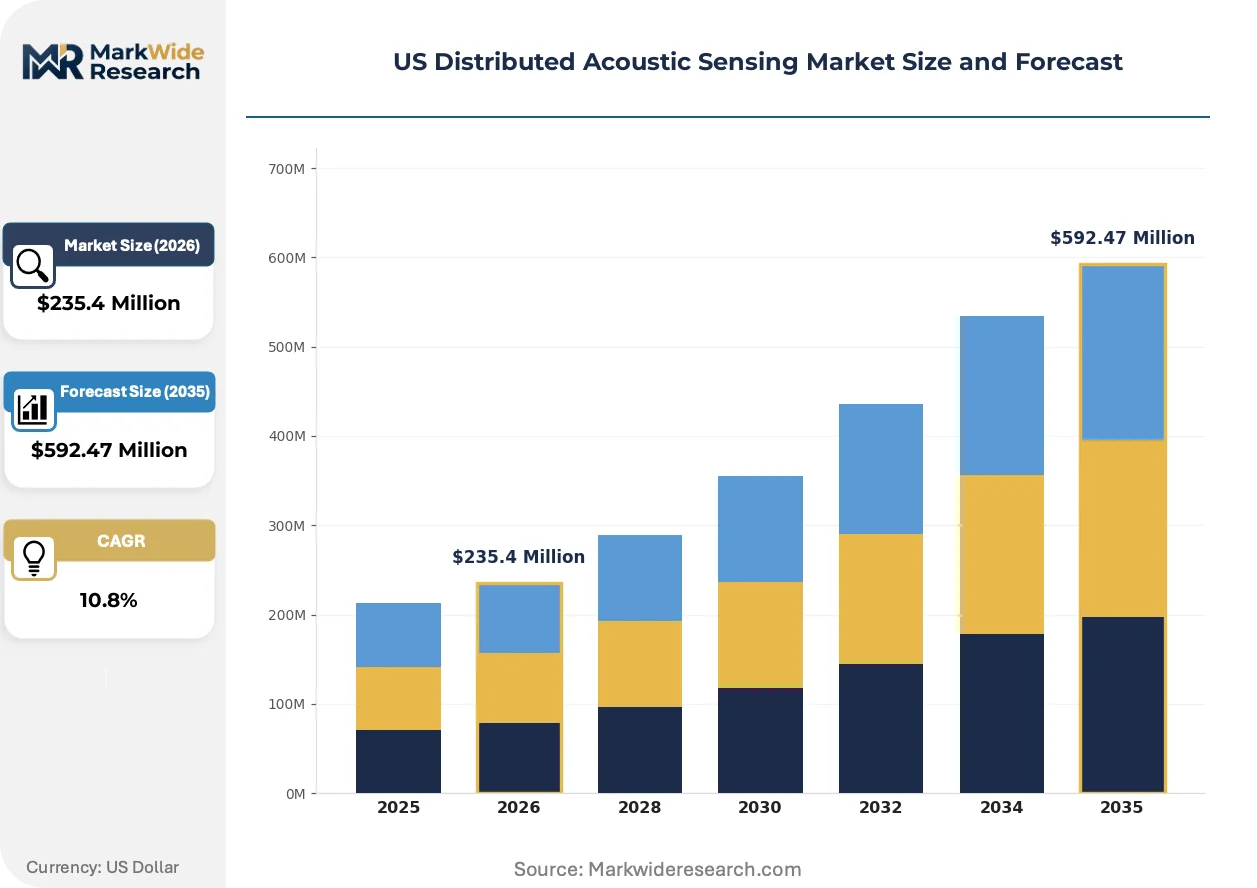
PHMSA's integrity management mandates under 49 CFR Part 195 have locked fiber-optic sensing into pipeline compliance architecture, converting DAS from optional monitoring to non-negotiable infrastructure. This regulatory embedding reshapes capital allocation cycles and vendor procurement patterns.
Growth Catalysts
- Methane emissions rules:EPA regulations compel continuous leak detection across natural gas infrastructure, expanding DAS deployment beyond liquid pipelines into gas transmission networks.
- Permian Basin concentration:Pipeline density in West Texas and New Mexico creates clustered demand that amortizes fiber installation costs across multiple operator contracts.
- Data center perimeter hardening:Hyperscale facilities in Northern Virginia and Dallas-Fort Worth adopt DAS for physical security, diversifying revenue beyond energy applications.
Market Restraints
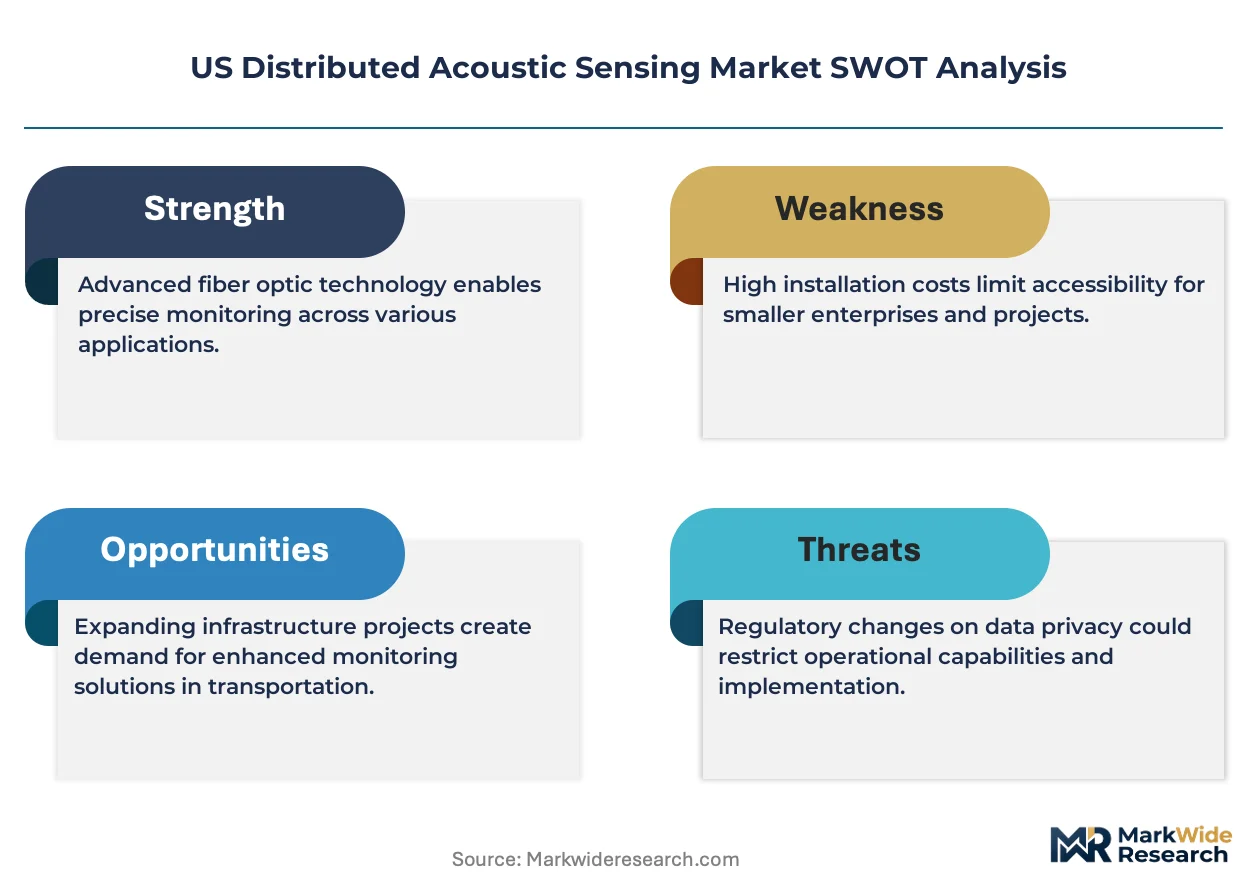
- Interrogator hardware costs:Photonic components and coherent laser systems carry upfront capital intensity that stretches payback periods for mid-size pipeline operators.
- Specialty fiber dependency:Sensing-grade single-mode fiber concentrates production among limited domestic suppliers, creating input bottlenecks during deployment surges.
- Electromagnetic sensing substitutes:Satellite-based methane monitoring and aerial leak detection offer alternative compliance pathways that fragment budget allocation.
Strategic Opportunities
- Offshore Gulf of Mexico:Subsea pipeline networks lack mature monitoring infrastructure, presenting greenfield deployment potential as decommissioning liabilities mount.
- Rail corridor monitoring:Class I railroads face FRA pressure to prevent third-party intrusion and track damage, opening adjacent infrastructure applications.
- Edge analytics convergence:Integration of DAS with AI-driven pattern recognition at the interrogator level enables real-time classification without cloud latency.
Industry Challenges
- Photonics engineering scarcity:The intersection of fiber-optic physics and signal processing demands specialized talent pools concentrated in Boston and Austin corridors.
- Legacy SCADA integration:Pipeline control rooms operate on decades-old architectures that resist seamless data ingestion from distributed sensor networks.
- PHMSA certification timelines:Validation of new DAS configurations for leak detection accuracy extends vendor sales cycles and delays revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Distributed Acoustic Sensing Market |
| Market Size in 2026 | $235.4 Million |
| Market Size in 2035 | $592.47 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Pipeline Monitoring, Perimeter Security, Environmental Monitoring, Transportation Safety Technology: Fiber Optic Sensors, Microwave Sensors, MEMS Sensors, Acoustic Sensors End User: Oil & Gas, Utilities, Transportation, Defense Installation: Onshore, Offshore, Underground, Aboveground |
| Companies Covered | Halliburton Company, Schlumberger Limited, Baker Hughes Company, OptaSense, Northrop Grumman Corporation, Future Fibre Technologies, Fotech Solutions Ltd., Luna Innovations Incorporated, Hifi Engineering Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Distributed Acoustic Sensing Market Trends and Innovations
Software-defined interrogator architectures are fragmenting hardware value into modular layers, enabling analytics upgrades without full system replacement. This decoupling reshapes vendor competitive dynamics and buyer lifecycle economics.
Photonic integration is collapsing the cost structure of coherent detection modules. Silicon photonics foundries now fabricate laser and receiver components on single chips, slashing unit economics. Midstream operators in the Eagle Ford Shale are piloting these integrated platforms, compressing deployment timelines from months to weeks.
EPA methane performance standards under the Inflation Reduction Act impose escalating fees on vented emissions, tightening detection thresholds. Pipeline operators must demonstrate continuous monitoring coverage or face penalty exposure. This regulatory compression accelerates DAS procurement in the Rocky Mountain and Appalachian basins where gathering line density complicates alternative monitoring.
Buying patterns are consolidating around multi-year service agreements that bundle hardware, software, and analytics. Operators prefer operational expenditure structures that transfer obsolescence risk to vendors. This shift concentrates contract awards among integrated service providers with balance sheet capacity to underwrite long-term performance guarantees, particularly visible in Permian and Bakken contract awards.
US Distributed Acoustic Sensing Market Segmentation
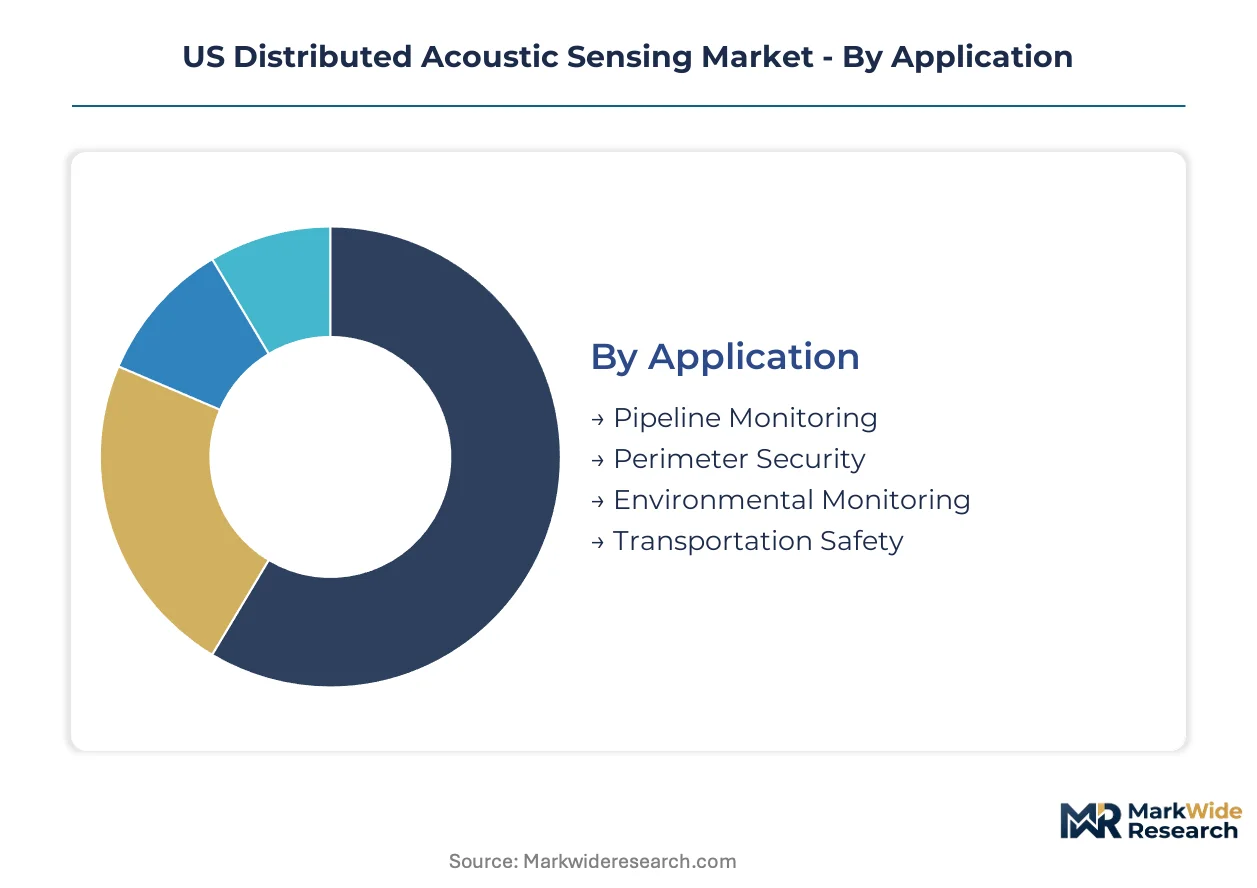
Segmentation in the US Distributed Acoustic Sensing Market reveals divergent procurement rhythms across application types and installation environments. Operators in the Permian Basin and Gulf Coast drive category-specific demand patterns that reshape vendor product roadmaps and service bundling strategies.
Application:
Refresh cycles vary dramatically across applications, with compliance-driven segments turning over every 5-7 years while security-focused deployments refresh on 3-4 year analytics upgrade timelines.
- Pipeline Monitoring:Deployments use continuous fiber-optic coverage to detect leaks, third-party intrusion, and structural anomalies along hazardous liquid and gas transmission corridors. PHMSA mandates under 49 CFR Part 195 lock this segment into baseline procurement for midstream operators in Texas, Louisiana, and Oklahoma, creating predictable replacement demand tied to integrity management audits.
- Perimeter Security:Systems deploy buried or fence-mounted fiber to detect climbing, cutting, or tunneling attempts with minimal false alarms. Hyperscale data centers in Northern Virginia and Dallas-Fort Worth are expanding this segment fastest as physical security budgets harden against infrastructure targeting.
- Environmental Monitoring:Applications track seismic activity, landslide risk, and groundwater movement using strain-sensitive fiber deployments. Demand concentrates near dam infrastructure and mining operations in the Rocky Mountain states where geohazard liability drives sensor density.
- Transportation Safety:Rail corridors and highway tunnels deploy DAS to detect track deformation, vehicle intrusion, or unauthorized access. Class I railroads piloting systems in the Midwest face FRA pressure to demonstrate continuous coverage for hazmat routes.
Pipeline Monitoring anchors the volume base while Perimeter Security gains share at the steepest rate.
Technology:
Cost tiers separate photonic interrogators from solid-state alternatives, with fiber-based systems commanding 3-4x the unit price but delivering superior spatial resolution and range.
- Fiber Optic Sensors:Coherent laser interrogators analyze Rayleigh backscatter in standard or specialty single-mode fiber to detect strain events over 50+ kilometer spans. The technology dominates revenue given immunity to electromagnetic interference and compatibility with existing telecom fiber infrastructure across the Eagle Ford and Bakken shale plays.
- Microwave Sensors:Radar-based systems detect motion and vibration without physical cable deployment, offering faster installation for temporary or mobile applications. Border security and event perimeter deployments in Arizona and Texas drive niche demand where fiber trenching proves impractical.
- MEMS Sensors:Micro-electromechanical accelerometers provide point-source vibration detection at lower cost per node but require dense spacing for equivalent coverage. Utilities in the Northeast deploy these for substation and transformer monitoring where distributed fiber remains uneconomical.
- Acoustic Sensors:Traditional piezoelectric or condenser microphones offer localized sound detection for indoor or contained environments. Data center server halls and critical facility entry points use these for targeted threat identification alongside broader perimeter fiber systems.
Fiber Optic Sensors command the premium tier while MEMS Sensors capture volume in cost-constrained utility deployments.
End User:
Customer type determines contract structure, with oil and gas operators favoring 10-year performance agreements while defense buyers operate on classified procurement cycles with irregular visibility.
- Oil & Gas:Midstream pipeline operators and upstream producers deploy DAS for leak detection, hydraulic fracture monitoring, and reservoir surveillance. The segment concentrates spending in the Permian Basin where gathering line density and PHMSA compliance pressure create clustered demand.
- Utilities:Electric transmission and water distribution operators use DAS for cable fault location, pipeline integrity, and third-party damage prevention. Investor-owned utilities in California and Texas are expanding deployments as wildfire liability and drought stress harden infrastructure protection budgets.
- Transportation:Railroads, port authorities, and state DOTs pilot DAS for track monitoring, tunnel security, and bridge structural health. Federal infrastructure spending is accelerating trial programs along critical freight corridors in the Pacific Northwest and Gulf Coast.
- Defense:Military installations and critical government facilities deploy classified DAS configurations for perimeter hardening and intrusion detection. Procurement flows through specialized channels with limited vendor visibility and extended validation timelines.
Oil & Gas dominates current contract value while Transportation is expanding most quickly as federal funding unlocks pilot programs.
Installation:
Deployment environment shapes capital intensity and vendor selection, with offshore and underground installations requiring specialized marine or directional drilling contractors that extend project timelines 40-60% versus aboveground alternatives.
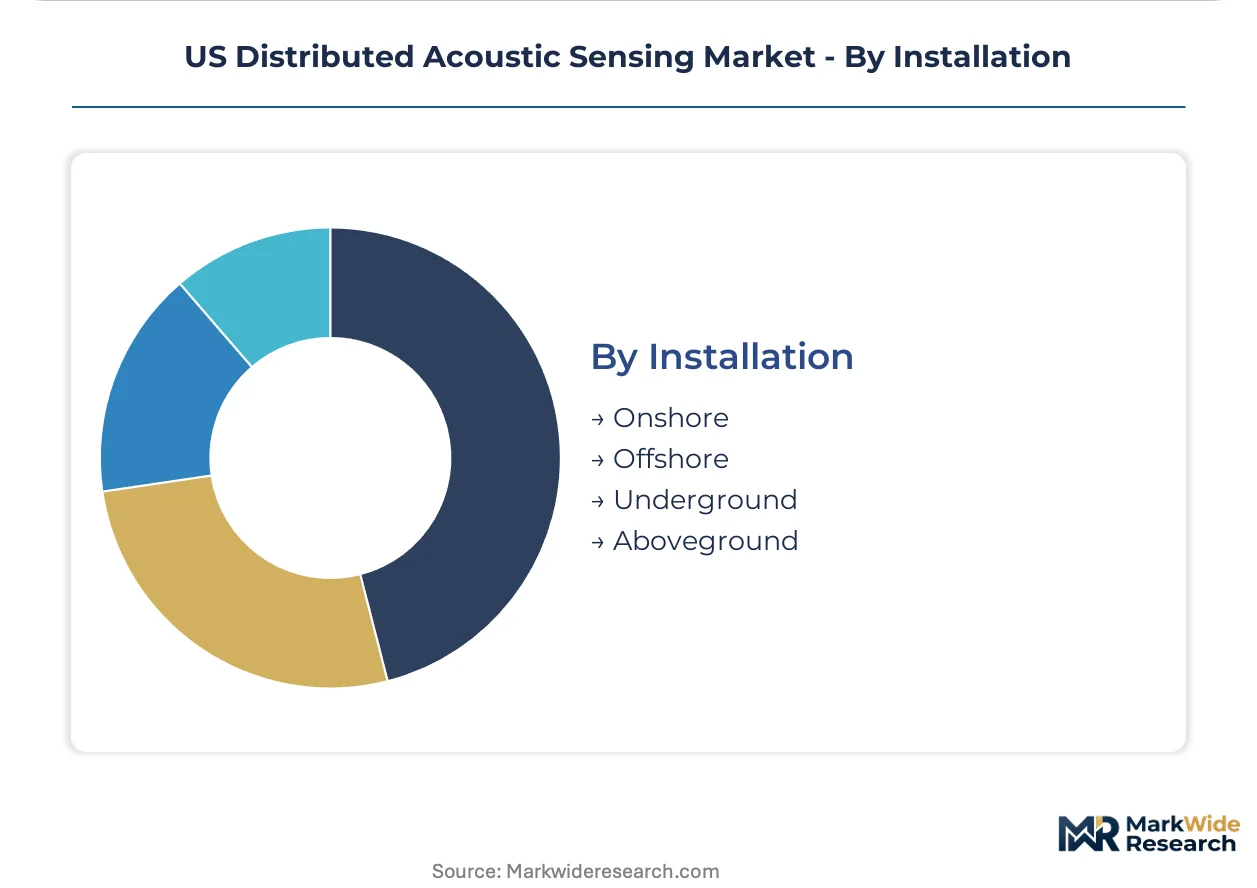
- Onshore:Surface-laid or shallow-buried fiber along pipeline rights-of-way and facility perimeters constitutes the majority of installed base. Standard trenching and aerial deployment methods in Texas and New Mexico keep unit costs lowest and contractor availability highest.
- Offshore:Subsea fiber installations on pipeline bundles and platform risers demand marine-grade cable armoring and wet-mate connectors. Gulf of Mexico decommissioning liability and new deepwater tiebacks are driving greenfield procurement as operators face expanded monitoring obligations.
- Underground:Deep-buried or horizontal directional-drilled deployments protect fiber in high-threat urban corridors and river crossings. Chicago and Houston transit authorities specify these for rail tunnel and critical utility protection where surface access is restricted.
- Aboveground:Fence-mounted or structure-attached sensors serve rapid-deployment security applications and temporary monitoring needs. Data center campuses and construction sites in Phoenix and Atlanta favor these for speed of installation and relocation flexibility.
Onshore deployment anchors the installed base while Offshore installations are climbing the fastest as Gulf of Mexico infrastructure ages and regulatory scrutiny intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US fiber-optic sensing equipment flows primarily to domestic pipeline operators in the Permian Basin and Gulf Coast, with secondary demand emerging from Canadian oil sands producers seeking spill detection systems for thermal extraction corridors.
Texas and Gulf Coast
PHMSA integrity management audits drive replacement cycles across 85,000 miles of hazardous liquid pipelines concentrated in Houston and Corpus Christi. The EPA's methane performance standards under the Inflation Reduction Act compel continuous monitoring deployment in the Eagle Ford Shale. Dallas-Fort Worth data center clusters are adopting perimeter DAS for physical security hardening.
Permian Basin
West Texas and Southeast New Mexico host the densest gathering line networks in North America, amortizing fiber installation costs across multi-operator contracts. FERC certificate conditions for new gas infrastructure mandate fiber sensing integration before commercial operation. Midland-Odessa service companies bundle DAS with hydraulic fracture monitoring for integrated completions workflows.
Rocky Mountain Region
Colorado and Wyoming pipeline operators face escalating penalty exposure from EPA vented emissions fees, tightening detection threshold requirements. State-level spill notification rules in Utah and Montana compress response time windows. Denver-Julesburg Basin midstream players are consolidating procurement around multi-year service agreements with integrated analytics.
Appalachian Basin
Marcellus and Utica shale producers deploy DAS for gathering line leak detection across Pennsylvania and West Virginia terrain where aerial monitoring proves unreliable. PHMSA gas transmission regulations under 49 CFR Part 192 extend compliance pressure beyond liquid pipelines. Pittsburgh-based engineering firms specialize in horizontal directional drilling for fiber protection in river crossing corridors.
California and Pacific Coast
Investor-owned utilities in California expand DAS deployment for wildfire liability mitigation along electric transmission corridors. State water district operators monitor aqueduct integrity using strain-sensitive fiber across the Central Valley. Los Angeles data center campuses and Bay Area critical facilities are piloting fence-mounted systems for intrusion detection.
US Distributed Acoustic Sensing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across interrogator hardware, fiber installation services, and analytics software layers. The vendor base clusters around three strategic archetypes: integrated oilfield services conglomerates with bundled offerings, standalone photonics specialists with modular interrogator platforms, and industrial IoT platform extenders with edge analytics capabilities. Dominant competitive moves include multi-year performance contracting that transfers obsolescence risk to vendors, and silicon photonics integration that collapses coherent detection module costs.
Within the integrated services tier, Halliburton Company and Schlumberger Limited anchor positions through oilfield services footprints that bundle DAS with completions and reservoir monitoring workflows. Baker Hughes Company occupies a position on the industrial IoT vector, extending platform capabilities into pipeline integrity applications. These three exemplify the channel-control strategy of underwriting long-term performance guarantees to capture Permian and Bakken contract awards.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Limited |
| Baker Hughes Company |
| OptaSense |
| Northrop Grumman Corporation |
| Future Fibre Technologies |
| Fotech Solutions Ltd. |
| Luna Innovations Incorporated |
| Hifi Engineering Inc. |
| Others |
Pricing and Supply Chain Analysis
Boston's photonics corridor anchors coherent laser module production, concentrating interrogator manufacturing capacity among a handful of specialized foundries. This geographic clustering grants upstream suppliers significant pricing leverage over downstream DAS integrators, particularly during deployment surges in the Permian Basin and Gulf Coast.
Pricing Analysis
Cost-plus contracts with laser component indexation dominate procurement between pipeline operators and DAS vendors. Three-tier pricing structure across premium, standard, and economy levels separates PHMSA-certified leak detection systems from perimeter security configurations and temporary monitoring deployments. Price differentiation hinges on EPA compliance certification tier and fiber spatial resolution specifications. Cost compression in standard-tier interrogators is intensifying because silicon photonics integration collapses coherent detection module economics. Mid-size gathering line operators in the Rocky Mountain region exhibit the highest price sensitivity, while supermajor pipeline operators in Texas prioritize performance guarantees over unit cost.
Supply Chain Analysis
Export control restrictions under ITAR and EAR limit coherent laser interrogator flows to certain defense and critical infrastructure applications, constraining vendor participation in classified procurement channels. Manufacturing concentrates in the United States, Germany, and Japan for photonic components and specialty single-mode fiber. The supply chain draws from rare-earth doped fiber, indium phosphide laser chips, and precision optical couplers as critical inputs. Single-source vulnerability around sensing-grade fiber production creates bottleneck risk during federal infrastructure deployment waves. Distribution runs through integrated oilfield services providers and direct vendor relationships with midstream operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Distributed Acoustic Sensing Market sits in early-cycle expansion, with EPA methane performance standards under the Inflation Reduction Act accelerating adoption beyond pipeline compliance into gas transmission networks.
For Market Incumbents: Harden defensive moats by deepening silicon photonics integration to collapse interrogator costs below emerging MEMS substitutes. Pursue PHMSA certification pre-approval for modular software-defined architectures to compress sales cycles. Anchor long-term service agreements in the Permian Basin where multi-operator fiber sharing amortizes deployment costs and locks out challenger vendors. For New Entrants and Emerging Players: Pursue white-space opportunities in offshore Gulf of Mexico subsea monitoring where legacy infrastructure lacks coverage and decommissioning liability creates procurement urgency. Target rail corridor applications in the Midwest where FRA pressure for hazmat route monitoring outpaces incumbent oilfield focus. Lead with rapid-deployment aboveground perimeter systems for data center campuses seeking speed-to-installation over fiber trenching depth. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors photonics specialists with modular interrogator platforms and edge analytics software stacks. The five-to-ten year viability window rewards vendors capturing recurring revenue from multi-year performance contracts rather than transactional hardware sales. Watch EPA enforcement intensity around vented emissions fees as the inflection signal for DAS procurement acceleration in gas-dominant basins.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Collapses coherent detection costs and compresses Permian deployment timelines from months to weeks. |
| Multi-Year Performance Contracting | Transfers obsolescence risk to vendors and concentrates awards among balance-sheet-capable integrated service providers. |
| PHMSA Certification Pre-Approval | Accelerates vendor sales cycles and delays revenue recognition for uncertified configurations. |
| Edge Analytics Convergence | Enables real-time pattern classification without cloud latency for pipeline leak detection. |
| Offshore Gulf Expansion | Captures greenfield subsea monitoring demand as decommissioning liabilities mount and regulatory scrutiny intensifies. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with pipeline integrity managers, photonics engineering directors, midstream procurement leads, and PHMSA regulatory specialists; and secondary validation through FERC certificate filings, EPA enforcement databases, SEC 10-K disclosures from integrated service providers, and fiber-optic component trade data. Bottom-up and top-down triangulation cross-checked unit deployment estimates against aggregate capital expenditure flows.
Forecast inputs considered application segmentation across pipeline monitoring, perimeter security, environmental monitoring, and transportation safety; technology tiers spanning fiber optic, microwave, MEMS, and acoustic sensors; and installation environments including onshore, offshore, underground, and aboveground. CAGRs were derived from regression analysis against regulatory mandate timelines and infrastructure replacement cycles. Industry-specific inputs incorporated PHMSA audit schedules, EPA methane fee escalation curves, and data center construction permits in Northern Virginia and Dallas-Fort Worth.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting midstream capital allocation or federal infrastructure spending authorization would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement continuity and fiber supply chain stability. Material shifts in EPA methane rule implementation timelines or ITAR export control scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Mass Flow Controller Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Micropump Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Industrial Transmitters Market