
 Europe Semiconductor Materials Market | 2026-2036
Europe Semiconductor Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Semiconductor Materials Market Foresight
Automotive electronics buyers is reorganizing procurement priorities toward silicon carbide and gallium nitride substrates for traction inverters and onboard chargers. Infineon Technologies AG anchors European substrate supply through its Dresden manufacturing complex. STMicroelectronics leverages integrated SiC epitaxy capacity in Catania, Italy. Siltronic AG dominates merchant silicon wafer supply for logic and memory fabs across the continent.
Europe semiconductor materials encompass high-purity substrates, deposited films, and process chemicals engineered to atomic-scale tolerances for integrated circuit fabrication. Silicon wafers with sub-nanometer surface roughness serve as the foundational platform for CMOS device layers. Silicon carbide substrates command premium positioning in power electronics due to superior thermal conductivity and breakdown voltage. Epitaxy services represent the fastest-growing technology segment as device makers outsource critical layer growth. Gallium nitride powders and compounds gain traction in RF and LED applications. Wafers remain the dominant form factor by value, though ingot sourcing is concentrating among vertically integrated producers.
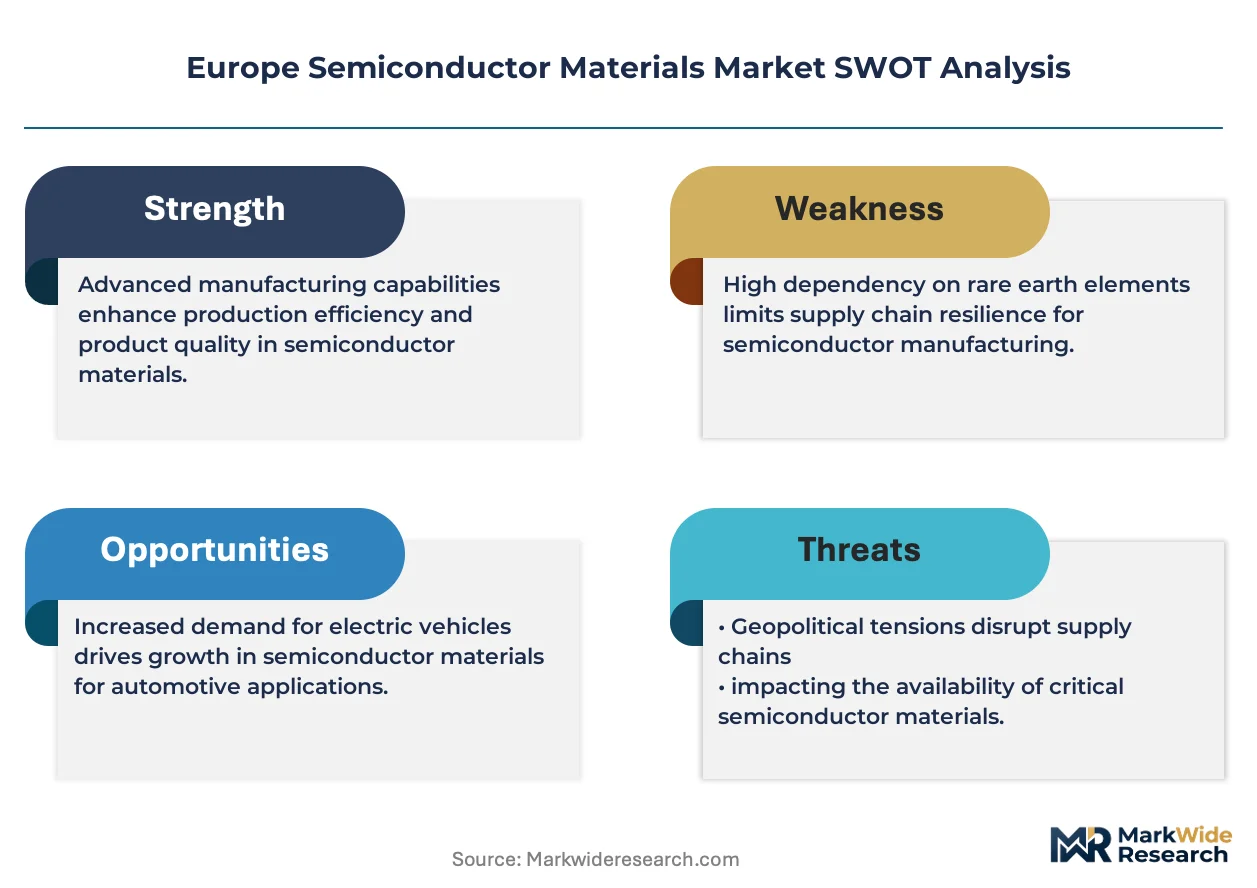
REACH and the EU Chips Act shape material purity standards and local content requirements for semiconductor supply chains. ECHA chemical restrictions limit certain etchants and deposition precursors, forcing reformulation of cleaning and patterning chemistries. The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in CVD and etch processes. Stakeholders must monitor how CSRD disclosure rules alter supplier qualification timelines and capital allocation toward greenfield European wafer capacity.
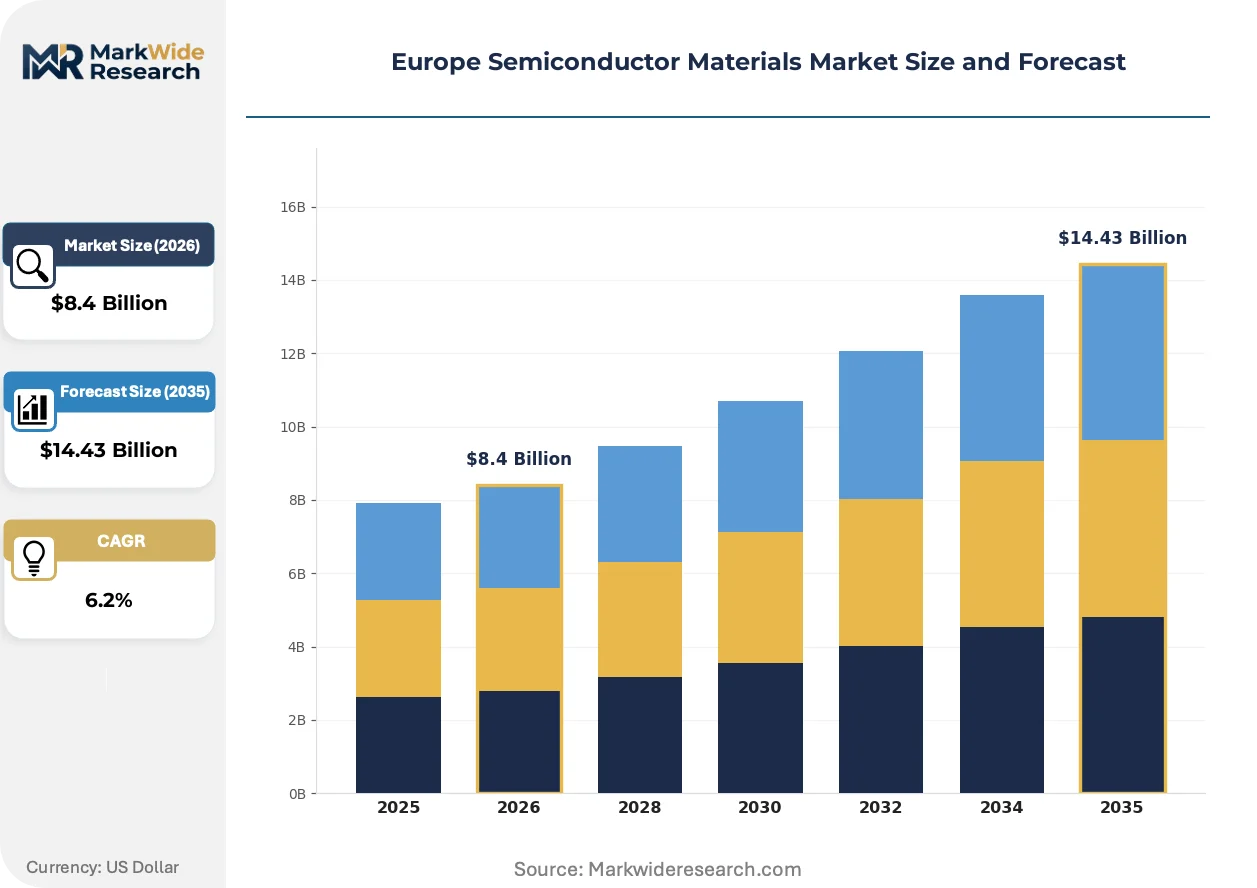
Market Dynamics
Automotive powertrain electrification is forcing a substrate technology transition from silicon to wide-bandgap materials, rewiring procurement relationships and capital allocation across European wafer supply chains.
Growth Catalysts
- EU Chips Act capital allocation:Sovereign funding instruments are accelerating greenfield silicon carbide substrate capacity in Germany and France. Domestic sourcing mandates redirect foundry procurement toward qualified European ingot suppliers.
- Traction inverter demand:Automotive OEMs are specifying silicon carbide MOSFETs for 800V architectures, pulling epitaxy services and bulk crystal growth into capacity expansion cycles.
- Grenoble-Saxony corridor concentration:Equipment makers and substrate specialists are co-locating R&D and pilot production within these clusters, compressing development timelines for next-generation node materials.
Market Restraints
- Silicon carbide boule cost structure:Crystal growth cycle times exceeding seven days and low geometric yield rates constrain substrate economics against silicon alternatives.
- Merchant silicon wafer supply concentration:German and Japanese suppliers control over 80% of 300mm prime wafer supply for logic fabs, creating single-source vulnerability for European foundry projects.
- Fluorinated gas constraints:EU F-Gas Regulation phase-down schedules are forcing CVD and etch process chemistry reformulation, extending equipment qualification periods.
Strategic Opportunities
- Polish packaging substrate corridor:Underdeveloped advanced substrate capacity in Central Europe offers greenfield entry points for fan-out wafer-level packaging material suppliers.
- CSRD disclosure acceleration:Corporate sustainability reporting mandates are creating first-mover advantage for material suppliers with verified Scope 3 carbon accounting and conflict-free mineral traceability.
- GaN-on-Si epitaxy convergence:Power and RF device makers are converging on 200mm gallium nitride epitaxy platforms, opening shared infrastructure investment models.
Industry Challenges
- Silicon carbide crystal growth technician scarcity:The specialized physics-chemistry hybrid skill set required for physical vapor transport boule production exceeds current European vocational pipeline output.
- Dual-use export control alignment:Coordinated EU-US semiconductor manufacturing equipment restrictions are complicating tool sourcing timelines for advanced node material production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Semiconductor Materials Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon, Gallium Nitride, Germanium, Silicon Carbide Form: Wafers, Powders, Compounds, Ingots Technology: Deposited Films, Epitaxy, Ion Implantation, Etching Application: Consumer Electronics, Telecommunications, Automotive Electronics, Industrial Equipment |
| Companies Covered | Osram Opto Semiconductors, IQE PLC, Infineon Technologies AG, AMS AG, Elmos Semiconductor, STMicroelectronics, NXP Semiconductors, Siltronic AG, ASM International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Semiconductor Materials Market Shifts & Advancements
Material purity thresholds and process chemistry specifications are tightening in parallel, forcing simultaneous investment in metrology capabilities and supply chain requalification across substrate and deposition precursor segments.
Silicon carbide substrates are displacing insulated-gate bipolar transistors in main traction inverters above 150kW power classes. Tier 1 automotive suppliers are qualifying 200mm SiC MOSFETs for 2025-2026 vehicle platforms. This displacement is compressing silicon epitaxy demand growth in power electronics while expanding merchant SiC substrate addressable market by an order of magnitude.
REACH authorization list expansion is restricting perfluorinated compound use in wet cleaning and deposition processes. ECHA regulatory timelines are forcing reformulation of buffered oxide etchants and ALD precursors before 2027 sunset dates. German chemical suppliers are accelerating fluorine-free alternative development, though qualification cycles with French and Italian foundries lag regulatory deadlines by 12-18 months.
Automotive electronics buyers are consolidating supplier panels and demanding captive epitaxy capacity commitments from substrate vendors. Long-term offtake agreements with minimum volume guarantees are replacing spot market wafer purchases for SiC and GaN materials. This consolidation is most advanced in Germany, where power module assemblers have reduced qualified SiC substrate sources from seven to three vendors since 2022.
Europe Semiconductor Materials Market Segmentation
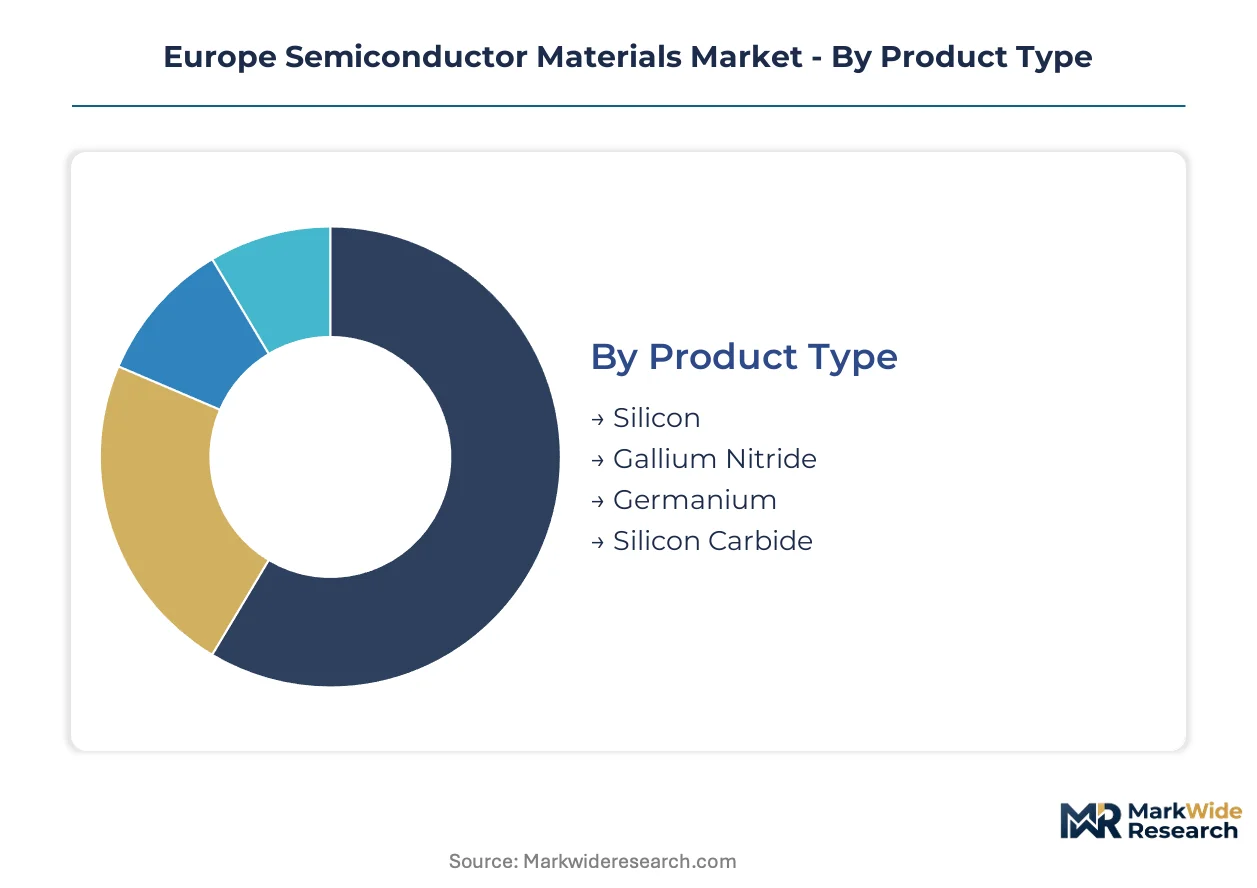
Semiconductor material selection in Europe operates under dual constraints: REACH chemical restrictions limit certain deposition precursors, while the EU Chips Act mandates local content verification. Segmentation reveals how substrate chemistry and processing technology align with end-use electrification requirements across automotive and industrial verticals.
Product Type:
ECHA substance restrictions and F-Gas Regulation phase-down schedules differentiate material adoption timelines, with fluorinated compound limits accelerating silicon carbide and gallium nitride qualification against legacy silicon platforms.
- Silicon:Crystalline silicon wafers with sub-nanometer surface roughness serve as the foundational substrate for CMOS logic and memory fabrication across Dresden and Grenoble clusters. German foundries consume the majority of 300mm prime wafers for advanced node production, though merchant supply concentration in German and Japanese vendors creates procurement vulnerability for EU sovereign capacity projects.
- Silicon Carbide:Wide-bandgap substrates with superior thermal conductivity and breakdown voltage displace insulated-gate bipolar transistors in traction inverters above 150kW power classes. French and German automotive OEMs are specifying SiC MOSFETs for 800V architectures, pulling epitaxy services and bulk crystal growth into capacity expansion cycles despite boule cost structures constrained by seven-day growth cycles and low geometric yields.
- Gallium Nitride:III-V compound semiconductors gain traction in RF power amplifiers and LED applications where high electron mobility delivers efficiency advantages.
- Germanium:Elemental substrate retains niche positioning in high-mobility channel materials for specialized photonics and infrared detector applications.
Established volume favors Silicon; emerging adoption favors Silicon Carbide.
Form:
Cost tier differentiation separates high-value processed substrates from raw material inputs, with wafer and epitaxy premiums reflecting yield loss through crystal growth and polishing stages.
- Wafers:Polished circular substrates represent the dominant value form factor, with 200mm and 300mm diameters serving distinct process node requirements. German silicon wafer suppliers and Italian SiC epitaxy providers capture premium positioning as automotive power module assemblers consolidate qualified vendor panels from seven to three sources.
- Ingots:As-grown boules undergo extensive slicing and surface preparation before device fabrication, with physical vapor transport crystal growth technician scarcity constraining European SiC ingot supply expansion.
- Powders:High-purity precursor materials feed chemical vapor deposition and molecular beam epitaxy processes for compound semiconductor fabrication.
- Compounds:Pre-synthesized III-V and II-VI material assemblies reduce deposition complexity for specialized optoelectronic and power device manufacturing.
Wafer processing commands margin concentration; ingot sourcing is concentrating among vertically integrated producers.
Technology:
Application-driven technology selection prioritizes atomic-scale precision for advanced nodes versus throughput optimization for power electronics.
- Epitaxy:Controlled crystalline layer deposition services represent the steepest expansion trajectory as device makers outsource critical SiC and GaN film growth to specialized providers. STMicroelectronics leverages integrated SiC epitaxy capacity in Catania, Italy, while merchant service providers scale 200mm GaN-on-Si platforms for converging power and RF device requirements.
- Deposited Films:Chemical and physical vapor deposition processes create insulating, conducting, and semiconducting layers with precise thickness control for interconnect and gate structures.
- Etching:Wet and dry material removal processes pattern circuit features, with EU F-Gas Regulation constraining fluorinated gas use and forcing reformulation of cleaning chemistries before regulatory sunset deadlines.
- Ion Implantation:Accelerated dopant introduction modifies electrical properties in targeted substrate regions for source, drain, and well formation.
Outsourced layer growth favors Epitaxy; in-house process integration favors Deposited Films.
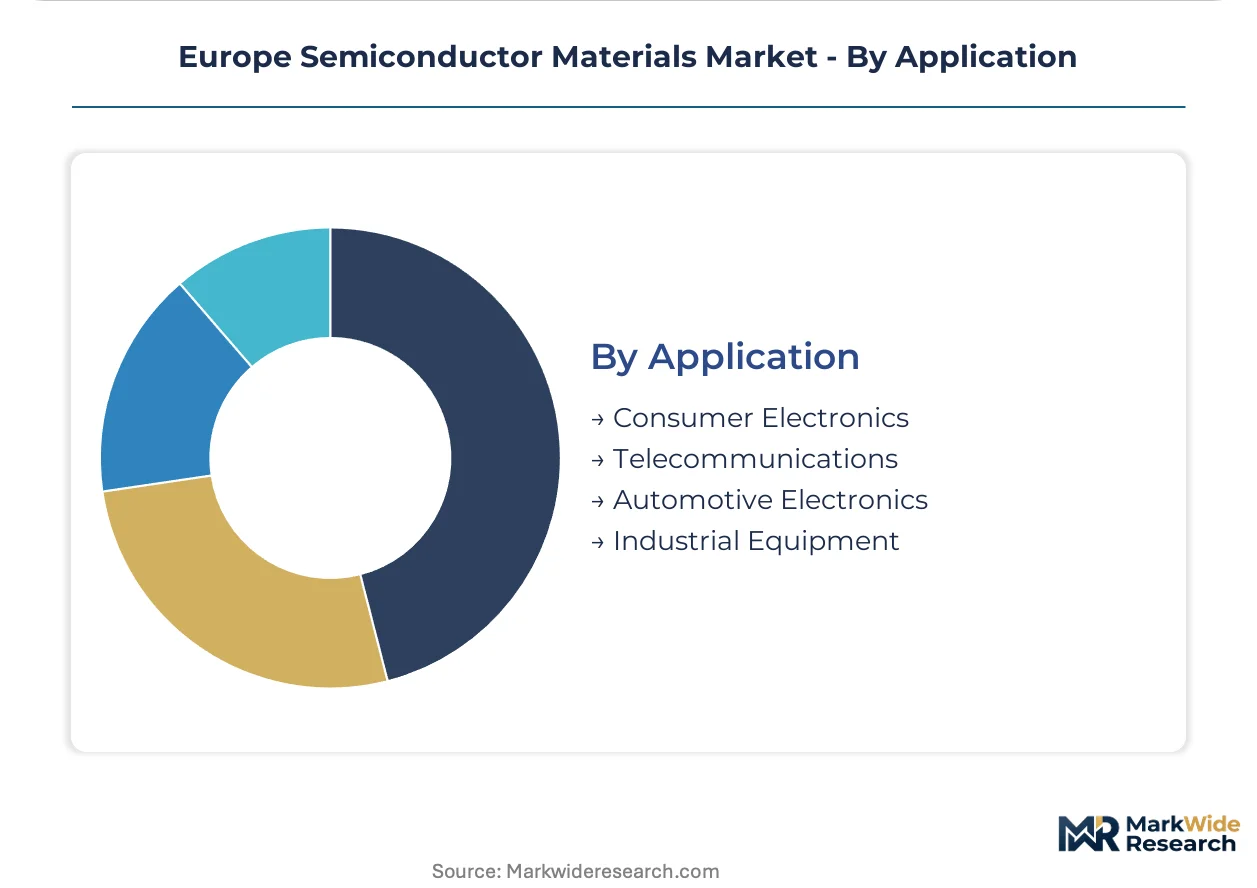
Application:
Customer type segmentation separates high-volume consumer procurement from long-cycle automotive qualification requirements.
- Automotive Electronics:Powertrain electrification and 800V platform deployment drive substrate technology transition from silicon to wide-bandgap materials. German automotive OEMs and Tier 1 module assemblers are reorganizing procurement priorities toward silicon carbide and gallium nitride substrates, with long-term offtake agreements replacing spot market purchases.
- Industrial Equipment:Motor drives and renewable energy inverters consume high-voltage power modules where SiC switching efficiency reduces thermal management requirements.
- Telecommunications:5G base station deployment and satellite communications infrastructure demand GaN RF power amplifiers with high-frequency performance.
- Consumer Electronics:Smartphone and computing device fabrication concentrates silicon wafer demand in advanced logic and memory nodes.
Procurement consolidation favors Automotive Electronics; volume scale favors Consumer Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electronics buyers concentrate procurement decisions in Germany's industrial belt, France's Rhône corridor, and Italy's Po Valley, with sovereign funding instruments redirecting wafer supply chains toward domestic substrate capacity.
Germany
Saxony's Dresden cluster anchors silicon carbide substrate production for 800V automotive platforms, with Infineon Technologies AG operating integrated manufacturing complexes. The EU Chips Act channels sovereign capital toward greenfield 300mm silicon wafer capacity in the region. Bavaria's Munich-Stuttgart corridor hosts power module assemblers consolidating qualified vendor panels from seven to three sources.
France
Grenoble's Isère Valley concentrates epitaxy services and wide-bandgap R&D for traction inverter applications, with STMicroelectronics leveraging regional cleanroom infrastructure. REACH authorization timelines force reformulation of buffered oxide etchants before 2027 sunset dates. Auvergne-Rhône-Alpes hosts equipment makers co-locating pilot production with substrate specialists.
Italy
Catania's Sicilian manufacturing base delivers integrated silicon carbide epitaxy capacity serving automotive power electronics. The EU Green Deal constrains fluorinated gas use in chemical vapor deposition processes across Lombardy and Veneto foundry operations. Emilia-Romagna's packaging corridor remains underdeveloped for advanced fan-out wafer-level substrates.
Netherlands
Eindhoven's Brainport region anchors deposition equipment and process chemistry development for atomic layer deposition precursors. CSRD disclosure rules alter supplier qualification timelines for Dutch chemical suppliers accelerating fluorine-free alternative development. ASM International occupies a central position in regional equipment supply chains.
United Kingdom
IQE PLC represents merchant epitaxy capacity for compound semiconductor applications serving RF and photonics verticals. ECHA substance restrictions limit certain etchants forcing UK-based foundries to requalify cleaning chemistries. South Wales clusters concentrate III-V material processing for specialized optoelectronic manufacturing.
Europe Semiconductor Materials Market Competitive Landscape
Player mix skews toward integrated device manufacturers with captive substrate capacity, merchant wafer suppliers controlling prime silicon supply, and specialized epitaxy service providers. The competitive structure divides across three archetypes: vertically integrated automotive power semiconductor specialists, merchant silicon wafer monopolists, and outsourced compound semiconductor layer growers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with long-term offtake agreements replacing spot market purchases.
Among Germany-based integrated manufacturers, Infineon Technologies AG and Siltronic AG occupy distinct positions within the substrate supply chain, with the former exemplifying captive power electronics capacity and the latter representing merchant silicon wafer supply concentration. STMicroelectronics anchors Franco-Italian integrated production across Catania and Grenoble facilities. IQE PLC sits within the merchant epitaxy specialist tier serving compound semiconductor device makers.
| Leading Market Players |
|---|
| Osram Opto Semiconductors |
| IQE PLC |
| Infineon Technologies AG |
| AMS AG |
| Elmos Semiconductor |
| STMicroelectronics |
| NXP Semiconductors |
| Siltronic AG |
| ASM International |
| Others |
Supply & Pricing Matrix
REACH substance authorization timelines gate both supplier qualification windows and price tier separation across European semiconductor materials procurement. ECHA sunset dates for fluorinated compounds force simultaneous chemistry reformulation and cost recertification, compressing margins for unprepared suppliers while creating premium positioning for qualified alternatives.
Pricing Analysis
Current-generation 200mm silicon carbide wafers command substantial premiums over prior-generation 150mm substrates and next-generation 300mm prototypes still in qualification. Contract-based long-term offtake agreements dominate automotive procurement, with price differentiation driven by epitaxy integration level and ECHA pre-registration status. Cost compression in merchant silicon wafers intensifies as German and Japanese suppliers expand 300mm prime capacity. Foundry buyers exhibit highest price sensitivity for standard-grade silicon, while automotive power module assemblers prioritize supply security over unit cost for SiC substrates.
Supply Chain Analysis
Germany and Japan anchor merchant 300mm silicon wafer supply, while Italy and France concentrate silicon carbide epitaxy and substrate capacity. European supply chains draw from high-purity polysilicon feedstock, fluorinated deposition precursors, and specialized crystal growth equipment. Single-source vulnerability pervades prime wafer procurement for EU sovereign foundry projects. Distribution runs through qualified vendor panels directly to automotive Tier 1 assemblers and integrated device manufacturer fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European semiconductor materials constitute a defensive-moat market where REACH compliance complexity and automotive qualification timelines create formidable switching costs for incumbent suppliers.
For Market Incumbents: Secure captive epitaxy capacity commitments from substrate vendors before automotive buyer consolidation completes. Deepen backward integration into high-purity polysilicon refining to offset merchant supply concentration. The threat of Chinese substrate entrants qualifying for European automotive panels demands preemptive capacity expansion in Saxony and Grenoble corridors. For New Entrants and Emerging Players: Anchor in Poland's underdeveloped advanced packaging substrate corridor where fan-out wafer-level capacity remains scarce. Target merchant GaN-on-Si epitaxy services for converging power and RF device requirements. A qualification-fast go-to-market angle prioritizes ECHA pre-registration completion ahead of competitor chemistry reformulation cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded semiconductor precursor assets awaiting REACH sunset compliance decisions. Long-term viability hinges on exposure to automotive electrification capex cycles rather than consumer silicon demand volatility. Watch SiC crystal growth technician training pipeline expansion as inflection indicator for European supply elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Refining | Siltronic AG and German suppliers reduce Japanese feedstock dependency for 300mm wafer production. |
| Long-term Supply Agreement | Automotive OEMs lock SiC substrate volumes through 2030 as qualified vendor panels consolidate. |
| Green Manufacturing Transition | French chemical suppliers accelerate fluorine-free etchant development ahead of ECHA 2027 deadlines. |
| Joint Venture | Equipment makers co-locate with substrate specialists in Grenoble-Saxony corridor compressing R&D timelines. |
| Capacity Expansion | STMicroelectronics scales integrated SiC epitaxy in Catania serving traction inverter demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across substrate vendors, deposition equipment manufacturers, and automotive power module assemblers. Primary interviews with crystal growth technicians, foundry procurement directors, and ECHA regulatory affairs specialists combined with secondary validation from EU Chips Act funding disclosures, ECHA authorization list updates, and SEC filings from listed wafer suppliers. Bottom-up capacity buildout tracking and top-down automotive semiconductor content analysis provided triangulation across the European supply base.
Across the analysis window, the forecasting framework modeled substrate chemistry, wafer diameter, epitaxy integration level, and automotive versus industrial end-use segmentation. CAGRs derived from capacity expansion announcements, equipment order backlogs, and long-term offtake agreement volumes. Industry-specific inputs included SiC boule yield improvement trajectories and REACH authorization timeline probabilities for fluorinated compounds.
Material uncertainties — ECHA regulatory acceleration, EU Chips Act funding disbursement delays, and SiC crystal growth technician pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions about automotive electrification penetration and sovereign capacity project completion rates. Recalibration cycles align with material shifts in ECHA substance restriction schedules and EU Green Deal implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Quartz Market
Semiconductor Material
Wet Chemicals for Electronics and Semiconductor Application Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Titanium Diboride Market