
 Global Silicon Alloys Market | 2026-2036
Global Silicon Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicon Alloys Market Foresight
Chinese ferroalloy smelter consolidation is broadening supply discipline across the Asia-Pacific rim. Elkem ASA leverages its Norwegian hydropower-backed smelting network to sustain low-carbon ferrosilicon output. Ferroglobe PLC anchors its position through Spanish and French furnace assets with deep integration into European steel mills. Hoshine Silicon Industry Co., Ltd. dominates volume flows from Xinjiang and Yunnan provinces, competing on thermal cost structure.
Silicon alloys comprise iron-silicon, manganese-silicon, and calcium-silicon compounds typically manufactured via submerged arc furnace reduction of quartz with carbon reductants at temperatures exceeding 1,800°C, serving primarily as deoxidizers and alloying agents in liquid steel refinement. Ferrosilicon commands the largest value pool due to its irreplaceable role in carbon and stainless steel desulfurization, while silicon manganese experiences the fastest structural expansion from rising mini-mill and electric arc furnace adoption worldwide. Steel Manufacturing absorbs the majority of alloy tonnage, whereas Chemical Synthesis and Electronics Production segments attract premium pricing for high-purity grades.
The EPA enforces particulate and sulfur dioxide thresholds for US ferroalloy producers under the Clean Air Act, while China's MEE implements dual carbon goals that cap smelter energy intensity and push capacity toward western provinces with hydroelectric access. REACH and RoHS frameworks in Europe restrict heavy metal content in alloy compositions, compelling reformulation investments from exporters seeking CE-marked product qualification. Stakeholders must monitor carbon border adjustment mechanisms and power purchase agreement structures as these will determine which furnace networks retain cost-competitive alloy supply positions.
Market Dynamics
China's dual carbon goals are compressing smelter capacity toward western provinces with hydroelectric access, while the EU's F-Gas Regulation and carbon border adjustment mechanisms simultaneously reshape cost structures for export-oriented furnace networks.
Growth Catalysts
- Electric Arc Furnace Expansion:Mini-mill steel production is accelerating silicon manganese consumption for deoxidation in liquid steel refinement across North American and European metallurgical hubs.
- REACH and RoHS Compliance:European heavy metal restrictions are compelling alloy reformulation investments that create premium qualification tiers for CE-marked ferrosilicon exporters.
- India's PLI Scheme:Domestic steel capacity incentives under the Production Linked Incentive framework are expanding procurement volumes for ferroalloy suppliers in Chhattisgarh State.
Market Restraints
- Quartz Supply Concentration:High-purity silica deposits cluster in limited geographies, exposing furnace operators to input cost volatility from Brazilian and Norwegian mining jurisdictions.
- Energy Intensity Caps:China's MEE enforcement of dual carbon goals is idling thermal-dependent smelter capacity in Hebei Province without immediate western relocation alternatives.
- Silicon Metal Substitution:Direct silicon metal injection in some stainless grades is displacing ferrosilicon in specific desulfurization applications at specialty steel mills.
Strategic Opportunities
- Indonesia Nickel-Steel Integration:Emerging battery-grade stainless complexes in Sulawesi and Halmahera are creating captive ferroalloy demand with localized supply gaps.
- Green Hydrogen Reduction Trials:Norwegian and Icelandic pilot programs are testing biomass and hydrogen reductants to produce near-zero-carbon ferrosilicon for automotive steel certification.
- Carbon Border Adjustment Arbitrage:Early power purchase agreement structures in Quebec and British Columbia are positioning Canadian smelters for EU CBAM-compliant alloy exports.
Industry Challenges
- Submerged Arc Furnace Retrofit Complexity:Legacy furnace rebuilds to meet EPA Clean Air Act particulate thresholds require extended downtime without guaranteed emission performance.
- Metallurgical Engineer Scarcity:Deep expertise in high-temperature reduction chemistry and electrode management is concentrating among retiring workforces in European and North American smelter clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicon Alloys Market |
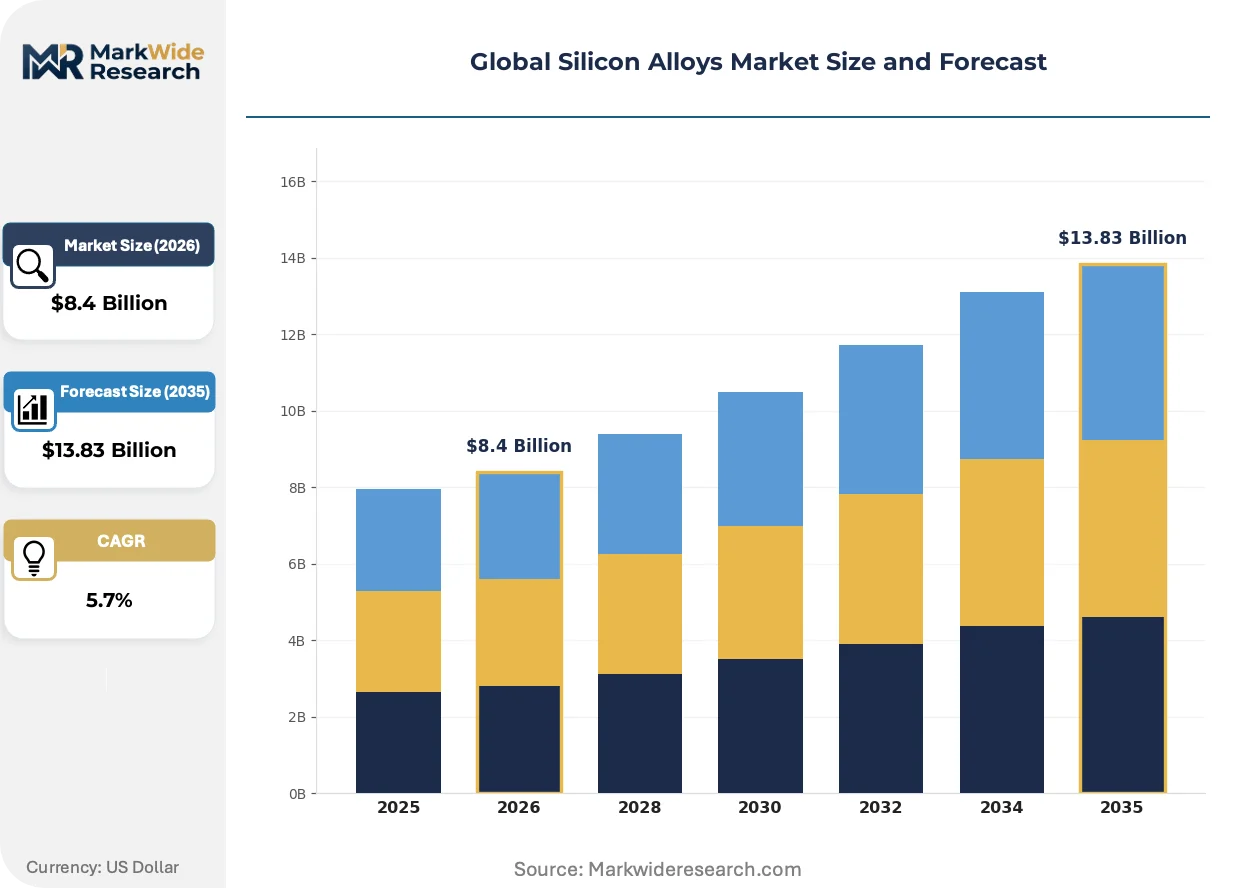
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferrosilicon, Silicon Manganese, Silicon Calcium, Silicon Aluminum, Silicon Zinc Industry Application: Steel Manufacturing, Foundry, Chemical Synthesis, Electronics Production, Construction Materials End User Type: Metal Fabricators, Chemical Manufacturers, Electronic Component Makers, Building Material Producers, Alloy Producers Packaging Type: Bags, Big Bags, Bulk, Drums, Boxes |
| Companies Covered | Elkem ASA, Ferroglobe PLC, ArcelorMittal S.A., OM Holdings Limited, Hoshine Silicon Industry Co., Ltd., RIMA Industrial, Wacker Chemie AG, Dragon Northwest Ferroalloy Co., Ltd., Tata Steel Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicon Alloys Market Shifts & Advancements
Process electrification and regulatory carbon accounting are converging to redefine competitive advantage in ferroalloy production, with furnace operators racing to secure renewable power contracts before border tariffs activate.
Silicon-carbide hybrid reduction technology is absorbing incremental carbon reduction requirements in pilot European installations. Specialty stainless producers in Germany and Sweden are trialing these modified electrode configurations to compress Scope 1 emissions without furnace rebuilds. The technology is absorbing capital allocation that would otherwise flow toward conventional submerged arc capacity expansion.
The EU's F-Gas Regulation is tightening reporting thresholds for sulfur hexafluoride and perfluorocarbon emissions from smelter operations. European ferroalloy importers now face documentary evidence requirements for embedded carbon intensity that Chinese exporters struggle to satisfy. High-purity ferrosilicon grades bound for automotive certification are experiencing the steepest compliance cost escalation.
Steel mill procurement consolidation is compressing supplier panels and extending contract durations. Large integrated producers in Japan and South Korea are migrating from spot-market ferroalloy purchases toward multi-year offtake agreements with carbon-disclosure clauses. This behavioral shift is most visible in contracts linking Hebei Province smelters to coastal Chinese steel complexes with renewable power verification requirements.
Global Silicon Alloys Market Segmentation
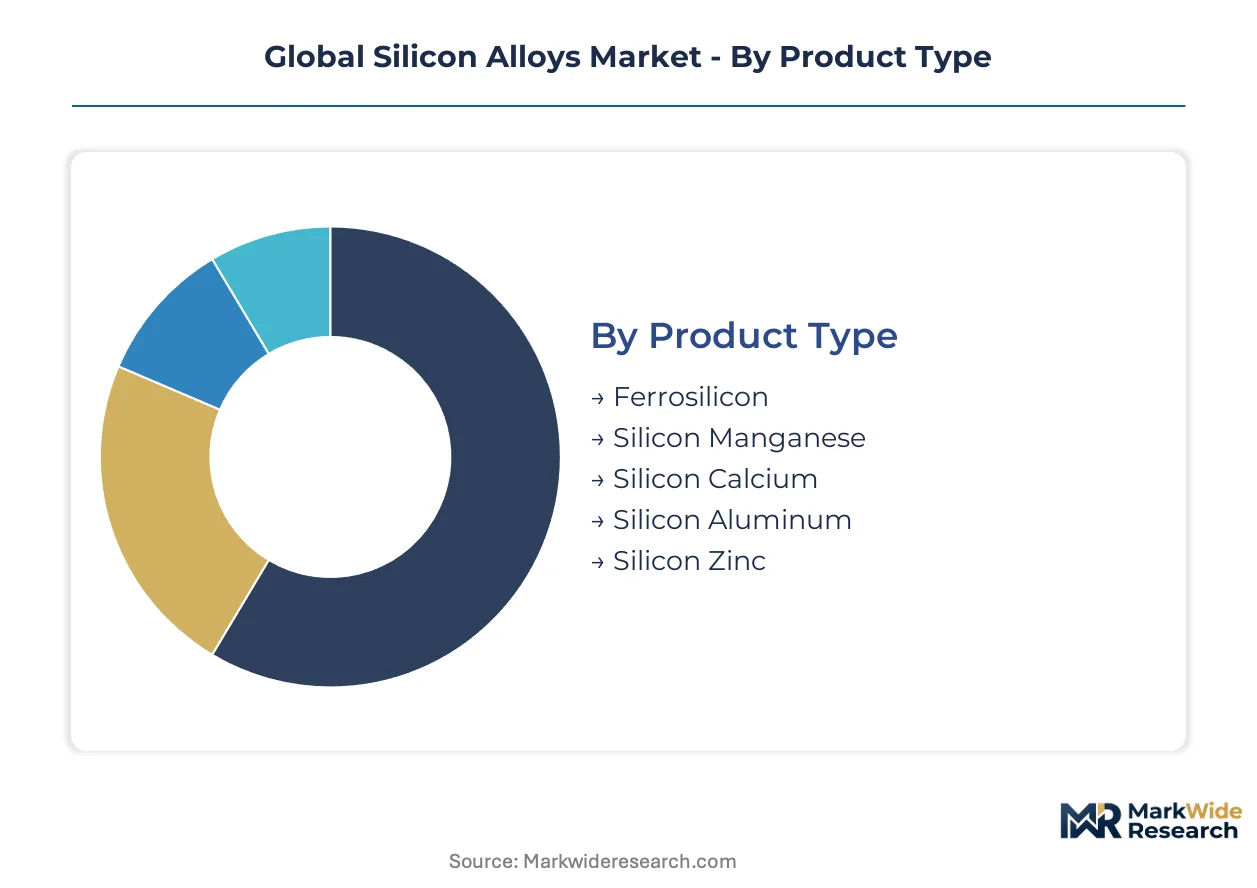
Segmentation in silicon alloys determines pricing power, certification burden, and supply chain configuration. Steel mills impose stricter purity thresholds than foundries, while electronics-grade material demands REACH and RoHS documentation that metallurgical-grade suppliers rarely maintain.
Product Type:
Certification intensity varies sharply across alloy chemistries, with automotive-facing grades requiring ISO/TS 16949 alignment and semiconductor-bound material demanding SEMI traceability.
- Ferrosilicon:Iron-silicon alloy typically containing 15-90% silicon content, manufactured via submerged arc furnace reduction of quartz with carbon reductants at temperatures exceeding 1,800°C. Demand concentrates in Hebei Province steel complexes and Chhattisgarh State mini-mills, where procurement officers prioritize GB standards compliance for Chinese mills and BIS certification for Indian infrastructure projects. EPA Clean Air Act thresholds and China's MEE dual carbon enforcement are compressing thermal-dependent capacity toward western provinces with hydroelectric access.
- Silicon Manganese:Manganese-silicon compound serving as both deoxidizer and alloying agent in liquid steel refinement, particularly critical for electric arc furnace operations. North American and European metallurgical hubs are accelerating consumption as mini-mill steel production expands, with procurement shifting toward multi-year offtake agreements featuring carbon-disclosure clauses.
- Silicon Calcium:Calcium-silicon alloy used for deep desulfurization in specialty steel grades, requiring controlled calcium content to prevent vaporization losses during injection.
- Silicon Aluminum:Aluminum-silicon master alloy serving foundry applications for hypoeutectic and hypereutectic aluminum casting modifications.
- Silicon Zinc:Zinc-silicon alloy primarily applied in galvanizing baths and corrosion-resistant coating formulations for construction materials.
Leading the category by volume: Ferrosilicon. Growing fastest: Silicon Manganese.
Industry Application:
Application segments stratify by margin structure, with electronics and chemical synthesis commanding premium pricing over commodity steel inputs.
- Steel Manufacturing:Primary absorption channel for ferrosilicon and silicon manganese tonnage, serving carbon steel desulfurization and stainless-grade refinement. Japanese and South Korean integrated producers are consolidating supplier panels and extending contract durations with renewable power verification requirements.
- Electronics Production:High-purity silicon alloy demand for semiconductor fabrication and photovoltaic cell manufacturing, requiring SEMI standards alignment and heavy metal content restrictions under REACH and RoHS frameworks.
- Chemical Synthesis:Silane and silicone precursor production utilizing metallurgical-grade silicon as feedstock, concentrated in German and Chinese chemical corridors.
- Foundry:Inoculation and nodularization applications in iron casting, with demand tied to automotive and machinery casting volumes.
- Construction Materials:Alloy additives for structural steel and reinforcing bar production, procurement patterns tracking infrastructure investment cycles.
Steel Manufacturing captures the dominant volume share. Electronics Production sustains the steepest margin expansion trajectory.
End User Type:
Customer sophistication determines specification stringency, with electronic component makers imposing purity documentation that metal fabricators rarely require.
- Metal Fabricators:Steel mills and mini-mill operators purchasing bulk ferrosilicon and silicon manganese for liquid steel refinement, increasingly demanding carbon intensity disclosures under EU CBAM and corporate Scope 3 reduction targets.
- Electronic Component Makers:Semiconductor and solar cell manufacturers sourcing ultra-high-purity grades with SEMI traceability and conflict mineral documentation, concentrated in Taiwan, South Korea, and German manufacturing clusters.
- Chemical Manufacturers:Silicone and silane producers requiring consistent metallurgical-grade silicon feedstock for organic silicon chemistry.
- Building Material Producers:Structural steel and concrete reinforcement suppliers with standardized alloy procurement protocols tied to national construction codes.
- Alloy Producers:Secondary refiners and master alloy manufacturers blending silicon alloys for specialized metallurgical applications.
Metal Fabricators anchor procurement volumes. Electronic Component Makers are climbing the fastest in specification complexity and supplier qualification burden.
Packaging Type:
Packaging selection tracks shipment scale and handling automation, with bulk dominating integrated mill deliveries and bags serving distributed foundry networks.
- Bulk:Unpackaged loose material delivered via pneumatic discharge or conveyor systems to integrated steel mills with dedicated alloy handling infrastructure, minimizing packaging cost and labor.
- Big Bags:Flexible intermediate bulk containers of 500-2,000 kg capacity serving mini-mills and medium-scale foundries with limited storage silo capacity.
- Bags:25-50 kg woven polypropylene sacks for foundry and small-scale metal fabrication operations requiring manual handling and precise batching.
- Drums:Sealed steel containers for moisture-sensitive or high-purity grades requiring contamination protection during transport.
- Boxes:Corrugated or wooden crating for specialty alloy samples, laboratory quantities, and air-freight shipments with dimensional weight constraints.
Bulk shipments lead the category by tonnage. Big Bags are gaining share fastest as mini-mill capacity expands without dedicated silo infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quartz deposits in Minas Gerais, Brazil, and hydroelectric corridors in Quebec, Canada, anchor the geographic dispersion of silicon alloy feedstock and energy inputs.
China
Steel complexes in Hebei Province consume ferrosilicon volumes for carbon steel desulfurization while the MEE enforces dual carbon goals that idle thermal-dependent smelter capacity. Relocation pressures push furnace operators toward Yunnan and Xinjiang provinces with hydropower access. Hoshine Silicon Industry anchors volume flows from western smelter networks.
India
Mini-mill expansion in Chhattisgarh State accelerates silicon manganese procurement for electric arc furnace operations. The PLI scheme incentivizes domestic steel capacity additions that expand ferroalloy demand. Raipur-based metallurgical clusters concentrate procurement activity for infrastructure-grade alloy specifications.
Norway
Hydropower-backed smelting networks sustain low-carbon ferrosilicon output for European automotive steel certification. Elkem ASA leverages Norwegian furnace assets to supply CE-marked product under tightening EU carbon border adjustment mechanisms. Rjukan and Salten industrial corridors concentrate submerged arc capacity.
United States
EPA Clean Air Act thresholds enforce particulate and sulfur dioxide limits on domestic ferroalloy producers. Electric arc furnace expansion in the Great Lakes region accelerates silicon manganese consumption for mini-mill steel production. Detroit-area automotive steel mills impose carbon-disclosure requirements on alloy suppliers.
Spain
Ferroglobe PLC anchors European supply through furnace assets in the Basque Country and Catalonia with deep integration into regional steel mills. REACH and RoHS frameworks compel heavy metal content reformulation for CE-marked export qualification. Bilbao metallurgical complexes serve as distribution nodes for Mediterranean steel producers.
Global Silicon Alloys Market Competitive Landscape
Global majors compete with regional champions across energy sourcing and carbon certification dimensions. The vendor base stratifies between hydropower-backed Nordic operators, thermal-dependent Chinese volume producers, and European integrated steel-alloy hybrids. Three archetypes dominate: renewable-powered low-carbon specialists, scale-driven thermal operators, and captive steel-mill alloy divisions. Competitive moves concentrate on securing power purchase agreements and achieving CE-marked product qualification ahead of carbon border tariff activation.
Within the renewable-powered tier, Elkem ASA exemplifies the Nordic hydropower archetype, while Ferroglobe PLC occupies a position bridging European furnace integration and automotive steel supply chains. Hoshine Silicon Industry Co., Ltd. represents the scale-driven thermal operator model competing on feedstock and energy cost structure from western Chinese smelter networks.
| Leading Market Players |
|---|
| Elkem ASA |
| Ferroglobe PLC |
| ArcelorMittal S.A. |
| OM Holdings Limited |
| Hoshine Silicon Industry Co., Ltd. |
| RIMA Industrial |
| Wacker Chemie AG |
| Dragon Northwest Ferroalloy Co., Ltd. |
| Tata Steel Limited |
| Others |
Supply & Pricing Matrix
Green hydrogen reduction trials in Norwegian and Icelandic pilot programs are compressing production economics for near-zero-carbon ferrosilicon while simultaneously concentrating supply among hydropower-backed furnace networks with validated carbon accounting. This dual shift rewards early movers with renewable power purchase agreements and penalizes thermal-dependent operators facing EU carbon border adjustment exposure.
Pricing Analysis
Carbon-certification bundling now separates quoted ferrosilicon prices, with CE-marked product commanding premiums over uncertified tonnage from Hebei Province smelters. Price differentiation rests on renewable power verification and heavy metal compliance under REACH frameworks, with automotive steel mills showing lowest price sensitivity due to Scope 3 reduction mandates. Cost compression in standard-grade ferrosilicon is intensifying as Chinese smelter consolidation idles thermal capacity without immediate western relocation alternatives.
Supply Chain Analysis
Metallurgical engineer scarcity in European and North American smelter clusters is constraining furnace rebuild timelines and electrode management expertise just as EPA Clean Air Act retrofit requirements demand extended downtime. Supply concentrates in China, Norway, and India, with quartz feedstock drawing from Brazilian and Norwegian mining jurisdictions. Single-source vulnerability runs through high-purity silica deposit concentration. Distribution runs through bulk pneumatic discharge to integrated steel mills and big-bag shipments to mini-mills without dedicated silo infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around carbon-certified supply positions as EU border mechanisms and corporate Scope 3 targets force thermal-dependent operators toward acquisition or exit.
For Market Incumbents: To counter silicon metal substitution in specialty stainless desulfurization, deepen captive quartz sourcing through backward integration into Norwegian or Brazilian mining jurisdictions while accelerating SEMI-traceable high-purity grade qualification for electronics-bound material. For New Entrants and Emerging Players: Enter via Indonesia nickel-steel integration corridors in Sulawesi and Halmahera, where localized ferroalloy supply gaps accompany battery-grade stainless complex development without established incumbent presence. For Investors and Strategic Acquirers: Exit pathways concentrate in hydropower-backed Nordic specialists with validated CE-marked product and long-term automotive steel offtake agreements. Watch for EU CBAM documentary evidence requirements tightening as the inflection signal separating compliant from stranded furnace assets.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement | Secures low-carbon ferrosilicon output eligibility under EU CBAM verification protocols for Norwegian operators. |
| Backward Integration into Quartz Mining | Captures Brazilian high-purity silica deposits to insulate furnace operators from input cost volatility. |
| SEMI Traceability Certification | Unlocks electronics-grade silicon alloy premiums from Taiwan and South Korean semiconductor manufacturers. |
| Submerged Arc Furnace Electrification | Compresses Scope 1 emissions for German specialty stainless producers without full furnace rebuilds. |
| Multi-year Offtake Agreement with Carbon Clauses | Locks in Japanese and South Korean steel mill procurement consolidation toward qualified supplier panels. |
Research Methodology
Multi-period observation of smelter capacity utilization, power purchase agreement structures, and carbon intensity disclosures anchored the trend analysis, supplemented by interviews with submerged arc furnace operators, steel mill procurement officers, metallurgical engineers, and quartz mining executives. Secondary validation drew from customs trade data, SEC filings of listed ferroalloy producers, EPA enforcement records, and MEE dual carbon policy documents. Bottom-up segment sizing triangulated against top-down steel production forecasts across the analysis window.
Segment-weighting applied product type, industry application, and end user sophistication dimensions across the modeling period, with ferrosilicon and silicon manganese volumes calibrated to electric arc furnace adoption curves and mini-mill capacity expansion. CAGRs derived from regression against historical procurement patterns and regulatory enforcement trajectories. Forecast inputs incorporated renewable power contract availability and carbon border adjustment mechanism phase-in assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE enforcement acceleration or quartz supply disruption from Brazilian mining jurisdictions. Material deviation in EU CBAM documentary evidence requirements or automotive steel Scope 3 target revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Fullerene Market
Semiconductor Material
Global Thermal Paste Market
Semiconductor Material
Polysilicon Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market