
 Display Driver IC Market | 2026-2036
Display Driver IC Market Size, Share, and Industry Trends Forecast 2026-2036
Display Driver IC Market Intelligence
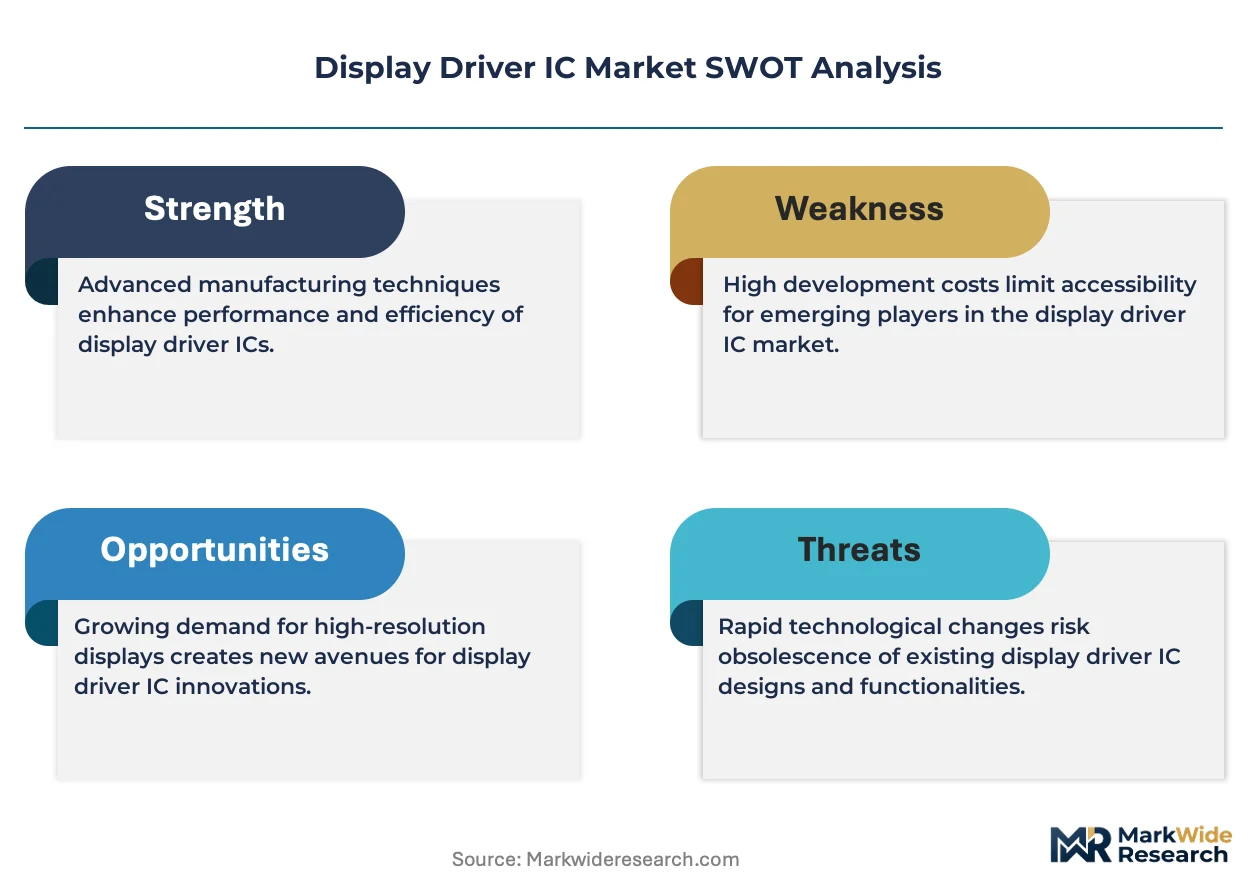
The gap between premium OLED driver ICs and commodity TFT LCD variants is expanding as panel makers demand higher refresh rates and integrated touch functionality for flagship devices. Novatek Microelectronics leverages its R&D intensity to dominate smartphone DDIC supply in Taiwan. Samsung Electronics anchors the premium tier through captive demand from its display division and proprietary AMOLED processes. Himax Technologies specializes in automotive-grade driver ICs with extended temperature tolerances, competing against MediaTek's scale advantages in mobile applications.
A display driver IC is a semiconductor that translates digital video signals into analog voltages to control individual pixels on flat-panel displays, typically fabricated at 40nm to 28nm nodes with integrated gamma correction and source/gate driving functions. TFT LCD driver ICs still occupy the largest volume share across televisions and digital signage, though margin pools are thinning. OLED driver ICs are recording the fastest value growth as integrated touch and flexible display support technologies penetrate wearable devices and foldable smartphones. High refresh rate specifications above 120Hz are becoming a standard differentiator in gaming consoles and premium handsets, reshaping R&D allocation across the supplier base.
FCC electromagnetic interference rules in the US, REACH substance restrictions in Europe, and China's GB standards for display energy efficiency collectively tighten compliance burdens on DDIC packaging and materials. South Korea's MFDS and Japan's METI coordinate semiconductor export controls that affect equipment access for advanced node migration. Stakeholders must monitor how automotive safety regulators in Germany and Japan certify driver ICs for head-up displays and instrument clusters, as qualification timelines will determine supplier lock-in for next-generation vehicle platforms.
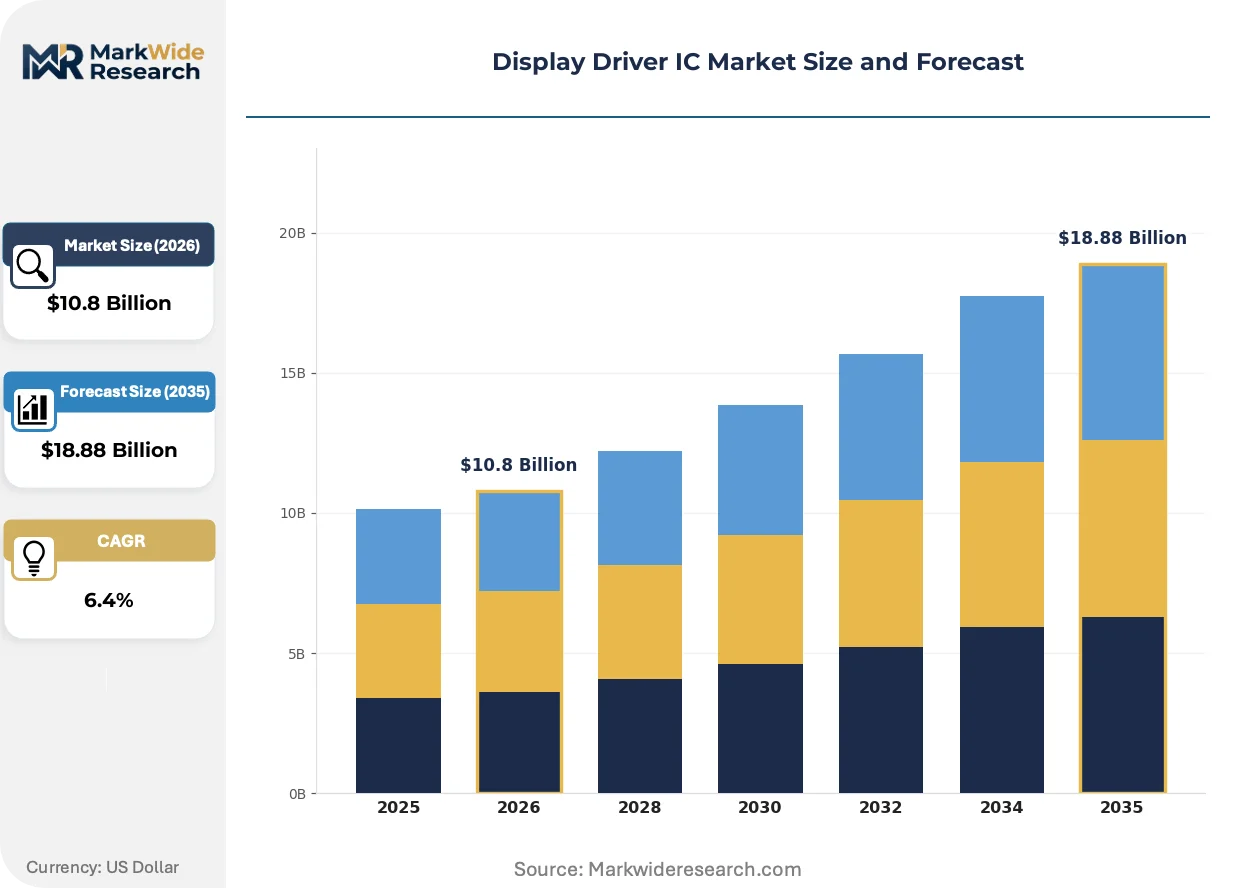
Market Dynamics
Panel makers are consolidating procurement around integrated touch-and-display driver solutions, compressing supplier margins while elevating technical qualification barriers for second-tier vendors.
Growth Catalysts
- Automotive cockpit digitization:Electric vehicle OEMs specify curved, high-resolution instrument clusters and head-up displays that require automotive-grade DDICs with extended temperature tolerances.
- REACH substance restrictions:European material compliance mandates are accelerating the phase-out of legacy packaging compounds, creating replacement demand for compliant driver IC substrates.
- Foldable form factors:Flexible OLED panels in smartphones and wearables require specialized gate-driver architectures that support dynamic bending radii without pixel degradation.
Market Restraints
- Advanced node equipment access:South Korea's MFDS and Japan's METI coordinate semiconductor export controls that restrict lithography tool availability for 28nm migration.
- Foundry concentration:Taiwan-based pure-play foundries handle the majority of DDIC wafer starts, creating geographic single-point vulnerability for capacity allocation.
- Silicon wafer input volatility:Polished silicon substrate pricing fluctuations directly compress fabrication margins for commodity TFT LCD driver ICs.
Strategic Opportunities
- India display manufacturing:The country's PLI scheme for semiconductor and display ecosystems offers capital subsidies for domestic DDIC packaging and testing facilities.
- MicroLED pre-positioning:Early architectural alignment with emerging microLED panel architectures allows driver IC suppliers to capture premium positioning before mass commercialization.
- China dual carbon goals:MIIT energy efficiency standards for display modules create certified-product preference windows for low-power driver IC designs.
Industry Challenges
- Automotive qualification timelines:German KBA and Japan's automotive safety regulators mandate extended reliability testing for head-up display driver ICs, stretching design-to-revenue cycles.
- Gamma calibration IP complexity:Proprietary voltage reference architectures from incumbent suppliers create licensing friction for new entrants targeting high-refresh-rate specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Driver IC Market |
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TFT LCD Driver IC, OLED Driver IC, AMOLED Driver IC, E-Paper Driver IC, MicroLED Driver IC Technology: Low Power, High Resolution, Integrated Touch, High Refresh Rate, Flexible Display Support Application: Smartphones, Wearable Devices, Televisions, Digital Signage, Automotive Displays, Gaming Consoles End User: Smart Device Manufacturers, Consumer Electronics OEMs, Public Information Systems, Vehicle Assembly Companies, Entertainment Hardware Producers |
| Companies Covered | Novatek Microelectronics Corporation, Magnachip Semiconductor, Ltd., FocalTech Systems Co., Ltd., Macroblock, Inc., Raydium Semiconductor Corporation, Himax Technologies, Inc., Samsung Electronics Co., Ltd., MediaTek Inc., LX Semicon Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Driver IC Market Strategic Shifts & Innovations
Silicon architecture is converging with system-level integration pressures, as panel makers demand fewer discrete components and tighter thermal envelopes across mobile and automotive applications.
LTPO backplane technology is rewriting power management assumptions in flagship smartphones. This variable-refresh-rate oxide semiconductor enables dynamic frequency scaling from 1Hz to 120Hz. Samsung Display and LG Display have qualified LTPO for premium handset lines. The technology is compressing demand for standalone timing controllers and consolidating functionality into single-chip driver solutions.
China's GB standards for display energy efficiency are tightening standby power thresholds and luminous efficacy requirements. MIIT certification now mandates third-party testing for driver IC power consumption at multiple gray levels. Premium television and monitor segments are responding with integrated power management blocks that reduce external component counts.
Fleet procurement by panel makers is consolidating around qualified vendor lists with multi-year volume commitments. Tier-one display manufacturers in South Korea and Taiwan now negotiate direct wafer allocation agreements with foundries, bypassing traditional distribution channels. This concentration is most visible in OLED driver IC supply, where Samsung Electronics and LX Semicon secure captive capacity through equity-linked partnerships.
Display Driver IC Market Segmentation
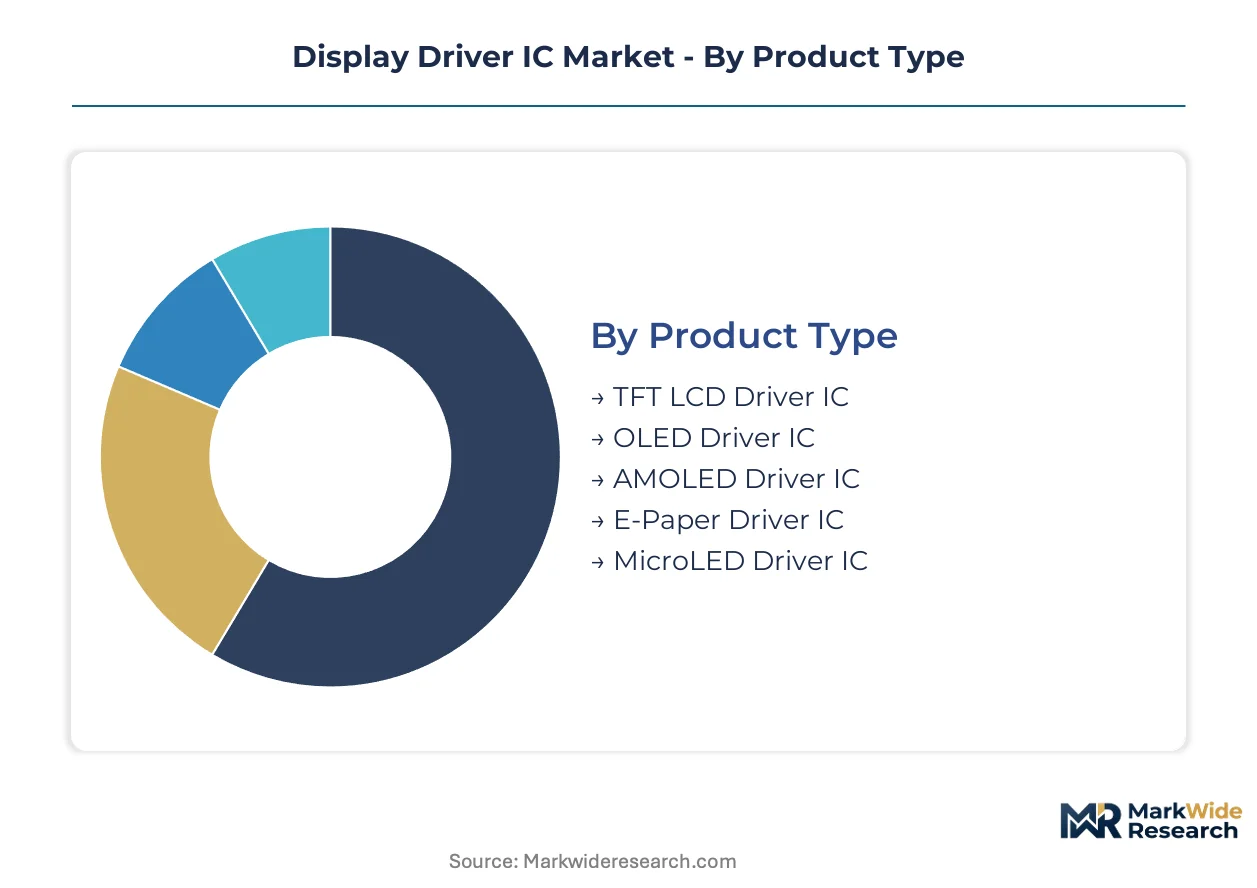
Display driver IC segmentation reveals how capital allocation, process node requirements, and qualification barriers concentrate margin pools across distinct technology tiers. Panel makers now specify integrated solutions that collapse multiple functions into single-chip architectures, reshaping supplier R&D priorities and foundry loading patterns.
Product Type:
Capital intensity varies sharply across product categories, with advanced node OLED fabrication requiring substantially higher upfront equipment investment than mature-node LCD alternatives.
- TFT LCD Driver IC:Mature-node semiconductors fabricated at 40nm and above, employing established polysilicon backplane interfaces. Volume concentrates in Chinese and Vietnamese television assembly plants where panel makers prioritize cost-per-unit over performance differentiation.
- OLED Driver IC:Premium 28nm-40nm devices with integrated gamma correction and source-gate driving functions. South Korean display clusters around Samsung and LX Semicon command the dominant share of wafer starts for smartphone and wearable applications.
- AMOLED Driver IC:Active-matrix variants with proprietary voltage reference architectures supporting high refresh rates. Taiwan-based foundries handle the majority of fabrication for flagship handset lines.
- E-Paper Driver IC:Ultra-low-power designs optimized for static image retention in e-readers and shelf-label systems.
- MicroLED Driver IC:Emerging architectural category requiring sub-micron current control for microscopic emitter arrays.
Most installed capacity flows through TFT LCD Driver IC. Expansion is steepest in OLED Driver IC.
Technology:
Cost tier stratification separates premium integrated solutions from baseline power-optimized variants, with qualification barriers rising fastest in automotive and foldable applications.
- Integrated Touch:TDDI architectures consolidating display driving and capacitive sensing into single-chip solutions. Korean panel makers specify these for mid-tier smartphones to reduce bill-of-materials complexity and assembly yield losses.
- High Refresh Rate:120Hz and above timing controllers with enhanced frame buffering. Gaming console OEMs in Japan and the United States now mandate these specifications for competitive multiplayer titles.
- Low Power:Aggressive voltage scaling and sleep-state optimization for battery-constrained wearables.
- High Resolution:Fine-pitch source drivers supporting 4K and 8K pixel densities in premium television segments.
- Flexible Display Support:Dynamic bending-radius compensation for foldable smartphone gate-driver architectures.
Integrated Touch commands the largest revenue share. Flexible Display Support is climbing the fastest.
Application:
Customer type differentiation separates automotive qualification-heavy procurement from consumer electronics volume purchasing, with contract structures and margin profiles diverging accordingly.
- Smartphones:The dominant volume segment where LTPO backplane integration is compressing demand for standalone timing controllers. Chinese OEMs now specify single-chip driver solutions for flagship lines.
- Automotive Displays:Curved instrument clusters and head-up displays requiring extended temperature tolerances from -40°C to 85°C. German KBA and Japan's automotive safety regulators mandate extended reliability testing that stretches design-to-revenue cycles.
- Wearable Devices:Compact form factors with aggressive power envelopes for smartwatches and fitness bands.
- Televisions:Large-area panels where commodity pricing pressures dominate procurement negotiations.
- Digital Signage:Commercial displays with 24/7 operational requirements and remote management capabilities.
- Gaming Consoles:Variable refresh rate support for tear-free rendering in premium entertainment hardware.
Smartphones absorb the greatest wafer volume. Automotive Displays show the steepest margin expansion trajectory.
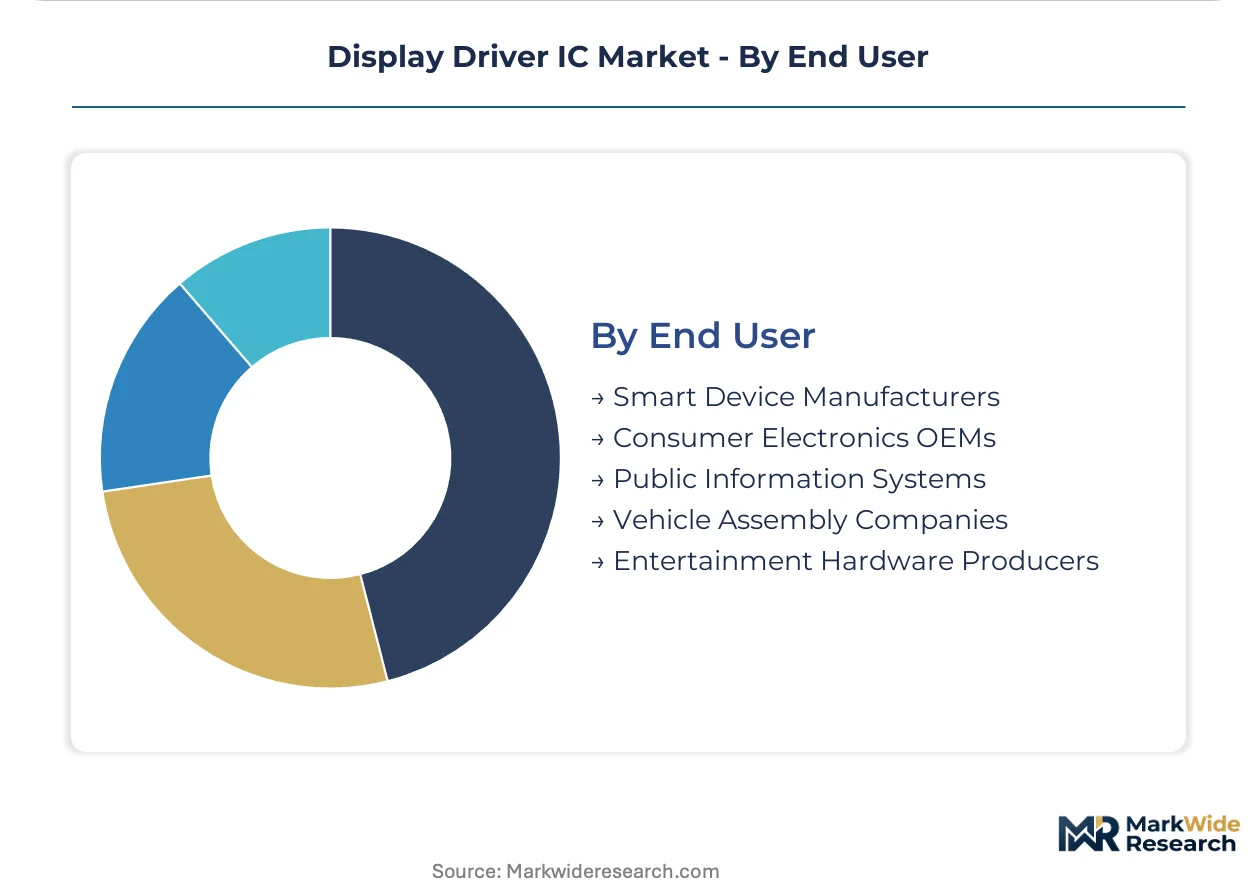
End User:
Supply concentration patterns reveal how captive semiconductor divisions and independent merchant suppliers partition the value chain across device categories.
- Smart Device Manufacturers:Vertically integrated procurement where Apple and Samsung secure dedicated foundry capacity through equity-linked partnerships.
- Vehicle Assembly Companies:Tier-one automotive suppliers in Germany and Japan specify driver ICs through multi-year qualification programs with stringent traceability requirements.
- Consumer Electronics OEMs:Price-sensitive television and monitor assemblers in China and Mexico.
- Public Information Systems:Government and transit authority procurement with localized content requirements.
- Entertainment Hardware Producers:Gaming peripheral and console manufacturers with performance-centric specifications.
Smart Device Manufacturers lock in the most captive capacity. Vehicle Assembly Companies are driving the fastest qualification timeline compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in semiconductor design and display manufacturing concentrate in East Asian metropolitan clusters, where foundry infrastructure and panel assembly ecosystems co-locate. South Korea, Taiwan, and China maintain the deepest concentrations of DDIC design engineers and wafer fabrication specialists. Regulatory frameworks in Germany and Japan impose automotive-grade qualification standards that filter supplier access to vehicle cockpit markets.
South Korea
Samsung Display and LX Semicon generate captive demand for OLED driver ICs across smartphone and wearable lines. The country's MFDS coordinates semiconductor export controls with Japan's METI, restricting lithography tool access for advanced node migration. Seoul's Pangyo Techno Valley hosts the densest cluster of fabless DDIC design houses serving global panel makers.
Taiwan
Pure-play foundries handle the majority of DDIC wafer starts for smartphone and tablet applications. Novatek Microelectronics leverages local R&D infrastructure to dominate mobile DDIC supply through integrated touch-and-display solutions. Hsinchu Science Park anchors the island's semiconductor manufacturing ecosystem with captive capacity allocation agreements.
China
MIIT display energy efficiency standards tighten standby power thresholds and luminous efficacy requirements for domestic television and monitor production. The country's dual carbon goals accelerate phase-out of legacy packaging compounds in favor of compliant driver IC substrates. Yangtze River Delta panel assemblers in Suzhou and Hefei drive volume demand for commodity TFT LCD driver ICs.
Japan
Automotive safety regulators mandate extended reliability testing for head-up display driver ICs, stretching design-to-revenue cycles for cockpit digitization. METI export controls on semiconductor equipment affect regional foundry access for 28nm node migration. Nagoya's automotive electronics corridor concentrates tier-one supplier procurement for curved instrument clusters.
Germany
The KBA imposes stringent traceability requirements on driver ICs for electric vehicle head-up displays and instrument clusters. REACH substance restrictions accelerate replacement demand for compliant packaging materials in premium automotive applications. Munich's automotive electronics cluster hosts qualification programs that determine supplier lock-in for next-generation vehicle platforms.
Display Driver IC Market Key Industry Players
Top-tier vendors anchor the premium OLED segment, while second-tier suppliers compete on cost in mature-node TFT LCD markets. The vendor base stratifies around captive semiconductor divisions, independent merchant suppliers, and specialized automotive-grade fabricators. Three archetypes dominate: integrated device manufacturers with display division demand, fabless design houses with foundry partnerships, and automotive specialists with extended temperature qualification. Competitive moves concentrate on wafer allocation agreements and multi-year procurement contracts with tier-one panel makers.
Among Taiwan-based fabless design houses, Novatek Microelectronics Corporation and Raydium Semiconductor Corporation exemplify the integrated touch-and-display driver archetype. Samsung Electronics Co., Ltd. occupies a position representing captive demand integration through its display division. Himax Technologies, Inc. anchors the automotive-grade specialization tier with extended temperature tolerance offerings.
| Leading Market Players |
|---|
| Novatek Microelectronics Corporation |
| Magnachip Semiconductor, Ltd. |
| FocalTech Systems Co., Ltd. |
| Macroblock, Inc. |
| Raydium Semiconductor Corporation |
| Himax Technologies, Inc. |
| Samsung Electronics Co., Ltd. |
| MediaTek Inc. |
| LX Semicon Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between automotive-qualified and consumer-grade driver ICs manifests in both pricing power and supply chain configuration. Automotive-grade devices command substantial premiums through extended temperature tolerance validation, while commodity TFT LCD variants compete on wafer cost in Chinese panel assembly ecosystems. This bifurcation concentrates margin pools in Seoul and Taipei, where foundry allocation agreements lock in captive capacity for premium OLED lines.
Pricing Analysis
Bundled single-chip solutions with integrated touch-and-display functionality carry substantial premiums over unbundled discrete component architectures. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified devices with KBA traceability from mid-tier smartphone TDDI variants and commodity television driver ICs. Cost compression in mature-node TFT LCD segments is intensifying because Chinese panel makers consolidate procurement around qualified vendor lists with multi-year volume commitments. Consumer electronics OEMs in Mexico and Vietnam exhibit the highest price sensitivity, while German vehicle assembly companies accept extended qualification timelines for certified cockpit components.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, with additional dependencies on South Korean and Taiwanese wafer fabrication inputs. Silicon wafer substrates draw from Japanese and German polysilicon refiners, while advanced packaging materials source from South Korean laminate suppliers. Single-source vulnerability concentrates in Taiwan-based pure-play foundries handling the majority of DDIC wafer starts for smartphone applications. Distribution runs through direct wafer allocation agreements between tier-one panel makers and foundries, bypassing traditional semiconductor distribution channels in Seoul and Hsinchu.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Display Driver IC Market functions as a stable compounder, with automotive cockpit digitization providing durable demand expansion across multiple vehicle platform cycles.
For Market Incumbents: To counter foundry capacity constraints from South Korea's MFDS and Japan's METI export controls, secure equity-linked partnerships with Taiwan-based pure-play foundries for 28nm node allocation. Invest in automotive-grade qualification programs with German KBA and Japan's automotive safety regulators to extend supplier lock-in for curved instrument cluster platforms.
For New Entrants and Emerging Players: Enter via India's PLI scheme for semiconductor and display ecosystems, where capital subsidies support domestic DDIC packaging and testing facilities. Target automotive-grade driver ICs for head-up displays as the most penetrable segment, given extended qualification timelines that deter rapid incumbent response. Pursue qualification partnerships with tier-one automotive suppliers in Nagoya's electronics corridor as the primary go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with automotive-specialist fabless design houses holding extended temperature tolerance certifications and active KBA qualification programs. Long-term viability centers on suppliers positioned for next-generation vehicle platform lock-in across the 5-10 year OEM design cycle. Monitor METI and MFDS equipment export control announcements as the critical signal for foundry access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Allocation Agreement | Secures 28nm wafer starts from Taiwan pure-play foundries for OLED driver IC production. |
| Automotive Qualification Program | Accelerates KBA certification for head-up display driver ICs in German electric vehicle platforms. |
| India PLI Facility Establishment | Captures capital subsidies for domestic DDIC packaging and testing in the country's emerging display cluster. |
| MicroLED Architecture Pre-positioning | Aligns R&D with emerging panel architectures before mass commercialization reshapes supplier rankings. |
| LTPO Backplane Integration | Consolidates timing controller functionality into single-chip solutions for Samsung Display and LG Display flagship lines. |
Research Approach
Coverage spans South Korea, Taiwan, China, Japan, and Germany, with primary inputs from each region's display manufacturing clusters. The approach combines primary interviews with fabless DDIC design executives, foundry capacity planners, tier-one automotive supplier procurement leads, and panel maker technology directors with secondary validation. Secondary sources include SEC 10-K semiconductor filings, MIIT display energy efficiency certification databases, KBA automotive component traceability records, and customs data from Yangtze River Delta and Hsinchu Science Park trade flows. Bottom-up wafer start estimates and top-down panel shipment projections undergo triangulation for convergence.
Segmentation granularity extends to product type, technology tier, application, and end-user archetype across the projection horizon. The analytical framework models OLED driver IC value expansion, TFT LCD volume concentration, and automotive-grade margin trajectory separately. CAGRs derive from foundry loading patterns, panel maker procurement consolidation trends, and regulatory timeline impacts. Industry-specific inputs include LTPO backplane adoption rates, foldable smartphone form factor penetration, and automotive head-up display qualification velocity.
The model holds under stable foundry equipment access conditions; deviation in METI or MFDS export control enforcement would shift capacity allocation assumptions. Forecasts incorporate assumptions regarding MIIT energy efficiency standard progression and REACH substance restriction phase-out timelines. A small set of triggers—automotive safety regulator certification delays, polysilicon substrate price volatility, and Taiwan foundry utilization spikes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Integrated CMOS Tri-Gate Transistor Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Global Application Specific Consumer Analog Integrated Circuit Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Standard Logic IC Market