
 Electrochemical Sensor Market | 2026-2036
Electrochemical Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Electrochemical Sensor Market Analysis
The gap between medical-grade precision electrochemical sensors and commodity industrial detectors is realigning competitive investment priorities. Alphasense leverages its R&D intensity to dominate high-accuracy gas sensing for environmental networks. Thermo Fisher Scientific anchors its position through backward integration into specialized electrode materials. MSA Safety competes aggressively in portable safety instrumentation for hazardous workplace environments.
Electrochemical sensors convert chemical information into measurable electrical signals through redox reactions at electrode-electrolyte interfaces, typically operating at detection limits in parts-per-million or parts-per-billion depending on target analyte and electrode configuration. Gas sensors lead volume shipments due to pervasive industrial safety mandates, while pH sensors command stronger margin pools in biopharmaceutical process control where calibration stability determines batch compliance. Amperometric technology occupies the largest installed base, though impedimetric methods are gaining ground in miniaturized wearable diagnostic platforms.
EPA mandates under the Clean Air Act and OSHA permissible exposure limits shape industrial gas sensor replacement cycles in the United States, while REACH and the EU F-Gas Regulation restrict certain electrolyte formulations and drive material substitution programs across European manufacturing. FDA oversight of clinical chemistry analyzers imposes stringent validation protocols on medical electrochemical sensor suppliers seeking US market access. Stakeholders must monitor evolving battery sensor specifications as electric vehicle thermal management systems integrate more sophisticated cell-level monitoring architectures.
Market Dynamics
The EU F-Gas Regulation is forcing electrolyte reformulation across European manufacturing while continuous patient monitoring programs in hospitals drive medical-grade sensor procurement at precision thresholds unmatched by industrial detectors.
Growth Catalysts
- EU Green Deal emissions mandates:Industrial operators in Germany must upgrade gas sensor fleets to meet tightening monitoring requirements, creating replacement demand for high-accuracy electrochemical detectors.
- Wearable diagnostic platforms:Impedimetric methods are displacing traditional amperometric architectures in miniaturized continuous glucose monitors and lactate sensors for athletic performance tracking.
- Automotive battery thermal management:Electric vehicle manufacturers are integrating cell-level electrochemical monitoring architectures to prevent thermal runaway and extend pack longevity.
Market Restraints
- Precious metal electrode costs:Platinum and gold price volatility directly compresses margins for medical-grade pH and dissolved oxygen sensors where alternative materials fail validation protocols.
- Electrolyte supply concentration:Specialized ionic liquid formulations for high-temperature gas sensing depend on German and Japanese chemical suppliers with limited qualified alternatives.
- REACH substance restrictions:The European Chemicals Agency's evolving candidate list forces material substitution programs that extend R&D timelines and recertification costs.
Strategic Opportunities
- Point-of-care clinic expansion:Rural and suburban healthcare networks in the United States are deploying portable electrochemical analyzers for rapid cardiac marker and electrolyte panels outside centralized lab infrastructure.
- Biopharmaceutical process analytics:Single-use bioreactor systems require disposable pH and dissolved oxygen sensors with calibration stability that determines batch release compliance.
- Industrial IoT convergence:Wireless electrochemical sensor nodes combined with edge computing architectures enable predictive maintenance for chemical processing equipment.
Industry Challenges
- Electrochemist talent scarcity:The specialized expertise required for electrode surface modification and electrolyte optimization concentrates in academic and national laboratory pipelines with limited industry crossover.
- FDA 510(k) validation timelines:Clinical chemistry analyzer submissions face extended review cycles when novel electrode materials lack predicate device equivalence.
- Legacy system integration friction:Plant operators struggle to retrofit digital electrochemical transmitters into analog-distributed control systems without full automation overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrochemical Sensor Market |
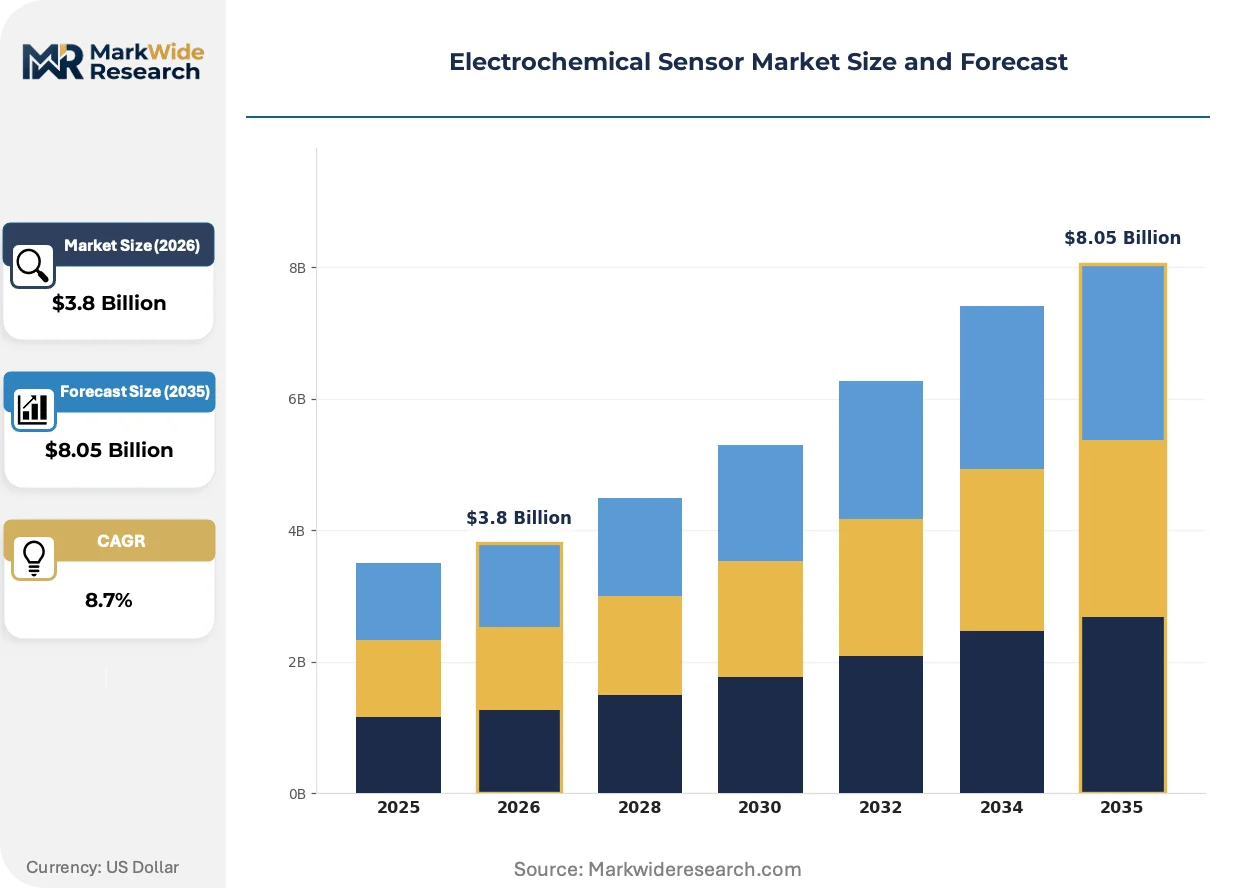
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Sensors, pH Sensors, Gas Sensors, Ion Sensors Technology: Amperometric, Potentiometric, Conductometric, Impedimetric Application: Medical Diagnostics, Environmental Monitoring, Industrial Process Control, Automotive Testing End User: Healthcare, Food & Beverage, Chemical Manufacturing, Research Institutions |
| Companies Covered | Conductive Technologies Inc., Alphasense, Thermo Fisher Scientific, Inc., Siemens Healthineers, Honeywell International Inc., MSA Safety, SGX Sensortech Ltd, Dragerwerk AG, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrochemical Sensor Market Emerging Trajectories
Solid-state electrolyte architectures and printed electrode manufacturing are compressing form factors while regulatory pressure on fluorinated gases accelerates material substitution programs across sensor supply chains.
Printed graphene electrodes are rewriting the cost-performance tradeoff for disposable medical sensors. Diagnostic OEMs in South Korea and Taiwan are adopting roll-to-roll manufacturing for continuous glucose monitoring strips at unit economics previously reserved for commodity industrial detectors. This manufacturing shift is compressing price floors across the medical-grade segment and enabling subscription-based sensor replenishment models.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing electrolyte reformulation in European environmental monitoring networks. Industrial gas sensor manufacturers must validate alternative ionic conductors that maintain selectivity for sulfur dioxide and nitrogen oxides without restricted fluorinated polymers. German automotive testing facilities face the most acute compliance pressure given their simultaneous exposure to F-Gas Regulation and EU Green Deal emissions verification mandates.
Hospital procurement departments are consolidating electrochemical sensor suppliers through multi-year preferred vendor agreements that bundle analyzer hardware, consumables, and calibration services. This purchasing concentration displaces fragmented spot-buying of individual electrode cartridges and pH buffers. The shift is most visible in United States health systems pursuing operational standardization across acquired regional hospital networks.
Electrochemical Sensor Market Segmentation
Electrochemical sensor architectures fragment sharply between standalone instrumentation requiring field calibration and embedded systems integrated into process control loops. Understanding these integration boundaries determines procurement patterns across medical, automotive, and industrial verticals.
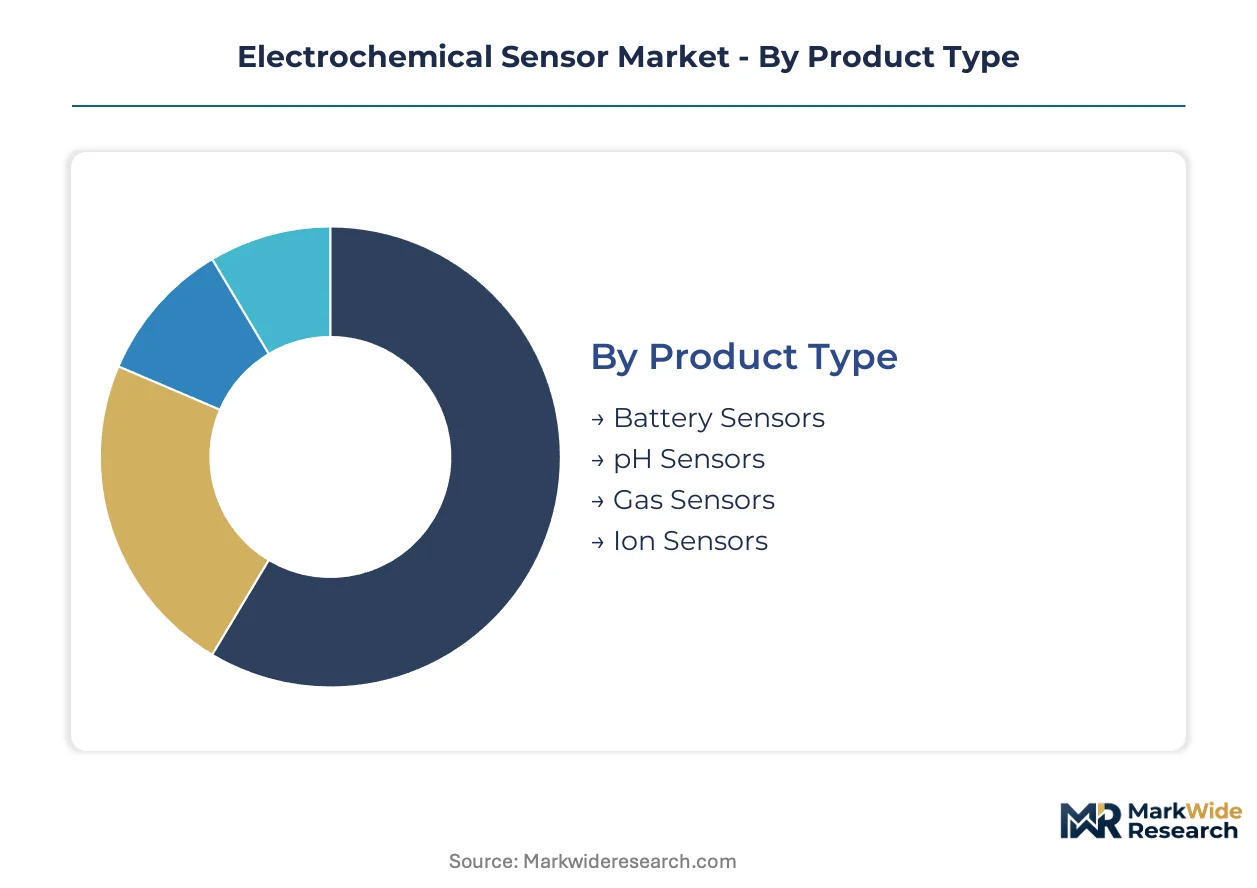
Product Type:
Standalone battery management systems demand discrete sensor modules with automotive-grade reliability, while embedded pH and gas sensors merge into continuous process streams with minimal maintenance windows.
- Gas Sensors:These detectors rely on redox reactions at catalytic electrodes to quantify toxic or combustible atmospheres. German automotive testing facilities and chemical manufacturing clusters in the Ruhr Valley drive procurement for sulfur dioxide and nitrogen oxide detection under EU F-Gas Regulation compliance deadlines.
- pH Sensors:Glass membrane or ISFET architectures measure hydrogen ion activity through potentiometric potential differences. Biopharmaceutical batch release compliance in United States health systems demands calibration stability that single-use disposable formats now address.
- Battery Sensors:Cell-level voltage and temperature monitoring architectures prevent thermal runaway in electric vehicle packs.
- Ion Sensors:Selective electrode membranes detect specific cations or anions in clinical chemistry and water quality applications.
Gas sensors lead volumes today; pH sensors are gaining share fastest in biopharmaceutical process control.
Technology:
Cost tier separation distinguishes mature amperometric platforms from emerging impedimetric architectures competing on miniaturization economics.
- Amperometric:Current measurement at fixed potential dominates dissolved oxygen and glucose detection with established calibration protocols. The installed base concentrates in hospital clinical chemistry analyzers and industrial safety instrumentation where FDA and OSHA validation frameworks favor proven electrode configurations.
- Impedimetric:Alternating current techniques measure complex impedance changes for label-free biosensing. South Korean and Taiwanese diagnostic OEMs deploy roll-to-roll manufacturing for continuous glucose monitoring strips at unit economics challenging traditional amperometric production.
- Potentiometric:Zero-current potential measurement underpins pH and ion-selective electrode operation.
- Conductometric:Solution conductivity detection serves water quality and chemical concentration monitoring.
Amperometric platforms retain the largest installed base; impedimetric methods are climbing the fastest in wearable diagnostic applications.
Application:
Customer type segmentation separates capital-intensive hospital infrastructure from distributed point-of-care networks with divergent procurement cycles.
- Medical Diagnostics:Clinical chemistry analyzers and portable cardiac marker detectors require electrode precision validated under FDA 510(k) protocols. Rural and suburban United States healthcare networks deploying rapid electrolyte panels outside centralized labs represent the steepest expansion trajectory.
- Environmental Monitoring:Continuous emissions verification networks deploy electrochemical detectors for regulatory compliance. German environmental agencies face acute pressure under simultaneous EU Green Deal mandates and REACH substance restrictions.
- Industrial Process Control:Chemical manufacturing integrates pH and dissolved oxygen sensors into automated feedback loops.
- Automotive Testing:Powertrain and battery thermal management systems require gas and temperature sensing architectures.
Medical diagnostics dominates revenue concentration; environmental monitoring is expanding most quickly under tightening emissions mandates.
End User:
Margin structure varies dramatically between regulated healthcare procurement and price-sensitive chemical manufacturing volume contracts.
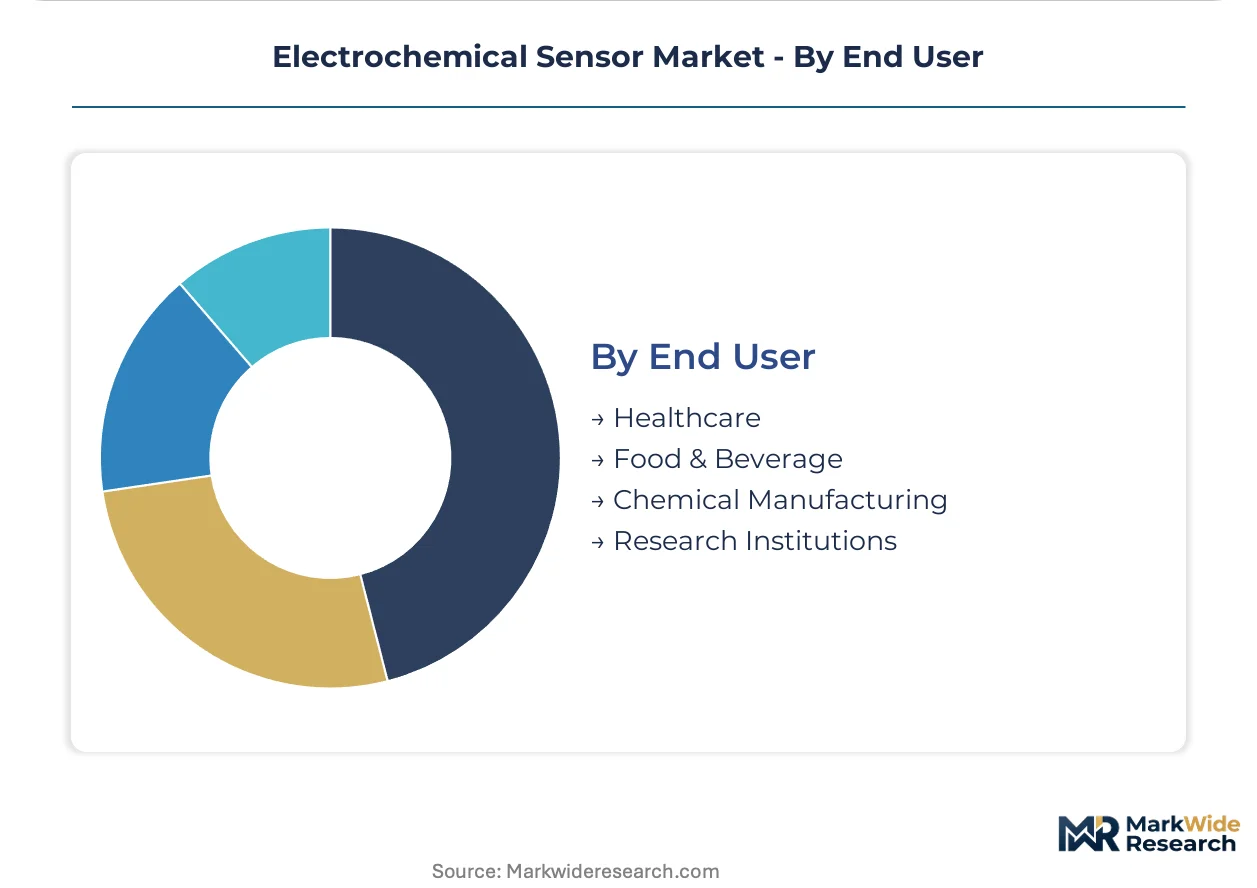
- Healthcare:Hospital procurement consolidation through multi-year preferred vendor agreements bundles analyzer hardware, consumables, and calibration services. United States health systems pursuing operational standardization across acquired regional networks displace fragmented spot-buying of individual electrode cartridges.
- Chemical Manufacturing:Process control instrumentation demands predictive maintenance integration through wireless sensor nodes and edge computing architectures. German chemical clusters drive high-accuracy gas sensor replacement cycles under F-Gas Regulation compliance pressure.
- Food & Beverage:pH and dissolved oxygen monitoring ensures batch consistency in fermentation and processing operations.
- Research Institutions:Specialized electrode configurations for novel analyte detection support academic and national laboratory pipelines.
Healthcare commands the strongest margin pools; chemical manufacturing represents the highest volume procurement segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany drives precision gas sensor procurement through automotive and chemical manufacturing clusters, while the United States anchors medical-grade demand through hospital consolidation and point-of-care expansion. Regulatory divergence between EU F-Gas mandates and FDA clinical validation protocols creates distinct procurement patterns across these markets.
United States
Hospital procurement departments bundle analyzer hardware, consumables, and calibration services through multi-year preferred vendor agreements. FDA 510(k) validation protocols govern clinical chemistry analyzer submissions for electrochemical sensor suppliers. Rural and suburban healthcare networks in the Southeast and Midwest deploy portable cardiac marker and electrolyte panels outside centralized lab infrastructure.
Germany
Automotive testing facilities and Ruhr Valley chemical manufacturing clusters drive high-accuracy sulfur dioxide and nitrogen oxide detector procurement. EU F-Gas Regulation and EU Green Deal emissions mandates force simultaneous electrolyte reformulation and sensor fleet upgrades. Bavarian environmental monitoring networks face acute compliance pressure for continuous emissions verification systems.
China
Electric vehicle manufacturers integrate cell-level electrochemical monitoring architectures for thermal runaway prevention in battery packs. MIIT dual carbon goals and GB standards tighten industrial emissions monitoring requirements for chemical processing facilities. Yangtze River Delta automotive and electronics clusters drive demand for miniaturized impedimetric sensors in wearable diagnostic platforms.
Japan
METI industrial safety mandates sustain replacement cycles for dissolved oxygen and pH sensors in pharmaceutical process control. PMDA oversight of clinical chemistry analyzers imposes validation protocols comparable to FDA requirements for medical electrochemical devices. Kansai region biopharmaceutical manufacturers require single-use disposable sensors with calibration stability for batch release compliance.
South Korea
Diagnostic OEMs deploy roll-to-roll manufacturing for continuous glucose monitoring strips at unit economics challenging traditional production methods. MFDS medical device regulations govern wearable biosensor platforms for athletic performance tracking. Seoul Capital Area electronics fabrication clusters supply printed graphene electrodes for disposable medical sensor formats.
Electrochemical Sensor Market Vendor Landscape
Top-tier vendors anchor high-accuracy gas sensing and medical diagnostics, while mid-scale specialists compete on miniaturization economics and regional regulatory compliance. The vendor base stratifies across three functional tiers: precision instrumentation incumbents with backward integration into electrode materials, safety equipment conglomerates with hazardous workplace distribution networks, and emerging diagnostic fabricators leveraging printed electronics manufacturing. Consolidation pressure concentrates among hospital procurement bundling and automotive battery thermal management contracts. Competitive moves emphasize strategic partnerships for electrolyte supply security and geographic expansion into point-of-care clinic networks.
Among precision instrumentation specialists, Alphasense and Thermo Fisher Scientific occupy positions exemplifying divergent strategic archetypes. Alphasense represents the environmental monitoring concentration with R&D intensity targeting high-accuracy gas sensing networks. Thermo Fisher Scientific anchors the clinical diagnostics tier through in-house production of specialized electrode materials. MSA Safety sits within the industrial safety equipment segment, competing in portable instrumentation for hazardous workplace environments. Dragerwerk AG exemplifies the European regulatory compliance specialization, while Honeywell International Inc. represents diversified industrial automation with sensor integration across process control architectures.
| Leading Market Players |
|---|
| Conductive Technologies Inc. |
| Alphasense |
| Thermo Fisher Scientific, Inc. |
| Siemens Healthineers |
| Honeywell International Inc. |
| MSA Safety |
| SGX Sensortech Ltd |
| Dragerwerk AG |
| Emerson Electric Co. |
| Others |
Supply Flow & Price Mechanics
Electrochemist talent scarcity in German research clusters widens labor-cost differentials between precision medical-grade production and commodity industrial detector assembly, stretching pricing-tier spreads across the value chain.
Pricing Analysis
The bundled-vs-unbundled service split separates hospital procurement consolidation from fragmented spot-buying of individual electrode cartridges. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification grade and volume scale commitments. Cost compression in disposable medical sensor tiers intensifies because South Korean and Taiwanese diagnostic OEMs deploy roll-to-roll manufacturing for continuous glucose monitoring strips. Chemical manufacturing buyers exhibit highest price sensitivity due to volume contract structures, while biopharmaceutical process control tolerates premium pricing for calibration stability guarantees.
Supply Chain Analysis
Warehouse-distribution layer configurations favor hub-and-spoke patterns radiating from German chemical clusters and South Korean electronics fabrication centers. Geographic supply concentration centers on Germany for specialized ionic liquid electrolytes, Japan for high-purity electrode materials, and South Korea for printed graphene substrates. Raw material dependencies rest on platinum and gold for medical-grade electrodes, fluorinated polymers for environmental gas sensing, and glass membrane formulations for pH sensors. Single-source vulnerability from German and Japanese chemical suppliers with limited qualified alternatives poses structural risk. Distribution runs through authorized instrumentation distributors serving hospital procurement departments and direct OEM supply agreements for automotive battery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrochemical sensor market functions as a stable compounder, with regulatory mandates for emissions monitoring and patient safety creating predictable replacement demand cycles across healthcare and industrial verticals.
For Market Incumbents: Deploy backward integration into specialized electrode materials to secure margin position against precious metal price volatility. Capture electrolyte supply security through strategic partnerships with German and Japanese chemical suppliers before REACH authorization restrictions tighten further. Fortify hospital procurement relationships through multi-year preferred vendor agreements that bundle analyzer hardware, consumables, and calibration services against emerging diagnostic fabricators. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for alternative ionic conductor validation services supporting industrial gas sensor manufacturers facing compliance deadlines. Target rural and suburban United States healthcare networks deploying portable cardiac marker and electrolyte panels outside centralized lab infrastructure. Pursue point-of-care clinic expansion through subscription-based sensor replenishment models rather than capital equipment sales. For Investors and Strategic Acquirers: Industrial safety equipment conglomerates are the most active acquirer in this space, seeking hazardous workplace distribution networks to complement existing product portfolios. Electrochemical sensor specialists with in-house electrode material production and FDA 510(k) cleared platforms represent the most defensible acquisition targets over a multi-year horizon. Watch for inflection when electric vehicle thermal management contracts consolidate around cell-level monitoring architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Reformulation Partnership | REACH compliance deadlines force material substitution programs across European environmental monitoring networks. |
| Roll-to-Roll Manufacturing Scale-Up | South Korean diagnostic OEMs achieve unit economics challenging traditional amperometric production methods. |
| Hospital Procurement Consolidation | United States health systems bundle analyzer hardware, consumables, and calibration through multi-year agreements. |
| Automotive Battery Sensor Integration | Electric vehicle manufacturers embed cell-level electrochemical monitoring for thermal runaway prevention. |
| Printed Graphene Electrode Development | Seoul Capital Area electronics clusters supply disposable medical sensor formats at compressed price floors. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital GPO contracts managers, chemical plant instrumentation leads, and automotive battery thermal management engineers combine with secondary validation from FDA 510(k) filings, EPA emissions monitoring databases, EU ECHA substance restriction updates, and SEC filings of listed sensor manufacturers. Triangulation across stakeholder inputs and documented regulatory mandates ensures coverage of both procurement decision-making and compliance-driven replacement cycles.
Input-output matrices map electrode material flows through fabrication stages to finished sensor shipments across product type, technology, application, and end user dimensions. CAGRs derive from segment-level demand build-ups incorporating regulatory mandate timelines, hospital procurement consolidation patterns, and automotive battery platform adoption curves. Industry-specific forecast inputs include REACH authorization schedules for per- and polyfluoroalkyl substances and MIIT dual carbon goal implementation trajectories for Chinese industrial emissions monitoring.
Revisions become necessary when electrolyte supply disruptions, precious metal price spikes, or regulatory timeline accelerations materialize outside modeled assumptions. Forecasts reflect documented parameters around electrode configuration validation protocols and regional procurement concentration trends. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Global Tilt Sensor Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Confocal Displacement Sensor Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
France Digital Thermometer Market