
 Battery Silver Paste Market | 2026-2036
Battery Silver Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Silver Paste Market Insights
GB/T 17472 silver paste qualification for crystalline silicon solar cells is reorganizing supplier eligibility across the battery silver paste value chain. Heraeus Holding GmbH leverages its in-house precious metals refining to sustain cost-advantaged feedstock access for photovoltaic-grade formulations. DuPont de Nemours anchors its position through fluoropolymer binder chemistry that differentiates paste rheology for high-speed screen printing lines. Samsung SDI competes by integrating silver paste development with its captive battery electrode manufacturing, creating closed-loop feedback on conductivity requirements.
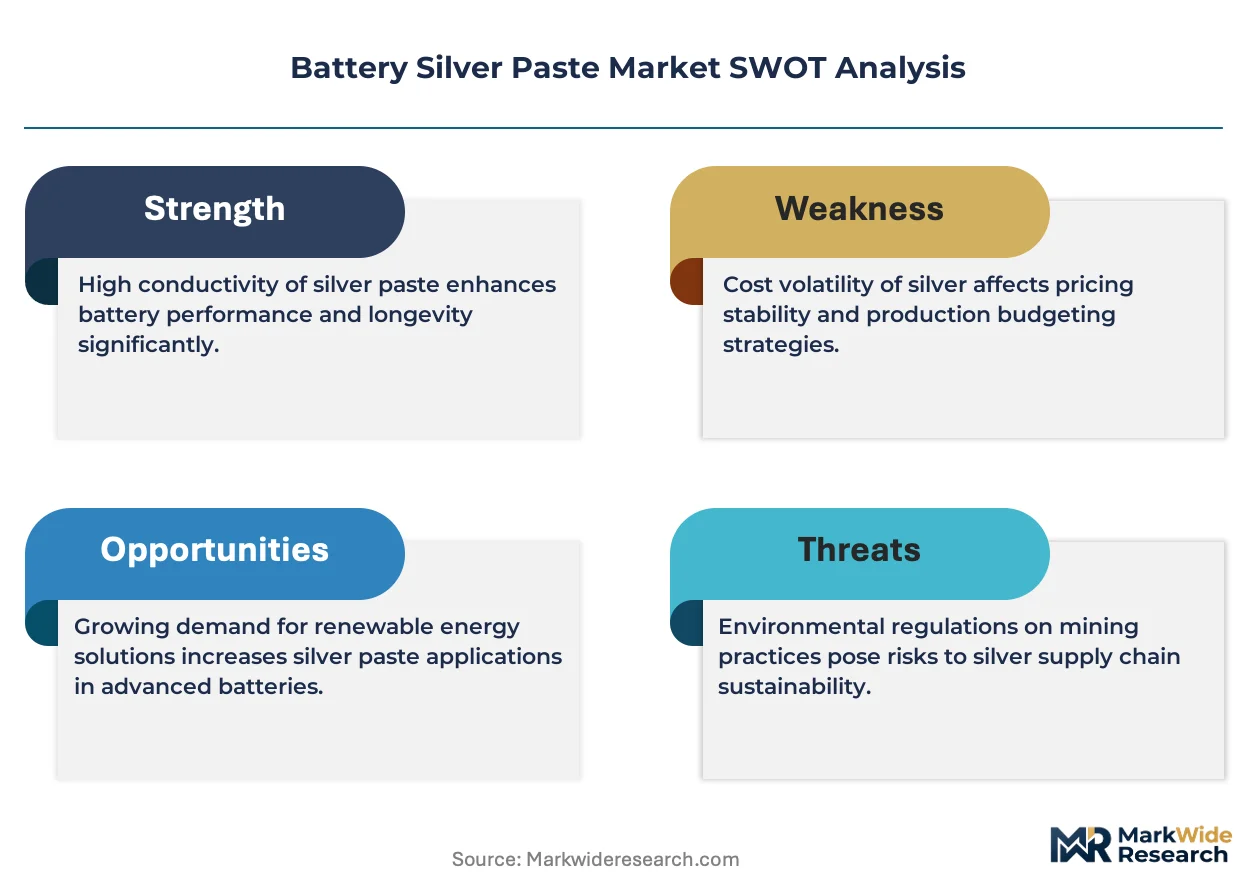
Battery silver paste denotes a silver particle-loaded functional material, typically comprising 80-90% metallic silver by weight in an organic vehicle with glass frit additives, engineered to form low-resistance electrical contacts on silicon wafers or battery current collectors through screen printing or dispensing processes. Its primary commercial purpose is to minimize contact resistance while maximizing adhesion in energy conversion and storage devices. Conductive paste occupies the largest volume share as photovoltaic manufacturers standardize on thick-film metallization, while specialty paste commands the highest margins as solid-state battery developers specify ultra-low-impurity formulations for lithium-metal anode interfaces. The end user dimension shows renewable energy procurement outgrowing consumer electronics, driven by utility-scale solar deployment and grid-storage battery builds.
REACH registration requirements for silver nanoparticle substances in Europe, China's GB standards for electronic materials under SAMR oversight, and the EPA's TSCA Section 5 scrutiny on new chemical formulations in the United States collectively elevate compliance costs and favor incumbents with established regulatory dossiers. These frameworks restrict market entry for unqualified suppliers while accelerating substitution research for silver-reduced or silver-free alternatives. Stakeholders must monitor evolving metallization efficiency targets and solid-state battery commercialization timelines to time capacity commitments and alloy development investments.
Market Dynamics
The transition from PERC to TOPCon cell architectures is compressing silver consumption per watt while demanding higher-performance paste formulations, forcing metallization suppliers to recalibrate solids loading and glass chemistry simultaneously.
Growth Catalysts
- China's dual carbon goals:National renewable energy targets under MEE oversight mandate utility-scale solar deployment, concentrating procurement of high-efficiency silver pastes in Hefei and Xuzhou manufacturing clusters.
- Grid-storage battery builds:Solid-state lithium-metal development programs specify ultra-low-impurity specialty pastes for anode current collectors, creating specification pull from next-generation cell producers.
- GB/T 17472 qualification:China's standardized silver paste certification for crystalline silicon cells is consolidating supplier eligibility and accelerating technical bar-raising across East Asian photovoltaic supply chains.
Market Restraints
- Silver price volatility:Precious metals feedstock fluctuations compress margin buffers for paste formulators lacking captive refining capabilities or long-term offtake hedging.
- REACH registration burden:ECHA compliance costs for silver nanoparticle substances in Europe favor incumbents with established dossiers and restrict new entrant participation.
- Copper-plated contact substitution:Electroplated copper seed layers on silicon wafers threaten thick-film silver paste volumes in cost-sensitive photovoltaic segments.
Strategic Opportunities
- Solid-state battery commercialization:Lithium-metal anode interfaces require ultra-pure specialty formulations, opening white space for paste suppliers with advanced impurity control capabilities.
- India's PLI scheme:Domestic solar cell manufacturing incentives under MNRE are localizing demand for screen-print metallization materials previously imported from East Asia.
- Fluoropolymer binder convergence:Integration of high-speed print rheology with perovskite-silicon tandem cell architectures enables paste suppliers to capture value from next-generation efficiency roadmaps.
Industry Challenges
- Screen printing technician scarcity:High-speed line operation and viscosity tuning for sub-20-micron finger widths require specialized skills concentrated in East Asian equipment hubs.
- GB standard compliance timelines:SAMR recertification cycles for reformulated glass frit compositions delay product launches and tie up R&D resources in documentation.
- Legacy furnace integration:New low-temperature curing pastes must demonstrate compatibility with existing belt furnace infrastructure without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Silver Paste Market |
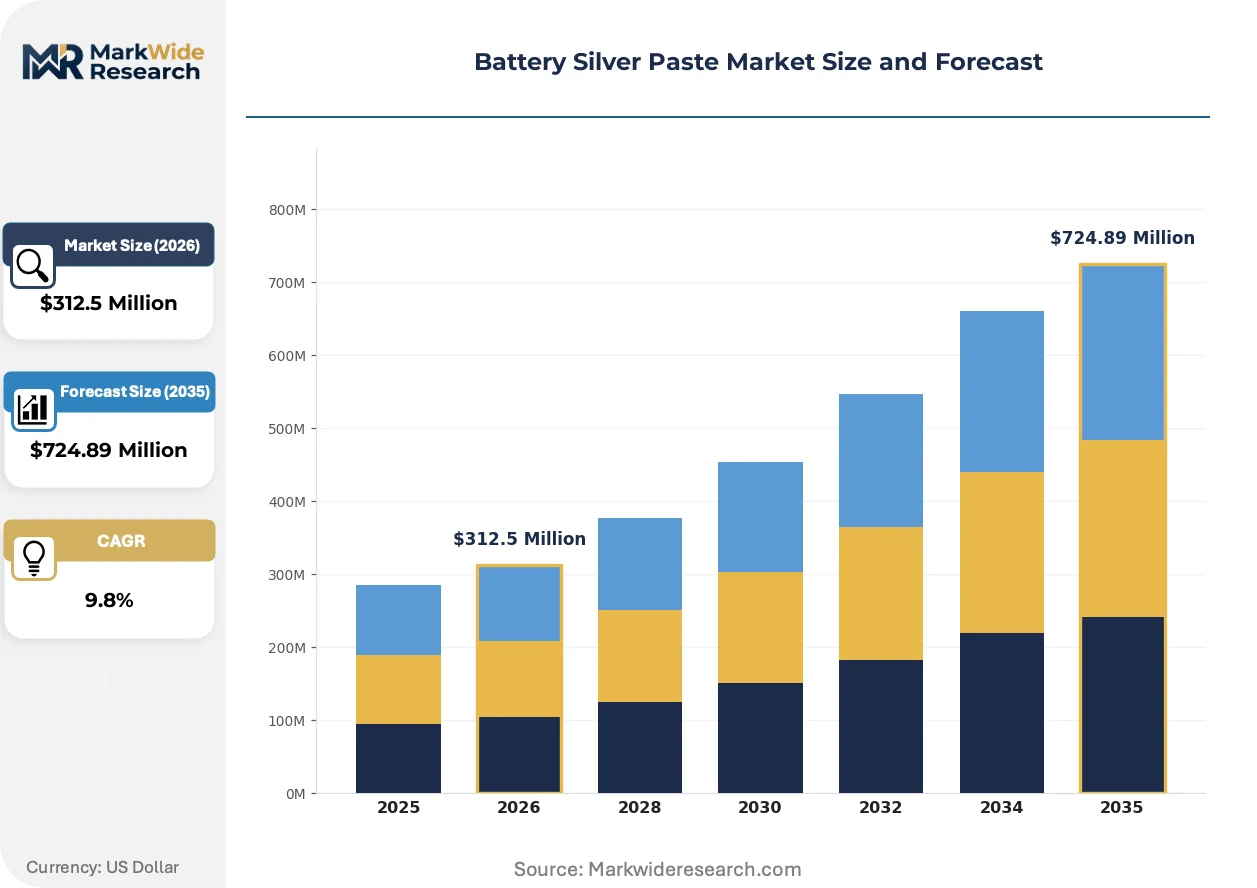
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $724.89 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Paste, Adhesive Paste, Screen Print Paste, Specialty Paste End User: Consumer Electronics, Automotive, Renewable Energy, Industrial Applications Application: Photovoltaic Cells, Batteries, Electronics Assembly, Sensor Devices Form: Powdered, Liquid, Gel, Paste |
| Companies Covered | Heraeus Holding GmbH, DuPont de Nemours, Samsung SDI, Giga Solar Materials, Henkel AG & Co. KGaA, KYOCERA Corporation, DOWA Electronics Materials, Johnson Matthey, DK Electronic Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Silver Paste Market Trends and Innovations
Metallization chemistry and deposition methods are diverging sharply between photovoltaic and battery applications, with each vertical imposing incompatible performance specifications on silver paste developers.
TOPCon tunnel oxide passivated contact architectures is supplanting PERC as the dominant silicon cell platform. Solar manufacturers in China's Yangtze River Delta are converting production lines at accelerated pace. This technology shift compresses silver consumption per watt while demanding pastes with enhanced contact selectivity on doped polysilicon surfaces.
REACH registration requirements for silver nanoparticle substances under ECHA oversight are elevating compliance barriers across European supply chains. Formulators without existing dossiers face multi-year registration timelines and toxicology testing costs. Specialty paste segments serving solid-state battery developers are absorbing these overheads into premium pricing structures.
Direct procurement contracts between cell manufacturers and paste formulators are consolidating distributor roles in East Asian supply chains. Long-term offtake agreements with fixed silver price mechanisms are replacing spot market purchasing for high-volume photovoltaic producers. This pattern is most visible in China's integrated solar manufacturing clusters, where captive paste development partnerships are becoming standard.
Battery Silver Paste Market Segmentation
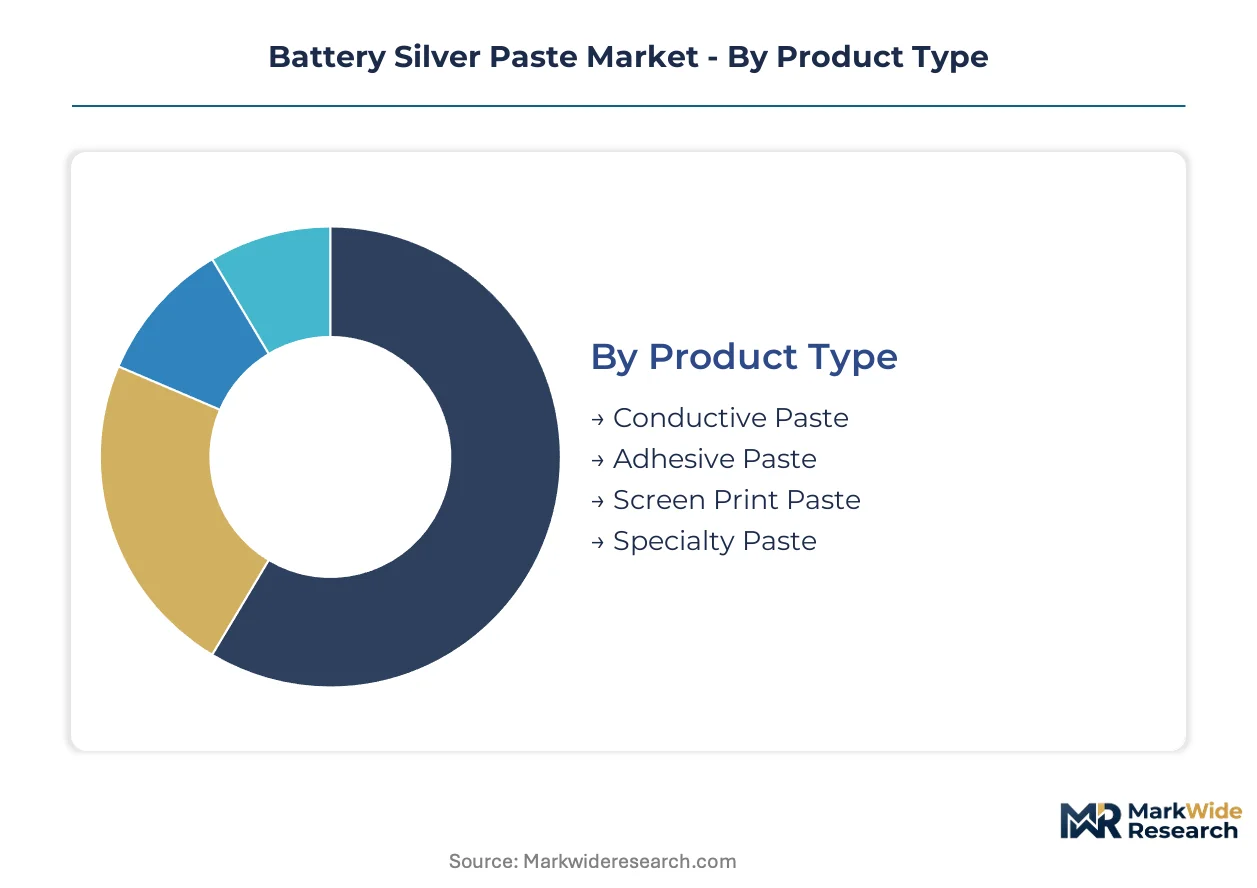
Silver paste segmentation reveals diverging substitution pressures across energy and electronics verticals, with photovoltaic metallization facing copper-plating displacement while battery applications command premium purity specifications. Understanding segment-level vulnerability to material substitution and regulatory burden directs supplier R&D allocation and capacity planning.
Product Type:
Conductive paste faces the most acute substitution threat from electroplated copper in cost-sensitive solar cell manufacturing, while specialty paste's ultra-purity requirements insulate it from near-term displacement.
- Conductive Paste:Thick-film formulations with 80-90% silver solids loading dominate crystalline silicon metallization. Procurement concentrates in China's Hefei and Xuzhou solar manufacturing clusters as TOPCon conversion accelerates. Copper-plated seed layers threaten volume in utility-scale segments where metallization cost dominates cell economics.
- Specialty Paste:Ultra-low-impurity formulations engineered for lithium-metal anode interfaces in solid-state battery development programs. Demand pulls from next-generation cell producers in Japan and South Korea specify impurity thresholds below 10 ppm for sodium and potassium. REACH registration costs embed into premium pricing structures that limit customer base expansion.
- Adhesive Paste:Bonding formulations for electronics assembly and thermal management applications. SAMR GB standards govern qualification for consumer electronics supply chains.
- Screen Print Paste:High-solid-content rheologies optimized for sub-20-micron finger widths on high-speed printing lines. India's PLI scheme is localizing demand previously served by East Asian imports.
Conductive paste retains volume leadership; specialty paste holds the steepest expansion curve.
End User:
Margin structures vary sharply across end-user tiers, with renewable energy procurement standardizing on cost-optimized formulations while automotive qualification timelines extend development payback periods.
- Renewable Energy:Utility-scale solar deployment under China's MEE oversight mandates high-throughput metallization materials. Long-term offtake agreements with fixed silver price mechanisms are replacing spot purchasing for integrated manufacturers.
- Automotive:Battery electric vehicle programs specify paste consistency across temperature cycling ranges for power electronics and cell interconnects. NHTSA and EPA compliance documentation extends qualification timelines.
- Consumer Electronics:Miniaturized device assembly drives demand for fine-pitch dispensing formulations. Procurement patterns favor established suppliers with SAMR certification dossiers.
- Industrial Applications:Sensor and RFID antenna manufacturing utilizes mid-tier conductivity specifications with less stringent impurity control.
Renewable energy commands the largest procurement volumes; automotive applications are climbing the fastest as electrification programs scale.
Application:
Technology roadmaps in photovoltaic cells and batteries are diverging metallization requirements, forcing paste developers to maintain incompatible formulation portfolios.
- Photovoltaic Cells:PERC-to-TOPCon architecture transition compresses silver consumption per watt while demanding enhanced contact selectivity on doped polysilicon surfaces. China's Yangtze River Delta manufacturing base is converting production lines at accelerated pace.
- Batteries:Solid-state lithium-metal development programs specify paste formulations for anode current collectors with ultra-low ionic impurity signatures. Japanese METI-funded research consortia are driving specification tightening.
- Electronics Assembly:Surface-mount and die-attach applications prioritize thermal cycling reliability over conductivity optimization.
- Sensor Devices:Printed electronics and wearable form factors utilize low-temperature curing pastes compatible with polymer substrates.
Photovoltaic cells maintain installed base dominance; battery applications are expanding most quickly as solid-state commercialization timelines firm.
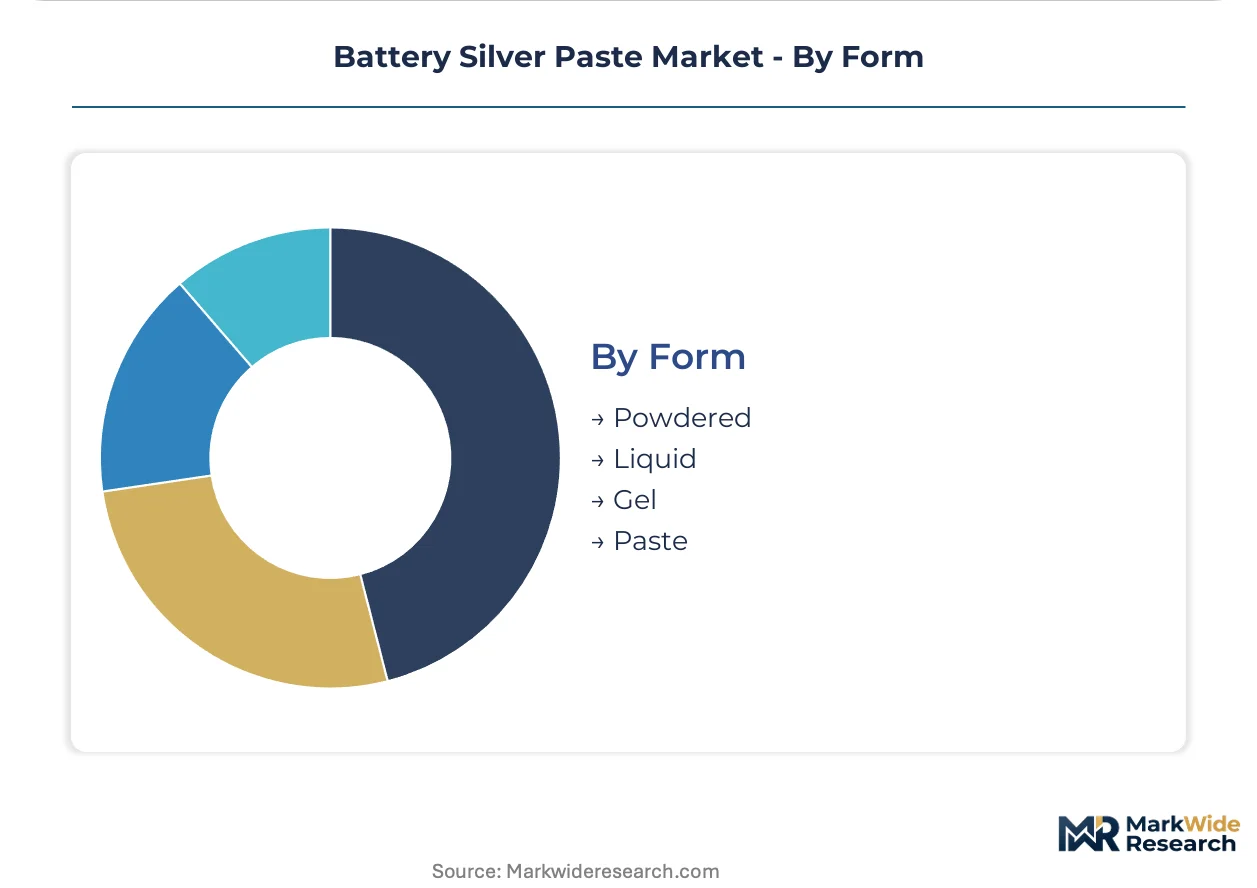
Form:
Supply chain configuration favors liquid and paste formulations with established cold-chain logistics, while powdered forms concentrate in captive manufacturing integrations.
- Paste:Ready-to-print rheologies dominate high-volume photovoltaic and battery electrode manufacturing. Heraeus and DuPont anchor supply through direct procurement contracts with cell manufacturers.
- Liquid:Dispensing-optimized formulations serve electronics assembly and sensor device applications with viscosity tuning for automated equipment.
- Powdered:Silver flake and nanoparticle feedstocks concentrate in formulators with in-house precious metals refining capabilities.
- Gel:Thixotropic formulations for stencil printing and conformal coating applications in specialized electronics segments.
Paste formulations retain volume leadership; liquid forms are gaining share fastest in precision electronics assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated solar cell manufacturers and solid-state battery developers concentrate procurement across East Asian industrial clusters, with qualification requirements and feedstock access determining supplier eligibility in each geography.
China
Photovoltaic manufacturers in Hefei and Xuzhou drive demand for high-solid-content screen print pastes as TOPCon conversion accelerates. SAMR oversight of GB/T 17472 certification is consolidating supplier eligibility across the Yangtze River Delta. Long-term offtake agreements with fixed silver price mechanisms are replacing spot purchasing for integrated producers.
Japan
Solid-state battery development programs specify ultra-low-impurity specialty pastes for lithium-metal anode interfaces. METI-funded research consortia are tightening impurity thresholds below 10 ppm for sodium and potassium. Osaka-based cell producers are driving specification pull for next-generation metallization materials.
South Korea
Battery electric vehicle power electronics and cell interconnect applications demand paste consistency across temperature cycling ranges. MFDS regulatory frameworks govern materials qualification for automotive supply chains. Samsung SDI's captive electrode manufacturing creates closed-loop feedback on conductivity requirements in the Seoul Capital Area.
Germany
REACH registration requirements for silver nanoparticle substances under ECHA oversight elevate compliance barriers for paste formulators. Distributor roles are compressing as direct procurement contracts consolidate supply relationships. Heraeus Holding leverages in-house precious metals refining to sustain cost-advantaged feedstock access.
India
Domestic solar cell manufacturing incentives under MNRE's PLI scheme are localizing demand for screen-print metallization materials. Procurement previously imported from East Asia is shifting to qualified domestic suppliers. Gujarat and Tamil Nadu manufacturing clusters are absorbing technology transfer for high-throughput paste application.
Battery Silver Paste Market Competitive Landscape
Player mix skews toward diversified materials conglomerates with captive precious metals refining or fluoropolymer chemistry capabilities. The supplier base concentrates around three strategic archetypes: integrated precious metals refiners, specialty chemical formulators with polymer binder expertise, and captive battery electrode developers. Competitive moves center on backward integration into silver feedstock supply and direct procurement contracting that eliminates distributor intermediaries.
Among German-based diversified materials groups, Heraeus Holding GmbH exemplifies the integrated refiner archetype with in-house precious metals capabilities. DuPont de Nemours occupies a position representing specialty chemical formulators leveraging fluoropolymer binder chemistry. Samsung SDI anchors the captive battery electrode developer tier, integrating paste development with internal cell manufacturing. These three entities represent the dominant competitive positioning vectors in the current supplier landscape.
| Leading Market Players |
|---|
| Heraeus Holding GmbH |
| DuPont de Nemours |
| Samsung SDI |
| Giga Solar Materials |
| Henkel AG & Co. KGaA |
| KYOCERA Corporation |
| DOWA Electronics Materials |
| Johnson Matthey |
| DK Electronic Materials |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with fixed silver price mechanisms anchor procurement relationships between East Asian cell manufacturers and paste formulators, locking in feedstock access while muting spot market exposure for integrated producers across China's Yangtze River Delta manufacturing clusters.
Pricing Analysis
Cost-plus contracts indexed to London Bullion Market Association silver spot prices dominate procurement between Heraeus, DuPont, and high-volume photovoltaic manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates GB/T 17472 certified formulations from uncertified alternatives and spot-market spot purchases. Pricing pressure stems from copper-plated contact substitution in utility-scale solar segments where metallization cost dominates cell economics. Cost-sensitive photovoltaic producers in India's PLI scheme exhibit highest price sensitivity, while solid-state battery developers in Japan absorb premium pricing for sub-10 ppm impurity thresholds.
Supply Chain Analysis
Inventory buffers and six-to-eight-week lead times for silver flake feedstock concentrate supply risk in formulators lacking captive refining capabilities. China, Germany, and Japan anchor global production, with Heraeus's Hanau refining complex and DOWA's Akita facility supplying downstream formulators. Raw material dependencies rest on silver bullion from Mexican and Peruvian mining operations, fluoropolymer binders from DuPont's Fayetteville plant, and borosilicate glass frit from Chinese specialty ceramics producers. Single-source vulnerability in high-purity silver nanoparticle synthesis elevates risk for specialty paste segments. Distribution runs through direct procurement contracts that displace distributor intermediaries in East Asian supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Battery Silver Paste Market is navigating a cyclical recovery driven by China's dual carbon goals under MEE oversight, which mandate sustained utility-scale solar deployment and concentrate procurement in Hefei and Xuzhou manufacturing clusters.
For Market Incumbents: Fortify backward integration into silver refining capabilities to offset precious metals price volatility compressing margin buffers for non-integrated formulators. Expand GB/T 17472 certification maintenance investments to defend eligibility as SAMR recertification cycles accelerate technical bar-raising across East Asian photovoltaic supply chains. For New Entrants and Emerging Players: Differentiate on ultra-low-impurity specialty formulations for solid-state battery anode interfaces, where Japanese METI-funded research consortia specify thresholds below 10 ppm for sodium and potassium. Target India's PLI scheme localization gap for screen-print metallization materials previously imported from East Asia, leveraging technology transfer partnerships with Gujarat and Tamil Nadu manufacturing clusters. For Investors and Strategic Acquirers: Fluoropolymer chemistry specialists with established perovskite-silicon tandem cell rheology capabilities represent the most attractive acquisition target archetype for capturing next-generation efficiency roadmap value. Monitor solid-state battery commercialization timelines as the critical inflection signal for timing specialty paste capacity commitments and alloy development investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Refining | Heraeus's Hanau complex demonstrates cost-advantaged feedstock access sustaining margin buffers against LBMA price volatility. |
| GB/T 17472 Certification Investment | SAMR oversight consolidates supplier eligibility, accelerating technical bar-raising across Yangtze River Delta procurement clusters. |
| Specialty Paste Capacity Buildout | Sub-10 ppm impurity control capabilities capture value from Japanese METI-funded solid-state battery development programs. |
| Direct Procurement Contracting | Long-term offtake agreements with fixed silver mechanisms displace distributor roles in East Asian supply chains. |
| Perovskite-Silicon Tandem Rheology Development | DuPont's fluoropolymer binder expertise positions for next-generation cell architecture metallization requirements. |
Research Methodology
A standing panel of paste formulator technical directors, photovoltaic cell procurement managers, solid-state battery R&D leads, and precious metals trading specialists provided ongoing calibration across the analysis window. Primary interviews combined with secondary validation from SAMR GB standard filings, ECHA REACH registration databases, SEC 10-K disclosures from listed materials conglomerates, and MNRE PLI scheme beneficiary records. Bottom-up volume modeling and top-down value triangulation cross-checked outputs against customs trade data and industry association production statistics.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, end-use vertical, application technology, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year observations, with sensitivity testing around silver price trajectory assumptions and TOPCon conversion pace assumptions.
Material uncertainties — silver price volatility, copper-plating substitution acceleration, and solid-state battery commercialization delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology transition timelines and regulatory enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Gallium Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Semiconductor Film Market