
 Digital Battery Internal Resistance Tester Market | 2026-2036
Digital Battery Internal Resistance Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Battery Internal Resistance Tester Market Insights
EU Battery Regulation sustainability mandates are restructuring procurement criteria across European battery supply chains. Hioki leverages its impedance spectroscopy heritage to dominate high-precision laboratory validation workflows. Megger sustains competitive positioning through deep channel control in utility-scale battery storage commissioning across industrialized markets.
A digital battery internal resistance tester measures the ohmic resistance of electrochemical cells using alternating current or direct current injection methods, typically resolving values in the micro-ohm to milli-ohm range to predict state-of-health and thermal runaway risk. Portable testers lead volume shipments for field service applications, while impedance spectroscopy commands premium pricing in research lab environments where electrochemical characterization depth determines funding access. Bench-top testers anchor margin pools in automotive OEM battery pack assembly lines, where throughput requirements favor automated fixture integration over handheld flexibility.
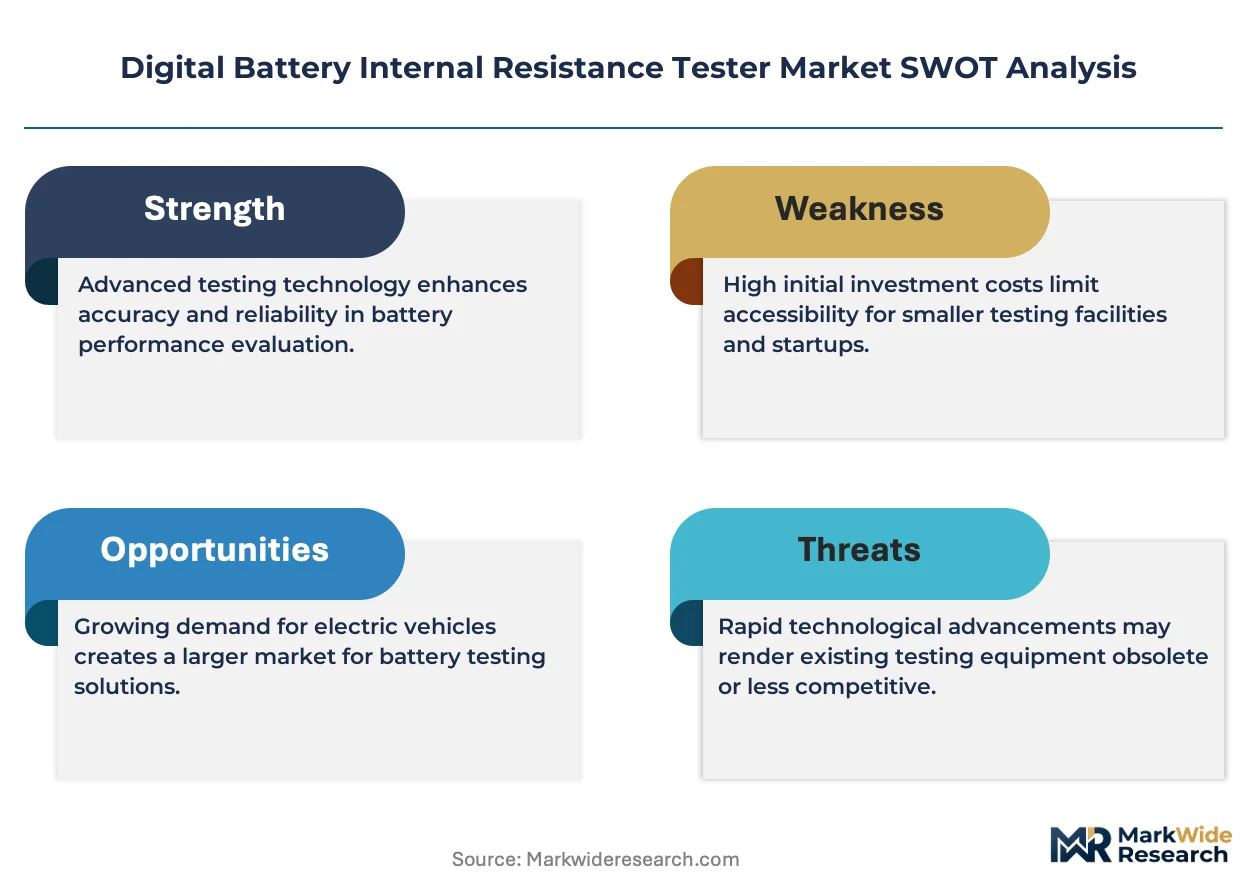
FDA oversight of medical device battery safety, EPA hazardous waste rules for end-of-life battery handling, and EU Battery Regulation carbon-footprint disclosure requirements collectively elevate testing documentation burdens. IEC 62660 and ISO 12405 standards shape product certification pathways, forcing instrument manufacturers to validate measurement repeatability across temperature extremes. Stakeholders must monitor how solid-state battery chemistry transitions alter resistance signature baselines and demand recalibration of existing tester architectures.
Market Dynamics
EU Battery Regulation carbon-footprint disclosure mandates are forcing instrument manufacturers to redesign validation workflows for traceable electrochemical characterization across European gigafactory supply chains.
Growth Catalysts
- Solid-state battery chemistry transitions:Next-generation cell architectures require recalibrated impedance baselines, creating replacement demand for laboratory-grade spectroscopy systems in South Korean and Japanese research clusters.
- Inline resistance monitoring:East Asian battery production lines now embed automated testers to catch thermal runaway precursors before cell assembly, reducing warranty failure exposure for electric vehicle OEMs.
- FDA medical device battery safety oversight:Implantable and portable diagnostic equipment manufacturers must document electrochemical stability, expanding precision tester procurement in North American healthcare supply chains.
Market Restraints
- High-precision component concentration:Specialized analog-to-digital converters and ultra-stable current sources concentrate among Japanese and German semiconductor suppliers, exposing instrument makers to single-source fragility.
- Calibration infrastructure gaps:Certified reference materials for micro-ohm traceability remain limited to national metrology institutes in the US, Germany, and Japan, constraining field-service accuracy in emerging production regions.
- Capital intensity of automated fixture integration:Automotive battery pack assembly lines require six-figure capital commitments per testing station, slowing adoption outside top-tier OEM supplier networks.
Strategic Opportunities
- Second-life battery grading services:Stationary energy storage installers in California and Texas need portable resistance mapping to sort retired electric vehicle cells, opening aftermarket service revenue streams.
- EU Battery Regulation repairability mandates:Independent service providers gain legal access to battery pack diagnostics, fragmenting demand from captive OEM laboratories toward distributed testing networks.
- Impedance spectroscopy and thermal imaging convergence:Combined diagnostic platforms enable simultaneous electrical and thermal characterization, commanding premium positioning in German automotive R&D contracts.
Industry Challenges
- Electrochemical modeling expertise scarcity:Field service technicians lack training to interpret complex Nyquist plots, forcing manufacturers to embed simplified pass-fail algorithms that erode differentiation.
- IEC 62660 certification timeline compression:Temperature-extreme validation protocols now require 18-month documentation cycles, delaying product launches and freezing engineering resources.
- Legacy battery management system integration friction:New testers must communicate with proprietary CAN bus protocols across decade-old vehicle fleets, multiplying firmware customization burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Battery Internal Resistance Tester Market |
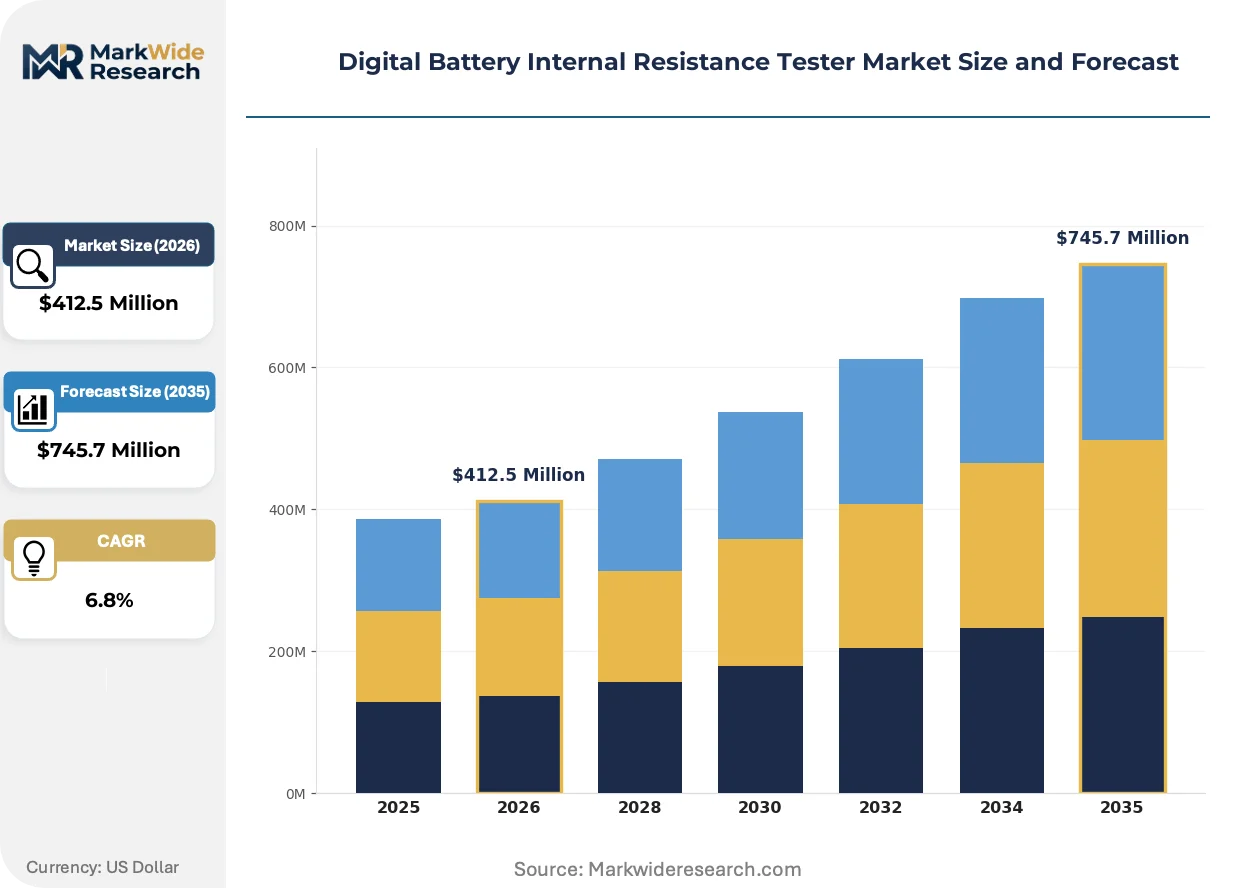
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Tester, Bench-Top Tester, High-Precision Tester, Smart Tester Technology: AC Resistance Measurement, DC Resistance Measurement, Impedance Spectroscopy, Microcontroller-Based End User: Automotive OEMs, Battery Manufacturers, Research Labs, Repair Shops Delivery Mode: Cloud-Based, On-Premises, Mobile Application, Standalone Device |
| Companies Covered | Fluke, Megger, Hioki, AEMC Instruments, ACT Meters, Fortive, Danaher, Kikusui, DV Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Battery Internal Resistance Tester Market Trends and Innovations
Tester architectures are bifurcating between portable field-service simplicity and laboratory-grade spectroscopic depth, with software-defined measurement engines bridging both domains through firmware reconfiguration.
Machine learning-based resistance signature analysis is automating state-of-health prediction for lithium-ion cells in German automotive battery pack assembly operations. BMW and Volkswagen suppliers now deploy neural-network-enhanced testers that compress diagnostic cycles from minutes to seconds. This capability is automating quality-control throughput scaling without proportional hardware investment.
REACH substance restrictions on lead-based solder and cadmium-plated connectors are forcing instrument manufacturers to redesign analog front-end assemblies. European testing equipment vendors face 24-month redesign cycles to maintain CE marking compliance. Bench-top product lines targeting EU medical and automotive certification workflows absorb the steepest cost and timeline impacts.
Buyer consolidation among tier-one battery cell producers is concentrating procurement leverage in South Korean and Chinese manufacturing conglomerates. These purchasers now demand outcome-based calibration service contracts rather than capital equipment ownership. The shift is most visible in CATL and LG Energy Solution supplier qualification programs, where five-year total-cost-of-ownership agreements displace traditional hardware-plus-maintenance purchasing.
Digital Battery Internal Resistance Tester Market Segmentation
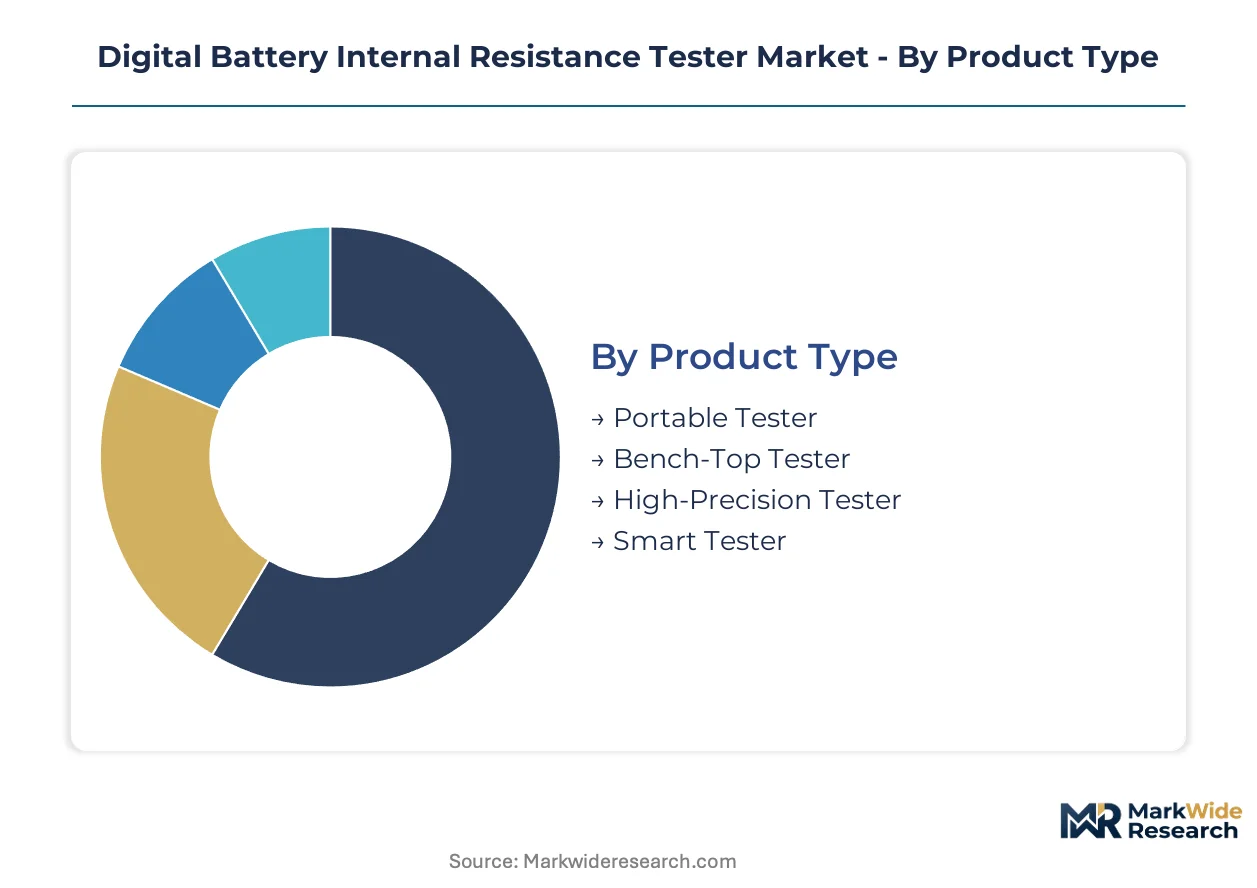
Segmentation in the digital battery internal resistance tester market reveals how capital allocation, technical requirements, and regulatory compliance pressures fragment procurement patterns across battery supply chains. Understanding these divisions exposes where margin pools concentrate and which configurations face substitution risk from converging diagnostic platforms.
Product Type:
Capital intensity varies dramatically across form factors, with automated fixture integration for production-line systems demanding tenfold higher upfront investment than handheld alternatives.
- Portable Tester:Battery-powered handheld units with micro-ohm resolution deploy field service technicians to electric vehicle fleets and stationary storage installations. Demand clusters in California and Texas second-life battery grading operations where mobility outweighs laboratory precision.
- Bench-Top Tester:Automated fixture-integrated systems anchor automotive OEM battery pack assembly lines in Germany, where throughput requirements favor hardware-in-the-loop validation over operator-dependent measurements. Six-figure capital commitments per station limit adoption to tier-one supplier networks.
- High-Precision Tester:Laboratory-grade systems achieve sub-micro-ohm repeatability for electrochemical research in South Korean and Japanese R&D clusters.
- Smart Tester:Firmware-reconfigurable architectures bridge field and laboratory applications through software-defined measurement engines.
Bench-top systems absorb the bulk of installed capacity; smart testers are expanding most quickly as vendors consolidate hardware platforms behind differentiated firmware.
Technology:
Measurement methodology determines certification pathway complexity and temperature-extreme validation burden under IEC 62660 protocols.
- AC Resistance Measurement:Alternating current injection at kilohertz frequencies isolates ohmic from polarization resistance components. German automotive suppliers favor this approach for inline quality control where speed dominates absolute accuracy.
- Impedance Spectroscopy:Multi-frequency excitation generates Nyquist plots for electrochemical model extraction in research environments. Solid-state battery chemistry transitions in Japanese laboratories are recalibrating impedance baseline libraries and driving replacement demand for spectroscopy systems.
- DC Resistance Measurement:Pulse-current methods dominate utility-scale storage commissioning where Megger maintains channel control.
- Microcontroller-Based:Embedded processing architectures reduce analog front-end component count for cost-sensitive repair shop applications.
AC resistance measurement carries the heaviest certification documentation load; impedance spectroscopy commands the steepest pricing premiums.
End User:
Procurement authority concentration among battery manufacturing conglomerates is shifting purchasing models from capital equipment ownership toward outcome-based service contracts.
- Automotive OEMs:BMW and Volkswagen supplier networks in Germany deploy neural-network-enhanced testers that compress diagnostic cycles from minutes to seconds. Machine learning integration is automating throughput scaling without proportional hardware investment.
- Battery Manufacturers:CATL and LG Energy Solution now demand five-year total-cost-of-ownership agreements displacing traditional hardware-plus-maintenance purchasing. This buyer consolidation concentrates leverage in East Asian production clusters.
- Research Labs:Academic and national laboratory funding access depends on electrochemical characterization depth, sustaining premium pricing for spectroscopic systems.
- Repair Shops:EU Battery Regulation repairability mandates are fragmenting demand from captive OEM laboratories toward independent service providers.
Battery manufacturers command the largest procurement volumes; repair shops are gaining legal access fastest under European regulatory restructuring.
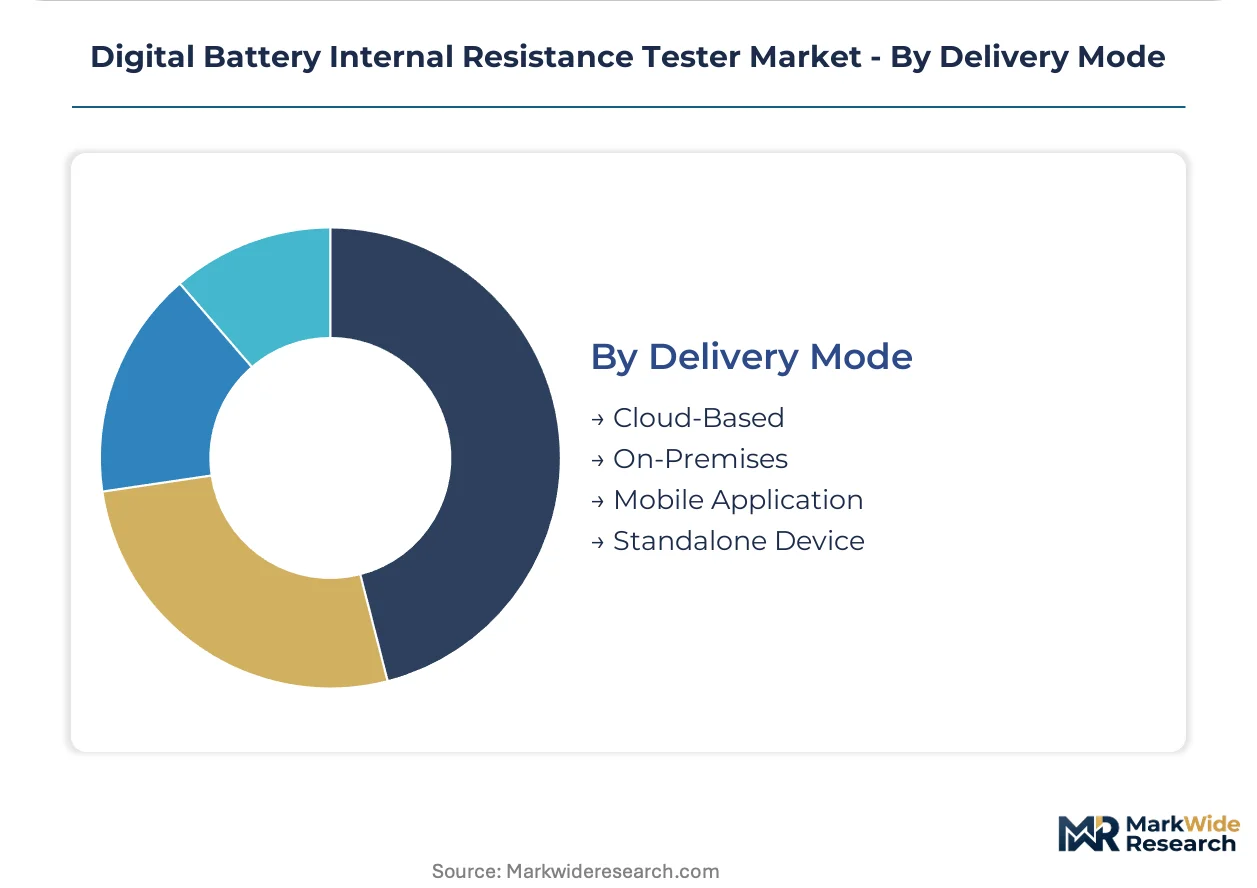
Delivery Mode:
Data architecture choices determine cybersecurity exposure and regulatory audit trail completeness for FDA medical device battery safety documentation.
- Cloud-Based:Centralized data aggregation enables fleet-wide state-of-health trending across dispersed electric vehicle populations. North American healthcare supply chains favor this architecture for implantable device battery monitoring.
- On-Premises:Air-gapped installations satisfy defense and critical infrastructure cybersecurity requirements where export control regulations restrict data transmission.
- Mobile Application:Smartphone-tethered interfaces reduce dedicated hardware costs for field service technicians interpreting simplified pass-fail algorithms.
- Standalone Device:Embedded processing without external connectivity persists in legacy automotive workshop environments.
Cloud-based deployments are capturing the most new installations; on-premises systems retain the most pricing power in security-sensitive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors East Asian demand for inline resistance monitoring as CATL and BYD suppliers embed automated testers across gigafactory production corridors. German automotive OEMs in Stuttgart and Munich are expanding laboratory validation capacity under EU Battery Regulation carbon-footprint mandates. Japanese research clusters in Osaka and Nagoya recalibrate impedance spectroscopy baselines for solid-state chemistry transitions.
China
Gigafactory scale-up in Fujian and Sichuan provinces drives procurement of automated fixture-integrated systems for lithium-ion cell validation. MIIT battery safety standards mandate traceable electrochemical characterization across production lines. Shenzhen and Dongguan manufacturing corridors concentrate smart tester assembly capacity serving CATL supplier networks.
Germany
BMW and Volkswagen supplier ecosystems in Bavaria deploy neural-network-enhanced testers to compress battery pack diagnostic cycles. EU Battery Regulation sustainability disclosure requirements force redesign of validation workflows for traceable documentation. Stuttgart and Munich R&D clusters command premium positioning for impedance spectroscopy and thermal imaging convergence platforms.
Japan
Solid-state battery chemistry research in Osaka and Nagoya recalibrates impedance baseline libraries, driving replacement demand for laboratory-grade spectroscopy systems. METI technology roadmaps prioritize electrochemical characterization depth for next-generation cell architectures. Kobe and Yokohama industrial zones concentrate high-precision component supply for analog front-end assemblies.
South Korea
LG Energy Solution and Samsung SDI supplier qualification programs shift procurement toward five-year total-cost-of-ownership agreements displacing traditional hardware purchasing. MFDS medical device battery safety oversight expands precision tester demand for implantable equipment. Gyeonggi-do and Chungcheongnam-do production belts embed inline resistance monitoring to reduce warranty failure exposure.
United States
Second-life battery grading operations in California and Texas create aftermarket demand for portable resistance mapping of retired electric vehicle cells. FDA oversight of medical device battery safety elevates documentation burdens for electrochemical stability validation. Detroit automotive supplier networks and Boston healthcare technology corridors split demand between field-service portability and laboratory precision.
Digital Battery Internal Resistance Tester Market Competitive Landscape
Premium-margin players sit above commodity-margin players across measurement precision and certification depth. Laboratory-grade spectroscopy systems command pricing multiples over portable field-service units due to IEC 62660 validation documentation burdens. Three archetypes dominate: Japanese precision electronics houses with impedance heritage, German industrial instrumentation specialists with automotive channel control, and diversified electrical test conglomerates with utility-scale storage positioning. Competitive moves concentrate on firmware-defined measurement engine consolidation and outcome-based calibration service contracting.
Among diversified test and measurement conglomerates, Fortive and Danaher occupy positions spanning industrial, medical, and automotive validation workflows. Hioki exemplifies the precision electronics archetype with heritage in impedance spectroscopy for laboratory environments. Megger anchors the utility-scale storage commissioning segment through deep channel control in industrialized markets. Fluke represents the field-service portability tier with handheld unit deployment across dispersed technician networks.
| Leading Market Players |
|---|
| Fluke |
| Megger |
| Hioki |
| AEMC Instruments |
| ACT Meters |
| Fortive |
| Danaher |
| Kikusui |
| DV Power |
| Others |
Pricing and Supply Chain Analysis
Tier-one battery manufacturing conglomerates in South Korea and China now dictate procurement terms across East Asian production clusters, compressing instrument vendors toward outcome-based calibration service contracts that displace traditional hardware ownership models.
Pricing Analysis
Value-based pricing anchored to diagnostic throughput and warranty failure reduction dominates automotive OEM supplier networks in Germany. Three-tier pricing structure across premium laboratory-grade spectroscopy, standard bench-top production systems, and economy portable field units reflects IEC 62660 certification documentation burdens and measurement precision differentials. Pricing pressure stems from buyer consolidation among CATL and LG Energy Solution procurement programs demanding five-year total-cost-of-ownership agreements. Repair shops and independent service providers exhibit highest price sensitivity, while research laboratories accessing national funding streams show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German semiconductor suppliers for specialized analog-to-digital converters and ultra-stable current sources. Component fabrication concentrates in Japan, Germany, and Taiwan, with final instrument assembly clustering in Shenzhen and Dongguan manufacturing corridors. Raw material dependencies include precision resistors, hermetically sealed reference cells, and temperature-stable substrate materials. Tariff exposure on Chinese-assembled units shipping to North American healthcare markets creates margin compression. Distribution runs through authorized channel partners serving automotive OEM supplier networks and direct sales teams for laboratory-grade systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around firmware-defined measurement platforms and outcome-based service contracting, with IEC 62660 certification timeline compression forcing weaker players lacking validation documentation capabilities toward exit.
For Market Incumbents: To counter buyer consolidation leverage in South Korean and Chinese battery manufacturing conglomerates, deepen captive calibration service infrastructure across East Asian production belts and embed machine-learning diagnostic algorithms that compress test cycle times for automotive OEM throughput requirements. For New Entrants and Emerging Players: Capture fragmented demand from EU Battery Regulation repairability mandates opening independent service provider networks in Germany and aftermarket second-life battery grading operations in California and Texas, leveraging smartphone-tethered mobile application interfaces to bypass capital-intensive hardware development. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision electronics specialists with impedance spectroscopy heritage in Japan and Germany over diversified test conglomerates lacking electrochemical characterization depth, with solid-state battery chemistry transition timelines serving as the critical inflection signal for laboratory-grade system replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Defined Measurement Engine Consolidation | Hioki and Kikusui bridge portable and laboratory architectures through reconfigurable hardware platforms. |
| Outcome-Based Calibration Service Contracting | Five-year TCO agreements with CATL and LG Energy Solution displace traditional equipment purchasing. |
| Machine Learning Diagnostic Integration | BMW and Volkswagen suppliers deploy neural-network-enhanced testers to compress battery pack validation cycles. |
| Impedance-Thermal Imaging Convergence | Combined diagnostic platforms command premium positioning in Stuttgart and Munich automotive R&D contracts. |
| Second-Life Battery Grading Service Expansion | California and Texas stationary storage installers create aftermarket revenue streams for portable resistance mapping. |
Research Methodology
SEC filings, IEC certification documentation, and national metrology institute calibration records formed the secondary backbone, supplemented by primary interviews with automotive OEM battery pack engineers, Tier 1 supplier procurement managers, laboratory instrumentation specialists, and field service technicians across German, Japanese, South Korean, and North American validation workflows. Bottom-up unit shipment estimates triangulated against top-down capital expenditure disclosures from battery manufacturing conglomerates.
Historical trendline analysis of instrument procurement patterns across automotive OEM supplier networks, battery manufacturing production lines, and research laboratory funding cycles established baseline growth trajectories. The analytical framework segmented demand by product form factor, measurement technology, end-user vertical, and delivery mode architecture across the projection horizon. CAGR derivation incorporated electrochemical characterization depth requirements, regulatory certification timeline compression, and solid-state battery chemistry transition pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state battery commercialization timelines, REACH substance restriction redesign cycles, and buyer consolidation leverage shifts among East Asian manufacturing conglomerates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Product Design Verification and Validation Solution Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
Laser Interferometer Market
Test and Measurement
Semiconductor Test Socket Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Fogging Tester Market
Test and Measurement
PXI Source Measure Unit Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
X-Ray Inspection System Market
Test and Measurement
Ground Grid Tester Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Sample Rate Converters Market