
 Transparent Electronics Market | 2026-2036
Transparent Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Electronics Market Intelligence
Direct OEM supply agreements for transparent display panels is rewriting procurement economics in the electronics value chain. Samsung Electronics Co. Ltd. anchors transparent OLED volume through captive display fabs and exclusive automotive partnerships. BOE Technology Group Co. Ltd. competes aggressively on manufacturing scale, leveraging government-backed capacity expansions to undercut Korean pricing. Corning Incorporated dominates the substrate layer with specialized alkali-free glass formulations that sustain thermal stability during thin-film transistor processing.
Transparent electronics encompasses devices fabricated on optically clear substrates where active components transmit visible light while performing electrical functions, typically achieving optical transmittance above 70% through indium tin oxide or silver nanowire conductive layers. These systems enable see-through displays, photovoltaic windows, and embedded sensors without obstructing the field of view in architectural or vehicular environments. Displays currently leads product type revenue due to mature transparent OLED manufacturing, while photovoltaics represents the fastest-growing category as building-integrated solar glass gains code traction in commercial construction. Transparent conductive films technology occupies the deepest margin pool because indium tin oxide alternatives command premium pricing from supply-constrained silver nanowire and carbon nanotube formulations.
The EPA regulates indium compounds under TSCA reporting requirements, while REACH restricts hazardous substances in transparent conductive material imports into Europe. Korea's Ministry of Trade, Industry and Energy enforces national standards for transparent display energy efficiency that shape product certification timelines. Stakeholders must monitor evolving rare earth export controls and substitution timelines for indium-dependent transparent electrode formulations.
Market Dynamics
Automotive OEMs are embedding transparent OLED dashboards and windshields at scale, compressing procurement timelines and forcing display suppliers to reconfigure fabrication lines for vehicle-grade certification cycles.
Growth Catalysts
- EU F-Gas Regulation:Tightening specifications for fluorinated compounds in transparent conductive film production are accelerating substitution toward silver nanowire and carbon nanotube formulations.
- Building-integrated photovoltaics:Commercial construction codes in Germany and Japan are mandating solar glass integration, pulling transparent electrode demand from display-centric to dual-use architectures.
- South Korean cluster concentration:Dedicated transparent OLED fabrication lines in Gumi and Paju are achieving yield rates that lower unit economics for automotive qualification programs.
Market Restraints
- Indium supply concentration:Over 80 percent of refined indium originates from Chinese zinc smelting byproduct recovery, exposing transparent electrode supply to export control volatility.
- REACH compliance friction:Hazardous substance restrictions on nanomaterial imports into Europe are extending certification timelines for silver nanowire film manufacturers by 12-18 months.
- Alternative display technologies:Micro-LED transparent modules are approaching optical transmittance parity with OLED, threatening incumbent technology lock-in for premium automotive contracts.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting substrate and conductive film assembly investments outside East Asian supply concentration.
- Aviation cabin retrofit:Airlines are specifying transparent OLED partitions and window overlays for premium cabin differentiation, opening a channel outside automotive and architectural verticals.
- Dual-carbon policy convergence:China's MIIT energy efficiency mandates and the EU Green Deal are aligning procurement criteria around embodied carbon in transparent electronics, favoring low-temperature processed alternatives.
Industry Challenges
- Thermal management engineering:Automotive qualification requires transparent displays to sustain 85°C operating temperatures without luminance degradation, stretching in-house thermal simulation capabilities.
- Patent thicket navigation:Indium tin oxide alternative formulations are encumbered by overlapping university and corporate licensing claims, complicating freedom-to-operate analysis for new entrants.
- Cross-industry certification:Display suppliers must simultaneously satisfy Korea's Ministry of Trade, Industry and Energy energy efficiency standards and automotive OEM crash-safety testing, duplicating validation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Electronics Market |
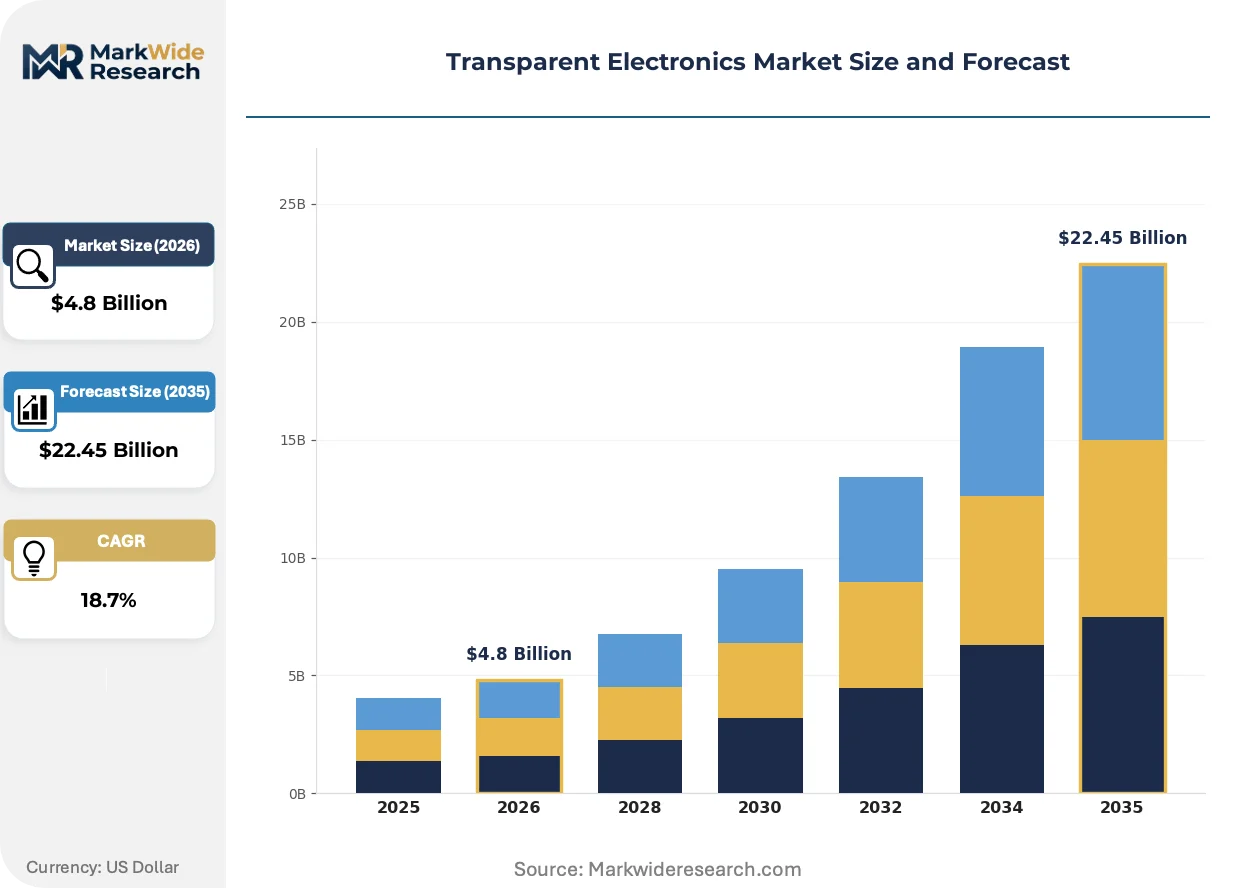
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Photovoltaics, Sensors, Antennas Technology: Organic Photonic, Transparent Conductive Films, Holography, Nanoelectronics Application: Consumer Electronics, Automotive Displays, Smart Windows, Wearable Devices End User: Retail, Healthcare, Automotive, Smart Home |
| Companies Covered | Cambrios Technologies Corp., Panasonic Holdings Corp., Samsung Electronics Co. Ltd., Apple Inc., 3M Company, LG Electronics Inc., BOE Technology Group Co. Ltd., ClearLED Ltd., Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Electronics Market Strategic Shifts & Innovations
Silver nanowire transparent conductive films are collapsing the cost-performance gap with indium tin oxide, while regulatory frameworks in Europe and Asia are hardening material specifications faster than substitution timelines can adapt.
Silver nanowire deposition is collapsing the traditional transparent electrode cost structure by eliminating vacuum sputtering equipment requirements. Automotive tier-1 suppliers are qualifying roll-to-roll coated films for windshield-integrated antenna and defrost applications. The technology is collapsing capital barriers that previously concentrated transparent conductor manufacturing among display-integrated conglomerates.
REACH restrictions on hazardous nanomaterial classifications are forcing reformulation of carbon nanotube conductive inks ahead of 2026 registration deadlines. European importers are demanding full substance dossiers from Asian film manufacturers, compressing supplier qualification pools. Building-integrated photovoltaic module assemblers in the Netherlands and Denmark are most exposed, accelerating in-house toxicology testing investment.
Fleet operators are consolidating transparent display procurement through direct OEM supply agreements, bypassing traditional electronics distributors. Automotive purchasing departments are mandating decade-long price-volume commitments with indexed raw material adjustments. This pattern is most visible in German premium OEM programs, where procurement teams are absorbing transparent OLED sourcing from tier-1 cockpit integrators.
Transparent Electronics Market Segmentation
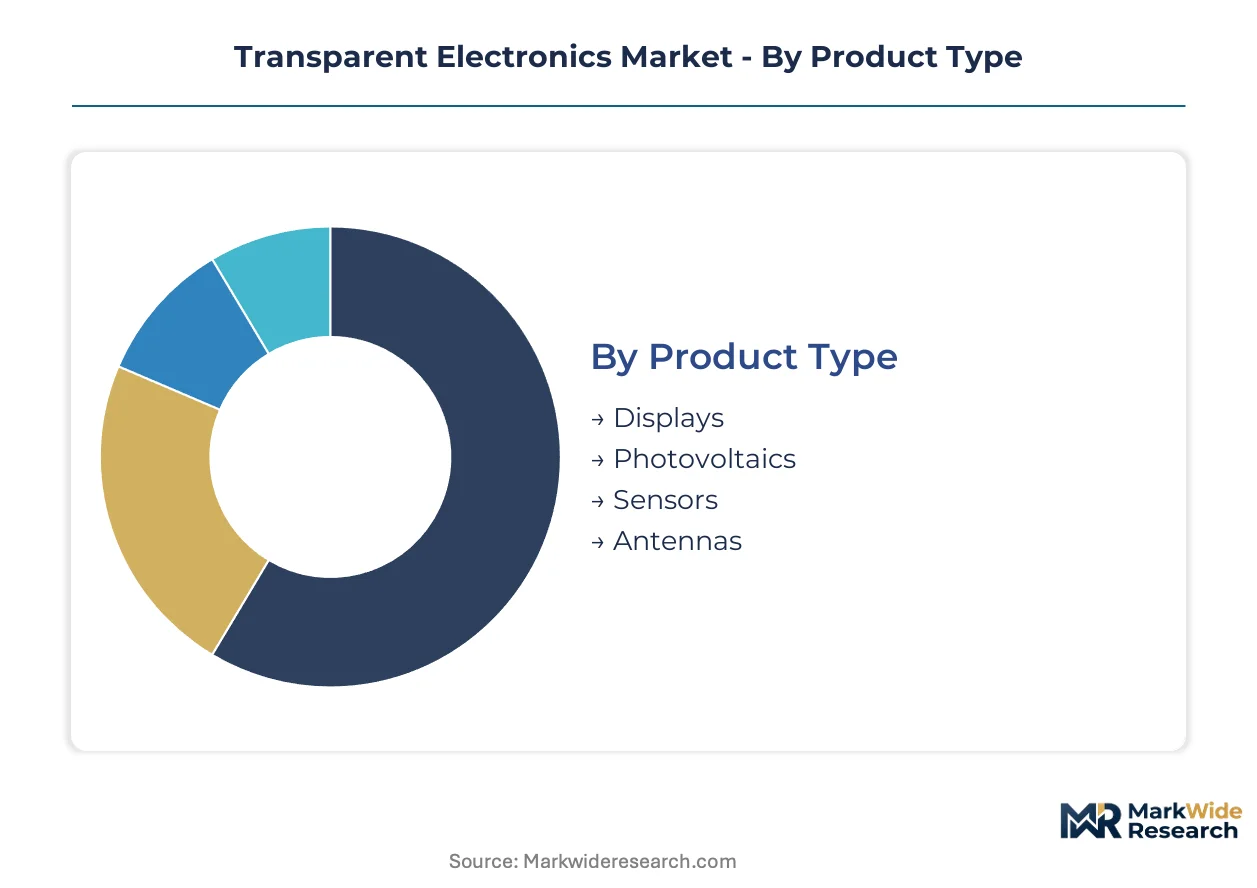
Transparent electronics demand fragments across four distinct category systems, each mapping different value capture points in the supply chain. Product type segmentation reveals where manufacturing scale concentrates, while technology and application splits expose which end-uses are driving specification changes and procurement timelines.
Product Type:
The use-case spectrum spans visual output, energy harvesting, environmental sensing, and signal transmission, with each segment imposing different substrate and electrode requirements.
- Displays:Transparent OLED and LCD panels achieve optical transmittance above 70% through indium tin oxide or silver nanowire conductive layers. Automotive OEMs in Germany and South Korea are embedding these into windshields and instrument clusters, compressing supplier qualification cycles to match vehicle platform timelines.
- Photovoltaics:Building-integrated solar glass incorporates transparent electrodes to generate electricity without obstructing sightlines. Commercial construction codes in Germany and Japan are mandating this integration, pulling demand from purely aesthetic glazing toward dual-function architectural systems.
- Sensors:Transparent capacitive and piezoelectric devices enable touch and pressure detection on see-through surfaces.
- Antennas:Windshield-embedded radio frequency elements maintain optical clarity while transmitting cellular and navigation signals.
The dominant share belongs to Displays, while Photovoltaics is closing the gap fastest.
Technology:
Cost tier differentiation separates vacuum-processed legacy systems from roll-to-roll printable alternatives that slash capital requirements.
- Transparent Conductive Films:Indium tin oxide alternatives command premium pricing from supply-constrained silver nanowire and carbon nanotube formulations. REACH restrictions on hazardous nanomaterial classifications are forcing reformulation of carbon nanotube conductive inks ahead of registration deadlines.
- Organic Photonic:Solution-processed organic semiconductors enable low-temperature fabrication on flexible plastic substrates. South Korean fabrication lines in Gumi and Paju are achieving yield rates that lower unit economics for automotive qualification programs.
- Holography:Diffractive optical elements project three-dimensional imagery without physical screens.
- Nanoelectronics:Graphene and carbon nanotube transistors promise mechanical flexibility with electronic performance.
Transparent Conductive Films capture the deepest margin pool, though Organic Photonic is expanding most quickly as display manufacturers seek lower thermal budgets.
Application:
Customer type stratification separates high-volume consumer shipments from low-volume, high-specification automotive and architectural contracts.
- Automotive Displays:Tier-1 suppliers are qualifying transparent OLED panels for dashboard and windshield integration under combined thermal and crash-safety protocols. Korea's Ministry of Trade, Industry and Energy energy efficiency standards and OEM testing requirements are duplicating validation expenditure.
- Consumer Electronics:Smartphones and televisions incorporate transparent screens for aesthetic differentiation and augmented reality overlays.
- Smart Windows:Electrochromic and suspended particle devices modulate light transmission for building climate control.
- Wearable Devices:Head-mounted displays and smart glasses demand lightweight, flexible transparent electronics.
Automotive Displays command the highest unit values, while Smart Windows is gaining share fastest on building code mandates.
End User:
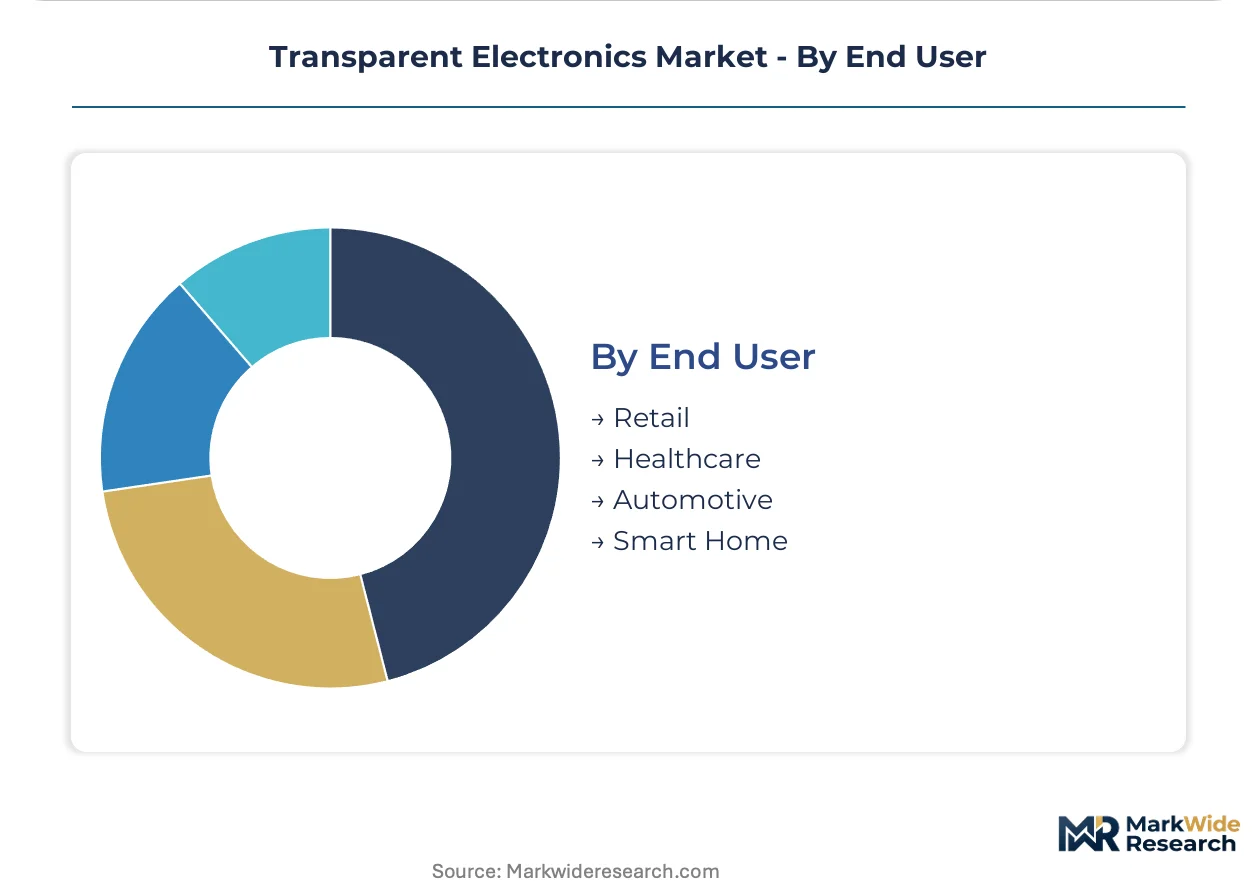
Volume concentration varies sharply, with automotive and smart home procurement consolidating through direct OEM agreements while healthcare and retail fragment across smaller installations.
- Automotive:Fleet operators are consolidating transparent display procurement through decade-long price-volume commitments with indexed raw material adjustments. This pattern is most visible in German premium OEM programs.
- Smart Home:Residential construction is integrating transparent control panels and photovoltaic windows into net-zero building designs.
- Healthcare:Surgical displays and transparent monitoring surfaces require sterilization-compatible transparent electrode formulations.
- Retail:Point-of-sale and advertising installations utilize transparent screens for product visualization.
Automotive holds the dominant procurement scale, while Smart Home is climbing the fastest on energy efficiency policy convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors South Korea's transparent electronics export corridor, handling specialized display panel shipments bound for German automotive assembly plants and Japanese architectural glass fabricators. This maritime infrastructure underwrites the country's dominance in transparent OLED volume manufacturing.
South Korea
Automotive OEMs in Gumi and Paju source transparent OLED panels for windshield-integrated instrument clusters. Korea's Ministry of Trade, Industry and Energy enforces energy efficiency standards that compress product certification timelines. Samsung Display operates dedicated fabrication lines serving both consumer electronics and vehicle-grade display contracts.
Germany
Premium automotive manufacturers in Munich and Stuttgart embed transparent dashboards into electric vehicle platforms under decade-long procurement agreements. The EU F-Gas Regulation tightens material specifications for fluorinated compounds in conductive film production. BASF and Merck KGaA supply specialized chemical formulations for transparent electrode substrates from Ludwigshafen.
United States
Corning Incorporated manufactures alkali-free glass substrates in Kentucky and New York for thin-film transistor processing. The EPA regulates indium compounds under TSCA reporting requirements, extending compliance timelines for transparent conductive material imports. Aviation retrofit programs in Seattle and Dallas specify transparent OLED cabin partitions.
Japan
Building-integrated photovoltaic mandates in Tokyo and Osaka pull transparent electrode demand toward dual-use solar glass architectures. METI commercial construction codes require solar integration in new commercial buildings. AGC Inc. and Nippon Electric Glass operate specialized substrate coating facilities in Kansai.
China
BOE Technology Group leverages government-backed capacity expansions in Beijing and Hefei to undercut Korean pricing on transparent display panels. MIIT dual-carbon policy mandates align procurement criteria around embodied carbon in electronics manufacturing. Silver nanowire deposition lines in Shenzhen serve automotive tier-1 suppliers.
Transparent Electronics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in substrate and conductive film layers. The market structure concentrates around three strategic archetypes: captive display conglomerates with in-house fabrication, government-backed scale manufacturers, and materials science incumbents controlling thermal stability formulations. Competitive positioning hardens through direct OEM supply agreements and indexed raw material price commitments. Capacity expansion in roll-to-roll coating and thermal simulation capabilities represents the dominant competitive moves.
Among Korean conglomerates, Samsung Electronics Co. Ltd. and LG Electronics Inc. occupy positions as captive display fabricators with automotive qualification programs. Corning Incorporated anchors the substrate specialist tier from its U.S. base. BOE Technology Group Co. Ltd. exemplifies the scale-driven manufacturer archetype leveraging state-supported capacity.
| Leading Market Players |
|---|
| Cambrios Technologies Corp. |
| Panasonic Holdings Corp. |
| Samsung Electronics Co. Ltd. |
| Apple Inc. |
| 3M Company |
| LG Electronics Inc. |
| BOE Technology Group Co. Ltd. |
| ClearLED Ltd. |
| Corning Incorporated |
| Others |
Cost & Logistics Intelligence
Gumi and Paju fabrication clusters anchor global transparent OLED capacity, concentrating thermal simulation expertise and vehicle-grade certification infrastructure that compresses supplier negotiation leverage for automotive tier-1 buyers. This geographic concentration feeds downstream pricing power toward Korean display conglomerates while forcing procurement departments into decade-long indexed commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade transparent OLED panels with dual certification from consumer displays and architectural glazing films. Price differentiation rests on thermal stability performance and crash-safety validation tiers. Cost compression in standard-grade conductive films is intensifying because silver nanowire deposition eliminates vacuum sputtering equipment requirements. Fleet operators exhibit lowest price sensitivity due to platform-locked sourcing, while retail signage installers face acute margin pressure from commoditized LCD alternatives.
Supply Chain Analysis
Export control regimes limiting rare earth flows expose transparent electrode supply to indium concentrate restrictions from Chinese zinc smelting byproduct recovery. Manufacturing gravity centers on South Korea, China, and Japan for substrate coating and display module assembly. Raw material dependencies span refined indium, alkali-free borosilicate glass, and silver nanowire ink formulations. Single-source vulnerability concentrates in indium tin oxide precursor chemicals. Distribution runs through direct OEM supply agreements that bypass traditional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive procurement consolidation through fleet operator direct agreements has shifted buyer power toward German premium OEMs and Korean vehicle platforms, fragmenting tier-1 cockpit integrator margins.
For Market Incumbents: Entrench vehicle-grade certification moats by deepening thermal simulation capabilities for 85°C operating environments and securing captive silver nanowire deposition capacity ahead of REACH nanomaterial registration deadlines. Micro-LED transparent modules threaten OLED technology lock-in for premium automotive contracts. For New Entrants and Emerging Players: Establish a beachhead in aviation cabin retrofit specifications for transparent OLED partitions, where qualification cycles remain nascent and incumbent concentration is lowest. India's PLI scheme for electronics manufacturing offers tariff-advantaged substrate assembly capacity outside East Asian supply concentration. Lead with roll-to-roll coating partnerships rather than capital-intensive fabrication investments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors materials science incumbents controlling alkali-free glass thermal stability formulations over display-integrated assemblers facing margin compression. Five-to-ten year viability hinges on substitution timelines for indium-dependent transparent electrodes. Watch silver nanowire yield rate convergence against indium tin oxide cost baselines as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Program Investment | Dual certification under Korea's MOTIE standards and OEM crash-safety protocols secures decade-long supply agreements. |
| Silver Nanowire Deposition Scale-Up | Roll-to-roll coating capacity eliminates vacuum sputtering capital barriers and collapses transparent electrode unit economics. |
| Backward Integration into Substrate Glass | Captive alkali-free borosilicate supply insulates against Corning's thermal stability formulation dominance. |
| Aviation Cabin Retrofit Partnership | Airlines specifying transparent OLED window overlays open a channel outside automotive procurement consolidation. |
| REACH Nanomaterial Compliance Investment | European hazardous substance dossier preparation extends supplier qualification pools for carbon nanotube ink formulations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC manufacturing capex disclosures, Korean MOTIE energy efficiency certification databases, and EU ECHA REACH registration filings. Display panel procurement directors, automotive tier-1 supplier quality engineers, and conductive film plant managers provided operational data. Bottom-up capacity modeling triangulates against top-down demand segmentation across automotive, architectural, and consumer electronics verticals.
Forecast inputs span transparent OLED yield rate trajectories, silver nanowire deposition cost curves, and building-integrated photovoltaic code adoption timelines across the projection horizon. Segmentation dimensions include product type, technology tier, application vertical, and end-user procurement concentration. CAGRs derive from installed base replacement cycles and new platform penetration assumptions. Indium price volatility and fluorinated compound substitution timelines represent critical sensitivity inputs.
Stress conditions across rare earth export control severity, REACH nanomaterial classification stringency, and micro-LED optical transmittance parity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around automotive platform adoption curves and commercial construction mandate enforcement. Material shifts in indium concentrate trade policy or transparent electrode technology substitution would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Roll to Roll Flexible Electronics Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Flexible Electronics Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market