
 Methyl Phenyl Silicone Resin Market | 2026-2036
Methyl Phenyl Silicone Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Phenyl Silicone Resin Market Analytics
Modular formulation kits that separate base resin, phenyl ratio modifiers, and catalyst packages are broadening procurement options for mid-size coating houses. Wacker Chemie AG leverages its integrated siloxane feedstock position to sustain cost discipline across phenyl-modified grades. Dow competes through geographic breadth in liquid silicone resin distribution, while Shin-Etsu Chemical Co., Ltd. anchors high-purity solid resin output for Japanese electronics laminators.
Methyl phenyl silicone resin comprises siloxane backbones with methyl and phenyl substituents, typically containing 5–50 mol% phenyl content to achieve thermal stability exceeding 250°C and ultraviolet resistance for protective coatings. The material functions primarily as a binder and film-former in high-performance applications where standard dimethyl silicones degrade. Coatings applications lead volume absorption due to sustained aerospace and industrial maintenance spending, while elastomers represent the fastest-expanding category as electric vehicle battery module manufacturers adopt phenyl silicone thermal interface materials. Solid-form resin concentrates margin pools because powder handling and precise phenyl content control command formulation premiums over commodity liquid grades.
REACH registration requirements administered by ECHA govern phenyl-containing siloxane imports into the European Union, compelling non-European suppliers to maintain exhaustive substance dossiers. EPA New Chemicals Program notifications in the United States and China's MEE environmental impact assessments for new silicone resin facilities add compliance layers that filter smaller entrants from cross-border supply. GB standards issued by SAMR specify phenyl content testing protocols for domestic Chinese sales, creating a dual-track certification burden for multinational producers. Stakeholders must monitor how tightening per- and polyfluoroalkyl substance restrictions in major jurisdictions redirect demand toward phenyl silicone alternatives in non-stick and protective coating formulations.
Market Dynamics
Phenyl-modified silicone resin procurement is tightening around aerospace certification requirements and REACH-compliant low-emission formulations, forcing coating houses to requalify supply chains around phenyl content precision and volatile organic compound thresholds.
Growth Catalysts
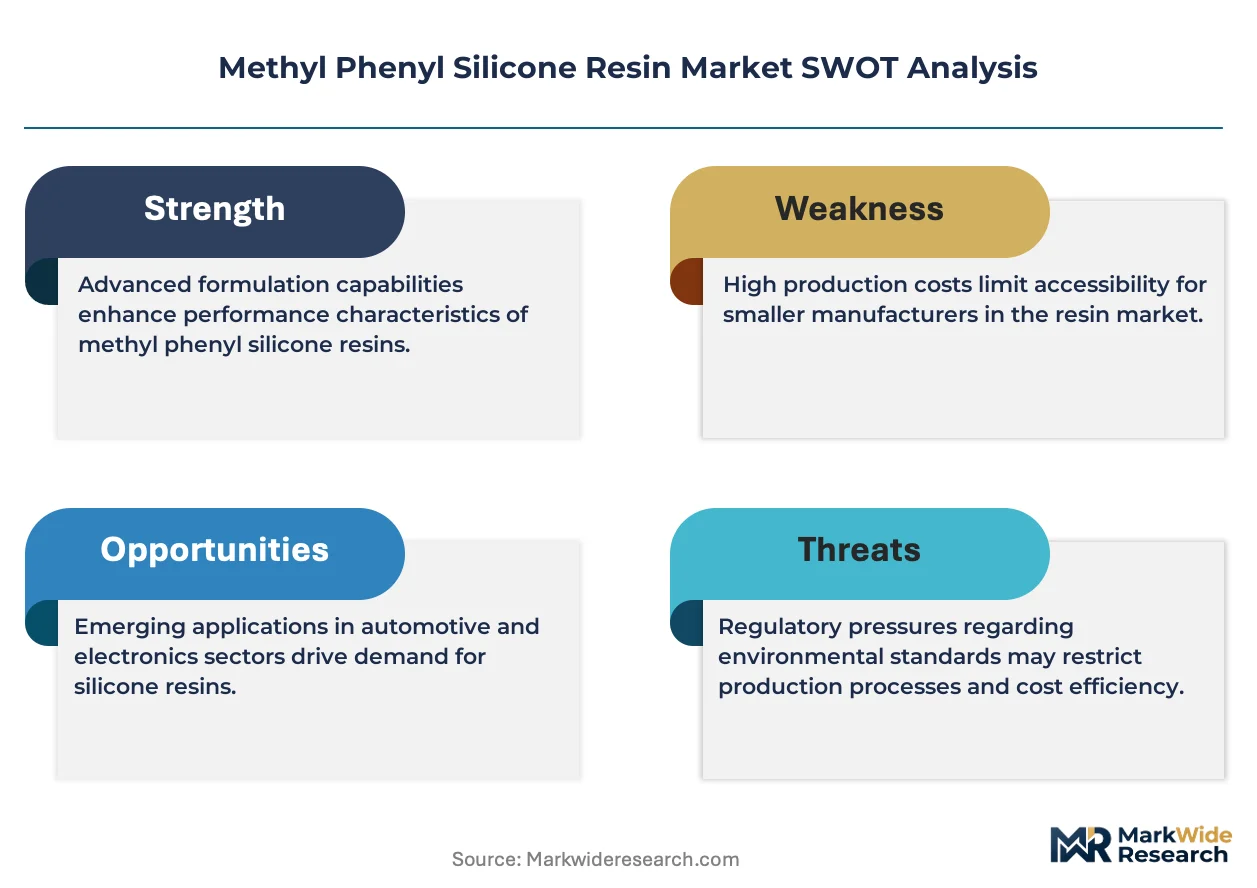
- REACH Phase-In Substances:ECHA registration deadlines for phenyl-containing siloxanes are filtering non-compliant imports, creating volume consolidation for registered European suppliers.
- Aerospace Thermal Management:Engine and airframe manufacturers in Germany, Japan, and the United States are expanding specifications for coatings exceeding 250°C service temperatures.
- Electric Vehicle Battery Modules:Thermal interface material adoption is pulling phenyl silicone elastomer demand from laminators serving Korean and Chinese cell producers.
Market Restraints
- Phenyl Precursor Volatility:Chlorophenylsilane and methylphenylchlorosilane feedstock costs swing with benzene and silicon metal pricing, compressing margin predictability for formulators.
- Jiangsu-Zhejiang Supply Concentration:East China's dominance in domestic silicone resin output creates geographic risk exposure for coating houses dependent on export-oriented Chinese producers.
- Per- and Polyfluoroalkyl Substitution Limits:PFAS restrictions in protective coatings are redirecting some demand toward phenyl silicones, but technical performance gaps in extreme non-stick applications limit full displacement.
Strategic Opportunities
- Modular Formulation Kits:Separated base resin, phenyl ratio modifiers, and catalyst packages are opening procurement flexibility for mid-size coating houses previously locked into integrated supplier relationships.
- Solid-Form Resin Premiumization:Powder handling and precise phenyl content control command formulation premiums over commodity liquid grades, concentrating margin pools with specialty producers.
- EPA New Chemicals Program:Notification pathways for phenyl-modified siloxanes are creating first-mover advantage for suppliers establishing pre-manufacture data packages in the United States.
Industry Challenges
- Dual-Track Certification Burden:Multinational producers must maintain both GB standards compliance for SAMR phenyl content testing in China and REACH dossiers for ECHA, stretching regulatory affairs capacity.
- Phenyl Content Precision:Electronics laminators demand tighter than ±2 mol% phenyl specification control, requiring capital investment in analytical infrastructure that smaller resin houses struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Phenyl Silicone Resin Market |
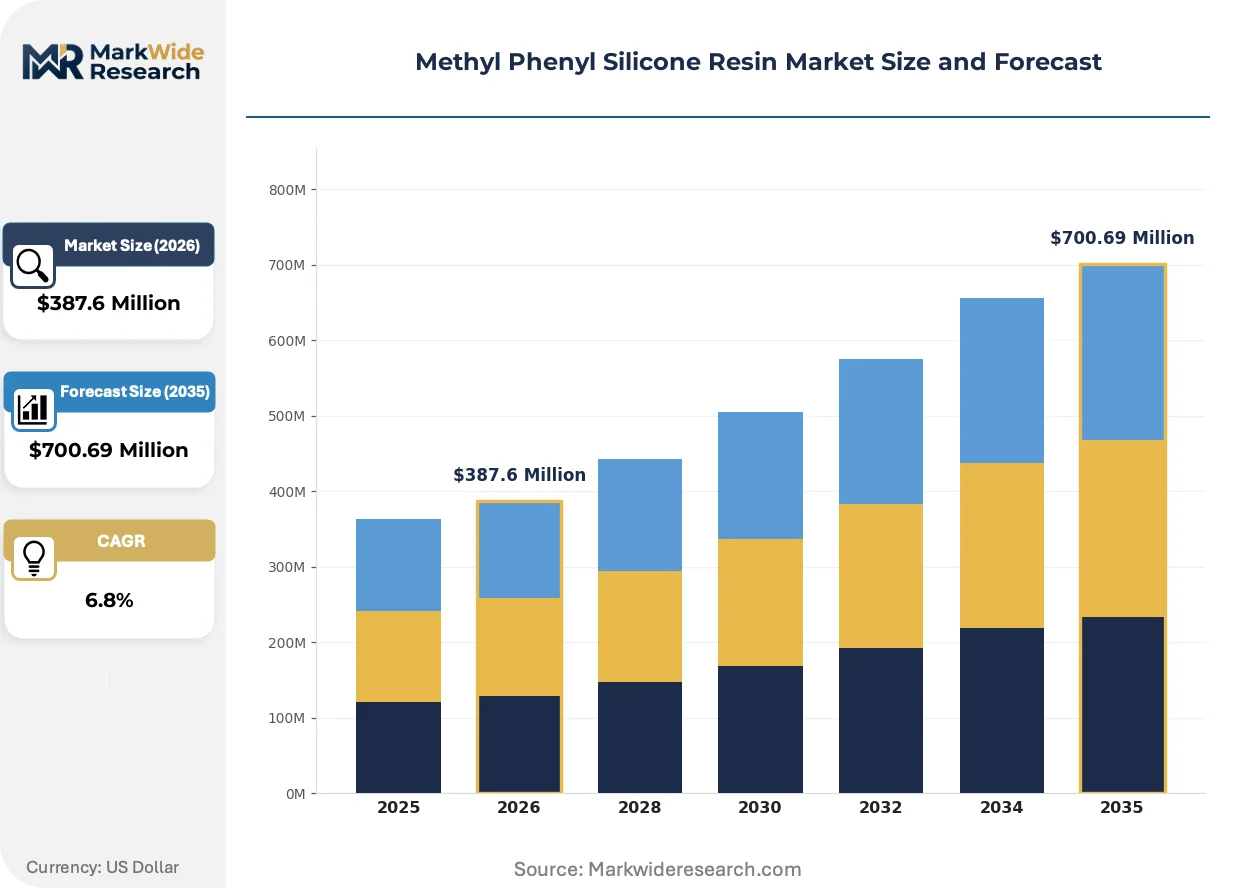
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Adhesives, Sealants, Elastomers End Use Industry: Construction, Automotive, Electronics, Aerospace Form: Liquid, Solid, Gel, Powder Application: Thermal Insulation, Electrical Insulation, Surface Protection, Waterproofing |
| Companies Covered | Wacker Chemie AG, Evonik Industries AG, Dow, Shin-Etsu Chemical Co., Ltd., Momentive, Elkem, SiSiB SILICONES, Genesee Polymers Corporation, Siltech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Phenyl Silicone Resin Market Evolving Landscape
Formulation architecture is fragmenting as buyers separate resin, modifier, and catalyst procurement, while regulatory tightening around fluorinated alternatives accelerates phenyl silicone qualification in protective coatings.
Solventless phenyl silicone resin systems are absorbing coating house demand previously served by high-VOC dimethyl alternatives. Aerospace maintenance divisions in the United States and Germany are adopting these materials for field repair applications where cure speed and emission control are weighted equally. The technology is absorbing volume from conventional solvent-borne silicones as EPA enforcement tightens around permissible exposure limits.
REACH authorization requirements for phenyl-containing siloxanes are compelling non-European suppliers to maintain exhaustive substance dossiers or exit the European Union market. Industrial coating formulators are consolidating procurement around registered suppliers with active ECHA submissions. Solid resin grades face tighter scrutiny than liquids under substance evaluation work programs, redirecting some laminator demand toward pre-registered liquid alternatives.
Specification-driven procurement is compressing supplier lists as aerospace OEMs consolidate approved material lists around phenyl content certification. Tier-one coating houses are disintermediating smaller resin traders, sourcing directly from integrated siloxane producers with in-house phenyl precursor capability. This concentration is most visible in Japan, where METI-indicated quality standards for electronics laminators have eliminated unqualified import sources from procurement consideration.
Methyl Phenyl Silicone Resin Market Segmentation
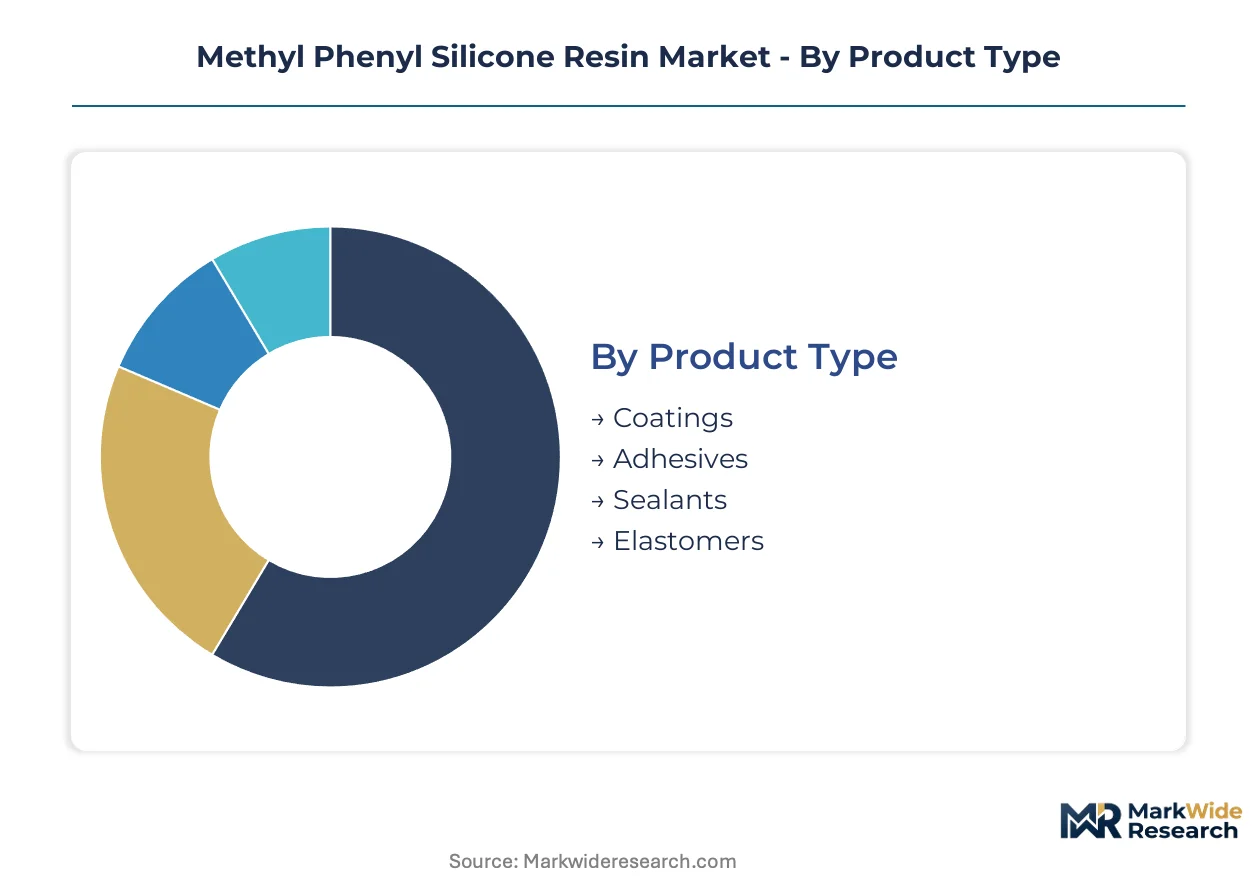
Segmentation in methyl phenyl silicone resin procurement reflects divergent technical requirements across aerospace certification, electronics laminator precision, and coating house formulation flexibility. Buyers prioritize phenyl content control, thermal stability thresholds, and regulatory compliance status when selecting grade specifications.
Product Type:
Customization intensity varies sharply across this category, with aerospace-qualified coatings demanding locked phenyl ratios while modular adhesive systems permit user-side adjustment.
- Coatings:Solventless and solvent-borne formulations serve engine manufacturers in Germany and airframe maintenance divisions in the United States demanding service temperatures above 250°C. Specifications consolidate around REACH-registered suppliers with ECHA dossiers for phenyl-containing siloxanes.
- Elastomers:Thermal interface materials for electric vehicle battery modules absorb the steepest demand climb from Korean and Chinese cell producers. Phenyl silicone elastomers displace dimethyl grades where module operating temperatures exceed conventional silicone limits.
- Adhesives:Bonding applications in electronics laminators require precise rheology control and phenyl content within ±2 mol% tolerance bands.
- Sealants:Construction and industrial maintenance applications favor cost-optimized liquid grades with broader phenyl content ranges.
Leading the category by volume: Coatings. Expanding most quickly: Elastomers.
End Use Industry:
Margin capture concentrates in segments where certification burdens filter supplier pools and phenyl precursor integration commands pricing power.
- Aerospace:Engine and airframe OEMs in Germany, Japan, and the United States specify coatings with documented thermal cycling performance and ECHA-registered substance dossiers. Tier-one coating houses source directly from siloxane producers with captive phenyl precursor supply.
- Electronics:Japanese laminators under METI-indicated quality standards demand solid resin grades with tighter than ±2 mol% phenyl specification control. Capital requirements for analytical infrastructure eliminate smaller resin traders from qualified supplier lists.
- Automotive:Battery module thermal management pulls phenyl silicone demand from Korean and Chinese electric vehicle supply chains.
- Construction:Industrial maintenance coatings favor commodity liquid grades with less stringent phenyl content precision.
Highest margin concentration: Aerospace. Fastest volume climb: Electronics.
Form:
Physical state determines handling infrastructure requirements and phenyl content control precision, with powder systems commanding formulation premiums over commodity liquids.
- Solid:Powder handling systems enable precise phenyl content metering for electronics laminators and aerospace coating houses. Solid grades concentrate margin pools with specialty producers capable of batch-to-batch consistency within tight specification bands.
- Liquid:Pump-and-blend systems suit high-volume coating houses and construction sealant formulators seeking procurement flexibility.
- Gel:Intermediate viscosity grades serve niche thermal interface and potting applications.
- Powder:Micronized solid resin enables dry-blend formulation kits for mid-size coating houses.
Premium pricing attaches to: Solid. Broadest volume base: Liquid.
Application:
Functional performance requirements segment procurement between specification-driven aerospace and electronics markets versus cost-optimized industrial maintenance.
- Surface Protection:Aerospace airframe and engine coatings in Germany and the United States specify ultraviolet resistance and thermal stability exceeding 250°C. REACH-compliant low-emission formulations displace conventional solvent-borne alternatives under tightening EPA enforcement.
- Thermal Insulation:Electric vehicle battery module manufacturers adopt phenyl silicone thermal interface materials for cell-to-cell and module-to-chassis heat dissipation.
- Electrical Insulation:Electronics laminators specify phenyl-modified silicones for high-temperature circuit board protection.
- Waterproofing:Construction and marine applications favor cost-optimized grades with standard phenyl content ranges.
Deepest specification control required: Surface Protection. Steepest demand trajectory: Thermal Insulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East China's silicone resin foundries supply coating houses worldwide, while German and Japanese aerospace manufacturers drive specification-grade demand. Consumption concentrates in industrial clusters where REACH compliance and thermal certification requirements filter supplier access.
United States
Airframe maintenance divisions in California and Texas specify solventless phenyl silicone coatings for field repair applications. EPA New Chemicals Program notifications create compliance thresholds that registered suppliers navigate. Aerospace OEMs in the Pacific Northwest consolidate approved material lists around phenyl content certification.
Germany
Engine manufacturers in Bavaria and Baden-Württemberg procure coatings exceeding 250°C service temperatures for thermal management. ECHA registration deadlines for phenyl-containing siloxanes filter non-compliant imports. Industrial coating houses in North Rhine-Westphalia requalify supply chains around REACH-compliant low-emission formulations.
China
Domestic silicone resin output from Jiangsu and Zhejiang provinces serves electronics foundries and export coating houses. SAMR's GB standards specify phenyl content testing protocols for domestic sales. Yangtze River Delta manufacturers face MEE environmental impact assessments for new resin facilities.
Japan
Electronics laminators under METI-indicated quality standards demand solid resin grades with tight phenyl specification control. Kanto and Kansai regions concentrate precision resin consumption for circuit board protection. Tier-one coating houses source directly from integrated siloxane producers with captive phenyl precursor supply.
South Korea
Battery module manufacturers in Seoul Capital Area adopt phenyl silicone thermal interface materials for electric vehicle supply chains. Domestic laminators pull elastomer demand from cell producers requiring module operating temperature resilience. Busan-Ulsan industrial corridors concentrate thermal management material formulation.
Methyl Phenyl Silicone Resin Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across phenyl-modified silicone resin supply. Market structure tilts toward consolidation as aerospace certification and REACH compliance elevate barriers for smaller traders. Three archetypes dominate: integrated siloxane producers with captive phenyl precursor supply, specialty resin houses commanding formulation premiums, and regional distributors serving cost-optimized industrial segments. Competitive dynamics center on backward integration into phenyl chlorosilane feedstock and geographic expansion of ECHA-registered substance dossiers.
Within the integrated producer tier, Wacker Chemie AG anchors European supply through its siloxane feedstock position, while Dow exemplifies geographic breadth in liquid resin distribution. Shin-Etsu Chemical Co., Ltd. occupies a position in high-purity solid resin output for precision electronics applications. These three represent the archetype of producers leveraging upstream control over phenyl precursors to sustain margin discipline across modified grades.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Evonik Industries AG |
| Dow |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive |
| Elkem |
| SiSiB SILICONES |
| Genesee Polymers Corporation |
| Siltech Corporation |
| Others |
Value Network & Pricing Analysis
Aerospace OEM consolidation around REACH-registered phenyl content certification is forcing coating houses to absorb premium pricing for qualified supply, compressing procurement flexibility and elevating cost pass-through to downstream formulators.
Pricing Analysis
Margin tightening in solid-form resin reflects benzene and silicon metal feedstock volatility coupled with capital-intensive phenyl content precision requirements. Three-tier pricing structure across aerospace-certified, electronics-laminator, and industrial-commodity grades separates specification control premiums from volume-liquid alternatives. Cost-down pressure on liquid grades accelerates because Jiangsu-Zhejiang export houses compete for coating house procurement. Construction sealant formulators exhibit highest price sensitivity, while Japanese electronics laminators under METI standards tolerate premium positioning for batch-to-batch consistency.
Supply Chain Analysis
Phenyl chlorosilane feedstock supply rests on German, Chinese, and Japanese specialty chemical producers with captive silicon metal and benzene integration. Methyl phenyl silicone resin manufacturing draws from chlorophenylsilane precursors, high-purity silicon metal, and aromatic hydrocarbon inputs. Single-source vulnerability concentrates in East China's Jiangsu-Zhejiang corridor where environmental compliance tightening threatens capacity expansion. Distribution runs through direct OEM-supplier relationships for aerospace and electronics tiers, with regional distributors serving cost-optimized industrial maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phenyl precursor integration capacity and ECHA dossier maintenance burdens are filtering marginal suppliers, propping pricing power for registered incumbents with backward integration into chlorosilane feedstock.
For Market Incumbents: Cement supply security through captive chlorophenylsilane production or long-term offtake agreements with benzene-silicon metal integrators. Deepen analytical infrastructure investment to maintain sub-±2 mol% phenyl specification control demanded by Japanese electronics laminators under METI quality standards. Defensive positioning against modular formulation kit disruptors requires locking coating houses into integrated resin-modifier-catalyst bundles rather than componentized procurement. For New Entrants and Emerging Players: Launch via solventless phenyl silicone systems targeting EPA-compliant field repair applications in United States airframe maintenance divisions, where emission enforcement creates procurement switching costs. White-space exists in solid-form micronized powder grades for mid-size coating houses seeking dry-blend formulation flexibility absent capital-intensive liquid handling infrastructure. Korean battery module thermal interface materials represent the most penetrable elastomer segment given steepest demand trajectory from cell producers. For Investors and Strategic Acquirers: The window for entry favors integrated siloxane producers with captive phenyl precursor supply and active ECHA substance dossiers, as regulatory compliance costs escalate beyond standalone resin house capabilities. Long-term viability across the projection horizon hinges on backward integration depth and aerospace certification portfolio breadth. Watch ECHA authorization list expansions for phenyl-containing siloxanes as inflection indicator for supply consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenyl Chlorosilane | Captive feedstock supply insulates margin from benzene-silicon metal volatility for German and Chinese producers. |
| ECHA Dossier Expansion | Registration breadth secures European Union market access as authorization deadlines filter non-compliant imports. |
| Solid-Form Resin Capacity Addition | Powder handling infrastructure captures formulation premiums from Japanese electronics laminators demanding precision control. |
| Solventless System Development | Low-VOC formulations absorb coating house demand as EPA enforcement tightens permissible exposure limits. |
| Modular Formulation Kit Launch | Separated component packaging opens procurement flexibility for mid-size coating houses previously locked into integrated supply. |
Research Methodology
Trade databases, ECHA registration filings, and SEC chemical segment disclosures formed the secondary backbone, cross-referenced with primary interviews involving silicone resin plant managers, aerospace coating procurement leads, electronics laminator technical directors, and specialty chemical distribution channel partners. Bottom-up volume estimates from phenyl chlorosilane feedstock throughput and top-down demand validation from end-use industry spending patterns were triangulated to establish market sizing.
Historical trendline analysis across silicone resin production volumes, phenyl content specification evolution, and regulatory compliance cost trajectories informed the projection framework. Segmentation modeling incorporated grade tier, end-use industry, physical form, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines, with specific weighting applied to electric vehicle battery module thermal interface adoption rates and aerospace maintenance spending cycles.
Feedstock price volatility, ECHA authorization list expansions, and Chinese environmental enforcement intensity are the dominant revision risks to the forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Zinc Oxide Nanoparticles Market