
 Train Collision Avoidance System Market | 2026-2036
Train Collision Avoidance System Market Size, Share, and Industry Trends Forecast 2026-2036
Train Collision Avoidance System Market Analysis
Project finance structures tied to rail infrastructure concessions is rewriting competitive entry barriers for collision avoidance technology. Siemens AG leverages its signaling-to-rolling-stock integration to anchor large European deployment programs. Alstom competes through its ERTMS-certified portfolio across multiple continental networks. Wabtec Corporation dominates the North American freight retrofit segment with its PTC-derived platform architecture.
A train collision avoidance system comprises sensor fusion arrays, onboard processing units, and communication links that continuously monitor track occupancy, speed limits, and moving block authorities to enforce automatic braking when human operators fail to respond. Radar systems currently lead installed volumes due to proven all-weather reliability, while camera systems represent the fastest-expanding category as convolutional neural networks improve obstacle classification accuracy. Among applications, high-speed trains command premium pricing because their braking distance requirements demand sub-second latency architectures, whereas freight trains generate volume through regulatory-mandated positive train control retrofits across aging locomotive fleets.
The Federal Railroad Administration enforces PTC compliance timelines that shape North American procurement schedules, while the European Union Agency for Railways certifies ERTMS baseline upgrades that determine product interoperability across member states. China's National Railway Administration issues GB standards that localize foreign supplier designs before network approval. Stakeholders must monitor how jurisdictional certification fragmentation affects platform development costs as systems migrate from siloed national standards toward modular, multi-territory architectures.
Market Dynamics
Sensor fusion architectures are compressing system latency requirements while national certification regimes fragment platform development roadmaps across multiple rail networks.
Growth Catalysts
- ERTMS Baseline 3 Mandate:The European Union Agency for Railways mandates interoperable signaling upgrades across member state corridors, forcing technology refresh cycles in Germany, France, and Italy.
- Freight Rail Electrification:Heavy-haul operators in Australia and Brazil are retrofitting collision avoidance systems onto diesel-to-electric conversion programs to meet corridor access requirements.
- Moving Block Signaling:Communications-based train control reduces headway distances on saturated corridors, creating demand for onboard processing units with sub-100-millisecond response cycles.
Market Restraints
- Silicon Carbide Supply Concentration:Power semiconductor fabrication for onboard traction inverters concentrates in East Asian foundries, exposing European and North American system integrators to input bottlenecks.
- Legacy Analog Interlocking:Mechanical relay-based signaling infrastructure in Eastern European and South Asian networks creates technical debt that slows digital overlay deployment.
- Multi-Territory Certification Costs:Separate homologation requirements from China's National Railway Administration, India's Ministry of Railways, and Brazil's ANTT force redundant testing protocols for each market entry.
Strategic Opportunities
- Southeast Asian Greenfield Networks:Vietnam and Indonesia are constructing new standard-gauge corridors without legacy signaling inheritance, enabling native digital signaling from commissioning.
- Urban Rail Autonomy:Driverless metro systems in Saudi Arabia's Riyadh Metro and UAE's Dubai Route 2020 extension create demand for camera-radar fusion with pedestrian intrusion detection.
- Battery-Electric Multiple Units:Regional rail electrification gaps in Scotland, Wales, and rural Japan are accelerating orders for self-powered trains with integrated collision avoidance.
Industry Challenges
- Functional Safety Engineering Talent:SIL-4 software verification expertise concentrates among a small pool of specialists in France, Germany, and Japan, constraining development bandwidth for new entrants.
- Obsolescence Management:Microprocessor architectures certified to EN 50129 safety standards face end-of-life discontinuation before rail-specific re-certification cycles complete.
- Cross-Border Interoperability Testing:France-Belgium-Germany corridor operators must reconcile diverging national implementation rules for identical ERTMS hardware specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Collision Avoidance System Market |
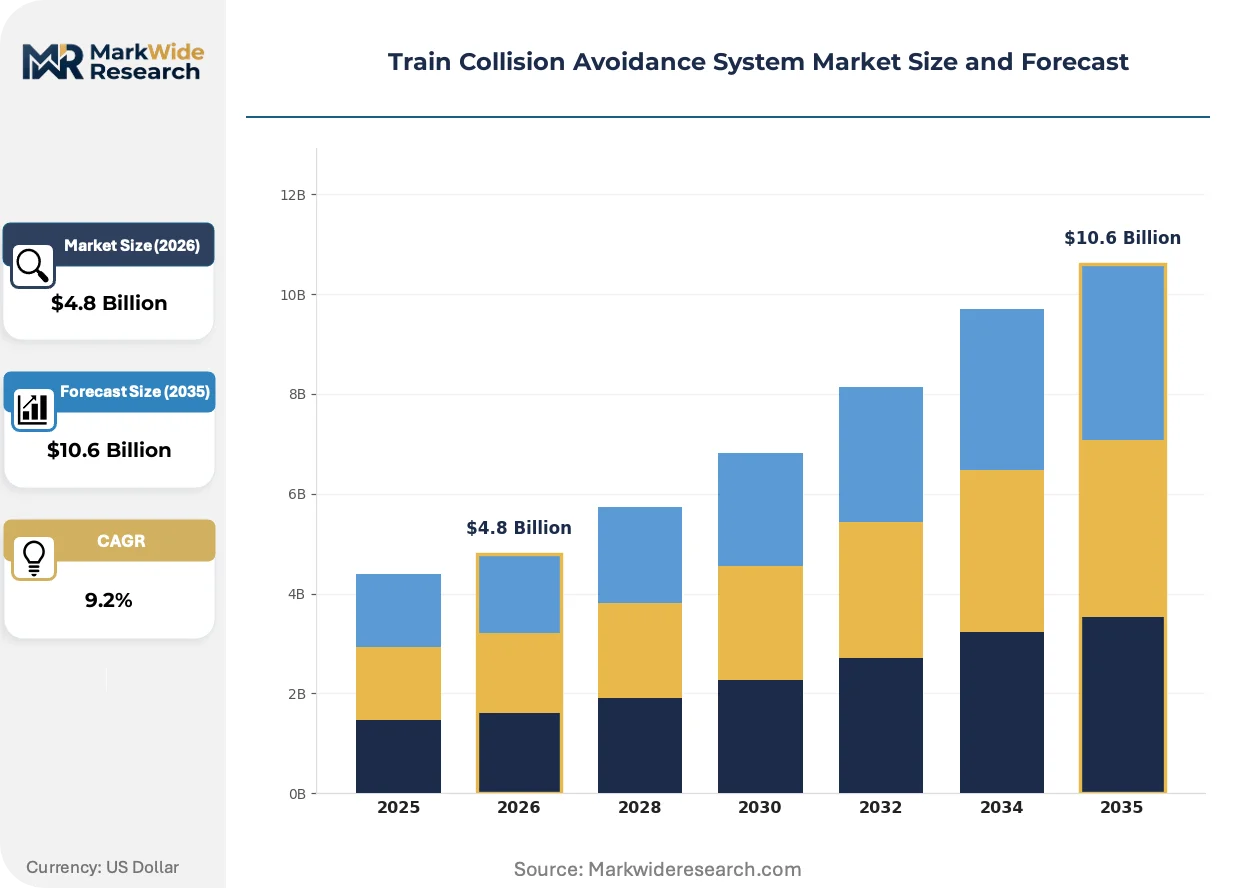
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar Systems, LIDAR Systems, Camera Systems, Ultrasonic Sensors Application: Intercity Trains, Commuter Trains, Freight Trains, High-Speed Trains End User: Railway Operators, Government Bodies, Private Companies, Logistics Providers Installation Type: Trackside Systems, Onboard Systems, Retrofit Solutions, Integrated Systems |
| Companies Covered | Thales Group, Knorr-Bremse AG, Siemens AG, CRRC Corporation Limited, Bombardier, Alstom, Wabtec Corporation, HBL Power Systems Ltd., Hitachi Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Collision Avoidance System Market Emerging Trajectories
Convolutional neural networks are redefining obstacle classification accuracy while edge computing architectures migrate processing from centralized interlockings to distributed onboard units.
Radar-lidar sensor fusion is hybridizing environmental perception for all-weather operation. High-speed operators in Spain's Madrid-Barcelona corridor and China's Beijing-Xi'an line are piloting fused arrays that maintain detection integrity through sandstorms and heavy precipitation. This convergence is hybridizing procurement specifications, as buyers now specify performance envelopes rather than sensor modalities.
The EU AI Act's risk classification framework is imposing documentation burdens on machine-learning components within safety-critical systems. European train control suppliers must now maintain algorithmic audit trails and explainability protocols for obstacle detection neural networks. High-speed rail OEMs are responding by segregating safety-critical braking logic from AI-enhanced advisory functions.
Performance-based maintenance contracts are displacing time-based service agreements in Nordic and Alpine rail networks. Swedish and Norwegian operators now compensate system integrators on availability metrics rather than scheduled inspections. This shift concentrates most visibly in Stockholm's commuter rail and Oslo's airport express services, where uptime guarantees drive predictive analytics investment.
Train Collision Avoidance System Market Segmentation
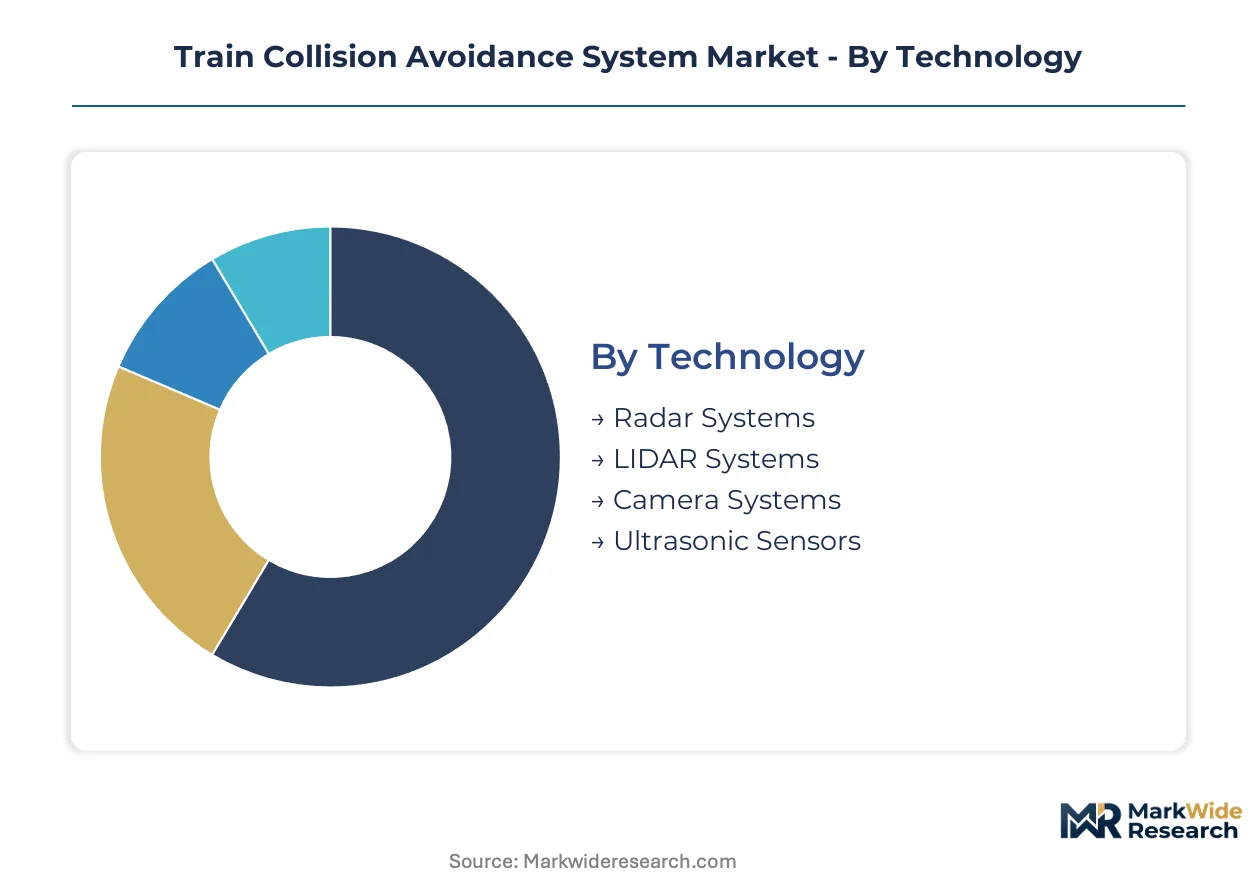
Segmentation in collision avoidance systems reveals how procurement priorities diverge across operational contexts. Technology choices reflect weather resilience requirements, while installation type decisions expose legacy fleet constraints versus greenfield network advantages.
Technology:
Mature sensing modalities dominate installed base volumes, yet emerging perception architectures are capturing specification momentum in new tenders.
- Radar Systems:Millimeter-wave arrays operate reliably through precipitation and particulate interference. Deutsche Bahn's Rhine-Ruhr corridor deployments specify radar as the primary detection layer for all-weather availability.
- Camera Systems:Convolutional neural networks process visual feeds for obstacle classification with improving accuracy. China's Beijing-Shanghai high-speed line pilots camera-radar fusion for pedestrian intrusion detection at grade crossings.
- LIDAR Systems:Time-of-flight laser scanning delivers centimeter-range precision for tunnel clearance verification.
- Ultrasonic Sensors:Short-range proximity detection supports low-speed yard operations and platform docking maneuvers.
Radar handles the majority of throughput; camera systems are expanding most quickly on specification share.
Application:
Operational speed regimes create divergent latency and braking distance requirements that shape system architecture selection.
- High-Speed Trains:Sub-second response architectures enforce automatic braking across 300+ km/h operating envelopes. Spain's Madrid-Barcelona corridor mandates triple-redundant processing chains for SIL-4 compliance.
- Freight Trains:Positive train control retrofits dominate North American procurement schedules. Union Pacific and BNSF Railway installation programs span thousands of aging locomotives.
- Intercity Trains:Mixed traffic operations require flexible authority management across signaling boundaries.
- Commuter Trains:High-frequency headways demand communications-based train control integration.
Freight retrofits absorb the largest contract values; high-speed installations command the steepest per-unit pricing.
End User:
Procurement authority concentrates with infrastructure owners, yet outsourcing patterns are fragmenting decision-making across operator types.
- Railway Operators:State-owned incumbents in Germany, France, and Japan specify integrated signaling-to-vehicle platforms.
- Government Bodies:Transport ministries in Vietnam and Indonesia fund greenfield corridor construction without legacy signaling inheritance.
- Private Companies:Mining and industrial rail operators in Australia and Brazil specify heavy-haul collision avoidance for captive networks.
- Logistics Providers:Intermodal terminal operators demand yard automation systems with intrusion detection.
Railway operators control the dominant share of capital deployment; private mining and industrial buyers are climbing the fastest as procurement participants.
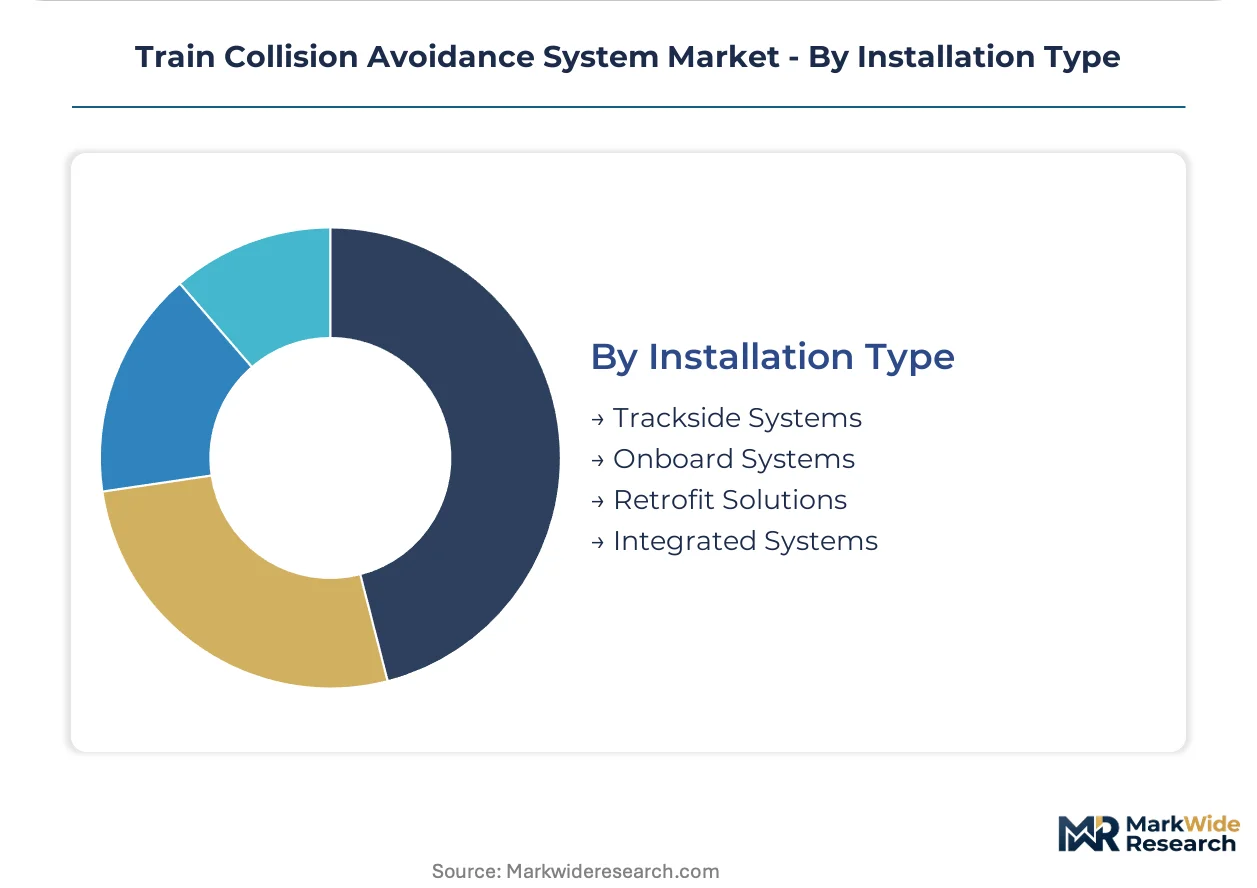
Installation Type:
Physical integration depth determines upgrade complexity and operational disruption exposure for network operators.
- Onboard Systems:Vehicle-mounted processing units and sensor arrays integrate with traction control for automatic brake enforcement. European ERTMS deployment mandates are accelerating onboard unit procurement across multiple national fleets.
- Retrofit Solutions:Aftermarket installation programs address legacy locomotives without factory-integrated safety systems. The Federal Railroad Administration's PTC compliance deadlines compress North American retrofit timelines.
- Trackside Systems:Wayside equipment monitors block occupancy and communicates movement authorities to passing trains.
- Integrated Systems:Factory-installed architectures align collision avoidance with rolling stock design from commissioning.
Retrofit solutions carry the heaviest near-term volume; integrated systems are gaining specification preference for new-build orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union Agency for Railways mandates ERTMS Baseline 3 upgrades across member state corridors, forcing technology procurement cycles in Germany, France, and Italy. China's National Railway Administration issues GB standards that localize foreign supplier designs before network approval. The Federal Railroad Administration enforces PTC compliance timelines that compress North American procurement schedules.
Germany
Deutsche Bahn's Rhine-Ruhr corridor deployments specify radar as the primary detection layer for all-weather availability. The KBA certifies ERTMS baseline upgrades that determine product interoperability across the federal network. Siemens AG anchors large European deployment programs through its signaling-to-rolling-stock integration capabilities.
China
High-speed operators along the Beijing-Shanghai corridor pilot camera-radar fusion for pedestrian intrusion detection at grade crossings. GB standards from the National Railway Administration require localization of foreign supplier designs before network approval. CRRC Corporation Limited dominates rolling stock manufacturing in the Yangtze River Delta cluster.
United States
Freight rail operators including Union Pacific and BNSF Railway execute installation programs spanning thousands of aging locomotives. The Federal Railroad Administration enforces PTC compliance deadlines that shape procurement schedules. Wabtec Corporation dominates the North American freight retrofit segment with its PTC-derived platform architecture.
France
SNCF mandates interoperable signaling upgrades across the Paris-Lyon high-speed corridor under EU directives. The ANSM and national rail safety frameworks certify ERTMS implementations. Alstom competes through its ERTMS-certified portfolio across multiple continental networks.
Japan
East Japan Railway Company and Central Japan Railway Company maintain dense commuter networks requiring sub-100-millisecond response cycles for communications-based train control. METI standards govern industrial safety equipment certification. Hitachi Ltd. supplies integrated signaling systems for the Tokyo-Osaka corridor.
Train Collision Avoidance System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct procurement authority tiers. Siemens AG and Alstom anchor European infrastructure programs through signaling-to-vehicle integration capabilities. Wabtec Corporation dominates North American freight retrofits through regulatory-mandated PTC deployment timelines. Strategic consolidation concentrates among rolling stock manufacturers acquiring signaling specialists, while technology licensing agreements proliferate between sensor fabricators and system integrators.
Within the integrated-systems tier, Siemens AG exemplifies the signaling-to-rolling-stock archetype through its European deployment programs. Alstom occupies a comparable position across multiple continental ERTMS-certified networks. Wabtec Corporation represents the retrofit-specialist archetype dominating North American freight compliance cycles. These three anchors illustrate how certification fragmentation creates divergent competitive positioning across jurisdictional boundaries.
| Leading Market Players |
|---|
| Thales Group |
| Knorr-Bremse AG |
| Siemens AG |
| CRRC Corporation Limited |
| Bombardier |
| Alstom |
| Wabtec Corporation |
| HBL Power Systems Ltd. |
| Hitachi Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in silicon carbide foundries across East Asia is compressing margins for European and North American system integrators while amplifying pricing power for power semiconductor suppliers serving onboard traction inverter architectures.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with SIL-4 software verification commanding substantial premiums over SIL-2 equivalents in tender specifications. Three-tier pricing structure across premium, standard, and economy levels reflects bundling depth: integrated signaling-to-rolling-stock platforms at the top, standalone onboard units in the middle, and retrofit kits with limited warranty at the base. Cost compression in the retrofit segment is intensifying because Federal Railroad Administration compliance deadlines compress procurement timelines for North American freight operators. Private mining rail operators in Australia and Brazil exhibit the highest price sensitivity due to captive network economics, while state-owned high-speed rail incumbents in Germany and Japan demonstrate the lowest sensitivity given safety-critical procurement mandates.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard practice among Tier 1 rolling stock manufacturers, pressuring component suppliers to access supply-chain finance facilities or absorb working capital strain. Geographic concentration centers on Germany and France for signaling system integration, Japan for precision sensor fabrication, and China for rolling stock manufacturing and GB standard localization. Raw material dependencies include silicon carbide substrates for power electronics, millimeter-wave radar modules, and specialized optical components for LIDAR arrays. Single-source vulnerability in East Asian silicon carbide foundries exposes European integrators to allocation risk during capacity crunches. Distribution runs through direct procurement relationships with state railway operators and OEM embedded contracts for factory-installed systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among state-owned railway operators consolidating procurement authority across national networks, fragmenting decision-making leverage for component suppliers and system integrators alike.
For Market Incumbents: Insulate certification assets through accelerated EN 50129 re-certification cycles before legacy microprocessor architectures face end-of-life discontinuation. Deepen backward integration into sensor fusion software stacks to defend against camera-radar module suppliers disintermediating system integrators. Prioritize SIL-4 verification talent retention in France and Germany where functional safety engineering expertise concentrates among scarce specialist pools. For New Entrants and Emerging Players: Pursue greenfield corridor opportunities in Vietnam and Indonesia where native digital signaling procurement lacks legacy analog interlocking technical debt. Target battery-electric multiple unit manufacturers in Scotland and Wales seeking integrated collision avoidance for regional electrification gaps. Lead with performance-based maintenance contract proposals that shift buyer risk to availability guarantees rather than capital equipment sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across urban rail autonomy segments as camera-radar fusion requirements multiply sensor counts per trainset. Acquire specialist firms holding ERTMS Baseline 3 certification credentials that transferable across EU member state networks. Monitor silicon carbide foundry utilization rates as the inflection indicator for input cost pressure transmission through system integrator margins.| Strategic Initiative | Industry Significance |
|---|---|
| ERTMS Baseline 3 Certification Investment | Unlocks interoperable deployment across Germany, France, and Italy under EU mandate. |
| Camera-Radar Sensor Fusion Development | Addresses Beijing-Shanghai corridor requirements for pedestrian intrusion detection. |
| Performance-Based Maintenance Contracting | Aligns integrator incentives with Stockholm commuter rail availability metrics. |
| SIL-4 Software Verification Talent Acquisition | Secures scarce functional safety engineering capacity concentrated in France and Germany. |
| Southeast Asian Greenfield Market Entry | Captures Vietnam and Indonesia standard-gauge corridor construction without legacy inheritance. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with rail signaling executives, rolling stock procurement directors, and ERTMS certification specialists; and secondary validation against Federal Railroad Administration PTC compliance filings, EU Agency for Railways interoperability directives, and National Railway Administration GB standard publications. Bottom-up triangulation across onboard unit shipment volumes and top-down reconciliation against infrastructure concession investment flows anchored market sizing.
Forecast inputs incorporated technology adoption curves across radar, camera, and LIDAR modalities; regulatory compliance timelines for PTC and ERTMS mandates; and fleet replacement cycles for aging North American locomotives. Segmentation dimensions modeled include train speed regime, installation type, and end-user procurement authority structure. CAGRs were derived from elasticity-adjusted penetration rates across the projection horizon, with corridor-specific saturation curves applied to high-density networks in the Rhine-Ruhr and Beijing-Shanghai corridors.
Sensitivities concentrate around regulatory deadline extensions, silicon carbide supply disruptions, and cross-border interoperability testing delays. Forecasts reflect assumptions on certification cycle durations and technology refresh timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
US Tolling Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Digital Shipment Market