
 Global Fourth Party Logistics Market | 2026-2036
Global Fourth Party Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fourth Party Logistics Market Analysis
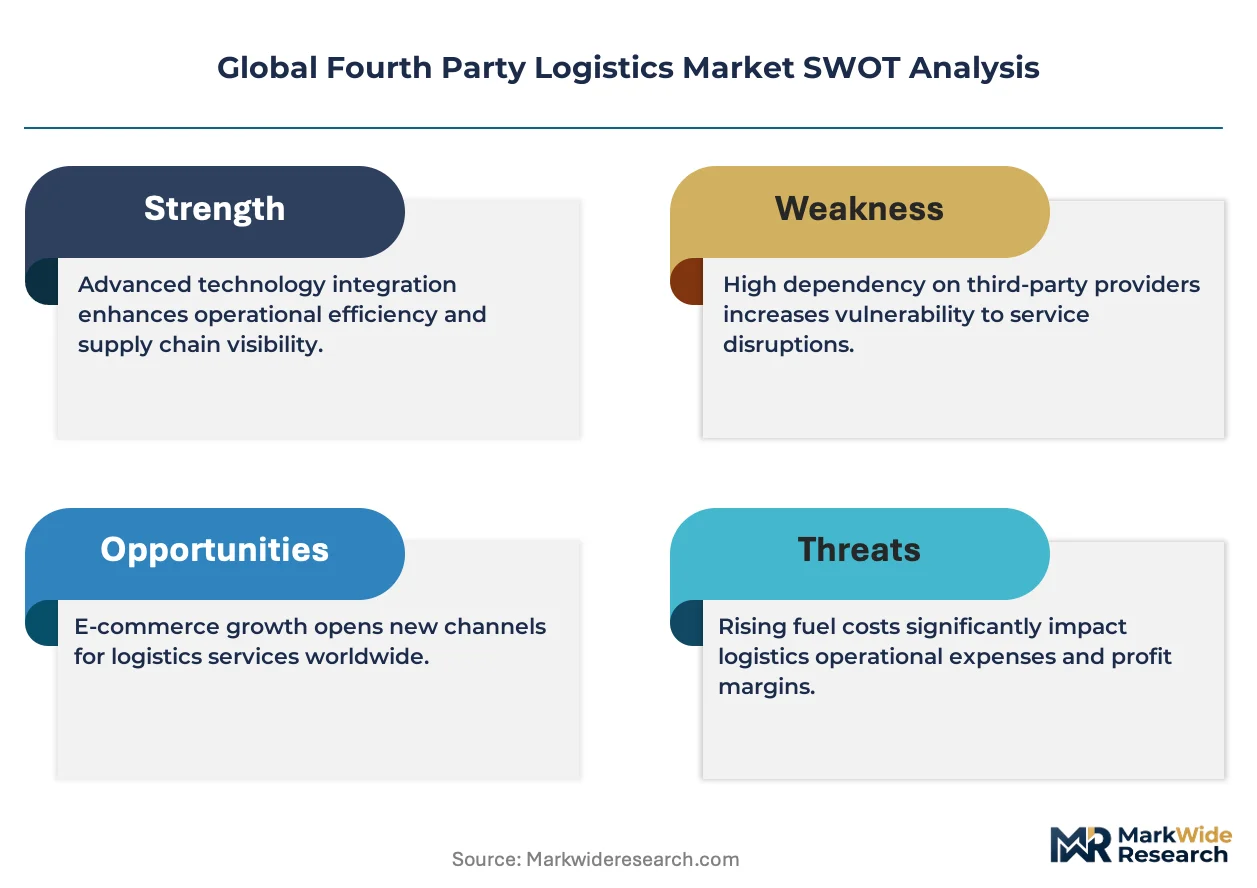
REACH compliance is decoupling European 4PL contracts from basic freight brokerage toward integrated chemical-handling certifications. DHL Supply Chain & Global Forwarding anchors its position through pharmaceutical cold-chain credentials. Kuehne + Nagel leverages proprietary control-tower platforms to sustain margin pools in automotive sequencing. DB Schenker differentiates via rail-forwarding integration across Central European corridors.
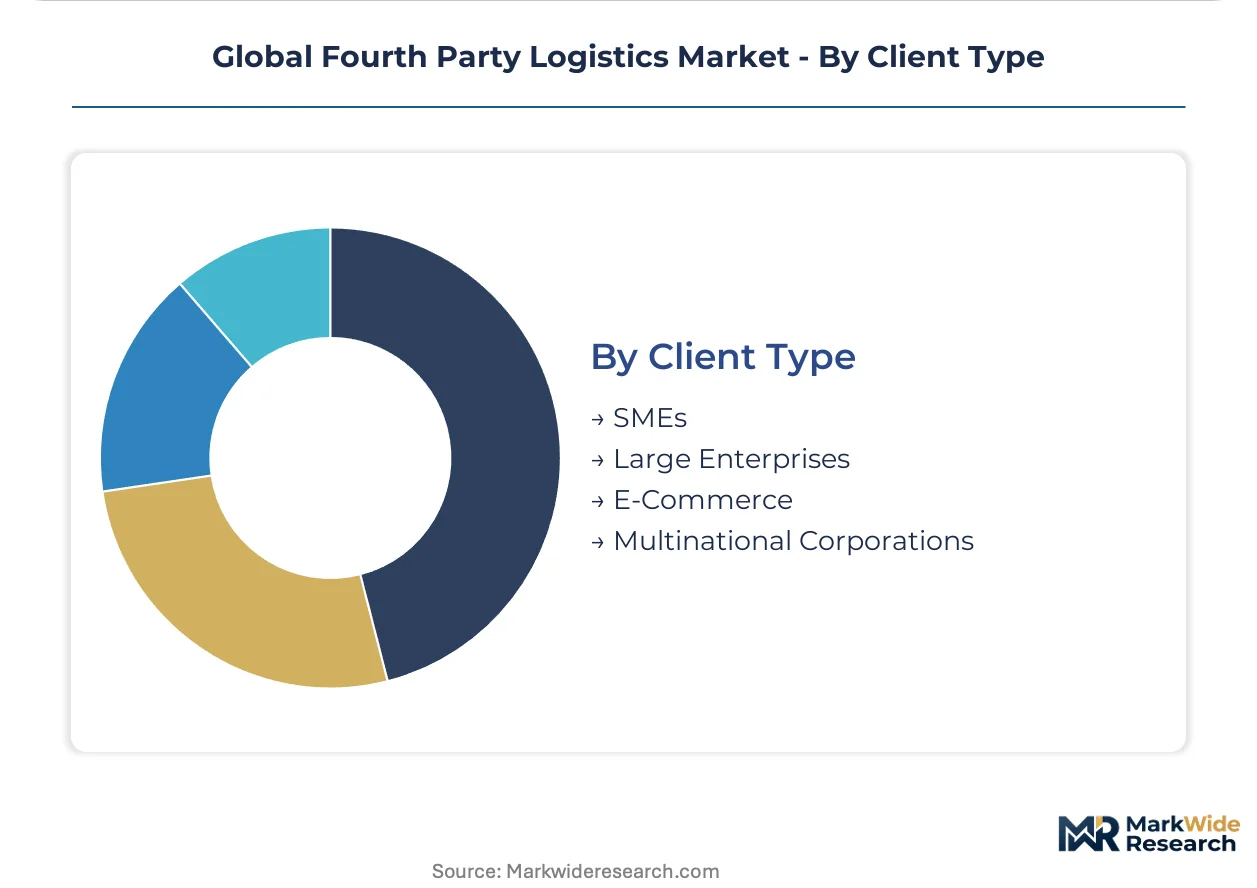
Fourth party logistics denotes an outsourced supply-chain orchestrator that designs, manages, and optimizes entire logistics networks through IT integration, multi-provider coordination, and continuous performance analytics rather than owning physical assets. The model deploys cloud-based visibility layers, API-connected carrier marketplaces, and AI-driven demand forecasting to replace fragmented third-party relationships with unified accountability. Transportation Management services currently occupy the largest revenue share among service types, though Inventory Management is recording the fastest expansion as just-in-case stocking replaces lean inventory doctrines. Large Enterprises dominate client-type spending, yet SMEs represent the fastest-growing adoption cohort as modular SaaS platforms lower contract minimums.
The EU AI Act, CSRD disclosure rules, and Germany's Supply Chain Due Diligence Act are collectively elevating compliance infrastructure from cost center to competitive differentiator in European 4PL procurement. The US EPA and FAA regulate cross-border freight emissions and drone-last-mile trials respectively, shaping where providers invest in electric fleet pilots and autonomous delivery R&D. Stakeholders must monitor which regulatory jurisdiction's compliance stack becomes the de facto passport for multinational contract eligibility.
Market Dynamics
Automotive OEMs are consolidating supplier tiers under single 4PL accountability, replacing fragmented third-party relationships with unified network orchestration. This structural compression is accelerating contract value migration from freight brokerage toward integrated control-tower platforms.
Growth Catalysts
- Germany's Supply Chain Due Diligence Act:Mandates human-rights due diligence across supplier networks, compelling manufacturers to outsource compliance monitoring to 4PL providers with audit infrastructure.
- Pharmaceutical cold-chain serialization:EMA track-and-trace requirements for temperature-sensitive biologics are driving demand for 4PLs with validated thermal packaging and real-time monitoring capabilities.
- API-connected carrier marketplaces:Cloud-based freight aggregation is automating spot-buying decisions and compressing procurement cycles for mid-market shippers.
Market Restraints
- Specialized talent scarcity:Control-tower operators with cross-modal optimization expertise command premium compensation, inflating service delivery costs.
- Rail-forwarding capacity concentration:Central European corridor bottlenecks limit modal flexibility for heavy-industry supply chains dependent on DB Schenker network access.
- Legacy TMS integration friction:Proprietary shipper systems resist API standardization, delaying visibility-layer deployment.
Strategic Opportunities
- EU CSRD emissions disclosure:Mandatory Scope 3 reporting creates recurring revenue streams for 4PLs with carbon-accounting software and supplier engagement protocols.
- SME modular SaaS adoption:Lower contract minimums are opening mid-market manufacturing segments previously excluded from enterprise-grade logistics orchestration.
- Drone-last-mile pilots:FAA Part 135 certification pathways for autonomous delivery are enabling 4PLs to design urban distribution networks bypassing road congestion.
Industry Challenges
- Multi-tier data harmonization:Supplier systems using incompatible EDI formats obstruct end-to-end visibility, requiring expensive middleware development.
- Cybersecurity certification timelines:ISO 27001 and TISAX audits for automotive 4PL contracts extend sales cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fourth Party Logistics Market |
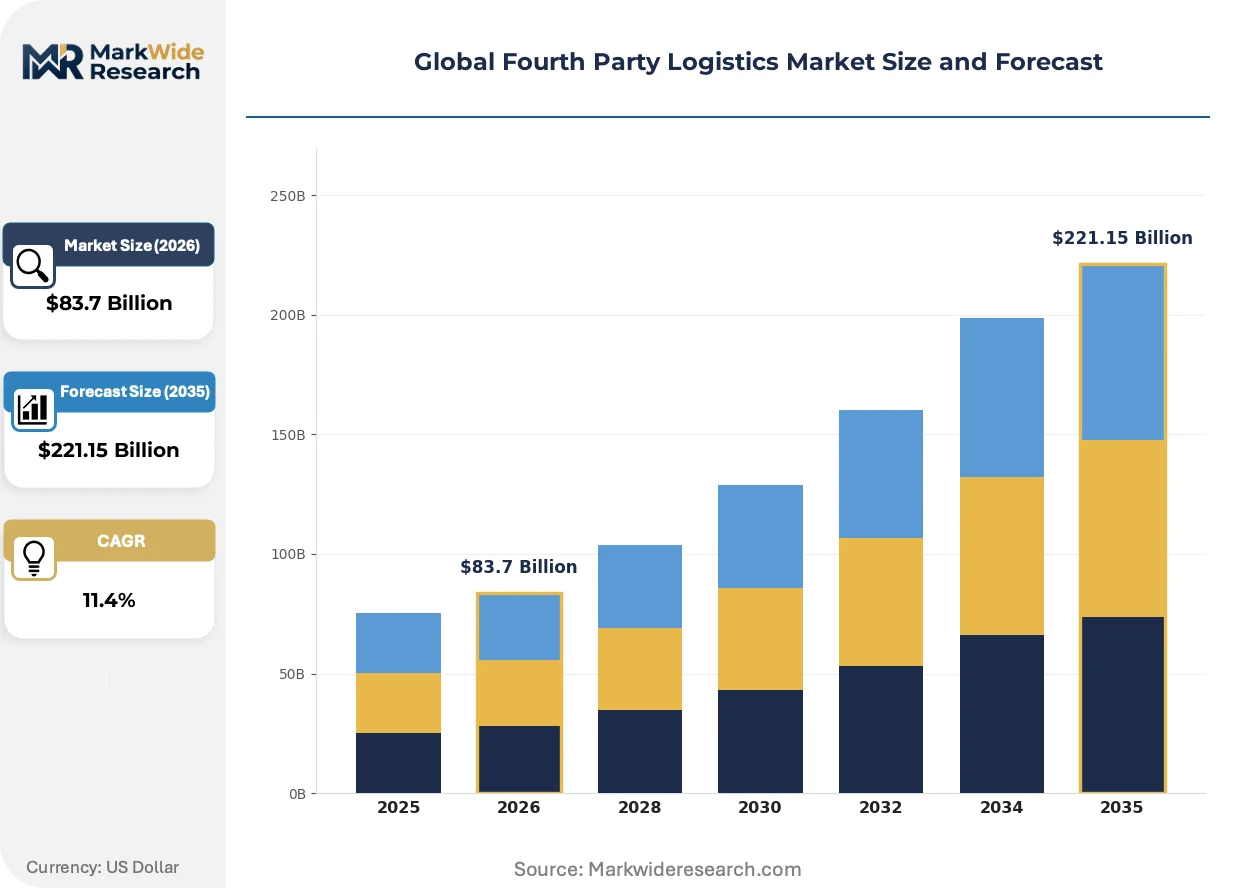
| Market Size in 2026 | $83.7 Billion |
| Market Size in 2035 | $221.15 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation Management, Warehousing Solutions, Inventory Management, Order Fulfillment Industry Vertical: Retail, Healthcare, Automotive, Consumer Electronics Delivery Model: On-Demand, Scheduled, Direct Shipping, Cross-Docking Client Type: SMEs, Large Enterprises, E-Commerce, Multinational Corporations |
| Companies Covered | CEVA Logistics, XPO Logistics, DHL Supply Chain & Global Forwarding, GEODIS, DSV, Kuehne + Nagel, UPS Supply Chain Solutions, C.H. Robinson, DB Schenker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fourth Party Logistics Market Emerging Trajectories
Cloud-native visibility architectures are displacing on-premise logistics software, compressing deployment timelines and enabling real-time network reconfiguration. This infrastructure shift is redrawing competitive boundaries between asset-light orchestrators and traditional freight forwarders.
Machine-learning demand forecasting is automating inventory positioning decisions across automotive sequencing operations. Tier-1 suppliers in Germany are adopting these tools to align component deliveries with hourly production schedules. The technology is automating buffer-stock calculations that previously required manual planner intervention.
The EU AI Act's risk-classification framework for automated decision systems is forcing 4PLs to document algorithmic transparency in carrier selection and route optimization. Providers serving pharmaceutical and medical-device verticals face heightened conformity assessment requirements. German automotive manufacturers are demanding audit trails for AI-driven supplier scorecards to satisfy product liability protocols.
Just-in-case inventory doctrines are displacing lean supply-chain strategies among industrial equipment manufacturers. Buyers are accepting higher carrying costs to mitigate semiconductor and specialty-chemical shortage risks. This behavioral shift is most visible in German Mittelstand export firms reconfiguring European distribution networks for safety-stock pre-positioning.
Global Fourth Party Logistics Market Segmentation
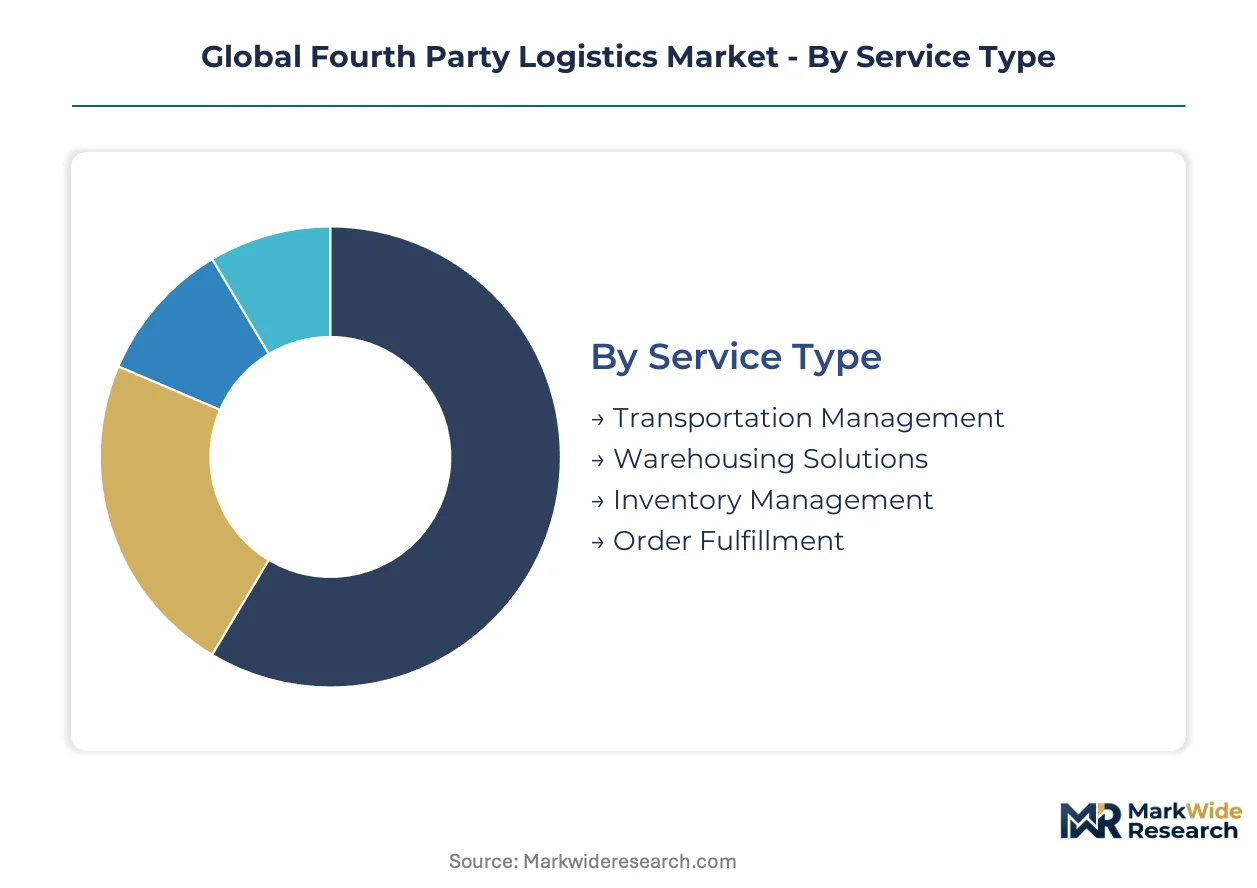
Segmentation in fourth party logistics reveals how certification requirements, asset ownership models, and client scale dictate procurement patterns. Providers configure service architectures differently across these dimensions, with regulatory compliance often determining contract eligibility before commercial terms are negotiated.
Service Type:
ISO 28000 supply-chain security certification and TAPA freight protection standards separate qualified providers from commodity brokers across service categories.
- Transportation Management:Multi-modal orchestration platforms integrate carrier procurement, route optimization, and freight audit through API-connected control towers. Automotive OEMs in Germany concentrate procurement here, driven by EUDR deforestation-free supply chain mandates requiring granular shipment traceability.
- Inventory Management:Demand forecasting engines and safety-stock positioning algorithms replace manual replenishment planning. German Mittelstand manufacturers expanding just-in-case stocking drive fastest adoption, accepting higher carrying costs to mitigate semiconductor shortage risks.
- Warehousing Solutions:Network design and slotting optimization for multi-tenant distribution centers. REACH compliance for chemical handling elevates provider selection criteria in European industrial corridors.
- Order Fulfillment:Last-mile orchestration and returns management through carrier marketplace integration. E-commerce peak-season volatility demands flexible labor pooling and micro-fulfillment node activation.
Transportation Management sits at the top of the volume ranking, with Inventory Management climbing the fastest.
Industry Vertical:
End-use concentration determines whether providers invest in specialized credentials—pharmaceutical cold-chain validation, automotive TISAX cybersecurity, or retail omnichannel integration.
- Automotive:Sequenced component delivery aligned to hourly production schedules through EDI-integrated supplier portals. KBA type-approval traceability requirements and TISAX audits extend provider onboarding timelines.
- Healthcare:Temperature-controlled distribution with GDP compliance and EMA serialization for track-and-trace. Biologics manufacturers in Germany and Switzerland demand validated thermal packaging with real-time deviation alerts.
- Retail:Omnichannel inventory positioning across store networks, dark stores, and direct-to-consumer fulfillment. Seasonal demand spikes require surge capacity contracts with penalty structures for service failures.
- Consumer Electronics:High-velocity replenishment for short product lifecycles with obsolescence risk. RoHS substance restrictions and WEEE take-back obligations shape reverse logistics network design.
Automotive commands the largest contract values, with Healthcare expanding most rapidly on biologics distribution requirements.
Delivery Model:
Asset-light orchestration versus owned-capital deployment creates diverging margin structures and capital intensity profiles.
- Scheduled:Fixed-route, contract-carrier networks optimized for predictable manufacturing supply chains. German automotive tier-1 suppliers rely on these arrangements for inbound-to-plant sequencing.
- On-Demand:Spot-market procurement through digital freight platforms for unpredictable demand spikes. API-connected marketplaces automate carrier matching and dynamic pricing.
- Direct Shipping:Point-to-point dedicated fleet operations bypassing consolidation nodes. Pharmaceutical manufacturers favor this model for high-value, time-critical biologics.
- Cross-Docking:Flow-through facilities minimizing inventory dwell time for fast-moving consumer goods. Retailers in European urban corridors deploy these to reduce last-mile delivery distances.
Scheduled delivery holds the highest volume share, while On-Demand is gaining share fastest on digital platform adoption.
Client Type:
Contract minimums and solution modularity determine which client tiers access enterprise-grade orchestration capabilities.
- Large Enterprises:Global network redesign with dedicated control towers and multi-year transformation roadmaps. EU CSRD Scope 3 disclosure mandates drive demand for integrated carbon accounting.
- SMEs:Modular SaaS platforms lowering entry barriers through subscription pricing and standardized integrations. German mid-market manufacturers represent the steepest expansion trajectory.
- Multinational Corporations:Harmonized operating models across regional business units with centralized procurement governance. Germany's Supply Chain Due Diligence Act compels outsourced compliance monitoring.
- E-Commerce:Peak-flexible fulfillment networks with returns processing and customer-experience metrics embedded in SLAs. Urban drone-last-mile pilots under FAA Part 135 pathways enable network innovation.
Large Enterprises dominate current spending, with SMEs recording the steepest adoption curve on platform democratization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fourth-party logistics originated in European automotive supply chains during the 1990s, when German OEMs pioneered outsourced network orchestration to manage multi-tier supplier complexity. This heritage continues shaping geographic deployment patterns today.
Germany
Automotive OEMs in Stuttgart and Munich drive concentrated 4PL procurement for sequenced component delivery aligned to hourly production schedules. The Supply Chain Due Diligence Act mandates human-rights due diligence across supplier networks, compelling manufacturers to outsource compliance monitoring. Mittelstand export firms in Baden-Württemberg reconfigure European distribution networks for just-in-case safety-stock pre-positioning.
United States
Pharmaceutical manufacturers in New Jersey and North Carolina demand validated cold-chain orchestration for temperature-sensitive biologics distribution. The FAA regulates drone-last-mile trials under Part 135 certification pathways, shaping urban distribution network design. E-commerce fulfillment networks in the Pacific Northwest deploy peak-flexible micro-fulfillment nodes with returns processing embedded in SLAs.
China
Consumer electronics manufacturers in the Yangtze River Delta seek high-velocity replenishment orchestration for short product lifecycles with obsolescence risk. MIIT cloud-service regulations shape data-localization requirements for visibility-layer deployment. Shanghai-based automotive tier-1 suppliers adopt API-connected carrier marketplaces to automate spot-buying decisions.
Japan
Precision equipment manufacturers in the Chubu region around Nagoya require multi-modal orchestration for just-in-time component flows. METI supply-chain resilience initiatives promote diversified sourcing strategies that increase network complexity. Osaka-based pharmaceutical distributors demand GDP-compliant temperature-controlled distribution with real-time deviation alerts.
India
Automotive component manufacturers in Tamil Nadu and Maharashtra expand 4PL adoption to manage export supply chain complexity. PLI scheme incentives for advanced cell chemistry battery manufacturing create new logistics orchestration requirements. Gujarat-based chemical processors seek REACH-compliant providers for European export corridor access.
Global Fourth Party Logistics Market Vendor Landscape
The competitive structure tilts toward integrated control-tower operators with specialized vertical credentials. Asset-light orchestrators with cloud-native platforms compete against traditional freight forwarders investing in visibility-layer acquisitions. Three archetypes dominate: pharmaceutical cold-chain specialists, automotive sequencing experts, and SME-focused SaaS platform providers. Consolidation through strategic partnerships and API ecosystem expansion represents the primary competitive vector.
Among European-integrated providers, DHL Supply Chain & Global Forwarding, Kuehne + Nagel, and DB Schenker occupy positions spanning pharmaceutical, automotive, and industrial verticals. These entities exemplify the credential-heavy archetype where regulatory certifications determine contract eligibility before commercial terms enter negotiation. Their geographic footprints concentrate in German industrial corridors and Central European rail-forwarding networks.
| Leading Market Players |
|---|
| CEVA Logistics |
| XPO Logistics |
| DHL Supply Chain & Global Forwarding |
| GEODIS |
| DSV |
| Kuehne + Nagel |
| UPS Supply Chain Solutions |
| C.H. Robinson |
| DB Schenker |
| Others |
Supply Flow & Price Mechanics
Control-tower operators with cross-modal optimization expertise in Germany command premium compensation that widens spreads between enterprise-grade orchestration and mid-market SaaS tiers. Labor-cost differentials between certified supply-chain architects in Stuttgart-Munich corridors and modular platform engineers in Eastern European delivery centers stratify pricing architectures across client segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract structures, with premium tiers anchored by TISAX cybersecurity certification and pharmaceutical cold-chain validation. Price differentiation hinges on vertical integration depth and API-connected carrier marketplace access. Cost compression in the economy tier is intensifying because mid-market SaaS platforms automate procurement cycles previously requiring manual intervention. SME manufacturers exhibit highest price sensitivity, while automotive OEMs prioritize compliance infrastructure over unit cost.
Supply Chain Analysis
Certification gating through ISO 28000 supply-chain security standards and TAPA freight protection protocols determines provider eligibility before commercial negotiation. Supply concentrates in Germany, China, and the United States, with automotive sequencing corridors, pharmaceutical cold-chain nodes, and API marketplace infrastructure anchoring regional hubs. Raw material dependencies span cloud-computing capacity, specialized thermal packaging, and EDI middleware. Single-source vulnerability in Central European rail-forwarding networks creates structural exposure. Distribution runs through multi-tenant control towers with real-time visibility layers replacing fragmented third-party relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between Germany's Supply Chain Due Diligence Act and less stringent disclosure regimes in Eastern European manufacturing zones creates geographic cost differentials for compliance infrastructure deployment.
For Market Incumbents: Deepen vertical integration into pharmaceutical cold-chain credentials and automotive sequencing platforms to defend margin pools against cloud-native SaaS entrants. Invest in TISAX and ISO 27001 certification acceleration to compress six-to-nine-month sales cycles. Prioritize API ecosystem expansion over proprietary TMS development to capture mid-market procurement automation demand. For New Entrants and Emerging Players: The 40-60% price-point gap between premium certified orchestration and economy SaaS tiers opens white-space in German Mittelstand manufacturing segments. Target mid-market automotive tier-2 suppliers with modular inventory management subscriptions. Pursue drone-last-mile pilot partnerships under FAA Part 135 pathways to bypass incumbent road-network dominance in urban corridors. For Investors and Strategic Acquirers: Private-equity-backed logistics platform consolidators are the most active acquirer in this space, driven by API marketplace aggregation strategies. Long-term viability centers on carbon-accounting software recurring revenue streams from EU CSRD Scope 3 mandates. Target acquisition archetype: cloud-native visibility-layer providers with pharmaceutical or automotive vertical credentials. Monitor FAA Part 135 certification velocity as inflection indicator for autonomous delivery network economics.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Automated carrier matching through cloud-based freight marketplaces compresses procurement cycles for mid-market shippers. |
| Carbon Accounting Platform Development | EU CSRD Scope 3 disclosure mandates create recurring revenue streams from supplier engagement protocols. |
| Cold-Chain Credential Acquisition | EMA track-and-trace compliance for temperature-sensitive biologics secures pharmaceutical manufacturer contracts. |
| Drone-Last-Mile Certification | FAA Part 135 pathways enable urban distribution networks bypassing road congestion in dense corridors. |
| Control-Tower Talent Retention | Cross-modal optimization expertise scarcity in Germany inflates service delivery costs without specialized workforce investment. |
Methodological Framework
Coverage spans Germany, the United States, China, and India, with primary inputs from each regional cluster. The analysis combines structured interviews with 4PL control-tower operators, automotive OEM procurement directors, pharmaceutical supply-chain executives, and SME manufacturing owners with secondary validation. Secondary sources include SEC filings from listed logistics providers, EU regulatory disclosure databases, FAA certification records, and customs trade data. Bottom-up service-type demand modeling and top-down macroeconomic triangulation anchor volume and value estimates.
Granularity-level modeling disaggregates projections across service type, industry vertical, delivery model, and client type dimensions, with additional segmentation by regulatory compliance tier. CAGRs derive from annualized growth rate reconciliation across the projection horizon. Forecast inputs incorporate API marketplace adoption curves, pharmaceutical cold-chain serialization mandates, and automotive sequencing automation penetration.
The model assumes a particular technology adoption path for cloud-native visibility architectures; alternative pathways for legacy TMS integration would alter the outlook. Forecasts reflect assumptions about regulatory enforcement timelines and carrier marketplace liquidity. Supply-side concentration in Central European rail corridors and cybersecurity certification bottlenecks represent revision risks. A model refresh is warranted upon material change in EU AI Act implementation schedules or FAA autonomous delivery certification velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Europe Road Freight Transport Market