
 Netherlands Road Freight Transport Market | 2026-2036
Netherlands Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Road Freight Transport Market Foresight
Dutch commercial vehicle fleet operators are restructuring capacity allocation around zero-emission zones in Amsterdam, Rotterdam, and Utrecht. DSV A/S leverages its integrated European network to consolidate cross-border loads through Venlo and Rotterdam distribution nodes. Jan de Rijk Logistics specializes in temperature-controlled pharmaceutical distribution, sustaining premium service positioning across the Benelux corridor. Ewals Cargo Care operates dedicated mega-trailer fleets for automotive and industrial clients, controlling niche volume contracts that reward asset specificity.
Road freight transport encompasses the movement of goods via motorized vehicles on public highway infrastructure, utilizing powertrains ranging from diesel combustion to battery-electric and hydrogen fuel cell systems with gross vehicle weights spanning 3.5 to over 44 tonnes. The sector functions as the dominant mode for domestic Dutch distribution and intra-European trade, handling containerized imports from Rotterdam Europoort, perishable exports from Schiphol logistics zones, and just-in-time manufacturing inputs for Eindhoven's high-tech assembly plants. Full Truck Load services dominate value capture on major corridor routes, while Less than Truck Load networks aggregate margin from fragmented shipper bases in SME manufacturing and wholesale trade. Intermodal Transport segments are expanding fastest as rail-terminal connectivity at Blerick and Tilburg reduces long-haul diesel exposure. Refrigerated Truck deployment within the Food & Beverage end user category anchors specialized fleet investment cycles tied to supermarket distribution center requirements.
The Dutch Human Environment and Transport Inspectorate enforces EU Mobility Package driving-time rules and cabotage restrictions that reshape cross-border operator economics and fleet utilization rates. National emission standards aligned with EU Green Deal targets mandate progressive CO2 reductions for new heavy-duty vehicles, forcing carriers to evaluate battery-electric and hydrogen alternatives against total cost of ownership horizons. Stakeholders must monitor charging infrastructure build-out pace along A15 and A67 corridors and assess whether green hydrogen refueling networks at Rotterdam port achieve commercial viability before fleet replacement cycles commit capital to single-technology pathways.
Market Dynamics
EU Green Deal emission performance standards for heavy-duty vehicles are forcing Dutch fleet operators into compressed replacement cycles, triggering capital reallocation between battery-electric and hydrogen powertrain pathways before charging infrastructure achieves corridor coverage.
Growth Catalysts
- Zero-Emission Zone Mandates:Amsterdam, Rotterdam, and Utrecht municipal authorities are banning diesel trucks from city centers by 2025, creating immediate demand for electric alternatives among last-mile distributors serving supermarket chains.
- E-commerce Fulfillment Density:Randstad corridor warehouse construction is concentrating inventory positions, shortening haul distances and enabling electric truck deployment with viable duty cycles.
- Rotterdam Port Rail Integration:Blerick and Tilburg intermodal terminals are expanding container handling capacity, allowing road hauliers to capture barge-rail-road combined transport margins on Germany-bound flows.
Market Restraints
- Battery Cost Volatility:Lithium carbonate price swings and cell supply bottlenecks are inflating electric truck total cost of ownership calculations beyond diesel parity horizons.
- Driver Shortage Concentration:Netherlands Transport and Logistics Association reports acute scarcity of certified heavy goods vehicle operators, compressing fleet utilization rates below 85 percent.
- EU Mobility Package Enforcement:Dutch Human Environment and Transport Inspectorate strict cabotage monitoring is reducing cross-border load consolidation efficiency for international operators.
Strategic Opportunities
- Green Hydrogen Corridor Development:Port of Rotterdam electrolyzer projects could establish commercial refueling infrastructure for fuel-cell trucks before 2030 fleet replacement waves.
- Pharmaceutical Cold Chain Specialization:Schiphol logistics zones and Eindhoven life sciences clusters are generating temperature-controlled pharmaceutical volumes requiring GDP-compliant transport certification.
- Maasvlakte Automated Trucking:Port terminal operator investment in autonomous vehicle corridors presents early-mover positioning for dedicated shuttle services between deep-sea terminals and inland depots.
Industry Challenges
- Charging Infrastructure Gap:A15 and A67 motorway fast-charging station deployment is lagging fleet electrification timelines, forcing operators into depot-constrained operational planning.
- Workforce Electrification Training:High-voltage system certification requirements for technicians and drivers are extending recruitment cycles and inflating training budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Road Freight Transport Market |
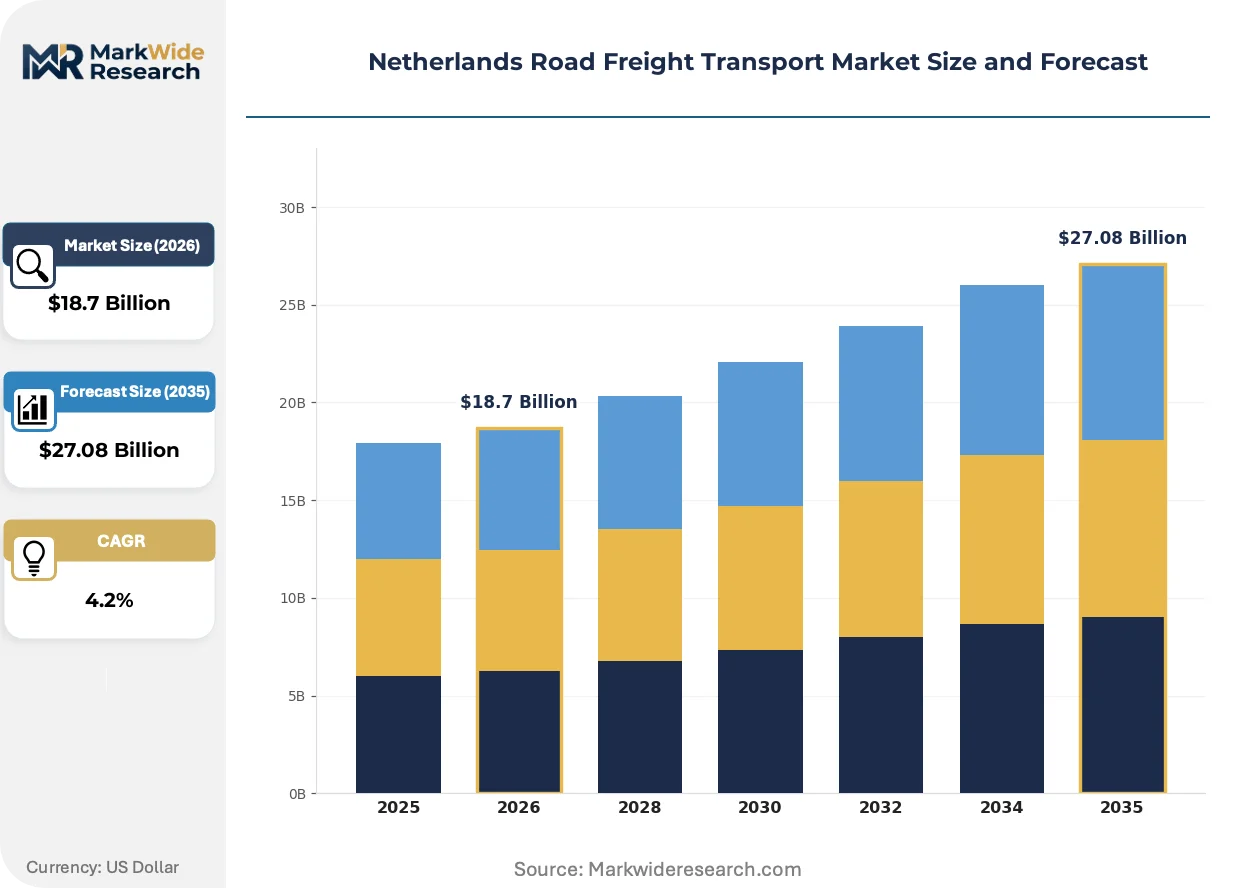
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less than Truck Load, Intermodal Transport, Express Delivery Vehicle Type: Rigid Truck, Semi-Trailer, Refrigerated Truck, Flatbed Trailer End User: Retail, Manufacturing, Construction, Food & Beverage Weight Class: Lightweight, Medium-weight, Heavy-weight, Super Heavy |
| Companies Covered | DSV A/S, Jan de Rijk Logistics, A.P. Moller - Maersk, DFDS Logistics, Dachser, Kuehne + Nagel International AG, DB Schenker, Ewals Cargo Care, DHL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Road Freight Transport Market Shifts & Advancements
Digital freight matching platforms and predictive load consolidation algorithms are compressing empty running ratios, while powertrain electrification and autonomous terminal operations are restructuring asset ownership and labor deployment models across Dutch logistics networks.
Telematics-enabled dynamic routing is converging with warehouse management system integration to enable real-time load reallocation. Mid-sized Dutch distributors serving FMCG clients are adopting these platforms fastest. The technology is converging with electric vehicle range optimization to eliminate depot-return constraints on multi-drop urban routes.
EU Green Deal CO2 performance standards for heavy-duty vehicles are mandating 15 percent emission reductions by 2025 and 30 percent by 2030. Dutch carriers must now order zero-emission trucks to avoid fleet-average penalties. Refrigerated transport operators face the steepest compliance costs due to auxiliary power demands.
Shippers are consolidating transport procurement around carbon accounting transparency requirements. Large Dutch retailers are displacing fragmented spot-market relationships with contracted lane commitments tied to verified emission reporting. Food and beverage manufacturers in the southern Netherlands are demanding this most aggressively.
Netherlands Road Freight Transport Market Segmentation
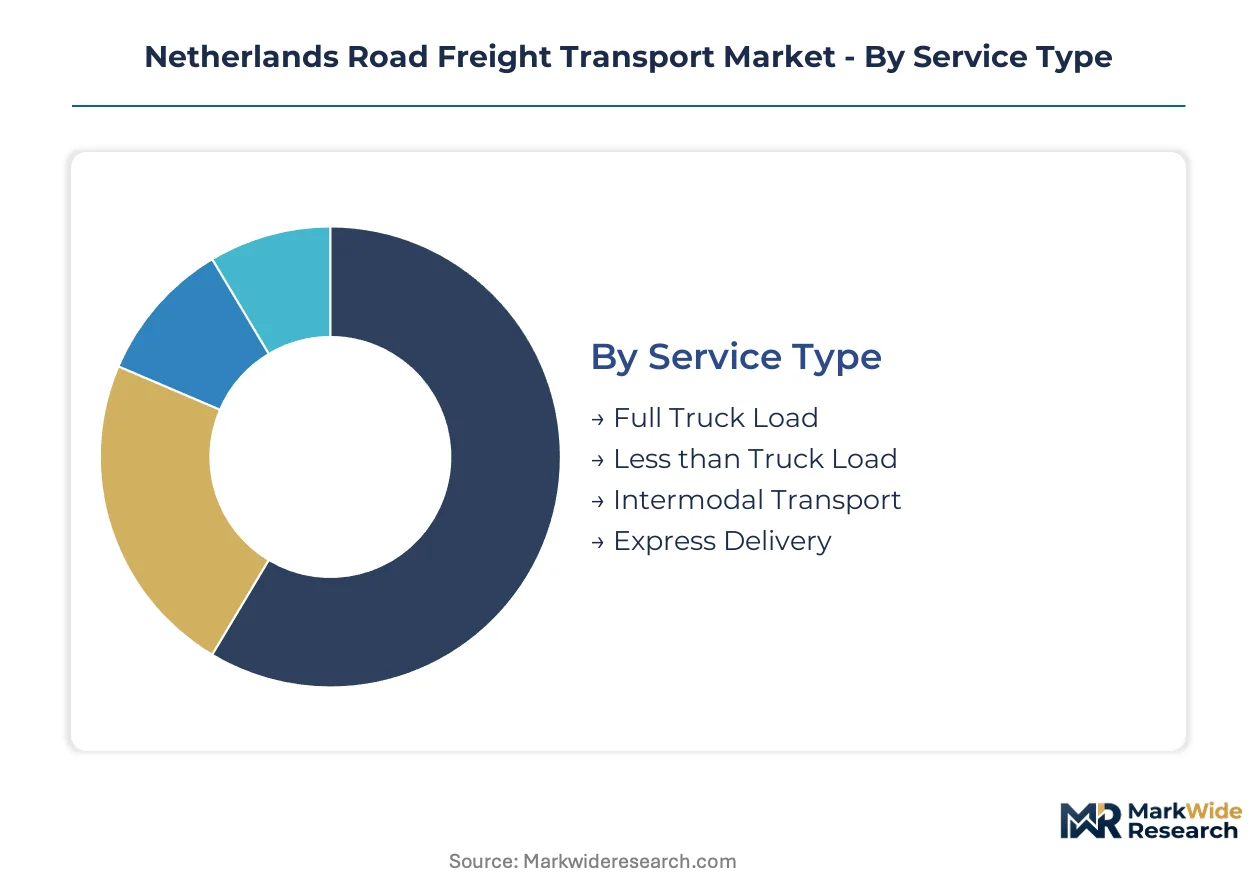
Dutch fleet operators configure service portfolios around corridor density and cargo consolidation economics. Segmentation reveals where capital concentrates across Rotterdam port hinterland flows versus fragmented inland distribution networks.
Service Type:
Shippers select service tiers based on shipment size predictability and inventory carrying cost trade-offs.
- Full Truck Load:Dedicated vehicle capacity for single-origin, single-destination movements. Containerized imports from Rotterdam Europoort and manufacturing inputs for Eindhoven high-tech assembly plants anchor volume concentration, though driver scarcity compresses utilization rates below optimal thresholds.
- Less than Truck Load:Consolidated multi-shipper cargo on hub-and-spoke networks. SME manufacturing and wholesale trade in the southern Netherlands generate fragmented demand that rewards density-optimized terminal operations.
- Intermodal Transport:Combined road-rail-barge movements through Blerick and Tilburg terminals. Rail-terminal connectivity reduces long-haul diesel exposure on Germany-bound corridors.
- Express Delivery:Time-definite services for e-commerce fulfillment networks. Randstad corridor warehouse concentration enables viable electric truck duty cycles on short-haul routes.
Full Truck Load leads on scale; Intermodal Transport leads on momentum.
Vehicle Type:
Asset acquisition decisions track payload requirements, modal flexibility needs, and zero-emission zone compliance timelines.
- Rigid Truck:Single-chassis vehicles with fixed cargo bodies. Urban last-mile distribution to Amsterdam, Rotterdam, and Utrecht supermarket chains faces immediate diesel ban deadlines, accelerating electric replacement cycles.
- Refrigerated Truck:Temperature-controlled units with auxiliary power systems. Pharmaceutical cold chain requirements from Schiphol logistics zones and Eindhoven life sciences clusters sustain premium positioning despite steepest EU Green Deal compliance costs.
- Semi-Trailer:Detachable cargo units hauled by tractor units. Cross-border long-haul corridors leverage standardized European loading gauge compatibility.
- Flatbed Trailer:Open-deck configurations for oversized and project cargo. Construction materials and industrial equipment movements favor this flexibility.
Refrigerated Truck commands highest asset specificity; Rigid Truck faces the most compressed replacement horizon.
End User:
Demand concentration varies by sector inventory velocity and supply chain control requirements.
- Food & Beverage:Temperature-sensitive supermarket distribution center replenishment drives specialized fleet investment. GDP-compliant transport certification requirements from Dutch Human Environment and Transport Inspectorate enforce cold chain integrity standards.
- Retail:Omnichannel fulfillment networks concentrate inventory in Randstad corridor warehouses. E-commerce penetration shortens order cycles and compresses delivery windows.
- Manufacturing:Just-in-time component flows for high-tech and automotive assembly. Eindhoven semiconductor and Maastricht automotive plants require synchronized inbound logistics.
- Construction:Project-based bulk materials and equipment movements. Seasonal demand patterns and site access constraints shape fleet deployment.
Food & Beverage anchors specialized fleet investment; Retail is expanding most quickly on e-commerce density.
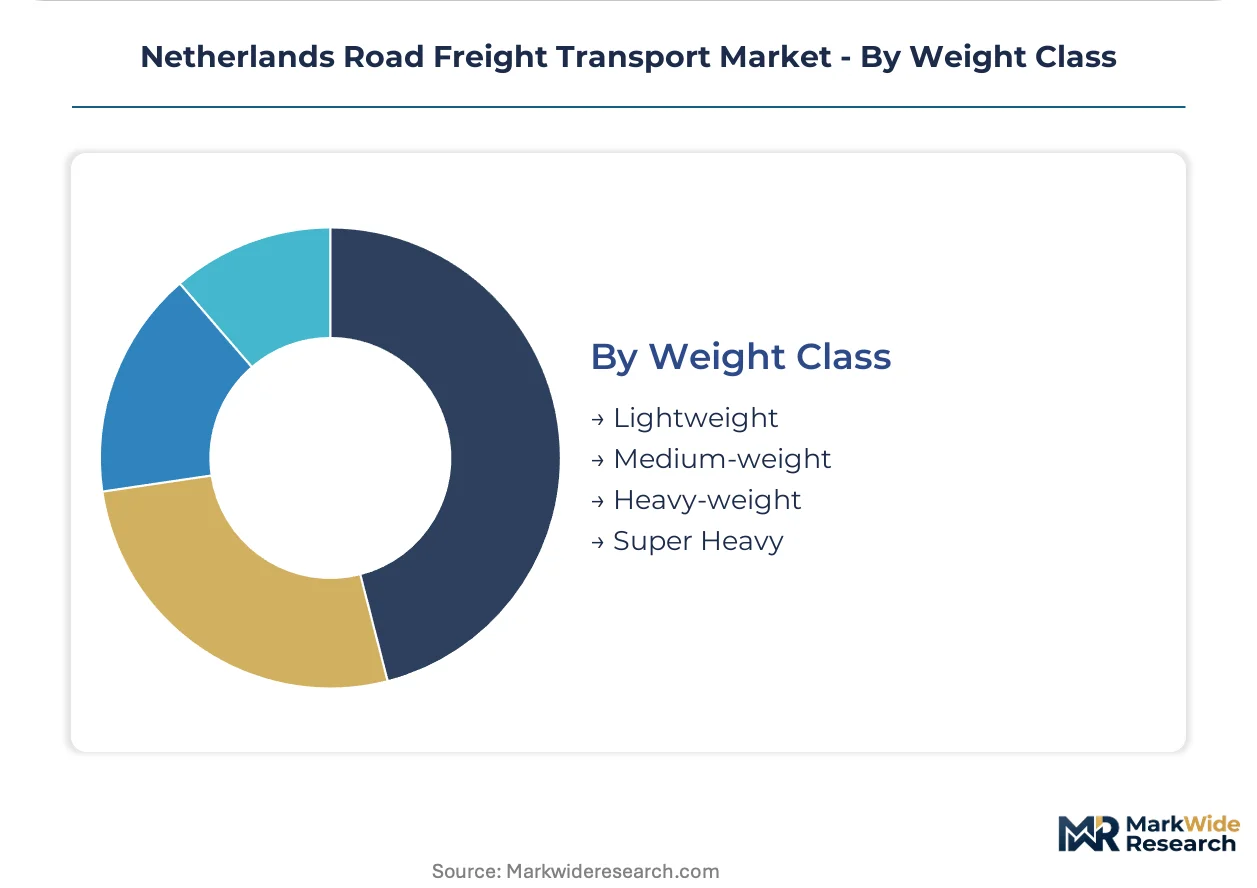
Weight Class:
Regulatory permitting and infrastructure access permissions segment operational capabilities across Dutch road networks.
- Heavy-weight:Vehicles exceeding standard EU axle load limits with special permits. Rotterdam port hinterland container movements and industrial freight corridors exploit maximum payload economics.
- Medium-weight:Standard heavy goods vehicles at 18-26 tonnes gross vehicle weight. Regional distribution networks balance payload efficiency with urban access flexibility.
- Lightweight:Vehicles below 7.5 tonnes operating on standard driving licenses. Last-mile parcel and urban service applications dominate deployment.
- Super Heavy:Exceptional load configurations requiring route surveys and escort vehicles. Project cargo and industrial components justify specialized permitting overhead.
Heavy-weight captures corridor volume concentration; Lightweight gains share fastest on zero-emission zone mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fleet investment patterns as Dutch carriers evaluate powertrain alternatives against neighboring countries' compliance timelines and subsidy regimes. Capital allocation tilts toward jurisdictions where zero-emission infrastructure matures fastest.
Germany
Ruhr industrial corridor freight volumes and Bavarian automotive supply chains drive cross-border demand from Dutch operators. KBA enforces EU Green Deal truck emission standards with stricter national inspection protocols. Duisburg intermodal terminals and Munich distribution clusters absorb significant Netherlands-originated capacity for eastbound manufacturing inputs.
Belgium
Antwerp port hinterland competition and Brussels last-mile congestion create overlapping operational zones with Dutch carriers. Federal Mobility Ministry coordinates zero-emission zone timelines with Dutch border cities. Flanders logistics parks around Ghent and Mechelen concentrate shared Dutch-Belgian fleet deployment for Benelux distribution.
France
Nord-Pas-de-Calais manufacturing zones and Paris basin consumption centers attract Dutch refrigerated and express capacity. ANSM and regional prefectures implement EU Mobility Package cabotage enforcement that affects Dutch cross-border operations. Lille logistics clusters and Lyon distribution hubs represent primary French destination points for Netherlands-originated flows.
United Kingdom
Post-Brexit customs complexity and Dover-Calais corridor constraints have restructured Dutch carrier UK service patterns. DVSA enforces distinct driver qualification recognition and vehicle certification requirements. Midlands distribution centers and London periphery warehouses retain demand for Dutch-controlled capacity despite regulatory friction.
Poland
Central European manufacturing migration and e-commerce fulfillment growth generate eastbound demand captured by Dutch international operators. Polish Road Transport Inspection applies EU driving-time regulations with variable enforcement intensity. Warsaw logistics zones and Wrocław industrial parks attract Netherlands-originated intermodal and long-haul road capacity.
Netherlands Road Freight Transport Market Competitive Landscape
Established operators occupy the asset-heavy tier; emerging platform-based entrants pursue digital freight matching and dynamic capacity optimization. The Netherlands market structures around three archetypes: integrated European network operators with cross-border consolidation capabilities, specialized temperature-controlled and pharmaceutical logistics providers, and regional mid-scale carriers with corridor-specific density. Dominant competitive moves include fleet electrification partnerships with charging infrastructure developers and strategic acquisitions of last-mile distributors in zero-emission zone municipalities.
Among integrated network operators, DSV A/S and Kuehne + Nagel International AG represent the pan-European consolidation archetype, leveraging multi-country terminal networks to capture cross-border load density. Jan de Rijk Logistics and Ewals Cargo Care exemplify specialization strategies, occupying positions tied to temperature-controlled pharmaceutical certification and dedicated mega-trailer industrial contracts respectively. DB Schenker and DHL Group sit within the diversified logistics conglomerate tier, anchoring broad service portfolios that span freight forwarding, contract logistics, and express delivery across Dutch and adjacent markets.
| Leading Market Players |
|---|
| DSV A/S |
| Jan de Rijk Logistics |
| A.P. Moller - Maersk |
| DFDS Logistics |
| Dachser |
| Kuehne + Nagel International AG |
| DB Schenker |
| Ewals Cargo Care |
| DHL Group |
| Others |
Supply & Pricing Matrix
Battery-electric powertrain adoption across Dutch heavy-duty fleets is compressing total cost of ownership calculations while redistributing pricing power toward carriers with depot-charging infrastructure and long-term energy contracts. This technology transition simultaneously elevates capital barriers for smaller operators and concentrates negotiating leverage among integrated networks with scale advantages in zero-emission zone municipalities.
Pricing Analysis
Direct-to-shipper contract rates dominate pricing structures, with three-tier pricing stratification across premium certified-lane, standard scheduled, and economy spot-market bands. Price differentiation hinges on EU Green Deal emission compliance certification and volume commitment scale, with refrigerated transport commanding steepest premiums due to auxiliary power demands. Cost compression in the economy tier is intensifying because lithium-ion battery supply bottlenecks inflate electric truck lease rates beyond diesel parity. SME manufacturing shippers exhibit highest price sensitivity, while pharmaceutical cold chain clients demonstrate lowest elasticity due to GDP certification requirements.
Supply Chain Analysis
Driver scarcity across Dutch, German, and Belgian logistics corridors is constraining fleet utilization rates and forcing wage inflation through the carrier cost base. Vehicle manufacturing draws from German chassis assembly, Polish trailer fabrication, and Chinese battery cell production. Single-source vulnerability in lithium carbonate supply from Chile and Australia feeds price volatility into electric truck procurement cycles. Distribution runs through Rotterdam port terminals, Venlo cross-dock hubs, and Randstad corridor last-mile depots in a hub-and-spoke configuration optimized for Benelux density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands road freight market functions as a regulatory-arbitrage corridor where EU Green Deal compliance timelines run 12-18 months ahead of German federal implementation, rewarding early-mover fleet electrification with premium contract access across the border.
For Market Incumbents: Hedge diesel asset stranded-cost exposure by accelerating battery-electric deployment in Amsterdam, Rotterdam, and Utrecht zero-emission zones ahead of 2025 enforcement deadlines. Consolidate last-mile distributors with established depot-charging infrastructure to capture supermarket chain contract renewals. Vertical integration into renewable energy procurement locks in electricity cost advantages against spot-market volatility. For New Entrants and Emerging Players: The premium-economy price-point gap in temperature-controlled pharmaceutical distribution creates white-space opportunity for GDP-certified niche operators serving Schiphol logistics zones and Eindhoven life sciences clusters. Target mid-scale food manufacturers in southern Netherlands with pay-per-use refrigerated capacity models. Deploy digital freight matching platforms to aggregate fragmented SME manufacturing demand into density-optimized Less than Truck Load networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mid-scale carriers with corridor-specific density but lacking zero-emission fleet transition capital. Long-term viability across the projection horizon favors acquisition targets with established charging depot real estate and contracted lane relationships with Randstad retailers. Monitor Port of Rotterdam electrolyzer project commissioning announcements as inflection signal for hydrogen fuel-cell pathway commercial viability.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Charging infrastructure developer alliances secure depot-energy cost advantages for Amsterdam-Rotterdam-Utrecht corridor operators. |
| Last-Mile Distributor Acquisition | Zero-emission zone municipality positioning captures supermarket chain contract renewals ahead of 2025 diesel bans. |
| Pharmaceutical Cold Chain Certification | GDP-compliant transport credentials unlock premium pricing from Schiphol logistics zone life sciences clusters. |
| Intermodal Terminal Investment | Blerick and Tilburg rail connectivity reduces long-haul diesel exposure on Germany-bound manufacturing flows. |
| Digital Freight Platform Integration | Telematics-enabled dynamic routing compresses empty running ratios for mid-scale FMCG distributors. |
Research Methodology
Multiple input streams — fleet operator interviews, shipper procurement director consultations, charging infrastructure developer assessments, and regulatory compliance officer surveys — were reconciled against secondary validation from EU Green Deal implementation tracking, Dutch Human Environment and Transport Inspectorate enforcement records, and Rotterdam port authority throughput statistics. Bottom-up carrier capacity modeling and top-down corridor flow analysis triangulated volume and value estimates across the analysis window.
Data-stream reconciliation anchored the forecast framework across service type, vehicle powertrain architecture, end-user industry vertical, and weight class regulatory tier segmentation dimensions. CAGRs were derived from electric truck adoption curve modeling calibrated to zero-emission zone enforcement timelines and battery cost learning rates. Key inputs included driver shortage elasticity coefficients and intermodal terminal capacity expansion schedules.
Caveats apply where EU Mobility Package cabotage enforcement intensity, lithium carbonate supply disruptions, or hydrogen refueling infrastructure deployment delays could materially shift the outlook. Forecasts embed assumptions regarding charging station build-out pace along A15 and A67 corridors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Parking Meter Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Perishable Goods Transportation Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
Road Haulage Market