
 Europe Long Haul Transport Market | 2026-2036
Europe Long Haul Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Long Haul Transport Market Foresight
CE marking under the EU's Vehicle Type Approval framework is reorganizing which fleet operators and logistics providers can deploy cross-border tractor-trailer combinations on European TEN-T corridors. Deutsche Post DHL Group leverages its integrated road-air-sea network to sustain density on long-haul lanes between the Benelux and Iberian Peninsula. Kuehne + Nagel anchors its European overland division through controlled capacity agreements with owner-operator networks across Central Europe.
Europe long haul transport encompasses the movement of goods and cargo over distances exceeding 300 kilometers using heavy-duty vehicles, typically articulated combinations with gross combination masses up to 40 tonnes under EU Directive 96/53/EC, primarily serving intercontinental supply chain connectivity and continental distribution. Freight transport commands the dominant revenue pool given its scale across automotive parts and bulk commodities, while cold chain services capture premium margins from pharmaceutical and perishable food sectors requiring temperature-controlled trailers with multi-compartment refrigeration units. Logistics solutions integrating real-time telematics and predictive routing algorithms represent the fastest-expanding service category as shippers prioritize visibility over pure ton-kilometer pricing.
The EU Green Deal's CO2 performance standards for heavy-duty vehicles, enforced by the European Commission in coordination with national type-approval authorities, mandate progressive emission reductions that reshape fleet procurement timelines and powertrain investments across member states. REACH compliance for vehicle materials and the F-Gas Regulation governing transport refrigeration unit coolants add layered compliance costs that favor larger operators with dedicated sustainability functions. Stakeholders must weigh total cost of ownership calculations spanning diesel, battery-electric, and hydrogen fuel cell platforms against evolving toll structures and low-emission zone access rules.
Market Dynamics
The EU Green Deal's CO2 performance standards for heavy-duty vehicles are compressing fleet procurement cycles as operators face binding emission reduction mandates across the TEN-T network. This regulatory pressure is restructuring capital allocation toward alternative powertrains while diesel assets face accelerated obsolescence risk.
Growth Catalysts
- EU Green Deal CO2 Standards:Binding emission targets for heavy-duty vehicles under EU Directive (EU) 2019/1242 are forcing fleet renewal toward battery-electric and hydrogen platforms, creating replacement demand across member states.
- Pharmaceutical Cold Chain:Temperature-sensitive biologics distribution from Belgium and Netherlands manufacturing clusters is expanding refrigerated trailer deployment on Rhine-Alpine corridors.
- Poland:Central European logistics hubs are attracting e-commerce fulfillment investment, driving cross-border tractor-trailer density between Warsaw, Wrocław, and German distribution centers.
Market Restraints
- Battery-Electric Range Constraints:Current lithium-ion energy density limits tractor-trailer combinations to sub-500-kilometer ranges, excluding long-haul lanes between Iberian Peninsula and Benelux markets.
- Charging Infrastructure Concentration:Ultra-fast megawatt charging corridors cluster along Rhine-Alpine and North Sea-Baltic TEN-T axes, leaving Mediterranean and Eastern European routes underserved.
- REACH Compliance Burden:Chemical substance registration requirements for vehicle materials and refrigerants under ECHA jurisdiction add fixed compliance costs that scale disproportionately against smaller fleet operators.
Strategic Opportunities
- CEE Corridor Development:Baltic-Adriatic and Orient/East-Med TEN-T corridors through Czech Republic, Slovakia, and Hungary remain underpenetrated relative to Rhine-Alpine density, offering volume expansion potential.
- Platooning Technology:Cooperative adaptive cruise control systems linking multiple tractor-trailers are converging with V2X infrastructure investments to reduce fuel consumption and driver labor intensity.
- F-Gas Regulation Phase-Down:Transport refrigeration unit refrigerant mandates under EU Regulation 517/2014 are creating retrofit and replacement demand for low-global-warming-potential cooling systems.
Industry Challenges
- Driver Qualification Shortage:EU Directive 2003/59/EC professional competence certification requirements are tightening labor supply as aging workforce exits exceed new entry rates across Germany and France.
- Multi-Powertrain Fleet Complexity:Parallel operation of diesel, battery-electric, and hydrogen fuel cell assets is fragmenting maintenance protocols and parts inventory management.
- Type-Approval Harmonization:CE marking divergence between EU member state interpretations of Vehicle Type Approval framework is delaying cross-border tractor-trailer deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Long Haul Transport Market |
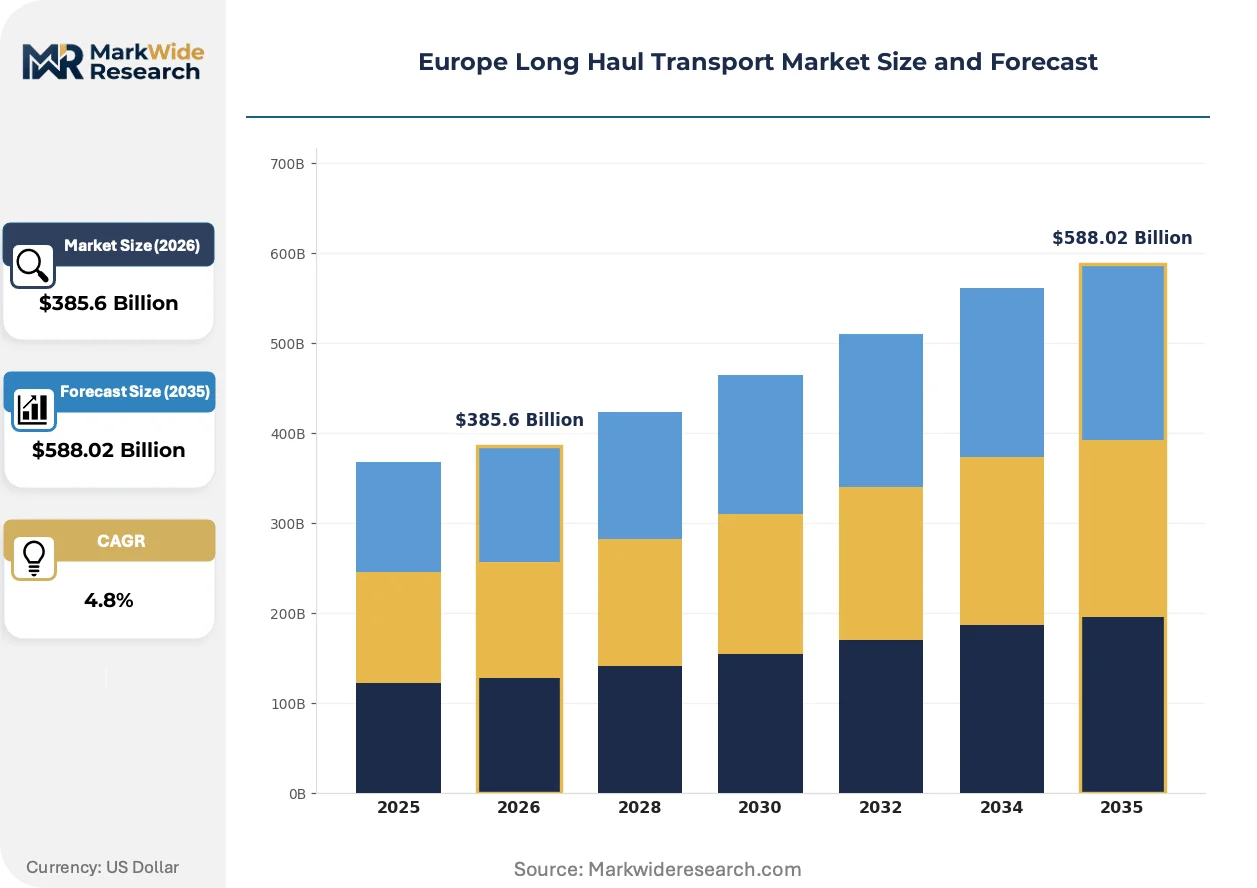
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $588.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Transport, Logistics Solutions, Warehousing, Cold Chain Vehicle Type: Trucks, Trailers, Vans, Buses End User: Retailers, Manufacturers, E-commerce, Distributors Delivery Mode: Direct Delivery, Scheduled Delivery, Same Day, Next Day |
| Companies Covered | Kuehne + Nagel, CEVA Logistics, Deutsche Post DHL Group, FIEGE Logistics, Rhenus Logistics, Dachser Logistics, DB Schenker, XPO Logistics, DSV Panalpina, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Long Haul Transport Market Shifts & Advancements
Telematics integration and predictive analytics are compressing operational planning cycles across European long-haul networks. Fleet operators now prioritize real-time visibility platforms over static routing optimization, reshaping technology procurement priorities and vendor selection criteria.
Battery-electric tractor platforms with megawatt charging capability are displacing diesel assets on scheduled lane operations under 400 kilometers. Food retailers and parcel carriers operating fixed depot networks are piloting overnight charging at distribution centers. This displacement is compressing total cost of ownership parity timelines and accelerating residual value risk for internal combustion fleets.
EU CSRD disclosure mandates are extending sustainability reporting obligations to logistics subcontractors. Transport operators must now document Scope 3 emissions across subcontracted haulage relationships. Automotive and pharmaceutical shippers in Germany and France are most affected, requiring ESG data integration into carrier procurement scorecards.
Shippers are consolidating carrier relationships around integrated logistics providers offering bundled road-rail intermodal solutions. Traditional spot-market brokerage is losing share to contracted capacity agreements with visibility guarantees. This concentration is most visible in Benelux-to-Italy corridors where automotive parts demand favors dedicated fleet partnerships over transactional sourcing.
Europe Long Haul Transport Market Segmentation
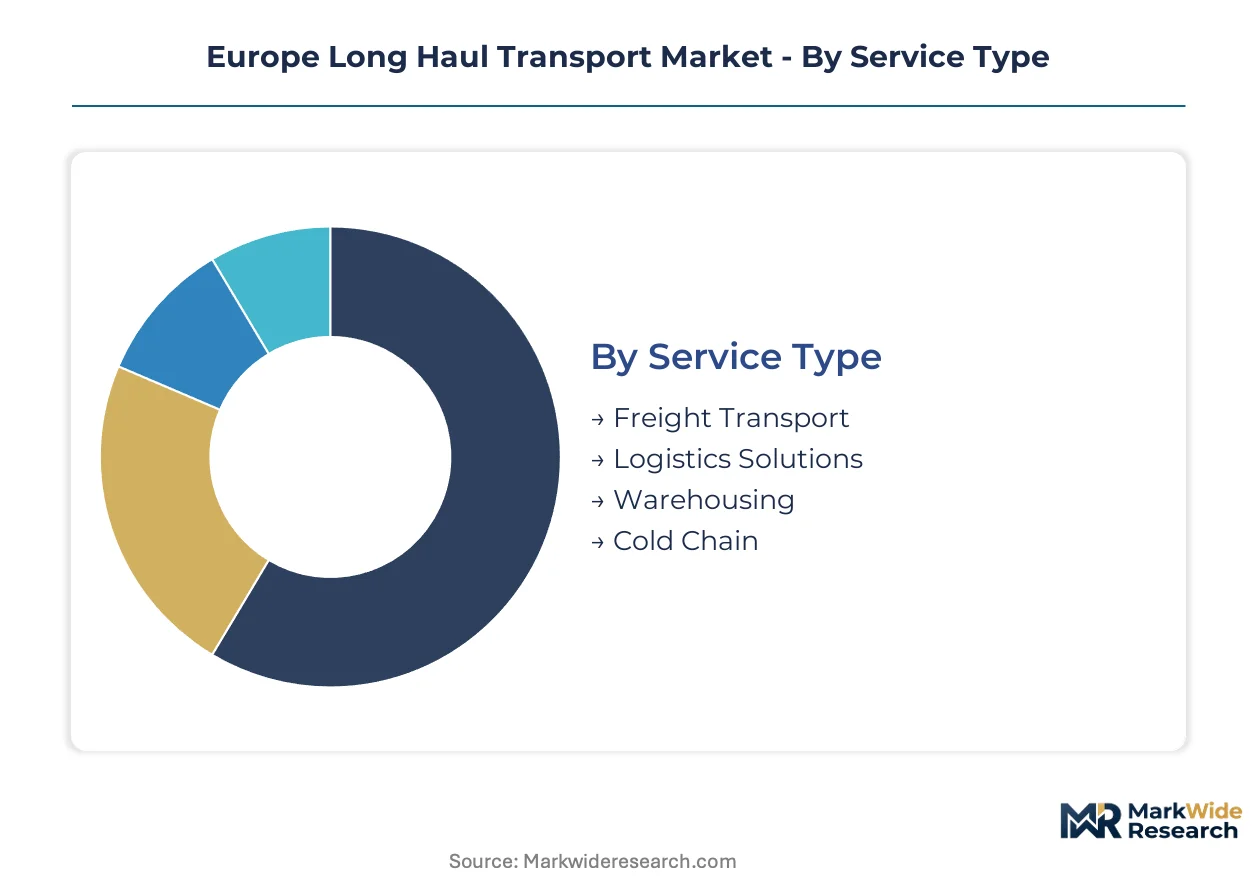
Channel configuration in European long-haul transport varies sharply by segment—freight transport flows through contracted carrier networks while cold chain services require dedicated refrigerated corridors with temperature validation protocols. Understanding these channel mechanics reveals where margin pools concentrate and which service tiers attract integrated logistics investment versus transactional spot-market procurement.
Service Type:
Channel mix divides sharply between asset-heavy freight operations and asset-light logistics orchestration, with cold chain commanding premium dedicated infrastructure and warehousing anchoring fixed-site network economics.
- Freight Transport:Articulated tractor-trailer combinations moving bulk commodities and automotive parts across TEN-T corridors. Demand concentrates in Rhine-Alpine lanes connecting Rotterdam, Antwerp, and Milan, driven by automotive OEM just-in-sequence supply chains requiring 48-hour delivery windows.
- Logistics Solutions:Integrated service bundles combining transport execution with customs brokerage and supply chain visibility platforms. Expansion concentrates in Poland and Czech Republic as e-commerce fulfillment networks seek cross-border consolidation hubs with real-time inventory tracking.
- Warehousing:Fixed-site storage and cross-dock facilities supporting distribution network density. German and Dutch distribution clusters around Duisburg and Venlo anchor multi-modal transshipment capacity.
- Cold Chain:Temperature-controlled transport for pharmaceuticals and perishables with multi-compartment refrigeration units. Belgian and Netherlands pharmaceutical manufacturing clusters drive refrigerated trailer deployment under EU GDP guidelines.
Freight Transport dominates installed base. Cold Chain is where expansion concentrates.
Vehicle Type:
Cost tier stratification separates heavy-duty assets with 40-tonne gross combination mass limits from lighter commercial vehicles serving final-mile feeder roles.
- Trucks:Heavy-duty tractor units with diesel, battery-electric, or hydrogen fuel cell powertrains. German fleet operators under KBA jurisdiction are accelerating procurement of megawatt-charging-capable electric tractors for sub-400-kilometer scheduled lanes.
- Trailers:Semi-trailers and refrigerated units subject to EU Directive 96/53/EC dimensional standards. Demand clusters in refrigerated variants for pharmaceutical distribution from Belgium and Netherlands manufacturing sites.
- Vans:Light commercial vehicles under 3.5 tonnes serving final-mile feeder operations from long-haul terminals. E-commerce parcel density in Warsaw and Wrocław corridors is expanding van fleet requirements.
- Buses:Intercity coach configurations repurposed for crew transport and mobile logistics support. Limited penetration in core freight applications outside specialized automotive plant shuttle services.
Trucks anchor capital deployment. Trailers are where technology differentiation concentrates.
End User:
Customer type determines contract structure—manufacturers favor dedicated fleet partnerships while e-commerce platforms prioritize flexible capacity with visibility guarantees.
- Retailers:Grocery and general merchandise chains requiring scheduled replenishment of distribution centers. German food retailers are piloting overnight electric charging at captive distribution facilities.
- Manufacturers:Automotive and industrial goods producers with just-in-sequence supply chain requirements. Benelux-to-Italy automotive parts corridors favor contracted capacity agreements over spot-market sourcing.
- E-commerce:Online retail platforms with volatile volume profiles and next-day delivery commitments. Polish fulfillment hub expansion is driving cross-border tractor-trailer density to German distribution centers.
- Distributors:Third-party logistics intermediaries consolidating shipments from multiple suppliers. REACH compliance burdens under ECHA jurisdiction favor larger operators with dedicated sustainability functions.
Manufacturers dominate contract value. E-commerce is where volume volatility concentrates.
Delivery Mode:
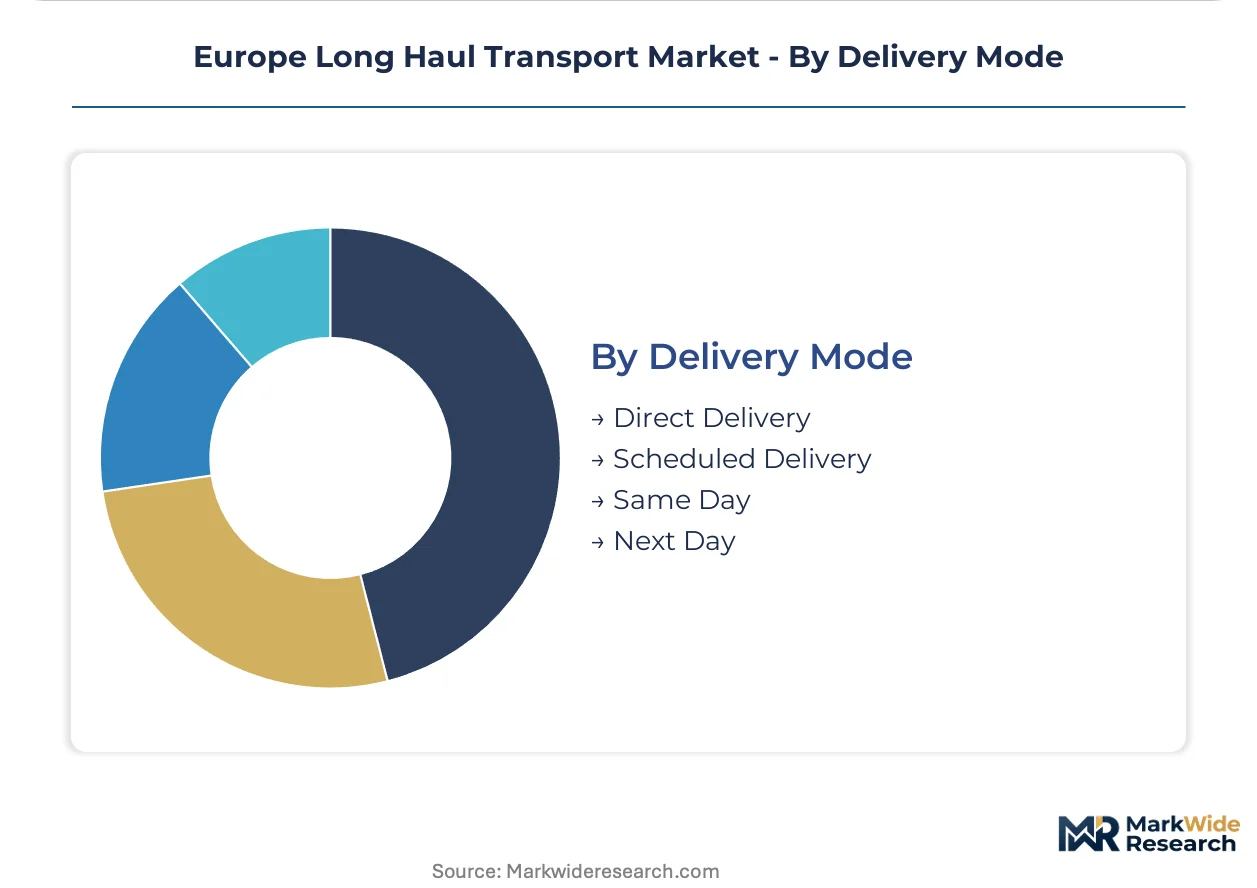
Maturity gradient separates established scheduled networks from emerging same-day capabilities that remain structurally constrained by long-haul distance economics.
- Direct Delivery:Point-to-point transport without intermediate consolidation, typical for high-value automotive components. Premium pricing reflects dedicated asset commitment and reduced handling risk.
- Scheduled Delivery:Recurring lane operations with fixed departure windows and contracted capacity. This segment anchors network density on Rhine-Alpine and North Sea-Baltic TEN-T corridors.
- Same Day:Expedited service within 24 hours, structurally limited to sub-500-kilometer ranges by driver hour regulations under EU Directive 2003/59/EC. Urban consolidation hubs in Milan and Madrid test operational feasibility.
- Next Day:24-48 hour delivery commitment balancing speed with cost efficiency. Pharmaceutical shippers in France and Germany are integrating this tier into ESG-weighted procurement scorecards under CSRD disclosure mandates.
Scheduled Delivery dominates network utilization. Next Day is where service premium expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal CO2 standards under Directive (EU) 2019/1242 are compressing fleet procurement cycles across member states. National type-approval authorities in Germany, France, and the Netherlands are accelerating powertrain transitions. Corridor-specific infrastructure investments are redrawing density maps on the TEN-T network.
Germany
Automotive just-in-sequence supply chains from Stuttgart and Munich are demanding contracted capacity on Rhine-Alpine corridors. KBA jurisdiction enforces stringent emission compliance timelines for heavy-duty fleet renewal. The Duisburg logistics cluster anchors multi-modal transshipment capacity linking road, rail, and inland waterway modes.
Poland
E-commerce fulfillment expansion around Warsaw and Wrocław is driving cross-border tractor-trailer density toward German distribution centers. EU cohesion funds are upgrading Baltic-Adriatic TEN-T corridor segments through Silesia. Katowice logistics parks are attracting controlled capacity agreements with owner-operator networks.
Netherlands
Rotterdam-Antwerp port hinterland traffic concentrates refrigerated trailer demand for pharmaceutical exports. ECHA REACH compliance requirements favor larger operators with dedicated sustainability functions. The Venlo distribution cluster supports overnight electric charging pilots for food retail chains.
Italy
Benelux-to-Milan automotive parts corridors favor dedicated fleet partnerships over transactional sourcing. ANSM pharmaceutical distribution guidelines under EU GDP standards expand temperature-controlled trailer deployment. Lombardy logistics hubs are testing platooning technology on A1 motorway segments.
Belgium
Pharmaceutical manufacturing clusters around Antwerp and Brussels drive premium cold chain service demand. F-Gas Regulation phase-down mandates under EU Regulation 517/2014 are accelerating transport refrigeration unit retrofits. Liège cargo airport integration is expanding road-air intermodal connectivity.
Europe Long Haul Transport Market Competitive Landscape
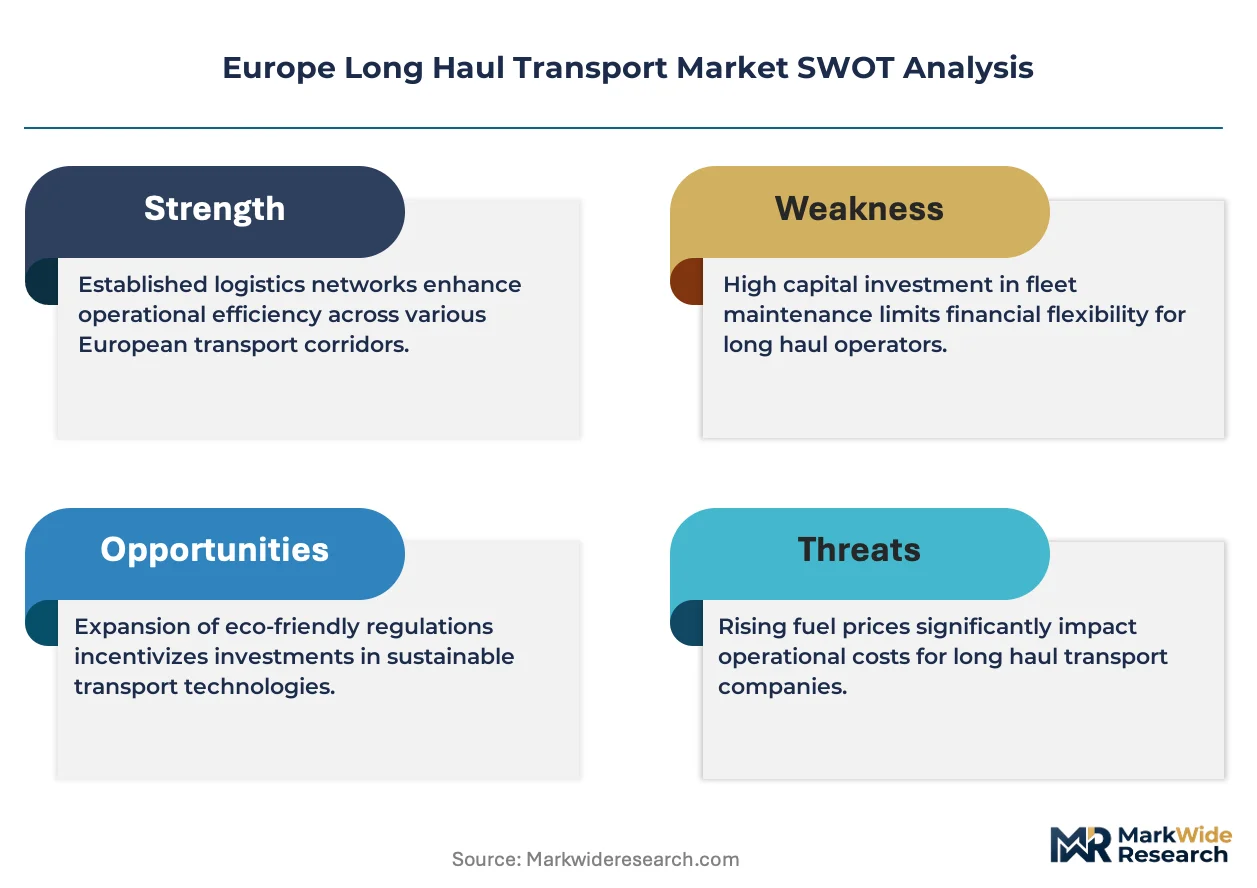
Player mix skews toward integrated logistics conglomerates with controlled capacity networks. Market structure concentrates around asset-heavy operators with dedicated fleet ownership and asset-light orchestrators leveraging subcontractor relationships. Two archetypes dominate: integrated road-rail-sea providers and specialized cold chain operators. Competitive moves center on strategic partnerships for charging infrastructure access and portfolio diversification into hydrogen fuel cell pilot programs.
Within the integrated logistics tier, Deutsche Post DHL Group and Kuehne + Nagel occupy positions anchoring cross-border density on core TEN-T corridors. Dachser Logistics exemplifies the mid-cap specialist archetype with concentrated Central European network control. DB Schenker represents the rail-integrated model combining captive intermodal capacity with road feeder operations. These operators sit within a competitive set where CE marking harmonization and CSRD disclosure mandates are raising barriers for smaller fleet operators lacking dedicated compliance infrastructure.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| CEVA Logistics |
| Deutsche Post DHL Group |
| FIEGE Logistics |
| Rhenus Logistics |
| Dachser Logistics |
| DB Schenker |
| XPO Logistics |
| DSV Panalpina |
| Others |
Supply & Pricing Matrix
CE marking under the EU's Vehicle Type Approval framework gates both fleet operator qualification and rate differentiation across European long-haul corridors. Operators without harmonized type-approval face exclusion from cross-border TEN-T lanes, compressing price competition among certified incumbents while premium cold chain services command spreads based on GDP compliance.
Pricing Analysis
Certification level (CE marking under EU Directive 96/53/EC) creates the primary spread between premium refrigerated pharmaceutical services and standard dry freight operations. Contract-based long-term offtake agreements dominate scheduled lane procurement, with automotive OEMs anchoring dedicated capacity at rates insulated from spot volatility. Cost compression in standard freight tiers is intensifying because battery-electric fleet amortization timelines remain uncertain against residual diesel asset values. E-commerce platforms exhibit highest price sensitivity, while pharmaceutical shippers under EU GDP guidelines prioritize temperature validation over per-kilometer rates.
Supply Chain Analysis
Germany and Poland anchor tractor-trailer manufacturing and assembly capacity serving Central European demand. Powertrain sourcing draws from battery cell production in Hungary and electric motor supply from Czech Republic industrial clusters. Single-source vulnerability concentrates in lithium-ion cell supply chains tethered to Asian production hubs. Distribution runs through owner-operator networks under controlled capacity agreements with integrated logistics providers, fragmenting last-mile feeder economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe long-haul transport operates as a regulatory-moat market where CE marking harmonization and CSRD disclosure mandates entrench incumbent positions through compliance infrastructure barriers. Switching costs for automotive OEMs amplify network effects on Rhine-Alpine corridors.
For Market Incumbents: Consolidate controlled capacity agreements with owner-operator networks across Poland and Czech Republic logistics hubs. Expand backward integration into megawatt charging infrastructure along Baltic-Adriatic TEN-T segments. Battery-electric range constraints on sub-500-kilometer lanes threaten diesel asset residual values, demanding accelerated powertrain portfolio diversification. For New Entrants and Emerging Players: Lead with F-Gas Regulation compliance services for refrigerated trailer retrofit demand in Belgium and Netherlands pharmaceutical corridors. Target underpenetrated Orient/East-Med TEN-T lanes through Slovakia and Hungary with hydrogen fuel cell pilot programs. Position around EU CSRD Scope 3 emissions documentation as a differentiated procurement gateway for German automotive shippers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric fleet procurement as megawatt charging infrastructure demands parallel investment. Five-to-ten-year viability favors operators with captive intermodal rail capacity and dedicated sustainability compliance functions. Acquisition targets should exhibit controlled owner-operator network density in CEE corridors. Signal to monitor: KBA enforcement timelines for CO2 performance standards under Directive (EU) 2019/1242.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Megawatt corridor deployment along Rhine-Alpine TEN-T axes reduces range anxiety for battery-electric fleet operators under KBA jurisdiction. |
| Controlled Capacity Agreement | Owner-operator network consolidation in Poland and Czech Republic secures cross-border density for e-commerce fulfillment expansion. |
| F-Gas Retrofit Program | Low-global-warming-potential refrigeration unit upgrades capture pharmaceutical cold chain premium in Belgium and Netherlands clusters. |
| Rail Intermodal Integration | Captive rail feeder capacity on North Sea-Baltic corridors insulates against driver qualification shortages under EU Directive 2003/59/EC. |
| Platooning Technology Pilot | Cooperative adaptive cruise control on Italian A1 motorway segments reduces fuel consumption and labor intensity for automotive parts lanes. |
Research Methodology
A standing panel of fleet operations directors, TEN-T corridor managers, pharmaceutical logistics procurement leads, and ECHA compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU transport statistics databases, KBA vehicle registration filings, EMA pharmaceutical distribution guidelines, and customs trade flow records. Bottom-up service segment sizing triangulated against top-down macroeconomic freight intensity models.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include service type, vehicle powertrain architecture, end-user industry, and delivery mode commitment tier. CAGRs derived from logistic curve adoption patterns for alternative powertrains and corridor-specific infrastructure investment trajectories. Forecast inputs incorporated EU Green Deal CO2 standard enforcement timelines and REACH compliance cost escalations.
Forecasts assume regulatory continuity in EU Directive (EU) 2019/1242 CO2 standards and EU Regulation 517/2014 F-Gas phase-down schedules; material policy shifts would require re-modeling. Specific risks include battery-electric range constraint breakthroughs, single-source lithium cell supply disruptions, and divergent member state CE marking interpretations. Recalibration cycles align with material shifts in powertrain cost parity timelines and TEN-T corridor infrastructure completion milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Czech Republic Road Freight Transport Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Parking Meter Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Boxcar Scars Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Nordics Road Freight Transport Market