
 Intermodal Freight Transportation Market | 2026-2036
Intermodal Freight Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Intermodal Freight Transportation Market Outlook
Software-defined freight orchestration is shifting how carriers bundle rail, road, and port services into unified contracts. J.B. Hunt Transport Services leverages its domestic container fleet to anchor high-frequency lane density between US interior markets and coastal ports. Kuehne + Nagel competes through proprietary control tower platforms that synchronize multi-leg shipments across European and Asian corridors. A.P. Moller-Maersk extends its ocean-rail integration into inland depot networks, reducing handoff friction for containerized agriculture and automotive cargo.
Intermodal freight transportation combines two or more transport modes under a single bill of lading, typically using standardized ISO containers with twist-lock corner castings and CSC safety approval to enable direct transfer between vessel, railcar, and chassis without cargo handling. Its primary purpose is to optimize cost per ton-mile by matching long-haul rail economies with flexible last-mile trucking. Rail mode dominates transcontinental volume in North America and Eurasia where double-stack car capacity reaches 20,000 TEU per train, while refrigerated container type commands premium pricing due to pharmaceutical and fresh-produce cold chain requirements. Service type stratification shows full container load capturing the majority of revenue, though less than container load aggregation is expanding among mid-sized retailers seeking inventory velocity without volume commitments.
The US EPA Tier 4 locomotive emissions standards and the EU Green Deal's Fit for 55 framework are accelerating carrier investment in alternative propulsion and terminal electrification, directly reshaping capital allocation for fleet renewal. China's MEE enforces GB standards on diesel truck access to port zones, pushing cargo toward rail feeders at Shanghai and Ningbo terminals. India's CEA and Dedicated Freight Corridor Corporation are expanding electrified broad-gauge corridors to absorb highway diversion. Stakeholders must monitor how carbon border adjustment mechanisms and fuel tax parity rules alter modal cost calculus before committing to long-term terminal and equipment contracts.
Market Dynamics
Software-defined freight orchestration platforms are compressing contract cycles from annual to quarterly, forcing asset-heavy carriers to rebalance fixed rail capacity against volatile truck spot markets.
Growth Catalysts
- EU Green Deal Fit for 55:The framework mandates 55% emissions reduction by 2030, redirecting cargo from road to electrified rail corridors across the Rhine-Alpine network.
- Pharmaceutical cold chain:Temperature-sensitive biologics require refrigerated ISO containers with real-time telemetry, creating premium intermodal demand.
- Double-stack rail economics:North American carriers achieve 20,000 TEU per train capacity, cutting per-unit costs below long-haul trucking on transcontinental lanes.
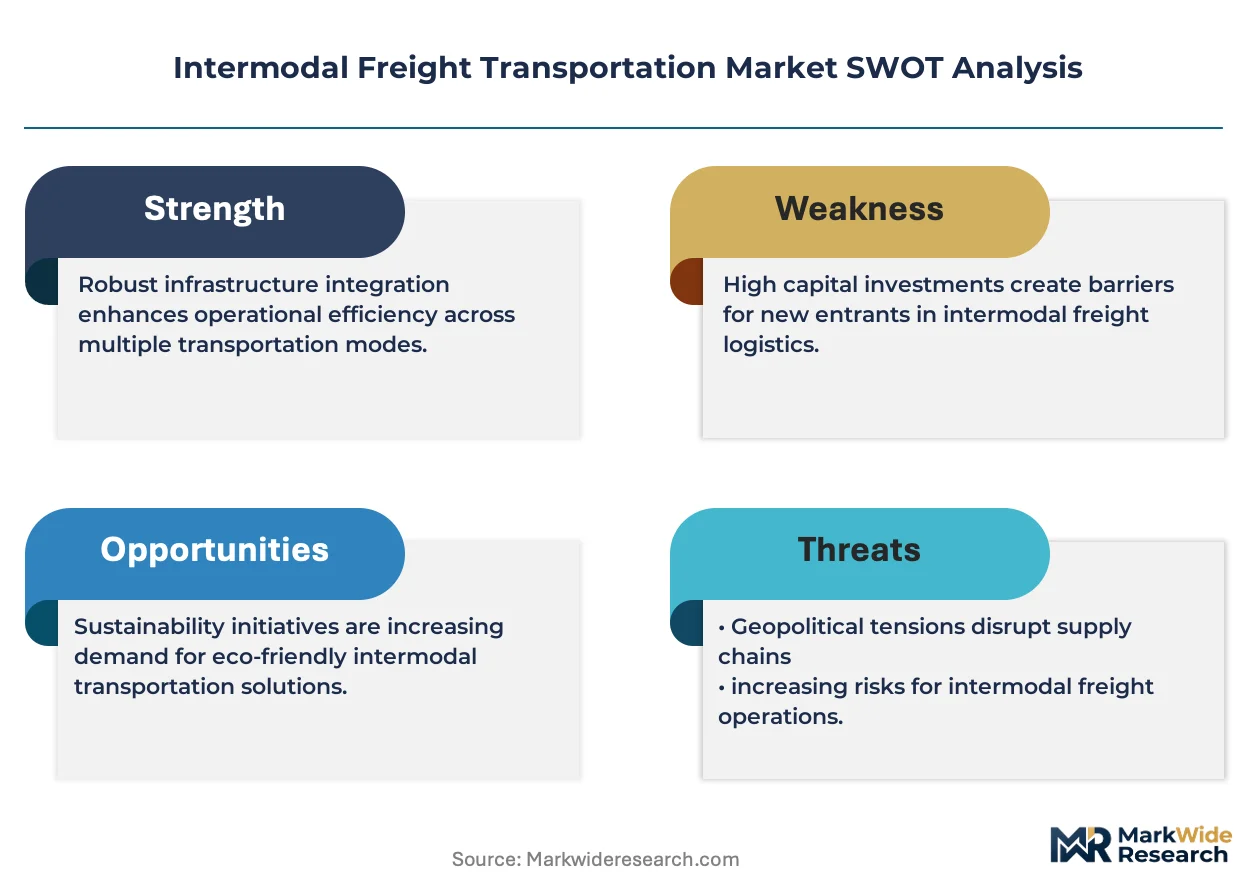
Market Restraints
- Terminal electrification capex:Shore power and crane conversion at inland depots requires capital commitments that strain mid-tier operators.
- Chassis pool concentration:US domestic container chassis availability clusters at Gulf Coast and Pacific port zones, creating equipment imbalances.
- Diesel price volatility:Drayage trucking legs remain exposed to fuel cost swings that rail contracts cannot fully hedge.
Strategic Opportunities
- India's Dedicated Freight Corridors:The CEA and DFCCIL electrified broad-gauge expansion absorbs highway diversion from Delhi-Mumbai industrial belts.
- Less-than-container-load aggregation:Mid-sized retailers seek inventory velocity without volume commitments, opening niche for digital freight platforms.
- Carbon border adjustment mechanisms:EU CBAM creates compliance-driven modal shifts for steel and automotive components entering Antwerp and Rotterdam.
Industry Challenges
- Interoperable data standards:Rail, port, and trucking systems use incompatible EDI protocols, forcing manual reconciliation at mode transfers.
- Twist-lock casting certification:CSC safety approval timelines delay container fleet renewal, constraining capacity during peak agricultural harvests.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intermodal Freight Transportation Market |
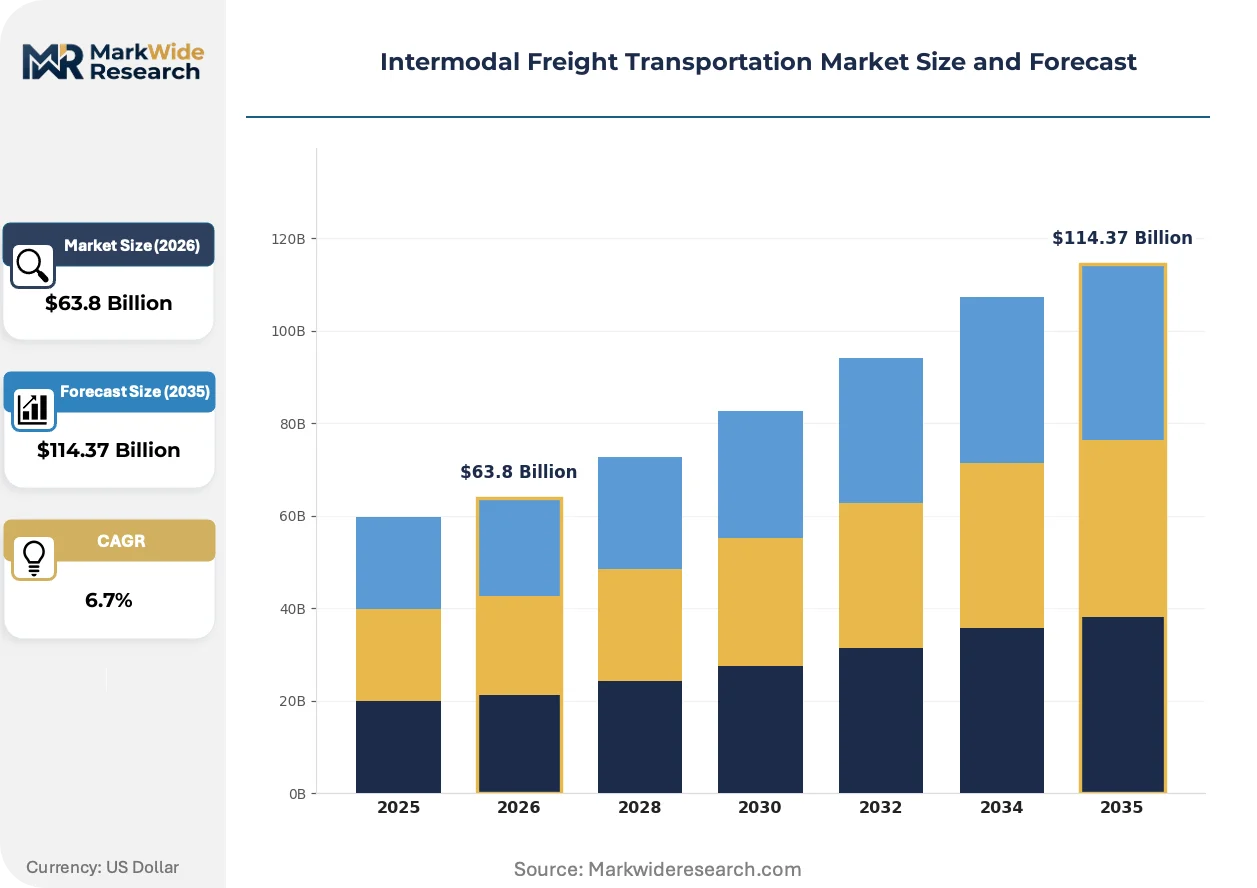
| Market Size in 2026 | $63.8 Billion |
| Market Size in 2035 | $114.37 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Mode: Rail, Road, Sea, Air Container Type: Standard, Refrigerated, Flat Rack, Open Top End User: Manufacturers, Retailers, Logistics Companies, Distributors Service Type: Full Container Load, Less Than Container Load, Intermodal Drayage, Transshipment |
| Companies Covered | Oracle Corporation, C.H. Robinson, DB Schenker, Kuehne + Nagel, DSV A/S, XPO Logistics, J.B. Hunt Transport Services, A.P. Moller-Maersk, Union Pacific Railroad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intermodal Freight Transportation Market Strategic Shifts
Digital freight matching platforms are dissolving traditional lane monopolies by algorithmically reallocating capacity across modal boundaries in real time.
Autonomous yard tractors are expanding into terminal operations to reduce chassis repositioning labor costs. Maersk and DP World deploy driverless shuttles at select inland depots in the Netherlands and UAE. The technology is expanding into 24/7 gate operations, compressing truck turn times from 90 minutes to under 30.
The US EPA Tier 4 locomotive emissions standards force fleet-wide engine retrofits or replacements by 2028. Rail carriers face $2-4 million per locomotive upgrade costs, accelerating consolidation among regional operators. Agricultural shippers in the Midwest corridor absorb fuel surcharge volatility as carriers pass compliance costs through contract structures.
Retail procurement teams now contract directly with intermodal marketing companies rather than relying on ocean carrier inland price bundles. This disintermediation fragments volume commitments across multiple rail providers. Apparel and electronics importers at Los Angeles-Long Beach increasingly source drayage, rail, and final-mile trucking as separate competitive bids.
Intermodal Freight Transportation Market Segmentation
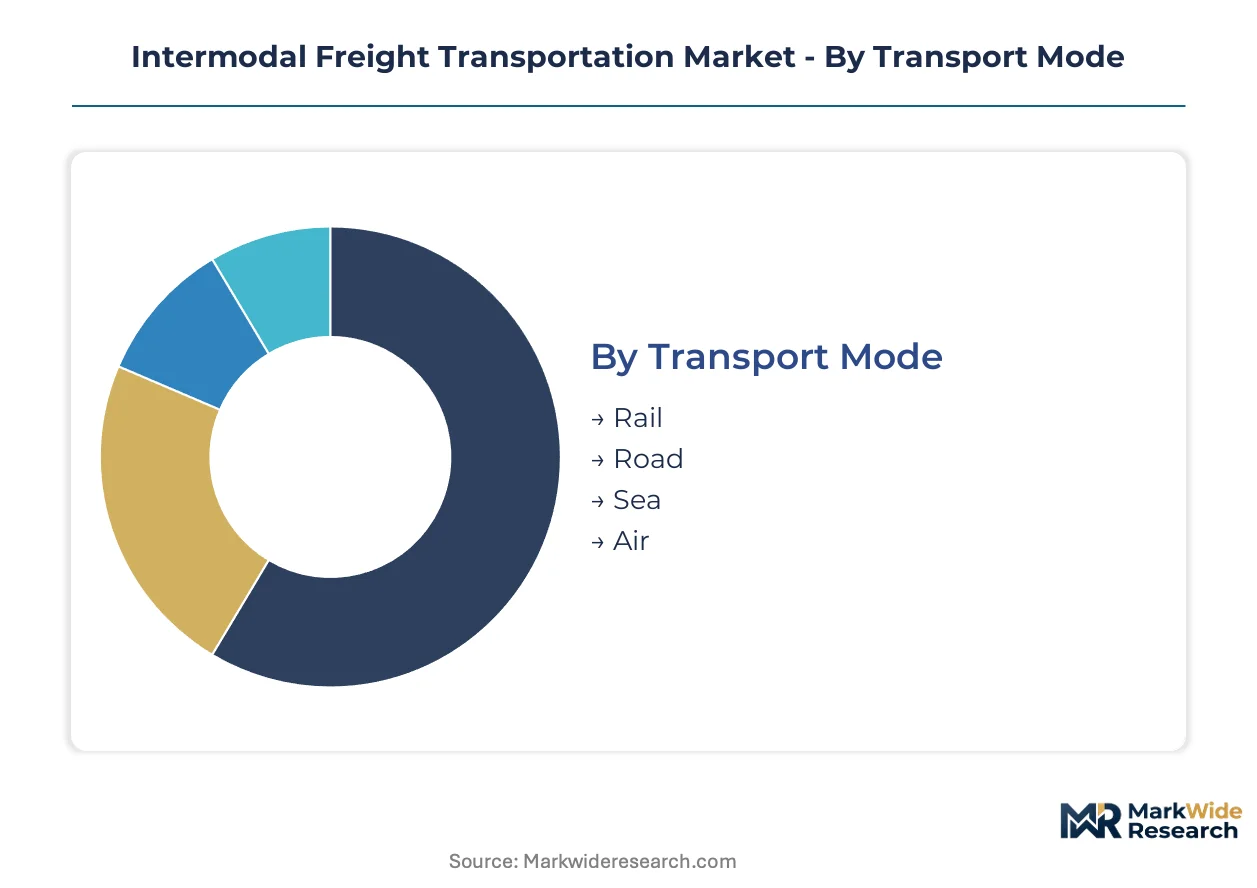
Intermodal freight segmentation determines equipment procurement, terminal infrastructure investment, and contract pricing structures. Carriers align fleet composition and service bundling against container specifications and modal combinations that match cargo density, temperature requirements, and delivery velocity demands.
Transport Mode:
Rail segments operate as embedded backbone capacity within multi-leg journeys, while road and air functions remain standalone final-mile or emergency interventions.
- Rail:Double-stack well cars and spine cars carry ISO containers across electrified corridors. Demand concentrates in the Germany-Netherlands-Belgium corridor where Rhine-Alpine networks connect North Sea ports to continental manufacturing hubs, driven by EU Green Deal Fit for 55 emissions mandates shifting cargo from highway to electrified track.
- Road:Chassis-mounted containers complete first and last-mile legs through drayage trucking and long-haul trucking. Fleets in the US Midwest agricultural belt face diesel price volatility and EPA Tier 4 compliance costs that carriers pass through fuel surcharge mechanisms.
- Sea:Deep-water vessels and feeder ships move containers between continental landmasses. Port calls at Shanghai and Ningbo absorb China's MEE diesel truck restrictions pushing cargo toward rail feeders.
- Air:Unit load devices and containerized cargo on freighter aircraft serve time-critical pharmaceuticals and electronics. Premium pricing reflects fuel intensity and slot scarcity at Frankfurt and Dubai hubs.
Rail leads volumes today; air is gaining share fastest among temperature-sensitive biologics corridors.
Container Type:
Cost tier stratification separates commodity dry cargo from premium temperature-controlled and specialized equipment categories.
- Standard:Dry van containers with CSC safety approval and twist-lock corner castings dominate general cargo. Retailers expanding intermodal adoption to reduce per-unit shipping costs drive procurement of forty-foot equivalent units across US interior-to-coastal lanes.
- Refrigerated:Insulated boxes with integrated gensets or cryogenic cooling maintain pharmaceutical cold chains. Real-time telemetry requirements from FDA and EMA distribution guidelines command premium lease rates.
- Flat Rack:Collapsible end-wall platforms accommodate oversized machinery and project cargo. Steel and automotive components entering EU ports under CBAM compliance drive modal shifts toward rail-integrated flat rack movements.
- Open Top:Removable tarpaulin roofs enable top-loading of bulk minerals and heavy equipment. India's DFCCIL electrified corridors absorb highway diversion for coal and ore movements from mining belts to port processors.
Standard containers lead volumes today; refrigerated units are climbing the fastest on biologics distribution expansion.
End User:
Customer type determines contract structure complexity, from direct asset control by manufacturers to outsourced orchestration by logistics intermediaries.
- Manufacturers:Automotive and electronics producers negotiate directly with intermodal marketing companies for inbound component flows. J.B. Hunt Transport Services anchors high-frequency lane density between US interior markets and coastal ports for this segment.
- Retailers:Apparel and consumer goods importers fragment volume commitments across competitive bids for drayage, rail, and final-mile trucking. Procurement teams now bypass ocean carrier inland bundles.
- Logistics Companies:Third-party operators aggregate less-than-container-load shipments through proprietary control tower platforms. Kuehne + Nagel synchronizes multi-leg movements across European and Asian corridors.
- Distributors:Wholesale intermediaries seek inventory velocity without volume commitments, opening niche demand for digital freight matching platforms.
Manufacturers lead volumes today; retailers are expanding most quickly through disintermediated procurement.
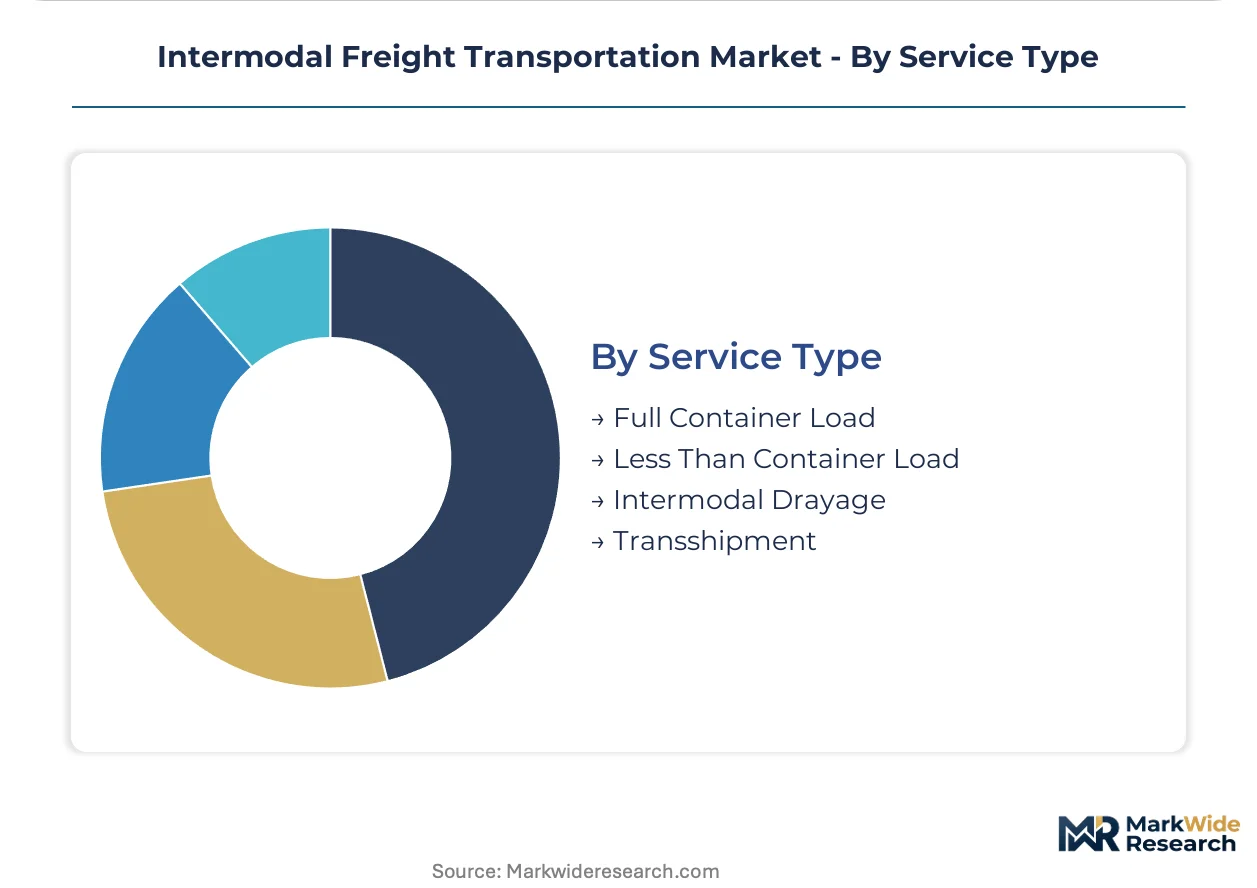
Service Type:
Volume scale and commitment duration separate committed contract structures from spot-market flexibility.
- Full Container Load:Single-shipper exclusive use of twenty-foot or forty-foot units. Captures majority revenue through annual contracts with agricultural exporters in Midwest US corridors.
- Less Than Container Load:Consolidated shipments from multiple shippers sharing container space. Mid-sized retailers seeking inventory velocity without volume commitments drive platform-based aggregation.
- Intermodal Drayage:Short-haul truck movements connecting ports to rail terminals. Chassis pool concentration at Gulf Coast and Pacific zones creates equipment imbalances.
- Transshipment:Container relay between vessels or modes at intermediate hubs. A.P. Moller-Maersk extends ocean-rail integration into inland depot networks to reduce handoff friction.
Full container load leads volumes today; less than container load is gaining share fastest among digital freight adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Alpine corridor moves higher container volumes per rail kilometer than Canada's prairie rail networks, yet both face divergent regulatory pressures on diesel-to-electric transitions.
United States
Midwest agricultural exporters and West Coast apparel importers drive transcontinental container flows. EPA Tier 4 locomotive emissions standards force $2-4 million per locomotive upgrade costs by 2028. Chicago anchors the largest inland rail hub, where J.B. Hunt Transport Services maintains high-frequency lane density between interior markets and coastal ports.
Germany
Automotive component manufacturers and chemical producers demand electrified rail corridors for inbound supply chains. EU Green Deal Fit for 55 mandates 55% emissions reduction by 2030, redirecting cargo from highway to rail. The Rhine-Alpine network connects Rotterdam and Antwerp ports to Stuttgart and Munich manufacturing belts.
China
E-commerce fulfillment centers and steel exporters generate heavy port-to-interior container movements. MEE enforces GB standards restricting diesel truck access to Shanghai and Ningbo port zones, pushing cargo toward rail feeders. The Yangtze River Delta integrates ocean-rail movements through Ningbo-Zhoushan terminal complexes.
India
Coal and ore movements from mining belts to port processors absorb expanding electrified capacity. CEA and DFCCIL broaden electrified broad-gauge corridors to capture highway diversion from Delhi-Mumbai industrial belts. Gujarat's Mundra and Hazira ports connect to northern hinterlands via Dedicated Freight Corridor infrastructure.
Netherlands
Rotterdam's status as Europe's largest seaport generates massive container transshipment demand. EU CBAM carbon border adjustments create compliance-driven modal shifts for steel and automotive components entering Antwerp and Rotterdam. Maersk and DP World deploy autonomous yard tractors at inland depots to compress truck turn times.
Intermodal Freight Transportation Market Competitive Environment
Top-tier vendors anchor integrated multimodal platforms, while mid-tier specialists compete on lane-specific density or digital orchestration capabilities. The market structure shows consolidation among asset-heavy rail carriers and ocean lines, with fragmentation in drayage trucking and freight brokerage segments. Three archetypes dominate: integrated logistics conglomerates with proprietary control towers, railroad operators with captive container fleets, and digital freight platforms aggregating spot capacity. Competitive moves center on M&A to secure terminal access and strategic partnerships to stitch together multi-leg service bundles.
Within the integrated logistics tier, Kuehne + Nagel and DSV A/S exemplify control tower operators synchronizing multi-leg shipments across European and Asian corridors. J.B. Hunt Transport Services occupies a distinct position as a domestic container fleet operator anchoring high-frequency US interior-to-coastal density. Among asset-heavy rail incumbents, Union Pacific Railroad represents the class I carrier archetype with embedded backbone capacity across North American transcontinental lanes.
| Leading Market Players |
|---|
| Oracle Corporation |
| C.H. Robinson |
| DB Schenker |
| Kuehne + Nagel |
| DSV A/S |
| XPO Logistics |
| J.B. Hunt Transport Services |
| A.P. Moller-Maersk |
| Union Pacific Railroad |
| Others |
Value Chain & Pricing Dynamics
Refrigerated container premiums against standard dry van rates bifurcate the intermodal freight market into temperature-controlled and commodity tiers, with pharmaceutical cold chain requirements from FDA and EMA distribution guidelines compressing lease spreads at the premium end while agricultural exporters in Midwest US corridors absorb fuel surcharge pass-throughs at the commodity base. This tier divergence manifests in equipment procurement cycles where refrigerated genset retrofits concentrate capital allocation among top-tier carriers, while dry van spot markets fragment across digital freight platforms competing on lane density rather than asset control.
Pricing Analysis
Capacity additions in China's electrified rail corridors are reshaping price floors for Asia-Europe container movements as MEE diesel truck restrictions at Shanghai and Ningbo terminals redirect cargo toward state-backed rail feeders. Contract pricing stratifies across premium refrigerated, standard dry van, and economy bulk equipment tiers, with temperature-controlled biologics commanding three-lease-rate multiples driven by real-time telemetry mandates. Price erosion runs through standard container spot markets as digital freight matching platforms dissolve traditional lane monopolies through algorithmic capacity reallocation. Mid-sized retailers seeking inventory velocity without volume commitments exhibit highest price sensitivity, while pharmaceutical distributors accept premium fixed-rate structures to secure cold chain integrity.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for logistics infrastructure are reshaping sourcing patterns for terminal equipment and electrified rolling stock as DFCCIL expands Dedicated Freight Corridor procurement. Container manufacturing concentrates in China, South Korea, and Vietnam, while chassis production clusters in Mexico and the US Gulf Coast to serve North American drayage demand. The supply chain draws from high-tensile steel plate, refrigeration compressors, and telematics sensor arrays as core inputs. Single-source vulnerability around Chinese container corner casting and CSC certification approvals creates bottlenecks during peak agricultural harvests. Distribution runs through ocean carrier inland price bundles, direct rail contracts, and fragmented drayage broker networks depending on shipper size and lane density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intermodal freight transportation market functions as a stable compounder anchored by structural modal shift mandates from EU Green Deal Fit for 55 and EPA Tier 4 locomotive standards that lock in decade-long equipment renewal cycles regardless of freight demand volatility.
For Market Incumbents: Anticipate margin compression from digital freight platforms dissolving lane monopolies through real-time algorithmic matching. Consolidate terminal access through M&A to secure inland depot networks before autonomous yard tractors compress turn times below 30 minutes. Prioritize backward integration into refrigerated container fleets to capture pharmaceutical cold chain premiums as biologics distribution expands.
For New Entrants and Emerging Players: Digital freight aggregators represent the most penetrable channel partner type for mid-sized retailers seeking inventory velocity without volume commitments. Target less-than-container-load consolidation platforms across US interior-to-coastal lanes where procurement teams bypass ocean carrier inland bundles. Pursue white-space in India Dedicated Freight Corridor electrified corridors where highway diversion from Delhi-Mumbai industrial belts outpaces carrier capacity additions.
For Investors and Strategic Acquirers: Consolidation pressure builds where chassis pool concentration at Gulf Coast and Pacific port zones creates equipment imbalances that strain mid-tier operators. Frame long-term viability around captive terminal access and proprietary control tower platforms that synchronize multi-leg movements across modal boundaries. Monitor carbon border adjustment mechanism implementation at Antwerp and Rotterdam as the signal indicating compliance-driven modal shift acceleration for steel and automotive components.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Electrification Investment | Shore power and crane conversion at inland depots aligns with EU Green Deal Fit for 55 mandates. |
| Refrigerated Fleet Expansion | Integrated genset containers capture pharmaceutical cold chain premiums from FDA distribution guidelines. |
| Digital Platform Integration | Algorithmic capacity matching dissolves traditional lane monopolies across modal boundaries. |
| Autonomous Yard Deployment | Driverless shuttles at Netherlands and UAE depots compress truck turn times from 90 to 30 minutes. |
| Dedicated Freight Corridor Access | DFCCIL electrified broad-gauge expansion absorbs highway diversion from Delhi-Mumbai industrial belts. |
Study Parameters
Bottom-up container volume modeling reconciled against top-down carrier capacity tracking forms the analytical core of this study. Primary interviews with rail operations executives, intermodal marketing company procurement leads, terminal infrastructure planners, and pharmaceutical logistics directors combined with secondary validation from EPA emissions filings, EU Green Deal implementation reports, SEC 10-K disclosures from Class I railroads, and customs trade data from Rotterdam and Los Angeles-Long Beach port authorities. Triangulation between shipper contract structures and carrier equipment deployment schedules anchors volume estimates.
Input-output matrices map container type specifications against modal combinations and end-user procurement patterns across the projection horizon. Segmentation dimensions include transport mode, container temperature control tier, service commitment structure, and regional regulatory cluster. CAGRs derive from equipment replacement cycles, emissions compliance deadlines, and modal shift elasticity coefficients. Forecast inputs incorporate locomotive Tier 4 retrofit timelines, refrigerated container genset deployment rates, and digital freight platform market penetration curves.
Revisions become necessary when carbon border adjustment mechanisms expand product coverage, autonomous yard tractor deployment accelerates beyond pilot depots, or chassis pool restructuring eliminates Gulf Coast-Pacific imbalances. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and fuel tax parity maintenance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Colombia Road Freight Transport Market
Transportation & Logistics
Poland Road Freight Transport Market