
 Europe Road Freight Transport Market | 2026-2036
Europe Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Road Freight Transport Market Analysis
German trucking capacity is rebalancing after energy cost shocks reshaped fleet economics. DHL Group leverages its integrated European network to sustain cross-border density. DSV AS anchors Nordic-Baltic lanes through disciplined asset-light positioning. DACHSER SE specializes in temperature-controlled pharmaceutical road freight across Central Europe.
Road freight transport encompasses the movement of goods by motorized vehicles over paved highway infrastructure, utilizing heavy-duty trucks with gross vehicle weights exceeding 12 tonnes and light-duty fleets for last-mile distribution, serving as the dominant mode for intra-European trade in manufactured goods, perishables, and retail inventory. Full Truckload services dominate margin pools on major corridors, while Less Than Truckload competes through consolidation efficiency in fragmented shipper bases. Refrigerated Trucks command premium pricing due to pharmaceutical cold-chain compliance and fresh food safety protocols.
The EU Green Deal and its Fit for 55 framework are forcing diesel fleet phase-outs through CO2 performance standards for heavy-duty vehicles. ECHA chemical safety rules and national toll schemes in Germany, Poland, and Austria reshape total cost of ownership calculations for operators. Stakeholders must monitor battery-electric and hydrogen truck infrastructure buildouts alongside evolving cabotage enforcement to align fleet investment with regulatory trajectory.
Market Dynamics
The EU Green Deal's Fit for 55 framework is compressing diesel fleet economics while battery-electric and hydrogen infrastructure buildouts force capital reallocation across European road freight operators.
Growth Catalysts
- E-commerce logistics density:Parcel volumes on the Germany-Poland-Netherlands corridor are pulling dedicated fleet investment and cross-border warehouse positioning from DHL Group and DSV AS.
- EU Green Deal mandates:CO2 performance standards for heavy-duty vehicles are accelerating zero-emission truck procurement timelines and charging infrastructure deployment.
- Pharmaceutical cold-chain expansion:Temperature-controlled road freight demand from EMA-regulated biologics distribution is commanding premium rate structures across Central Europe.
Market Restraints
- Energy cost volatility:Diesel price fluctuations and electricity grid instability in Germany and Poland are distorting total cost of ownership calculations for fleet operators.
- Driver shortage concentration:Aging workforce demographics in Italy and Spain are tightening capacity on southern European lanes faster than training pipelines can replenish.
- Cabotage enforcement fragmentation:Inconsistent interpretation of EU mobility rules across member states is creating regulatory friction for international operators.
Strategic Opportunities
- Baltic corridor underpenetration:Lithuania and Latvia offer lane density expansion potential as Nordic-Baltic trade flows consolidate through disciplined asset-light positioning.
- Battery-electric truck convergence:Integration of megawatt charging systems with fleet management software is enabling depot-based electrification for urban distribution.
- CSRD disclosure requirements:Scope 3 emissions reporting mandates are creating service differentiation opportunities for operators with verified carbon accounting infrastructure.
Industry Challenges
- Technician skill gaps:High-voltage electrical systems and hydrogen fuel cell maintenance require retraining programs that outpace current vocational pipeline output.
- Multi-fuel fleet complexity:Parallel diesel, battery-electric, and hydrogen vehicle operations are straining maintenance scheduling and parts inventory systems.
- Permitting timeline compression:Grid connection approvals for depot charging infrastructure in the Netherlands and Germany are extending lead times beyond vehicle delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Road Freight Transport Market |
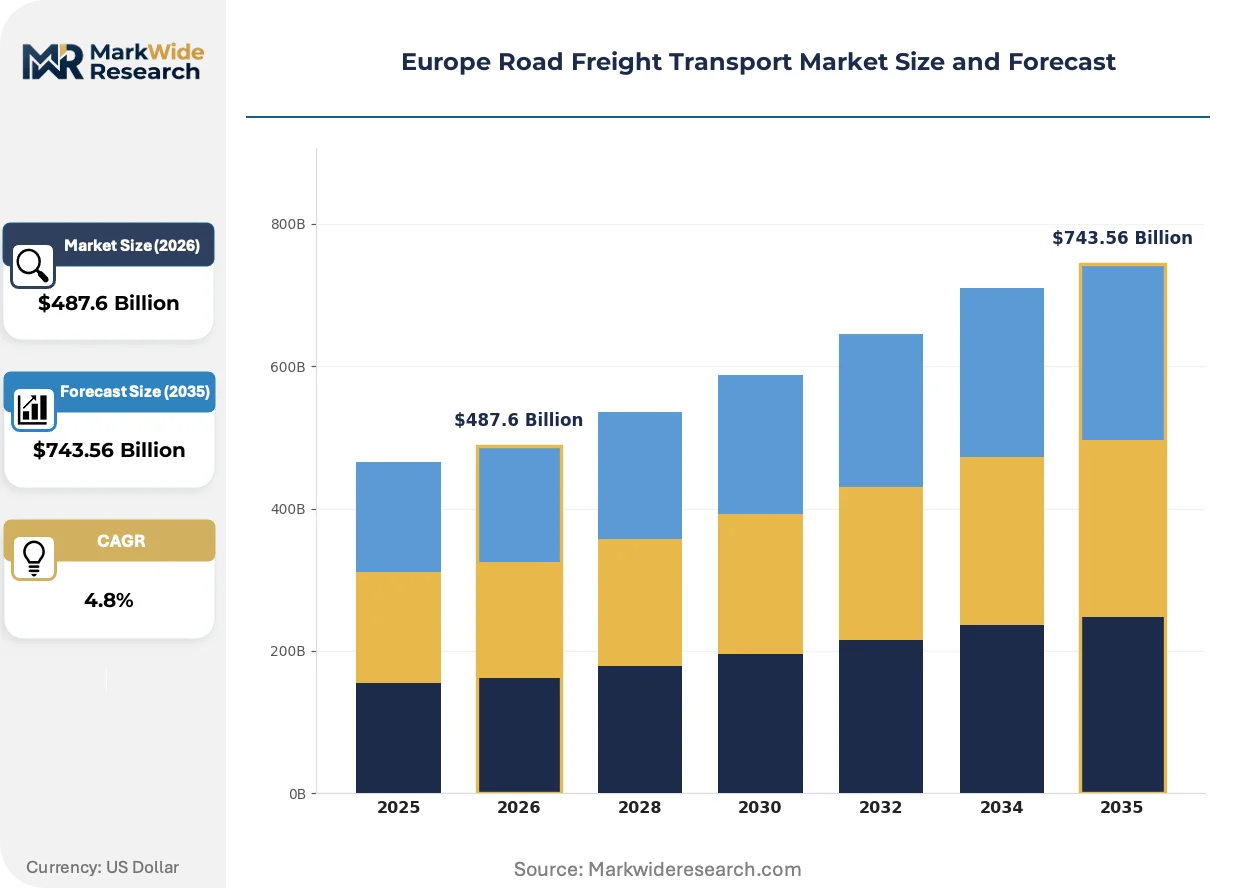
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Intermodal, Dedicated Freight Vehicle Type: Heavy-duty Trucks, Light-duty Trucks, Cargo Vans, Refrigerated Trucks End User: Retail, Manufacturing, E-commerce, Food & Beverage Operational Model: Contractual, Spot Market, In-house, Third-party Logistics |
| Companies Covered | DHL Group, DSV AS, Kuehne Nagel Management AG, DACHSER SE, UAB Girteka Logistics, DB Schenker, AP Moller Maersk AS, CEVA Logistics, Rhenus SE and Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Road Freight Transport Market Emerging Trajectories
Telematics and predictive analytics are compressing empty-mile ratios while alternative powertrain deployment reshapes fleet capital structures across European road freight.
Telematics platforms that fuse real-time traffic data with cargo temperature monitoring are integrating dispatch optimization and compliance documentation into unified control systems. Pharmaceutical distributors and fresh food retailers are adopting these systems fastest, with deployment timelines compressing from multi-year rollouts to 12-month implementations. This convergence is integrating route efficiency gains with automated proof-of-condition reporting, collapsing the operational gap between transport execution and customer visibility.
The EU Green Deal's CO2 performance standards are mandating progressive emission reductions for heavy-duty vehicle manufacturers through binding fleet-average targets. Operators face compressed diesel resale values and accelerated obsolescence timelines as 2035 phase-out dates approach. German and Dutch fleets are responding with pre-emptive battery-electric procurement, while Polish operators delay commitment pending charging infrastructure density improvements.
Shippers are consolidating carrier relationships around bundled visibility and carbon reporting services rather than transactional spot-rate procurement. Long-term framework agreements with embedded emissions tracking are displacing annual tender cycles in retail and automotive verticals. This concentration is most visible in the Netherlands, where sustainability-linked contract structures now govern a majority of contracted tonnage.
Europe Road Freight Transport Market Segmentation
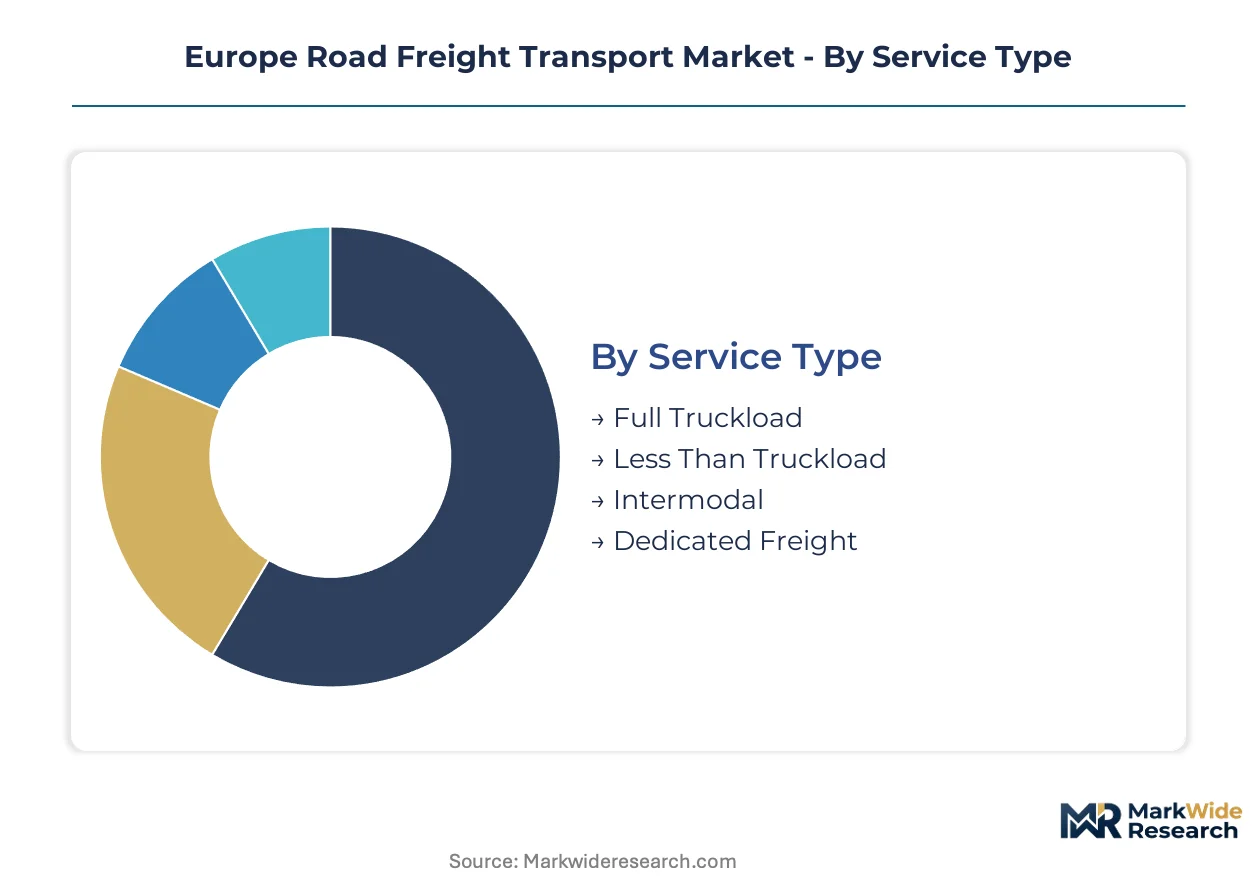
Road freight segmentation in Europe reflects divergent buyer priorities across service reliability, payload optimization, and regulatory compliance. Shippers select service tiers based on cargo value density, temperature sensitivity, and route predictability rather than cost alone.
Service Type:
Fleet investment decisions hinge on contract duration and lane density predictability.
- Full Truckload:Dedicated vehicle capacity for single-shipper cargo moving direct from origin to destination without intermediate handling. Manufacturing supply chains across the Germany-Poland corridor favor this mode for just-in-time component delivery where schedule reliability outweighs unit cost.
- Less Than Truckload:Consolidated shipments from multiple shippers sharing trailer capacity through hub-and-spoke terminal networks. E-commerce fulfillment networks in the Netherlands deploy LTL for mid-volume SKUs where daily frequency matters more than exclusive vehicle access.
- Intermodal:Seamless truck-rail-truck combinations leveraging rail corridors for long-haul emission reduction.
- Dedicated Freight:Exclusive fleet assignment for single-account operations with embedded drivers and equipment.
Volume sits with Full Truckload; growth tilts toward Intermodal as EU Green Deal compliance pressures mount.
Vehicle Type:
Powertrain selection now dominates procurement committees alongside payload specification.
- Heavy-duty Trucks:Tractor-trailer combinations exceeding 12 tonnes gross vehicle weight serving long-haul international lanes. Battery-electric variants are penetrating German depot-based distribution fleets where overnight charging aligns with duty cycles.
- Light-duty Trucks:Rigid vehicles under 12 tonnes GVW handling urban distribution and last-mile consolidation. Parcel carriers in Dutch cities are electrifying these fleets fastest due to low daily mileage and established charging infrastructure.
- Cargo Vans:Unibody commercial vehicles under 3.5 tonnes for dense urban access and restricted zones.
- Refrigerated Trucks:Insulated and mechanically cooled trailers maintaining temperature-controlled environments for perishables and pharmaceuticals. EMA-regulated biologics distribution across Central Europe commands premium rate structures for these units.
Heavy-duty Trucks carry the tonnage base; Refrigerated Trucks are climbing the fastest on pharmaceutical cold-chain expansion.
End User:
Vertical-specific compliance requirements reshape carrier qualification criteria.
- Retail:Scheduled distribution to regional distribution centers and store replenishment with strict delivery windows. Fashion and general merchandise retailers in Germany prioritize carriers with real-time visibility integration.
- Manufacturing:Component inbound logistics and finished goods outbound serving assembly plants and distribution networks. Automotive OEMs in Poland require sequenced delivery capabilities synchronized to production line takt times.
- E-commerce:Parcel and small-package final-mile delivery with returns handling and customer notification systems.
- Food & Beverage:Temperature-sensitive distribution with hazard analysis critical control point documentation and traceability requirements.
Manufacturing anchors contracted capacity; E-commerce is gaining share fastest on parcel volume expansion.
Operational Model:
Asset ownership strategy separates balance-sheet-heavy operators from network orchestrators.
- Contractual:Multi-year framework agreements with rate stability, dedicated capacity, and embedded service level agreements. Dutch retail and automotive verticals now mandate sustainability-linked contract structures governing majority of contracted tonnage.
- Spot Market:Transactional procurement through digital freight platforms and broker networks for surge and backhaul optimization. Polish operators leverage spot markets to rebalance equipment after unidirectional agricultural harvest flows.
- In-house:Captive fleet operations owned and operated by shipper organizations for core lane control.
- Third-party Logistics:Outsourced transportation management with integrated warehousing, inventory control, and value-added services.
Contractual relationships hold the volume base; Third-party Logistics shows the steepest expansion trajectory on shipper preference for bundled visibility and carbon reporting services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diesel refining capacity around Rotterdam anchors northwest European freight economics. The Rhine-Ruhr industrial corridor generates dense manufacturing flows that feed cross-border lane networks. Baltic port infrastructure is reshaping east-west cargo routing as Polish manufacturing expands.
Germany
Automotive component flows from Stuttgart and Wolfsburg drive dedicated fleet demand for just-in-time sequencing. The EU Green Deal's CO2 performance standards are accelerating battery-electric truck procurement through KBA fleet registration mandates. The Rhine-Main logistics cluster around Frankfurt is consolidating as operators pre-position zero-emission capacity ahead of 2035 phase-out deadlines.
Poland
Contract manufacturing expansion near Poznań and Wrocław is pulling cross-border warehouse investment from German retailers. National toll schemes on the A2 and A4 corridors are reshaping total cost of ownership calculations for international operators. The Silesian industrial basin is emerging as a consolidation hub for eastbound freight entering Ukraine and Baltic states.
Netherlands
Rotterdam port throughput and Schiphol air cargo connectivity generate high-value pharmaceutical distribution demand. CSRD disclosure requirements are embedding sustainability-linked contract structures into majority of contracted tonnage. The Randstad logistics ring is deploying megawatt charging infrastructure fastest due to urban distribution electrification mandates.
France
Paris basin retail distribution and Lyon pharmaceutical manufacturing sustain temperature-controlled lane density. ECHA chemical safety rules are tightening trailer specifications for hazardous cargo crossing German and Belgian borders. The Grand Est region is gaining intermodal traction as Rhine corridor congestion pushes freight toward rail-truck combinations.
Italy
Fashion and luxury goods exports from Milan and Florence require high-security dedicated fleet assignment. Aging workforce demographics are tightening driver availability faster than regional training pipelines can replenish. The Po Valley manufacturing belt is experiencing capacity constraints on northbound lanes toward German distribution centers.
Europe Road Freight Transport Market Vendor Landscape
Global majors compete with regional champions across network density and specialized service capabilities. The vendor base separates into integrated pan-European operators, Nordic-Baltic lane specialists, and temperature-controlled niche providers. Three archetypes dominate: asset-heavy fleet owners balancing diesel obsolescence risk, asset-light network orchestrators leveraging brokered capacity, and vertical specialists commanding premium rates through compliance certification. M&A activity concentrates on cross-border terminal networks and electric fleet assets, while strategic partnerships target charging infrastructure sharing.
Within the integrated logistics tier, DHL Group and DSV AS represent contrasting scale approaches to European network coverage. DACHSER SE exemplifies the specialized pharmaceutical cold-chain archetype through its Central European density. UAB Girteka Logistics anchors the asset-heavy Baltic corridor position. These operators occupy positions that reflect divergent bets on electrification timing, lane concentration, and vertical service bundling.
| Leading Market Players |
|---|
| DHL Group |
| DSV AS |
| Kuehne Nagel Management AG |
| DACHSER SE |
| UAB Girteka Logistics |
| DB Schenker |
| AP Moller Maersk AS |
| CEVA Logistics |
| Rhenus SE and Co. KG |
| Others |
Supply Flow & Price Mechanics
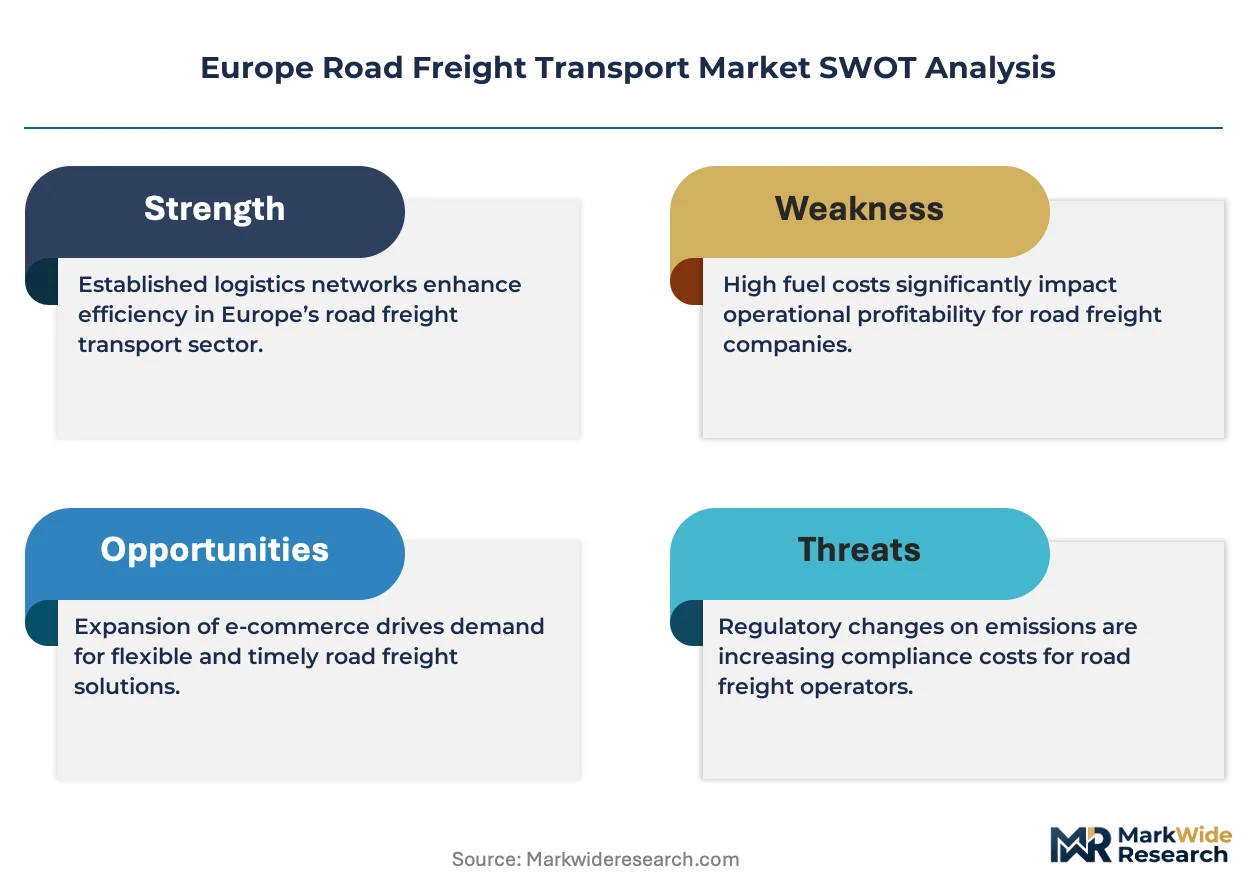
EU Green Deal procurement mandates are forcing fleet operators to bundle carbon reporting with core freight services, compressing margins on unbundled spot-rate transactions while rewarding integrated sustainability-linked contract structures.
Pricing Analysis
Warranty and service bundling separates contractual pricing from transactional spot markets. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain certification grade and embedded emissions tracking capabilities. Price differentiation centers on pharmaceutical GDP compliance and real-time visibility integration. Pricing pressure stems from diesel resale value collapse as KBA fleet registration mandates accelerate zero-emission procurement timelines. E-commerce parcel carriers exhibit highest price sensitivity; EMA-regulated biologics distributors accept premium positioning.
Supply Chain Analysis
CE marking and GDP certification gating restricts trailer procurement to qualified manufacturers in Germany, Poland, and the Netherlands. Raw material dependencies include high-voltage battery systems, hydrogen fuel cell stacks, and refrigerated insulation composites. Supply chain risk concentrates on single-source vulnerability for megawatt charging infrastructure components. Distribution runs through Rotterdam port clusters and Rhine-Ruhr terminal networks serving cross-border lane density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Fit for 55 framework has erected a cost-of-compliance moat where CSRD disclosure infrastructure and zero-emission fleet certification now function as barrier-to-entry mechanisms favoring capitalized incumbents.
For Market Incumbents: Hedge diesel obsolescence risk through pre-emptive battery-electric procurement in German depot-based distribution fleets. Secure grid connection permits for charging infrastructure ahead of vehicle delivery schedules. Reinforce cross-border terminal network density through Baltic corridor acquisitions. For New Entrants and Emerging Players: Digital freight platforms offer the most penetrable channel partner type for asset-light market entry. Target Lithuanian and Latvian lane consolidation as Nordic-Baltic trade flows reshape east-west routing. Pursue pharmaceutical cold-chain specialization through EMA-regulated GDP certification investment. For Investors and Strategic Acquirers: The window for entry favors asset-light network orchestrators with embedded carbon accounting infrastructure. Long-term viability concentrates on operators capable of integrating megawatt charging systems with fleet management software. Watch battery-electric truck infrastructure buildout velocity as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Emission Fleet Procurement | Pre-positions operators ahead of KBA diesel phase-out mandates tightening fleet economics. |
| Megawatt Charging Infrastructure Deployment | Enables depot-based electrification for urban distribution fleets in Dutch Randstad logistics clusters. |
| Cross-Border Terminal Network Expansion | Captures Baltic corridor density as Polish manufacturing pulls warehouse investment eastward. |
| Pharmaceutical GDP Certification Investment | Commands premium rate structures for EMA-regulated biologics distribution across Central Europe. |
| CSRD-Compliant Carbon Accounting Integration | Differentiates service offerings as Dutch retail verticals mandate sustainability-linked contract structures. |
Methodological Framework
Multi-period observation of fleet registration data, charging infrastructure deployment timelines, and cross-border lane density metrics anchored the trend analysis, supplemented by interviews with fleet operations directors, EU regulatory affairs specialists, pharmaceutical logistics managers, and intermodal terminal operators. Secondary validation drew from KBA vehicle statistics, Eurostat trade flow databases, EMA GDP inspection reports, and EU Green Deal implementation tracking. Bottom-up service-type segmentation triangulated against top-down corridor-level volume estimates.
Input-output matrix modeling connected powertrain adoption curves with infrastructure buildout assumptions across the projection horizon. Segmentation dimensions spanned service type, vehicle class, end-use vertical, operational model, and regional regulatory cluster. CAGRs derived from logistic curve fitting of zero-emission penetration rates and diesel fleet retirement schedules. Forecast inputs incorporated ECHA chemical safety compliance costs and national toll scheme evolution in Germany, Poland, and Austria.
Caveats apply where grid connection approval delays, hydrogen infrastructure buildout shortfalls, or cabotage enforcement fragmentation could materially shift the outlook. Forecasts reflect assumptions about battery-electric total cost of ownership convergence and charging network density thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
Perishable Goods Transportation Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
Train Collision Avoidance System Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Inland Water Freight Transport Market