
 Digital Shipment Market | 2026-2036
Digital Shipment Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Shipment Market Analysis
Buyer concentration among e-commerce platforms is pivoting toward integrated logistics providers that bundle fulfillment with digital visibility. A.P. Moller - Maersk leverages its TradeLens blockchain infrastructure to anchor long-term contracts with enterprise retailers. COSCO SHIPPING International competes through port-to-port IoT coverage across Asia-Pacific manufacturing clusters.
Digital shipment refers to the technology-enabled orchestration of freight movement through real-time data exchange, API-connected carrier networks, and automated documentation workflows that replace paper-based bills of lading with cryptographically verified electronic records. Its primary commercial purpose is to reduce dwell time at ports and eliminate manual reconciliation across multimodal handoffs. Express delivery commands premium pricing due to time-definite service guarantees, while blockchain-enabled documentation trails are gaining fastest among cross-border freight services where customs pre-clearance creates margin pools. Cloud solutions dominate technology spending as carriers migrate legacy terminal operating systems to scalable architectures.
The EU Digital Transport and Logistics Forum mandates interoperable data standards for freight corridors, while the IMO's Maritime Single Window initiative compels sea carriers to submit standardized electronic manifests prior to port arrival. The US FMC reviews detention and demurrage billing transparency rules that directly shape digital invoicing platform demand. Stakeholders must monitor which regulatory jurisdiction first mandates API-native customs filing, as that standard will propagate across bilateral trade agreements.
Market Dynamics
API-native customs filing mandates are compressing technology upgrade cycles across carrier networks, forcing multimodal operators to replace legacy terminal operating systems before depreciation schedules complete.
Growth Catalysts
- E-commerce fulfillment integration:Enterprise retailers demand bundled visibility platforms that synchronize last-mile delivery with ocean freight tracking, pulling investment toward unified data architectures.
- EU Digital Transport and Logistics Forum interoperability mandates:Standardized data exchange protocols across freight corridors eliminate bilateral integration costs that previously fragmented carrier networks.
- Blockchain-based electronic bills of lading:Cryptographic verification of cargo documentation reduces port dwell time by replacing manual reconciliation with automated smart contract execution.
Market Restraints
- Legacy system replacement costs:Terminal operating systems built on mainframe architectures require complete rebuilds rather than modular upgrades, stretching carrier IT budgets across 5-7 year cycles.
- Cloud infrastructure concentration:Three hyperscale providers dominate maritime software hosting, creating single-point-of-failure exposure for carrier data sovereignty.
- Skilled API integration talent scarcity:Shortage of developers proficient in both logistics domain logic and modern microservices architecture slows platform deployment timelines.
Strategic Opportunities
- India's port modernization program:Jawaharlal Nehru Port Trust and Mundra Port Authority procurement cycles favor digital visibility platforms that integrate with customs pre-clearance systems.
- Refrigerated container IoT convergence:Temperature monitoring sensors fused with blockchain documentation create premium service tiers for pharmaceutical cold chain shippers.
- IMO Maritime Single Window expansion:Mandatory electronic manifest submission prior to port arrival creates recurring revenue pools for compliance software vendors.
Industry Challenges
- Interoperability standard fragmentation:Competing data format specifications between EU, US, and Asia-Pacific regulatory jurisdictions force platform vendors to maintain multiple API versions.
- Cybersecurity certification complexity:ISO 27001 and IEC 62443 compliance timelines for maritime critical infrastructure extend sales cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Shipment Market |
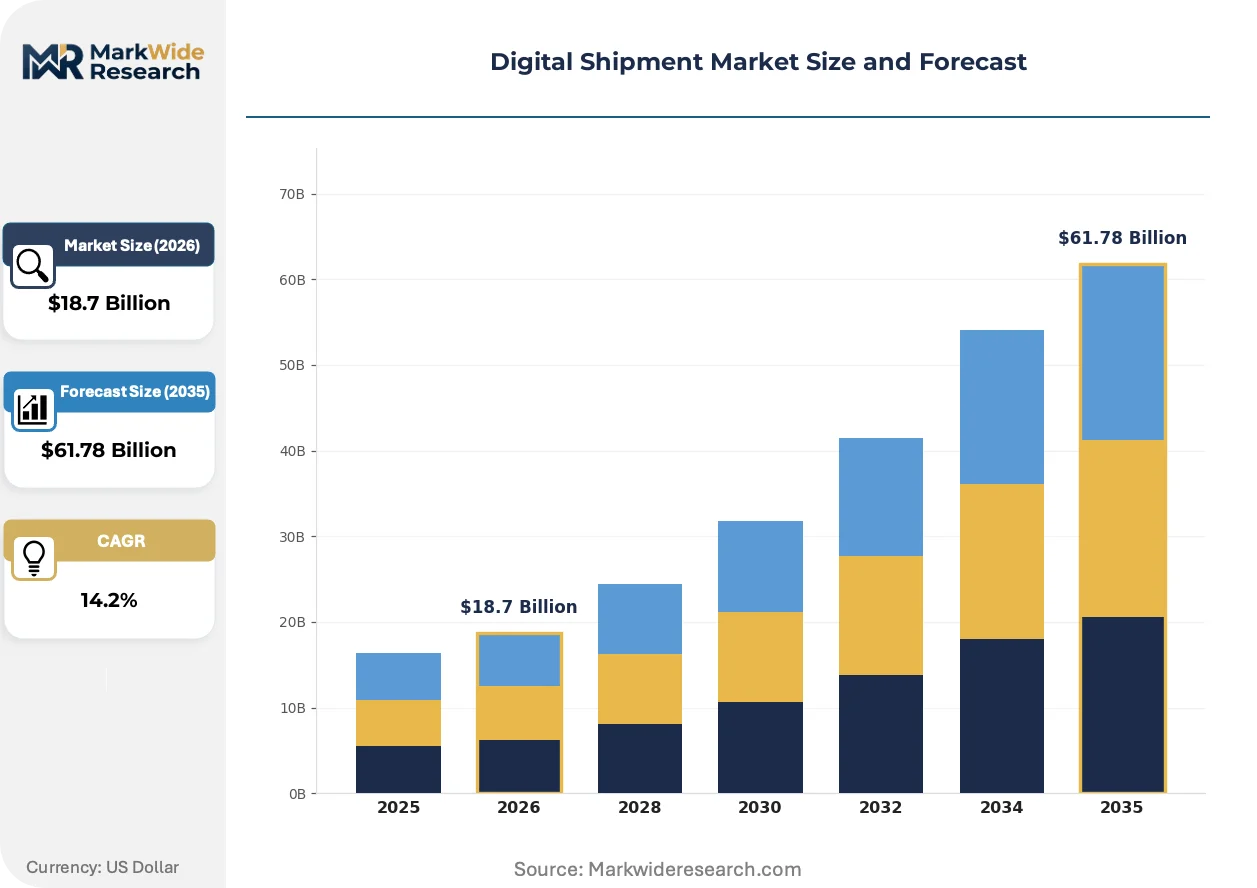
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Shipping, Express Delivery, Freight Services, Last Mile Delivery Technology: Blockchain, IoT Tracking, AI Logistics, Cloud Solutions End User: Retailers, E-commerce Platforms, Manufacturers, Third-party Logistics Delivery Mode: Air Freight, Sea Freight, Road Transport, Rail Transport |
| Companies Covered | A.P. Moller - Maersk, COSCO SHIPPING International, Hapag Lloyd, Evergreen Group, HYUNDAI Merchant Marine, Ocean Network Express, ZIM Integrated Shipping Services, Mediterranean Shipping Company, CMA CGM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Shipment Market Emerging Trajectories
Real-time visibility platforms are compressing the information asymmetry that historically separated cargo owners from actual vessel positions, dissolving the broker intermediary role that profited from opacity.
API-first architecture is overtaking EDI-based message exchange as the dominant integration protocol between carriers and shippers. Large enterprise retailers now require RESTful API endpoints as a contractual precondition for freight procurement. This shift is compressing vendor selection cycles toward platforms built on microservices rather than monolithic legacy codebases.
The EU's Digital Transport and Logistics Forum has mandated interoperable data standards for core freight corridors by 2025, compelling national customs authorities to harmonize electronic filing formats. Sea carriers serving Rotterdam, Hamburg, and Antwerp must now submit standardized electronic manifests prior to port arrival. Container lines with pre-existing API infrastructure capture preferential berthing slots through faster customs pre-clearance.
Shipper procurement teams now require outcome-based contracting with freight visibility guarantees rather than rate-per-container pricing. Large manufacturing conglomerates in Germany's automotive corridor negotiate contracts where carriers bear penalties for documentation delays that trigger customs holds. This behavioral shift concentrates contract awards toward integrated logistics providers with captive customs brokerage capabilities.
Digital Shipment Market Segmentation
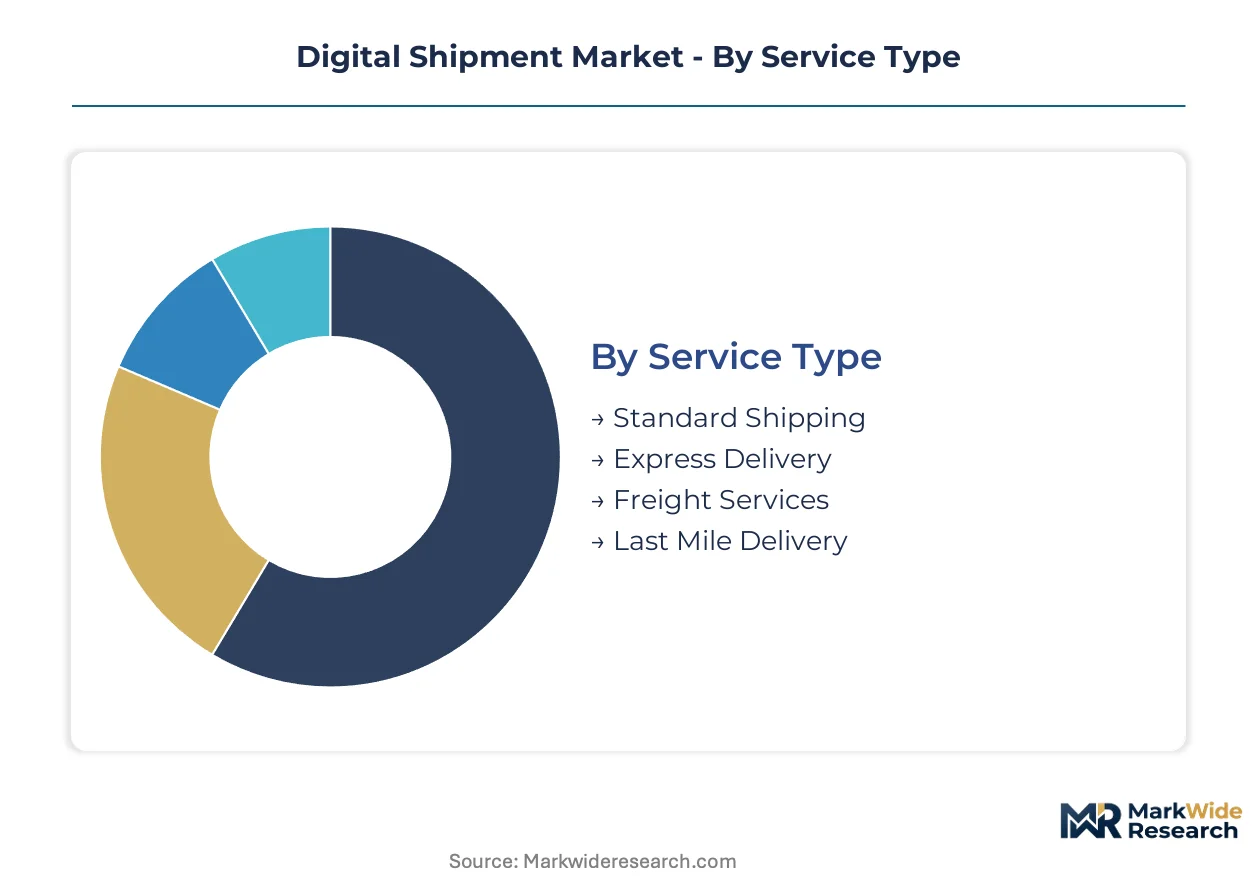
Digital shipment platforms require differentiated architectural investments across service tiers, sensing technologies, and multimodal integration layers. Segment-specific capital allocation determines competitive positioning in contract negotiations with enterprise shippers.
Service Type:
Capital intensity peaks where infrastructure must guarantee time-definite performance against contractual penalties.
- Express Delivery:Temperature-controlled aircraft charters and dedicated last-mile fleets demand the highest fixed-asset deployment. Pharmaceutical shippers in Germany's Rhine-Ruhr corridor pay premiums for cold-chain guarantees that require redundant sensor networks.
- Freight Services:Heavy-haul rail siding access and port terminal automation absorb substantial upfront investment. Container lines serving Jawaharlal Nehru Port and Mundra Port deploy automated guided vehicles to compress vessel turnaround windows.
- Standard Shipping:Consolidated parcel networks optimize through density algorithms rather than dedicated infrastructure.
- Last Mile Delivery:Micro-fulfillment nodes in urban peripheries balance real estate costs against delivery radius compression.
Freight Services absorbs the bulk of installed capacity; Express Delivery is expanding most quickly.
Technology:
Development cycles and certification burdens separate quick-deployment tools from multi-year platform builds.
- Cloud Solutions:Scalable container orchestration replaces legacy terminal operating systems without on-premise hardware refresh. Carriers migrating from mainframe architectures favor pay-as-you-grow models that defer capital commitment.
- Blockchain:Cryptographic verification of electronic bills of lading requires consortium governance structures and cross-carrier protocol standardization. TradeLens and competing platforms invest heavily in smart contract auditing and maritime cybersecurity certification.
- IoT Tracking:Sensor hardware and cellular/satellite connectivity bundles create recurring equipment financing obligations.
- AI Logistics:Machine learning demand forecasting demands specialized data science teams and training infrastructure.
Cloud Solutions command the largest share of current technology spending; Blockchain is climbing the fastest as customs authorities mandate electronic documentation.
End User:
Procurement sophistication and integration complexity shape platform customization requirements.
- E-commerce Platforms:API-native architectures support real-time inventory synchronization across distributed fulfillment networks. Enterprise retailers require RESTful endpoints as contractual preconditions, forcing carriers to retire EDI-based message exchange.
- Third-party Logistics:Multi-client visibility dashboards demand white-label customization and tenant-isolated data architectures. 4PL providers serving automotive manufacturers in Stuttgart and Munich negotiate outcome-based contracts with documentation delay penalties.
- Retailers:Seasonal volume spikes require elastic capacity reservation mechanisms.
- Manufacturers:Just-in-sequence production lines mandate precise arrival windows with dock scheduling integration.
E-commerce Platforms drive the majority of platform development roadmaps; Third-party Logistics is gaining share fastest through bundled visibility offerings.
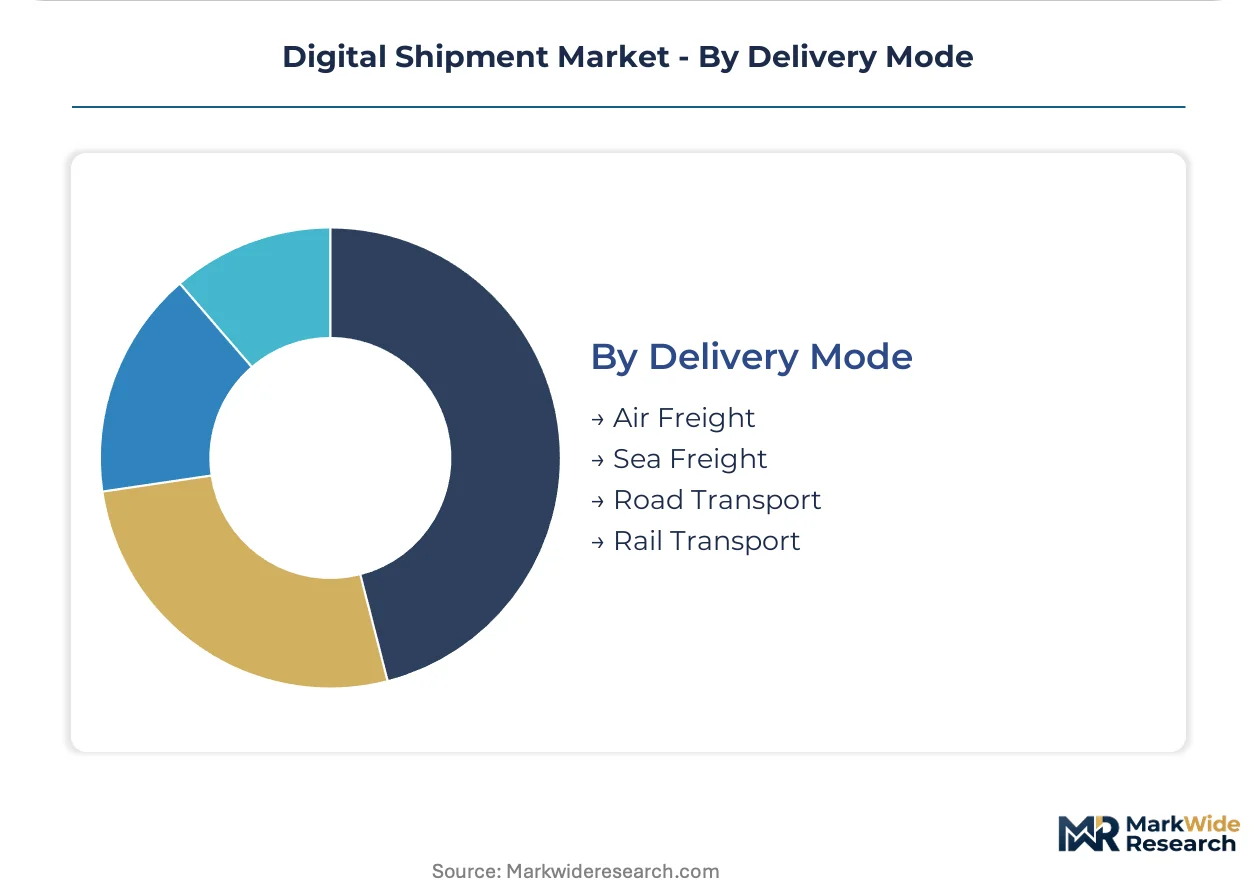
Delivery Mode:
Physical infrastructure lock-in and regulatory jurisdiction density determine expansion economics.
- Sea Freight:Vessel charter commitments and port terminal concessions span decade-long horizons. Container lines serving Rotterdam, Hamburg, and Antwerp capture preferential berthing through pre-arrival electronic manifest submission under EU interoperability mandates.
- Air Freight:Slot-constrained airport pairs and fuel hedging programs create volatile operating leverage. Express carriers at Frankfurt and Amsterdam Schiphol invest in automated sortation to meet pharmaceutical cold-chain service tiers.
- Road Transport:Cross-border cabotage restrictions and driver availability limit network design flexibility.
- Rail Transport:Track access agreements and intermodal terminal handoffs require coordination across national rail operators.
Sea Freight carries the greatest fixed-asset base; Air Freight is expanding most quickly on pharmaceutical and e-commerce express demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise retailers in Germany's Rhine-Ruhr corridor drive concentrated procurement of integrated visibility platforms, while customs modernization programs across India and the United States reshape carrier technology investment priorities.
United States
Pharmaceutical cold-chain shippers around Philadelphia and New Jersey ports demand temperature-verified documentation trails. The Federal Maritime Commission reviews detention and demurrage billing transparency rules that directly shape digital invoicing platform specifications. Los Angeles-Long Beach terminal operators deploy automated guided vehicles to compress vessel turnaround under port efficiency mandates.
Germany
Automotive manufacturers in Stuttgart and Munich negotiate outcome-based contracts with documentation delay penalties. The EU Digital Transport and Logistics Forum mandates interoperable data standards for freight corridors through Rotterdam, Hamburg, and Antwerp. Container lines serving Hamburg capture preferential berthing through pre-arrival electronic manifest submission.
India
Jawaharlal Nehru Port Trust and Mundra Port Authority procurement cycles favor digital visibility platforms integrating with customs pre-clearance systems. The country's central trade regulator accelerates API-native filing requirements for maritime single window compliance. Gujarat's manufacturing clusters absorb sensor-enabled container tracking for pharmaceutical exports to European markets.
China
Cross-border e-commerce platforms in the Yangtze River Delta require real-time synchronization between ocean freight and last-mile networks. The Ministry of Transport advances electronic bill of lading standards for Shanghai and Ningbo-Zhoushan port complexes. Shenzhen-based technology providers supply blockchain documentation infrastructure to Asia-Pacific manufacturing clusters.
Singapore
Maritime trade finance institutions demand cryptographically verified cargo documentation for letter-of-credit processing. The Maritime and Port Authority mandates digital port clearance systems linking shipping lines with customs and immigration databases. Tuas Port automation investments attract carrier technology partnerships for next-generation terminal operating systems.
Digital Shipment Market Vendor Landscape
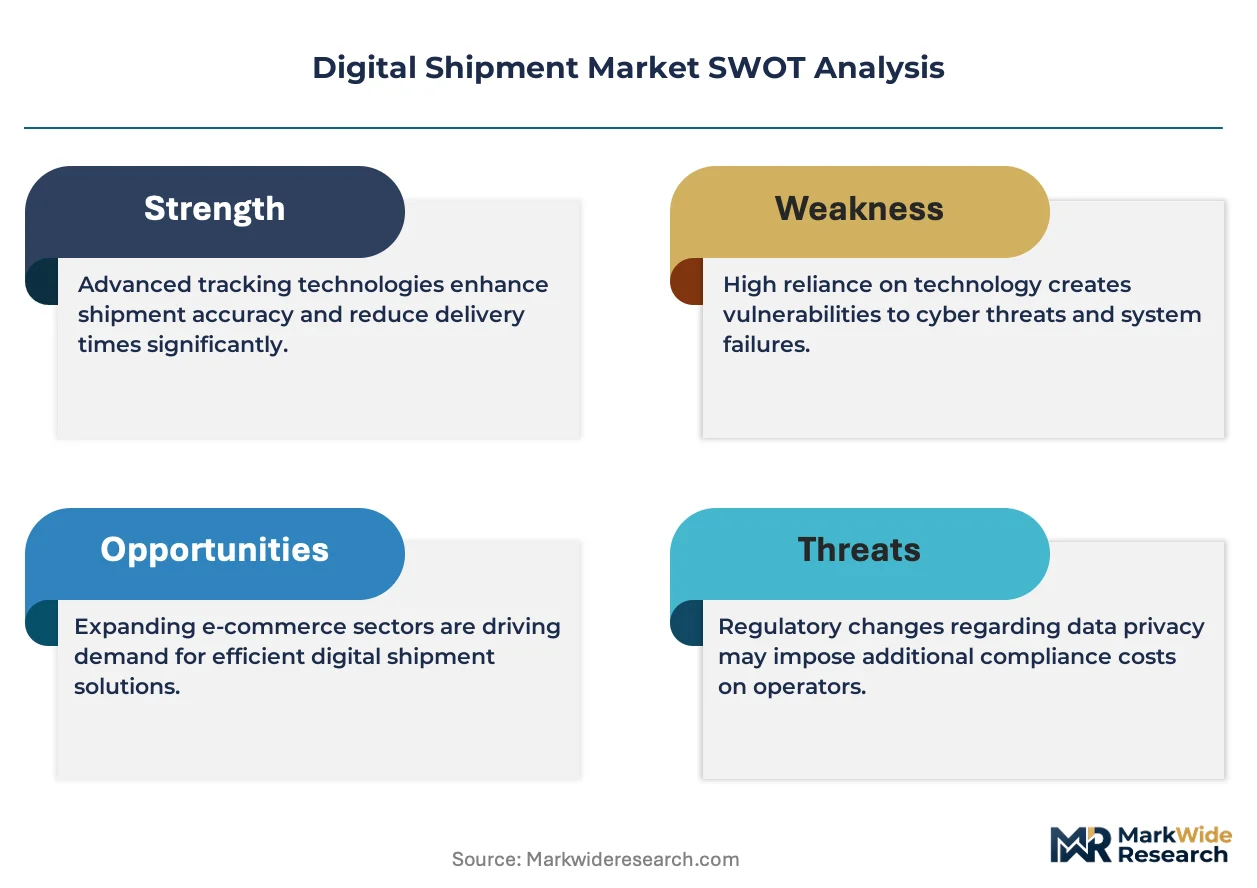
Established carriers occupy the standard tier; emerging technology entrants pursue API-native platform specialization. The market structure concentrates around integrated logistics providers with captive customs brokerage capabilities and container lines with pre-existing blockchain infrastructure. Three archetypes dominate: ocean carriers with terminal operating system control, third-party logistics providers bundling visibility with fulfillment, and software vendors selling compliance-as-a-service. Competitive moves center on strategic partnerships between carriers and customs technology providers, plus vertical integration into port terminal automation.
Among Denmark-based integrated logistics groups, A.P. Moller - Maersk anchors the carrier-technology convergence archetype through its TradeLens blockchain infrastructure. COSCO SHIPPING International represents the Asia-Pacific port-to-port coverage model with IoT-enabled vessel tracking. Mediterranean Shipping Company exemplifies the scale-driven documentation standardization approach serving enterprise retail procurement teams.
| Leading Market Players |
|---|
| A.P. Moller - Maersk |
| COSCO SHIPPING International |
| Hapag Lloyd |
| Evergreen Group |
| HYUNDAI Merchant Marine |
| Ocean Network Express |
| ZIM Integrated Shipping Services |
| Mediterranean Shipping Company |
| CMA CGM Group |
| Others |
Supply Flow & Price Mechanics
Enterprise retailer procurement teams demanding API-native visibility platforms as contractual preconditions are compressing carrier margins and forcing technology vendors to absorb integration costs upfront. This buyer-side specification pressure concentrates pricing power with integrated logistics providers that bundle customs brokerage capabilities, while fragmenting returns among standalone software vendors.
Pricing Analysis
Volume concentrates in standardized freight services where per-container rates face compression from cloud infrastructure commoditization; margins pool in express delivery tiers where temperature-definite guarantees command pharmaceutical premiums. Price differentiation hinges on customs pre-clearance speed certification and blockchain documentation audit trails. Pricing pressure intensifies in the standard shipping tier as hyperscale cloud providers consolidate maritime software hosting. Third-party logistics providers exhibit highest price sensitivity due to multi-client margin stacking, while e-commerce platforms prioritize integration speed over unit cost.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscale data center operators concentrated in the United States, Ireland, and Singapore. Sensor hardware draws from Taiwanese semiconductor foundries and South Korean memory producers. Maritime software development feeds from Indian API integration talent pools and Eastern European cybersecurity specialists. Single-source vulnerability concentrates in terminal operating system codebases maintained by three dominant vendors. Distribution runs through carrier-direct enterprise sales teams and systems integrator channel partners serving mid-market freight forwarders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive customs brokerage capabilities and port terminal automation is separating winners from margin-compressed carriers in this market. Players controlling both documentation infrastructure and physical handoff points capture preferential contract terms.
For Market Incumbents: Anticipate API-native platform entrants by accelerating blockchain consortium governance investments before interoperability standards solidify. Defensive consolidation should target customs technology providers with pre-certified IMO Maritime Single Window integrations. Priority capacity addition belongs in Jawaharlal Nehru Port and Mundra Port corridors where Indian modernization programs favor integrated visibility platforms.
For New Entrants and Emerging Players: Mid-market pharmaceutical cold-chain shippers in Germany's Rhine-Ruhr corridor represent an underserved buyer archetype lacking integrated temperature-verified documentation solutions. White-space targets include refrigerated container IoT convergence for European export corridors and compliance-as-a-service for Asia-Pacific manufacturing clusters lacking in-house customs expertise. Go-to-market positioning should emphasize outcome-based contracting with documentation delay penalty absorption.
For Investors and Strategic Acquirers: The window for entry favors software vendors with pre-certified maritime cybersecurity credentials and existing API infrastructure. Long-term viability over the next decade hinges on regulatory capture through early interoperability standard adoption. Acquisition targets should display captive customs brokerage relationships or port terminal automation partnerships. Watch for the first jurisdiction mandating API-native customs filing as the signal that standard propagation will accelerate across bilateral trade agreements.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Consortium Expansion | TradeLens and competing platforms anchor smart contract standardization across Rotterdam-Hamburg-Antwerp corridors. |
| Customs Technology Acquisition | Carriers capturing pre-clearance software vendors secure preferential berthing slots under EU interoperability mandates. |
| Port Terminal Automation Partnership | Tuas Port investments in Singapore attract carrier technology alliances for next-generation operating systems. |
| Refrigerated Container IoT Integration | Temperature sensor fusion with blockchain documentation creates premium service tiers for pharmaceutical exporters. |
| API-First Platform Migration | RESTful endpoint adoption replaces EDI message exchange as enterprise retailer procurement precondition. |
Methodological Framework
Multi-period observation of carrier technology spending patterns, customs filing system procurement cycles, and port automation investment timelines anchored the trend analysis, supplemented by interviews with terminal operating system vendors, maritime software engineers, enterprise logistics procurement managers, and customs technology integrators. Secondary validation drew from IMO regulatory filings, EU Digital Transport and Logistics Forum policy documents, carrier SEC disclosures, and trade data covering container throughput at major port complexes. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting across service type, technology layer, end-user archetype, and delivery mode dimensions informed the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to technology adoption S-cycles and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated API-native filing mandate acceleration curves and cloud infrastructure migration timelines for legacy terminal operating systems.
Revisions become necessary when regulatory jurisdictions advance conflicting data format specifications, hyperscale cloud providers alter maritime hosting economics, or cybersecurity certification timelines extend materially. Forecasts reflect documented assumptions regarding interoperability standard harmonization and carrier IT budget allocation priorities. A small set of triggers—API mandate timing, blockchain consortium governance outcomes, and port automation procurement cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Latin America Cross Border Road Freight Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
Rail Asset Management Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Czech Republic Road Freight Transport Market