
 United States Automotive Collision Avoidance Systems Market | 2026-2036
United States Automotive Collision Avoidance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Collision Avoidance Systems Market Analytics
Sensor fusion bundling is repositioning buyer choice away from standalone radar or camera modules toward integrated perception stacks. Continental AG leverages its domain controller expertise to anchor premium OEM contracts across Detroit automakers. Robert Bosch sustains manufacturing scale through its Charleston, South Carolina facility, which supplies radar units to multiple domestic assembly plants. Mobileye specializes in vision-based algorithms that compete directly with tier-one hardware suppliers for design wins at major US manufacturers.
Automotive collision avoidance systems combine multi-modal sensing architectures—typically millimeter-wave radar operating at 77 GHz, CMOS image sensors with HDR capability, and solid-state lidar—to detect obstacles and initiate autonomous braking or steering interventions. These systems serve the primary commercial purpose of reducing frontal and side-impact collisions while lowering liability exposure for fleet operators and insurers. Automatic emergency braking dominates unit volumes as NHTSA phased mandates push OEM integration rates upward, while lidar-based configurations represent the fastest-growing technology segment as costs decline below five-hundred dollars per unit for highway-speed applications. Camera-based systems retain margin pools in the aftermarket channel where retrofit demand from commercial fleets and insurance-sponsored safety programs creates sustained replacement cycles.
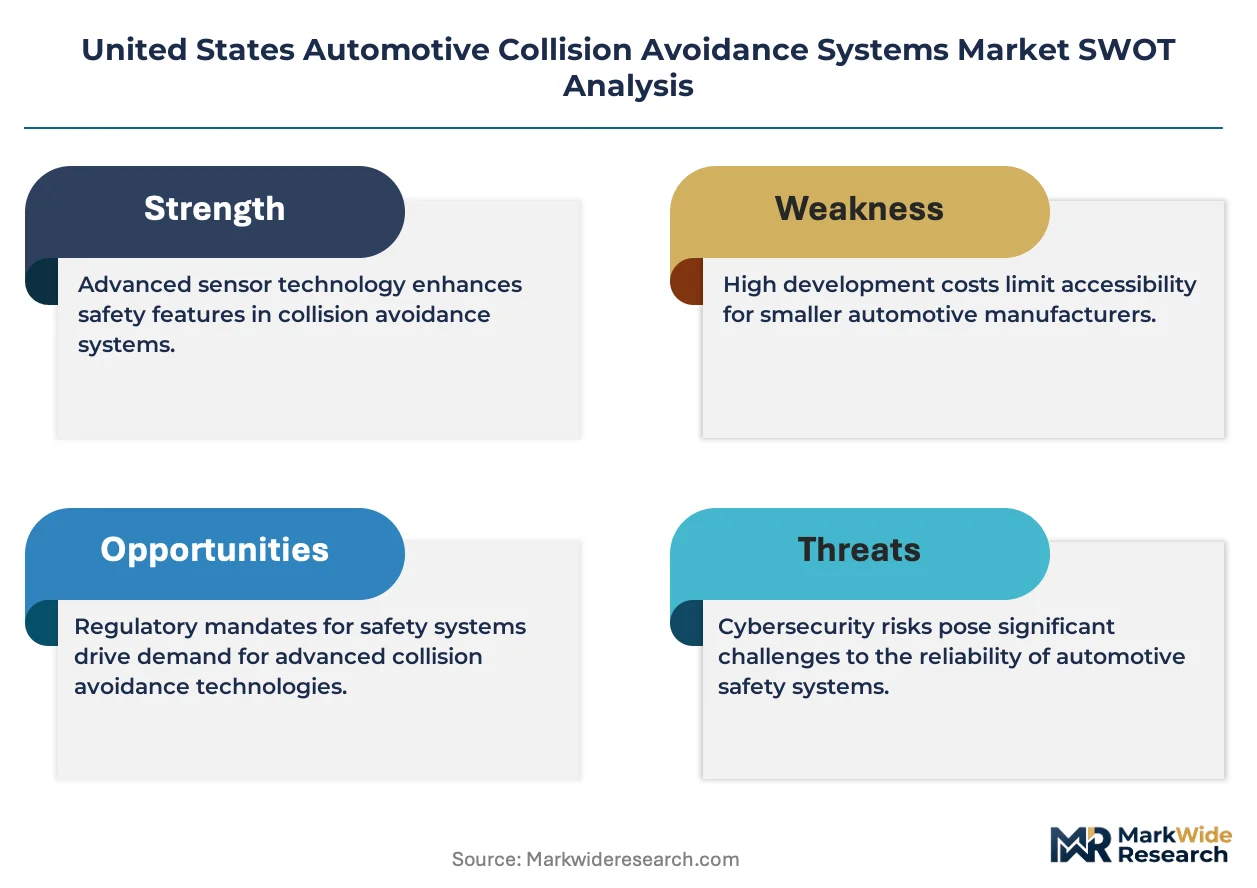
NHTSA Federal Motor Vehicle Safety Standard 127 mandates automatic emergency braking on all new passenger vehicles, while EPA fuel economy incentives reward lightweight sensor packaging that preserves aerodynamic efficiency. The Department of Transportation's AV TEST initiative creates voluntary reporting frameworks that shape consumer trust and insurer risk pricing for advanced driver assistance features. Stakeholders must monitor how state-level tort liability frameworks evolve around Level 2+ system failures, as California and Texas court precedents will determine whether OEMs or component suppliers bear catastrophic loss exposure.
Market Dynamics
NHTSA Federal Motor Vehicle Safety Standard 127 mandates automatic emergency braking on all new passenger vehicles, forcing OEMs to integrate multi-sensor perception stacks into vehicle architectures regardless of trim level. This regulatory compression is restructuring supplier relationships and procurement timelines across domestic assembly plants.
Growth Catalysts
- FMVSS 127 Mandate:NHTSA's phased automatic emergency braking requirement creates guaranteed baseline demand for radar and camera modules through 2029.
- Commercial Fleet Liability:Insurance carriers in Michigan and Texas now mandate collision avoidance suites for heavy-duty trucking contracts, accelerating retrofit installations.
- 77 GHz Radar Migration:Higher-resolution millimeter-wave sensors enable highway-speed object discrimination, opening premium positioning for integrated perception stacks.
Market Restraints
- Semiconductor Input Volatility:CMOS image sensor and radar MMIC foundry capacity concentrates in Taiwan and South Korea, exposing US module assemblers to geopolitical supply risk.
- California Tort Uncertainty:State court precedents around Level 2+ system failure liability remain unsettled, chilling OEM deployment of advanced steering interventions.
- LiDAR Cost Floor:Solid-state optical phased array units remain above three hundred dollars at volume, blocking mass-market adoption outside luxury segments.
Strategic Opportunities
- Aftermarket Retrofit Channel:Commercial fleets in Texas corridor states seek camera-based warning systems through insurance-sponsored safety programs, bypassing OEM integration delays.
- EPA Aerodynamic Incentives:Lightweight sensor packaging that preserves fuel economy ratings creates design wins for thin-form-factor radar-in-bumper configurations.
- Sensor Fusion Convergence:Integration of 4D imaging radar with HDR cameras enables redundant perception without LiDAR, targeting mid-price vehicle segments.
Industry Challenges
- Functional Safety Certification:ISO 26262 ASIL-D validation for braking actuators extends development cycles by fourteen to eighteen months, compressing supplier margins.
- Legacy Vehicle Integration:Retrofit kits for pre-2020 commercial trucks require CAN bus protocol adaptation across fragmented OEM electrical architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Collision Avoidance Systems Market |
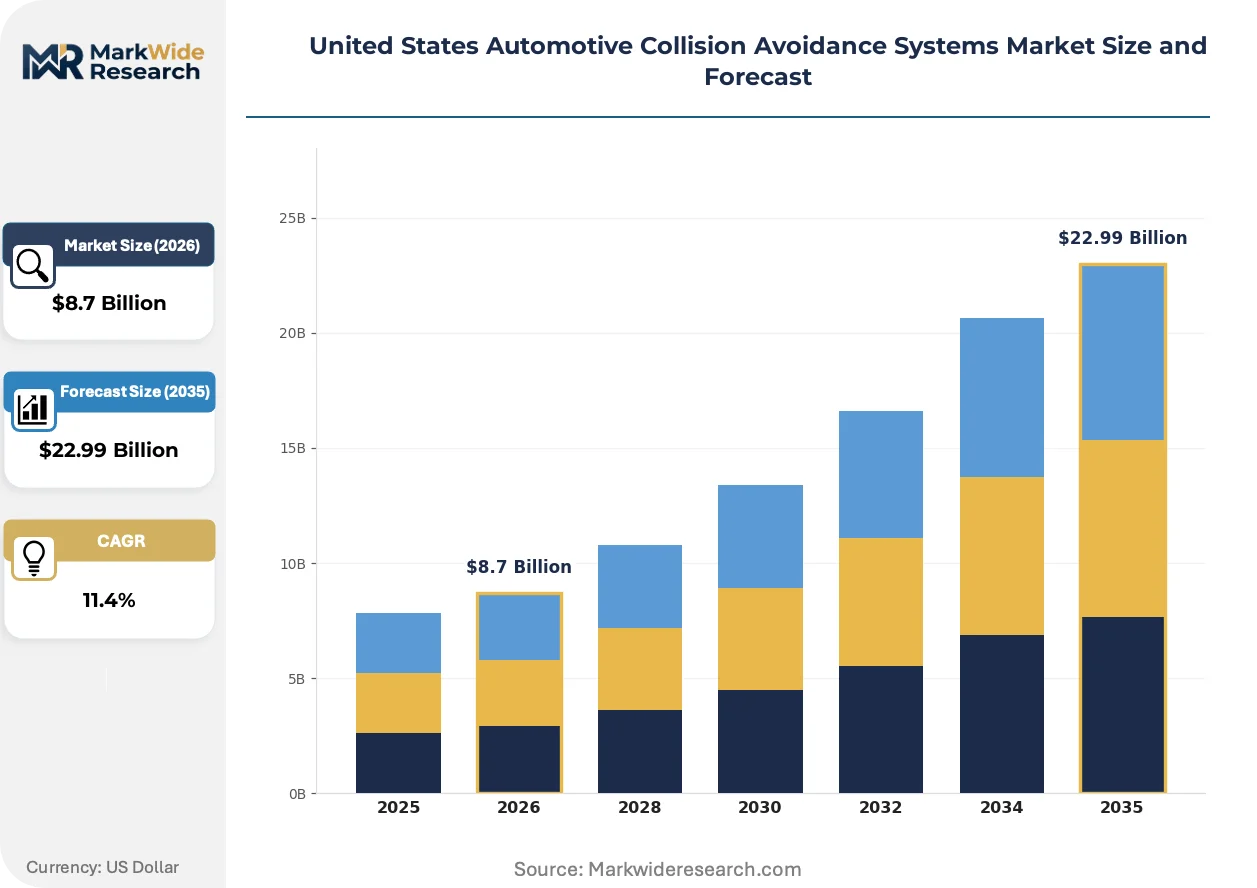
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Cruise Control, Lane Departure Warning, Automatic Emergency Braking, Blind Spot Detection Technology: Radar-Based, Camera-Based, Lidar, Ultrasonic End User: OEMs, Aftermarket Providers, Fleet Managers, Insurance Companies Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy Machinery |
| Companies Covered | Continental AG, Robert Bosch, ZF Friedrichshafen AG, Mobileye, Denso Corporation, Aptiv, Autoliv Inc, Valeo, Infineon Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Collision Avoidance Systems Market Evolving Landscape
Perception hardware is consolidating from discrete radar and camera modules into unified domain controllers, while software-defined architectures enable over-the-air feature upgrades. These shifts are compressing tier-one supplier margins and opening entry points for algorithm specialists.
4D imaging radar with elevation detection and dense point-cloud output is expanding into mid-size SUV and pickup segments previously served by basic 2D radar units. Ford and GM procurement teams are qualifying Continental and Bosch units for 2026 model year integration. This capability expansion is compressing the price-performance gap between premium and standard ADAS tiers, forcing tier-two suppliers toward aftermarket channels.
NHTSA's AV TEST voluntary reporting framework is reshaping consumer trust metrics and insurer risk pricing for advanced driver assistance features. The Department of Transportation publishes standardized disengagement and crash data that directly influences IIHS safety ratings. California and Texas fleet operators now require AV TEST participation as a procurement qualification, filtering supplier eligibility.
Commercial fleet buyers are consolidating sensor procurement through national leasing companies rather than fragmented dealer networks. Enterprise Fleet Management and ARI now specify collision avoidance suites as standard equipment, bypassing traditional OEM option packaging. This concentration is most visible in Michigan and Ohio manufacturing corridors where fleet density supports direct supplier negotiation.
United States Automotive Collision Avoidance Systems Market Segmentation
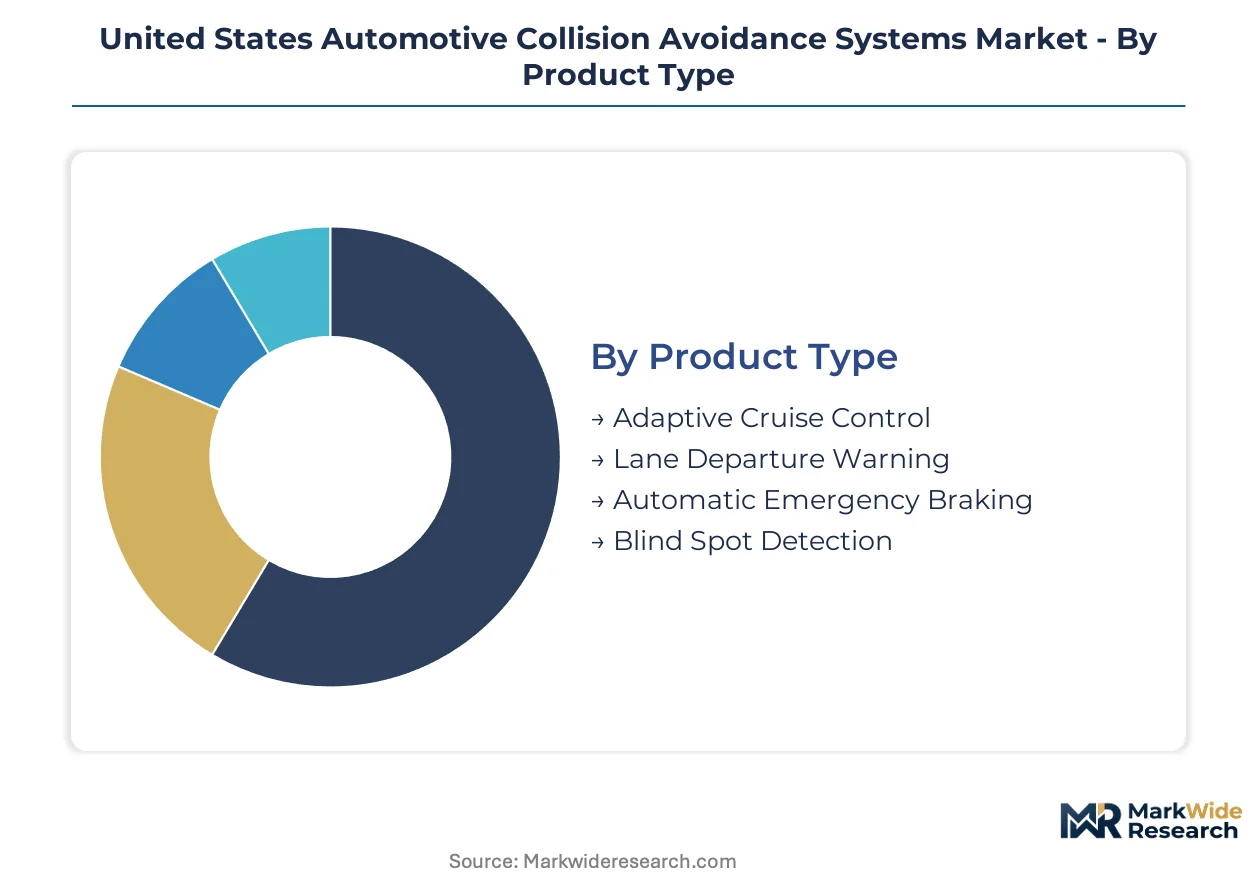
Collision avoidance systems fragment across four critical dimensions that determine procurement patterns and margin structures. Product type and technology choices dictate hardware integration depth, while end-user and application segments reveal where retrofit demand diverges from factory-installed architectures.
Product Type:
Standalone warning systems occupy dashboard real estate without chassis integration, while braking-intervention suites embed directly into vehicle control modules.
- Adaptive Cruise Control:Combines longitudinal radar sensing with throttle and brake actuation to maintain following distances. Michigan OEM assembly lines prioritize this function for highway-rated pickup trucks where towing workloads demand precise speed modulation.
- Automatic Emergency Braking:Fuses forward-facing radar and camera inputs to execute autonomous braking when collision probability exceeds thresholds. NHTSA FMVSS 127 mandates this capability across all new passenger vehicles, anchoring baseline procurement volumes for domestic tier-one suppliers.
- Lane Departure Warning:Vision-based edge detection alerts drivers through haptic steering or audible signals without steering torque intervention.
- Blind Spot Detection:Short-range radar modules mounted in rear quarter panels monitor adjacent lane occupancy for passenger and commercial vehicle mirrors.
Automatic Emergency Braking leads volumes today; Adaptive Cruise Control is gaining share fastest.
Technology:
Cost tiers separate proven 77 GHz radar from emerging solid-state optical systems, with hybrid fusion architectures commanding premium positioning.
- Radar-Based:Millimeter-wave sensors operating at 77 GHz deliver all-weather obstacle detection through precipitation and darkness. Texas commercial trucking corridors specify these units for heavy-duty fleet contracts where liability exposure drives specification rigor.
- Camera-Based:HDR CMOS image sensors with neural network processing enable lane marking recognition and traffic sign detection. California passenger vehicle OEMs favor camera-dominant stacks for their software upgrade pathways and lower per-unit bill-of-materials.
- Lidar:Solid-state optical phased arrays generate dense point clouds for highway-speed object classification.
- Ultrasonic:Low-frequency acoustic sensors provide parking maneuver assistance and close-proximity obstacle detection at minimal cost.
Radar-Based systems anchor current revenue; Lidar is climbing the fastest as unit economics approach mass-market thresholds.
End User:
Factory integration channels differ fundamentally from retrofit procurement, with fleet intermediaries consolidating specification power.
- OEMs:Vehicle manufacturers integrate collision avoidance hardware during body-in-white assembly, locking suppliers into multi-year platform contracts. Detroit Three procurement teams specify domain-controller architectures that bundle perception, planning, and actuation.
- Fleet Managers:National leasing companies in Ohio and Michigan now mandate collision avoidance suites as standard equipment, bypassing traditional dealer option packaging.
- Aftermarket Providers:Independent installers serve commercial vehicle retrofit demand through insurance-sponsored safety programs.
- Insurance Companies:Carriers in Texas and California sponsor device installations to reduce claims frequency and severity.
OEMs dominate revenue today; Fleet Managers are expanding procurement fastest through direct supplier negotiation.
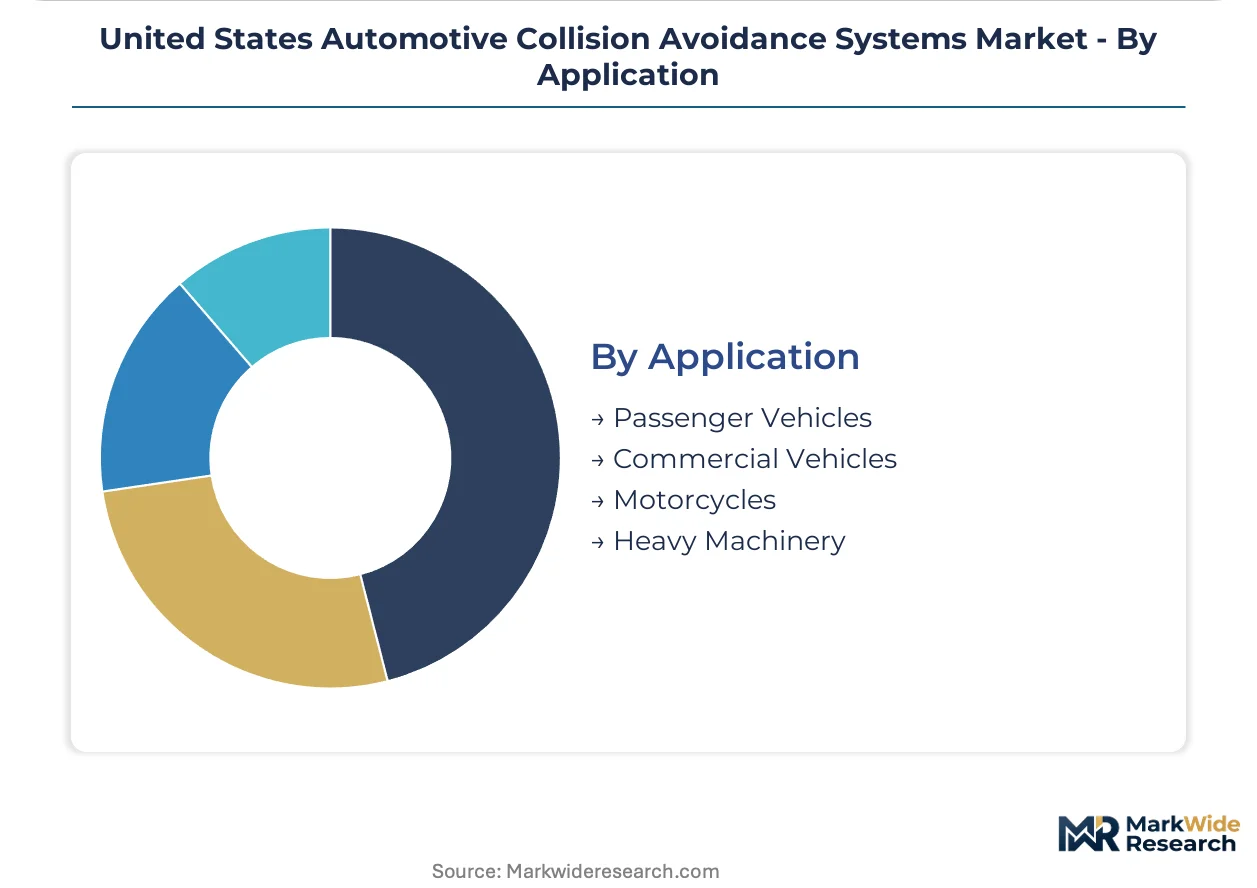
Application:
Vehicle mass and duty cycle dictate sensor range requirements and intervention aggressiveness, separating highway-rated systems from low-speed parking assistance.
- Passenger Vehicles:Light-duty cars and light trucks integrate multi-sensor fusion stacks behind windshields and within front grilles. California and Texas registration volumes drive sensor procurement concentration for this segment.
- Commercial Vehicles:Class 8 trucks and delivery vans require extended-range radar and reinforced actuator hardware for highway-speed emergency braking. Michigan manufacturing corridors and Texas interstate corridors generate concentrated fleet retrofit demand.
- Motorcycles:Two-wheel platforms present packaging constraints that favor compact radar-in-mirror configurations.
- Heavy Machinery:Construction and agricultural equipment deploy ultrasonic and short-range radar for worksite proximity alerting.
Passenger Vehicles anchor unit volumes today; Commercial Vehicles show the steepest expansion trajectory as fleet liability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collision avoidance technology first achieved commercial scale in Michigan's automotive manufacturing corridor during the early 2000s, with Detroit Three OEMs pioneering radar-based adaptive cruise control for premium vehicle lines before NHTSA mandates accelerated nationwide deployment.
Michigan
Detroit metropolitan assembly plants consume the highest domestic sensor volumes as Ford, GM, and Stellantis integrate automatic emergency braking across light-truck platforms. NHTSA FMVSS 127 enforcement timelines compress supplier qualification cycles at Warren and Dearborn technical centers. Tier-one domain controller manufacturing clusters in Auburn Hills anchor Continental and Bosch engineering operations.
California
Silicon Valley software development centers drive vision-based algorithm advancement for camera-dominant ADAS stacks. California Air Resources Board zero-emission vehicle incentives reward lightweight sensor packaging that preserves electric range ratings. Los Angeles basin fleet operators now mandate collision avoidance suites for commercial leasing contracts exceeding fifty units.
Texas
Interstate trucking corridors generate concentrated demand for heavy-duty radar systems as insurance carriers mandate collision avoidance for Class 8 fleet coverage. Texas Department of Transportation freight infrastructure investments prioritize highway-speed object detection along I-35 and I-10 corridors. Dallas-Fort Worth logistics hubs host retrofit installation centers serving national leasing companies.
Ohio
Midwest manufacturing supply chains support sensor module assembly for Detroit Three procurement networks. Ohio Bureau of Workers Compensation premium reductions incentivize commercial fleet adoption of lane departure warning systems. Toledo and Cleveland metropolitan areas concentrate aftermarket distribution channels for independent installer networks.
South Carolina
Charleston regional manufacturing facilities supply radar units to multiple southeastern assembly plants. South Carolina Commerce Department automotive incentives attracted Bosch production capacity serving BMW Spartanburg and Mercedes-Benz Tuscaloosa operations. Greenville technical workforce pipelines support MMIC testing and calibration operations.
United States Automotive Collision Avoidance Systems Market Competitive Landscape
The competitive structure tilts toward tier-one automotive suppliers with domain controller expertise and established OEM platform relationships. Continental AG and Robert Bosch anchor the consolidated premium tier through multi-year Detroit Three contracts, while semiconductor specialists and algorithm developers occupy adjacent technology layers. Two strategic archetypes dominate: integrated hardware-software stack providers and component specialists licensing perception algorithms. Competitive moves concentrate on sensor fusion bundling to displace standalone module procurement, and vertical integration into foundry relationships to secure MMIC supply.
Within the integrated tier-one archetype, Continental AG exemplifies domain controller consolidation through its Detroit automaker anchor contracts, while Robert Bosch occupies a position as scale-driven manufacturing specialist with South Carolina production capacity. Mobileye represents the algorithm-centric challenger archetype, competing directly for design wins at major US manufacturers through vision-based software stacks rather than hardware fabrication.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch |
| ZF Friedrichshafen AG |
| Mobileye |
| Denso Corporation |
| Aptiv |
| Autoliv Inc |
| Valeo |
| Infineon Technologies |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up aftermarket specialists have consolidated independent installer networks across Texas and Ohio, compressing procurement margins for camera-based retrofit systems while enforcing volume-based pricing discipline on tier-two radar module suppliers. This ownership concentration feeds upstream into sensor fusion bundling decisions at Detroit Three technical centers, where procurement teams leverage multi-year platform contracts to extract cost concessions from Continental and Bosch domain controller divisions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs collision avoidance system procurement, with ISO 26262 ASIL-D certification tier and volume scale driving price differentiation between integrated OEM stacks and aftermarket retrofit kits. Cost compression in standard-tier radar-camera fusion modules is intensifying because NHTSA FMVSS 127 mandates force baseline feature parity across trim levels. Fleet managers at national leasing companies exhibit highest price sensitivity through consolidated direct negotiation, while luxury OEM platform engineers remain least sensitive when specifying highway-speed lidar configurations.
Supply Chain Analysis
MMIC foundry technician shortages in Taiwan and South Korea constrain radar module output expansion, forcing Bosch Charleston and Continental Auburn Hills facilities to compete for qualified test-and-calibration engineers. Semiconductor wafer processing draws from TSMC and Samsung foundries, while CMOS image sensor die sourcing centers on Sony and Omnivision operations. Single-source vulnerability around 77 GHz radar MMICs exposes US module assemblers to geopolitical disruption. Distribution runs through tier-one domain controller manufacturers directly into OEM assembly plants, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA Federal Motor Vehicle Safety Standard 127 functions as a regulatory compounder, guaranteeing baseline demand for automatic emergency braking hardware through mandated integration timelines that reshape supplier procurement cycles.
For Market Incumbents: Extend domain controller software roadmaps to capture over-the-air feature upgrade revenue streams, countering algorithm-centric challengers like Mobileye that threaten hardware-software stack bundling. Deepen captive supply of 77 GHz radar MMICs through foundry partnerships in Taiwan and South Korea, insulating against geopolitical supply disruption that could fracture multi-year Detroit Three platform contracts. For New Entrants and Emerging Players: Begin with aftermarket retrofit channel penetration in Texas and Ohio commercial fleet corridors, where insurance-sponsored safety programs bypass OEM integration delays and create immediate revenue traction. Target camera-based warning systems for pre-2020 Class 8 truck retrofit, exploiting fragmented CAN bus protocol adaptation needs that tier-one suppliers neglect. Pursue direct leasing company procurement qualification as the fastest path to volume scale outside dealer networks. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two radar module specialists lacking domain controller integration capabilities, as sensor fusion convergence compresses standalone hardware margins. Five-to-ten year viability hinges on regulatory enforcement durability rather than technology differentiation, favoring targets with locked OEM platform relationships over algorithm-only assets. Monitor California tort precedent evolution around Level 2+ system failure liability as the critical inflection signal determining catastrophic loss exposure allocation between OEMs and component suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Standardization | Continental and Bosch consolidate multi-sensor stacks into unified domain controllers for Detroit Three assembly lines. |
| 77 GHz Radar MMIC Supply Agreement | Long-term foundry contracts with TSMC and Samsung secure wafer capacity for highway-speed object detection modules. |
| Aftermarket Retrofit Channel Expansion | Independent installer networks in Texas corridor states capture commercial fleet liability-mandated demand outside OEM integration. |
| Software-Defined Vehicle Investment | Over-the-air feature upgrade pathways enable recurring revenue from camera-dominant ADAS stacks at California OEMs. |
| Geographic Manufacturing Footprint | South Carolina and Michigan production clusters anchor domestic assembly proximity for NHTSA compliance timelines. |
Research Methodology
Direct dialogue with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and commercial fleet safety managers anchored qualitative findings, cross-referenced against NHTSA FMVSS 127 implementation schedules, EPA fuel economy incentive documentation, IIHS safety rating methodologies, and IHS Markit vehicle production databases. Bottom-up sensor unit shipment estimates triangulated against top-down OEM platform content analysis across the analysis window.
Unit volume and value projections derived from multi-dimensional segmentation modeling across product type, technology architecture, end-user channel, and vehicle application, with CAGRs calibrated to NHTSA mandate phase-in schedules and commercial fleet liability insurance penetration curves. Forecast inputs incorporated 77 GHz radar cost decline trajectories, solid-state lidar unit economics thresholds, and domain controller software licensing revenue recognition patterns.
Several conditions sit outside the modeled scope, including potential California tort liability rulings reallocating catastrophic loss exposure, Taiwan Strait geopolitical disruption of MMIC foundry supply, and EPA regulatory shifts affecting lightweight sensor packaging incentives. Forecasts reflect assumptions about NHTSA enforcement continuity and insurance carrier mandate durability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
China Airbag Systems Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Avalanche Airbags Market
Automotive Safety and Security Systems
Automotive TPMS Market
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Global Automotive Intelligent Door System Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Vehicle Barrier System Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market