
 Saudi Arabia Courier, Express, and Parcel (CEP) Market | 2026-2036
Saudi Arabia Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Courier, Express, and Parcel (CEP) Market Insights
The Saudi Arabia CEP sector is rebalancing between premium express services and commoditized standard delivery as e-commerce volume floods lower-margin tiers. DHL Group leverages its integrated air-ground network to sustain premium positioning across pharmaceutical and automotive verticals. Saudi Post-SPL anchors domestic coverage through Naqel Express, which controls the deepest last-mile infrastructure outside major metros. Zajil Express specializes in B2B heavy freight and competes on route density within industrial city corridors.
Courier, express, and parcel services encompass time-definite transportation of documents and goods ranging from sub-kilogram envelopes to multi-ton freight, utilizing multimodal networks with tracking granularity at the shipment level. These services enable inventory velocity for manufacturers, just-in-time supply chains, and direct-to-consumer fulfillment across geographically dispersed populations. Same-day delivery and next-day delivery represent the fastest-expanding service categories as consumer expectations compress transit windows, while international shipping retains the highest margin pool due to customs complexity and fuel surcharge structures. E-commerce and corporate customer segments now dominate volume flows, with retailers migrating from owned logistics to outsourced CEP partnerships.
The Communications, Space and Technology Commission (CST) licenses postal and logistics providers, while the Saudi Standards, Metrology and Quality Organization (SASO) governs packaging material specifications and product safety in transit. The General Authority of Civil Aviation (GACA) regulates air cargo operations and drone delivery trials now underway in designated economic zones. Stakeholders must monitor how forthcoming data localization requirements and emissions disclosure rules reshape fleet investment and technology vendor selection.
Market Dynamics
E-commerce volume saturation across Riyadh and Jeddah is compressing delivery margins while forcing operators to reconfigure hub-and-spoke networks toward micro-fulfillment nodes. The Communications, Space and Technology Commission's licensing mandates are accelerating fleet modernization timelines and reshaping last-mile operator economics.
Growth Catalysts
- Digital retail penetration:E-commerce platforms are capturing an expanding share of consumer spending across the Kingdom, generating parcel volume density that justifies dedicated sortation infrastructure in secondary cities.
- CST licensing frameworks:The Communications, Space and Technology Commission's regulatory clarity is consolidating operator compliance standards and raising barriers for informal last-mile providers.
- Industrial zone clustering:Concentrated manufacturing and logistics parks around Jeddah Islamic Port and King Abdulaziz Port are creating B2B freight corridors with predictable route economics.
Market Restraints
- Fuel price volatility:Diesel and jet fuel exposure in air-ground networks creates margin instability that standard fuel surcharges only partially offset for express operators.
- Last-mile labor concentration:Reliance on expatriate driver pools in Riyadh and Jeddah creates recruitment bottlenecks during peak seasonal windows.
- Address infrastructure gaps:Incomplete geocoding and informal settlement layouts outside major metros extend delivery times and raise failed-attempt rates.
Strategic Opportunities
- Drone delivery corridors:The General Authority of Civil Aviation's designated economic zone trials are creating regulatory sandboxes for autonomous last-mile pilot programs.
- Pharmaceutical cold chain:Temperature-controlled logistics for biologics and vaccines remains underdeveloped relative to Gulf neighbor capabilities.
- Makkah and Madinah pilgrimage logistics:Seasonal volume surges around Hajj and Umrah create demand for flexible capacity augmentation models.
Industry Challenges
- Warehouse automation integration:Legacy WMS platforms at Saudi Post-SPL and established operators resist seamless API connectivity with emerging robotics vendors.
- Emissions disclosure readiness:Anticipated SASO environmental reporting requirements are forcing fleet operators to deploy telematics before standardized calculation methodologies exist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Courier, Express, and Parcel (CEP) Market |
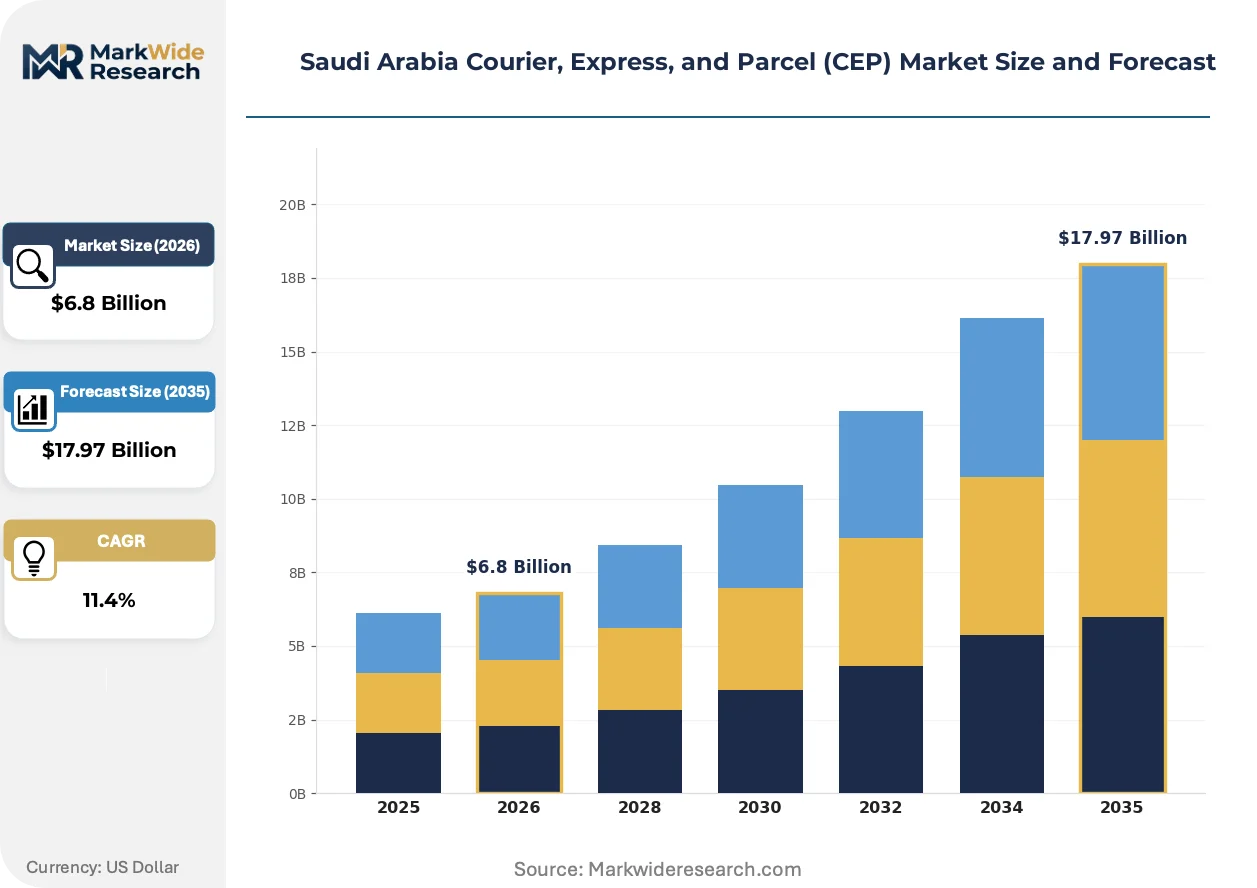
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, International Shipping, Standard Delivery Customer Type: Retailers, E-Commerce, Corporates, Individuals Package Size: Small, Medium, Large, Oversized Delivery Mode: Ground, Air, Sea, Drone |
| Companies Covered | DHL Group, UPS, Saudi Post-SPL (including Naqel Express), Zajil Express, Esnad Express, Aramex, FedEx, Abdul Latif Jameel IPR Company Limited, SMSA Express, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Courier, Express, and Parcel (CEP) Market Trends and Innovations
Technology deployment across Saudi CEP networks is shifting from centralized mega-hubs toward distributed micro-fulfillment architectures. Regulatory pressure on emissions and data localization is accelerating capital redeployment into domestic infrastructure.
Autonomous sorting robotics is decentralizing parcel handling from major hubs to neighborhood-scale facilities. E-commerce pure-play retailers are piloting these systems in Riyadh's northern logistics corridor. This technology is decentralizing inventory positioning and compressing same-day delivery radii from 50 kilometers to 15 kilometers.
The Communications, Space and Technology Commission's data localization requirements are mandating domestic server infrastructure for shipment tracking systems. This policy is forcing international operators to establish sovereign cloud instances within Saudi borders. Express and pharmaceutical verticals are responding by accelerating local technology vendor partnerships to ensure compliance continuity.
Subscription-based delivery memberships are displacing per-shipment pricing among frequent e-commerce buyers. Retailers are bundling free shipping into annual loyalty programs rather than absorbing costs on individual transactions. This shift is most visible in Jeddah's affluent northern districts where digital wallet penetration supports recurring payment models.
Saudi Arabia Courier, Express, and Parcel (CEP) Market Segmentation
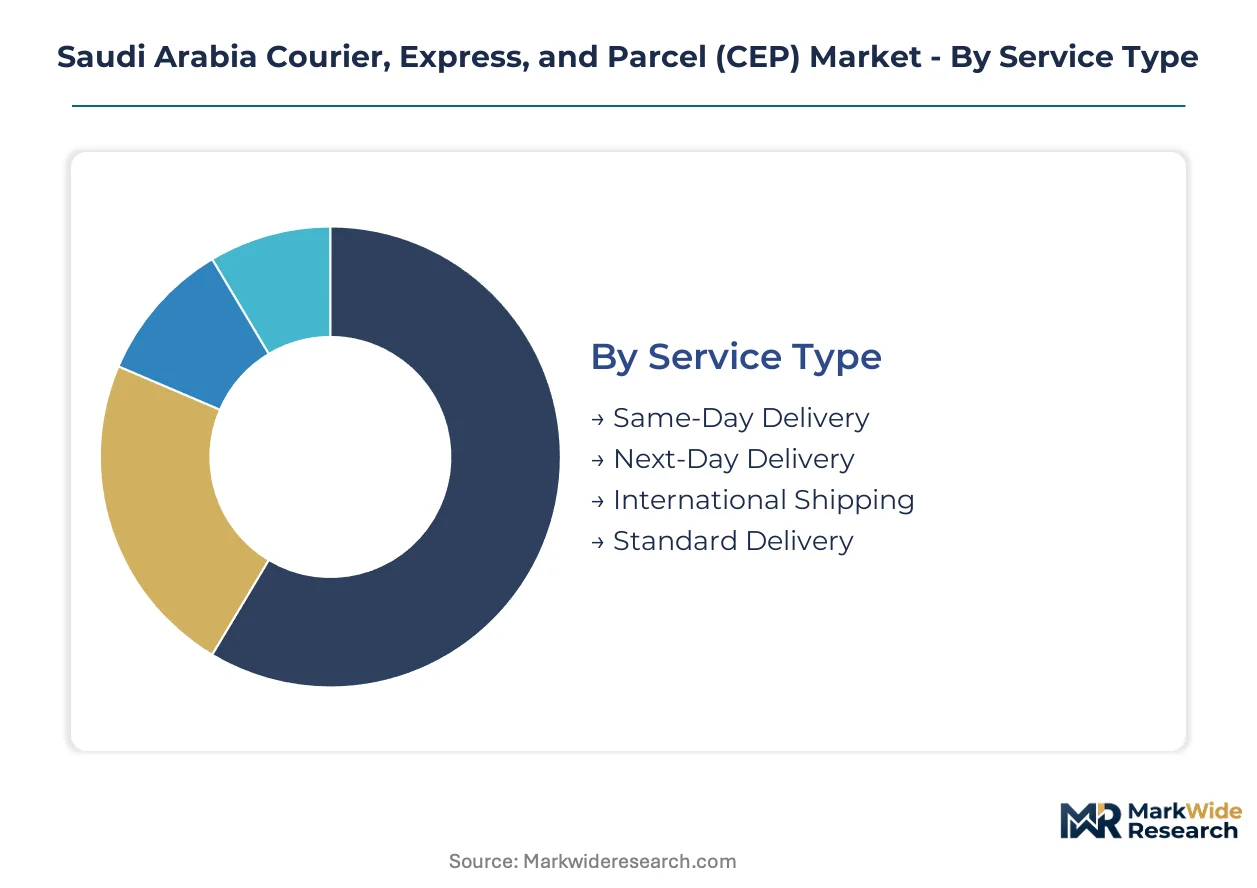
Service differentiation across Saudi Arabia's CEP landscape determines margin capture and infrastructure investment priorities. Customer heterogeneity spans pilgrimage logistics, pharmaceutical cold chains, and high-frequency e-commerce fulfillment, each demanding distinct operational configurations.
Service Type:
Volume gravitates toward commoditized tiers while premium segments sustain network economics through fuel surcharge pass-through and customs complexity.
- Same-Day Delivery:Ultra-rapid fulfillment compresses delivery radii to 15 kilometers through micro-fulfillment nodes in Riyadh's northern logistics corridor. Demand concentrates among grocery platforms and electronics retailers in Jeddah's affluent districts where digital wallet penetration supports subscription models.
- Next-Day Delivery:Time-definite service leverages hub-and-spoke networks with guaranteed morning or afternoon windows. E-commerce pure-plays in Riyadh and Jeddah drive volume density that justifies dedicated sortation infrastructure, though margin pressure intensifies during promotional windows.
- International Shipping:Cross-border express maintains the highest margin pool through customs brokerage and fuel surcharge structures. Pharmaceutical and automotive verticals in King Abdullah Economic City generate predictable B2B flows.
- Standard Delivery:Economical ground-based service with 2-5 day windows serves price-sensitive retailers migrating from owned logistics to outsourced partnerships.
Mature deployment sits with Standard Delivery. Newer deployment is concentrated in Same-Day Delivery.
Customer Type:
Procurement authority separates enterprise-grade contract negotiations from transactional platform economics.
- E-Commerce:Digital retail platforms generate parcel volume density that reshapes last-mile operator requirements across the Kingdom. CST licensing frameworks are consolidating compliance standards as informal providers face barriers to entry.
- Corporates:B2B freight corridors with predictable route economics concentrate around Jeddah Islamic Port and King Abdulaziz Port industrial zones. Zajil Express competes on route density within these manufacturing clusters.
- Retailers:Traditional merchants adopt hybrid fulfillment models blending owned inventory with third-party logistics partnerships.
- Individuals:C2C shipment volume remains fragmented across informal channels though regulatory clarity is formalizing peer-to-peer logistics.
Enterprise contracting dominates revenue concentration. Platform-native purchasing is climbing the fastest.
Package Size:
Dimensional weight pricing and sortation automation compatibility segment handling infrastructure.
- Small:Sub-kilogram envelopes and polybags dominate e-commerce apparel and electronics accessories. Autonomous sorting robotics in Riyadh's logistics corridor processes these items at neighborhood-scale facilities.
- Medium:Standard parcel dimensions align with automated conveyor systems and represent the baseline for API connectivity with emerging robotics vendors.
- Large:Bulky items require manual handling protocols and specialized vehicle fleets, creating capacity constraints during seasonal peaks.
- Oversized:Multi-ton freight and irregular dimensions demand flatbed and specialized equipment, with B2B concentration in industrial city corridors.
Automated processing coverage peaks with Small. Manual intervention requirements expand across Large.
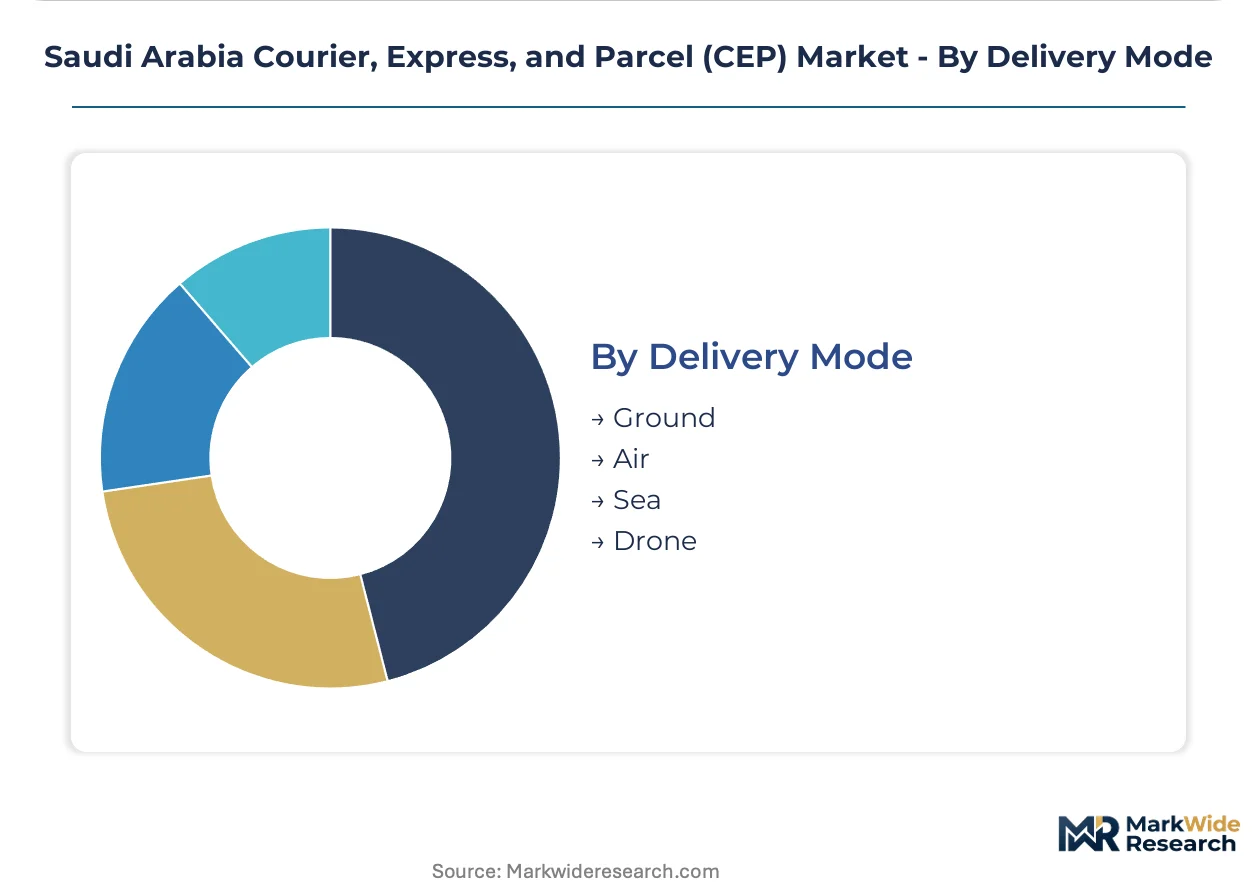
Delivery Mode:
Modal selection balances speed imperatives against fuel exposure and regulatory sandbox availability.
- Ground:Diesel-dependent fleet networks provide cost-effective coverage across Riyadh-Jeddah-Dammam corridors. SASO emissions disclosure requirements are forcing telematics deployment ahead of standardized calculation methodologies.
- Air:Jet fuel exposure creates margin instability that express operators partially offset through surcharge mechanisms. GACA regulates cargo operations with pharmaceutical cold chain representing underdeveloped vertical potential.
- Sea:Maritime freight serves non-urgent B2B flows through Jeddah Islamic Port with extended transit windows acceptable for bulk inventory replenishment.
- Drone:GACA-designated economic zone trials create regulatory sandboxes for autonomous last-mile pilot programs in controlled geographies.
Established fleet scale concentrates with Ground. Experimental authorization is advancing through Drone.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh and Jeddah concentrate Saudi Arabia's CEP volume gravity through urban density and industrial zone clustering. The Communications, Space and Technology Commission's licensing mandates reshape operator requirements across the Kingdom's logistics corridors.
Riyadh
E-commerce pure-plays and grocery platforms drive same-day delivery density through Riyadh's northern logistics corridor. The CST mandates data localization for shipment tracking systems, forcing domestic server infrastructure deployment. Micro-fulfillment nodes with autonomous sorting robotics compress delivery radii to fifteen kilometers in this corridor.
Jeddah
Affluent northern districts generate subscription-based delivery membership demand alongside electronics retail volume. The General Authority of Civil Aviation regulates air cargo operations supporting pharmaceutical cold chain development. Industrial parks around Jeddah Islamic Port create B2B freight corridors with predictable route economics for heavy freight specialists.
Eastern Province
Petrochemical and manufacturing clusters generate B2B parcel flows requiring time-definite transportation. The Saudi Standards, Metrology and Quality Organization governs packaging specifications for industrial goods in transit. King Abdulaziz Port anchors maritime freight connections with extended transit windows for bulk inventory replenishment.
Makkah and Madinah
Seasonal pilgrimage logistics create surging demand for flexible capacity augmentation during Hajj and Umrah periods. The CST's regulatory clarity formalizes peer-to-peer logistics channels previously fragmented across informal providers. Religious tourism infrastructure concentrates last-mile labor recruitment challenges during peak seasonal windows.
NEOM Northwest
Designated economic zones host GACA-sanctioned drone delivery trials for autonomous last-mile pilot programs. The Communications, Space and Technology Commission's emissions disclosure rules reshape fleet investment in this greenfield development. Regulatory sandboxes enable experimental authorization for autonomous sorting and delivery technologies absent legacy infrastructure constraints.
Saudi Arabia Courier, Express, and Parcel (CEP) Market Competitive Landscape
Capital-heavy network operators compete with asset-light platform intermediaries for margin capture across Saudi Arabia's CEP sector. The market structure consolidates around integrated air-ground networks, state-affiliated domestic infrastructure, and specialized B2B freight operators. Three strategic archetypes dominate: global express integrators leveraging multimodal density, national postal operators controlling last-mile reach, and industrial corridor specialists optimizing route economics. Competitive moves concentrate on fleet modernization timelines and micro-fulfillment node deployment.
Among global integrators, DHL Group and UPS exemplify the premium express archetype through integrated air-ground positioning. Saudi Post-SPL anchors the national infrastructure tier through Naqel Express, representing state-affiliated last-mile depth. Zajil Express occupies a position within the B2B heavy freight specialization, competing on industrial corridor route density.
| Leading Market Players |
|---|
| DHL Group |
| UPS |
| Saudi Post-SPL (including Naqel Express) |
| Zajil Express |
| Esnad Express |
| Aramex |
| FedEx |
| Abdul Latif Jameel IPR Company Limited |
| SMSA Express |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed infrastructure operators including Saudi Post-SPL anchor supply-side concentration through Naqel Express's last-mile dominance, enabling disciplined pricing tiers that informal competitors cannot match. This ownership pattern compresses margin competition in Riyadh and Jeddah while CST licensing mandates raise compliance costs that filter through to customer pricing.
Pricing Analysis
Time-definite delivery guarantees serve as the value-based pricing anchor across Saudi Arabia's CEP sector, with express operators commanding premiums for pharmaceutical and automotive verticals. Three-tier pricing structure across premium, standard, and economy levels segments customer willingness-to-pay, with subscription memberships displacing per-shipment models among frequent e-commerce buyers in Jeddah's affluent districts. Price differentiation rests on fuel surcharge pass-through mechanisms and customs brokerage complexity for cross-border flows. Margins are tightening due to e-commerce volume saturation compressing delivery economics in Riyadh's northern corridor. Corporate B2B contracts exhibit lowest price sensitivity, while individual C2C shippers demonstrate highest elasticity.
Supply Chain Analysis
Reverse logistics flows for e-commerce returns are accelerating infrastructure investment in neighborhood-scale sortation facilities across the Kingdom. Equipment and fleet assets concentrate manufacturing in Germany, China, and Japan for automated conveyor systems and last-mile vehicles. Diesel and jet fuel dependencies create exposure to global commodity swings, while packaging materials draw from regional petrochemical feedstocks. Single-source vulnerability sits with expatriate driver recruitment pools concentrated in Riyadh and Jeddah. Distribution runs through hub-and-spoke networks anchored by DHL Group's integrated air-ground infrastructure and Naqel Express's domestic last-mile density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's CEP sector functions as a cost-of-compliance story where CST licensing frameworks erect barrier-to-entry moats favoring operators with capital to modernize fleets and deploy domestic server infrastructure.
For Market Incumbents: Anticipate margin compression from e-commerce pure-plays building captive logistics capabilities by accelerating micro-fulfillment node deployment in secondary cities. Vertical integration into pharmaceutical cold chain infrastructure captures underdeveloped vertical potential. Certification investment in SASO emissions disclosure readiness creates competitive separation as regulatory clarity emerges.
For New Entrants and Emerging Players: GACA-designated economic zone trials in NEOM Northwest open a window for drone delivery specialists to establish regulatory sandbox credentials absent legacy infrastructure constraints. Pharmaceutical cold chain and Makkah-Madinah pilgrimage logistics represent the most penetrable white-space targets. A go-to-market angle anchored in temperature-controlled biologics transportation bypasses saturated e-commerce corridors.
For Investors and Strategic Acquirers: CST's acceleration of fleet modernization timelines is the leading indicator that compliance-ready operators will consolidate market share. Long-term viability favors asset-heavy networks with sovereign-affiliated last-mile depth over platform intermediaries. Acquisition target archetypes include industrial corridor specialists with route density in King Abdullah Economic City. Monitor GACA drone delivery authorization expansions as inflection signal for autonomous last-mile viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Node Deployment | Autonomous sorting robotics in Riyadh's northern corridor compresses same-day delivery radii to fifteen kilometers. |
| Pharmaceutical Cold Chain Buildout | Temperature-controlled infrastructure captures biologics and vaccine logistics demand from Saudi healthcare expansion. |
| Domestic Cloud Infrastructure Establishment | CST data localization mandates force international operators to deploy sovereign server instances within Kingdom borders. |
| Drone Delivery Corridor Authorization | GACA-sanctioned trials in NEOM Northwest create regulatory sandbox credentials for autonomous last-mile operators. |
| Subscription Membership Program Launch | Digital wallet penetration in Jeddah's affluent districts supports recurring revenue models displacing per-shipment pricing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with logistics operations directors, fleet procurement managers, CST compliance officers, e-commerce platform supply chain leads, and pharmaceutical distribution specialists. Secondary sources included Communications Space and Technology Commission licensing databases, General Authority of Civil Aviation cargo operation records, Saudi Standards Metrology and Quality Organization packaging specifications, and customs import documentation for logistics equipment. Bottom-up parcel volume modeling triangulated against top-down macroeconomic consumption indicators.
Granularity-level modeling deployed service-type segmentation at the shipment level across same-day, next-day, international, and standard delivery tiers, with customer-type disaggregation for e-commerce platforms, corporate B2B contracts, traditional retailers, and individual shippers. Package size and delivery mode dimensions were modeled with regional splits across Riyadh, Jeddah, Eastern Province, Makkah-Madinah, and NEOM Northwest. CAGRs were derived from trend extrapolation of e-commerce penetration curves and industrial zone clustering patterns, with fleet modernization investment cycles and fuel surcharge pass-through mechanisms as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for autonomous drone delivery would alter the outlook if GACA regulatory sandboxes expand beyond designated economic zones. Forecasts reflect assumptions around CST licensing enforcement intensity and SASO emissions disclosure implementation timelines. Practitioners should monitor GACA drone authorization scope expansions and CST data localization deadline clarifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market