
 Fuel Management Systems (FMS) Market | 2026-2036
Fuel Management Systems (FMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Management Systems (FMS) Market Foresight
Commercial fleet operations is expanding as the dominant demand vertical for fuel management systems, displacing traditional industrial plant deployments. Samsara leverages its integrated telematics platform to anchor cloud-based fuel tracking across North American logistics networks. Motive competes through AI-powered fuel analytics that extend visibility into driver behavior and vehicle performance. Fleetio sustains its position with subscription software that controls maintenance-to-fuel cost correlations for mid-size operators.
Fuel management systems comprise hardware and software architectures that monitor, control, and optimize fuel distribution, storage, and consumption across vehicle fleets and stationary equipment. These systems typically incorporate flow meters, tank-level sensors, automated dispensing controllers, and cloud dashboards that deliver real-time inventory visibility and prevent unauthorized fuel access. Mobile fuel management systems represent the fastest-expanding product category as remote construction and mining sites abandon fixed infrastructure for portable, satellite-connected dispensing units. Fleet management applications generate the deepest margin pools because recurring software subscriptions attach to long-term vehicle telematics contracts. Cloud-based deployment is displacing on-premise systems as transportation companies prioritize centralized data access across distributed vehicle networks.
The EPA enforces greenhouse gas standards for medium and heavy-duty trucks that compel fleet operators to document fuel efficiency improvements through certified management systems. EMA's evolving automotive emissions frameworks in Europe mandate tamper-proof fuel monitoring as a precondition for CO2 compliance certification. India's BIS fuel quality standards and the country's PLI scheme for automotive components are accelerating domestic adoption of certified dispensing and tracking equipment. Stakeholders must decide whether to build proprietary IoT fuel sensor networks or partner with established telematics platforms as regulatory documentation requirements tighten across jurisdictions.
Market Dynamics
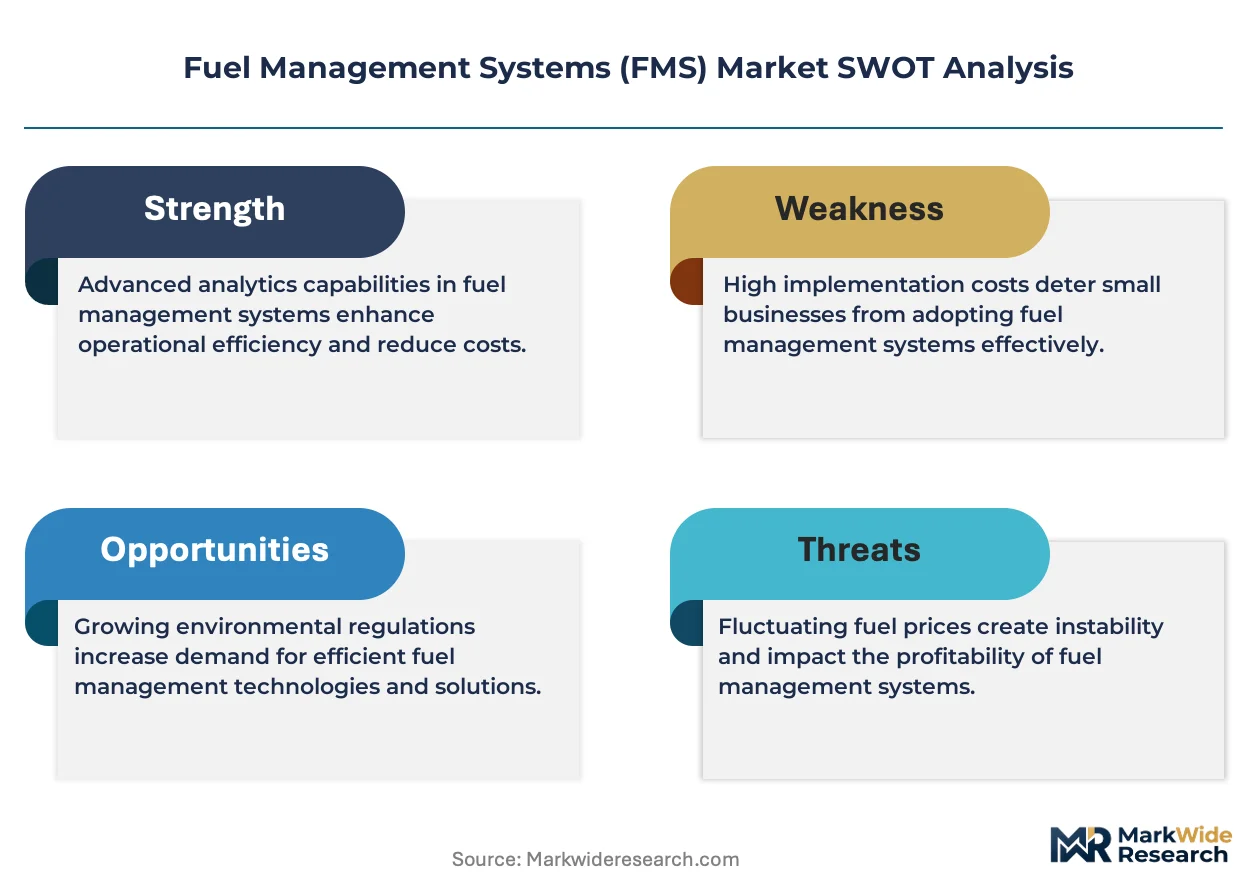
Fleet digitization mandates are compressing deployment timelines for fuel management infrastructure as operators face simultaneous pressure from emissions accountability rules and margin compression in logistics.
Growth Catalysts
- EPA greenhouse gas standards:Medium and heavy-duty truck operators must document fuel efficiency improvements through certified monitoring systems, creating compliance-driven procurement.
- Cloud-connected telematics platforms:Transportation fleets are consolidating vendor relationships around integrated fuel tracking and vehicle management dashboards.
- Construction and mining:Remote site operators are abandoning fixed fuel infrastructure for portable satellite-connected dispensing units with real-time inventory visibility.
Market Restraints
- Sensor hardware costs:Precision flow meters and tank-level monitoring equipment require significant upfront capital outlay that mid-size fleet operators struggle to justify.
- Semiconductor supply concentration:IoT fuel sensor production depends on chip fabrication concentrated in East Asian foundries, exposing lead times to geopolitical disruption.
- Legacy system incompatibility:Existing on-premise fuel management architectures in industrial plants resist seamless cloud migration without costly middleware development.
Strategic Opportunities
- India's automotive PLI scheme:Domestic component manufacturing incentives are accelerating certified dispensing equipment production for South Asian fleet operators.
- AI-powered predictive maintenance:Machine learning models that correlate fuel consumption patterns with engine degradation are opening subscription revenue streams.
- EU Green Deal transport decarbonization:CO2 compliance certification requirements are mandating tamper-proof fuel monitoring as a precondition for commercial vehicle licensing.
Industry Challenges
- Embedded systems engineering talent:Shortage of firmware developers with expertise in low-power IoT sensor networks delays product roadmaps for hardware vendors.
- Multi-jurisdiction certification timelines:Equipment must satisfy divergent EPA, EMA, and BIS testing protocols before cross-border deployment, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Management Systems (FMS) Market |
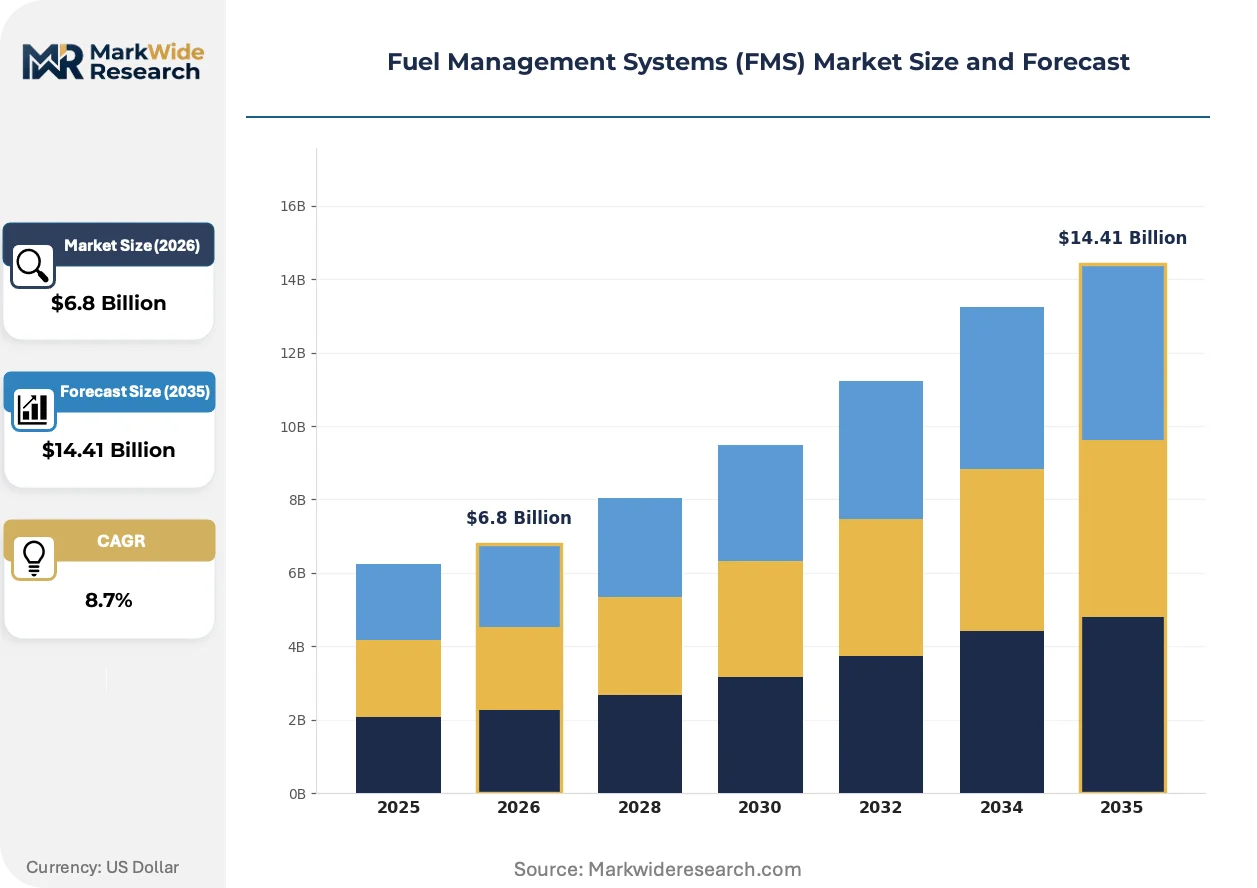
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Fuel Dispensers, Manual Fuel Dispensers, Electronic Fuel Dispensers, Mobile Fuel Management Systems Application: Fleet Management, Industrial Plants, Construction Equipment, Agricultural Machinery, Mining Operations End User: Transportation Companies, Marine Operators, Aviation Services, Municipal Services, Construction Firms Deployment: Cloud-Based Solutions, On-Premise Systems, Hybrid Platforms, Mobile Applications |
| Companies Covered | Azuga, Simply Fleet, Samsara, GPSTab, AUTOsist, Motive, FuelForce, FuelCloud, Fleetio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Management Systems (FMS) Market Shifts & Advancements
Edge computing architectures and satellite connectivity are redefining where fuel data gets processed, while regulatory documentation requirements harden around tamper-evident digital records.
Ultrasonic fuel level sensors with embedded edge AI are absorbing the processing load previously handled by centralized cloud platforms, enabling real-time leak detection and theft alerts at remote dispensing sites. Mining operators in Australia and construction contractors in Canada are deploying these units at pace. The shift is absorbing margin from traditional telemetry gateway providers as sensor vendors bundle analytics directly into hardware.
REACH chemical registration requirements and the EU F-Gas Regulation are tightening material specifications for fuel system seals and gaskets used in European commercial vehicle fleets. Component suppliers must document substance compliance across complex supply chains. German and French fleet operators are responding by specifying certified fuel management hardware with full material traceability documentation.
Subscription-based fuel analytics are replacing perpetual software licenses as the dominant commercial model for fleet management platforms. Mid-size logistics operators in the United States are driving this transition, preferring operational expenditure treatment over capital-intensive on-premise deployments. The shift is compressing vendor cash conversion cycles while locking in longer customer relationships through embedded telematics integration.
Fuel Management Systems (FMS) Market Segmentation
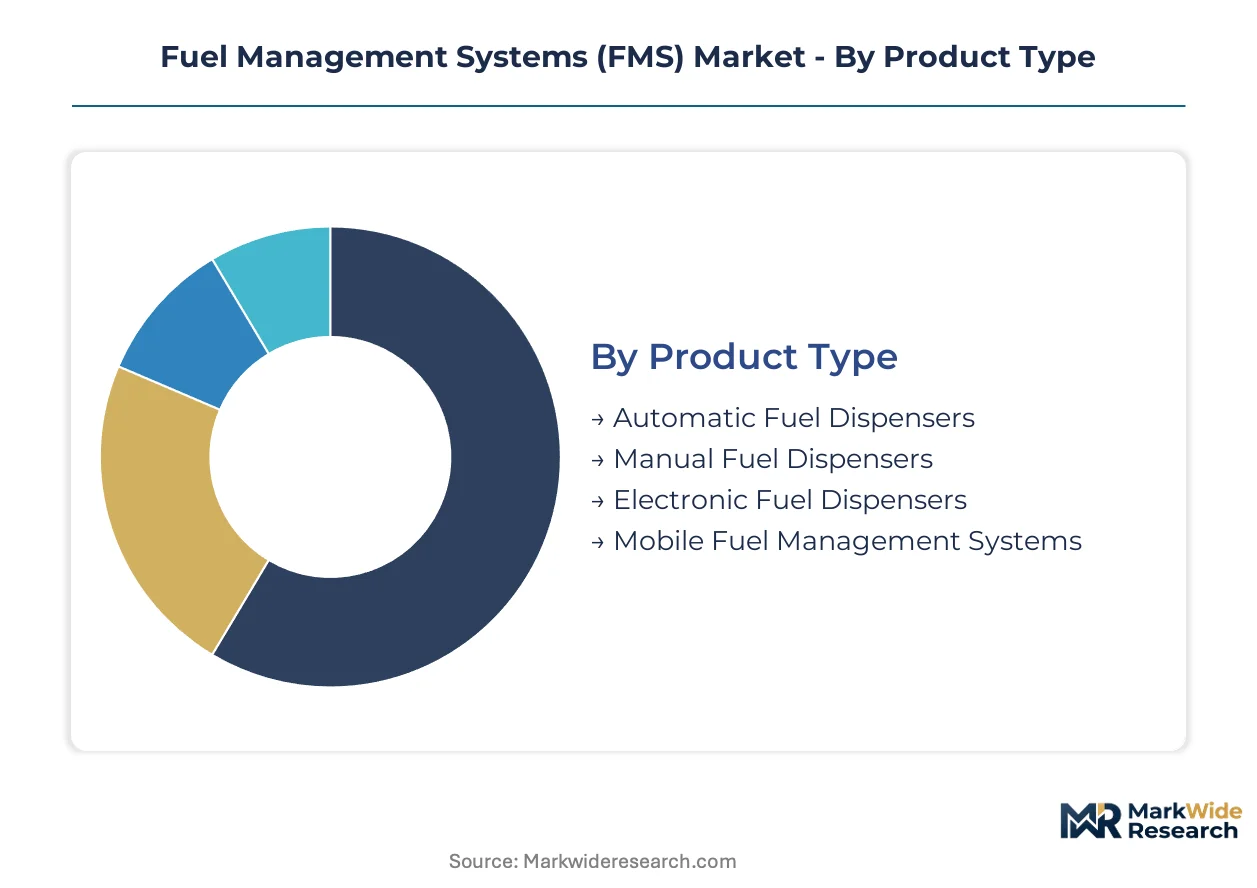
Fuel management systems fragment across hardware specifications, operational environments, and data architectures. Each segmentation axis reveals distinct procurement patterns and margin structures that vendors must navigate.
Product Type:
Specification tiers separate precision dispensing equipment from basic mechanical units, with connectivity modules now defining upgrade pathways.
- Automatic Fuel Dispensers:These units integrate programmable logic controllers with flow meters and tank-level sensors for unattended fueling operations. Demand concentrates in United States logistics hubs where EPA documentation requirements mandate tamper-evident transaction logging for medium and heavy-duty fleets.
- Mobile Fuel Management Systems:Portable satellite-connected dispensing units carry embedded edge processors for real-time inventory tracking at remote sites. Mining contractors in Australia and construction operators in Canada are deploying these fastest as fixed infrastructure becomes economically unviable for dispersed operations.
- Electronic Fuel Dispensers:Digital display units with basic networking capabilities serve mid-size fleet operators seeking upgrade paths from mechanical systems.
- Manual Fuel Dispensers:Mechanical pump-and-meter configurations persist in developing markets with limited electrical infrastructure or as backup systems for critical facilities.
Mature deployment sits with automatic fuel dispensers in established logistics corridors. Newer deployment is concentrated in mobile fuel management systems for resource extraction and remote construction.
Application:
Operational intensity and regulatory exposure determine which verticals absorb premium system architectures versus basic monitoring configurations.
- Fleet Management:Cloud-connected telematics integration enables real-time fuel consumption correlation with vehicle location, driver behavior, and maintenance schedules. United States transportation companies and German freight operators are consolidating procurement around platforms that unify fuel data with emissions compliance documentation.
- Construction Equipment:Harsh operating environments demand ruggedized sensors and satellite connectivity for dispersed job sites. Remote project operators in Canada and mining contractors in Australia are abandoning fixed fuel infrastructure for portable dispensing with real-time theft alerts.
- Industrial Plants:Tank farm monitoring and process fuel tracking systems serve manufacturing facilities with centralized fuel storage.
- Mining Operations:High-volume continuous consumption patterns require precision flow measurement and automated replenishment scheduling.
- Agricultural Machinery:Seasonal usage patterns favor basic dispensing units with simple record-keeping for tax credit documentation.
Procurement volume clusters in fleet management for compliance documentation. Margin expansion is steepest in construction equipment where environmental harshness commands premium pricing.
End User:
Operational scale and regulatory scrutiny separate enterprise-grade deployments from standardized configurations.
- Transportation Companies:Multi-vehicle logistics operators require centralized dashboards correlating fuel costs with route efficiency and driver performance metrics.
- Marine Operators:Bunker fuel tracking for international vessels demands compliance with MARPOL documentation and port state control inspection protocols.
- Aviation Services:Into-plane fueling systems for fixed-base operators integrate with airline billing platforms and weight-and-balance calculations.
- Municipal Services:City fleet operators balance public accountability requirements with constrained capital budgets across police, fire, and public works vehicles.
- Construction Firms:Project-based fuel consumption tracking supports job costing and equipment utilization analysis for contract bidding.
System complexity peaks with marine and aviation operators facing international regulatory overlap. Standardized deployments dominate municipal services where procurement follows public sector bidding protocols.
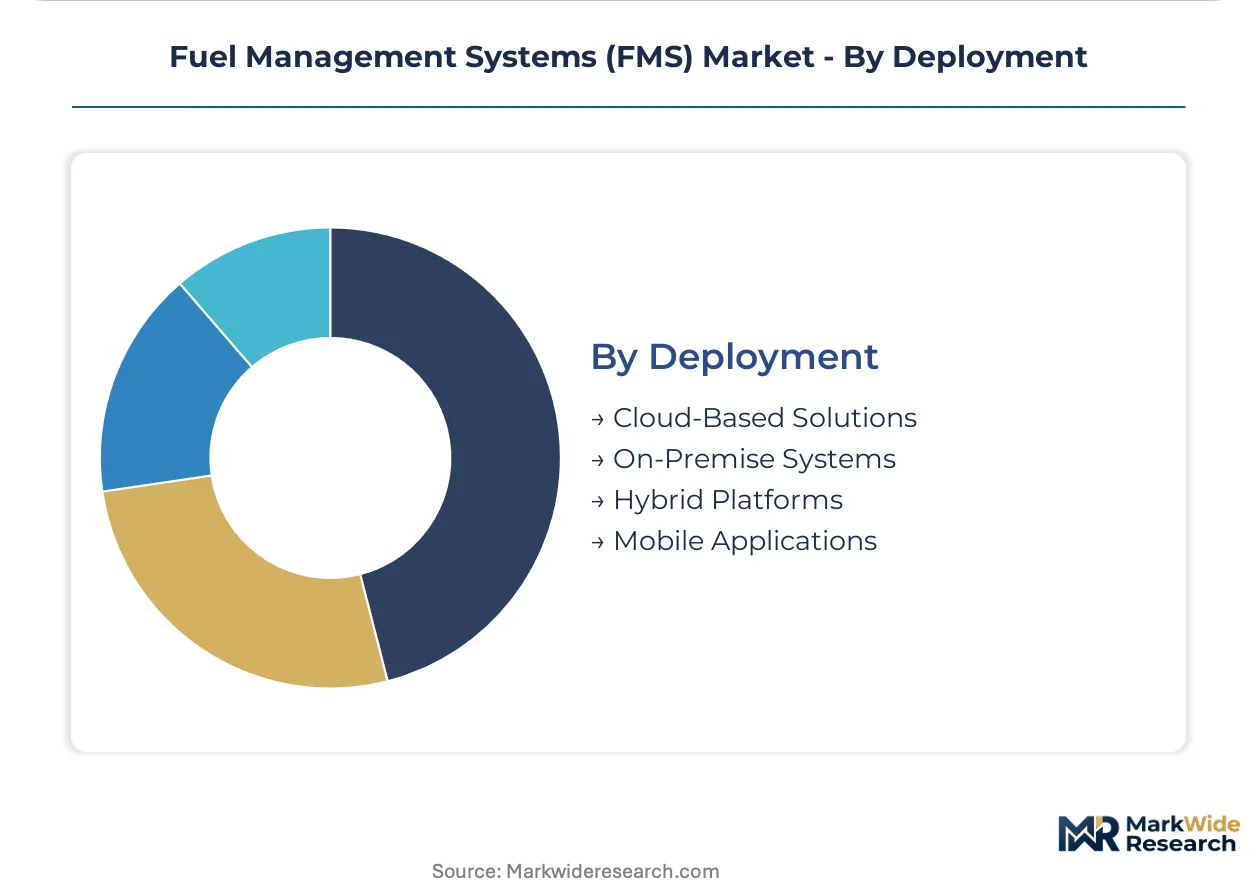
Deployment:
Data sovereignty requirements and connectivity infrastructure determine architectural choices between centralized cloud platforms and retained on-premise control.
- Cloud-Based Solutions:Subscription models deliver centralized access across distributed vehicle networks with automatic software updates and API integration to telematics platforms. United States mid-size logistics operators are driving this transition preferring operational expenditure treatment.
- On-Premise Systems:Local server installations retain full data control for operators with sensitive security requirements or unreliable internet connectivity.
- Hybrid Platforms:Edge processing with cloud synchronization balances real-time responsiveness with centralized analytics for large-scale deployments.
- Mobile Applications:Smartphone-based interfaces extend visibility to field supervisors without dedicated terminal hardware.
Cloud-based solutions are expanding most quickly in North American logistics networks. On-premise systems persist where data residency regulations or security classifications prohibit external hosting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones and logistics corridors are concentrating fuel management infrastructure investment in jurisdictions with fleet digitization incentives. Tax-advantaged warehousing districts in Germany, the United States, China, India, and Australia are anchoring procurement clusters for cloud-connected fuel tracking systems.
United States
Mid-size logistics operators across the Midwest and Southeast are consolidating vendor relationships around integrated telematics platforms. EPA greenhouse gas standards for medium and heavy-duty trucks mandate tamper-evident fuel documentation, driving compliance-driven procurement in Ohio and Illinois distribution corridors. Dallas-Fort Worth and Atlanta logistics hubs are deploying cloud-based fuel tracking at scale.
Germany
Freight operators in Bavaria and North Rhine-Westphalia are specifying fuel management hardware with full material traceability documentation. The EU F-Gas Regulation and REACH chemical registration requirements tighten specifications for fuel system seals and gaskets. Stuttgart and Munich automotive logistics clusters are mandating certified dispensing equipment for commercial vehicle fleets.
China
Domestic fleet operators in the Yangtze River Delta are adopting IoT fuel sensors under MIIT-connected vehicle mandates. Dual carbon goals and GB standards for commercial vehicle emissions accelerate certified monitoring system deployment. Shanghai and Suzhou logistics zones are integrating fuel data with national vehicle telematics platforms.
India
Maharashtra and Gujarat-based fleet operators are sourcing certified dispensing equipment under the PLI scheme for automotive components. BIS fuel quality standards and evolving emissions frameworks accelerate domestic adoption of tamper-proof tracking systems. Mumbai-Pune and Ahmedabad industrial corridors are digitizing fuel infrastructure for commercial vehicle compliance.
Australia
Mining contractors in Western Australia and Queensland are abandoning fixed fuel infrastructure for portable satellite-connected dispensing units. Real-time inventory visibility and theft prevention drive demand at remote extraction sites. Perth and Brisbane resource logistics clusters are deploying edge-enabled fuel management at dispersed operations.
Fuel Management Systems (FMS) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with software-integrated platforms commanding premium positioning against hardware-centric suppliers. The vendor base organizes into three tiers: telematics-native platforms with embedded fuel analytics, standalone fuel hardware specialists, and fleet management software providers extending into fuel tracking. Consolidation pressure is intensifying as transportation fleets demand unified dashboards. Strategic moves center on API integration partnerships and sensor-to-cloud vertical integration to capture recurring subscription revenue.
Within the telematics-integrated tier, Samsara and Motive exemplify platforms that anchor fuel data within broader vehicle management ecosystems. Samsara occupies a position representing cloud-native fleet infrastructure, while Motive exemplifies AI-powered analytics extension into driver behavior correlation. Fleetio sits within the subscription software archetype, demonstrating how maintenance-to-fuel cost control modules lock in mid-size operator relationships. These three companies represent distinct competitive vectors: hardware-telemetry bundling, predictive intelligence layering, and SaaS workflow embedding.
| Leading Market Players |
|---|
| Azuga |
| Simply Fleet |
| Samsara |
| GPSTab |
| AUTOsist |
| Motive |
| FuelForce |
| FuelCloud |
| Fleetio |
| Others |
Supply & Pricing Matrix
Edge AI integration into ultrasonic fuel sensors is compressing hardware margins while concentrating production among vendors with captive firmware development. This dual shift rewards integrated platforms that bundle analytics with telemetry, squeezing standalone sensor manufacturers on both cost and differentiation.
Pricing Analysis
Premium pricing attaches to short-lead-time fulfillment for EPA-certified automatic dispensers, while spot inventory of basic electronic units trades at discounts. Subscription-based SaaS tiers dominate fleet management applications, with price differentiation driven by telematics integration depth and emissions documentation automation. Pricing pressure stems from semiconductor cost volatility and mid-size fleet operator budget constraints. Municipal services exhibit highest price sensitivity due to public procurement protocols, whereas mining contractors absorb premium positioning for satellite-connected mobile systems.
Supply Chain Analysis
Firmware engineering talent shortages in Germany and the United States are constraining production scaling for edge-enabled sensor vendors. IoT fuel sensor manufacturing draws from Taiwan and South Korea for chip fabrication, with precision flow meter components sourced from German and Japanese suppliers. Single-source vulnerability concentrates in East Asian semiconductor foundries, exposing lead times to geopolitical disruption. Distribution runs through telematics platform partnerships and direct fleet operator contracts, with cloud-based deployment compressing traditional hardware distributor roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated telematics platforms as EPA documentation mandates force smaller hardware vendors into partnership or exit. Fleet operator procurement consolidation favors vendors with embedded software subscriptions over standalone equipment suppliers.
For Market Incumbents: Cement platform stickiness through API-native integration with Samsara and Motive telematics ecosystems, locking in recurring revenue against modular competitors. Invest in backward integration into edge AI chip design to reduce dependency on Taiwan foundry allocations and accelerate product roadmaps. Defend against cloud-native entrants by acquiring specialized construction equipment sensor vendors with ruggedized IP portfolios. For New Entrants and Emerging Players: The mid-tier price gap between premium telematics-integrated platforms and economy manual dispensers offers white-space entry for hybrid cloud-on-premise solutions targeting Indian and Australian mid-size fleets. Penetrate India's PLI-accelerated automotive corridor with certified dispensing equipment priced below German imports. Pursue construction equipment operators in Canada through satellite-connectivity-first positioning without legacy on-premise infrastructure baggage. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by telematics platforms seeking fuel analytics capabilities, with financial sponsor rollup opportunities in fragmented European hardware specialists. Long-term viability favors vendors with recurring software revenue exceeding fifty percent of mix and regulatory certification across EPA, EMA, and BIS jurisdictions. Watch for EPA enforcement acceleration on medium-duty truck documentation as inflection signal for compliance-driven procurement spikes.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Platform Integration | Embedded fuel analytics within Samsara and Motive ecosystems lock in multi-year fleet contracts. |
| Edge AI Chip Design Investment | Captive ultrasonic sensor processing reduces cloud dependency and accelerates theft-alert responsiveness. |
| Multi-Jurisdiction Certification | Simultaneous EPA, EMA, and BIS compliance opens cross-border procurement for global fleet operators. |
| Construction Equipment Specialization | Ruggedized satellite-connected units command premium pricing in Australian mining and Canadian remote sites. |
| Subscription Revenue Transition | Recurring SaaS models improve cash conversion cycles and customer lifetime value versus perpetual licenses. |
Research Methodology
Multi-period observation of fleet telematics adoption rates and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with fleet operations directors, IoT sensor engineering leads, EPA compliance officers, and logistics procurement managers. Secondary validation drew from EPA enforcement databases, EMA automotive emissions filings, Indian PLI scheme disbursement records, and customs trade data for fuel dispensing equipment. Bottom-up fleet operator spend estimates triangulated against top-down vendor revenue disclosures.
Segment-weighting applied product type, application vertical, deployment architecture, and regional regulatory cluster as primary dimensions across the projection horizon. CAGRs derived from logistic diffusion modeling of cloud adoption curves and compliance mandate phase-in schedules. Forecast inputs incorporated semiconductor supply lead time indices and commercial vehicle production forecasts by powertrain category.
Inputs from fleet operator interviews and regulatory filing databases were available through the study window; gaps in real-time inventory data from private mining contractors introduce uncertainty bands around mobile system deployment estimates. Forecasts reflect documented assumptions regarding EPA enforcement continuity and EMA F-Gas Regulation implementation pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
Parking Meter Market
Transportation & Logistics
ASEAN Road Freight Transport Market