
 Indonesia Courier, Express, and Parcel (CEP) Market | 2026-2036
Indonesia Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Courier, Express, and Parcel (CEP) Market Insights
Fragmentation among e-commerce sellers is restructuring buyer concentration across Indonesia's CEP landscape. J&T Express leverages its proprietary sorting technology to dominate cross-island parcel flows. JNE Express sustains one of the deepest rural branch networks, anchoring its position in intercity standard delivery. SiCepat Ekspres differentiates through aggressive same-day coverage in Greater Jakarta and surrounding satellite cities.
Indonesia Courier, Express, and Parcel services encompass time-definite and non-time-definite logistics solutions handling items from documents to bulk freight, typically operating through hub-and-spoke distribution with automated sortation facilities and multi-modal island connectivity. The primary commercial purpose is bridging geographic dispersion across the Indonesian archipelago for retail, manufacturing, and personal correspondence needs. Same day delivery commands premium pricing and captures the fastest expansion as urban consumers expect instant fulfillment, while ground transportation remains the backbone mode due to cost efficiency across short-haul intra-island routes. E-commerce platforms represent the most concentrated customer segment, generating disproportionate volume share and dictating service-level requirements across the industry.
Indonesia's Ministry of Transportation governs commercial vehicle licensing and freight operator permits, while the Ministry of Communications and Informatics oversees digital platform regulations affecting e-commerce logistics integration. BIS certification requirements for packaging materials influence operational standards, and the country's national postal regulator shapes universal service obligations that constrain pricing freedom for certain delivery categories. Stakeholders must monitor how evolving cross-border customs digitization and emerging carbon accounting rules for freight fleets will reshape cost structures and competitive barriers.
Market Dynamics
E-commerce platform consolidation and the Ministry of Communications and Informatics digital infrastructure mandates are compressing delivery timelines while forcing capital deployment into automated sortation and last-mile density across the Indonesian archipelago.
Growth Catalysts
- Digital infrastructure mandates:Indonesia's Ministry of Communications and Informatics policies accelerate fiber-optic backbone expansion and 4G/5G penetration into tier-2 and tier-3 cities, enabling real-time tracking and dynamic routing for parcel networks.
- Same-day service tier:Urban consumers in Greater Jakarta and satellite cities now expect sub-24-hour fulfillment, pulling investment into micro-fulfillment centers and motorcycle-based courier density.
- Cross-island connectivity:Roll-on/roll-off sea freight integration with ground distribution reduces inter-island transit times between Java, Sumatra, and Sulawesi, unlocking previously uneconomical routes.
Market Restraints
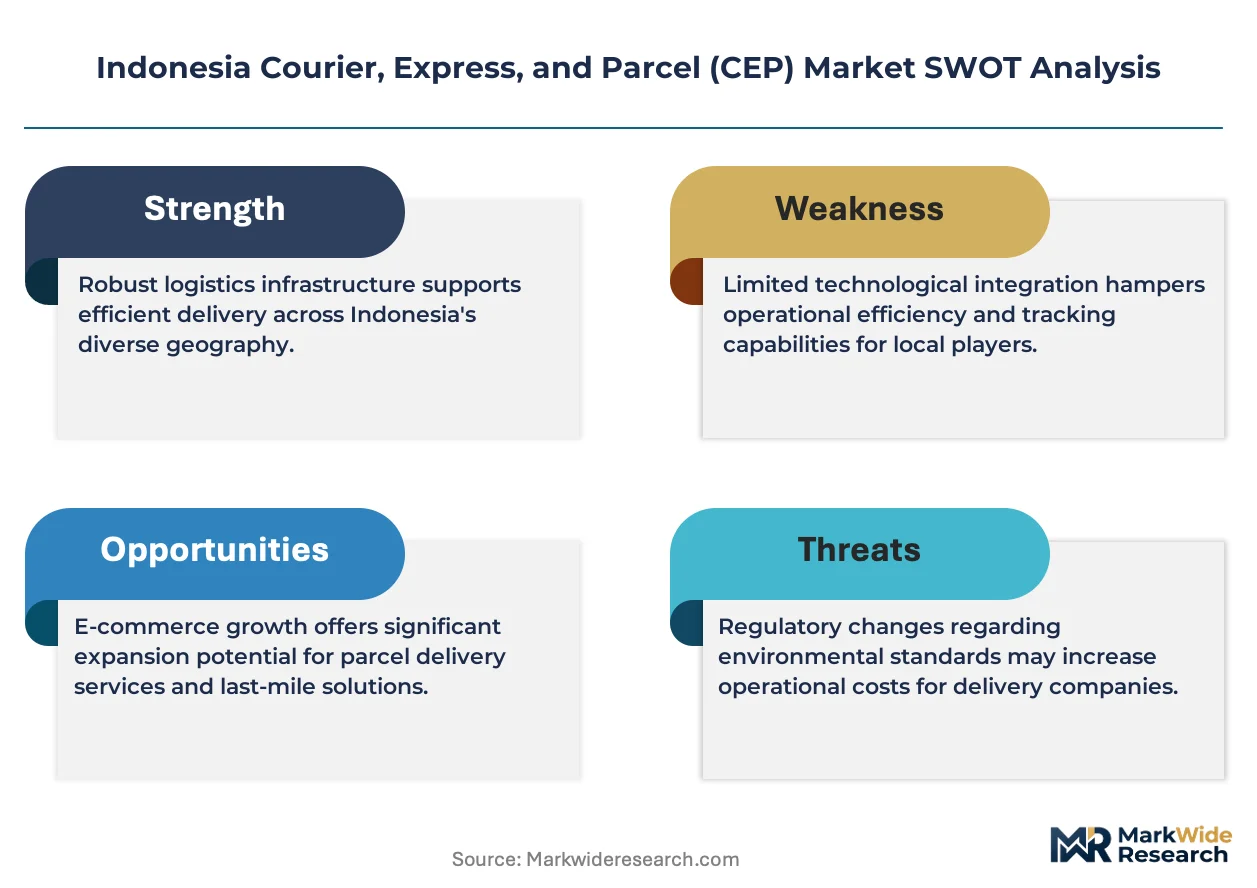
- Fuel cost volatility:Diesel and gasoline price fluctuations directly compress ground transportation margins, which constitute the backbone mode for intra-island parcel movement across the archipelago.
- Java-centric volume concentration:Over 70% of parcel flows originate from or terminate in Jakarta, Surabaya, and Bandung, creating asymmetric network utilization and deadhead inefficiency for outer island routes.
- Customs digitization gaps:Incomplete cross-border customs automation at major ports generates clearance delays for international express shipments, constraining premium service reliability.
Strategic Opportunities
- Eastern Indonesia penetration:Papua, Maluku, and Nusa Tenggara Timur remain underserved by integrated parcel networks, presenting first-mover advantage for hub-and-spoke infrastructure investment.
- Cold chain express:Temperature-controlled pharmaceutical and fresh food logistics represent an emerging application segment with premium pricing and limited incumbent specialization.
- Carbon accounting rules:Anticipated Ministry of Transportation emissions reporting requirements for commercial freight fleets will favor early adopters of electric two-wheelers and route optimization software.
Industry Challenges
- Last-mile labor retention:Motorcycle courier churn rates exceed sustainable thresholds in Greater Jakarta, eroding service consistency and inflating recruitment costs for express operators.
- Legacy IT integration:Mid-tier logistics providers struggle to API-connect with major e-commerce platforms, creating order-to-fulfillment latency and inventory visibility gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Courier, Express, and Parcel (CEP) Market |
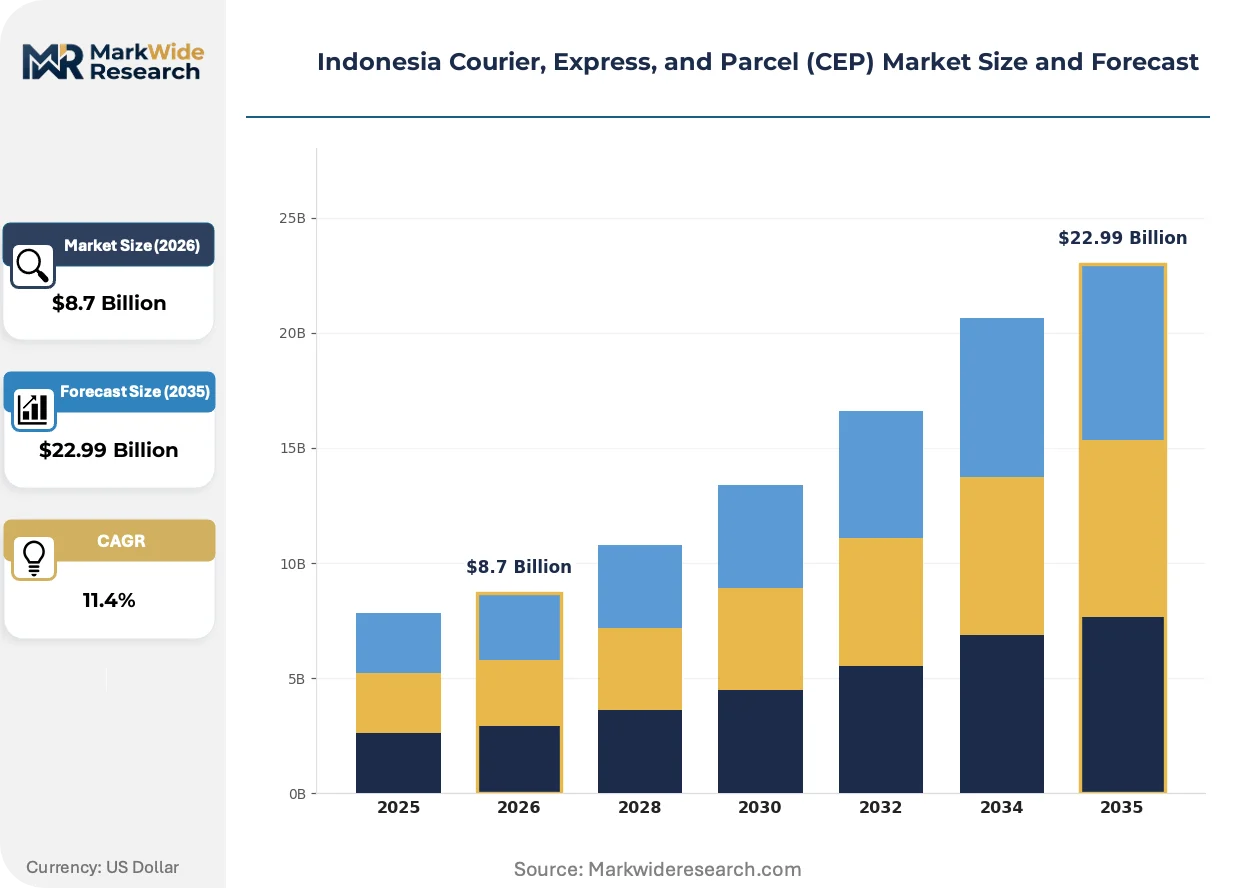
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Same Day Delivery, Next Day Delivery, Scheduled Delivery Delivery Mode: Ground, Air, Sea, Intermodal Customer Type: Individual Consumers, Small Businesses, Corporates, E-commerce Platforms Package Size: Small, Medium, Large, Extra Large |
| Companies Covered | J&T Express, JNE Express, SiCepat Ekspres, Ninja Xpress, Pos Indonesia, TIKI, Pahala Express, Anteraja, JET Express, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Courier, Express, and Parcel (CEP) Market Trends and Innovations
Automated sortation and dynamic routing algorithms are compressing hub dwell times while reconfiguring competitive advantage around data infrastructure rather than physical network scale alone.
Automated parcel sortation systems utilizing machine vision and robotic arm induction are overtaking manual sorting in Java's mega-hubs. J&T Express and SiCepat Ekspres have deployed proprietary systems capable of processing over 10,000 parcels per hour with sub-1% mis-sort rates. This technology is overtaking labor-intensive operations as the primary determinant of unit economics at volume.
Indonesia's Ministry of Transportation is tightening commercial vehicle licensing requirements for freight operators, mandating GPS tracking and periodic safety inspections. The regulation compresses informal carrier participation while favoring fleet-owning incumbents with compliance infrastructure. Express operators are responding by consolidating subcontractor relationships and bringing core routes in-house.
Buyer concentration among e-commerce platforms is restructuring procurement power toward volume-based rate cards with service-level guarantees. Third-party logistics providers now face compressed margins and performance penalties that were absent in fragmented seller markets. This shift is most visible in Greater Jakarta, where platform-owned logistics arms and independent CEP providers compete for exclusive fulfillment contracts.
Indonesia Courier, Express, and Parcel (CEP) Market Segmentation
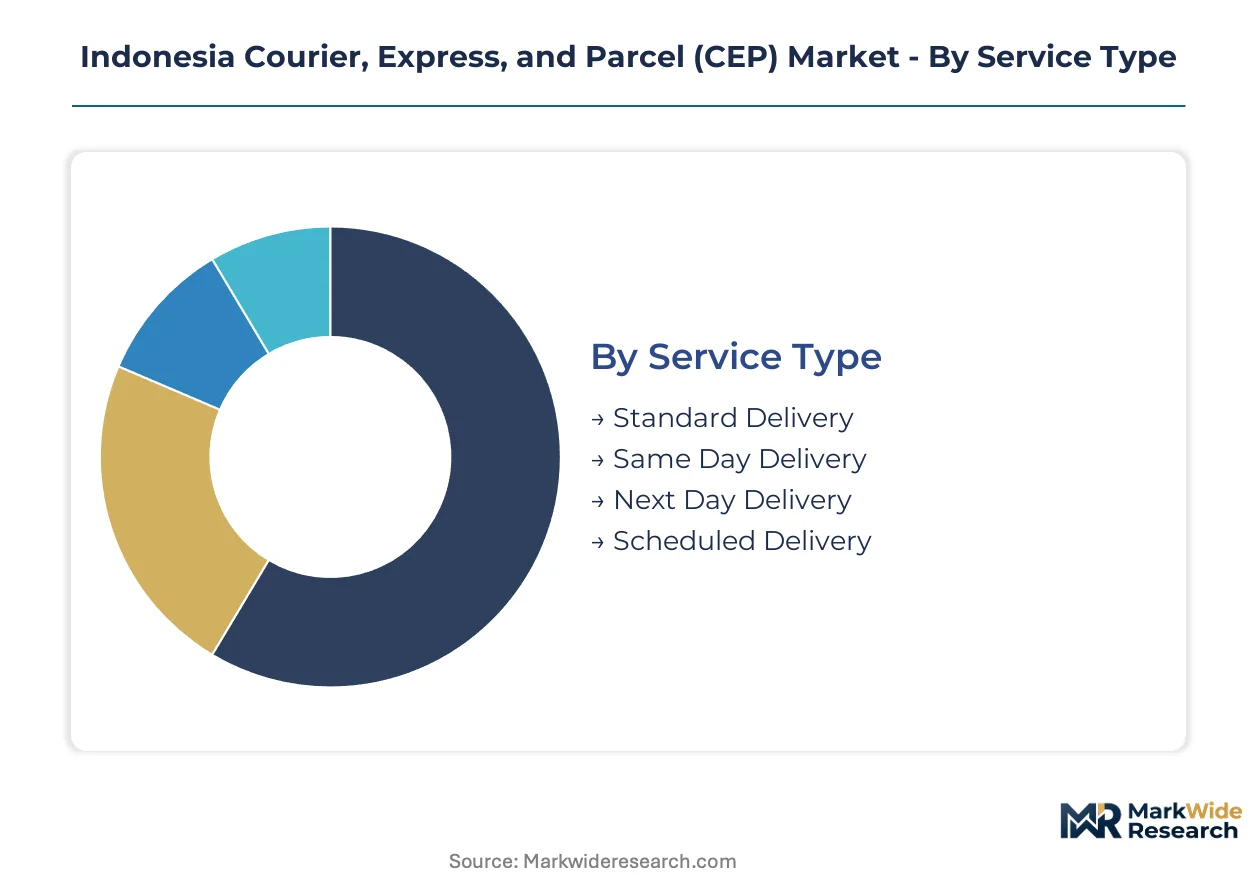
Segmentation in Indonesia's CEP market reveals how service tiers, infrastructure modes, and customer concentration create distinct competitive battlegrounds. Each dimension exposes where capital deploys for margin defense versus volume capture across the archipelago's fragmented geography.
Service Type:
Volume concentrates in deferred delivery tiers while premium services capture disproportionate margin expansion in Greater Jakarta's dense urban corridors.
- Standard Delivery:Non-time-definite ground transportation serving intercity routes across Java, Sumatra, and Sulawesi with 2-5 day transit windows. Demand clusters with marketplace sellers optimizing for cost over speed, particularly in tier-2 cities where fiber-optic backbone expansion enables tracking parity with premium tiers.
- Same Day Delivery:Sub-6-hour fulfillment utilizing motorcycle courier density and micro-fulfillment nodes in Jakarta, Surabaya, and Bandung. Urban consumers in satellite cities now expect this service tier as default, pulling investment from J&T Express and SiCepat Ekspres into hyperlocal warehouse networks.
- Next Day Delivery:Time-definite service bridging standard and same-day tiers through prioritized sortation at automated Java hubs.
- Scheduled Delivery:Appointment-based delivery windows targeting furniture, appliances, and bulk freight requiring recipient presence.
Today's leader: Standard Delivery. Tomorrow's challenger: Same Day Delivery.
Delivery Mode:
Cost efficiency versus speed trade-offs reconfigure modal choice across Indonesia's island geography, with ground dominance yielding to multimodal integration for outer island penetration.
- Ground:Diesel and gasoline-powered truck and motorcycle fleets constituting the backbone for intra-island movement. Java's highway network supports this mode's cost advantage, though fuel price volatility directly compresses margins for operators serving Jakarta-Surabaya-Bandung corridors.
- Air:Narrow-body cargo and belly-hold freight for inter-island express connecting Java to Papua, Maluku, and Nusa Tenggara Timur. Premium document and pharmaceutical shipments concentrate here, with limited cargo capacity at secondary airports constraining network expansion.
- Sea:Roll-on/roll-off ferry integration for palletized freight between Java, Sumatra, and Kalimantan.
- Intermodal:Synchronized ground-sea-air transfers reducing transit times on uneconomical direct routes.
Ground transportation retains volume dominance. Intermodal solutions are gaining share fastest on outer island routes.
Customer Type:
Procurement power concentrates with platform-integrated buyers while fragmented sellers accept standardized rate cards with performance penalties.
- E-commerce Platforms:Consolidated volume aggregators dictating service-level agreements, real-time API integration requirements, and exclusive fulfillment contracts. Tokopedia, Shopee, and TikTok Shop's logistics arms compete directly with independent CEP providers for this segment in Greater Jakarta.
- Corporates:Manufacturing and retail enterprises with contracted logistics arrangements spanning B2B document exchange and spare parts distribution. Banking and insurance sectors drive consistent demand for secure document handling with chain-of-custody verification.
- Small Businesses:Marketplace sellers and social commerce operators with variable volume and price sensitivity.
- Individual Consumers:Occasional shippers utilizing retail counter services and cash-on-delivery options.
E-commerce Platforms command procurement leverage today. Small Businesses represent the expansion frontier for specialized service tiers.
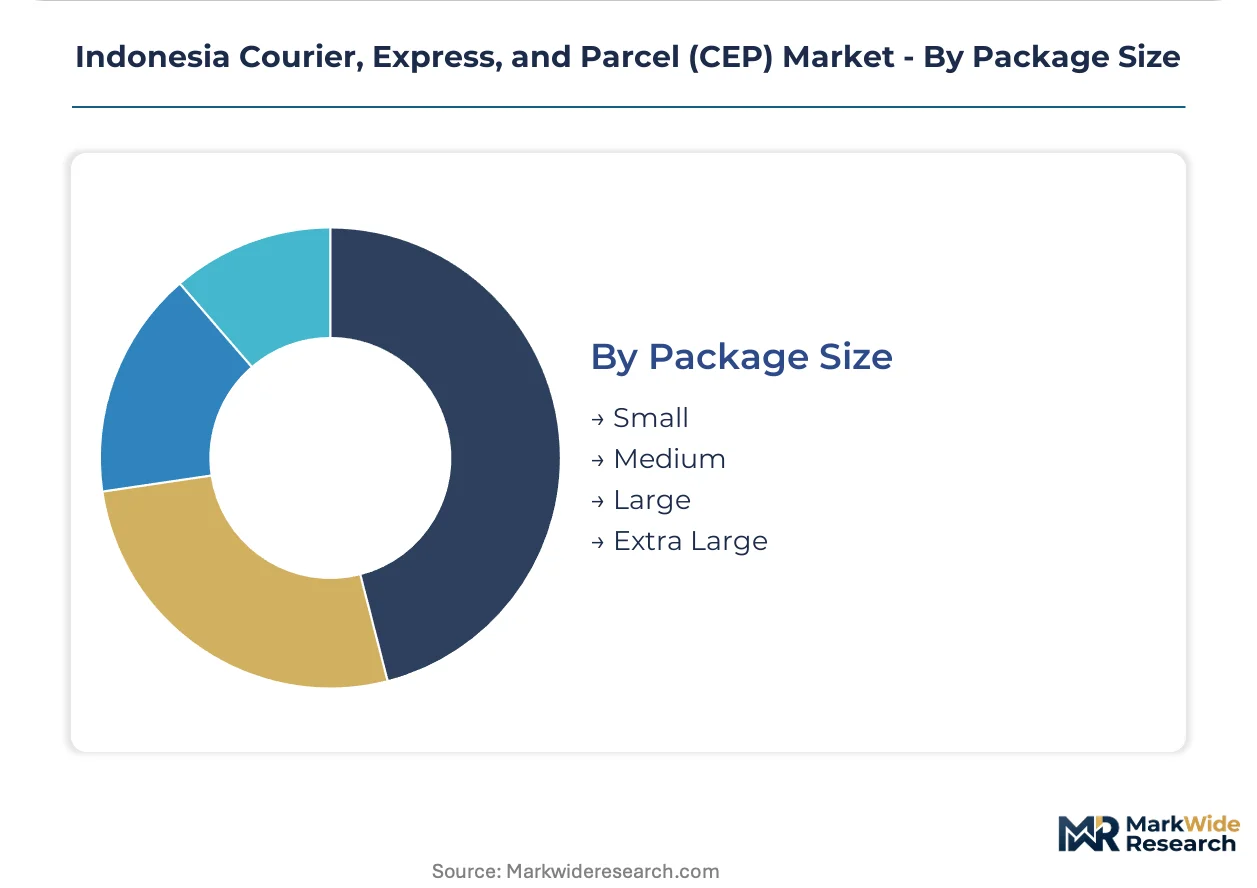
Package Size:
Dimensional weight pricing and sortation automation compatibility shape profitability across parcel categories, with mid-size formats optimizing for automated hub throughput.
- Small:Documents, electronics accessories, and apparel under 2kg dimensional weight. Automated sortation systems at J&T Express and SiCepat Ekspres mega-hubs process these at 10,000+ units hourly with minimal mis-sort rates, driving unit economics at volume.
- Medium:Consumer electronics, home goods, and multi-item orders between 2-10kg. Fashion and beauty e-commerce concentrates demand here, with packaging BIS certification requirements influencing operational standards for cross-border shipments.
- Large:Furniture components, appliances, and bulk retail inventory requiring manual handling.
- Extra Large:Industrial equipment and palletized freight outside standard parcel network specifications.
Small parcels dominate automated throughput. Medium parcels are climbing fastest as basket sizes expand in tier-2 city online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Motorcycle courier density in Greater Jakarta anchors Indonesia's parcel workforce concentration, with satellite city networks expanding outward as fulfillment expectations compress.
Java
Jakarta, Surabaya, and Bandung generate over 70 percent of national parcel volumes, driven by e-commerce platform consolidation and same-day delivery mandates. Indonesia's Ministry of Communications and Informatics fiber-optic backbone expansion enables real-time tracking parity across tier-2 cities. The Jakarta-Bandung corridor hosts automated mega-hubs processing 10,000-plus parcels hourly.
Sumatra
Medan and Palembang concentrate demand for cross-island freight integration with Java, with roll-on/roll-off sea freight reducing transit times. The Ministry of Transportation's commercial vehicle licensing requirements mandate GPS tracking for ground fleets serving Sumatra's highway network. Batam's free trade zone generates cross-border express demand with Singapore connectivity.
Sulawesi
Makassar and Manado anchor parcel flows for eastern Indonesia distribution, with intermodal ground-air transfers compensating for limited direct cargo capacity. BIS certification requirements for packaging materials influence operational standards for pharmaceutical shipments originating here. The Makassar industrial zone supports manufacturing logistics requiring time-definite delivery.
Kalimantan
Balikpapan and Samarinda serve mining and energy sector logistics with heavy freight specialization outside standard parcel networks. The Ministry of Transportation's emissions reporting requirements for commercial freight fleets will reshape cost structures for diesel-dependent ground operators. East Kalimantan's new capital zone Nusantara drives infrastructure logistics demand.
Eastern Indonesia
Papua, Maluku, and Nusa Tenggara Timur remain underserved by integrated parcel networks, presenting first-mover infrastructure investment opportunities. Incomplete customs digitization at major ports generates clearance delays constraining premium service reliability. Jayapura and Ambon function as hub-and-spoke nodes for archipelago connectivity.
Indonesia Courier, Express, and Parcel (CEP) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Indonesia's CEP landscape, creating a tiered structure where scale advantages separate national operators from regional carriers. The market fragments between platform-owned logistics arms and independent providers, with procurement power concentrating among e-commerce volume aggregators. Three archetypes dominate: automated hub operators with proprietary sortation technology, rural branch network incumbents with intercity coverage depth, and hyperlocal same-day specialists with micro-fulfillment density. Competitive moves center on exclusive fulfillment contract capture and automated sortation capacity expansion.
Among Indonesia-based express operators, J&T Express, JNE Express, and SiCepat Ekspres exemplify the three dominant strategic archetypes. J&T Express occupies a position representing automated cross-island parcel flow specialists with proprietary sortation systems. JNE Express anchors the rural network depth archetype, sustaining intercity standard delivery coverage across outer island routes. SiCepat Ekspres sits within the hyperlocal same-day tier, with aggressive coverage concentration in Greater Jakarta and satellite cities.
| Leading Market Players |
|---|
| J&T Express |
| JNE Express |
| SiCepat Ekspres |
| Ninja Xpress |
| Pos Indonesia |
| TIKI |
| Pahala Express |
| Anteraja |
| JET Express |
| Others |
Pricing and Supply Chain Analysis
Same-day versus standard delivery bifurcation in Indonesia's CEP market manifests in divergent pricing floors and supply chain architectures, with premium urban corridors commanding motorcycle-courier density while inter-island standard tiers optimize for roll-on/roll-off sea freight integration. This divergence compresses margins in Java's saturated corridors while inflating capital requirements for automated sortation hubs that service platform-exclusive contracts.
Pricing Analysis
Capacity additions in Greater Jakarta are reshaping price floors for same-day delivery tiers as J&T Express and SiCepat Ekspres deploy micro-fulfillment nodes. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery velocity and API integration depth. Cost compression in standard delivery intensifies because e-commerce platforms aggregate procurement power through volume-based rate cards. Small businesses exhibit highest price sensitivity, while e-commerce platforms leverage exclusivity clauses to extract performance guarantees at fixed rates.
Supply Chain Analysis
Regional distribution centers in Jakarta, Surabaya, and Bandung anchor hub-and-spoke patterns that concentrate automated sortation capacity on Java. Manufacturing of conveyor systems and machine vision components draws from China, South Korea, and Japan. Diesel fuel sourcing rests on Pertamina's subsidized pricing regime, creating single-source vulnerability for ground fleet operators. Distribution runs through platform-owned logistics arms and independent CEP providers competing for exclusive fulfillment contracts in Greater Jakarta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's CEP market compounds steadily as archipelagic e-commerce penetration deepens and Ministry of Communications and Informatics mandates force digitization investment across tier-2 and tier-3 cities.
For Market Incumbents: Acquire automated sortation technology to defend against platform-owned logistics arms capturing exclusive fulfillment contracts. Consolidate subcontractor relationships into in-house fleet operations ahead of Ministry of Transportation GPS tracking mandates. Prioritize cold chain certification investment for pharmaceutical express corridors.
For New Entrants and Emerging Players: Launch via intermodal ground-air transfers targeting Papua, Maluku, and Nusa Tenggara Timur where integrated parcel networks remain sparse. Penetrate scheduled delivery for furniture and appliances requiring recipient presence. Pursue white-label logistics partnerships with social commerce operators lacking API integration capabilities.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier providers struggle to API-connect with major e-commerce platforms and face inventory visibility gaps. Long-term viability favors operators with captive automated hub capacity and exclusive platform contracts. Monitor Ministry of Transportation emissions reporting rulemaking as signal for electric two-wheeler adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sortation Deployment | J&T Express and SiCepat Ekspres mega-hubs process 10,000-plus parcels hourly with sub-1% mis-sort rates. |
| Micro-Fulfillment Network Expansion | Hyperlocal warehouse density in Greater Jakarta satellite cities enables sub-6-hour fulfillment windows. |
| Intermodal Ground-Air Integration | Synchronized transfers reduce transit times to Papua and Maluku where direct cargo capacity remains limited. |
| Platform API Integration | Real-time order-to-fulfillment connectivity determines eligibility for exclusive e-commerce logistics contracts. |
| Electric Two-Wheeler Pilot Programs | Anticipated Ministry of Transportation emissions reporting favors early fleet electrification adopters. |
Research Methodology
Direct dialogue with logistics operations directors, e-commerce platform supply chain managers, motorcycle courier fleet supervisors, and Ministry of Transportation regulatory officers grounded qualitative findings. Secondary validation drew from customs trade databases, Ministry of Communications and Informatics infrastructure disclosures, BIS certification registries, and SEC filings of listed logistics conglomerates. Bottom-up parcel volume modeling triangulated against top-down e-commerce GMV projections.
Segmentation outputs across service type, delivery mode, customer archetype, and package size dimensioned market sizing across the projection horizon. CAGRs derived from historical volume trajectories and elasticity-adjusted e-commerce penetration curves. Forecast inputs incorporated fiber-optic backbone expansion timelines and roll-on/roll-off sea freight capacity additions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fuel subsidy regime changes and customs digitization delays. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
LAMEA Last Mile Delivery Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Rail Logistics Market
Logistics and Shipping
Cold Chain Logistics Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market