
 Cold Chain Vehicles Market | 2026-2036
Cold Chain Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Chain Vehicles Market Insights
Buyer concentration in pharmaceutical logistics is decoupling from traditional food-service fleet procurement as biologics distributors build dedicated cold-chain capacity. Thermo King leverages its transport refrigeration installed base to sustain aftermarket service revenue across North American pharmaceutical lanes. Carrier Transicold anchors European regulatory compliance through advanced electric standby systems. Daikin Industries competes in Asian markets with compact refrigeration units engineered for dense urban delivery routes.
Cold chain vehicles are purpose-built transport assets engineered to maintain temperatures between minus 25 degrees Celsius and plus 25 degrees Celsius through insulated cargo compartments integrated with mechanical or cryogenic cooling systems, serving industries where thermal excursion destroys product integrity. Refrigerated trucks and vans lead unit volume as food retailers and pharmaceutical distributors replace aging diesel fleets, while electric fuel-type variants are gaining fastest though from a smaller base as battery thermal management improves. Active temperature control methods command premium pricing against passive systems, particularly for cell-and-gene therapies requiring continuous real-time monitoring.
The US EPA and California Air Resources Board mandate phase-down of high-global-warming-potential refrigerants in transport refrigeration, compelling manufacturers to redesign cooling architectures. The EU F-Gas Regulation and impending Euro VII standards tighten parallel requirements across European member states, reshaping product development roadmaps for Kögel Trailer and Schmitz Cargobull. Stakeholders must decide whether to prioritize electric platform development for zero-emission zones or extend diesel-electric hybrid architectures that bridge current infrastructure gaps.
Market Dynamics
Transport refrigeration electrification is compressing total cost of ownership calculations as battery thermal management advances meet zero-emission zone mandates across dense urban logistics corridors.
Growth Catalysts
- Biologics Distribution Networks:Cell-and-gene therapy cold chains require minus 80 to minus 150 degrees Celsius transport, expanding dedicated fleet procurement beyond traditional food-service channels.
- California Air Resources Board TRU At-Berth Regulation:Mandatory electric standby connections for transport refrigeration units at California ports and distribution centers accelerate shore-power infrastructure deployment.
- Last-Mile Vaccine Programs:National immunization drives in India and Indonesia concentrate refrigerated van demand for rural health post connectivity.
Market Restraints
- Lithium-Ion Battery Cost Volatility:Cathode material price swings compress electric refrigerated vehicle margins, particularly for compact last-mile van platforms where battery share of bill-of-materials exceeds 35 percent.
- Compressor Supply Concentration:European and Japanese compressor manufacturers control 70 percent of transport refrigeration cooling system supply, creating single-source vulnerability for North American vehicle integrators.
- Refrigerant Transition Friction:The US EPA Significant New Alternatives Policy creates compliance timeline uncertainty as hydrofluoroolefin availability lags phase-down schedules for high-global-warming-potential refrigerants.
Strategic Opportunities
- Indonesia Archipelago Cold Chain:Underdeveloped inter-island temperature-controlled logistics creates first-mover advantage for reefers with hybrid diesel-electric architectures bridging port electrification gaps.
- Real-Time Temperature Telemetry:Integration of IoT sensors with blockchain verification protocols enables outcome-based cargo insurance products, unbundling risk from traditional freight contracts.
- EU Green Deal Fleet Renewal Subsidies:Member-state co-financing programs for zero-emission commercial vehicles reduce electric refrigerated truck acquisition premiums in Germany, France, and the Netherlands.
Industry Challenges
- Refrigeration Technician Shortage:Transport cooling system maintenance requires combined mechanical-electrical skill sets that vocational training programs have not scaled to match fleet electrification timelines.
- Multi-Temperature Zone Integration:Pharmaceutical distributors demand simultaneous minus 25, plus 2 to plus 8, and plus 15 to plus 25 degrees Celsius compartments within single vehicles, complicating insulation engineering and load optimization algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Chain Vehicles Market |
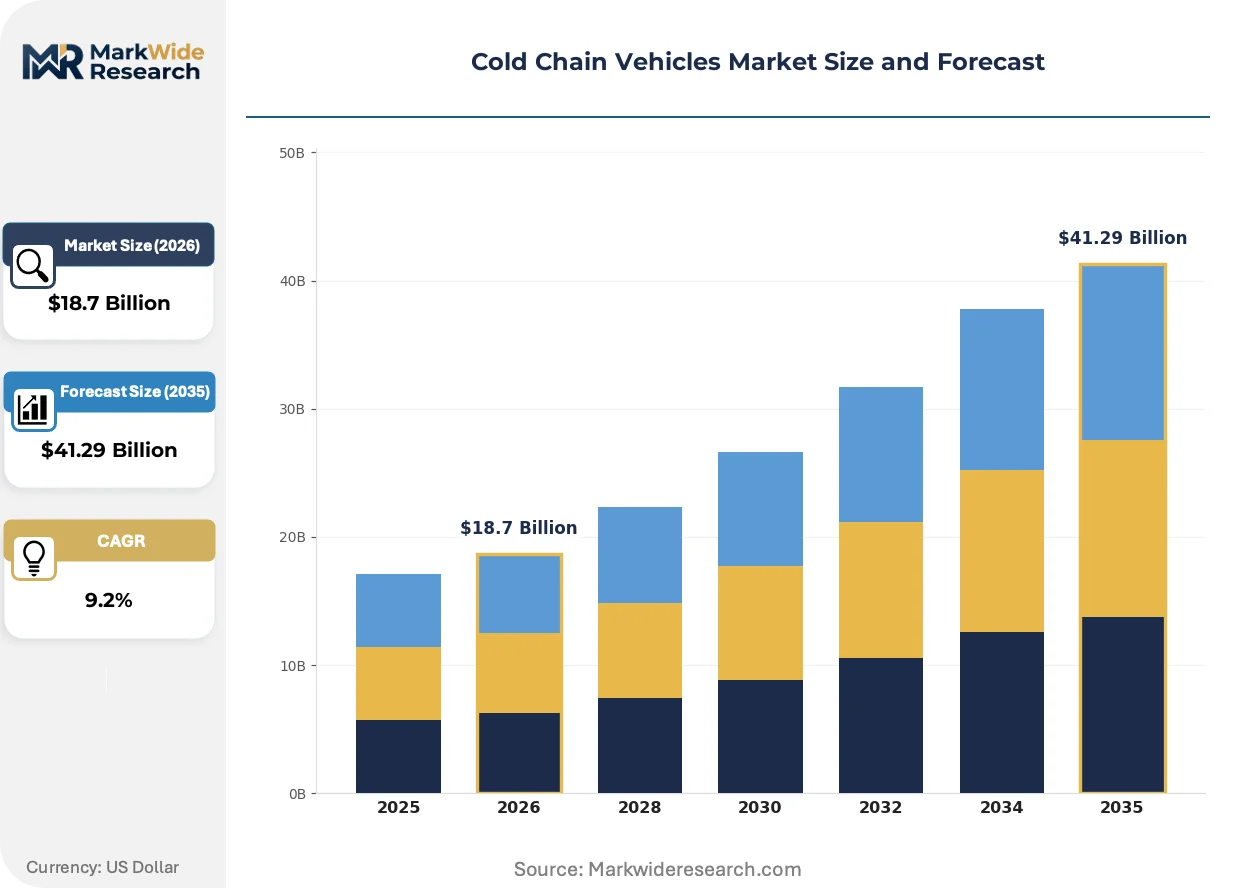
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.29 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Refrigerated Trucks, Vans, Trailers, Containers Temperature Control Method: Active, Passive, Refrigeration, Freezing Fuel Type: Diesel, Natural Gas, Electric, Hybrid End User: Pharmaceuticals, Food & Beverages, Chemicals, Others |
| Companies Covered | Thermo King, Carrier Transicold, Daikin Industries, Schmitz Cargobull, Webasto Group, Denso Corporation, Wabash National, Kögel Trailer, Great Dane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Chain Vehicles Market Trends and Innovations
Digital freight platforms are compressing cold chain asset utilization rates as real-time demand matching replaces static route planning in temperature-sensitive logistics networks.
Solid-state battery chemistries are converging with transport refrigeration applications as energy density improvements enable extended range for electric reefers without payload compromise. Pharmaceutical distributors in Germany and the Netherlands are piloting these systems for inter-city biologics lanes. The structural consequence is converging with fleet electrification roadmaps previously constrained by diesel range anxiety.
The EU F-Gas Regulation mandates 90 percent reduction in hydrofluorocarbon consumption by 2030, forcing cooling system redesigns across European trailer manufacturers. Transport refrigeration unit producers must accelerate hydrofluoroolefin and natural refrigerant transitions while maintaining performance in ambient temperatures exceeding 40 degrees Celsius. Southern European freight operators face compressed retrofit timelines as Euro VII standards parallel these refrigerant mandates.
Consolidation among third-party logistics providers is concentrating refrigerated fleet purchasing power, shifting negotiation leverage from vehicle OEMs toward contract terms covering total cost per pallet-kilometer. Food retailers in the United Kingdom and France now bundle vehicle procurement with temperature monitoring service subscriptions. This pattern is most visible in grocery e-commerce fulfillment networks where same-day delivery promises require dynamic fleet scaling.
Cold Chain Vehicles Market Segmentation
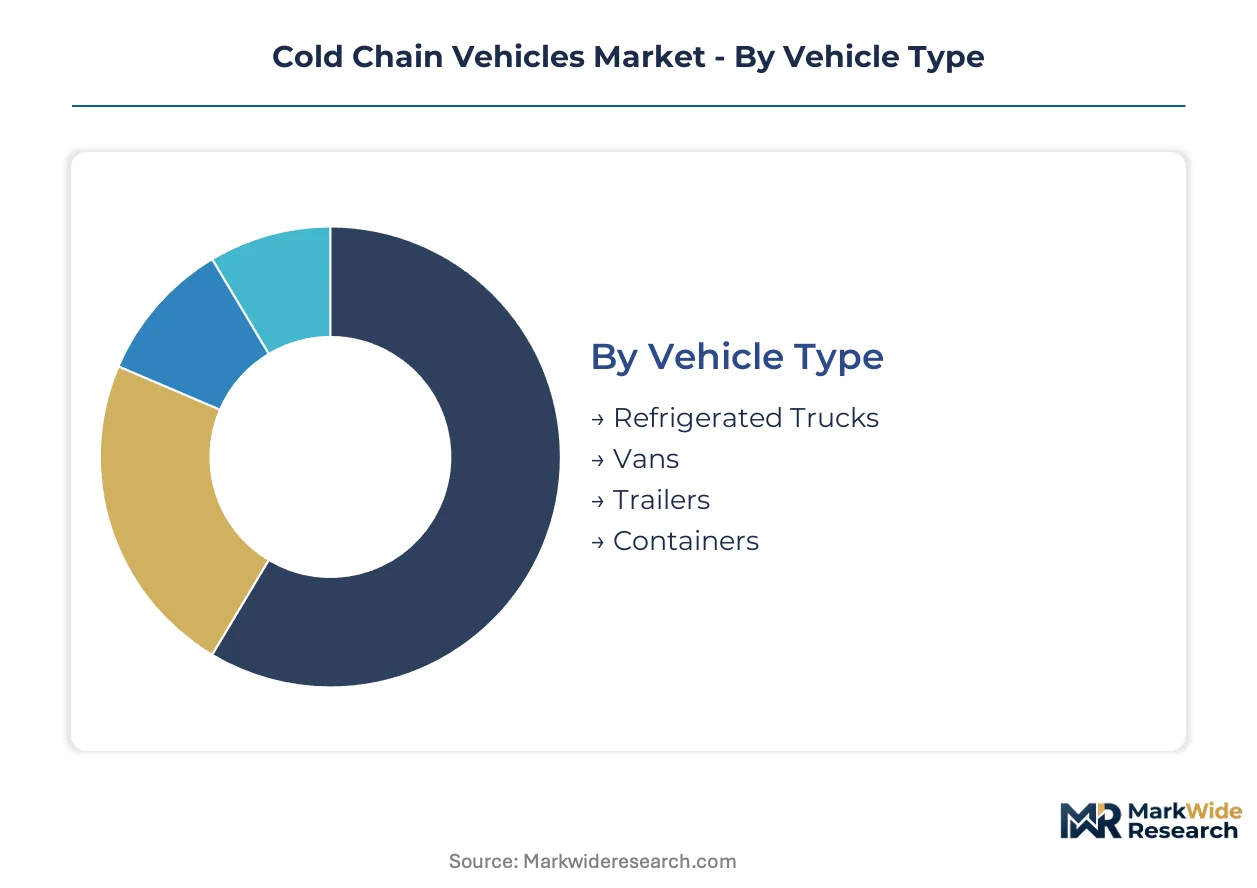
Cold chain vehicle procurement patterns diverge sharply across temperature requirements, payload scales, and regulatory exposure. Fleet operators segment investments by total cost of ownership horizons and compliance jurisdiction rather than upfront sticker price alone.
Vehicle Type:
Capital deployment intensity peaks with multi-temperature trailers requiring advanced insulation engineering, while compact vans demand lower initial outlay but higher per-unit operating expenditure across dense urban routes.
- Refrigerated Trucks:Medium-duty chassis with integrated transport refrigeration units serve inter-city pharmaceutical distribution and regional food wholesale networks. German chemical distributors and US Midwest meat processors concentrate procurement here, driven by Euro VII pre-buy activity and EPA refrigerant phase-down timelines.
- Vans:Compact last-mile platforms with roof-mounted or chassis-integrated cooling systems dominate vaccine delivery programs in India and Indonesia. Battery thermal management constraints and California Air Resources Board zero-emission zone mandates are compressing diesel retention horizons.
- Trailers:Semi-trailer reefers with independent power units anchor long-haul biologics corridors across the European Union.
- Containers:Intermodal temperature-controlled boxes bridge maritime and rail segments for export-oriented agricultural producers.
Refrigerated trucks absorb the bulk of installed capacity; vans are expanding most quickly.
Temperature Control Method:
Operating cost structures separate segments by energy input requirements and monitoring sophistication, with premium-tier systems commanding three to five-year payback periods through cargo loss prevention.
- Active:Continuous mechanical or cryogenic cooling with real-time telemetry integration maintains precise setpoints for cell-and-gene therapies requiring minus 80 degrees Celsius transport. Pharmaceutical 3PLs in the Netherlands and Massachusetts concentrate demand, compelled by FDA validation requirements and EMA Good Distribution Practice audits.
- Passive:Insulated containers with phase-change materials or dry ice suit short-duration vaccine campaigns and emergency humanitarian logistics.
- Refrigeration:Vapor-compression cycles using hydrofluoroolefin or natural refrigerants serve plus 2 to plus 8 degrees Celsius pharmaceutical standards.
- Freezing:Sub-minus 18 degrees Celsius systems protect frozen food and certain chemical intermediates.
Active systems dominate pharmaceutical lane revenue; passive configurations gain share fastest in emerging market immunization programs.
Fuel Type:
Infrastructure availability and subsidy eligibility determine capital allocation, with electric platforms requiring depot grid upgrades that hybrid architectures circumvent.
- Diesel:Compression-ignition engines with transport refrigeration unit power take-offs retain installed base dominance across long-haul corridors lacking charging infrastructure.
- Natural Gas:Compressed or liquefied methane suits regional distribution networks with established refueling stations in California and British Columbia.
- Electric:Battery-electric chassis with dedicated refrigeration compressors are penetrating last-mile grocery fulfillment in London, Paris, and Amsterdam. EU Green Deal fleet renewal subsidies and Netherlands zero-emission zone mandates are accelerating procurement, despite lithium-ion cathode material cost volatility compressing OEM margins.
- Hybrid:Diesel-electric architectures bridge port electrification gaps and archipelago logistics in Indonesia.
Diesel retains the largest operational footprint; electric platforms are climbing the fastest.
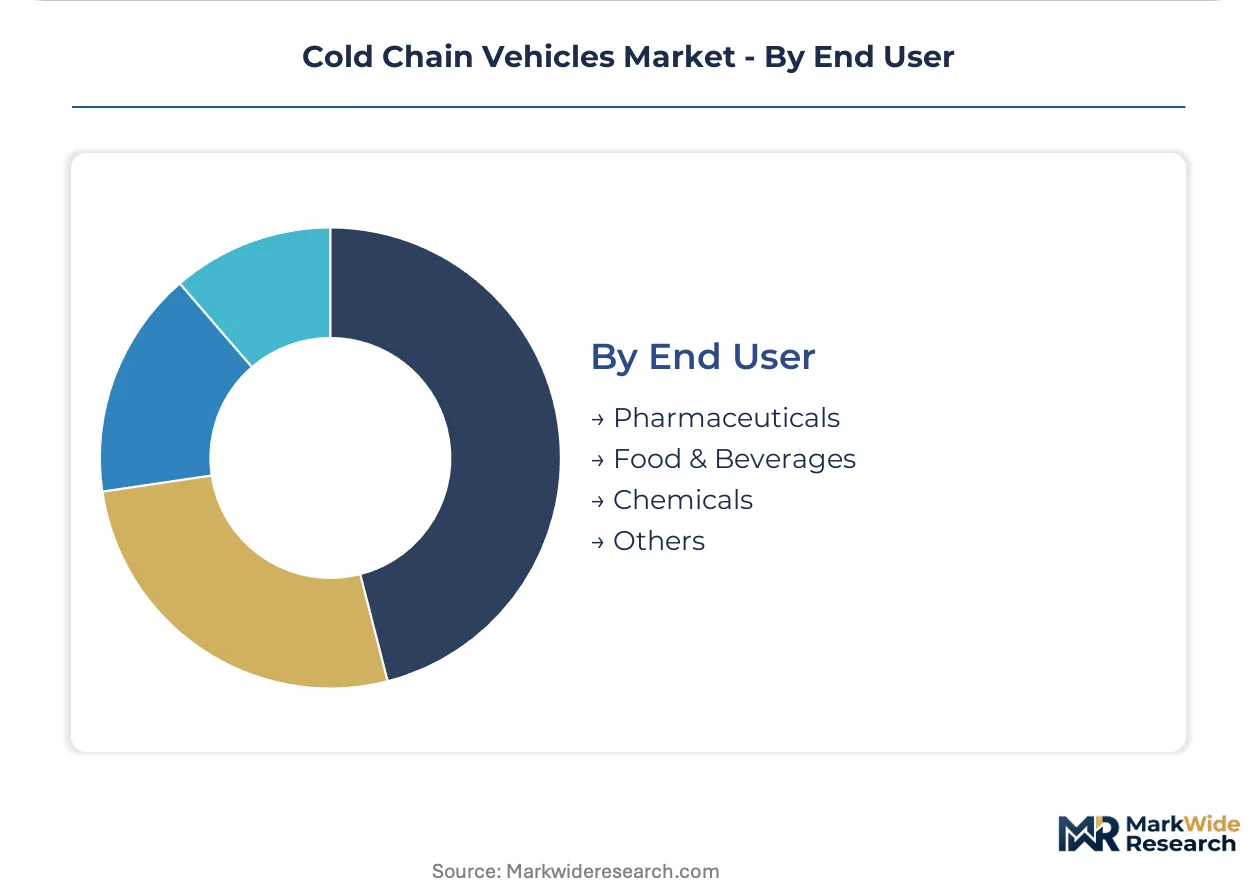
End User:
Compliance stringency and cargo value density create divergent specification requirements, with pharmaceutical fleets demanding validation documentation that food-service operators rarely require.
- Pharmaceuticals:GDP-compliant vehicles with calibrated temperature mapping and alarm systems serve biologics distributors. Cell-and-gene therapy cold chains in Germany, Switzerland, and Singapore drive minus 150 degrees Celsius cryogenic transport investments, compelled by FDA and EMA serialization mandates.
- Food & Beverages:Multi-temperature compartments accommodate frozen, chilled, and ambient zones for grocery retailers.
- Chemicals:Explosion-proof refrigeration and hazardous materials placarding protect temperature-sensitive industrial intermediates.
- Others:Floral, aerospace, and specialty electronics applications occupy niche specification tiers.
Food and beverage applications deploy the widest fleet volume; pharmaceuticals command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical logistics concentration in Germany, the United States, and China is decoupling fleet procurement from traditional food-service channels as biologics distributors build dedicated cold-chain capacity. National immunization programs in India and Indonesia are compressing last-mile van deployment timelines. Regulatory fragmentation across EPA, EU F-Gas, and CARB mandates is forcing manufacturers to maintain parallel compliance roadmaps.
United States
Cell-and-gene therapy distribution networks in Massachusetts and North Carolina are driving minus 80 degrees Celsius transport investments. The EPA Significant New Alternatives Policy and CARB TRU At-Berth Regulation are accelerating shore-power infrastructure at California ports and distribution centers. Midwest meat processors and pharmaceutical 3PLs in the Boston-Cambridge corridor concentrate medium-duty refrigerated truck procurement ahead of refrigerant phase-down deadlines.
Germany
Chemical distributors and biologics 3PLs in the Rhine-Ruhr and Bavaria regions anchor European demand for multi-temperature trailers. The EU F-Gas Regulation and impending Euro VII standards are compelling cooling system redesigns across trailer manufacturers. Eindhoven-anchored logistics networks and Rotterdam port electrification are compressing hybrid-to-electric transition timelines for pharmaceutical lanes serving Swiss and Dutch distribution hubs.
China
Fresh-food e-commerce fulfillment in the Yangtze River Delta and Pearl River Delta is concentrating compact refrigerated van procurement for dense urban delivery routes. The Ministry of Ecology and Environment dual carbon goals and GB standards for transport refrigeration are tightening emissions requirements. Shanghai and Shenzhen zero-emission zone pilots are accelerating battery-electric chassis adoption despite thermal management constraints.
India
National immunization drives and rural health post connectivity programs are expanding refrigerated van fleets across Maharashtra, Gujarat, and Karnataka. The Food Safety and Standards Authority of India cold chain guidelines and PLI scheme incentives for electric commercial vehicles are reshaping procurement criteria. Mumbai-Pune and Delhi-NCR logistics corridors concentrate last-mile vaccine distribution infrastructure.
Indonesia
Underdeveloped inter-island temperature-controlled logistics across the Java Sea and Sulawesi routes is creating demand for hybrid diesel-electric architectures. The national pharmaceutical regulator's distribution integrity requirements and archipelago port infrastructure gaps are bridging electrification timelines. Surabaya and Makassar maritime hubs concentrate reefers serving pharmaceutical import corridors from Singapore and Malaysia.
Cold Chain Vehicles Market Competitive Landscape
North American and European producers anchor the premium transport refrigeration tier; Asian specialists hold volume positions in compact urban delivery systems. The vendor base concentrates around integrated transport refrigeration unit manufacturers and trailer fabricators with captive cooling partnerships. Three archetypes dominate: legacy refrigeration incumbents with installed-base service networks, trailer OEMs with outsourced cooling integration, and electric chassis specialists with native thermal management. Consolidation is accelerating through refrigeration-trailer bundling contracts and cross-border technology licensing for zero-emission zone compliance.
Within the legacy incumbent tier, Thermo King and Carrier Transicold exemplify service-network-dependent competitive positioning, while Daikin Industries occupies a compact-system specialization node. These three anchors represent divergent geographic emphases—North American pharmaceutical lanes, European regulatory compliance, and Asian urban density—without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Thermo King |
| Carrier Transicold |
| Daikin Industries |
| Schmitz Cargobull |
| Webasto Group |
| Denso Corporation |
| Wabash National |
| Kögel Trailer |
| Great Dane |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical 3PL procurement concentration in Germany, the United States, and Switzerland anchors contract-based long-term offtake pricing with embedded service subscriptions, compressing transactional spot markets for standalone vehicle sales. Food retailers in France and the United Kingdom bundle temperature monitoring telemetry with fleet acquisitions, shifting negotiation leverage toward total cost per pallet-kilometer rather than upfront chassis sticker price.
Pricing Analysis
High-volume food-service fleet operators capture standard-tier pricing through multi-year procurement contracts, while pharmaceutical distributors absorb premium-tier positioning for GDP-validated vehicles with real-time telemetry integration. Price differentiation hinges on EMA Good Distribution Practice certification grade and after-sales service bundling. Cost compression in compact electric van platforms is intensifying because lithium-ion cathode material volatility exceeds 35 percent of bill-of-materials. Food retailers exhibit highest price sensitivity; cell-and-gene therapy 3PLs demonstrate lowest sensitivity due to cargo loss prevention value.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns for transport refrigeration unit assembly and trailer integration. Compressor manufacturing draws from Japan, Germany, and South Korea, while battery cell production rests on Chinese and South Korean supply. Single-source vulnerability in European and Japanese compressor suppliers creates structural risk for North American vehicle integrators. Distribution runs through captive OEM service networks and third-party cold chain logistics providers with bundled maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-electric chassis with integrated thermal management are displacing diesel-electric hybrid architectures in last-mile pharmaceutical lanes, compressing payback horizons as EU Green Deal subsidies and zero-emission zone mandates accelerate fleet renewal timelines.
For Market Incumbents: Hedge refrigerant transition exposure by accelerating hydrofluoroolefin and natural refrigerant cooling system redesigns ahead of EPA Significant New Alternatives Policy deadlines. Secure captive supply of compressor assemblies through backward integration into European supplier networks or long-term offtake agreements. Defend installed-base service revenue by embedding IoT telemetry subscriptions that lock pharmaceutical 3PLs into aftermarket ecosystems. For New Entrants and Emerging Players: Regional trucking cooperatives in Indonesia and India represent the most penetrable channel partner type for hybrid diesel-electric reefers bridging archipelago port electrification gaps. Target underdeveloped inter-island temperature-controlled logistics with lease-to-own financing structures that circumvent upfront capital constraints. White-space exists in cryogenic transport for cell-and-gene therapy corridors between Singapore and Australian clinical trial sites. For Investors and Strategic Acquirers: The window for entry favors electric chassis specialists with native battery thermal management capabilities and existing pharmaceutical validation documentation. Mid-term viability hinges on subsidy dependency transitioning to standalone total cost of ownership parity across dense urban logistics corridors. Watch California Air Resources Board zero-emission zone expansion timelines as the inflection signal for electric refrigerated van demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform Development | Battery-electric chassis with dedicated refrigeration compressors meet CARB zero-emission zone mandates in California ports. |
| Refrigerant Transition Investment | Hydrofluoroolefin and natural refrigerant cooling architectures comply with EPA phase-down schedules and EU F-Gas Regulation. |
| Aftermarket Service Expansion | IoT-enabled predictive maintenance contracts lock pharmaceutical 3PLs into recurring revenue streams across North American lanes. |
| Multi-Temperature Engineering | Simultaneous minus 25, plus 2 to plus 8, and plus 15 to plus 25 degrees Celsius compartments address pharmaceutical distributor complexity. |
| Geographic Manufacturing Footprint | Regional assembly in Germany, China, and the United States reduces logistics costs and tariff exposure for trailer refrigeration units. |
Research Methodology
Document review covered SEC 10-K filings, EU F-Gas regulatory impact assessments, and EPA refrigerant phase-down schedules, complemented by interviews with fleet procurement directors at pharmaceutical 3PLs, transport refrigeration OEM product managers, and cold chain logistics operators. Primary fieldwork included discussions with aftermarket service heads and regulatory compliance officers at trailer manufacturers. Secondary validation drew from customs trade data, vehicle registration databases, and national immunization program procurement disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Unit volume and value projections across the analysis window employed a segmented analytical framework incorporating vehicle type, temperature control method, fuel type, and end-use industry dimensions. CAGRs were derived from logistic curve fitting to technology adoption patterns and regulatory compliance deadline clustering. Forecast inputs included battery energy density improvement trajectories, zero-emission zone mandate rollout schedules, and pharmaceutical cold chain validation requirement evolution.
Caveats apply where lithium-ion cathode material price volatility, compressor supply concentration, or refrigerant availability delays could materially shift the outlook for electric platform penetration. Forecasts reflect assumptions regarding subsidy continuity and infrastructure deployment timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Transportation Aggregators Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
Europe Fleet Management Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
Europe Road Feeder Services Market