
 Transportation and Security System Market | 2026-2036
Transportation and Security System Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation and Security System Market Intelligence
The market's structure is shifting as integrated, software-defined solutions diverge from standalone hardware components. Thales Group specializes in complex, large-scale deployments for rail and aviation clients, requiring deep systems integration capabilities. Honeywell International leverages its extensive portfolio in building controls and fire alarm systems to offer bundled security packages. In contrast, Rapiscan Systems dominates the niche of cargo and vehicle inspection technologies, focusing on high-performance screening equipment.
Transportation and security systems are an integrated suite of technologies designed to safeguard infrastructure and manage operational flow, often featuring video surveillance linked with access control on a unified software platform. Their primary purpose is to deter, detect, and respond to security threats in real-time. While video surveillance constitutes a foundational layer, growth is now centered in AI analytics and biometrics. Demand from airport and port applications continues to lead investment due to strict security requirements.
Regulatory mandates fundamentally shape technology adoption and system requirements. In the United States, the Transportation Security Administration (TSA) sets stringent standards for passenger and baggage screening technologies. Similarly, European Union directives govern security protocols for critical port and rail infrastructure, influencing access control and surveillance specifications. System vendors must therefore navigate a complex web of certifications to ensure market access and compliance with evolving threat assessments.
Market Dynamics
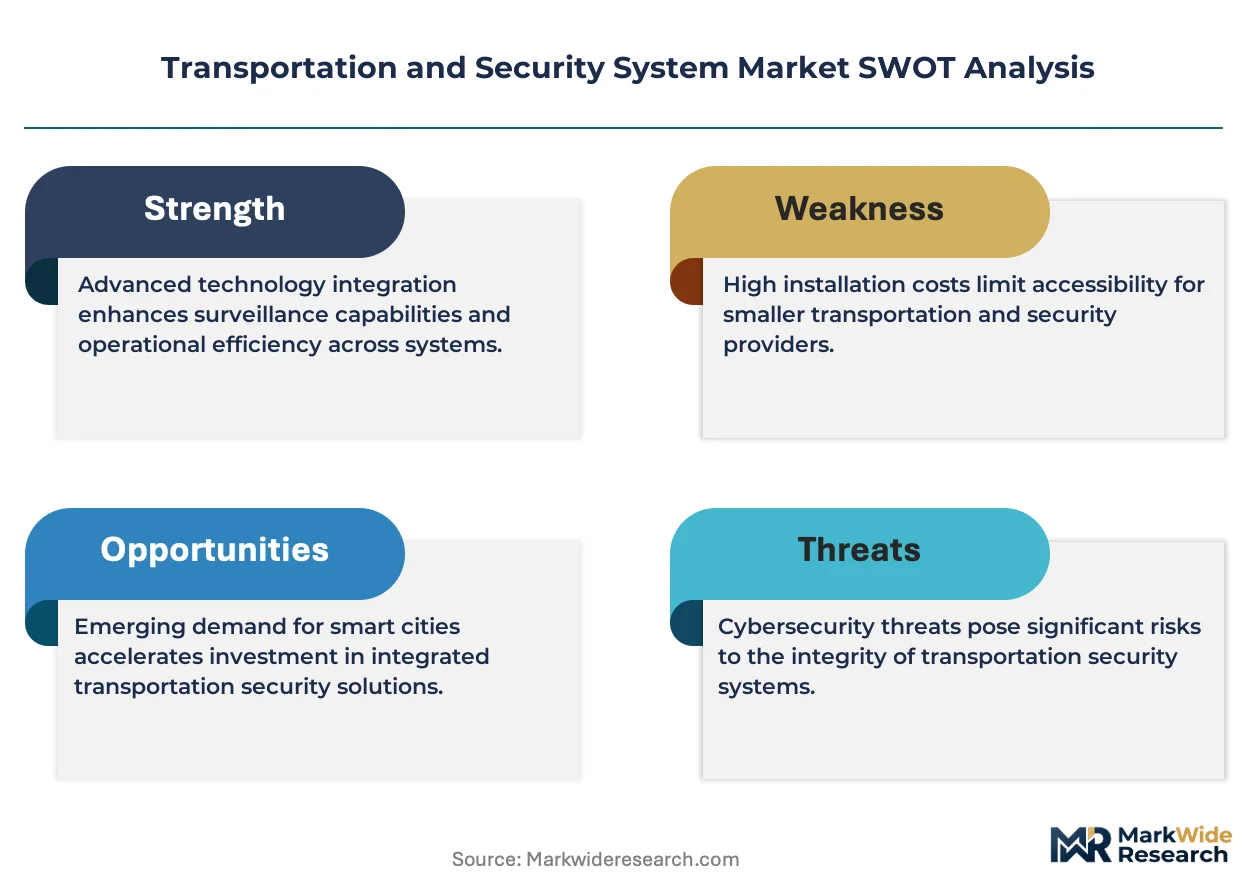
The central dynamic is the market's bifurcation between legacy hardware and integrated, software-defined security platforms. Government mandates for intelligent infrastructure in aviation and public transit are forcing a convergence of physical access control, video surveillance, and AI-powered analytics, shifting value toward software and systems integration.
Growth Catalysts
- Government Security Mandates:Increased government investment in public safety, guided by regulations from bodies like the US Transportation Security Administration (TSA), propels upgrades to screening and surveillance technologies in the airports sector.
- AI and Biometric Integration:The incorporation of artificial intelligence for real-time video analytics and biometrics for frictionless access control is enhancing threat detection capabilities, driving adoption in high-traffic public transit systems.
- Infrastructure Modernization:Large-scale public works projects, particularly for high-speed rail and port expansion in China, create substantial demand for complex, large-scale deployments of integrated security systems.
Market Restraints
- High Capital Investment:The significant upfront cost associated with deploying and integrating advanced technologies like full-body scanners and AI-powered surveillance networks across vast infrastructures such as international airports remains a major barrier.
- System Interoperability:Integrating new, sophisticated systems with legacy infrastructure from multiple vendors creates significant technical challenges, often leading to performance issues and increased implementation costs.
- Stringent Certification Cycles:New technologies must undergo lengthy and expensive certification processes to comply with standards set by regulators like the TSA in the US or to meet EU-wide directives, slowing the pace of innovation reaching the market.
Strategic Opportunities
- Security-as-a-Service (SaaS):Offering subscription-based models for analytics, system management, and threat intelligence allows transportation authorities to access advanced capabilities with lower upfront capital expenditure, broadening the addressable market.
- Cyber-Physical Security Convergence:Developing integrated solutions that protect both the physical and digital layers of transportation networks addresses a critical vulnerability, as critical infrastructure becomes a target for cyber-attacks.
- Small and Mid-Sized Hubs:Targeting smaller regional airports and municipal transit systems with scalable, modular security packages presents an opportunity in underpenetrated segments that are beginning to upgrade their foundational security capabilities.
Industry Challenges
- Integration Complexity:The operational challenge of ensuring seamless communication between disparate systems, such as access control, video management, and passenger screening platforms, remains a primary hurdle for system integrators and end-users.
- Specialized Talent Shortage:A deficit of technicians and engineers with hybrid expertise in physical security hardware, network engineering, and AI software development complicates the deployment and maintenance of modern integrated systems.
- Data Privacy Compliance:Navigating the complex and evolving landscape of data privacy regulations, such as GDPR in Europe, regarding the use of biometrics and extensive video surveillance in public areas poses a significant compliance challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation and Security System Market |
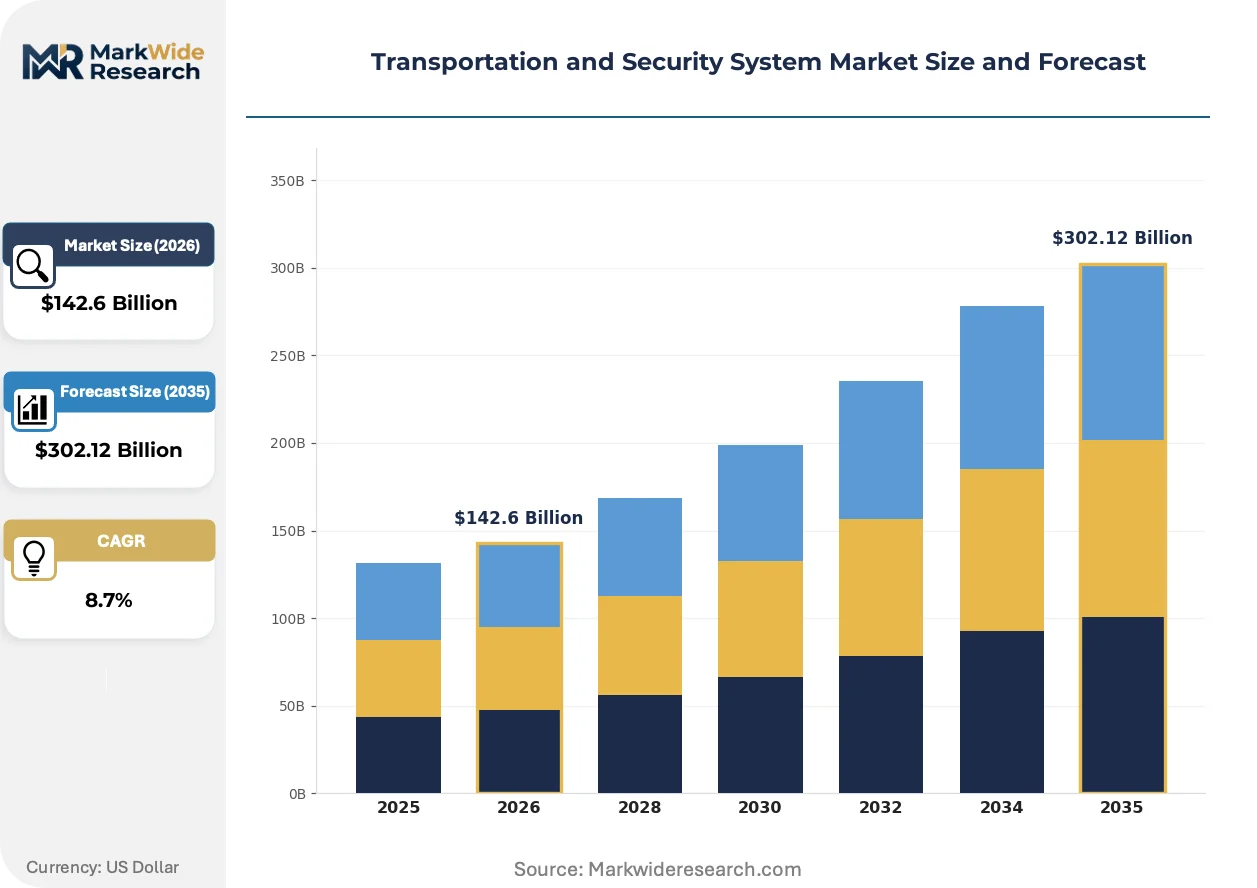
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $302.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Access Control, Intrusion Detection, Video Surveillance, Fire Alarm, Perimeter Security, Traffic Management Technology: Biometrics, RFID, IoT Sensors, AI Analytics, Cloud Computing, Machine Learning Application: Railways, Airports, Ports, Warehousing, Public Transit, Customs End User: Government Agencies, Logistic Operators, Security Firms, Facility Managers, Event Organizers |
| Companies Covered | Raytheon Company, Thales Group, Honeywell International, Kapsch Group, Alstom, Smiths Group, Rapiscan Systems, Bosch, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation and Security System Market Strategic Shifts & Innovations
The market's evolution is defined by the shift from hardware-centric sales to data-driven, software-enabled ecosystems. Intelligence is moving from centralized command posts to the network edge, transforming how security data is processed and acted upon in real-time environments like airports and rail networks.
Edge computing embeds AI analytics directly within security cameras and sensors, enabling on-device processing of video and other data streams. Airport authorities and mass transit operators are adopting this technology to enable immediate threat detection and operational alerts without congesting network bandwidth. This development is decentralizing intelligence from a core server architecture to the periphery of the network, significantly reducing latency for critical security event responses.
New regulations like the European Union's AI Act are setting stringent requirements for the use of artificial intelligence in public safety applications. The act classifies AI-driven surveillance and biometric identification systems as high-risk, mandating rigorous assessments of algorithmic fairness, transparency, and data governance. Consequently, system vendors targeting the EU market must now provide exhaustive compliance documentation to secure CE marking approval for their products.
A notable shift in purchasing behavior involves moving away from large, one-time capital acquisitions toward more flexible, subscription-based service models. This approach allows transportation agencies to convert heavy capital expenditures into predictable operational costs for software, analytics, and system updates. The model is gaining traction in North America and Europe, where public entities seek continuous technological improvement without massive upfront investment.
Transportation and Security System Market Segmentation
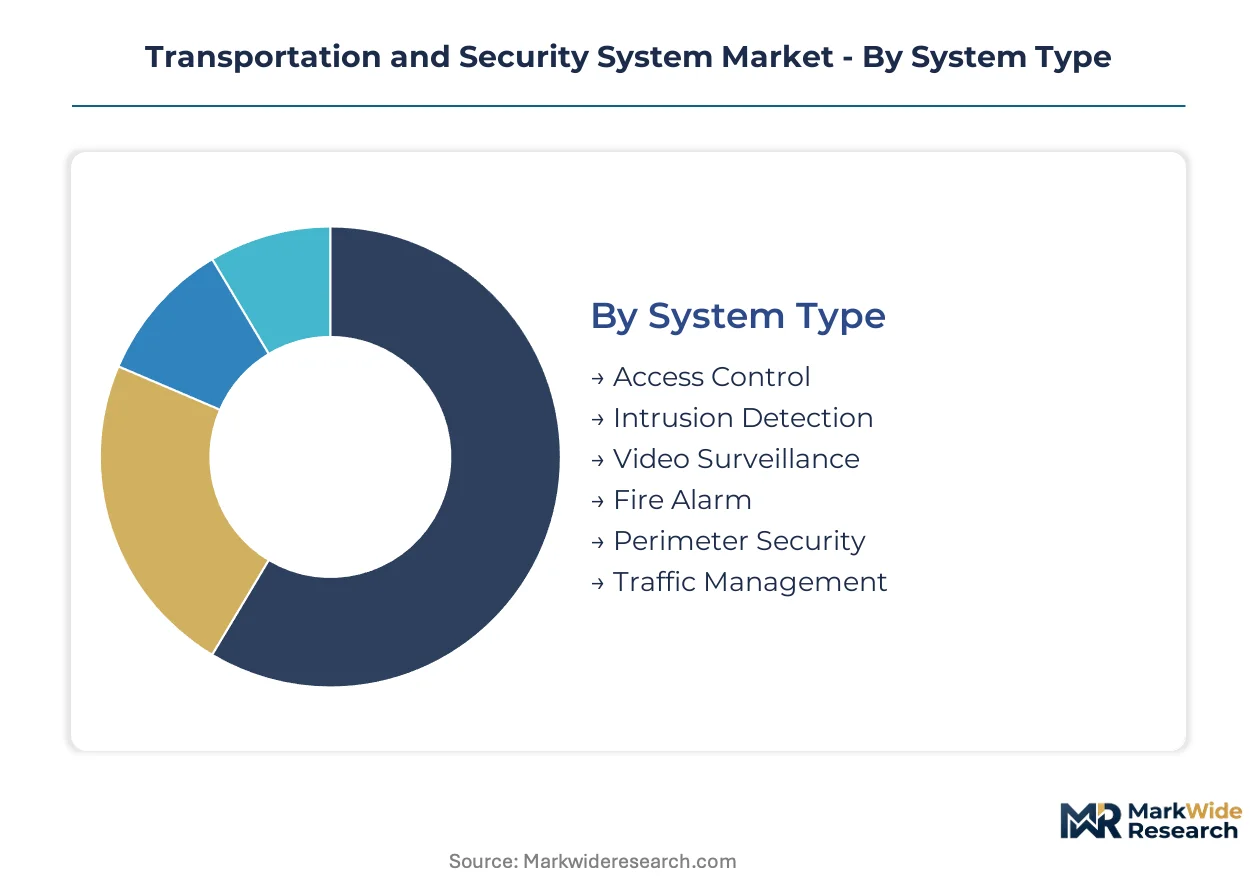
The Transportation and Security System Market segmentation provides a granular view of distinct product offerings and end-user requirements. Understanding these segments helps stakeholders identify specific investment areas and technological priorities. This detailed breakdown clarifies where innovation is concentrating and where established solutions maintain market dominance.
System Type:
The System Type segment highlights the varying capital intensity required for different security infrastructure components.
- Video Surveillance:These systems encompass cameras, recording devices, and video management software for monitoring and recording activities. Demand concentrates in airports and ports due to stringent regulatory requirements for continuous oversight.
- Access Control:Solutions manage and restrict entry to specific areas using credentials, biometrics, and electronic locks. Public transit systems are upgrading access control to enhance passenger flow and operational security.
- Intrusion Detection:Sensors and alarms identify unauthorized entry into protected zones. Warehousing facilities deploy these systems to safeguard valuable cargo and prevent theft.
- Fire Alarm:These systems detect fire and smoke, alerting occupants and emergency services. Railway stations integrate advanced fire detection for passenger safety and infrastructure protection.
- Perimeter Security:Physical barriers, sensors, and surveillance protect the outer boundaries of critical sites. Customs checkpoints utilize perimeter security to prevent illicit crossings and smuggling.
- Traffic Management:Technologies optimize vehicle flow and enhance safety on roadways and within transportation hubs. Airports implement sophisticated traffic management for ground vehicle coordination.
Video Surveillance absorbs the bulk of installed capacity; Access Control is expanding most quickly.
Technology:
Technology segmentation delineates solutions based on their core functional application across various transportation environments.
- AI Analytics:Artificial intelligence algorithms process video and sensor data for real-time threat detection and anomaly identification. Airports leverage AI analytics to enhance baggage screening and passenger monitoring efficiency.
- Biometrics:Systems verify identity using unique physical or behavioral characteristics like fingerprints or facial recognition. Public transit operators deploy biometrics for frictionless access and enhanced security checks.
- RFID:Radio-frequency identification tags track assets, personnel, and cargo within logistics operations. Warehousing and port facilities use RFID for efficient inventory management and supply chain visibility.
- IoT Sensors:Connected physical devices collect environmental data, movement, and other parameters for security and operational insights. Railways integrate IoT sensors for predictive maintenance and infrastructure monitoring.
- Cloud Computing:Remote servers and networks store, manage, and process security data, offering scalability and accessibility. Logistic operators utilize cloud computing for centralized data management across distributed operations.
- Machine Learning:Algorithms enable systems to learn from data without explicit programming, improving detection accuracy over time. Customs agencies employ machine learning for intelligent cargo inspection and risk assessment.
AI Analytics platforms are gaining market share fastest; Cloud Computing offers scalable infrastructure.
Application:
The Application segment differentiates demand volume across critical transportation infrastructure types.
- Airports:These facilities require comprehensive security for passenger screening, baggage handling, and perimeter protection. Strict regulatory mandates from bodies like the TSA drive technology adoption in US airports.
- Ports:Large-scale maritime terminals demand integrated solutions for cargo inspection, vessel monitoring, and access control. European Union directives shape security protocols for critical port infrastructure.
- Railways:Security systems protect passengers, infrastructure, and rolling stock across vast networks. China's high-speed rail expansion creates substantial demand for advanced surveillance and access control.
- Warehousing:Storage facilities implement security measures to protect goods, manage inventory, and monitor access. Logistic operators rely on robust security to prevent theft and ensure operational continuity.
- Public Transit:Urban bus, metro, and tram systems require surveillance, access control, and emergency communication. Major cities in Europe are upgrading public transit security to enhance passenger safety.
- Customs:Border control points utilize inspection technologies and surveillance for trade compliance and security. Government agencies deploy advanced screening equipment to detect contraband.
Airports consistently generate the highest revenue contributions; Public Transit systems show the steepest expansion trajectory.
End User:
End User segmentation categorizes demand based on the primary organizational structure procuring security solutions.
- Government Agencies:These entities, including national security bodies and transportation departments, fund and implement large-scale security projects. The US Transportation Security Administration (TSA) sets standards for passenger and baggage screening technologies.
- Logistic Operators:Companies managing the flow of goods require security for warehouses, distribution centers, and transport vehicles. These operators focus on supply chain integrity and asset protection.
- Security Firms:Specialized companies provide security services, including system installation, monitoring, and personnel. These firms offer expertise in complex system integration and operational management.
- Facility Managers:Professionals overseeing the operation and maintenance of buildings and infrastructure require integrated security solutions. They prioritize systems that enhance safety and operational efficiency.
- Event Organizers:Entities planning large public gatherings need temporary or scalable security systems for crowd control and threat detection. They focus on rapid deployment and real-time monitoring capabilities.
Government Agencies represent the largest spending block; Security Firms are increasingly influencing procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City's major transportation hubs, including JFK and LaGuardia airports, drive significant investment in advanced security systems. These complex environments require integrated solutions for passenger screening and access control. Governments globally are prioritizing infrastructure upgrades to enhance public safety and operational efficiency.
United States
Increased government funding for public transit and port infrastructure upgrades fuels demand for advanced security systems. The Transportation Security Administration (TSA) sets stringent standards for passenger and baggage screening technologies across airports. Major port cities like Los Angeles are implementing sophisticated cargo inspection and perimeter security solutions.
China
Large-scale public works projects for high-speed rail and port expansion generate substantial demand for integrated security deployments. China's dual carbon goals influence the adoption of energy-efficient security technologies in new infrastructure. The Yangtze River Delta region is a hub for smart city initiatives that incorporate advanced surveillance and traffic management systems.
Germany
Modernization efforts across railway networks and critical infrastructure drive investment in advanced fire alarm and intrusion detection systems. European Union directives govern security protocols for rail and port infrastructure, influencing access control specifications. The Frankfurt Airport complex represents a significant market for AI analytics and biometric integration in aviation security.
United Kingdom
Upgrades to urban public transit systems and major airport facilities necessitate investment in video surveillance and access control technologies. Compliance with GDPR regulations impacts the implementation of biometric systems and extensive video monitoring in public areas. London's extensive underground network is a focus for real-time threat detection and emergency communication system enhancements.
India
Rapid expansion of airport capacity and development of new metro rail lines create significant opportunities for integrated security solutions. The Bureau of Indian Standards (BIS) guides technology adoption in public safety and infrastructure projects. Bengaluru's Kempegowda International Airport is actively deploying AI-powered surveillance and frictionless passenger processing systems.
Transportation and Security System Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in the transportation and security system market. The market structure exhibits a tiered consolidation, with large conglomerates offering integrated solutions alongside specialized niche players. Strategic archetypes include systems integrators, hardware manufacturers, and software platform developers. Companies frequently engage in strategic partnerships to combine hardware expertise with advanced software capabilities, and pursue portfolio diversification to address various end-user requirements.
Within the tier of comprehensive solution providers, Thales Group and Honeywell International exemplify organizations with extensive portfolios spanning multiple security domains. Thales Group, a France-based entity, represents large-scale, complex deployments for rail and aviation clients, requiring deep systems integration. Honeywell International, a US-based corporation, occupies a position leveraging its extensive portfolio in building controls and fire alarm systems to offer bundled security packages. Rapiscan Systems, a US-based specialist, anchors the niche of cargo and vehicle inspection technologies, focusing on high-performance screening equipment.
| Leading Market Players |
|---|
| Raytheon Company |
| Thales Group |
| Honeywell International |
| Kapsch Group |
| Alstom |
| Smiths Group |
| Rapiscan Systems |
| Bosch |
| Lockheed Martin |
| Others |
Cost & Logistics Intelligence
High-performance sensor component costs, sourced primarily from East Asian manufacturers, significantly influence the final price points of integrated security platforms, particularly for large-scale governmental deployments.
Pricing Analysis
Outcome-based pricing models are increasingly prevalent in the transportation security system market, reflecting the value delivered through enhanced safety and operational efficiency. Price differentiation stems from certification levels, such as TSA compliance, and the degree of system customization required for complex infrastructure deployments. Pricing pressure stems from the need for cost-effective upgrades in public transit, where budget constraints are common. Public transit operators are generally the most price-sensitive, while airport authorities prioritize compliance and advanced capability.
Supply Chain Analysis
Specialized sensor and AI chip supply rests heavily on manufacturers in Taiwan, South Korea, and the United States, forming critical input dependencies. Complex integrated systems rely on microcontrollers, advanced optics, and specialized cabling. Single-source vulnerability for certain high-performance components poses a structural supply chain risk for system integrators. Distribution runs through a network of specialized system integrators and direct sales channels to large government entities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transportation and security system market is a vertical-integration race, with players actively pursuing deeper control over AI analytics software development to enhance platform capabilities.
For Market Incumbents: Cement market leadership by consolidating smaller software-defined solution providers, enhancing integrated offerings for critical infrastructure. Defensive moves include investing heavily in advanced certification processes for new biometric technologies to counter emerging regulatory shifts. This protects against the threat of specialized AI startups disintermediating traditional hardware sales, leveraging R&D in edge computing.
For New Entrants and Emerging Players: Capture underpenetrated small and mid-sized hubs by offering scalable, modular security packages with subscription-based analytics. These segments represent white-space targets in regional airports and municipal transit systems. A go-to-market angle involves partnering with local system integrators to provide rapid deployment and localized support.
For Investors and Strategic Acquirers: New government funding announcements for public transit upgrades are the leading indicator that sustained investment will continue across the analysis window. The market demonstrates long-term viability, driven by continuous infrastructure modernization and evolving threat landscapes over the next decade. Acquisition targets should be specialized software firms with strong AI analytics expertise and established compliance frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire AI Analytics Specialist | Accelerates integration of advanced real-time threat detection into security platforms. |
| Invest in Edge Computing R&D | Reduces latency for critical security event responses in high-traffic environments like airports. |
| Expand SaaS Offerings | Allows transportation authorities to access advanced capabilities with lower upfront capital expenditure. |
| Pursue Cyber-Physical Security Solutions | Addresses critical vulnerabilities in transportation networks by protecting both physical and digital layers. |
| Obtain EU AI Act Compliance | Ensures market access and regulatory approval for high-risk AI systems in Europe. |
Research Approach
Document review covered government reports, transportation authority procurement data, and regulatory body publications, complemented by interviews with security system integrators, airport operations managers, and public transit security leads. This approach combined primary insights with secondary validation, employing both bottom-up and top-down triangulation to ensure data accuracy.
The quantitative model produced detailed volume and value projections across the analysis window, segmented by system type, technology, application, and end-user. CAGRs were derived from historical growth patterns and projected technology adoption rates. Key forecast inputs included government infrastructure spending and regulatory mandate timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical events and evolving cyber threats. These projections reflect underlying assumptions regarding technological advancements and regulatory stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Latin America Cross Border Road Freight Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
United States Road Freight Transport Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
GCC International Express Service Market