
 Saudi Arabia Land-Based Fuel Transportation Market | 2026-2036
Saudi Arabia Land-Based Fuel Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Land-Based Fuel Transportation Market Insights
Asset-light leasing and operational hire-purchase structures is rewriting competitive entry conditions for mid-scale hauliers in the Kingdom. Aldrees Petroleum and Transport Services Company leverages its captive maintenance yards and driver training academies to sustain fleet utilization rates above industry norms. Saudi Aramco dominates wholesale fuel allocation, while Petroly Petroleum Services & Transportation competes through specialized ethanol and biofuel handling certifications for industrial clients.
Saudi Arabia land-based fuel transportation encompasses the road movement of refined petroleum products, biofuels, and alternative liquid energy carriers via purpose-built tankers, rigid trucks, and articulated trailers engineered to ADR-equivalent pressure and temperature specifications. The primary commercial purpose centers on bridging refinery gate, import terminal, and strategic storage locations to end-use consumption points across industrial, mining, and construction sites. Tankers within the Vehicle Type segment anchor the highest capital deployment and regulatory scrutiny, while the Fuel Type dimension shows diesel retaining volume leadership against nascent biofuel traction in logistics corridors serving the Red Sea coast. Service Type fragmentation reveals Delivery as the mature revenue pool, with Maintenance emerging as a margin-accretive attach category as SASO inspection intervals compress.
The Saudi Standards, Metrology and Quality Organization (SASO) mandates periodic tanker integrity testing and driver hazardous-material certification, directly shaping fleet replacement cycles and compliance costs for operators. The Ministry of Transport and Logistic Services enforces axle-load limits and route restrictions through the electronic Rabat tracking platform, conditioning dispatch economics on real-time regulatory visibility. Stakeholders must monitor how the General Authority for Competition interprets collective fuel transport pricing in deregulated wholesale markets, as this determination will clarify whether independent hauliers can secure contracted volumes against integrated operator preferences.
Market Dynamics
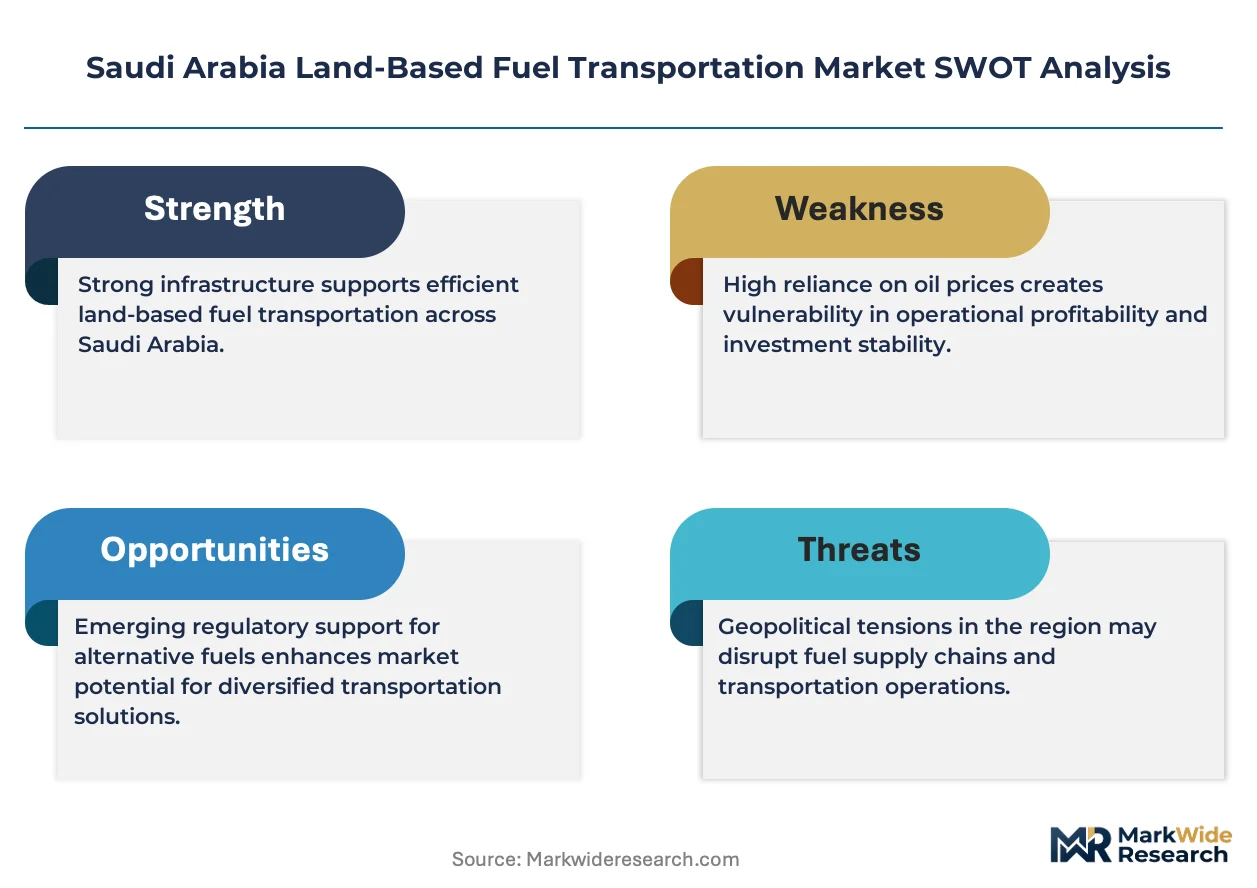
SASO's tightened tanker safety certification regime is compressing fleet replacement cycles and elevating compliance costs for domestic road transport operators across the Kingdom.
Growth Catalysts
- Giga-project construction:NEOM, Red Sea Global, and Qiddiya developments are expanding contracted fuel delivery arrangements for heavy equipment fleets operating on remote sites.
- Jubail Industrial City density:Aramco-affiliated logistics clusters in the Eastern Province concentrate fuel off-take from refineries and strategic storage terminals.
- Biofuel handling certification:Specialized ethanol and alternative liquid energy carrier qualifications are opening industrial client segments beyond conventional petroleum distribution.
Market Restraints
- Wholesale allocation concentration:Saudi Aramco's dominance in refined product allocation limits independent haulier access to contracted volumes against integrated operator preferences.
- Steel and aluminum input volatility:Tanker fabrication costs fluctuate with global metal pricing, pressuring capital deployment timelines for fleet expansion.
- ADR-equivalent specification compliance:Purpose-built pressure and temperature engineering requirements raise per-unit asset costs above regional peer markets.
Strategic Opportunities
- Red Sea coast logistics corridors:Nascent biofuel traction along western shipping routes offers first-mover positioning for certified handlers.
- Maintenance service unbundling:SASO inspection interval compression is creating attach-category margin pools beyond core delivery revenue.
- Operational hire-purchase structures:Asset-light leasing models are rewriting competitive entry conditions for mid-scale hauliers without captive capital reserves.
Industry Challenges
- Hazmat driver certification throughput:SASO-mandated hazardous-material training academies face capacity constraints matching fleet expansion timelines.
- Rabat platform integration:Real-time axle-load compliance and route restriction tracking requires dispatch system upgrades for legacy fleet management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Land-Based Fuel Transportation Market |
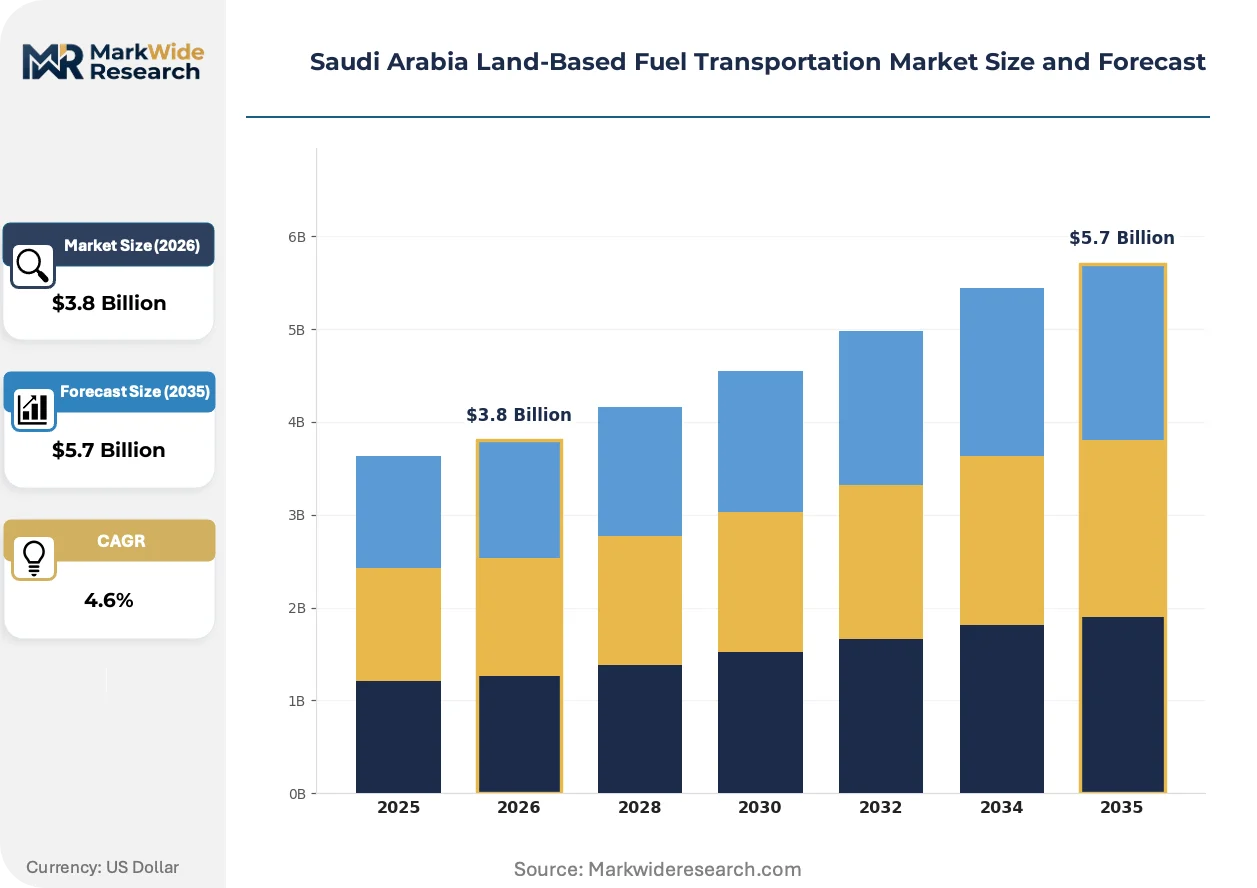
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Tankers, Trucks, Trailers, Buses Service Type: Delivery, Storage, Maintenance, Pumping Fuel Type: Diesel, Gasoline, Biofuels, Ethanol End User: Mining, Construction, Agriculture, Logistics |
| Companies Covered | Aldrees Petroleum and Transport Services Company, Arabian Petroleum Supply Company (APSCO), Petroly Petroleum Services & Transportation, Alsudais for Trading & Transports, Well Petroleum Services, Saudi Aramco, Petromin Corporation, NAFT Services Company Limited, Wafi Energy Company LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Land-Based Fuel Transportation Market Trends and Innovations
Telematics integration and predictive maintenance systems are reshaping how operators manage tanker integrity, driver certification compliance, and route optimization across the Kingdom's dispersed industrial zones.
IoT-enabled tanker monitoring systems are digitizing pressure, temperature, and location telemetry for hazardous cargo in transit. Construction and mining fleet operators are adopting these platforms fastest, driven by SASO audit trail requirements. The technology is digitizing compliance documentation workflows and compressing incident response times for spills or temperature excursions.
SASO's periodic tanker integrity testing mandates now require documented pressure vessel inspection records linked to individual asset registration numbers. This regulatory shift forces fleet operators into shorter replacement cycles and accelerates scrappage of pre-2018 fabricated tankers. Eastern Province hauliers are responding by consolidating maintenance yards to achieve scale economies in certification preparation.
Contracted fuel delivery arrangements are displacing spot-market transactions for giga-project construction fleets. Long-term offtake agreements with fixed volume commitments and penalty clauses are replacing transactional procurement at remote sites. This pattern concentrates most visibly in Tabuk and NEOM development zones where supply security outweighs price flexibility in contractor selection criteria.
Saudi Arabia Land-Based Fuel Transportation Market Segmentation
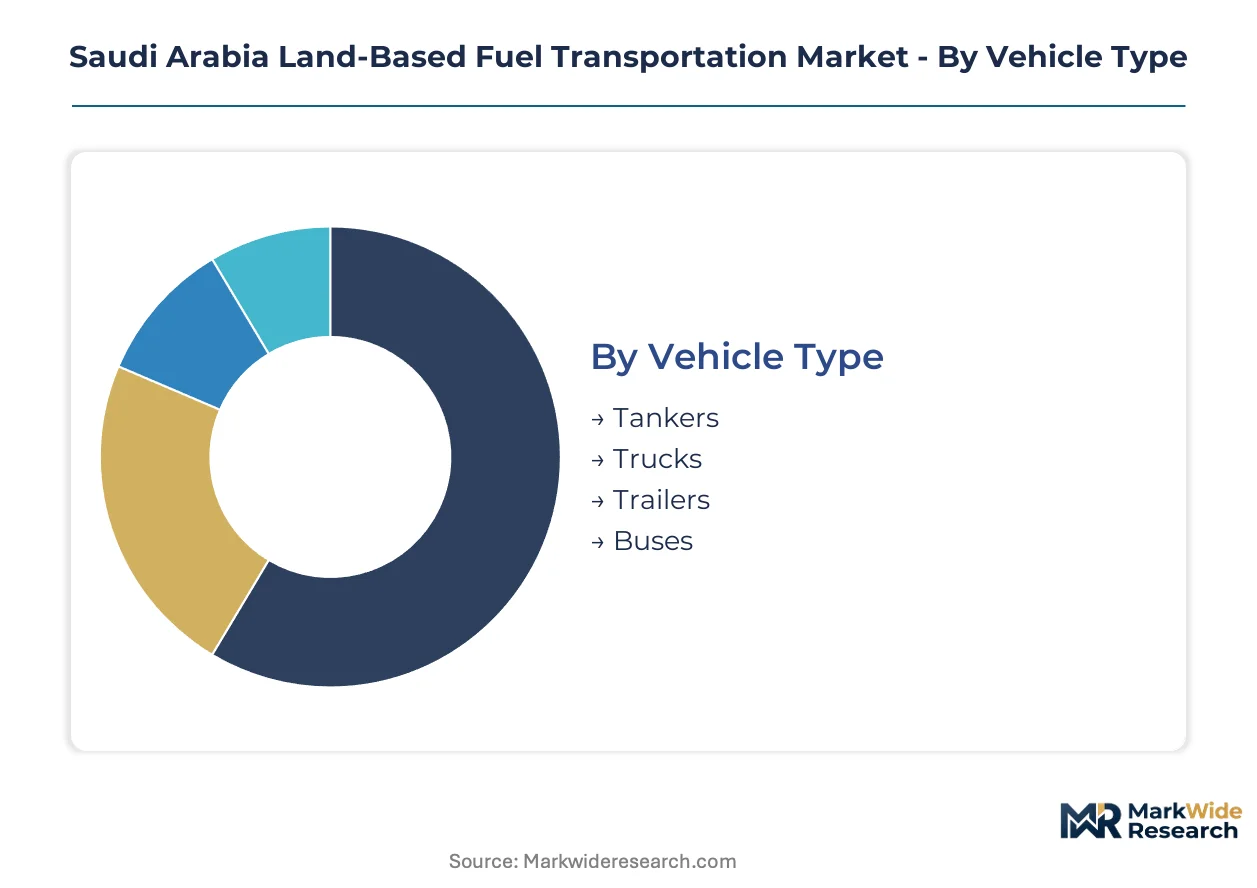
Segmentation in Saudi Arabia's land-based fuel transportation market reveals how capital intensity, regulatory burden, and customer concentration fragment competitive positioning across asset classes and service tiers. Operators must align fleet composition and certification portfolios against the specific density patterns of Eastern Province industrial clusters versus western giga-project corridors.
Vehicle Type:
Mature rigid platforms anchor established revenue pools while articulated configurations capture emerging long-haul and high-volume applications.
- Tankers:Purpose-built pressure vessels engineered to ADR-equivalent specifications carry refined petroleum, biofuels, and alternative liquid energy carriers. Eastern Province hauliers around Jubail Industrial City deploy these assets most densely, where Aramco-affiliated logistics clusters concentrate fuel off-take from refineries and strategic storage terminals.
- Trucks:Rigid chassis with integrated tankage serve shorter-radius distribution loops and construction site fueling. NEOM and Red Sea Global developments are expanding contracted delivery arrangements for these units as giga-project fleets displace spot-market procurement with fixed-volume commitments.
- Trailers:Articulated configurations enable payload scaling across long-haul corridors connecting import terminals to inland consumption points.
- Buses:Mobile fueling platforms serve dispersed mining and construction sites lacking fixed infrastructure.
Tankers retain volume leadership; buses hold the steepest expansion curve as remote site fueling requirements proliferate.
Service Type:
Revenue concentration shifts from core delivery toward attach-category services as SASO compliance intervals compress and customers unbundle maintenance procurement.
- Delivery:The mature revenue pool bridging refinery gates, import terminals, and strategic storage locations to end-use consumption points. Construction and mining fleet operators in Tabuk development zones are adopting long-term offtake agreements with penalty clauses, displacing transactional procurement.
- Maintenance:Pressure vessel inspection, certification preparation, and preventive servicing emerge as margin-accretive categories. Eastern Province operators consolidate maintenance yards to achieve scale economies as SASO mandates documented tanker integrity testing linked to individual asset registration numbers.
- Storage:Intermediate tankage and buffer inventory management at customer sites.
- Pumping:Transfer and dispensing services for bulk fuel handling at industrial facilities.
Delivery commands the largest revenue base; maintenance is climbing the fastest as regulatory compliance costs reshape procurement patterns.
Fuel Type:
Conventional petroleum products dominate current throughput while certified alternative carriers unlock premium positioning in industrial segments.
- Diesel:Retains volume leadership across construction, mining, and logistics applications. Heavy equipment fleets operating at remote giga-project sites depend on reliable diesel supply security, outweighing price flexibility in contractor selection criteria.
- Gasoline:Serves lighter commercial vehicle fleets and power generation backup systems.
- Biofuels:Specialized ethanol and alternative liquid energy carrier qualifications are opening industrial client segments beyond conventional petroleum distribution. Red Sea coast logistics corridors show nascent traction as western shipping routes develop alternative fuel infrastructure.
- Ethanol:Requires dedicated handling certifications and segregated tankage for industrial offtake.
Diesel retains volume leadership; biofuels hold the steepest expansion curve as industrial decarbonization mandates deepen.
End User:
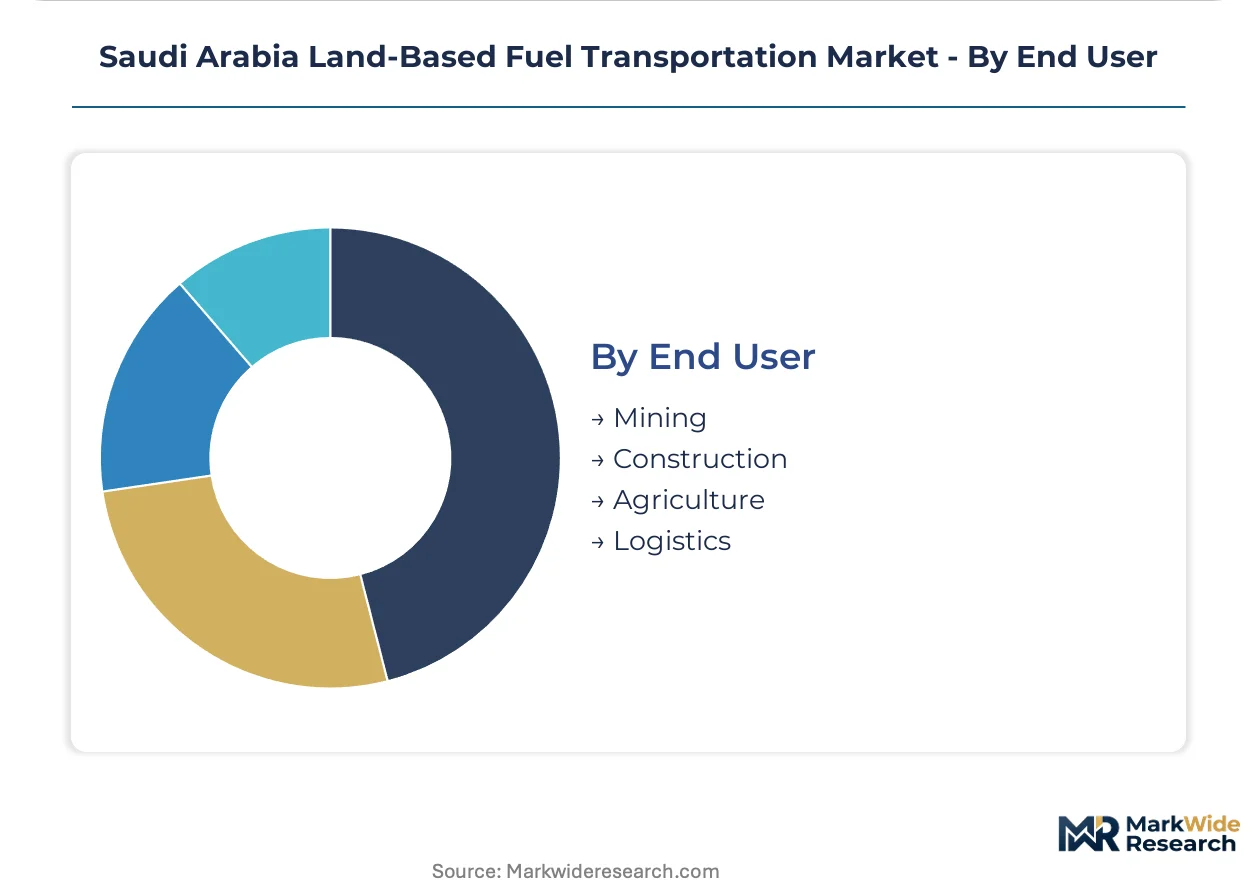
Customer concentration patterns diverge between capital-project-driven construction demand and steady-state industrial consumption in established zones.
- Construction:Giga-project developments at NEOM, Qiddiya, and Red Sea Global are expanding contracted fuel delivery arrangements. Fleet operators prioritize supply security and fixed-volume commitments over spot-market flexibility at these remote sites.
- Mining:Continuous extraction operations require uninterrupted fuel supply to power heavy equipment fleets. IoT-enabled tanker monitoring systems digitize pressure, temperature, and location telemetry for hazardous cargo serving these customers.
- Agriculture:Seasonal demand patterns and dispersed geographic distribution characterize this segment.
- Logistics:Third-party haulage and fleet operators serving multi-customer distribution networks.
Construction commands the largest revenue base; mining is expanding most quickly as extraction capacity scales in the Kingdom's mineral development push.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's land-based fuel transportation market balances domestic refinery output with strategic import dependencies along Red Sea and Gulf coasts. The Kingdom's logistics corridors concentrate fuel movement from Eastern Province production zones to western construction and industrial sites.
Eastern Province
Jubail Industrial City anchors the densest fuel off-take cluster, where Aramco-affiliated logistics groups coordinate refinery gate distribution to petrochemical complexes. The Saudi Standards, Metrology and Quality Organization mandates periodic tanker integrity testing for all operators serving this zone. Ras Tanura and Dammam storage terminals feed articulated trailer fleets moving diesel and gasoline to inland consumption points.
Riyadh
The central region's construction boom drives contracted fuel delivery arrangements for heavy equipment fleets building Qiddiya and Diriyah Gate. The Ministry of Transport and Logistic Services enforces axle-load compliance through the Rabat electronic tracking platform. Fleet operators consolidate dispatch operations around the capital to optimize route density against regulatory visibility requirements.
Western Region
Jeddah and Yanbu ports handle refined product imports that supply Red Sea coast logistics corridors with growing biofuel traction. The General Authority for Competition monitors wholesale transport pricing in these deregulated zones. Industrial clients near King Abdullah Economic City are procuring certified ethanol handling services from specialized operators.
NEOM Northwest
Remote giga-project construction at NEOM, Oxagon, and Sindalah is expanding mobile fueling platform deployment where fixed infrastructure remains absent. Long-term offtake agreements with penalty clauses are displacing spot-market procurement for mining and construction fleets. Tabuk-based hauliers are investing in IoT-enabled tanker monitoring systems to satisfy SASO audit trail mandates.
Saudi Arabia Land-Based Fuel Transportation Market Competitive Landscape
On the supply side, the industry is consolidating around integrated petroleum conglomerates with captive logistics arms, while mid-scale independent operators compete through specialized certifications and asset-light structures. Three strategic archetypes dominate: state-affiliated integrated operators controlling wholesale allocation, diversified transport service companies with captive maintenance infrastructure, and niche specialists holding biofuel and alternative carrier qualifications. Capacity expansion in driver training academies and maintenance yard consolidation represent the primary competitive vectors as SASO compliance intervals compress.
Within the integrated operator tier, Saudi Aramco occupies a position as the dominant wholesale fuel allocator, conditioning market access for downstream hauliers. Aldrees Petroleum and Transport Services Company exemplifies the diversified transport archetype through its established operational footprint across the Kingdom. Petroly Petroleum Services & Transportation sits within the specialization tier, representing operators competing through differentiated handling certifications for industrial fuel segments.
| Leading Market Players |
|---|
| Aldrees Petroleum and Transport Services Company |
| Arabian Petroleum Supply Company (APSCO) |
| Petroly Petroleum Services & Transportation |
| Alsudais for Trading & Transports |
| Well Petroleum Services |
| Saudi Aramco |
| Petromin Corporation |
| NAFT Services Company Limited |
| Wafi Energy Company LLC |
| Others |
Pricing and Supply Chain Analysis
Saudi Aramco's wholesale fuel allocation monopoly concentrates upstream supply control in the Kingdom, directing margin pools toward integrated operators with captive logistics arms and squeezing independent haulier profitability.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the Kingdom's fuel transportation market. Three-tier pricing structure across premium, standard, and economy levels reflects SASO certification grade, volume scale, and after-sales maintenance bundling. Cost compression in the standard tier is intensifying because steel and aluminum input volatility pressures tanker fabrication economics. Construction fleet operators at giga-project sites demonstrate least price sensitivity due to supply security priorities, while spot-market independent hauliers face greatest margin erosion.
Supply Chain Analysis
Extended payment terms from domestic fabricators and supply-chain finance facilities from Aramco-affiliated logistics clusters are restructuring working capital requirements for fleet operators. Tanker fabrication draws from China, South Korea, and Germany for pressure vessel steel and ADR-equivalent component systems. Single-source vulnerability concentrates in specialized ethanol handling seals and IoT-enabled monitoring hardware. Distribution runs through Eastern Province refinery gates, Rabat-tracked corridor networks, and Jubail Industrial City consolidation yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maintenance service unbundling represents the fastest-expanding recurring-revenue layer, outpacing core fuel delivery growth as SASO inspection intervals compress and industrial clients outsource certification preparation.
For Market Incumbents: Build captive driver training academy capacity as a certification moat against independent haulier expansion. Consolidate maintenance yard footprints in the Eastern Province to capture scale economies in SASO-mandated tanker integrity testing. Defensive positioning against asset-light leasing entrants requires locking long-term offtake agreements with penalty clauses at NEOM and Red Sea Global construction zones.
For New Entrants and Emerging Players: Establish a beachhead in biofuel handling certification for Red Sea coast industrial clients where specialized ethanol qualifications remain underpenetrated. Target mobile fueling platform deployment at remote mining sites lacking fixed infrastructure. Go-to-market execution should leverage operational hire-purchase structures to bypass capital intensity barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale hauliers holding 2018-era tanker fleets facing accelerated scrappage under tightened SASO regimes. Long-term viability favors operators with integrated maintenance infrastructure and Rabat platform compliance capabilities. Watch for General Authority for Competition rulings on wholesale transport pricing as the inflection signal for independent haulier market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Maintenance Yard Consolidation | Eastern Province operators achieve SASO scale economies through centralized certification preparation infrastructure. |
| Biofuel Handling Certification | Petroly Petroleum Services demonstrates premium positioning through specialized ethanol qualifications for industrial clients. |
| IoT-Enabled Tanker Monitoring | Tabuk-based hauliers digitize audit trails to satisfy SASO telemetry mandates for NEOM construction fleets. |
| Driver Training Academy Expansion | Aldrees Petroleum sustains above-norm fleet utilization through captive hazmat certification throughput. |
| Operational Hire-Purchase Structures | Asset-light leasing rewrites competitive entry conditions for mid-scale hauliers without captive capital reserves. |
Research Methodology
Operator-level perspectives from fleet dispatch managers, SASO compliance officers, Aramco wholesale allocation specialists, and construction procurement directors anchored the qualitative base for this study. Primary interview findings triangulated against customs records from the Kingdom's import terminals, Ministry of Transport Rabat platform disclosure summaries, and SEC filings from listed transport operators. Bottom-up vehicle deployment counts and top-down fuel consumption estimates were reconciled across Eastern Province, Riyadh, and Western Region clusters.
Scenario-bracketing around giga-project construction timelines, biofuel adoption curves, and SASO enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle type, service tier, fuel category, and end-use industry density patterns. CAGRs derived from elasticity-adjusted volume projections incorporating fleet replacement cycle compression and inspection interval regulatory changes.
Stress conditions across steel input pricing, driver certification academy capacity, and wholesale allocation policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding construction fleet expansion and regulatory compliance cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
US Tolling Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
Road Transport Refrigeration Equipment Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market