
 Road Haulage Market | 2026-2036
Road Haulage Market Size, Share, and Industry Trends Forecast 2026-2036
Road Haulage Market Intelligence
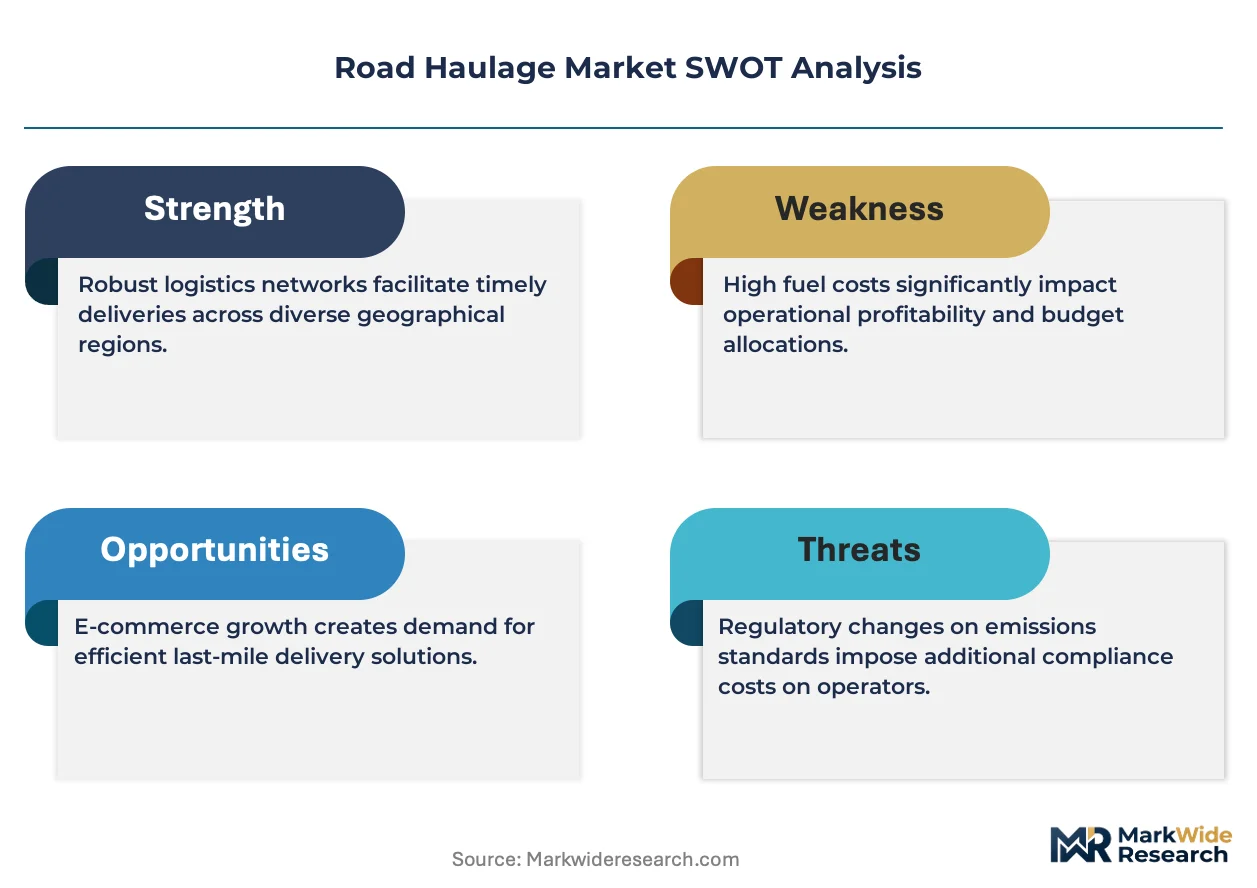
A widening capability gap between asset-heavy and technology-first operators is redrawing competitive boundaries in road haulage. J.B. Hunt Transport Services leverages its integrated multimodal platform to control intermodal conversion flows. Old Dominion Freight Line anchors its position through dense terminal networks and premium less-than-truckload service density. XPO Inc. differentiates via technology-intensive freight brokerage that matches capacity with shipper demand in real time.
Road haulage encompasses the commercial movement of goods by motorized vehicles over public highway networks, utilizing power units ranging from light-duty vans to super-heavy tractor-trailers with gross combination weights exceeding 80,000 pounds, and serves as the dominant mode for last-mile delivery and regional distribution. Full truckload services command the largest revenue pool due to shipper preferences for dedicated capacity, while refrigerated trailers within the vehicle type category capture outsized margins from temperature-sensitive pharmaceutical and food shipments. The end user base tilts toward retail and manufacturing, where just-in-inventory strategies require predictable transit windows.
The US EPA, the EU Green Deal framework, and the US DOT Hours-of-Service regulations collectively reshape fleet composition, driver availability, and carbon compliance costs across the industry. EPA Phase 3 standards will force accelerated zero-emission powertrain adoption, while HOS rules cap operational hours and intensify capacity tightness. Stakeholders must weigh electrification capex against regulatory penalty exposure and evolving shipper sustainability scorecards.
Market Dynamics
Electrification mandates from the US EPA and EU Green Deal are compressing fleet replacement cycles while simultaneously inflating capital intensity, forcing operators to restructure asset ownership models around battery-electric powertrains and charging infrastructure partnerships.
Growth Catalysts
- E-commerce fulfillment density:Parcel carriers are expanding dedicated contract carriage to serve next-day delivery networks, pulling capacity from spot markets into committed lanes.
- EU Green Deal fleet standards:Carbon compliance deadlines are accelerating zero-emission vehicle procurement timelines across German, French, and Dutch logistics corridors.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution is driving refrigerated trailer investment in last-mile and intermodal handoffs.
Market Restraints
- Lithium-ion battery supply concentration:Cell production clustering in China and South Korea creates procurement vulnerability for European and North American fleet electrification programs.
- Driver hour caps under HOS regulations:US DOT rules limit operational utilization and intensify wage competition for qualified operators.
- Charging infrastructure gaps:Highway corridor electrification lags vehicle deployment, constraining long-haul electric truck range economics.
Strategic Opportunities
- India's logistics corridor development:Dedicated freight highways and industrial zone connectivity offer first-mover positioning in contract carriage expansion.
- Battery-swapping standardization:Converging automated swap station technology with fleet telematics enables asset-light electrification models for mid-size operators.
- Carbon border adjustment mechanisms:EU CBAM implementation creates premium pricing power for verified low-emission haulage services serving import-heavy manufacturing.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance operations face recruitment gaps for battery-electric powertrain diagnostics and repair certification.
- Telematics-legacy TMS integration:Real-time freight matching platforms encounter friction connecting with shipper enterprise resource planning systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Haulage Market |
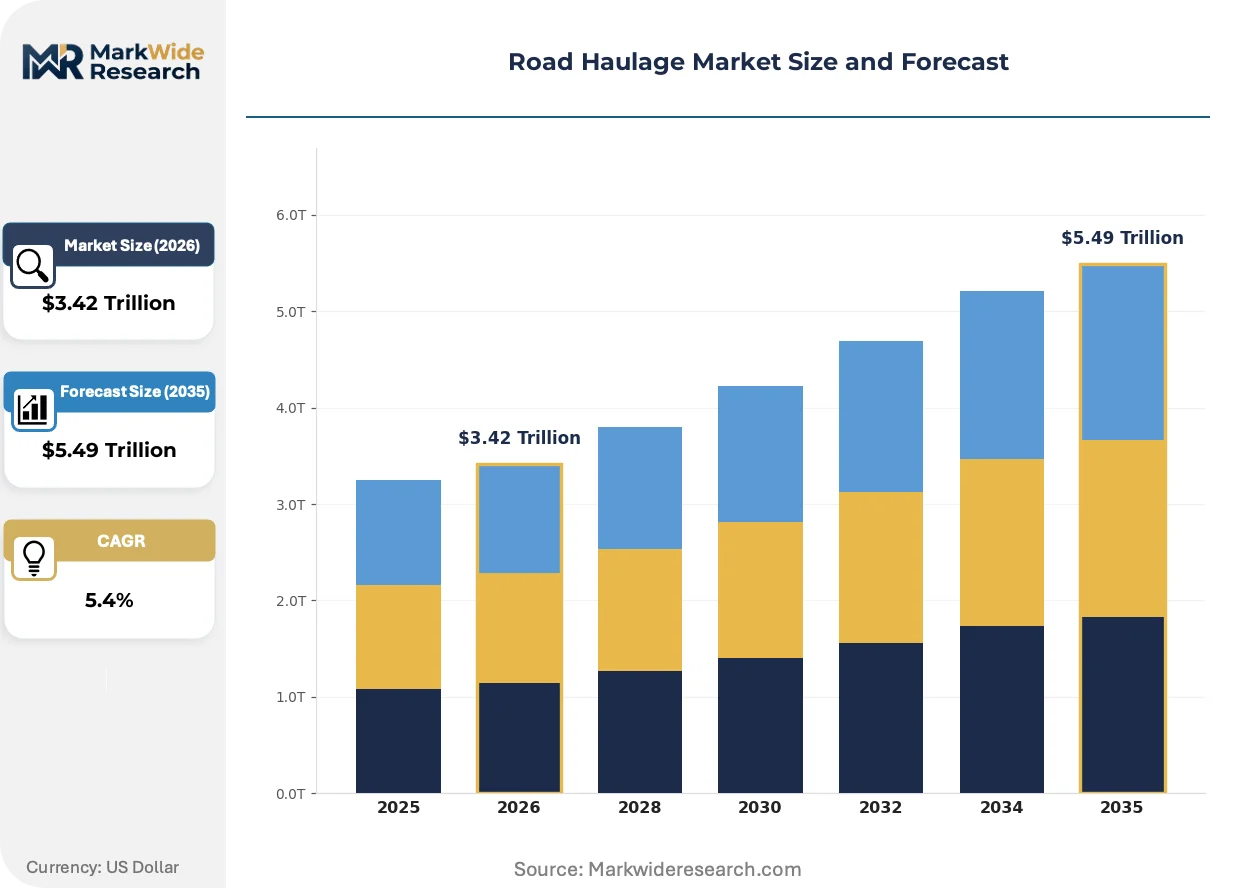
| Market Size in 2026 | $3.42 Trillion |
| Market Size in 2035 | $5.49 Trillion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Expedited Freight, Dedicated Contract Carriage Vehicle Type: Flatbed Trucks, Refrigerated Trailers, Tankers, Dry Van Trailers End User: Retail, Construction, Agriculture, Manufacturing Payload Capacity: Lightweight, Medium Duty, Heavy Duty, Super Heavy |
| Companies Covered | J.B. Hunt Transport Services, XPO Inc., UPS Inc., Old Dominion Freight Line, Knight-Swift Transportation, FedEx Corp., TFI International, Schneider National, Ryder System Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Haulage Market Strategic Shifts & Innovations
Digital freight platforms and autonomous vehicle development are converging to compress transaction costs and reshape driver workforce economics across long-haul corridors.
Autonomous trucking software stacks are displacing conventional driver-dependent operating models on designated freight-only highway segments. Mining and port logistics operators in Arizona and Texas are deploying supervised autonomous convoys for repetitive route loops. This displacement is compressing per-mile labor costs and forcing incumbent carriers to restructure compensation around remote monitoring roles rather than cab occupancy.
The EU Green Deal's Fit for 55 package mandates progressive CO2 reduction targets for heavy-duty vehicles through 2040. Manufacturers must phase out internal combustion engine sales or face fleet-average penalty exposure. German and Dutch haulage associations are responding by pooling charging infrastructure investments and negotiating green electricity procurement contracts at corridor scale.
Shippers are consolidating procurement around sustainability-verified carriers with published emission intensity metrics. Retail and automotive verticals are replacing transactional spot bidding with multi-year dedicated capacity agreements tied to carbon reporting. This concentration is most visible in the Rhine-Ruhr logistics cluster, where manufacturing density supports contracted lane economics for zero-emission fleet operators.
Road Haulage Market Segmentation
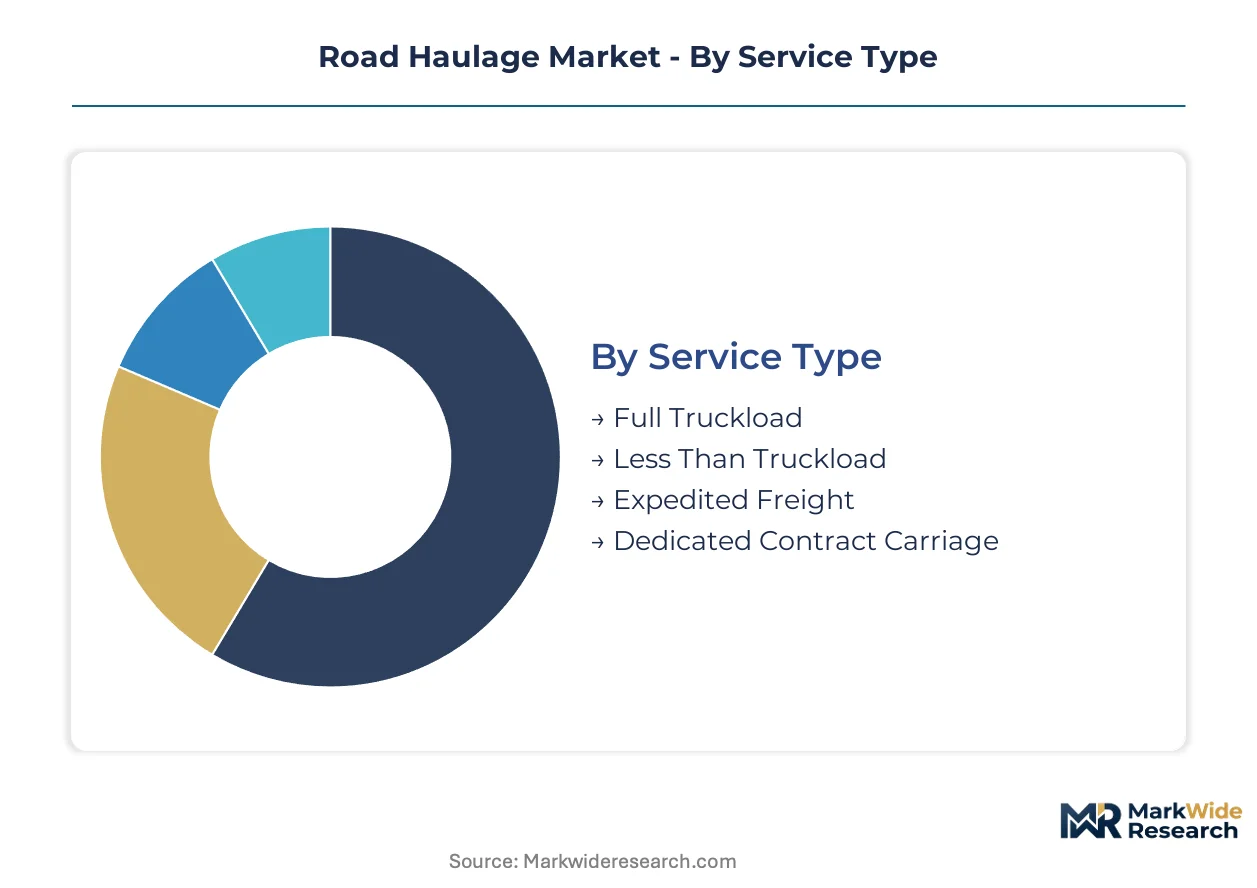
Road haulage segmentation reflects divergent capital intensity and regulatory exposure across service tiers. Fleet operators structure asset portfolios around payload economics and temperature control requirements while navigating divergent compliance timelines for electrification.
Service Type:
EPA Phase 3 and EU Green Deal standards apply asymmetrically across service tiers, with dedicated contract carriage absorbing compliance costs through long-term pricing while spot-market segments face margin compression.
- Full Truckload:Dedicated tractor-trailer capacity moving single-shipper freight from origin to destination without intermediate handling. Retail and automotive manufacturers in Germany's Rhine-Ruhr corridor are locking in multi-year contracts to secure predictable transit windows for just-in-inventory networks.
- Less Than Truckload:Consolidated freight from multiple shippers moving through hub-and-spoke terminal networks. Dense lane economics in the US Southeast and Benelux regions support premium service density investments by asset-heavy operators.
- Expedited Freight:Time-definite delivery with guaranteed transit windows for critical manufacturing components. Aerospace and medical device supply chains in Texas and Baden-Württemberg drive demand for satellite-tracked expedited lanes.
- Dedicated Contract Carriage:Long-term fleet provision with driver and equipment assignment to single shipper accounts. E-commerce fulfillment networks are pulling capacity from spot markets into committed lanes for next-day delivery coverage.
Full Truckload handles the majority of throughput; Dedicated Contract Carriage is gaining share fastest as shippers prioritize capacity certainty over spot-market savings.
Vehicle Type:
Cost tier differentiation separates commodity dry freight from specialized temperature-controlled and liquid bulk equipment requiring advanced monitoring systems.
- Refrigerated Trailers:Insulated van units with integrated refrigeration systems maintaining precise temperature bands for biologics and perishables. Pharmaceutical cold chain expansion across the US Northeast and Ile-de-France is driving refrigerated trailer investment in last-mile handoffs.
- Dry Van Trailers:Enclosed box trailers for non-temperature-sensitive general freight. Standardized dimensions enable intermodal rail compatibility and maximize cubic utilization for retail distribution networks.
- Flatbed Trucks:Open-deck configurations for oversized construction machinery and building materials. Infrastructure stimulus programs in Texas and Florida are accelerating flatbed demand for steel and equipment transport.
- Tankers:Cylindrical vessels for liquid chemicals, food-grade products, and petroleum derivatives. Specialized cleaning protocols and hazardous materials certification create entry barriers for general freight operators.
Refrigerated Trailers command the highest margins per mile; Dry Van Trailers move the largest absolute freight volumes across highway networks.
End User:
Application-specific requirements shape fleet specifications, with manufacturing and retail verticals driving divergent technology adoption timelines for electrification.
- Retail:High-frequency, predictable-lane distribution to distribution centers and fulfillment nodes. Next-day delivery promises are compressing lead times and expanding dedicated contract carriage procurement.
- Manufacturing:Just-in-time component delivery with narrow delivery windows tied to production schedules. Automotive assembly plants in Stuttgart and Detroit require synchronized inbound logistics with minimal inventory buffers.
- Construction:Project-based heavy equipment and materials movement with seasonal demand spikes. Infrastructure investment cycles in Arizona and North Rhine-Westphalia create volatile capacity requirements.
- Agriculture:Seasonal harvest transport and temperature-sensitive produce distribution from growing regions to processing facilities. California Central Valley and Alentejo corridor operations demand flexible fleet scaling.
Retail generates the highest lane density; Manufacturing is expanding most quickly on sustainability-verified carrier procurement.
Payload Capacity:
Volume-maturity segmentation separates established heavy-duty tractor-trailer operations from emerging lightweight electric last-mile configurations.
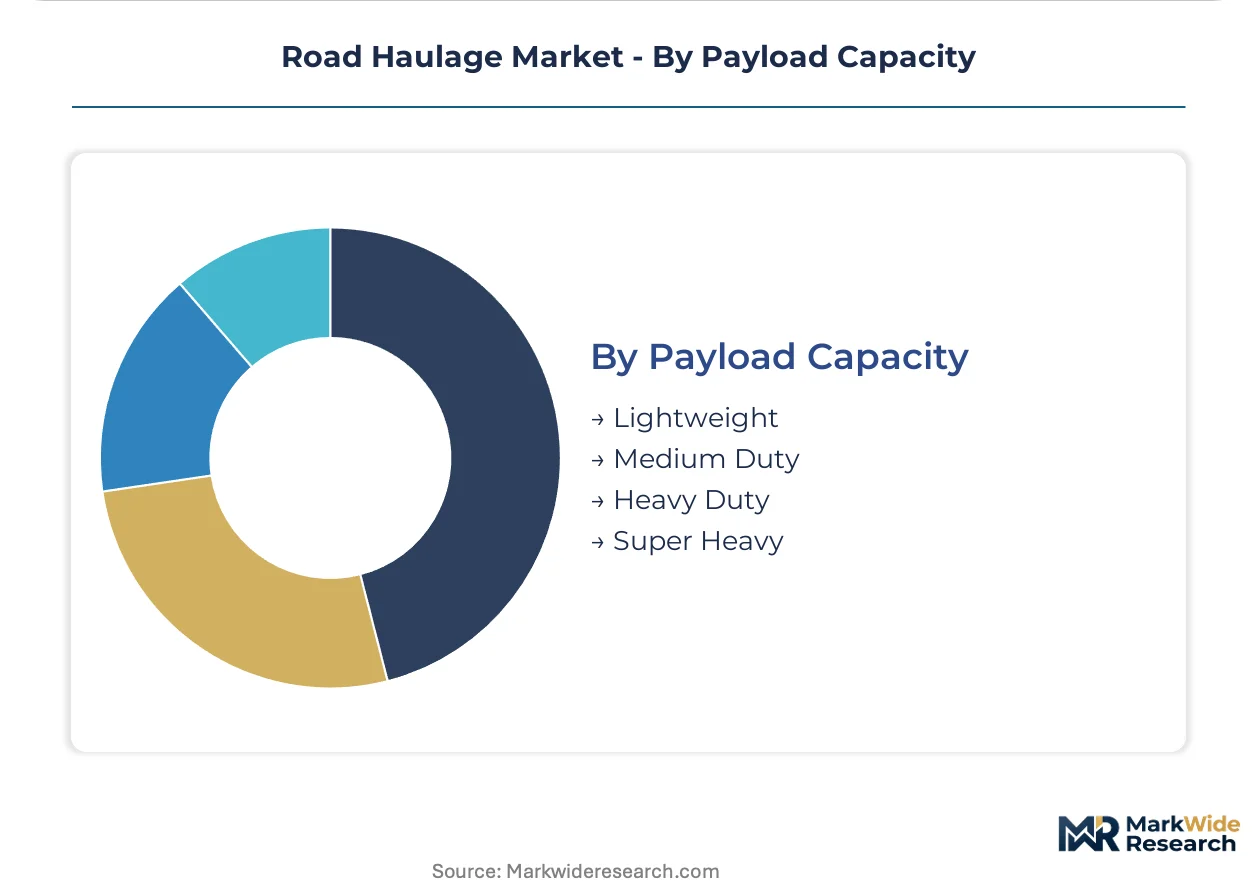
- Heavy Duty:Tractor-trailer combinations with gross vehicle weights between 26,000 and 80,000 pounds. Long-haul corridor economics favor diesel and emerging battery-electric powertrains for US interstate and EU TEN-T network operations.
- Super Heavy:Specialized permit-required combinations exceeding 80,000 pounds for mining equipment and wind turbine components. Escort vehicle requirements and route planning complexity limit competition to specialized operators.
- Medium Duty:Single-unit trucks and smaller tractor configurations for regional distribution and urban freight. California Air Resources Board regulations are accelerating medium-duty electrification in Los Angeles and San Francisco metro areas.
- Lightweight:Van and small truck configurations for final-mile parcel and grocery delivery. E-commerce density in London, Paris, and New York is driving electric van deployment for congestion zone compliance.
Heavy Duty dominates ton-mile production; Lightweight vehicles are climbing the fastest on electrification mandates and urban access restrictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import intensity is redrawing road haulage demand geography. Manufacturing supply chains concentrate freight flows into specific corridors where port connectivity and inland distribution networks intersect.
United States
E-commerce fulfillment networks and automotive component supply chains drive dedicated contract carriage demand. EPA Phase 3 greenhouse gas standards accelerate zero-emission powertrain procurement timelines for interstate operators. The Dallas-Fort Worth metroplex anchors cross-border freight consolidation for Mexican manufacturing integration.
Germany
Rhine-Ruhr manufacturing density and Dutch port connectivity sustain Europe's highest truck-kilometer intensity per capita. EU Green Deal Fit for 55 mandates compress fleet replacement cycles toward battery-electric configurations. Stuttgart's automotive cluster demands synchronized inbound logistics with narrow delivery windows.
China
Domestic consumption expansion and cross-border e-commerce pull capacity into dedicated contract carriage for last-mile fulfillment. MIIT new energy vehicle subsidies accelerate medium-duty electrification in urban freight corridors. Yangtze River Delta port-hinterland connections concentrate super-heavy container movements.
India
Dedicated freight corridor development and industrial zone connectivity expand contract carriage penetration beyond fragmented owner-operator markets. PLI scheme manufacturing incentives concentrate automotive and electronics logistics demand around Chennai and Pune. National logistics policy reforms compress transit documentation delays.
Netherlands
Rotterdam port throughput and Benelux distribution hub status generate Europe's highest trailer-to-population ratio. EU Green Deal fleet standards drive charging infrastructure pooling among Dutch haulage associations. Venlo's logistics park concentration supports pharmaceutical cold chain handoffs to German manufacturing.
Road Haulage Market Key Industry Players
Concentration sits with asset-heavy integrated operators controlling intermodal conversion flows. The vendor base spans three tiers: multinational contract carriage platforms, regional less-than-truckload specialists, and technology-intensive freight brokers. Dominant competitive moves include charging infrastructure partnerships for electrification compliance and strategic alliances with e-commerce fulfillment networks.
Among North American integrated carriers, J.B. Hunt Transport Services and Old Dominion Freight Line exemplify divergent archetypes—multimodal platform control versus dense terminal network density. XPO Inc. occupies a position within the technology-first brokerage tier, matching capacity with shipper demand through real-time platforms.
| Leading Market Players |
|---|
| J.B. Hunt Transport Services |
| XPO Inc. |
| UPS Inc. |
| Old Dominion Freight Line |
| Knight-Swift Transportation |
| FedEx Corp. |
| TFI International |
| Schneider National |
| Ryder System Inc. |
| Others |
Cost & Logistics Intelligence
Forty-five to sixty-day equipment lead times for battery-electric tractors compress fleet replacement cycles and amplify pricing power for OEMs with secured cell supply, while spot-market hauliers absorb margin erosion from diesel price volatility and driver wage inflation.
Pricing Analysis
The customization-premium spread between standard dry van contracts and configured refrigerated or flatbed dedicated carriage runs three hundred to five hundred basis points, reflecting equipment specialization and temperature monitoring bundling. Contract-based long-term offtake dominates, with multi-year dedicated agreements locking in lane economics while spot transactions face acute price differentiation driven by fuel surcharge volatility and driver availability. Pricing pressure stems from lithium-ion battery cost pass-through and electrification capex amortization. Asset-light brokers exhibit highest price sensitivity; pharmaceutical shippers demonstrate lowest, prioritizing temperature integrity over rate negotiation.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell fabrication for electric powertrains, while Germany and the United States concentrate tractor and trailer manufacturing. The supply chain draws from cobalt and lithium extraction in the Democratic Republic of Congo and Chile, plus semiconductor components from Taiwan. Single-source vulnerability in battery cell procurement creates fleet electrification timeline risk for North American and European operators. Distribution runs through OEM-dealer networks for equipment and direct procurement contracts for energy infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Road haulage is restructuring as a service-attach opportunity, with charging infrastructure management and carbon reporting subscriptions expanding faster than tractor hardware sales as fleet operators seek asset-light electrification pathways.
For Market Incumbents: Consolidate terminal density in the Rhine-Ruhr and Dallas-Fort Worth corridors to defend against technology-first brokers capturing intermodal conversion flows. Acquire certified high-voltage technician training programs to address maintenance scarcity before electrification mandates deepen. Lock in long-term green electricity procurement contracts at corridor scale to neutralize carbon compliance cost exposure.
For New Entrants and Emerging Players: Differentiate on battery-swapping standardization for mid-size fleet operators lacking capital for overnight charging infrastructure. Target India's dedicated freight corridors around Chennai and Pune, where contract carriage penetration remains below Western levels and national logistics reforms compress documentation friction. Pursue pharmaceutical cold chain specialization with GDP-compliant temperature monitoring as the go-to-market anchor.
For Investors and Strategic Acquirers: Long-term, this sits as a utility-like infrastructure play because electrification transforms haulage from vehicle ownership into energy-and-mobility service provisioning. Target regional LTL specialists with dense terminal networks in manufacturing corridors. Watch EPA Phase 3 enforcement intensity and EU Green Deal penalty implementation as inflection signals for accelerated fleet replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Pools capital burden for EU Green Deal compliance across German and Dutch haulage associations. |
| Battery Supply Agreement | Secures lithium-ion cell allocation from South Korean producers for zero-emission fleet deployment. |
| Technology Platform Integration | Connects real-time freight matching with shipper ERP systems via API-first brokerage architecture. |
| Geographic Expansion | Captures contract carriage growth in India's PLI-driven manufacturing corridors around Pune. |
| Certification Investment | Builds GDP-compliant cold chain capability for pharmaceutical distribution in the US Northeast. |
Research Approach
Cross-validation between carrier operating data and shipper procurement records anchors the qualitative findings, combining primary interviews with fleet operations directors, shipper logistics managers, charging infrastructure developers, and regulatory compliance officers with secondary validation from EPA filings, EU transport emissions databases, customs trade records, and SEC 10-K disclosures. Bottom-up fleet deployment estimates and top-down modal share analysis triangulate market sizing.
Sensitivity analysis across electrification adoption curves, battery cost trajectories, and driver supply scenarios frames the analytical approach over the projection horizon. Segmentation dimensions include service type, vehicle configuration, payload capacity tier, end-use vertical, and regional regulatory cluster. CAGRs derive from equipment replacement cycle modeling and lane economics analysis, incorporating fuel price elasticity and carbon penalty exposure as industry-specific forecast inputs.
Material uncertainties — battery cell supply disruption, HOS regulation amendments, and autonomous vehicle deployment timelines — sit outside the modeled envelope. Forecasts reflect assumptions around policy enforcement consistency and technology cost curves. Recalibration cycles align with material shifts in EPA Phase 3 implementation and EU Fit for 55 package revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
Brazil Cold Chain Logistics Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Romania Road Freight Transport Market