
 Train Market | 2026-2036
Train Market Size, Share, and Industry Trends Forecast 2026-2036
Train Market Intelligence
Modular trainset configuration is hardening as the dominant procurement model, letting operators mix powered and unpowered cars to match route economics. CRRC Corporation Limited leverages its integrated manufacturing base to deliver fully customized trainsets at scale. Siemens AG anchors European demand through its established electric traction platforms. Alstom SA differentiates via hydrogen and battery-electric variants that address emerging zero-emission mandates.
A train is a self-propelled or externally powered rail vehicle designed to transport passengers or cargo on steel wheel-and-rail systems, with typical configurations ranging from 100 to 400 meters in length and operating speeds from 40 km/h for urban transit to over 350 km/h for high-speed service. Its primary purpose is to provide energy-efficient, high-capacity movement of people and goods over fixed guideway networks. Electric traction now leads technology adoption across intercity and commuter applications, while hybrid systems represent the fastest-growing segment as operators bridge diesel phase-out timelines. Freight trains command substantial margin pools in North American and Russian corridors where bulk commodity volumes sustain long-haul economics.
The EU F-Gas Regulation and REACH framework constrain refrigerant and material choices in European train manufacturing, while the EPA and FRA in the United States enforce Tier 4 emission standards and crashworthiness requirements that shape locomotive design. China's MIIT and GB standards govern domestic rolling stock certification, creating segmented compliance pathways for multinational suppliers. Stakeholders must monitor how diverging carbon accounting rules across these jurisdictions reshape total cost of ownership calculations and sourcing strategies.
Market Dynamics
Modular trainset procurement is forcing suppliers to reconfigure manufacturing footprints around flexible car-body welding and distributed final assembly rather than centralized production lines.
Growth Catalysts
- EU Green Deal emission targets:The framework mandates diesel phase-out timelines that electrify intercity corridors and hydrogen pilots across member states.
- India's Dedicated Freight Corridors:These infrastructure projects generate concentrated locomotive and wagon demand with standardized specifications.
- Battery-electric multiple units:This traction technology opens non-electrified branch lines to zero-emission service without catenary investment.
Market Restraints
- Steel and copper price volatility:Input cost swings compress margin visibility for multiyear build contracts indexed to raw material baskets.
- CRRC supply concentration:Dominance in complete trainset manufacturing creates single-source risk for operators outside China's domestic market.
- REACH chemical compliance:The framework restricts interior material choices and extends homologation timelines for European deliveries.
Strategic Opportunities
- Southeast Asian urban rail:Metro expansions in Vietnam, Indonesia, and the Philippines lack established supplier relationships.
- Freight-as-a-service platforms:Rail operators are unbundling locomotive provision from crew and maintenance in North American corridors.
- EU F-Gas Regulation:The mandate for lower-GWP refrigerants in HVAC systems differentiates compliant trainset configurations.
Industry Challenges
- Electrical traction engineering talent:Shortages in power electronics and motor control specialization delay platform development cycles.
- Legacy signaling integration:New ETCS-equipped trainsets must interoperate with national ATP systems during transitional decades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Market |
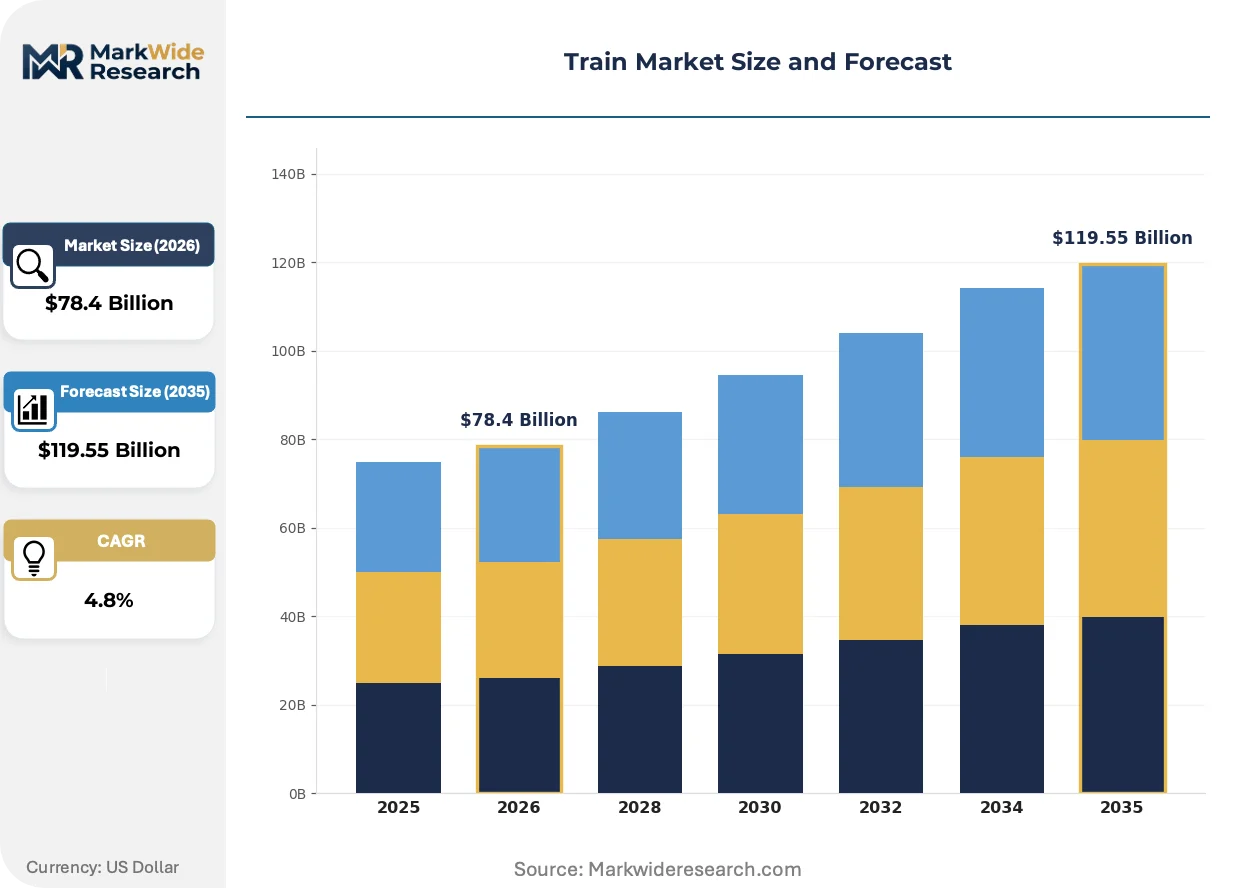
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Trains, Freight Trains, Passenger Trains, Light Rail Technology: Electric Traction, Diesel Traction, Magnetic Levitation, Hybrid Systems End User: Public Transport Authorities, Private Operators, Logistics Companies, Government Agencies Application: Urban Transit, Intercity Travel, Cargo Transport, Commuter Services |
| Companies Covered | CRRC Corporation Limited, Alstom SA, Siemens AG, Stadler Rail AG, Wabtec Corporation, Hitachi Ltd., Kawasaki Heavy Industries Ltd, Nippon Sharyo Ltd, Škoda Transportation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Market Strategic Shifts & Innovations
Digitalization of train control and predictive maintenance is compressing operational cost structures while regulatory pressure on embodied carbon reshapes material specifications.
Condition-based monitoring using axle-mounted sensors and edge computing is automating fault detection in braking and traction systems before depot intervention. European commuter operators are retrofitting existing fleets with these modules to extend asset life. The technology is automating workforce redeployment from scheduled inspections to targeted repairs.
China's MIIT GB standards for intelligent train operation now mandate automated train operation capability in new metro procurements. These rules force multinational suppliers to localize software development and certify against domestic cybersecurity protocols. The regulation most affects Japanese and European incumbents bidding for tier-one city contracts.
Passenger rail authorities are consolidating maintenance contracts into single-source fifteen-year agreements that bundle component supply, labor, and availability guarantees. This displaces the traditional spot-purchase model for brake pads, filters, and bearings. The shift is most advanced in British and Australian commuter networks where franchise structures incentivize whole-life cost optimization.
Train Market Segmentation
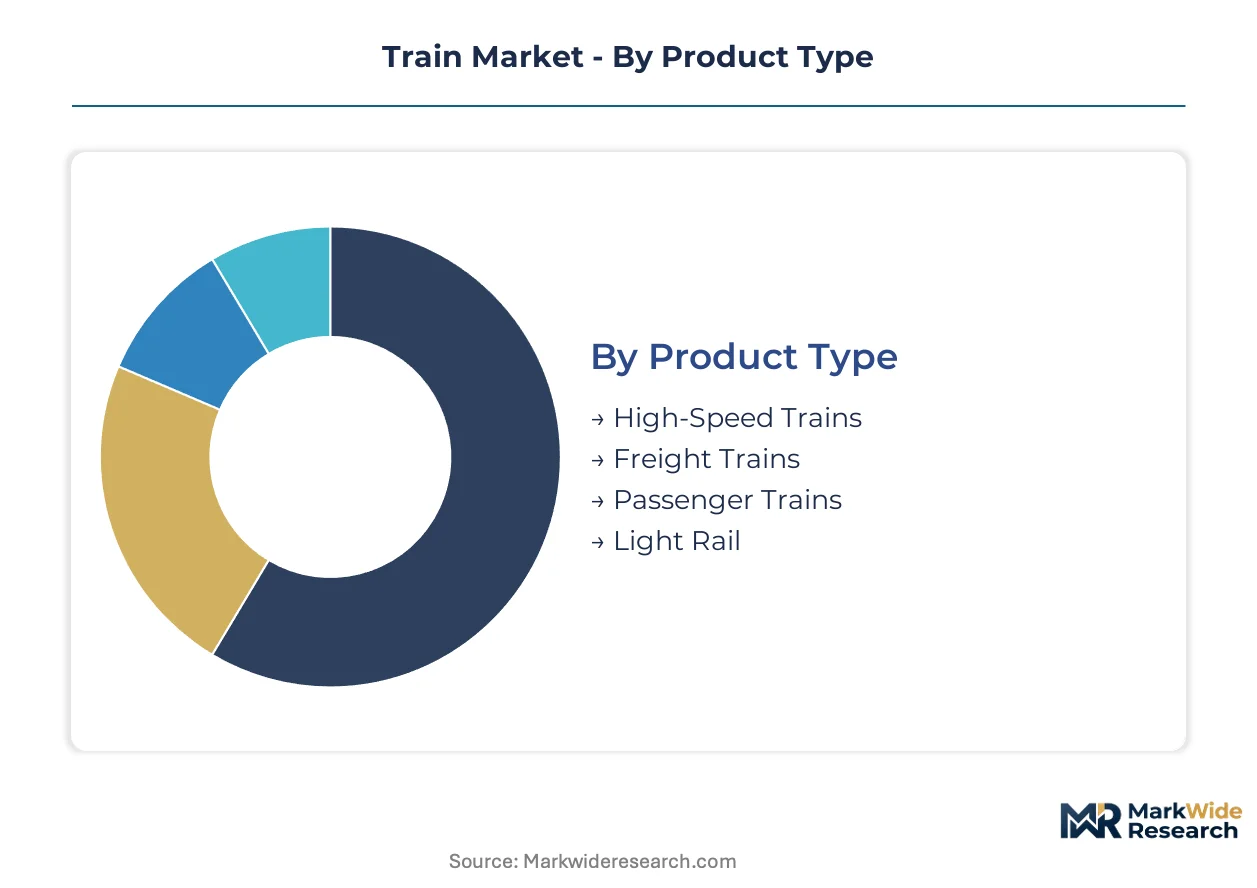
Train procurement patterns diverge sharply across operating environments, with certification requirements and infrastructure compatibility dictating supplier selection. Manufacturers configure platforms around traction technology, route length, and ownership structure rather than pursuing universal designs.
Product Type:
EU Green Deal emission targets and China's GB standards impose divergent certification burdens on each train category, shaping where manufacturers localize production.
- High-Speed Trains:These systems operate at 250-350 km/h on dedicated electrified corridors with automated train protection. China's intercity rail network absorbs the dominant share of new deliveries as provincial governments expand connectivity between tier-one cities. MIIT cybersecurity protocols for intelligent train operation add software localization requirements for foreign suppliers.
- Freight Trains:Heavy-haul configurations move bulk commodities across North American and Russian corridors with diesel-electric or fully electric locomotives. India's Dedicated Freight Corridors generate concentrated demand for standardized electric locomotives with 25-ton axle loads.
- Passenger Trains:Intercity and regional configurations balance seating density with luggage capacity for medium-distance routes.
- Light Rail:Low-floor tramways and streetcars serve urban density corridors with frequent stops and shared rights-of-way.
Freight trains sit at the top of the volume ranking, with high-speed trains climbing the fastest.
Technology:
Cost tier separation between mature traction systems and emerging alternatives determines supplier R&D allocation and operator procurement timelines.
- Electric Traction:Overhead catenary or third-rail systems deliver 85-90% energy efficiency for high-utilization corridors. European operators prioritize these platforms to meet EU Green Deal diesel phase-out mandates, with battery-electric variants extending reach to non-electrified branch lines.
- Diesel Traction:Tier 4 emission standards in the United States and EPA compliance requirements constrain new locomotive designs to exhaust after-treatment systems. North American Class I railroads sustain demand for diesel-electric platforms in long-haul corridors where electrification economics fail.
- Magnetic Levitation:Electrodynamic suspension systems eliminate wheel-rail contact for speeds exceeding 400 km/h on dedicated guideways.
- Hybrid Systems:Dual-mode locomotives switch between diesel and electric operation at network boundaries.
Electric traction dominates current procurement volumes, with hybrid systems gaining share fastest where infrastructure gaps persist.
End User:
Customer type dictates contract structure, with public authorities favoring availability-based agreements and private operators prioritizing capital efficiency.
- Public Transport Authorities:Government-owned entities in France, Germany, and Japan bundle rolling stock procurement with 15-year maintenance contracts. These authorities enforce strict F-Gas Regulation compliance for HVAC systems and REACH material restrictions in passenger interiors.
- Private Operators:British and Australian franchise holders optimize whole-life costs through performance-based leasing structures.
- Logistics Companies:Freight-as-a-service platforms unbundle locomotive provision from crew and maintenance in North American corridors.
- Government Agencies:Defense and border control applications require specialized configurations with hardened communications.
Public transport authorities anchor procurement volumes, with logistics companies expanding fastest through service unbundling.
Application:
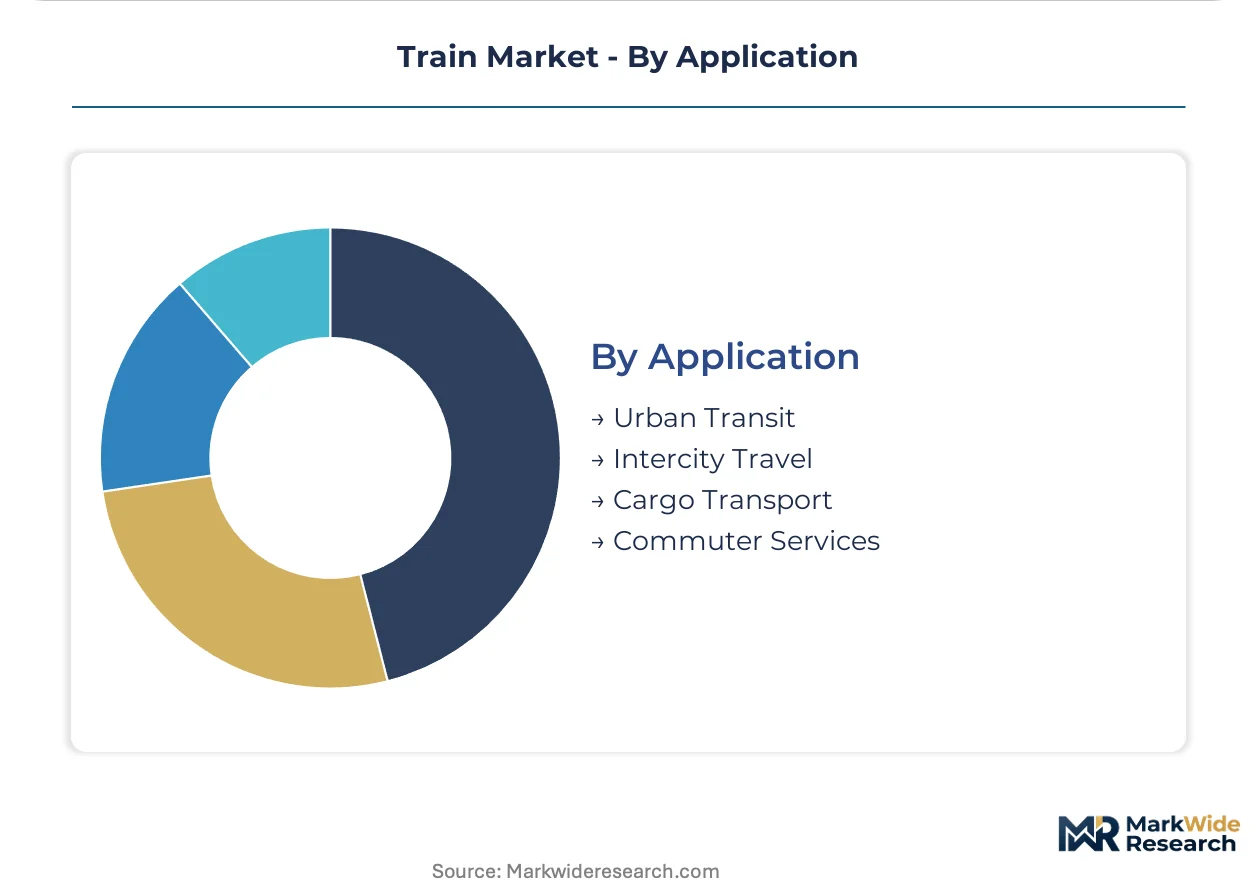
Route length and stop frequency determine trainset configuration, with urban applications demanding rapid acceleration and intercity services prioritizing cruising efficiency.
- Urban Transit:Metro and tram systems require 3-5 minute headways with high passenger throughput per train. China's tier-one cities mandate automated train operation capability under MIIT GB standards, forcing software localization by multinational suppliers.
- Intercity Travel:Services connecting 200-800 km city pairs compete with aviation on journey time and reliability.
- Cargo Transport:Unit trains and manifest freight move bulk commodities and intermodal containers across continental distances.
- Commuter Services:Suburban rail connects residential zones to employment centers with morning and evening peak demand concentration.
Urban transit commands the largest installed base, with cargo transport expanding most quickly through dedicated corridor investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rail manufacturing traces its modern origins to Britain's industrial revolution, with steam locomotive production spreading to Germany, the United States, and Japan by the late 19th century. Today's procurement patterns reflect this historical diffusion, with distinct regional specializations in high-speed passenger systems, heavy-haul freight, and urban transit.
China
Provincial governments are expanding intercity connectivity between tier-one cities through dedicated high-speed corridors. MIIT GB standards mandate automated train operation capability and cybersecurity certification for intelligent train systems. CRRC Corporation leverages its integrated manufacturing base in Changchun and Qingdao to deliver customized trainsets at scale for domestic and export markets.
Germany
Deutsche Bahn's fleet renewal programs and municipal transit authorities sustain demand for electric multiple units and light rail vehicles. EU Green Deal emission targets and F-Gas Regulation compliance requirements shape HVAC system specifications and material choices. Siemens anchors European demand through established traction platforms manufactured at its Krefeld and Vienna facilities.
United States
Class I railroads sustain diesel-electric locomotive demand for long-haul bulk commodity corridors where electrification economics fail. EPA Tier 4 emission standards and FRA crashworthiness requirements constrain new locomotive designs to exhaust after-treatment systems. Wabtec concentrates manufacturing and remanufacturing operations in Pennsylvania and Texas to serve North American freight operators.
India
Dedicated Freight Corridors generate concentrated demand for standardized electric locomotives with 25-ton axle loads for heavy-haul operations. Indian Railways' electrification push and Make in India localization mandates require foreign suppliers to establish domestic joint ventures. Alstom and Siemens have localized production in Bihar and Gujarat to meet procurement requirements for metro and intercity rolling stock.
Japan
Shinkansen network expansion and urban metro renewals sustain premium-tier demand for high-reliability trainsets. METI industrial policy and JIS standards govern domestic certification, creating segmented compliance pathways for multinational suppliers. Hitachi and Kawasaki Heavy Industries concentrate engineering and final assembly in Kobe and Kawasaki for domestic and export high-speed contracts.
Train Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology differentiation and service bundling dimensions. The supplier base organizes into three tiers: integrated systems houses with full trainset capability, component specialists in traction and braking, and regional assemblers serving protected domestic markets. Competitive dynamics center on manufacturing footprint reconfiguration for modular production and long-term service contract capture.
Within the integrated systems tier, CRRC Corporation Limited and Alstom SA exemplify contrasting geographic anchoring strategies—Chinese state-backed scale versus European technology-led positioning. Siemens AG occupies a position bridging both vectors through its established electric traction platforms. These three represent the dominant archetypes: state-integrated champion, technology-differentiated European house, and diversified industrial conglomerate.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Alstom SA |
| Siemens AG |
| Stadler Rail AG |
| Wabtec Corporation |
| Hitachi Ltd. |
| Kawasaki Heavy Industries Ltd |
| Nippon Sharyo Ltd |
| Škoda Transportation |
| Others |
Cost & Logistics Intelligence
Steel and copper input cost volatility propagates through multiyear build contracts indexed to raw material baskets, compressing margin visibility for tier-one manufacturers while forcing procurement officers toward fixed-price clauses with secondary suppliers.
Pricing Analysis
Contract-based long-term offtake agreements dominate high-speed and freight train procurement, with pricing stratifying across premium, standard, and economy tiers based on customization depth and after-sales service bundling. Tier-one operators in Germany and Japan exhibit lowest price sensitivity due to availability guarantees and fifteen-year maintenance contracts, whereas emerging market authorities in Southeast Asia prioritize capital efficiency over service inclusion. Cost compression in the standard tier is intensifying because CRRC's integrated manufacturing base enables aggressive export pricing.
Supply Chain Analysis
Remanufacturing flows for traction motors and braking systems concentrate in Pennsylvania, Texas, and Changchun, where Wabtec and CRRC operate dedicated refurbishment facilities extending component life cycles. Primary manufacturing draws from China, Germany, and Japan for complete trainset assembly, with specialty steel from South Korea and power electronics from Taiwan feeding into motor control systems. Single-source vulnerability around CRRC's dominance in car-body welding creates procurement risk for operators outside China's domestic market. Distribution runs through direct manufacturer-operator relationships for large fleet orders, with component aftermarket flowing via authorized service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The train market represents a late-cycle quality story as public transport authorities consolidate procurement around fifteen-year availability contracts that privilege whole-life cost optimization over upfront capital expenditure.
For Market Incumbents: Cement service contract capture by embedding predictive maintenance modules into new trainset deliveries, insulating against emerging battery-electric specialists. Lock in raw material hedging instruments to offset steel and copper price swings that threaten multiyear build margins. Prioritize certification investment against China's MIIT GB cybersecurity protocols to defend tier-one city positions against domestic champions. For New Entrants and Emerging Players: Enter via Southeast Asian urban rail expansions in Vietnam, Indonesia, and the Philippines where established supplier relationships remain unsettled. Target hydrogen and battery-electric traction segments where zero-emission mandates outpace incumbent platform refresh cycles. Pursue joint development agreements with local engineering firms to satisfy Make in India localization requirements without full manufacturing footprint investment. For Investors and Strategic Acquirers: Consolidation pressure builds where electrical traction engineering talent shortages delay platform development cycles and inflate specialist valuations. Long-term viability favors component specialists in power electronics and motor control with captive relationships to tier-one systems houses. Monitor EU Green Deal diesel phase-out enforcement velocity as inflection indicator for electrification capex acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Manufacturing Footprint Reconfiguration | Flexible car-body welding in distributed final assembly locations reduces logistics costs for CRRC and Siemens. |
| Long-term Service Contract Consolidation | Fifteen-year availability agreements in British and Australian networks displace spot-purchase aftermarket models. |
| Battery-Electric Traction Platform Development | Non-electrified branch line service opens without catenary investment under EU Green Deal timelines. |
| Cybersecurity Certification Localization | MIIT GB standards force Japanese and European suppliers to establish domestic software development centers. |
| Freight-as-a-Service Platform Launch | North American logistics companies unbundle locomotive provision from crew and maintenance operations. |
Research Approach
Bottom-up operator fleet planning reconciled against top-down supplier order book tracking forms the analytical core of this study. Primary interviews with rolling stock procurement directors, maintenance contract managers, railway authority planning officers, and component aftermarket specialists were validated against secondary sources including MIIT GB standard filings, EU F-Gas Regulation compliance disclosures, EPA Tier 4 certification records, and customs trade data for steel and copper inputs.
Input-output matrices map traction technology adoption rates against infrastructure electrification timelines and regulatory mandate enforcement across the projection horizon. Segmentation dimensions include product type, traction technology, end-user ownership structure, and application environment, with CAGRs derived from rolling stock delivery schedules and fleet replacement cycles. Forecast inputs incorporate raw material price index trajectories and REACH chemical compliance cost escalators.
The model holds under stable regulatory enforcement and infrastructure investment continuity; deviation in EU Green Deal diesel phase-out acceleration or China's intercity rail subsidy levels would shift volume distributions. Practitioners should monitor steel and copper price volatility indices and cybersecurity certification timeline extensions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
Global Passenger Cars Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Luxury Vehicles Market