
 Driverless Cab Service Market | 2026-2036
Driverless Cab Service Market Size, Share, and Industry Trends Forecast 2026-2036
Driverless Cab Service Market Foresight
The EU Green Deal is rebalancing procurement criteria for urban mobility fleets across European metropolitan areas. Waymo leverages its accumulated real-world mileage advantage to sustain operational credibility in Arizona and California deployments. Baidu anchors its position through vertical integration into proprietary AI chip design and mapping infrastructure. Zoox differentiates via its purpose-built bidirectional vehicle architecture optimized for dense urban corridors.
Driverless cab service denotes commercial passenger transport delivered by vehicles operating without human drivers, relying on sensor arrays generating 360-degree environmental perception at refresh rates exceeding 10 Hz and decision latency below 100 milliseconds. The primary commercial purpose is to reduce per-mile operating costs while extending service availability beyond human driver shift limitations. Lidar-based technology configurations currently occupy the premium tier of fleet deployments, while computer vision approaches compete on hardware cost reduction for mass-market scalability. Ride-hailing service models dominate current revenue generation, though shuttle services represent the fastest-expanding segment for campus and airport corridor applications.
The National Highway Traffic Safety Administration in the United States sets federal safety benchmarks for autonomous vehicle deployment, while the California Public Utilities Commission governs commercial service permits for passenger operations. The EU AI Act introduces conformity requirements for algorithmic decision-making in transport applications, directly affecting market access timelines. Stakeholders must monitor how evolving liability frameworks redistribute risk between fleet operators, technology suppliers, and municipal insurers.
Market Dynamics
Fleet operators confront a fundamental restructuring as municipal liability frameworks shift accident responsibility from human drivers to algorithmic systems and their corporate deployers. This reallocation of risk is compressing insurance structures and forcing technology suppliers to absorb operational exposure previously borne by individual contractors.
Growth Catalysts
- EU AI Act conformity pathways:The European Union's algorithmic accountability requirements are creating certification benchmarks that reduce regulatory ambiguity for cross-border service expansion.
- Last-mile shuttle corridors:Airport and corporate campus networks are deploying autonomous shuttles to close connectivity gaps where traditional transit density proves economically unviable.
- Lidar cost curves:Solid-state sensor manufacturing advances are collapsing hardware expenses for 360-degree environmental perception systems.
Market Restraints
- Compute chip supply concentration:Advanced driver-assistance processors rely on fabrication capacity concentrated in Taiwan and South Korea, exposing fleet scaling timelines to geopolitical disruption.
- NHTSA incident reporting thresholds:Mandatory disclosure requirements for autonomous vehicle crashes generate public perception volatility that constrains consumer trial rates.
- Human-supervised fallback costs:Remote operator centers required for edge-case intervention maintain labor overhead that erodes projected per-mile operating advantages.
Strategic Opportunities
- India urban mobility corridors:Metropolitan congestion pricing experiments in Bangalore and Mumbai are creating regulatory openings for autonomous fleet pilots in high-density corridors.
- V2X infrastructure convergence:Vehicle-to-everything communication protocols are converging with 5G network rollouts to enable coordinated intersection traversal.
- Japan Olympic corridor legacy:Automated transport infrastructure deployed for Tokyo 2020 is converting to permanent commercial service routes in Kansai and Chubu regions.
Industry Challenges
- Simulation-to-reality validation gaps:Synthetic training environments fail to capture edge-case scenarios involving adversarial human driver behavior, forcing expensive on-road mileage accumulation.
- HD mapping refresh cycles:High-definition road data requires continuous update pipelines that strain operational budgets when construction frequency accelerates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driverless Cab Service Market |
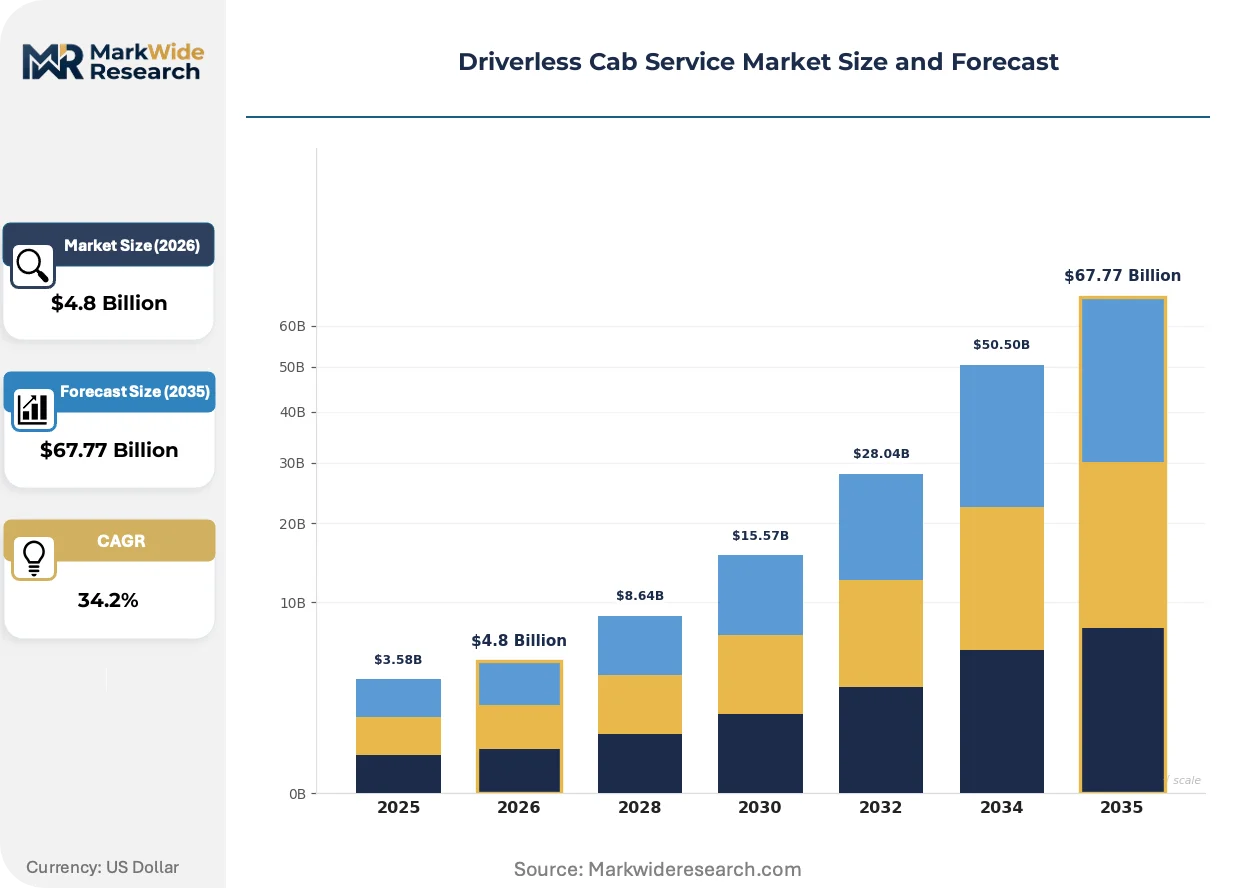
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $67.77 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedans, SUVs, Vans, Compact Cars Technology: Lidar, Computer Vision, AI Algorithms, Sensor Fusion Service Model: Ride-Hailing, Shuttle Services, Delivery Services, Fleet Management End User: Private Users, Corporate Clients, Public Transport, Logistics Companies |
| Companies Covered | Waymo, Cruise, Baidu, Zoox, WeRide, Pony.ai, AutoX, Motional, May Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driverless Cab Service Market Shifts & Advancements
Sensor fusion architectures are actively displacing single-modality perception stacks as fleet operators demand redundancy against environmental edge cases. This hardware evolution is compressing development timelines and reshaping supplier hierarchies.
Lidar point-cloud processing is converging with neural radiance field reconstruction to enable real-time 3D scene understanding without pre-mapped infrastructure dependence. Autonomous fleet operators in Arizona and California are deploying these integrated perception stacks for unmapped rural corridor testing. The technology convergence is collapsing the historical advantage of HD mapping incumbents.
The EU AI Act's risk-classification framework for transport algorithms is mandating conformity assessment procedures that extend market access timelines by 12-18 months. European metropolitan procurement committees are embedding these certification requirements into RFP evaluation criteria. German and French fleet operators are front-loading documentation investment to secure first-mover positioning in Paris and Berlin service launches.
Corporate mobility managers are consolidating vendor relationships around integrated fleet-management platforms that bundle autonomous shuttle scheduling with existing employee transit benefits. This procurement consolidation is displacing point-solution providers who lack enterprise software integration capabilities. The pattern is most visible in North American technology campus deployments where facilities teams control transportation budget authority.
Driverless Cab Service Market Segmentation
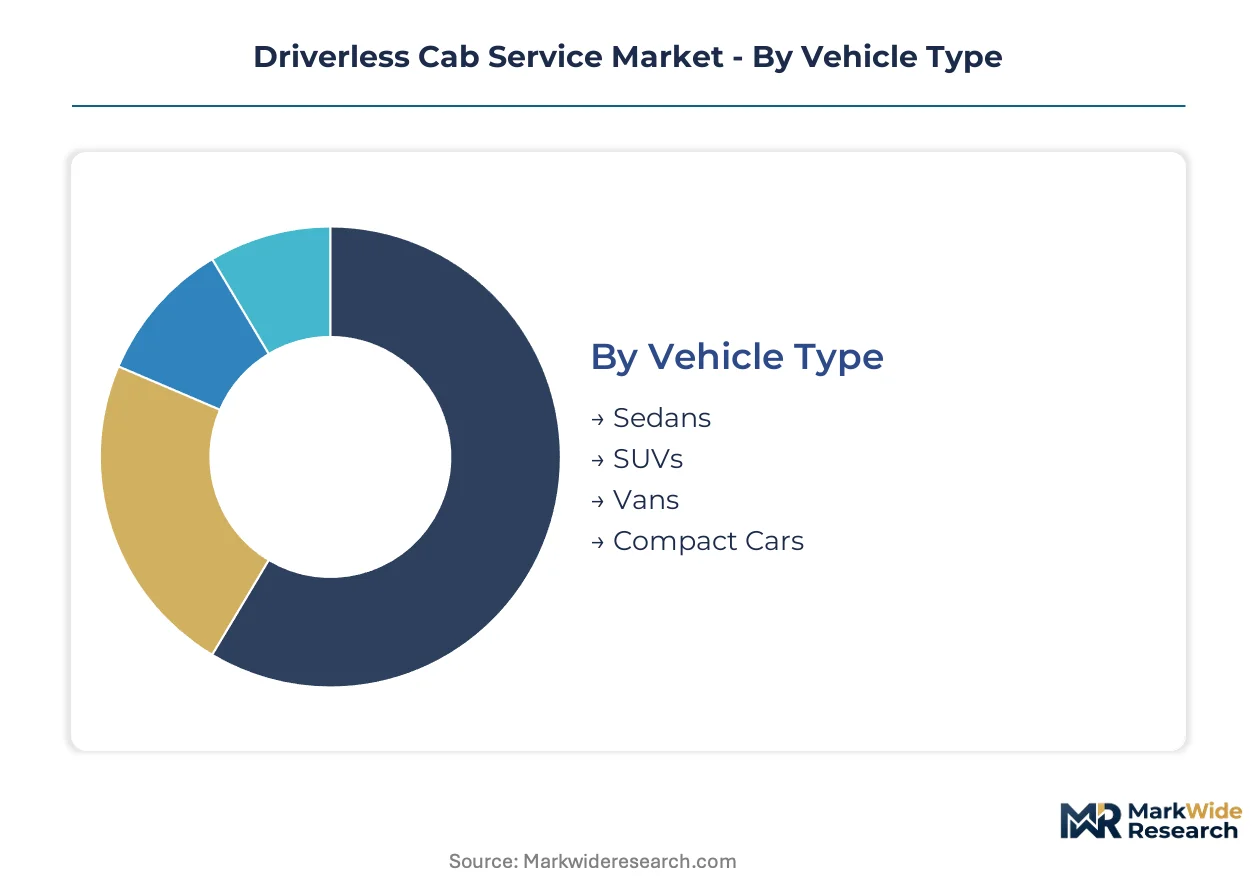
Segmentation in driverless cab services reveals how capital deployment, technical complexity, and regulatory exposure vary across operational configurations. Fleet operators use these divisions to allocate sensor hardware investments and match vehicle specifications to corridor density and trip distance profiles.
Vehicle Type:
Capital intensity peaks with larger passenger configurations requiring redundant sensor arrays and extended battery range for all-day commercial cycling.
- Sedans:Mid-size passenger vehicles deploy streamlined sensor pods with 120-degree forward lidar coverage for highway corridor operations. Demand concentrates in Arizona and California suburbs where single-occupant commutes dominate trip requests and parking infrastructure is abundant.
- SUVs:Higher-roof platforms accommodate multi-lidar configurations with 360-degree environmental perception and enhanced thermal management for sensor compute loads. Fleet operators in San Francisco prioritize this segment for premium ride-hailing tiers where passenger volume and luggage capacity justify per-mile rate premiums.
- Vans:Wheelchair-accessible configurations with lowered floor ramps and dedicated securement zones for paratransit-eligible passengers.
- Compact Cars:Short-wheelbase urban runabouts optimized for dense grid navigation with minimal turning radius and reduced sensor mounting complexity.
Sedans absorb the bulk of installed capacity; SUVs are expanding most quickly.
Technology:
Hardware cost structures and software development timelines diverge sharply between perception modalities, shaping how operators stage fleet rollouts.
- Lidar:Solid-state and mechanical spinning arrays generate dense point clouds for centimeter-level localization in GPS-denied urban canyons. Procurement concentrates among premium fleet tiers in California where NHTSA safety benchmarks mandate redundant environmental sensing for commercial permits.
- Computer Vision:Camera-only stacks leverage convolutional neural networks for object detection at hardware costs below lidar equivalents by an order of magnitude. Chinese operators deploy this approach for mass-market scalability in high-density corridors where infrastructure familiarity reduces edge-case frequency.
- AI Algorithms:Behavioral prediction models and motion planning frameworks processing sensor inputs into driving decisions.
- Sensor Fusion:Multi-modality integration architectures combining lidar, radar, and camera feeds for fault-tolerant perception.
Lidar carries the heaviest upfront hardware burden; computer vision is climbing the fastest as solid-state manufacturing matures.
Service Model:
Revenue predictability and operational control vary across customer relationship structures, influencing how operators finance fleet acquisition.
- Ride-Hailing:On-demand passenger transport matching individual trip requests through mobile applications with dynamic pricing algorithms. Demand concentrates in San Francisco and Phoenix where municipal regulators have issued commercial service permits for fully autonomous operations without human safety drivers.
- Shuttle Services:Fixed-route, scheduled passenger transport along defined corridors with predetermined stops and dwell times. Corporate campuses in North America are expanding pilot fleets for employee transit benefits where last-mile connectivity gaps persist between transit hubs and office clusters.
- Delivery Services:Autonomous goods transport with modified vehicle configurations for cargo compartment security and temperature control.
- Fleet Management:Vehicle-as-a-service platforms providing autonomous capacity to third-party operators under subscription or per-mile arrangements.
Ride-Hailing dominates current revenue generation; Shuttle Services are gaining share fastest in campus and airport corridor applications.
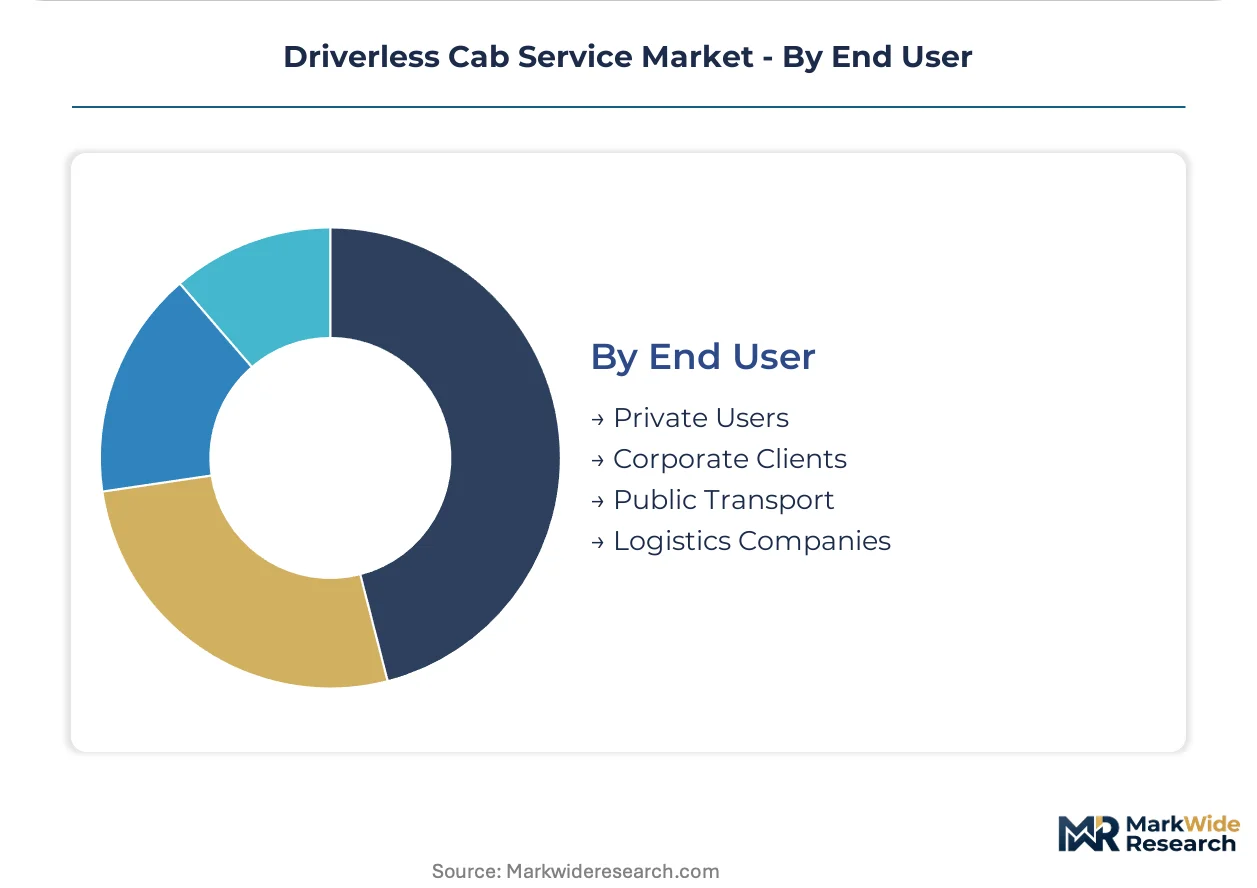
End User:
Procurement authority and trip purpose shape how operators configure service tiers and price accessibility.
- Private Users:Individual consumers accessing on-demand transport through personal mobile accounts with stored payment credentials. Demand concentrates in early-deployment cities where consumer trial rates respond to NHTSA incident reporting transparency and municipal safety track records.
- Corporate Clients:Enterprise mobility managers consolidating vendor relationships around integrated fleet-management platforms bundling autonomous shuttle scheduling with existing employee transit benefits. Facilities teams at North American technology campuses control transportation budget authority and prioritize vendors with enterprise software integration capabilities.
- Public Transport:Municipal transit authorities procuring autonomous capacity to supplement fixed-route bus networks.
- Logistics Companies:Freight and parcel carriers deploying autonomous vehicles for middle-mile and last-mile goods movement.
Corporate Clients absorb the bulk of contracted fleet capacity; Private Users are expanding most quickly as municipal service permits proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors commercial deployment activity through municipal permits for fully autonomous passenger operations without human safety drivers. Fleet operators concentrate sensor validation and consumer trial programs in this corridor. Regulatory precedents established here propagate to adjacent state jurisdictions.
United States
Arizona and California host the densest pilot fleet concentrations for highway corridor testing and urban grid navigation. The NHTSA mandates crash reporting thresholds that shape public disclosure practices and consumer perception management. Phoenix and San Francisco municipal regulators issue commercial service permits that allow fare collection from autonomous operations.
China
Metropolitan congestion pricing in Beijing and Shanghai accelerates regulatory openings for autonomous fleet deployment in designated high-density corridors. The MIIT governs intelligent vehicle standards and cross-provincial testing permits for commercial service expansion. Baidu anchors operations in Wuhan and Chongqing through vertical integration into mapping infrastructure and proprietary AI chip design.
Germany
The KBA administers type approval for autonomous vehicle systems under EU harmonized technical standards. Stuttgart and Munich automotive clusters supply lidar hardware and sensor fusion engineering to global fleet operators. The EU AI Act conformity pathways extend market access timelines by 12-18 months for algorithmic accountability certification.
Japan
METI coordinates automated transport infrastructure conversion from Olympic corridor legacy deployments to permanent commercial routes. The Kansai and Chubu regions host fixed-route shuttle services connecting airport terminals to urban cores. Toyota City and Nagoya manufacturing bases supply vehicle platforms modified for autonomous sensor integration.
United Kingdom
London transport authorities procure autonomous capacity to supplement fixed-route bus networks in outer borough connectivity gaps. The national automated vehicle regulatory framework permits supervised trials on public roads with safety operator presence. Milton Keynes and Cambridge host campus shuttle pilots for employee transit benefit programs.
Driverless Cab Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sensor hardware sophistication and accumulated real-world mileage validation. The vendor base stratifies into three tiers: technology-integrated fleet operators, component-specialist suppliers, and platform-agnostic service enablers. Dominant competitive moves include strategic partnerships for compute chip supply security and geographic licensing agreements for HD mapping data access.
Within the integrated fleet operator tier, Waymo and Cruise exemplify archetypes built on accumulated real-world mileage advantages and municipal permit holdings in Arizona and California. Baidu anchors the China-based contingent through upstream control over AI chip design and captive mapping infrastructure. Zoox occupies a distinctive position via purpose-built vehicle architecture optimized for dense urban bidirectional navigation.
| Leading Market Players |
|---|
| Waymo |
| Cruise |
| Baidu |
| Zoox |
| WeRide |
| Pony.ai |
| AutoX |
| Motional |
| May Mobility |
| Others |
Supply & Pricing Matrix
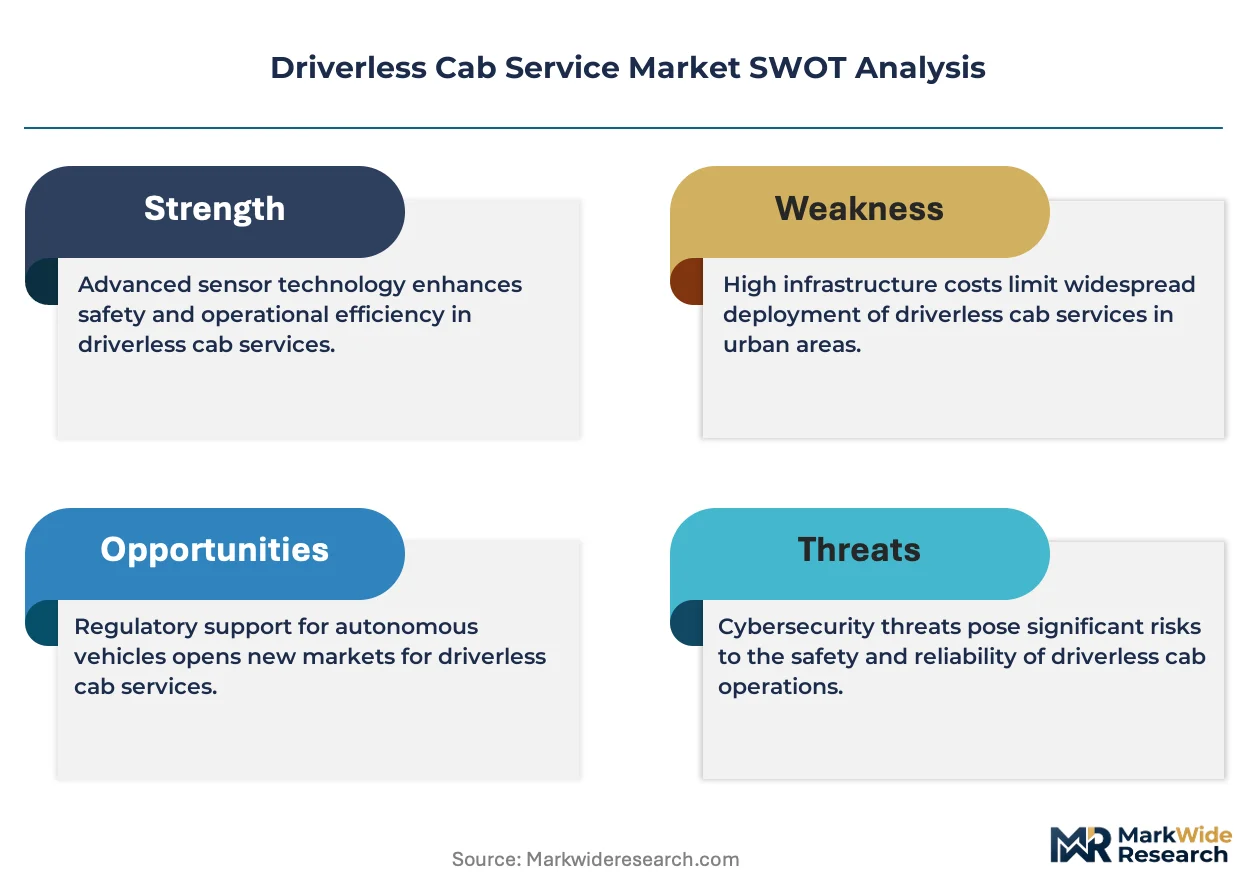
Captive integration into proprietary lidar manufacturing and AI chip design anchors supply positioning and pricing power for fleet operators deploying at commercial scale. Waymo and Baidu leverage this backward integration to compress hardware costs while maintaining premium service tiers, whereas operators dependent on external sensor suppliers absorb margin pressure from concentrated fabrication capacity.
Pricing Analysis
Uptime-based pricing anchors revenue models, with fleet operators charging per-mile rates that scale with vehicle availability guarantees rather than hardware depreciation schedules. Three-tier pricing structure across premium, standard, and economy levels separates SUV configurations with redundant 360-degree sensing from streamlined sedan pods and compact urban runabouts. Pricing pressure stems from solid-state lidar cost curves collapsing hardware expenses for 360-degree environmental perception systems. Corporate mobility managers exhibit lowest price sensitivity due to bundled procurement authority, while individual private users respond to municipal safety track records and NHTSA incident transparency.
Supply Chain Analysis
Specialized engineering talent availability in Taiwan, South Korea, and Germany constrains expansion timelines for advanced driver-assistance processor fabrication and solid-state lidar manufacturing. The supply chain draws from rare earth elements for sensor magnetics, high-purity silicon for AI compute chips, and lithium-ion cells for extended-range battery configurations. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing capacity for neural processing units. Distribution runs through direct OEM partnerships for vehicle platform modification and tiered supplier networks for sensor component integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic conformity pathways have erected a cost-of-compliance barrier that favors incumbents with documentation investment capacity and front-loaded certification timelines.
For Market Incumbents: Anticipate regulatory fragmentation as municipal liability frameworks redistribute accident responsibility from human drivers to algorithmic deployers. Absorb operational exposure through captive insurance structures while consolidating HD mapping data access through geographic licensing agreements. Prioritize sensor fusion R&D to maintain redundancy advantages against camera-only entrants. For New Entrants and Emerging Players: Corporate campus mobility managers represent an underserved buyer archetype with consolidated procurement authority and integrated fleet-management platform requirements. Penetrate North American technology campus shuttle corridors where facilities teams control transportation budgets and last-mile connectivity gaps persist. Deploy purpose-built bidirectional vehicle architectures optimized for dense urban grid navigation. For Investors and Strategic Acquirers: Exit pathways concentrate in technology-integrated fleet operators with accumulated real-world mileage validation and municipal permit holdings across multiple jurisdictions. Long-term viability hinges on upstream control over AI chip design and mapping infrastructure rather than point-solution sensor hardware. Watch NHTSA incident reporting thresholds as inflection indicators for consumer trial rate volatility and public perception management.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary AI Chip Development | Baidu's vertical integration into Kunlun processors reduces dependency on Taiwan fabrication capacity. |
| Municipal Permit Expansion | Waymo leverages Arizona and California commercial service authorizations to anchor operational credibility. |
| HD Mapping Data Licensing | Geographic exclusivity agreements with municipal authorities collapse competitor market access timelines. |
| Sensor Fusion Architecture Deployment | Multi-modality integration mandates compress development timelines and reshape supplier hierarchies. |
| Corporate Campus Shuttle Pilots | Facilities teams at North American technology campuses consolidate vendor relationships around integrated platforms. |
Research Methodology
Independent corroboration across fleet operations executives, municipal regulatory affairs leads, sensor hardware procurement directors, and insurance risk underwriters underwrites the qualitative findings. Primary interviews with autonomous vehicle program managers at technology-integrated operators and remote operator center supervisors supplemented secondary validation through NHTSA crash reporting databases, California Public Utilities Commission permit filings, EU AI Act conformity assessment documentation, and municipal transit authority RFP archives. Bottom-up fleet deployment tallies triangulated against top-down mobility service revenue estimates.
Comparable-period anchoring to accumulated real-world mileage validation and commercial permit issuance dates structured the forecast window across the analysis window. Segmentation dimensions modeled include vehicle type, perception technology modality, service model configuration, and end-user procurement authority. CAGRs derived from logistic diffusion curves for autonomous fleet penetration and hardware cost decay functions for solid-state sensor manufacturing. Forecast inputs incorporated lidar point-cloud processing convergence with neural radiance fields and V2X infrastructure rollout timelines.
Revisions become necessary when municipal liability frameworks materially reallocate accident responsibility, geopolitical disruption constrains Taiwan or South Korea fabrication capacity, or EU AI Act conformity timelines extend beyond current certification benchmarks. Forecasts reflect assumptions regarding sensor cost curves, regulatory permit proliferation, and consumer trial rate responsiveness to incident transparency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
India Autonomous Navigation Market
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Autonomous Navigation Sensing System Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
Africa Autonomous Navigation Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
L4 Autonomous Driving Market