
 US Tolling Market | 2026-2036
US Tolling Market Size, Share, and Industry Trends Forecast 2026-2036
US Tolling Market Outlook
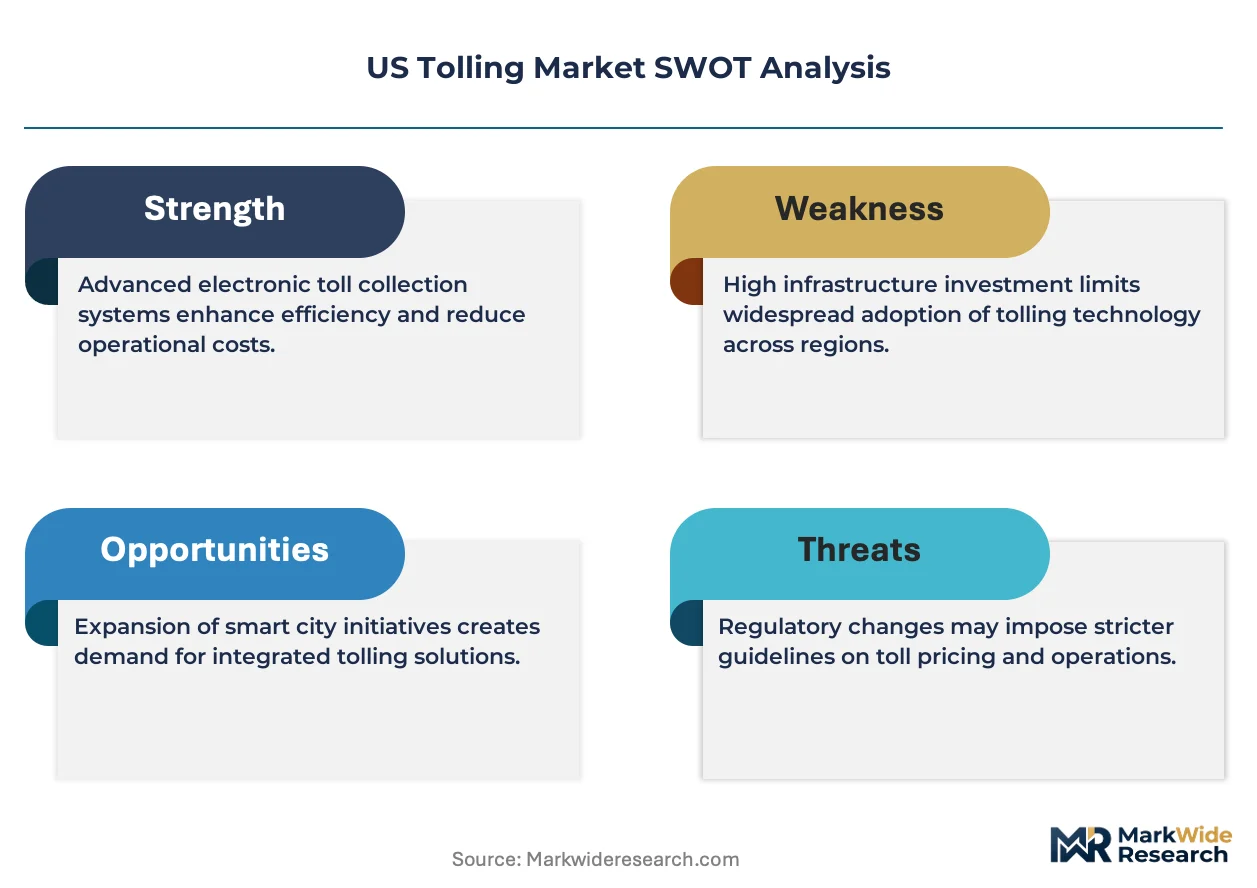
Public-private partnership financing and availability-payment structures are reshaping competitive entry in the US tolling sector, lowering capital barriers for technology vendors relative to traditional infrastructure concessionaires. Verra Mobility Corporation leverages its dominant position in automated enforcement and tolling services across multiple state contracts. TransCore sustains its integrated advantage through captive manufacturing of RFID transponder hardware and lane systems. Kapsch TrafficCom AG competes on European-hardened back-office platforms adapted for multi-agency US deployments.
Tolling encompasses the automated or manual collection of fees from vehicles using designated roadways, bridges, or tunnels, typically employing radio-frequency identification, video analytics, or barrier-gated systems to process transactions at speeds up to highway velocity. Electronic Toll Collection leads technology deployment as agencies eliminate cash handling, while License Plate Recognition grows fastest where retrofitting legacy infrastructure avoids full lane reconstruction. Cloud-Based deployment models are displacing On-Premise installations among mid-sized transportation authorities seeking operational expenditure flexibility, though Hybrid architectures persist where legacy mainframe integration remains necessary for customer account management.
The Federal Highway Administration oversees tolling eligibility under 23 U.S.C. § 129, while individual state legislatures govern revenue allocation and rate-setting authority, creating a fragmented compliance landscape that vendors must navigate contract by contract. The Infrastructure Investment and Jobs Act expands federal loan programs for toll-backed projects, directly shaping procurement timelines across state departments of transportation. Stakeholders must monitor evolving state privacy statutes governing license plate data retention, as these rules determine back-office architecture requirements and ongoing compliance costs for system operators.
Market Dynamics
Federal funding acceleration through the Infrastructure Investment and Jobs Act is compressing procurement timelines for state transportation authorities, while all-electronic tolling mandates are forcing capital reallocation away from cash-handling infrastructure.
Growth Catalysts
- IIJA Loan Expansion:Federal credit assistance programs under 23 U.S.C. § 129 are unlocking project finance for managed lane expansions across Texas and Florida corridors.
- Congestion Pricing Pilots:California metropolitan planning organizations are advancing dynamic pricing on interstate access points, creating demand for real-time transaction processing systems.
- RFID Transponder Standardization:Multi-state interoperability agreements are reducing account fragmentation and driving replacement cycles for legacy tag hardware.
Market Restraints
- Copper and Semiconductor Input Costs:Lane system manufacturing faces margin pressure from volatile commodity pricing for RFID antenna components and video processing chipsets.
- State Legislative Fragmentation:Revenue allocation authority varies across 50 state statutes, forcing vendors to maintain jurisdiction-specific compliance architectures.
- Privacy Statute Divergence:License plate data retention rules differ materially between California Consumer Privacy Act frameworks and Texas transportation codes, complicating back-office design.
Strategic Opportunities
- Cloud Migration Among Mid-Sized Agencies:Operational expenditure models are penetrating state DOTs below top-ten population tiers, displacing capital-intensive on-premise deployments.
- Managed Lane Network Convergence:Dynamic pricing algorithms and HOV enforcement systems are merging procurement scopes, favoring integrated platform vendors.
- Video Analytics Retrofit Cycles:License Plate Recognition upgrades are avoiding full lane reconstruction costs for cash-constrained authorities in secondary metropolitan areas.
Industry Challenges
- Legacy Mainframe Integration:Hybrid cloud architectures require specialized middleware talent scarce among transportation technology vendors.
- Interoperability Certification Timelines:Multi-state tag compatibility testing extends deployment schedules and strains project delivery commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Tolling Market |
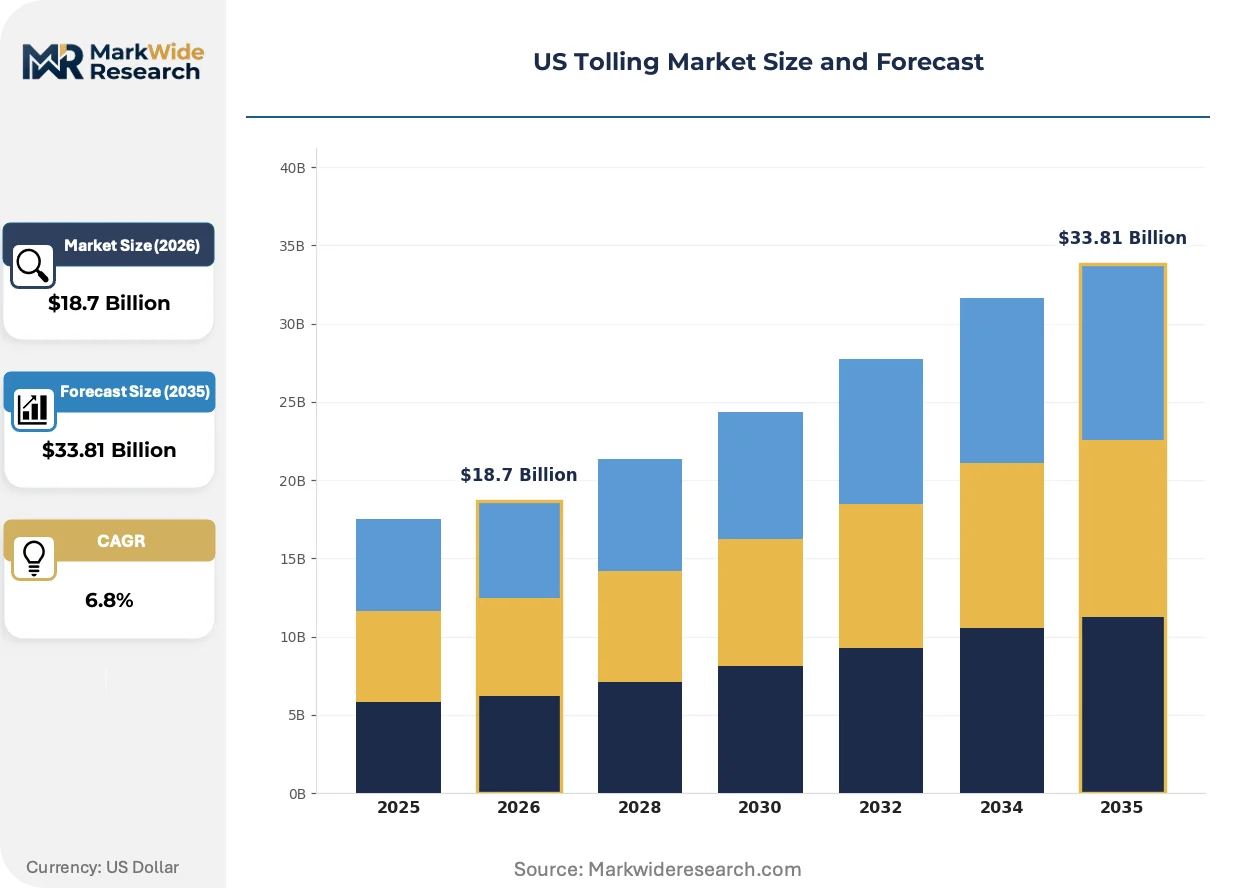
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electronic Toll Collection, Manual Toll Collection, Hybrid Systems, License Plate Recognition Deployment Model: Cloud-Based, On-Premise, Hybrid, Mobile Solutions Service Type: Transaction Processing, Data Management, Customer Support, System Maintenance End User: Government Agencies, Private Operators, Transportation Authorities, Highway Authorities |
| Companies Covered | Siemens Mobility GmbH, Verra Mobility Corporation, Conduent Inc., Neology Inc., TransCore, Cubic Corporation, Thales Group S.A., ST Engineering Ltd., Kapsch TrafficCom AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Tolling Market Strategic Shifts
Transaction processing architectures are pivoting toward real-time cloud-native platforms, while enforcement modalities are converging video analytics with automated violation management.
Multi-protocol transponder systems are migrating from single-standard RFID tags toward dual-frequency units compatible with both 6C and ISO 18000-6B protocols. State transportation authorities in high-traffic corridors are mandating backward compatibility to preserve existing account bases. This migration from proprietary standards is compressing hardware replacement cycles and consolidating vendor qualification lists around interoperable platform providers.
The Federal Highway Administration's expanded tolling eligibility guidance under IIJA implementation is accelerating public-private partnership structures for greenfield corridor development. State legislatures are responding with enabling statutes for availability-payment concessions. Texas and Florida DOTs are most affected, embedding performance-based maintenance clauses into twenty-year system operation contracts.
Transportation authorities are unbundling back-office operations from lane hardware procurement, separating account management from toll collection infrastructure. Mid-sized state DOTs are engaging managed services providers for customer service and violation processing. This shift is most visible in California's regional tolling agencies, where operational expenditure contracts are displacing capital ownership models for customer-facing functions.
US Tolling Market Segmentation
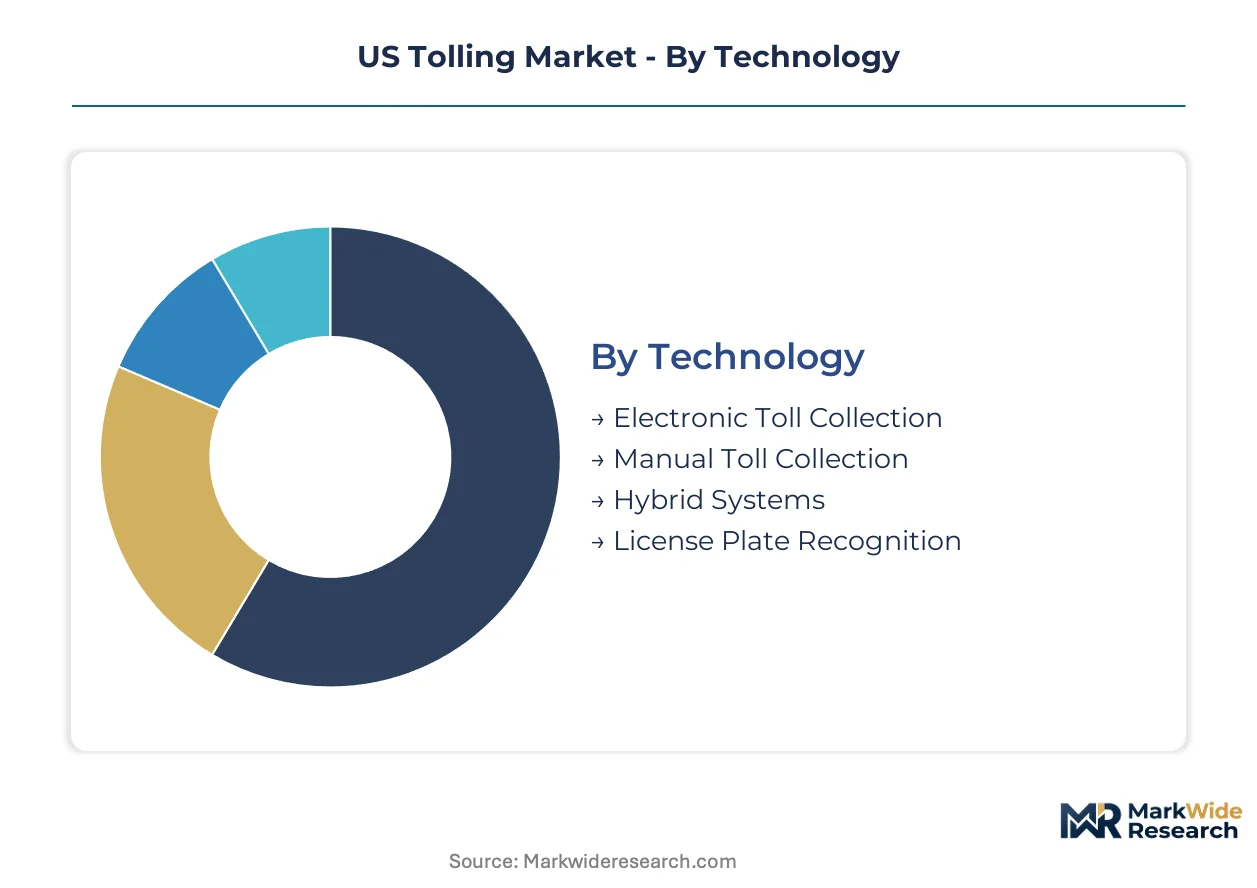
Technology deployment and service delivery models in the US tolling sector determine procurement scope, operational expenditure profiles, and compliance architecture requirements for state transportation authorities. Segment boundaries are blurring as agencies unbundle lane infrastructure from back-office operations and migrate toward managed services frameworks.
Technology:
Collection modalities span the velocity spectrum from highway-speed electronic processing to barrier-gated manual lanes, with retrofit economics driving hybrid adoption patterns across state DOTs.
- Electronic Toll Collection:RFID transponder systems process transactions at highway velocity without vehicle deceleration, with demand concentrating in Texas and Florida where all-electronic mandates are eliminating cash infrastructure. Multi-state interoperability agreements are accelerating hardware replacement cycles for legacy proprietary tags.
- License Plate Recognition:Video analytics capture plate data for post-pay account linking or violation enforcement, expanding fastest in California metropolitan areas where congestion pricing pilots require real-time vehicle identification without transponder dependency. Privacy statute divergence across state lines complicates back-office design for multi-jurisdiction deployments.
- Manual Toll Collection:Cash-handling infrastructure with human operators persists in legacy corridor segments where capital constraints delay full electronic conversion, concentrated among secondary metropolitan authorities.
- Hybrid Systems:Dual-mode lanes accommodating both electronic tags and cash payment preserve operational flexibility during transition periods, favored by agencies with mixed fleet populations.
The dominant share belongs to Electronic Toll Collection, while License Plate Recognition is gaining share fastest among agencies prioritizing retrofit economics over full lane reconstruction.
Deployment Model:
Capital ownership structures are yielding to operational expenditure models as mid-sized transportation authorities seek budget cycle flexibility and reduced on-site infrastructure maintenance.
- Cloud-Based:SaaS architectures for transaction processing and customer account management eliminate data center capital requirements, penetrating state DOTs below top-ten population tiers where IT staffing constraints favor externalized operations.
- Hybrid:Split architectures maintain sensitive customer data on-premise while offloading compute-intensive analytics to cloud instances, addressing legacy mainframe integration requirements that persist in established tolling programs.
- On-Premise:Fully captive infrastructure remains concentrated among the largest regional authorities with established data center investments and specialized compliance teams.
- Mobile Solutions:Smartphone-based toll payment applications serve occasional users without transponder accounts, expanding through white-label partnerships between technology vendors and state agencies.
Cloud-Based deployments command the largest expansion trajectory, though Hybrid architectures retain sticky adoption where legacy system interdependencies resist full migration.
Service Type:
Functional unbundling is separating customer-facing operations from technical infrastructure, enabling specialized vendor qualification for distinct competency domains.
- Transaction Processing:Real-time toll calculation and payment authorization at lane speed, with demand anchored in high-volume corridors requiring sub-second latency guarantees and 99.999% uptime SLAs.
- Data Management:Account lifecycle operations including registration, replenishment, and reconciliation, increasingly contracted to managed services providers under operational expenditure frameworks.
- Customer Support:Call center and digital channel operations for account inquiries and dispute resolution, frequently outsourced to vendors with multi-agency scale economies.
- System Maintenance:Field service for lane hardware, communications infrastructure, and back-office platform upkeep, often bundled with original equipment procurement under performance-based contracts.
Transaction Processing captures the dominant revenue share, while Data Management is climbing the fastest as agencies externalize customer account operations.
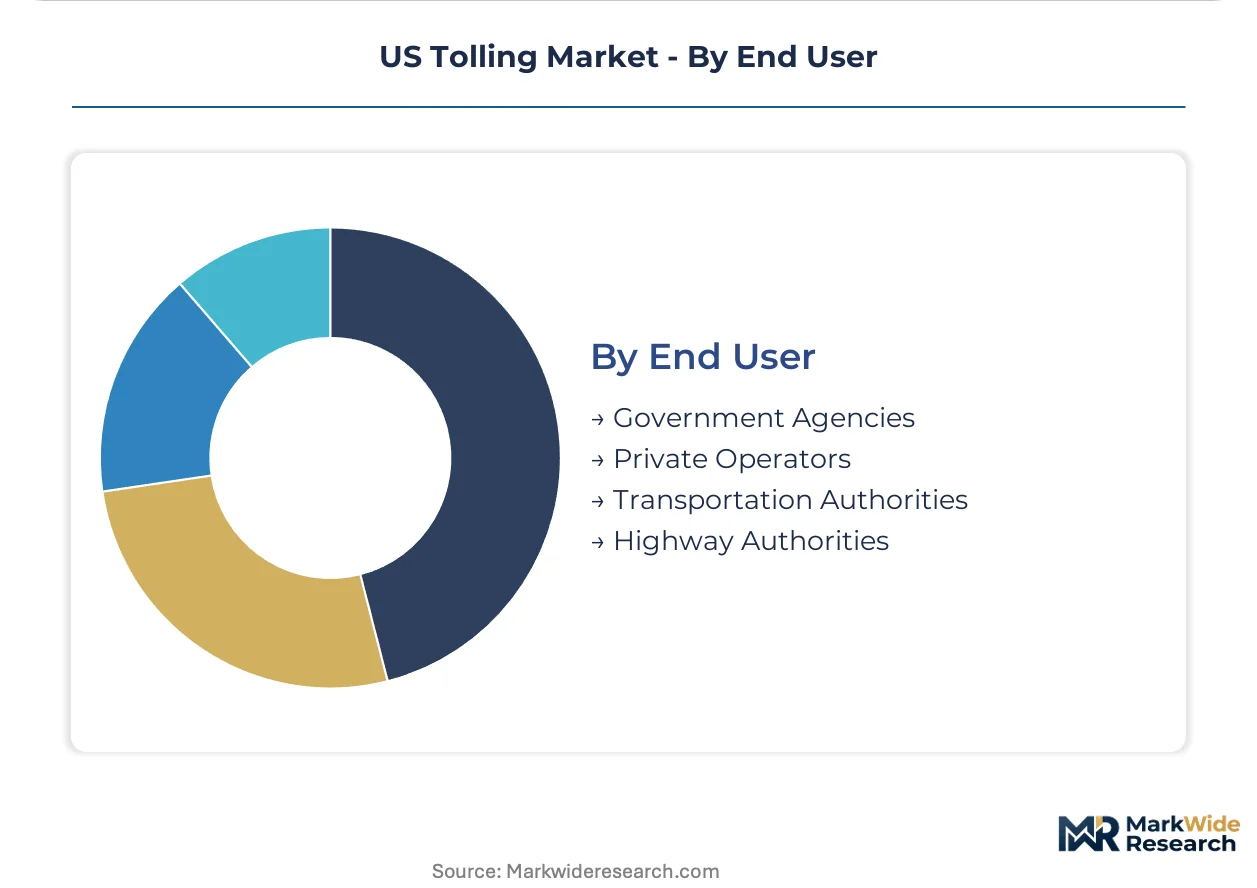
End User:
Procurement authority fragmentation across government levels creates multiple entry points with distinct contracting vehicles and compliance requirements.
- Transportation Authorities:Multi-county regional entities operating established toll networks, concentrated in California and Texas with consolidated procurement for lane systems and back-office platforms.
- Government Agencies:State departments of transportation deploying tolling on federally aided interstate corridors, leveraging IIJA loan programs for managed lane expansions.
- Highway Authorities:Single-corridor or bridge-specific operators with narrower procurement scopes and higher vendor switching frequency.
- Private Operators:Concession holders under availability-payment or revenue-risk structures for greenfield developments, most active in Florida and Texas P3 frameworks.
Transportation Authorities represent the largest addressable base, though Private Operators are expanding most quickly under IIJA-enabled concession structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California command divergent procurement premiums, with Lone Star corridor expansions extracting steeper availability-payment terms than Golden State congestion pricing pilots. This asymmetry reflects state-level P3 maturity and legislative appetite for revenue-risk transfer.
Texas
Managed lane networks around Dallas-Fort Worth and Houston generate sustained demand for multi-protocol transponder systems. The Texas Department of Transportation leverages IIJA loan programs under 23 U.S.C. § 129 for SH 288 and LBJ Express expansions. Austin-based regional mobility authorities are unbundling back-office operations from lane infrastructure procurement.
California
Metropolitan Planning Organizations in Los Angeles and the Bay Area advance dynamic congestion pricing on interstate access points. The California Consumer Privacy Act governs license plate data retention rules for video analytics deployments. Orange County and San Diego transportation corridors concentrate retrofit demand for license plate recognition upgrades.
Florida
Turnpike Enterprise expansions and regional tollway authorities in Orlando and Tampa drive all-electronic conversion mandates. Florida DOT enabling statutes for availability-payment concessions attract private operator participation. Miami-Dade and Broward counties anchor demand for integrated managed lane and HOV enforcement systems.
Illinois
The Illinois State Toll Highway Authority maintains one of the nation's largest legacy transponder account bases requiring interoperability upgrades. State legislation governs revenue allocation between tollway operations and regional transit subsidies. Chicago metropolitan corridor expansions concentrate demand for hybrid cloud back-office architectures.
New York Metro
The Metropolitan Transportation Authority and Port Authority of New York and New Jersey operate converged bridge-tunnel networks with multi-state interoperability requirements. Federal Highway Administration oversight of Hudson River crossing tolling shapes procurement compliance frameworks. New Jersey Turnpike Authority expansions drive demand for real-time transaction processing platforms.
US Tolling Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying RFID transponders, video analytics modules, and lane hardware. The vendor landscape organizes into three tiers: full-service concessionaires bundling finance, construction, and operations; technology platform vendors delivering interoperable back-office and lane systems; and component suppliers providing specialized sensors, antennas, and processing chipsets. Strategic moves concentrate on public-private partnership qualification and cloud-native platform certification for mid-sized state DOT procurement.
Among integrated platform providers, Verra Mobility Corporation and TransCore occupy positions spanning automated enforcement and tolling services across multiple state contracts. Kapsch TrafficCom AG represents the European-hardened back-office archetype adapted for multi-agency US deployments. These three anchors exemplify competitive positioning around interoperability certification, captive hardware manufacturing, and managed services scale respectively.
| Leading Market Players |
|---|
| Siemens Mobility GmbH |
| Verra Mobility Corporation |
| Conduent Inc. |
| Neology Inc. |
| TransCore |
| Cubic Corporation |
| Thales Group S.A. |
| ST Engineering Ltd. |
| Kapsch TrafficCom AG |
| Others |
Value Chain & Pricing Dynamics
RFID antenna manufacturing concentration in Taiwan and South Korea concentrates margin capture among lane system integrators, while copper and semiconductor input volatility forces mid-sized state DOTs toward operational expenditure models that transfer component price risk to vendors.
Pricing Analysis
Configured-to-order lane systems command 15-25% premiums over standard catalog configurations, reflecting agency-specific compliance architectures and legacy mainframe integration requirements. Three-tier pricing structure across premium interoperability-certified, standard multi-protocol, and economy single-frequency hardware tiers dominates hardware procurement. Pricing pressure stems from copper and video processing chipset commodity volatility compressing margins on fixed-price installation contracts. Private operators under availability-payment structures exhibit lowest price sensitivity, while secondary metropolitan authorities with federal formula funding constraints drive hardest bargain negotiations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates component sourcing strategy for video analytics modules and RFID transponder chipsets. Lane system manufacturing draws from Taiwan, Mexico, and domestic US assembly for final integration, with semiconductor fabrication anchored in South Korea and Taiwan. Single-source vulnerability concentrates in specialized toll-grade camera sensors and 6C protocol RFID chipsets. Distribution runs through state DOT procurement offices and regional transportation authority RFP processes, with original equipment manufacturers maintaining direct field service organizations for performance-based maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across 50 state regulatory frameworks creates niche entry points for specialized compliance vendors, as unbundling of back-office operations from lane hardware multiplies contract opportunities below tier-one incumbent dominance.
For Market Incumbents: Insulate installed base relationships through captive interoperability certification programs and backward integration into transponder manufacturing to offset semiconductor supply volatility. Texas and Florida DOT consolidation of managed lane procurement favors vendors with twenty-year performance-based maintenance track records. Cloud-native platform certification for mid-sized agencies below top-ten population tiers represents the priority defensive investment area. For New Entrants and Emerging Players: California metropolitan planning organizations implementing congestion pricing pilots represent the most penetrable entry point, given real-time transaction processing requirements that strain legacy incumbent architectures. License plate recognition retrofit cycles in secondary metropolitan areas offer hardware-light deployment paths avoiding full lane reconstruction capital barriers. White-label smartphone toll payment applications for occasional users provide channel partnership routes bypassing direct state DOT qualification timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed tolling technology platforms acquired during prior infrastructure privatization waves. Five-to-ten year viability hinges on cloud migration completion rates among state DOT customer bases. Monitor IIJA loan program utilization velocity as inflection indicator for greenfield corridor development pipeline depth.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Investment | Multi-state tag compatibility testing accelerates procurement qualification for Texas and Florida corridor expansions. |
| Cloud-Native Platform Migration | SaaS transaction processing displaces on-premise deployments among mid-sized transportation authorities seeking operational expenditure flexibility. |
| License Plate Recognition Retrofit Cycles | Video analytics upgrades avoid full lane reconstruction costs for cash-constrained authorities in secondary metropolitan areas. |
| Managed Services Unbundling | Customer account operations outsourcing separates revenue streams from capital-intensive infrastructure ownership. |
| Public-Private Partnership Qualification | Availability-payment concession structures in Texas and Florida embed twenty-year system operation contracts with performance clauses. |
Study Parameters
Desk research of Federal Highway Administration tolling eligibility guidance, state legislative statutes, and IIJA implementation documents preceded structured interviews with state DOT procurement officers, regional transportation authority technology directors, toll system integrator program managers, and back-office managed services providers. Secondary validation drew from FHWA project databases, state transportation improvement program filings, and vendor contract disclosure records. Bottom-up lane system deployment tracking and top-down federal funding allocation analysis were triangulated against primary interview intelligence.
Assumptions held fixed across the analysis window include IIJA loan program continuity and multi-state interoperability agreement durability, while variables tested included state privacy statute divergence pace and copper/semiconductor input cost trajectories. Segmentation modeling incorporated technology modality, deployment architecture, service unbundling depth, and end-user procurement authority tier. CAGRs were derived from corridor expansion pipeline quantification and replacement cycle timing analysis, with federal funding acceleration schedules and congestion pricing pilot conversion rates as key demand-side inputs.
Practitioners should monitor state legislative sessions for privacy statute amendments affecting license plate data retention rules, IIJA reauthorization negotiations, and semiconductor supply chain normalization indicators for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
US Reverse Logistics Market
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
Colombia Road Freight Transport Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Boxcar Scars Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
Train Collision Avoidance System Market
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
Hungary Road Freight Transport Market