
 Railway Brake Pads Market | 2026-2036
Railway Brake Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Brake Pads Market Insights
Market Context
Chinese specialty foundries is decoupling from European composite pad supply as domestic rail OEMs expand captive production. Knorr-Bremse leverages its integrated braking systems portfolio to anchor fleet renewal contracts across Deutsche Bahn and SNCF networks. Wabtec Corporation competes on North American freight retrofit programs where its cast iron formulations dominate Class I railroad specifications. Nabtesco Corporation specializes in precision metallic blends for Japan's Shinkansen depots, sustaining technical barriers against commodity imports.
Technical Definition and Segment Structure
Railway brake pads are friction elements engineered from sintered metallic powders, organic resins, or ceramic composites, designed to dissipate kinetic energy through controlled wear against cast iron or steel brake discs at operating temperatures exceeding 600°C. These components ensure stopping compliance for rolling stock ranging from 40-ton freight wagons to 16-car high-speed trainsets under varying adhesion and thermal load conditions. Composite pads command premium positioning in European passenger fleets where REACH restrictions on copper content reshape material specifications, while cast iron retains volume leadership across emerging-market freight operators prioritizing unit cost over thermal performance. Ceramic segments occupy niche growth trajectories in light rail and metro applications where reduced wheel and rail wear offset higher procurement outlays.
Regulatory Framework
Europe's ECHA REACH restrictions on copper particulate emissions and the EU Green Deal's embedded carbon requirements compel reformulation investments across friction material suppliers seeking CE-marked market access. China's GB/T rail standards and NMPA-equivalent rail safety certifications mandate domestic testing protocols that filter non-compliant imports from CRRC supply chains. India's BIS certification for brake components and CEA rail safety directives tighten as the Dedicated Freight Corridor scales operations, forcing OEMs and aftermarket distributors to align quality systems with evolving national specifications. Stakeholders must monitor divergence between EU copper-free mandates and other jurisdictions' slower regulatory timelines when allocating R&D and regional manufacturing capacity.
Market Dynamics
Europe's ECHA REACH copper restrictions and China's GB/T rail standards are forcing simultaneous material reformulation and domestic supply chain reconfiguration across friction manufacturers serving multinational rolling stock OEMs.
Growth Catalysts
- High-speed rail expansion:China's intercity corridor buildout and India's Dedicated Freight Corridor modernization generate sustained procurement volumes for high-performance brake systems.
- REACH copper mandates:European low-copper and copper-free friction formulations create premium product differentiation opportunities for compliant suppliers.
- Thermal management advances:Ceramic composite materials enable extended service intervals in metro and light rail applications where wheel wear reduction justifies higher unit costs.
Market Restraints
- Raw material volatility:Copper, nickel, and rare earth element price swings compress margin predictability for sintered metallic pad producers.
- Supply concentration:Chinese captive foundry production limits market access for European composite pad exporters serving CRRC supply chains.
- Technical substitution limits:Cast iron formulations retain cost advantages in freight applications where thermal performance thresholds remain below 400°C.
Strategic Opportunities
- India aftermarket buildout:Dedicated Freight Corridor scaling creates demand for localized brake pad remanufacturing and depot-level inventory positioning.
- EU embedded carbon compliance:Green Deal lifecycle assessment requirements favor suppliers with low-carbon sintering processes and regional manufacturing footprints.
- Predictive maintenance integration:Sensor-enabled brake wear monitoring converges with fleet telematics platforms to enable condition-based replacement scheduling.
Industry Challenges
- Multi-jurisdiction certification:Divergent testing protocols between ECHA REACH, China's NMPA-equivalent rail safety framework, and India's BIS standards extend product qualification timelines.
- Legacy fleet compatibility:New low-copper formulations must demonstrate equivalent braking performance across aging rolling stock with cast iron discs and varied adhesion conditions.
Report Scope
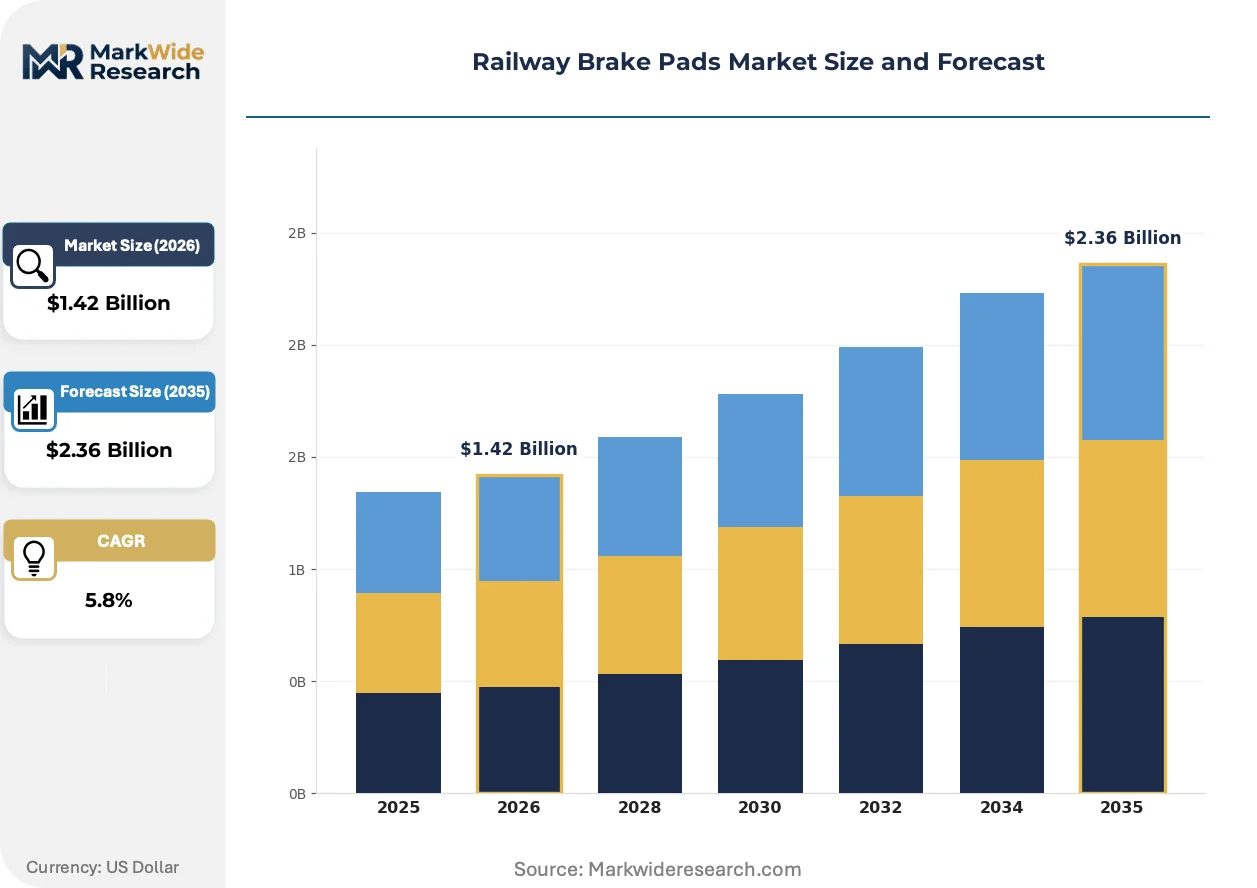
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Brake Pads Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite, Cast Iron, Ceramic, Steel Application: Freight Trains, Passenger Trains, High-Speed Trains, Light Rail Technology: Friction Materials, Semi-Metallic, Organic, Metallic End User: OEMs, Aftermarket, Railway Operators, Maintenance Providers |
| Companies Covered | EBC Brakes, Bremskerl, Knorr-Bremse, Tenneco Braking, Tribo, Wabtec Corporation, CRRC Qishuyan Institute, Nabtesco Corporation, Akebono Brake Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Brake Pads Market Trends and Innovations
Material science breakthroughs and regulatory chemistry mandates are compressing traditional friction formulation cycles while digitizing fleet maintenance protocols reshape aftermarket demand patterns.
Sintered metallic-ceramic hybrid formulations are consolidating technical leadership in high-speed passenger applications where thermal loads exceed 600°C. Deutsche Bahn and SNCF network specifications now prioritize these blends for fleet renewal contracts. The technology is consolidating supplier tiers by eliminating smaller foundries lacking vacuum sintering capabilities.
EU Green Deal embedded carbon requirements and ECHA REACH copper particulate limits compel reformulation investments across CE-marked suppliers. Industrial consequence includes accelerated R&D spend on copper-free binders and recycled content verification systems. European passenger OEMs respond by dual-sourcing from compliant domestic producers and audited Asian contract manufacturers.
Condition-based replacement scheduling displaces fixed-interval maintenance across Class I freight operators and urban transit agencies. Traditional distributor stocking models face compression as direct sensor-to-depot data flows enable just-in-time inventory positioning. North American freight retrofit programs and Japanese Shinkansen maintenance depots exhibit the most advanced adoption of this operational shift.
Railway Brake Pads Market Segmentation
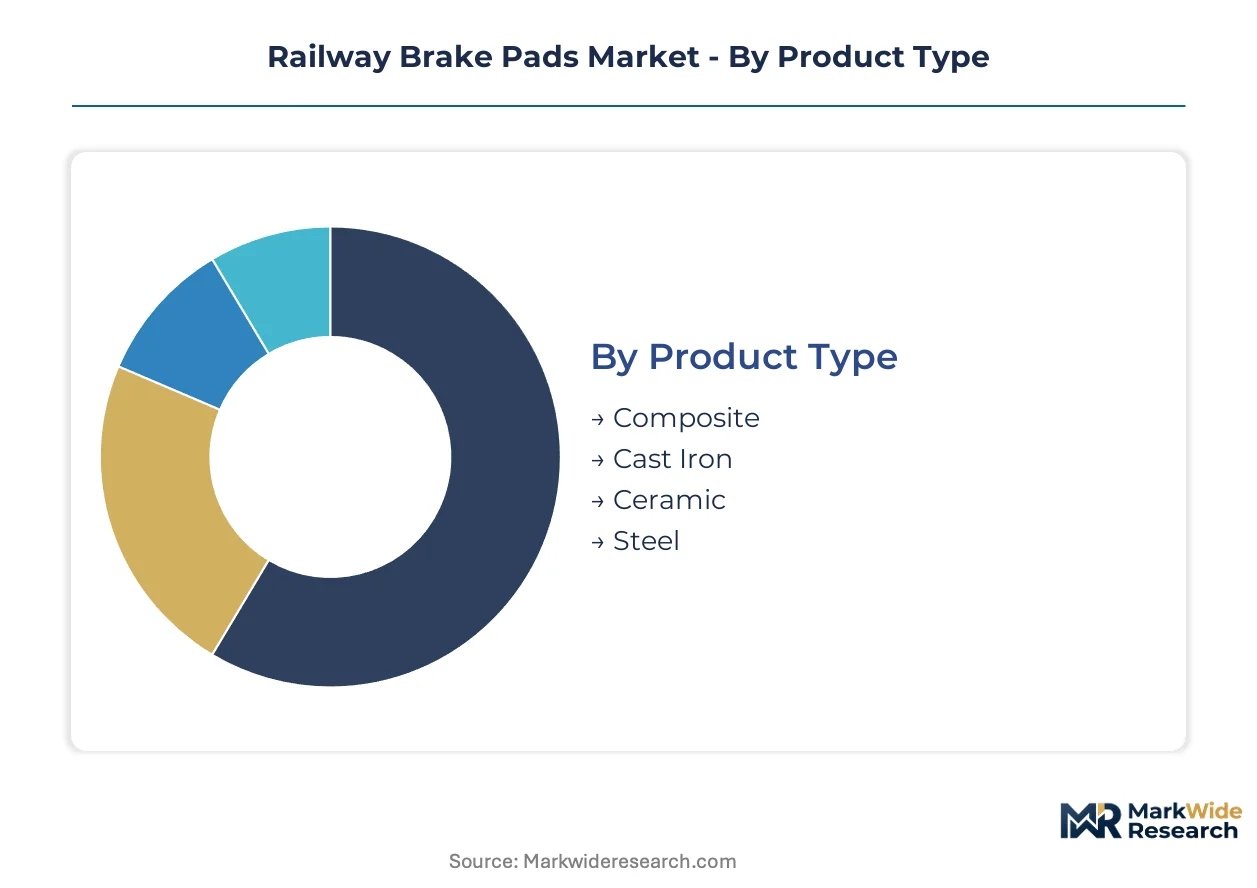
Railway brake pad procurement splits across thermal performance requirements, regulatory compliance tiers, and fleet lifecycle positioning. Material selection and channel strategy determine margin profiles and qualification barriers for friction suppliers serving multinational rolling stock markets.
Product Type:
Customization intensity spans from commodity cast iron to engineered ceramic composites, with formulation complexity dictating supplier qualification depth and pricing power.
- Composite:Engineered from resin-bonded fibers and friction modifiers, these pads balance thermal stability against wear rates in European passenger fleets. ECHA REACH copper mandates are accelerating reformulation investments toward copper-free binders for CE-marked market access. Deutsche Bahn and SNCF specifications now prioritize compliant composite formulations for fleet renewal contracts.
- Cast Iron:Traditional metallurgical formulations dominate freight applications where operating temperatures remain below 400°C and unit cost outweighs thermal performance. China's Dedicated Freight Corridor and Indian freight modernization programs sustain procurement volumes for cast iron pads from domestic foundries with captive OEM relationships.
- Ceramic:Oxide-based composites serve niche metro and light rail segments where reduced wheel and rail wear offset premium procurement costs.
- Steel:Hardened alloy formulations persist in legacy rolling stock and specific adhesion-critical applications requiring consistent friction coefficients across temperature ranges.
Most installed capacity flows through Cast Iron. Expansion is steepest in Composite.
Application:
Operational intensity and stop frequency create divergent wear profiles across freight haulage versus high-frequency passenger service.
- Freight Trains:Heavy-haul operations with extended braking distances and lower thermal cycling frequency prioritize cost efficiency over advanced material specifications. India's Dedicated Freight Corridor and North American Class I networks sustain demand for standardized pad configurations with predictable wear rates.
- Passenger Trains:Regional and intercity services with frequent station stops generate accelerated wear patterns requiring balanced friction stability. European operators under ECHA REACH mandates are shifting procurement toward low-copper formulations without sacrificing performance across varied adhesion conditions.
- High-Speed Trains:Kinetic energy dissipation requirements exceeding 600°C operating temperatures drive specification toward sintered metallic-ceramic hybrids with vacuum-sintered microstructures.
- Light Rail:Urban transit systems with noise restrictions and reduced wheel wear priorities favor ceramic and low-metallic formulations despite higher per-unit costs.
Freight Trains anchor current procurement volumes. Light Rail is climbing the fastest as urban transit electrification accelerates.
Technology:
Material science advancement separates premium thermal performance tiers from commodity friction solutions.
- Friction Materials:Broad category encompassing engineered composites with tailored coefficient-of-friction profiles across temperature ranges. Formulation control separates qualified suppliers from commodity producers in OEM specification battles.
- Semi-Metallic:Hybrid constructions blending metallic fibers with organic binders balance thermal conductivity against noise and rotor wear characteristics.
- Organic:Non-asbestos formulations with reduced metallic content serve noise-sensitive applications and jurisdictions with strict particulate emission limits.
- Metallic:Sintered powder metallurgy constructions dominate high-speed and heavy-haul segments where thermal capacity requirements exceed organic material limits.
Metallic technology retains the largest installed base. Friction Materials are gaining share fastest through regulatory-driven reformulation cycles.
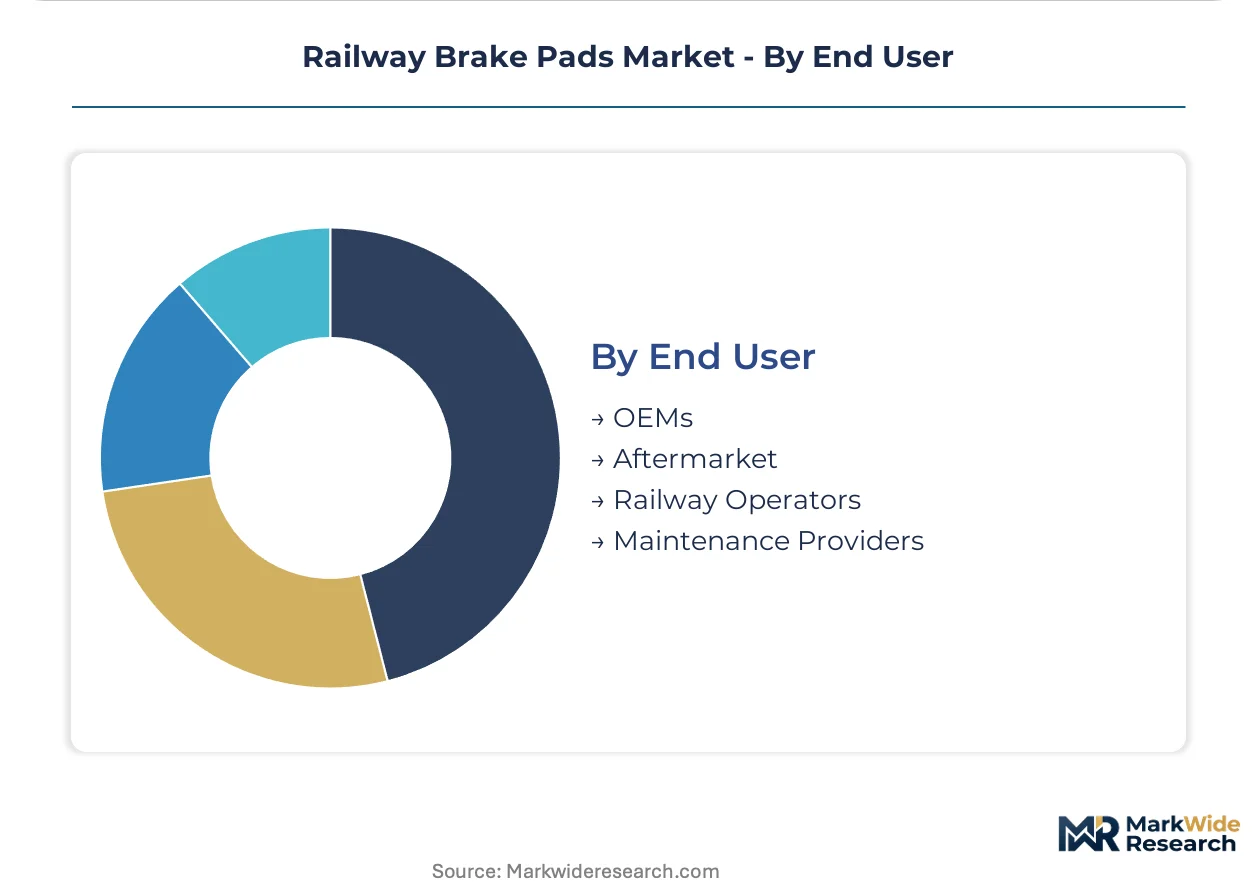
End User:
Channel structure bifurcates between specification-controlled OEM supply and price-sensitive aftermarket procurement.
- OEMs:Rolling stock manufacturers including CRRC, Alstom, and Siemens Mobility specify brake pads during original equipment design, locking in multi-year supply agreements with qualified friction producers. China's GB/T standards and domestic captive foundry expansion are filtering non-compliant imports from CRRC supply chains.
- Aftermarket:Depot-level replacement demand concentrates in mature rail networks with aging fleets requiring compatible formulations. India's Dedicated Freight Corridor scaling is prompting localized remanufacturing investments to serve distributed maintenance facilities.
- Railway Operators:State-owned and private fleet managers with direct procurement authority leverage volume concentration for pricing leverage in competitive tenders.
- Maintenance Providers:Third-party service contractors managing outsourced fleet maintenance negotiate supply agreements based on total cost of ownership rather than unit pricing alone.
OEMs control specification authority for new build programs. Aftermarket is expanding most quickly as fleet age profiles lengthen replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as ECHA REACH compliance costs in Europe widen cost-of-compliance gaps against Asian manufacturing bases. Foundry investments are migrating toward jurisdictions with slower environmental timelines while maintaining technical access to premium markets through dual-certification strategies.
China
CRRC's captive foundry expansion across intercity rail corridors is displacing European composite pad imports. GB/T rail standards and NMPA-equivalent safety certifications mandate domestic testing protocols that filter non-compliant suppliers. Yangtze River Delta specialty foundries are scaling sintered metallic production to serve high-speed fleet buildouts.
Germany
Deutsche Bahn fleet renewal contracts prioritize ECHA REACH-compliant low-copper formulations. KBA rail safety oversight and EU Green Deal embedded carbon requirements compel reformulation investments. Ruhr industrial clusters host vacuum-sintering facilities serving premium passenger OEM specifications.
India
Dedicated Freight Corridor modernization generates procurement volumes for cast iron and semi-metallic pads. BIS certification tightening and CEA rail safety directives force alignment with evolving national standards. Gujarat and Maharashtra depot networks are attracting localized remanufacturing investments for aftermarket positioning.
Japan
Shinkansen maintenance depots sustain demand for precision metallic blends with technical barriers against commodity imports. METI industrial standards and JIS certification frameworks maintain qualification depth for domestic suppliers. Kansai and Chubu industrial corridors concentrate sintering capacity for thermal-performance-critical applications.
United States
Class I freight railroad retrofit programs sustain cast iron formulation dominance where thermal thresholds remain below 400°C. FRA safety regulations and AAR interchange standards govern specification compliance. Midwest industrial centers anchor foundry supply serving North American freight operator procurement.
Railway Brake Pads Market Competitive Landscape
European producers anchor the premium compliance tier; Asian specialists hold volume leadership through captive OEM relationships. Market structure bifurcates between consolidated integrated braking system suppliers and fragmented regional foundries serving price-sensitive freight segments. Strategic archetypes include integrated system vendors, captive rail OEM foundries, and independent friction material specialists. Competitive moves concentrate on dual-certification capacity expansion and backward integration into raw material processing.
Among integrated system specialists, Knorr-Bremse and Wabtec Corporation exemplify the consolidated tier anchoring fleet renewal contracts through full braking system portfolios. Nabtesco Corporation occupies a precision-focused position within the Japanese supplier archetype. These three entities represent divergent geographic and technical positioning strategies across the competitive spectrum.
| Leading Market Players |
|---|
| EBC Brakes |
| Bremskerl |
| Knorr-Bremse |
| Tenneco Braking |
| Tribo |
| Wabtec Corporation |
| CRRC Qishuyan Institute |
| Nabtesco Corporation |
| Akebono Brake Industry |
| Others |
Pricing and Supply Chain Analysis
Copper powder and rare earth element costs cascade through sintered metallic pad production, with ECHA REACH compliance premiums in Europe widening spreads against Chinese captive foundry output serving domestic OEMs.
Pricing Analysis
Distributor margins compress as direct OEM contracts expand across fleet renewal programs. Three-tier pricing structure across premium, standard, and economy levels separates ECHA REACH-compliant composite formulations from cast iron commodity grades and ceramic niche applications. Pricing pressure stems from raw material volatility in nickel and copper feedstocks. Freight operators exhibit highest price sensitivity, while high-speed rail procurement prioritizes thermal performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Deutsche Bahn and SNCF mandate qualified European and audited Asian contract manufacturers for critical friction components. Geographic supply concentration centers on China, Germany, and Japan for vacuum-sintering capacity and precision metallurgy. Raw material dependencies draw from Chilean copper, Chinese rare earth processing, and European resin binder production. Single-source vulnerability persists in high-purity metallic powder supply. Distribution runs through OEM direct channels for new build programs and depot-level stocking for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
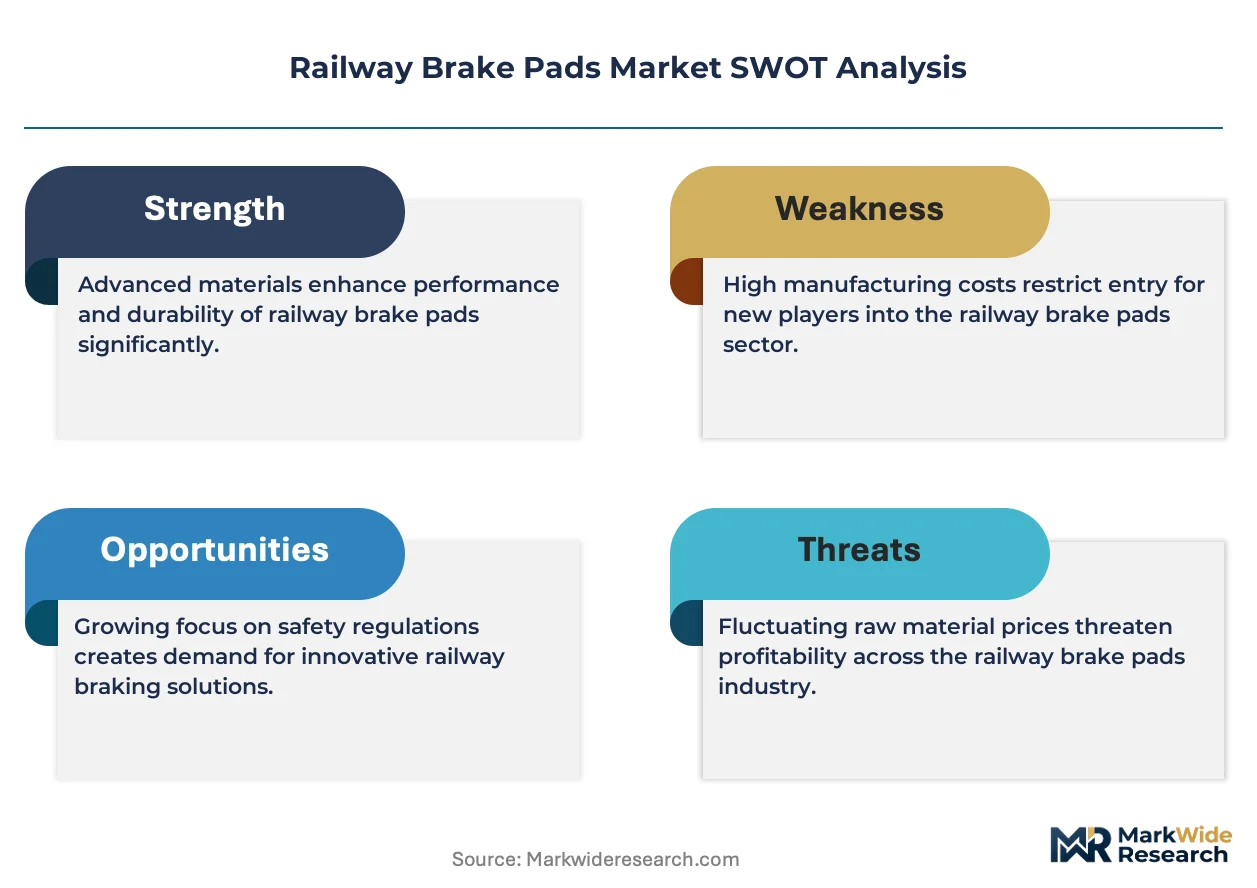
Regulatory arbitrage between ECHA REACH compliance costs in Europe and slower environmental timelines in India creates margin expansion opportunities for dual-certified suppliers.
For Market Incumbents: Extend certification coverage across China's GB/T standards and India's BIS frameworks to defend against captive foundry expansion. Backward integration into copper-free binder R&D offsets reformulation cost exposure from REACH mandates. Capacity positioning in Gujarat depot corridors captures Dedicated Freight Corridor aftermarket demand.
For New Entrants and Emerging Players: ECHA REACH copper restrictions in Europe open a window for compliant composite formulation specialists to penetrate SNCF and Deutsche Bahn supply chains. India's aftermarket remanufacturing segment offers lowest qualification barriers for regional entrants. Sensor-enabled predictive maintenance integration provides differentiated go-to-market positioning against traditional distributor models.
For Investors and Strategic Acquirers: Consolidation pressure builds where vacuum-sintering technical barriers eliminate smaller foundries from high-speed rail specifications. Long-term viability favors suppliers with dual-certification capacity spanning ECHA REACH and Asian regulatory frameworks. Acquisition targets include precision metallic blend specialists serving Shinkansen maintenance depots. Watch for Indian BIS certification tightening as inflection indicator for aftermarket localization mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Free Formulation R&D | ECHA REACH compliance secures CE-marked access to Deutsche Bahn and SNCF fleet contracts. |
| Vacuum Sintering Capacity Expansion | Technical barrier elimination consolidates supplier tiers for high-speed thermal performance applications. |
| Indian Depot Localization | Dedicated Freight Corridor scaling creates captive aftermarket positioning in Gujarat and Maharashtra corridors. |
| Dual-Certification Manufacturing | Parallel ECHA REACH and GB/T compliance enables supply to both European and Chinese OEM specifications. |
| Predictive Maintenance Integration | Sensor-to-depot data flows displace fixed-interval replacement scheduling across Class I freight networks. |
Research Methodology
Coverage spans China, Germany, India, Japan, and the United States, with primary inputs from each market cluster. Triangulation combines interviews with rolling stock OEM procurement directors, friction material R&D heads, railway operator maintenance chiefs, and aftermarket distributor managers with secondary validation from customs trade data, FRA safety filings, KBA rail oversight reports, and SEC supplier disclosures. Bottom-up segment sizing and top-down macro reconciliation anchor volume and value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include material type, application intensity, thermal performance tier, and regulatory compliance cluster. CAGRs derive from rolling stock fleet expansion schedules, replacement cycle analysis, and formulation shift assumptions. Industry-specific inputs incorporate CRRC production forecasts, Dedicated Freight Corridor deployment timelines, and ECHA REACH implementation phasing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility and regulatory timeline acceleration scenarios. Deviation in Chinese captive foundry expansion rates or Indian BIS certification stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Trailer Axle Market
Vehicle Components
Tow Tractor Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
EV Connectors Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
RV Battery Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Engine Components Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
Steering Stabilizers Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Digital Tire Inflator Market