
 Transport Refrigeration Unit (TRU) Market | 2026-2036
Transport Refrigeration Unit (TRU) Market Size, Share, and Industry Trends Forecast 2026-2036
Transport Refrigeration Unit (TRU) Market Insights
Subscription-based fleet uptime monitoring is hardening into a standard contract feature across the TRU sector. Thermo King leverages its telematics platform to lock in recurring service revenue from logistics providers running cross-border routes. Carrier Transicold anchors North American trailer refrigeration through dense dealer service coverage and OEM bundling with major trailer manufacturers. DENSO competes in Asia-Pacific markets with compact, high-efficiency compressor designs purpose-built for dense urban delivery van configurations.
A transport refrigeration unit is a self-contained mechanical vapor-compression system designed to maintain cargo temperatures between minus 25 degrees Celsius and plus 25 degrees Celsius using diesel-powered or electric compressor-drive architectures. These systems integrate evaporator coils, condenser units, and microprocessor-based temperature controllers to protect perishable commodities and temperature-sensitive pharmaceuticals during transit. Trailer refrigeration commands the largest installed base due to long-haul interstate and international freight volumes, while hybrid systems are gaining fastest in urban last-mile delivery where emissions restrictions bite hardest. Mechanical refrigeration still dominates manufacturing scale and aftermarket parts economics, though cryogenic alternatives occupy niche pharmaceutical lanes requiring ultra-low temperatures.
The EPA's AIM Act refrigerant phasedown and California Air Resources Board fleet rules are forcing accelerated diesel-to-electric powertrain transitions in TRU equipment sold across the United States. The EU F-Gas Regulation and CE marking requirements under the Machinery Directive shape parallel compliance burdens for manufacturers exporting into European logistics markets. Stakeholders must weigh total cost of ownership calculations against regulatory compliance timelines when sizing fleet replacement cycles and powertrain technology bets.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is compressing fleet replacement cycles and forcing powertrain diversification decisions across interstate logistics operators. Equipment procurement committees now weigh total cost of ownership against compliance timelines that lock in technology choices for fifteen-year asset lives.
Growth Catalysts
- Pharmaceutical cold chain logistics:Vaccine distribution infrastructure and biologics transport are deepening reliance on precise temperature-controlled transport, expanding addressable fleet demand for validated TRU systems.
- California Air Resources Board fleet rules:Zero-emission mandates for drayage and last-mile operations are accelerating electric TRU adoption in urban freight corridors with the strictest air quality enforcement.
- Interstate food distribution networks:Modernization of refrigerated trailer fleets serving regional distribution centers is driving replacement demand for higher-efficiency diesel and hybrid architectures.
Market Restraints
- Copper and aluminum input volatility:Compressor manufacturing and heat exchanger fabrication face margin pressure from base metal price swings that TRU OEMs cannot fully pass through under long-term fleet contracts.
- Dealer service network concentration:Dense coastal coverage contrasts with sparse inland service points, creating uptime risk for cross-country operators running routes through Mountain and Plains states.
- Cryogenic temperature limitations:Mechanical vapor-compression systems cannot reach ultra-low thresholds required for certain cell therapies, ceding niche pharmaceutical lanes to liquid nitrogen alternatives.
Strategic Opportunities
- Urban last-mile electrification:European city centers with congestion charging and low-emission zones present first-mover advantage for battery-electric TRU configurations in dense delivery van segments.
- Telematics-enabled subscription services:Real-time temperature monitoring and predictive maintenance contracts create recurring revenue streams beyond equipment sale margins.
- EU F-Gas Regulation compliance exports:Lower-global-warming-potential refrigerant architectures developed for European markets can be repositioned for US operators anticipating AIM Act phase-down schedules.
Industry Challenges
- Electrification technician scarcity:Fleet maintenance departments lack sufficient trained personnel for high-voltage compressor drive diagnostics and battery thermal management repairs.
- Dual powertrain inventory complexity:Dealers and leasing companies must stock diesel, hybrid, and fully electric TRU variants simultaneously, straining working capital and floor space.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transport Refrigeration Unit (TRU) Market |
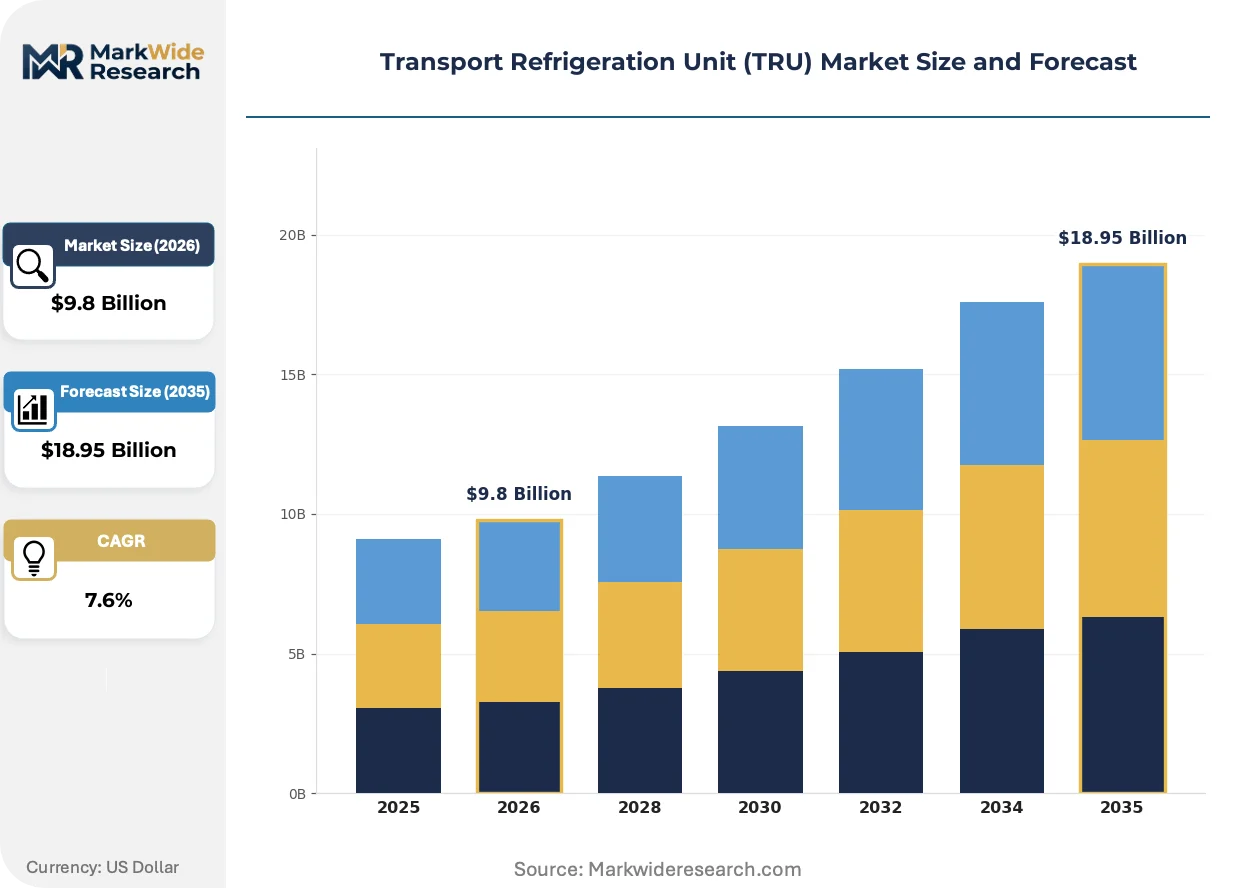
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reefer Truck, Trailer Refrigeration, Container Refrigeration, Refrigerated Van Technology: Mechanical Refrigeration, Cryogenic Refrigeration, Thermoelectric, Hybrid Systems End User: Logistics Providers, Food Distribution, Pharmaceuticals, Retail Chains Installation: OEM Installation, Aftermarket Installation, Retrofit Solutions, Integrated Systems |
| Companies Covered | Thermo King, Carrier Transicold, DENSO, Zanotti, Mitsubishi Heavy Industries, Daikin Industries, Hwasung Thermo, Hubbard Products, SONGZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transport Refrigeration Unit (TRU) Market Trends and Innovations
Equipment architecture is fragmenting into purpose-built configurations as regulatory thresholds and duty-cycle requirements diverge across geographies and end-use verticals. This specialization is compressing the viable lifespan of generalist platform designs.
Thermal battery packs using phase-change materials are modularizing trailer refrigeration architectures. Pharmaceutical logistics providers operating validated lanes are adopting these systems to maintain temperature integrity during diesel engine shutdowns at border crossings. The technology is modularizing aftermarket retrofit opportunities by decoupling cooling capacity from engine runtime.
The EU F-Gas Regulation is banning refrigerants with global warming potential above 150 in new mobile equipment from 2025. TRU manufacturers serving European export markets are requalifying compressor designs for R-452A and CO2 alternatives. Trailer refrigeration units bound for Germany and France face the most compressed retooling timelines.
Leasing companies are unbundling equipment acquisition from maintenance services, forcing OEMs to compete for recurring revenue through uptime guarantees rather than upfront sale margins. Fleet operators in the United States are consolidating vendor relationships to reduce contract administration overhead. This consolidation is most visible among regional grocery distributors modernizing aging trailer pools.
Transport Refrigeration Unit (TRU) Market Segmentation
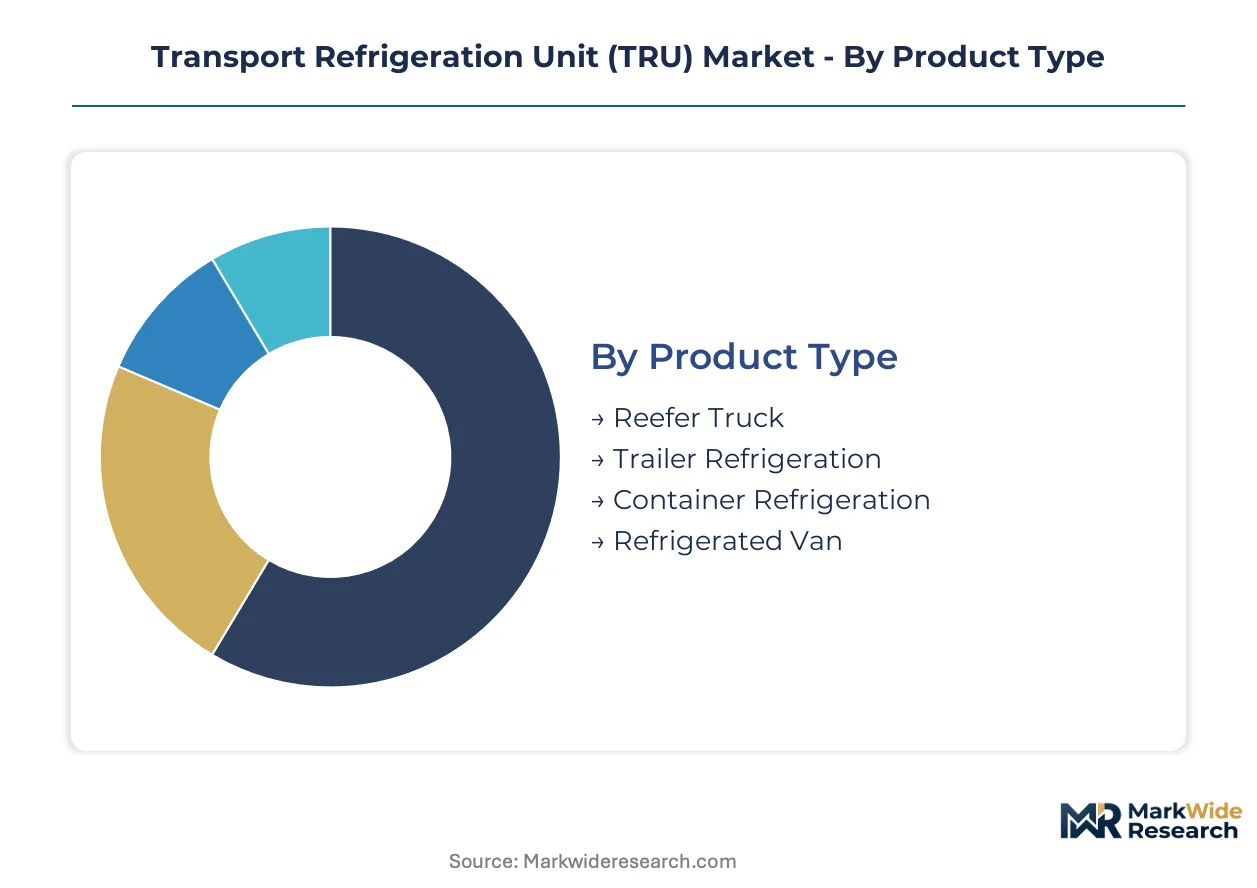
TRU procurement cycles diverge sharply across product configurations and powertrain technologies. Fleet operators size replacement investments against regulatory compliance windows and route-specific duty cycles.
Product Type:
Upgrade urgency varies by chassis attachment point and cargo volume requirements, with interstate operators facing compressed replacement timelines under EPA refrigerant phasedown rules.
- Reefer Truck:Self-contained units mounted on rigid truck chassis serve regional distribution networks with frequent stop-start cycles. Demand clusters among grocery distributors in California and Texas modernizing medium-duty fleets ahead of CARB zero-emission mandates.
- Trailer Refrigeration:Diesel-powered or electric compressor systems attach to semi-trailers for long-haul interstate freight. Interstate food distributors running cross-country routes dominate installed base replacement, though electrification faces range and weight trade-offs on 53-foot dry van configurations.
- Container Refrigeration:Clip-on units for intermodal shipping containers handle international pharmaceutical and produce lanes. Port drayage operators in Los Angeles and Savannah drive retrofit demand as marine terminals enforce idle-reduction policies.
- Refrigerated Van:Compact units for light commercial vehicles address urban last-mile delivery with strict curb weight limits. European city centers with congestion charging accelerate battery-electric configurations in this segment.
Volume placements concentrate in Trailer Refrigeration; the faster expansion belongs to Refrigerated Van.
Technology:
Cost tier stratification separates proven mechanical architectures from emerging alternatives requiring technician retraining and charging infrastructure.
- Mechanical Refrigeration:Vapor-compression systems using R-452A or CO2 refrigerants dominate manufacturing scale and aftermarket parts availability. Long-haul operators prioritize this technology for fifteen-year asset life certainty under AIM Act compliance timelines.
- Cryogenic Refrigeration:Liquid nitrogen or CO2 systems achieve ultra-low temperatures for cell therapy transport. Pharmaceutical logistics providers operating validated lanes adopt these units despite higher operating costs and refueling complexity.
- Thermoelectric:Solid-state cooling without moving parts suits small payload medical transport in noise-restricted zones. Limited capacity constrains adoption to courier services handling temperature-sensitive biologics.
- Hybrid Systems:Dual diesel-electric architectures allow engine-off operation at distribution centers and border crossings. Urban freight corridors with the strictest air quality enforcement show steepest adoption curves.
Mechanical Refrigeration retains the dominant share; Hybrid Systems are climbing the fastest on regulatory pressure.
End User:
Customer type determines service contract structure and uptime guarantee requirements, with pharmaceutical lanes demanding validated temperature documentation.
- Logistics Providers:Third-party cold chain operators manage multi-customer fleets with telematics-enabled compliance reporting. Cross-border route density drives subscription-based maintenance contracts with real-time temperature monitoring.
- Food Distribution:Regional grocery and produce distributors operate high-utilization trailer pools with compressed replacement cycles. Interstate network modernization focuses on diesel efficiency gains ahead of electrification readiness.
- Pharmaceuticals:Vaccine and biologics manufacturers require validated lanes with continuous temperature documentation. Ultra-low temperature cell therapies force adoption of cryogenic alternatives outside mechanical refrigeration limits.
- Retail Chains:Corporate fleet operators balance private-label distribution with outsourced logistics. Consolidated vendor relationships reduce contract administration overhead during fleet modernization programs.
Food Distribution accounts for the largest fleet base; Pharmaceuticals shows the steepest expansion trajectory on cold chain infrastructure investment.
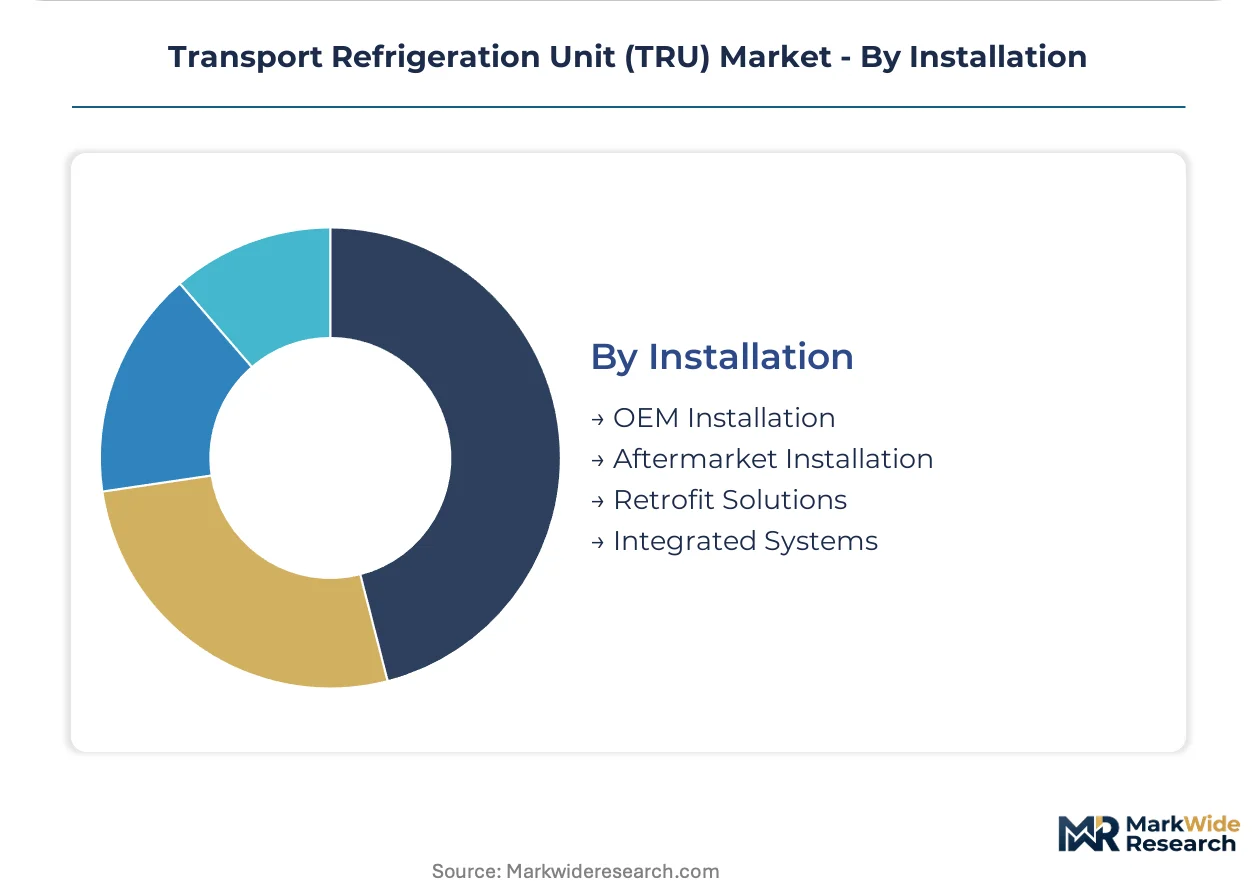
Installation:
Supply channel configuration shapes margin capture, with OEM bundling locking in long-term service revenue versus aftermarket price competition.
- OEM Installation:Factory-integrated units ship with new chassis or trailers under bundled financing. Major trailer manufacturers specify preferred TRU suppliers to streamline warranty coverage and service network alignment.
- Aftermarket Installation:Independent dealers mount units on existing chassis during mid-life fleet refresh cycles. Price competition intensifies as leasing companies unbundle equipment from maintenance services.
- Retrofit Solutions:Phase-change material thermal batteries and electric standby kits extend asset life without full replacement. Border-crossing pharmaceutical lanes adopt these modular upgrades to maintain temperature integrity during engine shutdowns.
- Integrated Systems:Chassis-TRU combinations engineered as unified platforms optimize weight distribution and aerodynamics. Electric powertrain integration demands this approach for battery thermal management and range optimization.
OEM Installation captures the highest volume placements; Retrofit Solutions are gaining share fastest on asset life extension demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors North American TRU demand through the Ports of Los Angeles and Long Beach, where drayage fleet electrification timelines compress procurement cycles for container refrigeration clip-ons serving trans-Pacific pharmaceutical and produce lanes.
United States
Interstate food distribution networks drive trailer refrigeration replacement across the Midwest and Southeast corridors. EPA's AIM Act refrigerant phasedown forces fleet operators to lock in fifteen-year asset decisions around lower-GWP compressor architectures. The Dallas-Fort Worth metroplex concentrates refrigerated trailer pooling operations for regional grocery distribution.
Germany
EU F-Gas Regulation bans refrigerants above 150 GWP in new mobile equipment from 2025, accelerating R-452A and CO2 system requalification. The Rhine-Ruhr industrial corridor hosts dense logistics provider clusters modernizing last-mile van fleets ahead of city-center low-emission zone enforcement. Berlin's congestion charging zone pushes battery-electric TRU adoption in urban delivery segments.
China
E-commerce cold chain expansion drives refrigerated van demand in the Yangtze River Delta last-mile networks. NMPA pharmaceutical distribution regulations tighten temperature validation requirements for vaccine transport. Shanghai's Pudong district concentrates domestic TRU manufacturing capacity serving Asia-Pacific export markets.
Japan
Compact urban delivery configurations dominate TRU procurement in Tokyo's dense ward logistics. METI energy efficiency standards push high-efficiency compressor designs for kei-truck refrigeration applications. Osaka's Kansai port cluster handles temperature-controlled pharmaceutical exports requiring validated container refrigeration systems.
Brazil
Agricultural export corridors from São Paulo state drive long-haul reefer truck demand for soy and meat transport. ANVISA pharmaceutical cold chain regulations expand validated lane requirements for vaccine distribution. The Santos port complex concentrates container refrigeration retrofit activity for Mercosur trade lanes.
Transport Refrigeration Unit (TRU) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the TRU sector, with integrated compressor manufacturing requiring foundry-scale investment while modular system integrators outsource core components. The vendor base stratifies into three tiers: full-stack refrigeration OEMs controlling compressor technology, chassis-agnostic system integrators, and regional service specialists capturing aftermarket maintenance contracts. Strategic moves concentrate on telematics platform development for recurring service revenue and refrigerant architecture repositioning ahead of regulatory phase-down deadlines.
Among full-stack refrigeration OEMs, Thermo King and Carrier Transicold anchor the premium tier through dense service network coverage and OEM bundling relationships with major trailer manufacturers. DENSO occupies a distinct position as a compressor technology specialist supplying compact, high-efficiency architectures purpose-built for Asian urban delivery van configurations. These three represent divergent competitive archetypes: the integrated North American fleet solution provider, the service-network-anchored refrigeration systems house, and the component-scale efficiency specialist serving dense urban duty cycles.
| Leading Market Players |
|---|
| Thermo King |
| Carrier Transicold |
| DENSO |
| Zanotti |
| Mitsubishi Heavy Industries |
| Daikin Industries |
| Hwasung Thermo |
| Hubbard Products |
| SONGZ |
| Others |
Pricing and Supply Chain Analysis
Aluminum LME spot volatility cascades through TRU manufacturing into three-tier pricing structure across premium, standard, and economy levels, compressing margins for compressor fabricators while fleet operators lock in long-term contracts to hedge input cost swings.
Pricing Analysis
Margin tightening in mid-tier mechanical refrigeration reflects copper and aluminum input volatility that OEMs cannot fully pass through under fifteen-year fleet contracts. Premium-mid-economy pricing differentiation separates validated pharmaceutical-grade systems from standard food distribution units based on certification level and after-sales service bundling. Cost-down pressure on standard-tier diesel architectures accelerates as leasing companies unbundle equipment from maintenance services. Food distribution fleets show highest price sensitivity, while pharmaceutical logistics providers absorb premium pricing for validated lane compliance.
Supply Chain Analysis
Regional distribution centers in the Dallas-Fort Worth metroplex anchor North American parts fulfillment, feeding dealer service networks across Midwest and Southeast corridors. Manufacturing gravity centers on China, Germany, and the United States, with compressor fabrication drawing from copper Chilean mine output and aluminum smelters in the Gulf Coast. Single-source vulnerability concentrates in semiconductor-based microprocessor controllers for electric TRU architectures. Distribution runs through OEM bundling with major trailer manufacturers and independent dealer channels serving aftermarket retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric compressor-drive architectures are displacing diesel-powered systems across urban freight corridors, forcing fleet operators and OEMs to reposition around battery thermal management and high-voltage technician training.
For Market Incumbents: Acquire telematics platform capabilities to lock in recurring service revenue as leasing companies unbundle equipment from maintenance contracts. Consolidate dealer service network coverage in Mountain and Plains states where sparse inland points create uptime risk for cross-country operators. Invest in high-voltage technician certification programs to address electrification skill scarcity before regulatory compliance windows compress. For New Entrants and Emerging Players: Independent regional grocery distributors operating aging trailer pools represent the most penetrable buyer archetype for modular retrofit solutions. Target phase-change material thermal battery offerings for pharmaceutical lanes requiring temperature integrity during border-crossing engine shutdowns. Pursue direct sales partnerships with port drayage operators facing idle-reduction mandates in Los Angeles and Savannah. For Investors and Strategic Acquirers: Distressed-cycle entries favor component-scale compressor specialists with captive European F-Gas Regulation compliance architectures in Germany. Five-to-ten year viability hinges on refrigerant architecture repositioning ahead of EPA AIM Act phase-down deadlines. Monitor California Air Resources Board zero-emission mandate enforcement velocity as inflection indicator for electric TRU adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables subscription-based uptime guarantees for logistics providers running cross-border pharmaceutical lanes. |
| Refrigerant Architecture Repositioning | Locks in fifteen-year asset compliance under EPA AIM Act hydrofluorocarbon phasedown schedules. |
| Electric Powertrain Certification Investment | Addresses technician scarcity for high-voltage compressor drive diagnostics and battery thermal management. |
| Dealer Network Geographic Expansion | Reduces uptime risk for interstate operators running routes through sparse Mountain and Plains service points. |
| Modular Thermal Battery Development | Captures pharmaceutical retrofit demand for engine-off temperature integrity at distribution centers and border crossings. |
Research Methodology
Multi-period observation of fleet replacement cycles, refrigerant compliance timelines, and base metal price indices anchored the trend analysis, supplemented by interviews with fleet maintenance directors, OEM procurement managers, dealer service heads, and pharmaceutical logistics compliance officers. Secondary validation drew from EPA AIM Act regulatory filings, EU F-Gas Regulation implementation guidance, aluminum LME price archives, and refrigerated trailer production databases. Bottom-up unit economics triangulated against top-down market sizing across powertrain technology and end-use verticals.
Input-output matrices modeled unit placements by product configuration, powertrain architecture, installation channel, and regional regulatory cluster across the projection horizon. CAGRs derived from logistic diffusion curves fitted to electrification adoption patterns and refrigerant transition timelines. Industry-specific forecast inputs incorporated CARB zero-emission mandate enforcement schedules and pharmaceutical cold chain infrastructure investment trajectories.
Revisions become necessary when EPA refrigerant phasedown schedules accelerate, base metal input costs spike beyond hedging thresholds, or electric TRU technician training pipelines fail to scale. Forecasts reflect documented assumptions around regulatory compliance windows and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
Boxcar Scars Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Europe Fleet Management Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
Indonesia Road Freight Transport Market