
 United States Retail Reverse Logistics Market | 2026-2036
United States Retail Reverse Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Retail Reverse Logistics Market Insights
AI-powered sortation and disposition engines are tilting how retailers route returned merchandise toward resale, refurbishment, or liquidation channels. United Parcel Service, Inc. leverages its nationwide hub network to consolidate returns volume at scale. FedEx Corporation anchors its reverse logistics offering through integrated first-mile pickup and backhaul optimization. Optoro Inc competes through proprietary algorithms that match returned units to highest-value secondary channels.
Retail reverse logistics encompasses the end-to-end management of product flows from consumers back to retailers or manufacturers, encompassing transportation, inspection, grading, disposition decisioning, and final channel placement with processing velocities typically measured in hours rather than days to preserve residual value. Returns processing dominates service type revenue as e-commerce penetration elevates volumes, while refurbishing commands margin premiums in consumer electronics where certified pre-owned programs extend product lifecycles. Online retail distribution channels generate disproportionate return rates compared to brick-and-mortar, particularly in apparel where fit uncertainty drives seasonal return surges.
The EPA oversees hazardous material handling in returned electronics and batteries, while OSHA governs warehouse safety standards affecting returns processing labor intensity; California's SB 54 and emerging state extended producer responsibility laws are mandating landfill diversion targets that reshape disposition economics. The FTC monitors environmental marketing claims around resale and recycling programs, creating compliance thresholds for circular economy messaging. Stakeholders must monitor how state-level packaging reduction mandates and federal carbon accounting rules alter the cost structure of returns transportation and processing decisions.
Market Dynamics
E-commerce return volumes are compressing processing timelines from days to hours as apparel merchants deploy automated disposition engines to preserve residual value on seasonal merchandise.
Growth Catalysts
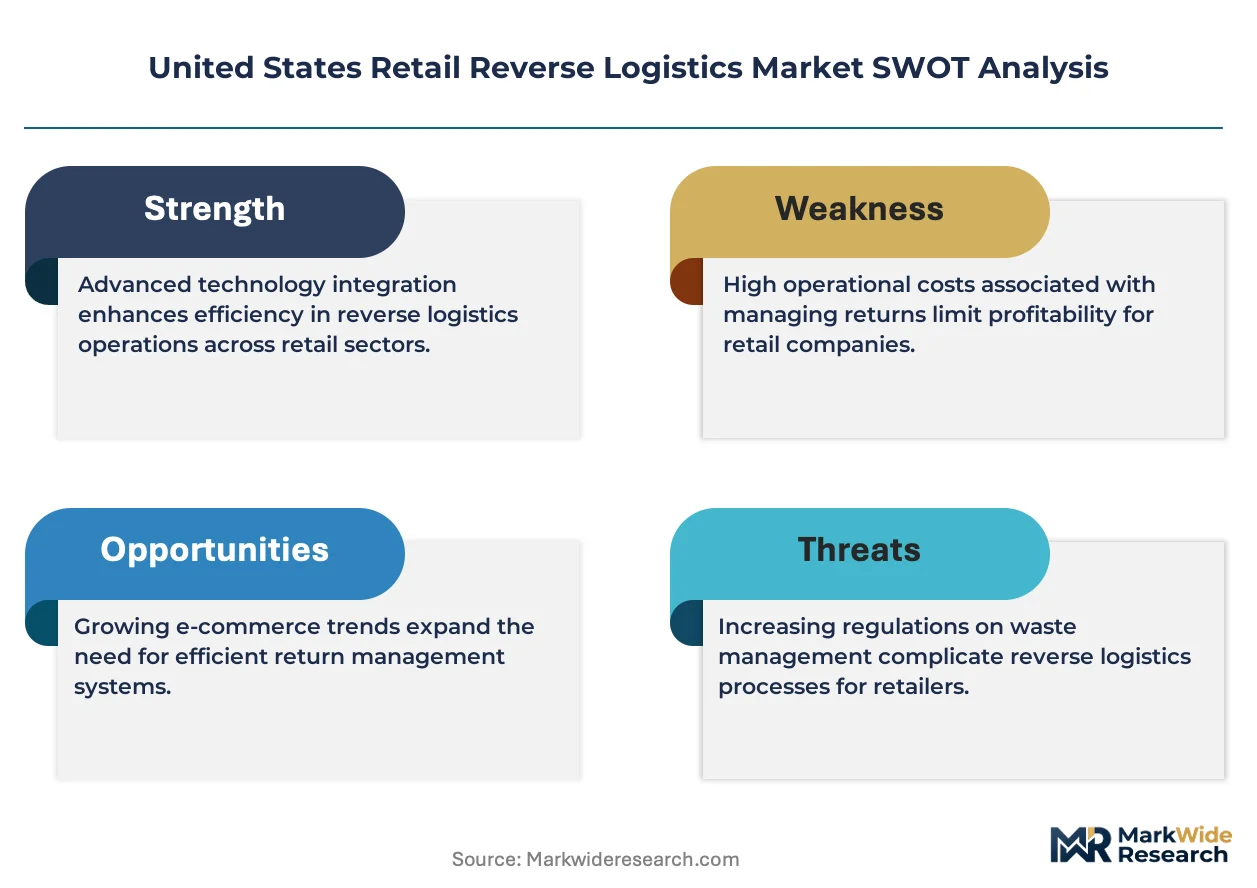
- Extended Producer Responsibility mandates:California's SB 54 and emerging state landfill diversion frameworks are compelling retailers to invest in refurbishment infrastructure rather than liquidation.
- AI-powered sortation:Machine vision systems now grade returned electronics and apparel at conveyor speeds, enabling real-time routing to resale channels.
- Fulfillment density concentration:Texas, California, and New York generate disproportionate returns volume due to e-commerce penetration and population scale.
Market Restraints
- Labor cost escalation:Warehouse wage pressure in major metropolitan hubs erodes margins on labor-intensive inspection and repackaging operations.
- Transportation fuel volatility:Diesel price swings directly impact first-mile pickup economics for fragmented residential returns.
- Regulatory fragmentation:State-level packaging reduction mandates create compliance complexity for multi-state retailers.
Strategic Opportunities
- Secondary market platform integration:Direct API connections between returns management systems and recommerce marketplaces bypass traditional liquidation brokers.
- Refurbishment certification programs:EPA-aligned electronics testing protocols enable certified pre-owned pricing premiums in consumer electronics.
- Regional hub consolidation:Underutilized industrial space in Ohio and Pennsylvania offers lower-cost processing capacity for East Coast returns volume.
Industry Challenges
- Data science talent scarcity:Demand forecasting for returns flows requires specialized machine learning expertise that competes with broader supply chain analytics roles.
- Legacy WMS integration:Returns modules must interface with decade-old warehouse management systems lacking real-time inventory visibility.
- Cross-state hazardous materials handling:EPA regulations on lithium batteries in returned electronics create training and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Retail Reverse Logistics Market |
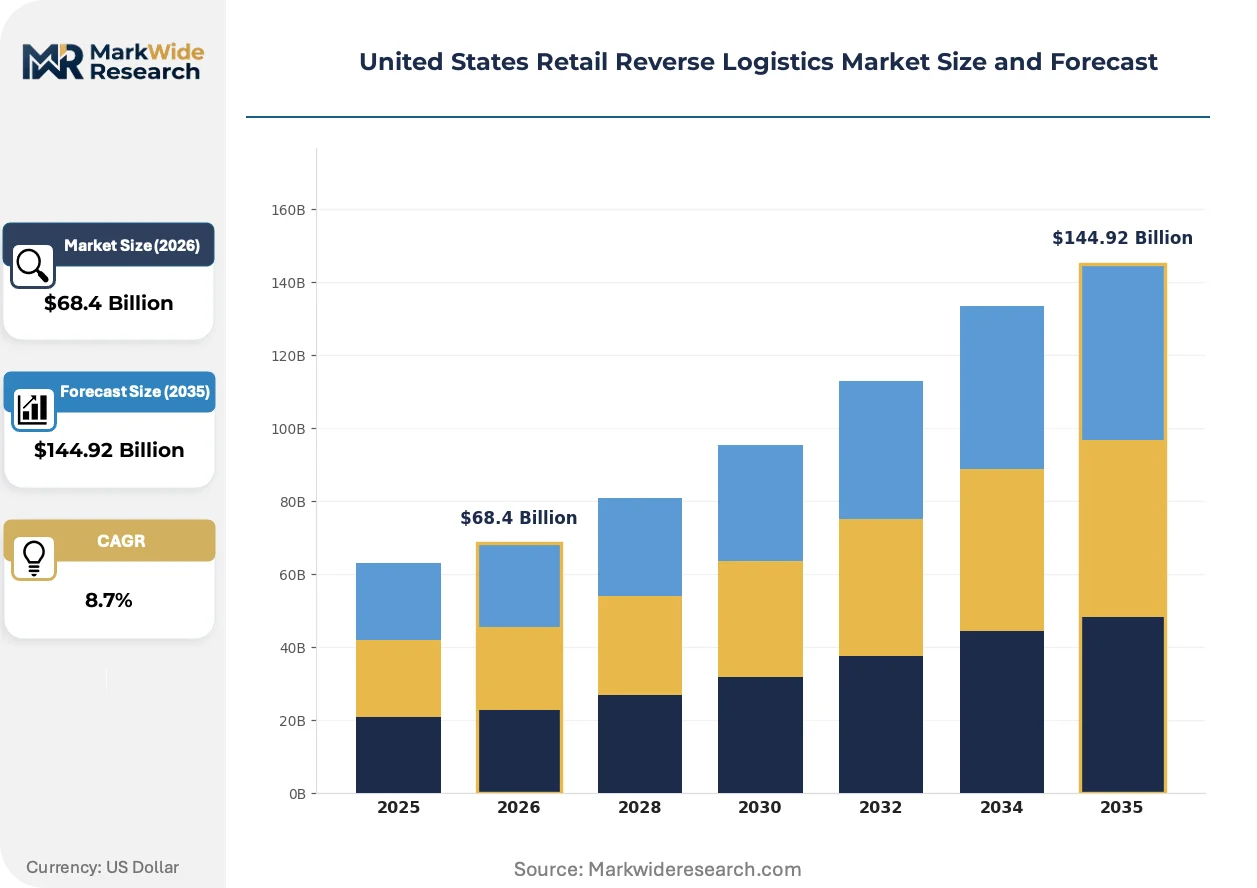
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Returns Processing, Recycling, Refurbishing, Reselling Return Reason: Defective Items, Change of Mind, Wrong Item, Seasonal Returns Industry Vertical: Consumer Electronics, Apparel, Furniture, Home Goods Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct Sales |
| Companies Covered | United Parcel Service, Inc., FedEx Corporation, DB SCHENKER, XPO Logistics, Deutsche Post DHL Group, C.H. Robinson Worldwide, Inc., Ryder System, Inc., ShipBob, Optoro Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Retail Reverse Logistics Market Trends and Innovations
Disposition automation is collapsing the time between customer return initiation and secondary channel listing, compressing value depreciation curves for seasonal and technology merchandise.
Computer vision grading systems are migrating from pilot installations to scaled deployment across apparel and electronics returns facilities. Major omnichannel retailers now process over half of returned units through automated inspection lines. This technology is migrating from experimental to standard infrastructure, eliminating manual touchpoints that previously delayed resale velocity.
OSHA warehouse safety standards are tightening around returns processing environments with elevated manual handling injury rates. The agency's updated ergonomic guidelines are forcing capital allocation toward automated material handling equipment. Third-party logistics providers in California and Texas are responding with accelerated conveyor and robotic depalletization investments.
Consumer tolerance for restocking fees is eroding as free return policies become table stakes in apparel e-commerce. Subscription-based wardrobe services and virtual try-on tools are displacing traditional purchase-then-return behavior among younger demographics. This pattern is most visible in urban coastal markets where rental and resale platform penetration runs highest.
United States Retail Reverse Logistics Market Segmentation
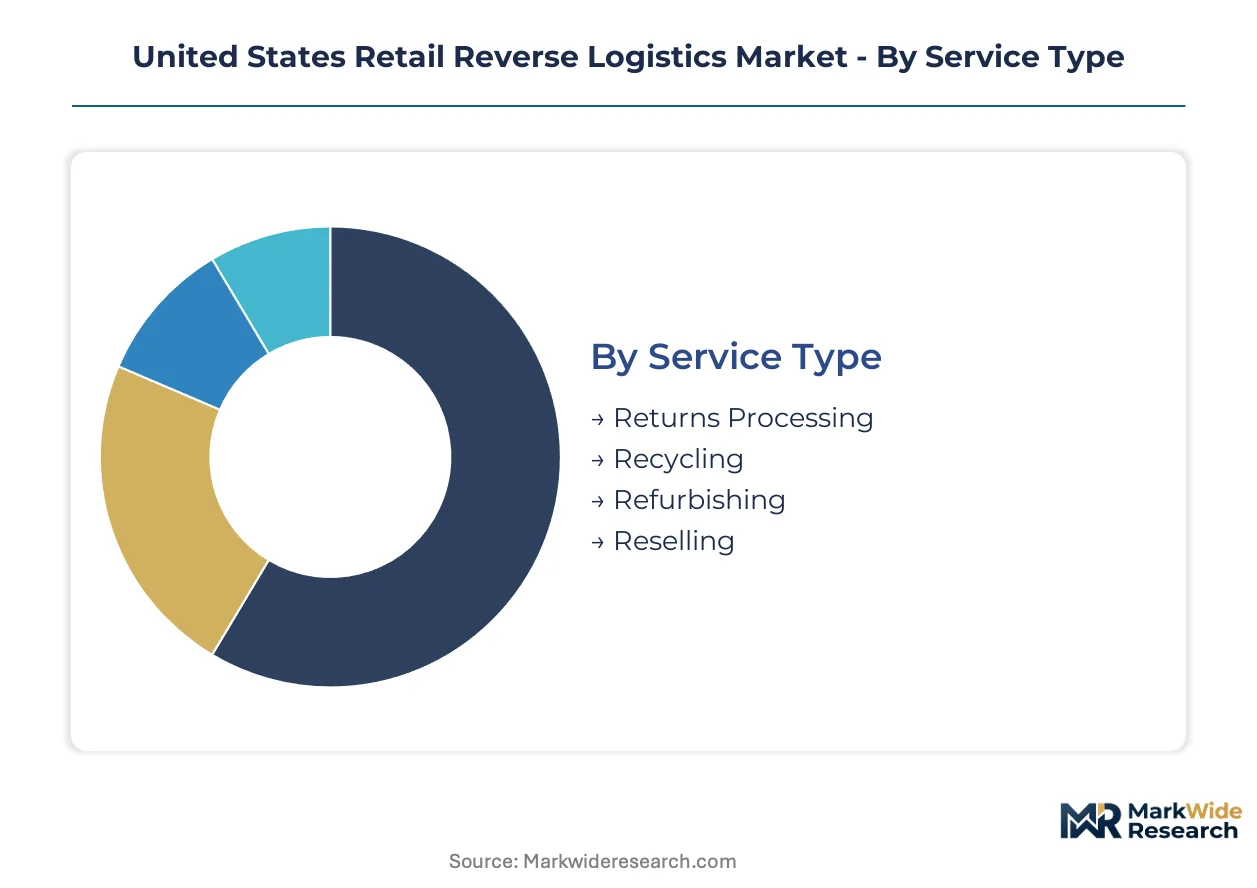
Reverse logistics segmentation reveals how service intensity, return causality, and channel economics reshape margin recovery across the United States. Each dimension exposes distinct operational requirements and value preservation timelines that separate profitable programs from cost centers.
Service Type:
After-sales-service intensity peaks where inspection granularity and velocity requirements converge, creating tiered infrastructure investments across the reverse value chain.
- Returns Processing:High-velocity sortation and disposition routing that compresses time-to-resale for seasonal merchandise. California and Texas fulfillment density drives automation deployment as labor costs escalate in coastal metropolitan hubs.
- Refurbishing:Technical reconditioning with certified pre-owned protocols that capture margin premiums in consumer electronics. EPA-aligned testing standards enable pricing power in secondary markets where warranty transferability matters.
- Recycling:Material recovery operations governed by state landfill diversion mandates including California's SB 54 framework. Electronics and battery handling triggers specialized hazardous materials training under OSHA guidelines.
- Reselling:Direct-to-secondary-market placement through API-integrated recommerce platforms. Liquidation broker displacement accelerates as retailers build direct marketplace connections.
By volume, Returns Processing leads. By growth pace, Refurbishing is ahead as extended producer responsibility laws reshape disposition economics.
Return Reason:
Cost tier stratification emerges sharply across return causality, with defect-driven flows commanding premium recovery infrastructure versus discretionary returns that tolerate velocity tradeoffs.
- Change of Mind:Discretionary returns dominant in apparel e-commerce where fit uncertainty and impulse purchase reversal generate seasonal surges. Virtual try-on adoption in coastal urban markets is beginning to displace this volume among younger demographics.
- Defective Items:Quality-failure returns requiring diagnostic triage and manufacturer chargeback processing. Electronics and furniture verticals concentrate warranty recovery complexity here.
- Wrong Item:Fulfillment error returns that trigger carrier liability claims and inventory reconciliation protocols. Warehouse management system integration gaps amplify these incidents in legacy distribution networks.
- Seasonal Returns:Calendar-compressed volumes post-holiday and post-promotional periods that stress processing capacity. Apparel merchants deploy automated disposition engines specifically to preserve residual value on time-sensitive merchandise.
Change of Mind generates the highest absolute volume. Seasonal Returns show the steepest expansion trajectory as e-commerce promotional intensity escalates.
Industry Vertical:
Application-specific handling requirements diverge across verticals, with electronics demanding technical grading infrastructure and apparel prioritizing speed-to-secondary-channel velocity.
- Apparel:Fit-driven return rates that peak in online channels and compress processing windows for seasonal relevance. Computer vision grading now handles over half of unit volume at major omnichannel retailers.
- Consumer Electronics:Functionality verification and data sanitization requirements that extend processing timelines but enable certified pre-owned pricing tiers. Lithium battery handling triggers EPA hazardous materials documentation.
- Furniture:Bulky item logistics with specialized last-mile collection and refurbishment economics that favor regional hub consolidation. Ohio and Pennsylvania industrial space offers lower-cost processing capacity for East Coast volume.
- Home Goods:Fragmented SKU complexity with lower individual unit values that push disposition toward liquidation channels. Packaging reduction mandates in multiple states complicate reusable container strategies.
Apparel dominates transaction volume. Consumer Electronics delivers the highest recovery rate per unit processed.
Distribution Channel:
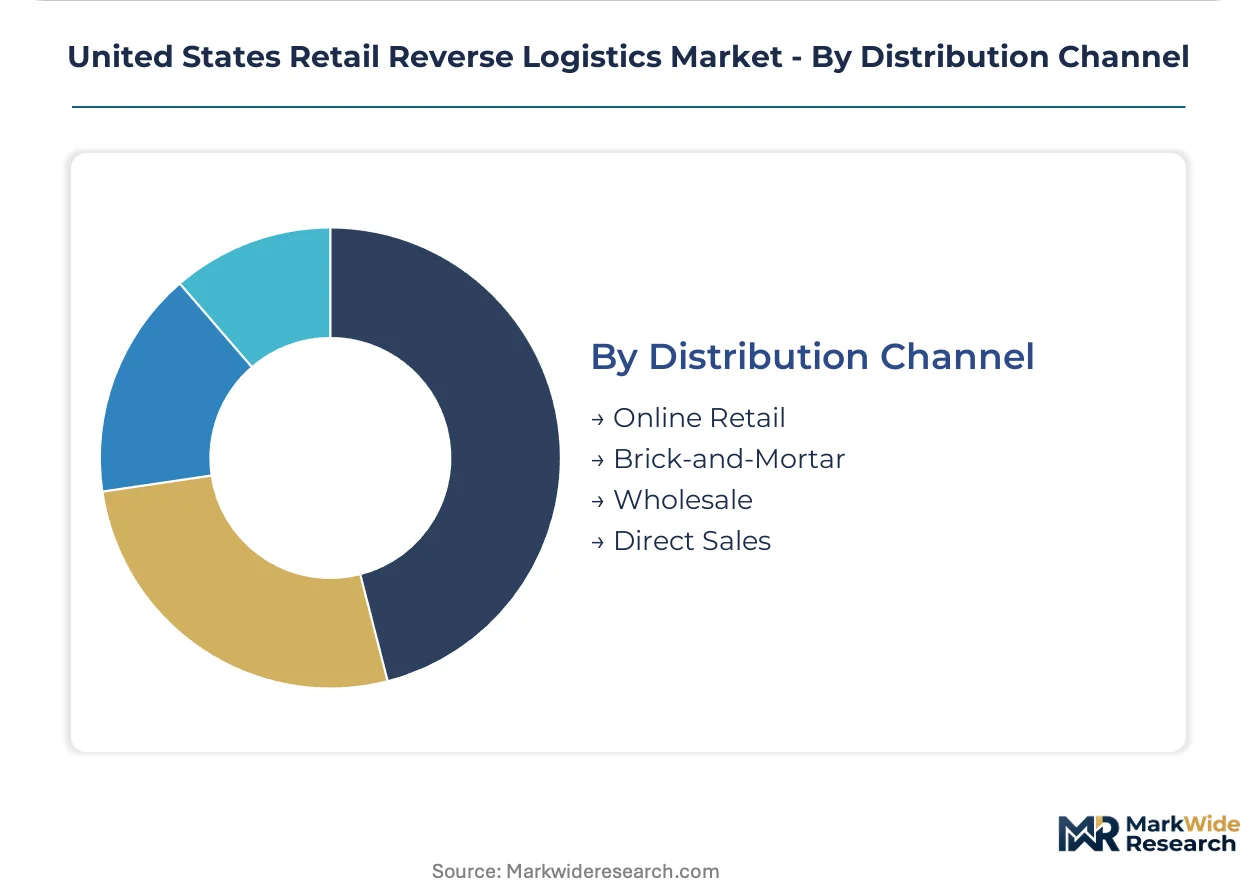
Customer type segmentation exposes channel-specific return rate spreads, with online retail generating disproportionate volume that demands residential-first-mile logistics investment.
- Online Retail:Return rates that exceed brick-and-mortar multiples in fit-dependent categories, driving consolidated pickup network economics. Free return policies have become table stakes, eroding consumer tolerance for restocking fees.
- Brick-and-Mortar:Immediate in-store processing that bypasses transportation costs and enables same-day resale for undamaged items. Store footprint concentration in Texas, California, and New York aligns with returns volume geography.
- Wholesale:B2B return flows with negotiated disposition terms and palletized consolidation that reduces per-unit handling intensity. Relationship-based channel placement bypasses secondary marketplace intermediaries.
- Direct Sales:Manufacturer-controlled return pathways that enable closed-loop refurbishment and brand-protected resale. Subscription wardrobe services in this channel are displacing traditional purchase-then-return behavior.
Online Retail processes the greatest unit volume. Direct Sales is gaining share fastest as brands internalize circular economy control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Returns volume concentrates along three distinct trade-flow corridors: coastal population centers importing from Asian manufacturing hubs, Midwest distribution nodes processing cross-border flows from Mexico, and Northeast corridors handling European luxury and apparel inbound.
California
E-commerce fulfillment density in the Los Angeles Basin and Central Valley generates the nation's highest per-capita return volumes, particularly for apparel and consumer electronics. The state's SB 54 extended producer responsibility framework mandates landfill diversion targets that reshape retailer disposition economics. Automated returns processing facilities in the Inland Empire now handle seasonal surges through machine vision grading systems.
Texas
Dallas-Fort Worth and Houston anchor major consolidated pickup networks serving cross-border e-commerce flows from Mexico. OSHA's updated warehouse ergonomic guidelines are accelerating capital deployment toward robotic material handling in these metro areas. Third-party logistics providers here leverage lower industrial real estate costs compared to coastal markets.
New York Metro
The Northeast corridor's dense population and premium retail concentration drive high-value returns requiring rapid velocity-to-resale. FTC monitoring of environmental marketing claims creates compliance thresholds for circular economy messaging among Manhattan-headquartered brands. Brooklyn and Queens industrial zones host refurbishment operations serving electronics and luxury apparel verticals.
Ohio River Valley
Underutilized industrial space in Ohio and Pennsylvania offers lower-cost processing capacity for East Coast returns volume. EPA hazardous materials handling requirements for lithium batteries in returned electronics trigger specialized training protocols at facilities near Cincinnati and Pittsburgh. Regional hub consolidation here captures backhaul efficiencies on east-west transportation corridors.
Southeast
Florida and Georgia distribution centers process seasonal surges from tourism-driven retail and growing e-commerce penetration in Atlanta and Miami. State-level packaging reduction mandates in this region create compliance complexity for multi-state retailers operating across jurisdictions. Charleston and Savannah port proximity enables direct routing of returned goods to secondary export channels.
United States Retail Reverse Logistics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where scale advantages separate national network operators from regional service providers. Consolidation pressure runs highest in first-mile pickup and automated disposition technology segments. Three archetypes dominate: integrated parcel carriers with reverse-enabled hub networks, software-driven disposition platforms, and specialized third-party logistics operators. Competitive moves center on API integration with recommerce marketplaces and regional hub consolidation in lower-cost industrial markets.
Within the integrated carrier tier, United Parcel Service, Inc. and FedEx Corporation exemplify network-scale competitors leveraging nationwide hub infrastructure for returns consolidation. Optoro Inc occupies a position among algorithm-driven disposition specialists, matching returned units to highest-value secondary channels through proprietary routing engines. These three companies represent the spectrum from physical network control to digital disposition optimization.
| Leading Market Players |
|---|
| United Parcel Service, Inc. |
| FedEx Corporation |
| DB SCHENKER |
| XPO Logistics |
| Deutsche Post DHL Group |
| C.H. Robinson Worldwide, Inc. |
| Ryder System, Inc. |
| ShipBob |
| Optoro Inc |
| Others |
Pricing and Supply Chain Analysis
Inland Empire-to-Los Angeles Basin freight corridors anchor cost dynamics for returns processing, where fuel volatility and warehouse wage compression simultaneously concentrate supply in lower-cost Midwest hubs and force three-tier pricing stratification across premium automated, standard manual, and economy liquidation service tiers.
Pricing Analysis
Current-gen automated disposition engines command premium pricing against prior-gen manual inspection and nascent next-gen AI-powered predictive routing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade for refurbished electronics and volume scale for apparel merchants. Pricing pressure stems from warehouse labor cost escalation in California and Texas metropolitan areas, compressing margins on inspection-heavy operations. Small-to-mid-size apparel e-commerce sellers exhibit highest price sensitivity, while consumer electronics brands with certified pre-owned programs tolerate premium service fees.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for electronics refurbishment components and automated sortation equipment. Manufacturing concentration rests on China for conveyor systems and machine vision hardware, Mexico for nearshored apparel processing capacity, and domestic Midwest production for palletized consolidation infrastructure. Raw material dependencies include steel for material handling equipment, lithium for battery diagnostics, and semiconductor components for grading systems. Single-source vulnerability concentrates in machine vision camera modules. Distribution runs through hub-and-spoke networks anchored by UPS and FedEx consolidation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level extended producer responsibility mandates creates specialized service niches, as California's SB 54 landfill diversion targets and emerging packaging reduction laws in multiple states reward localized compliance expertise over national scale.
For Market Incumbents: Entrench market position through backward integration into refurbishment certification infrastructure and capacity expansion in Ohio River Valley processing hubs. Automated disposition technology from emerging software specialists threatens carrier-integrated incumbents; defend through exclusive API partnerships with recommerce marketplaces. For New Entrants and Emerging Players: Southeast distribution corridors from Florida through Georgia offer underpenetrated processing capacity for tourism-driven retail returns. Target furniture and home goods verticals where bulky item logistics expertise commands premium positioning. Launch through white-label refurbishment certification services for direct-to-consumer brands lacking in-house technical capabilities. For Investors and Strategic Acquirers: Specialized third-party logistics operators with EPA hazardous materials handling credentials represent compelling acquisition targets. Five-to-ten-year viability hinges on state-level EPR mandate expansion. Monitor California SB 54 enforcement intensity and copycat legislation introduction in Texas and New York as inflection indicators for refurbishment infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Disposition Engine Deployment | Machine vision grading at conveyor speeds compresses time-to-resale for seasonal apparel. |
| Regional Hub Consolidation | Ohio and Pennsylvania industrial space captures backhaul efficiencies on east-west corridors. |
| EPA-Aligned Refurbishment Certification | Electronics testing protocols enable certified pre-owned pricing premiums in secondary markets. |
| API Integration with Recommerce Marketplaces | Direct platform connections bypass traditional liquidation brokers and accelerate resale velocity. |
| Robotic Material Handling Investment | OSHA ergonomic guideline compliance reduces injury rates in high-volume returns facilities. |
Research Methodology
A standing panel of returns operations directors, third-party logistics procurement leads, EPA compliance officers, and recommerce platform engineers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with warehouse automation vendors and apparel merchant supply chain executives. Secondary validation drew from OSHA enforcement databases, EPA sustainable materials management reports, state legislative tracking systems, and carrier network capacity disclosures. Bottom-up facility capacity estimates and top-down e-commerce return rate projections were triangulated against trade flow data.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchors. Segmentation dimensions modeled include service type intensity, return reason causality, industry vertical handling requirements, and distribution channel logistics complexity. CAGRs were derived from historical volume trajectories and regulatory mandate implementation timelines. Forecast inputs incorporated diesel price elasticity for first-mile pickup economics and warehouse wage inflation indices for coastal metropolitan hubs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by venture-backed disposition software providers would shift outcomes. Material shifts in federal carbon accounting rules for transportation or state-level packaging reduction mandate proliferation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
Hong Kong Customs Brokerage Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market