
 Topical Pain Relief Market | 2026-2036
Topical Pain Relief Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Pain Relief Market Intelligence
Asset-light contract manufacturing and royalty-based licensing arrangements is reshaping how mid-sized entrants compete against established pharmaceutical giants. Johnson & Johnson leverages its consumer health spin-off structure to sustain focused R&D investment in dermatological delivery systems. Sanofi anchors its position through controlled distribution partnerships with hospital procurement networks. GlaxoSmithKline differentiates via specialized manufacturing scale in transdermal patch production.
Topical pain relief comprises externally applied formulations containing active pharmaceutical ingredients such as menthol, capsaicin, or salicylates in carrier bases designed for percutaneous absorption, with specified drug release rates and skin permeation coefficients determining therapeutic efficacy. These products serve industrial and commercial purposes by providing localized analgesia without systemic opioid exposure, reducing gastrointestinal side effects and dependency risks associated with oral administration. Creams and gels dominate volume sales through retail pharmacy channels, while patches command premium positioning due to extended-release formulations and higher patient compliance rates. The athlete end-user segment shows accelerated uptake as sports medicine protocols increasingly prioritize non-invasive recovery modalities.
FDA monograph regulations and EPA manufacturing standards govern active ingredient concentrations, labeling claims, and environmental discharge limits for topical analgesic production facilities. The FDA's ongoing review of OTC topical drug categories creates compliance uncertainty that favors companies with dedicated regulatory affairs infrastructure and documented clinical safety databases. Stakeholders must monitor how tightening dermatological safety standards will reshape permissible formulation ranges and determine which legacy products require reformulation investment.
Market Dynamics
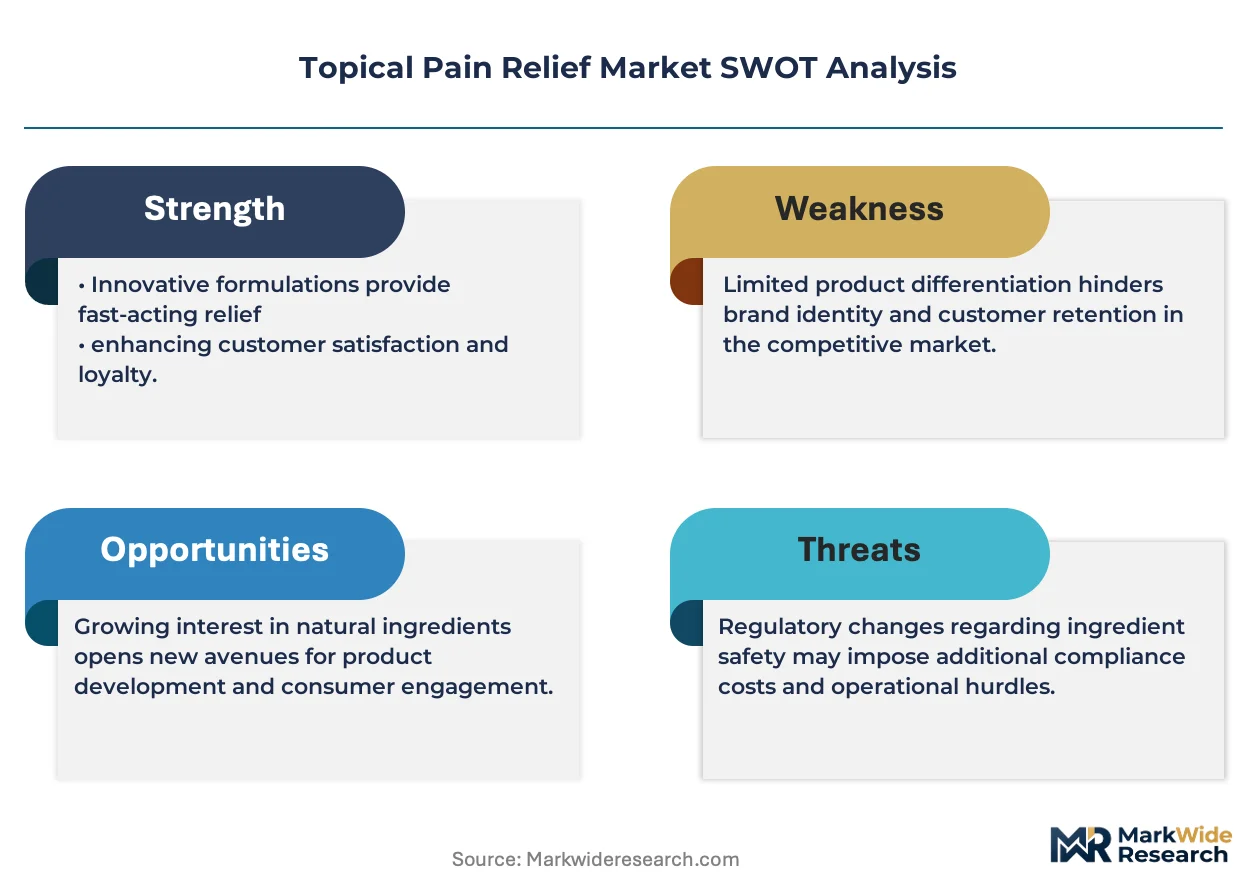
FDA's ongoing OTC topical drug monograph overhaul is compressing permissible formulation ranges while simultaneously elevating documentation burdens, forcing manufacturers to choose between reformulation investment and portfolio rationalization.
Growth Catalysts
- Aging demographics in the United States:Rising life expectancy and sustained athletic participation among older adults create dual demand streams for non-systemic analgesic alternatives.
- REACH-compliant bioadhesive polymers:European regulatory acceptance of next-generation skin-contact materials enables extended-release patch formulations with improved permeation coefficients.
- Sports medicine protocol evolution:Team physicians and physical therapists are embedding topical NSAIDs and counterirritants into standardized recovery regimens ahead of opioid-sparing mandates.
Market Restraints
- API supply concentration:Synthetic capsaicin and high-purity menthol production clusters in specific Chinese chemical manufacturing zones, creating single-source vulnerability.
- Dermatological safety thresholds:FDA's tightening irritation and sensitization standards restrict maximum permissible concentrations of salicylates and counterirritants in combination products.
- Transdermal delivery physics:The stratum corneum barrier limits molecular weight and lipophilicity windows, excluding numerous promising active pharmaceutical ingredients from viable topical development.
Strategic Opportunities
- India's outpatient clinic expansion:Government-funded primary health centers in tier-2 and tier-3 cities lack cold-chain infrastructure for injectable analgesics, creating demand for shelf-stable topical alternatives.
- Telehealth-integrated prescription fulfillment:Direct-to-patient shipping of prescription-strength topical NSAIDs bypasses traditional pharmacy intermediaries in markets with relaxed remote prescribing rules.
- ISO 13485-certified contract manufacturing:Asset-light entrants can access medical-grade production capacity without captive facility investment, accelerating time-to-market for novel delivery formats.
Industry Challenges
- Clinical endpoint standardization:Lack of harmonized pain reduction metrics across regulatory jurisdictions complicates multi-territory submission strategies and extends approval timelines.
- Legacy ERP integration:Mid-sized manufacturers struggle to embed serialized track-and-trace capabilities into existing batch record systems ahead of DSCSA enforcement milestones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Pain Relief Market |
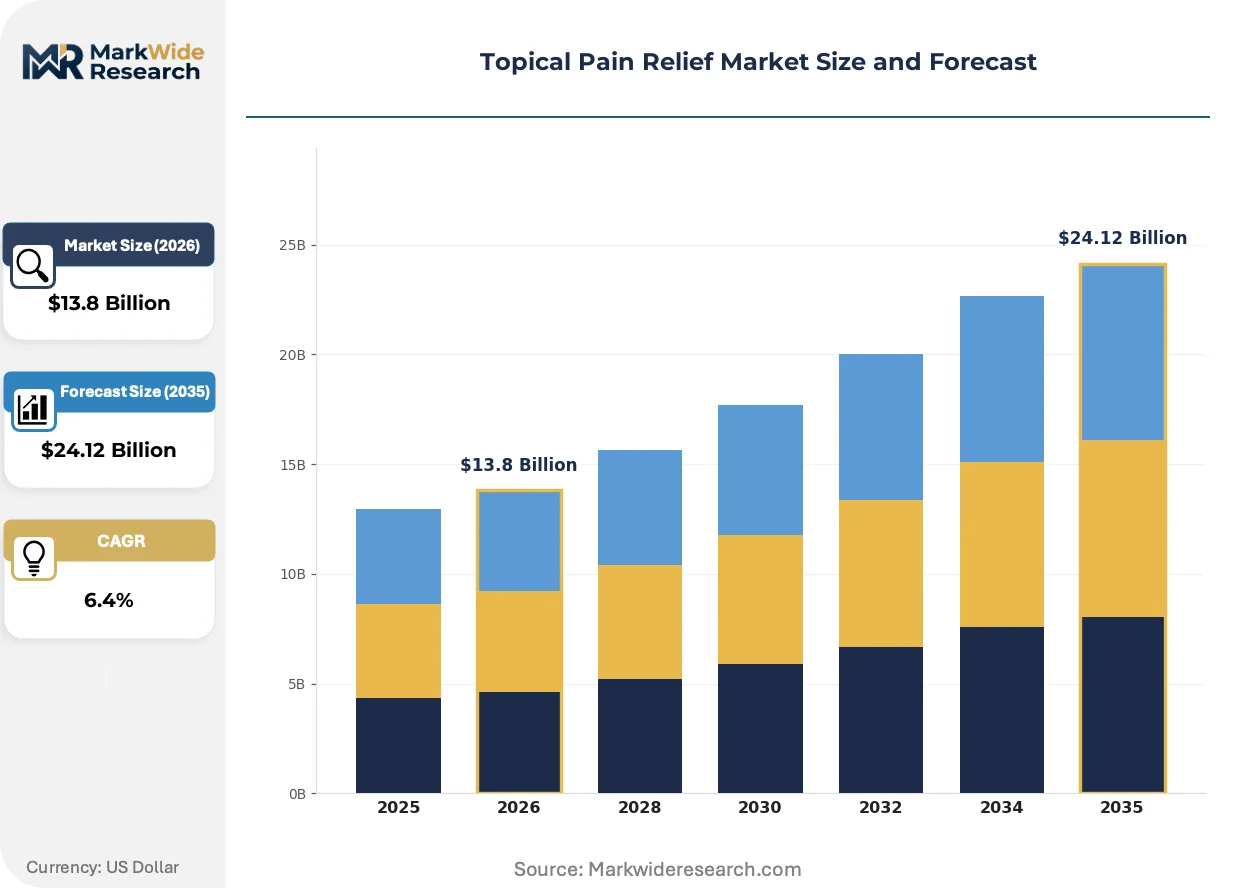
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Patches, Sprays Active Ingredient: Menthol, Camphor, Capsaicin, Salicylates Distribution Channel: Retail Pharmacies, Online Stores, Hospitals, Clinics End User: Adults, Athletes, Geriatric Population, Patients |
| Companies Covered | Johnson & Johnson, Sanofi, GlaxoSmithKline, Pfizer Inc, Novartis AG, Sun Pharmaceutical Industries Ltd, Reckitt Benckiser Group plc, Bayer AG, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Pain Relief Market Strategic Shifts & Innovations
Microstructured transdermal arrays and bioerodible microneedle platforms are compressing the efficacy gap between topical and injectable delivery, while regulatory bodies on three continents simultaneously recalibrate safety documentation requirements.
Microneedle patch technology is collapsing the historical trade-off between patient convenience and bioavailability. Sports medicine clinics in Germany and Australia are piloting dissolving arrays containing ketoprofen and diclofenac for acute soft-tissue injuries. The format is collapsing resistance among payers who previously restricted reimbursement to oral or injectable routes.
EMA's 2023 revision to its topical products quality guidelines imposes stricter in vitro release testing and scale-up validation requirements. European manufacturers must now demonstrate thermodynamic stability across expanded temperature ranges. Hospital procurement networks in France and Italy are demanding compliant documentation as a prerequisite for formulary inclusion, compressing vendor qualification cycles.
Athletic trainers and physical therapists are consolidating purchasing through group purchasing organizations and specialized sports medicine distributors. Independent retail pharmacy channels in the United States are losing volume to direct clinic dispensing and subscription-based athlete recovery kits. This consolidation is most visible in collegiate and professional sports settings where equipment managers now coordinate analgesic procurement alongside bracing and rehabilitation devices.
Topical Pain Relief Market Segmentation
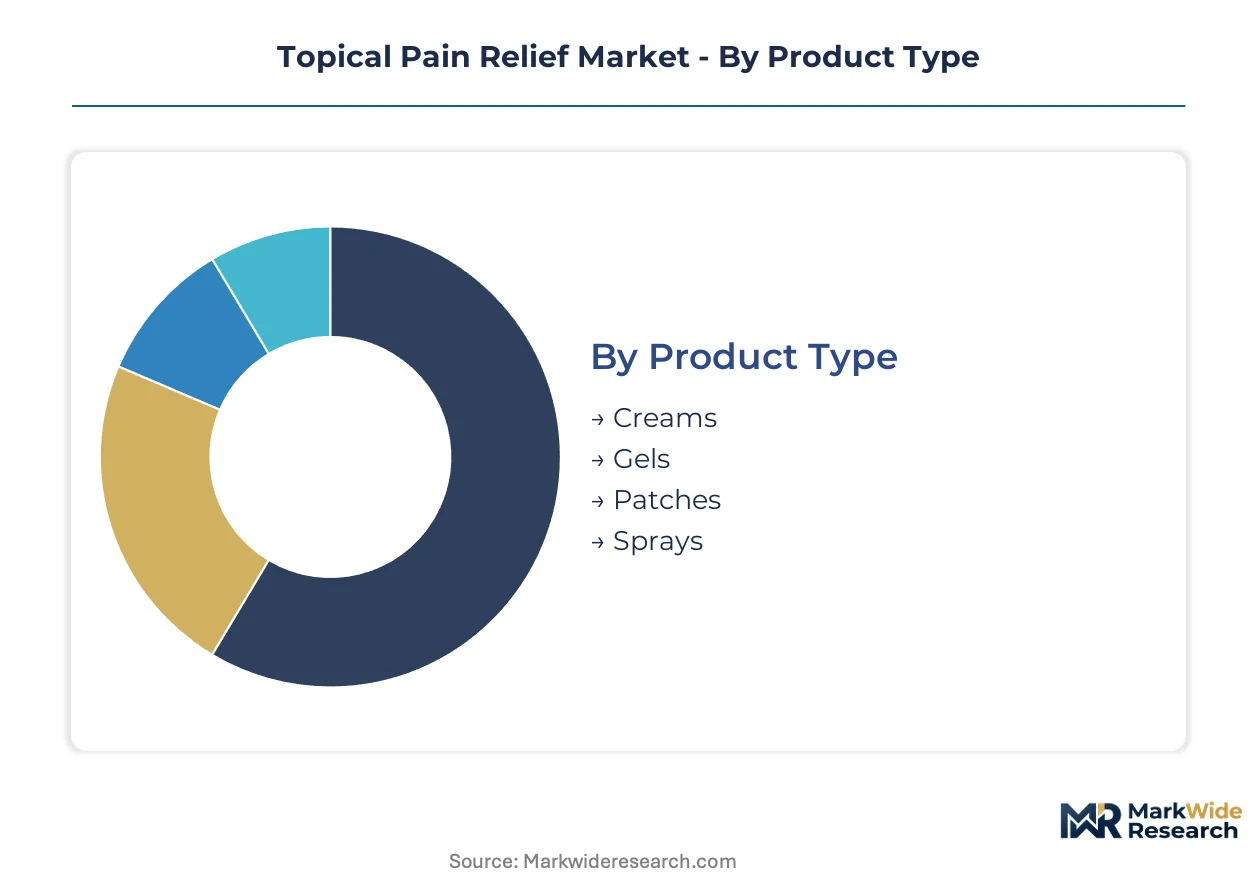
Topical pain relief formulations serve divergent use cases ranging from acute sports injuries to chronic arthritic conditions. Segmentation reveals how delivery format, active chemistry, and procurement channel each dictate distinct regulatory pathways and margin structures.
Product Type:
Use-case spectrum spans immediate cooling relief for gym-bag portability through multi-day sustained release for post-surgical recovery.
- Creams:Oil-in-water emulsions with 2-5% menthol or methyl salicylate content spread easily over large surface areas. Mass-market retail shelves in the United States allocate prime positioning to cream formats targeting arthritis sufferers in Florida and Arizona retirement communities. Established volume favors creams; emerging adoption favors patches.
- Gels:Hydroalcoholic bases with rapid evaporative cooling deliver faster onset than emulsion formats. German sports medicine clinics specify gel presentations for acute soft-tissue protocols, driving formulary preference ahead of national opioid-reduction mandates.
- Patches:Matrix or reservoir designs with defined drug release rates and 8-12 hour wear durations command premium reimbursement. Japanese PMDA approvals for lidocaine-containing patches established the clinical precedent that European EMA reviewers now reference.
- Sprays:Metered-dose aerosol or pump formats enable single-hand application for hard-to-reach anatomical locations. Australian TGA registrations for capsaicin sprays expanded the category beyond institutional settings into consumer self-selection.
Volume concentrates in creams and gels; patches capture value expansion through extended-release premiums.
Active Ingredient:
Cost tier stratification separates commodity botanical extracts from synthetic high-purity actives with documented permeation coefficients.
- Menthol:Terpene alcohol derived from peppermint oil or synthetic routes triggers TRPM8 cold receptors for immediate analgesia. Brazilian ANVISA monographs permit higher concentrations than FDA OTC limits, creating formulation divergence across export markets.
- Camphor:Ketonic terpenoid with mild counterirritant and rubefacient properties historically blended with menthol in traditional liniments. Indian BIS standards for Ayurvedic-derived camphor specifications differ from USP-NF purity grades, complicating contract manufacturing qualification.
- Capsaicin:Vanilloid alkaloid depleting substance P from nociceptive fibers requires 0.025-0.1% concentrations for neuropathic indications. High-purity synthetic production clusters in specific Chinese chemical zones, exposing supply chains to environmental compliance disruptions under MEE discharge regulations.
- Salicylates:Ester derivatives including methyl salicylate and trolamine salicylate provide topical NSAID activity with systemic absorption below oral thresholds. FDA irritation testing protocols have compressed permissible combination concentrations with menthol, forcing reformulation of legacy products.
Commodity menthol dominates unit volume; capsaicin commands specification premiums in neuropathic segments.
Distribution Channel:
Customer type determines whether procurement runs through insurance reimbursement, direct out-of-pocket payment, or institutional tender processes.
- Retail Pharmacies:Brick-and-mortar chains and independent dispensaries stock OTC formats with pharmacist counseling as a secondary purchase driver. CVS and Walgreens shelf-space allocations in California and Texas prioritize private-label menthol gels during allergy and flu seasons.
- Online Stores:Direct-to-consumer platforms and pharmacy e-commerce enable subscription replenishment for chronic users. Amazon's logistics network bypasses traditional wholesale distribution, compressing margin capture for brand manufacturers.
- Hospitals:Formulary committees within integrated delivery networks specify prescription-strength patches and compounded preparations. Kaiser Permanente and Mayo Clinic procurement protocols require documented clinical outcomes for topical NSAID inclusion.
- Clinics:Sports medicine and pain management practices increasingly dispense directly to patients, capturing retail margin. Athletes' Performance facilities in Arizona and Colorado bundle topical kits with physical therapy protocols.
Retail pharmacy retains volume leadership; clinic direct-dispensing captures margin migration from traditional channels.
End User:
Maturity gradient separates established adult self-medication from emerging athlete and geriatric segments with distinct compliance requirements.
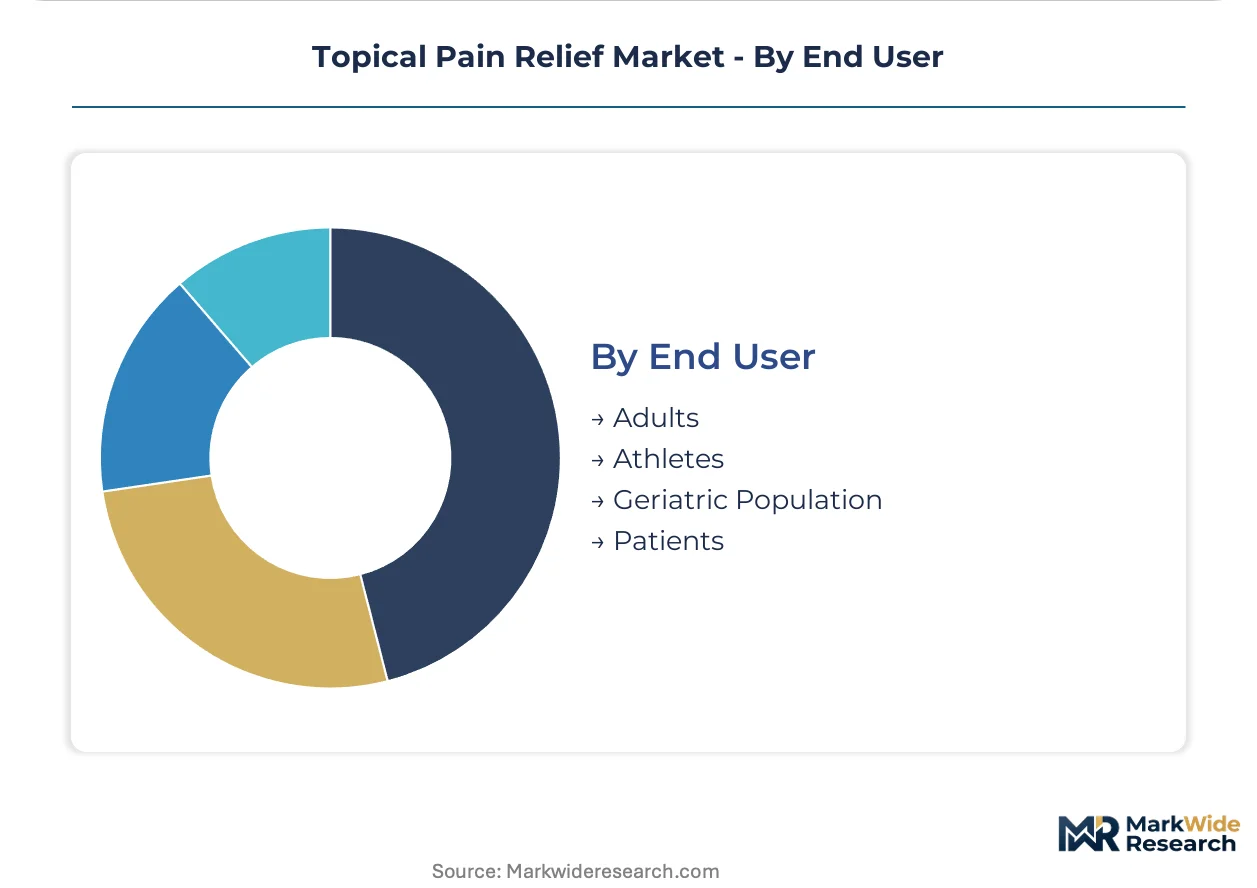
- Adults:General population aged 18-64 seeking occasional relief from minor musculoskeletal complaints represents the baseline demand pool. Occupational health programs at manufacturing facilities in Michigan and Ohio distribute counterirritant creams as first-line intervention.
- Athletes:Collegiate, professional, and recreational competitors drive uptake of cooling gels and warming rubs as recovery protocol components. NCAA training rooms and NFL locker rooms specify NSF Certified for Sport formulations to avoid banned substance contamination.
- Geriatric Population:Adults over 65 with polypharmacy concerns favor topical routes to minimize drug-drug interactions and gastrointestinal risks. Medicare Advantage plans in Florida and Pennsylvania increasingly cover prescription lidocaine patches for post-herpetic neuralgia.
- Patients:Individuals under active medical supervision for chronic pain conditions including fibromyalgia and diabetic neuropathy. Pain management clinics in New York and Massachusetts integrate topical capsaicin into multimodal regimens ahead of opioid tapering requirements.
Adult self-medication anchors volume; athlete and geriatric segments are gaining share fastest through protocol integration and reimbursement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where prescription patch premiums exceed German retail equivalents by substantial margins, while manufacturing scale advantages cluster in Chinese chemical zones serving cost-sensitive Southeast Asian markets.
United States
Medicare Advantage expansion in Florida and Pennsylvania drives prescription lidocaine patch volumes among polypharmacy-conscious seniors. FDA's ongoing OTC monograph overhaul tightens permissible salicylate concentrations, forcing reformulation of legacy combination products. Greater Boston hosts concentrated contract research capacity serving dermatological delivery system startups.
Germany
Sports medicine clinics in Bavaria and North Rhine-Westphalia specify hydroalcoholic gel formats for acute soft-tissue protocols ahead of national opioid-reduction mandates. EMA's 2023 topical products quality guidelines impose stricter in vitro release testing and expanded temperature stability validation. Frankfurt procurement networks demand compliant documentation as prerequisite for formulary inclusion.
China
Tier-2 and tier-3 city outpatient expansion creates demand for shelf-stable alternatives lacking cold-chain infrastructure. MEE discharge regulations under dual carbon goals expose synthetic capsaicin and high-purity menthol production clusters to environmental compliance disruptions. Yangtze River Delta chemical manufacturers dominate API supply for export markets.
India
Government-funded primary health centers in Maharashtra and Gujarat lack infrastructure for injectable analgesics, accelerating topical adoption. BIS standards for Ayurvedic-derived camphor specifications diverge from USP-NF purity grades, complicating contract manufacturing qualification. Karnataka's pharmaceutical formulation clusters serve domestic and African export markets.
Japan
Aging demographics in Kanto and Kansai regions sustain premium patch demand for chronic neuropathic conditions. PMDA approvals for lidocaine-containing patches established clinical precedent that European EMA reviewers now reference. Tokyo-based medical device manufacturers pioneer dissolving microneedle arrays for ketoprofen delivery.
Topical Pain Relief Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream on raw material and delivery technology vectors. The vendor base stratifies between diversified pharmaceutical conglomerates with captive consumer health divisions and asset-light entrants accessing contract manufacturing capacity. Three archetypes dominate: legacy pharmaceutical houses with dermatological R&D infrastructure, consumer health spin-offs optimizing focused investment, and specialty manufacturers leveraging ISO-certified contract production. Competitive moves concentrate on portfolio rationalization ahead of regulatory tightening and royalty-based licensing arrangements to compress capital requirements.
Among diversified pharmaceutical conglomerates, Johnson & Johnson, Sanofi, and GlaxoSmithKline exemplify distinct strategic positioning within the competitive structure. Johnson & Johnson occupies the consumer health spin-off archetype, sustaining focused R&D investment through dedicated operational structure. Sanofi anchors the controlled distribution partnership model, securing hospital procurement network access. GlaxoSmithKline represents specialized manufacturing scale advantages in transdermal patch production. These three entities collectively illustrate how legacy pharmaceutical houses are restructuring competitive approaches without converging on identical capability configurations.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Sanofi |
| GlaxoSmithKline |
| Pfizer Inc |
| Novartis AG |
| Sun Pharmaceutical Industries Ltd |
| Reckitt Benckiser Group plc |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd |
| Others |
Cost & Logistics Intelligence
Undercapacity in Yangtze River Delta synthetic capsaicin facilities is tightening supplier bargaining power and compressing margin capture for mid-tier patch manufacturers. This utilization squeeze feeds directly into formulation cost escalation and accelerates portfolio rationalization among legacy cream producers.
Pricing Analysis
The customization-premium spread between standard menthol gels and configured-to-order microneedle arrays exceeds threefold in German sports medicine procurement. Pricing stratifies across premium, standard, and economy tiers, with ISO 13485 certification and documented permeation coefficients driving differentiation. Cost compression in commodity creams is intensifying because Amazon's logistics network bypasses traditional wholesale distribution. Occupational health programs at Michigan manufacturing facilities exhibit highest price sensitivity; hospital procurement networks in Frankfurt show lowest sensitivity due to formulary lock-in.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta chemical manufacturers are becoming standard for Indian formulation clusters seeking high-purity menthol supply. API production concentrates in China, India, and Germany, with synthetic capsaicin and pharmaceutical-grade polymers as critical inputs. Single-source vulnerability in Chinese environmental compliance zones under MEE discharge regulations threatens continuity. Distribution runs through hospital procurement networks, specialized sports medicine distributors, and direct-to-clinic dispensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based athlete recovery kits and remote patient monitoring companions are expanding faster than base topical formulations, converting one-time purchases into recurring revenue streams.
For Market Incumbents: Insulate formulary positions through backward integration into high-purity menthol production and captive microneedle array manufacturing capacity. FDA's tightening dermatological safety thresholds threaten legacy combination products; vertical integration into REACH-compliant bioadhesive polymer supply secures extended-release patch margins against reformulation mandates. For New Entrants and Emerging Players: India's tier-2 and tier-3 city outpatient clinics lack cold-chain infrastructure for injectable analgesics, creating shelf-stable topical demand. Target government-funded primary health centers in Maharashtra and Gujarat through asset-light contract manufacturing partnerships. Telehealth-integrated prescription fulfillment offers the most penetrable go-to-market angle in markets with relaxed remote prescribing rules. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microneedle platform development as ISO 13485-certified contract manufacturing matures. Long-term viability favors asset-light entrants with royalty-based licensing arrangements over captive facility investment. Watch FDA OTC monograph finalization timing as the critical signal for portfolio valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | PMDA precedent for lidocaine patches accelerates EMA reviewer reference and market entry. |
| Backward Integration | Captive high-purity menthol production insulates against Yangtze River Delta environmental compliance disruptions. |
| Strategic Partnership | Controlled distribution agreements with Kaiser Permanente procurement networks secure formulary positioning. |
| Platform Integration | Dissolving microneedle arrays collapse the efficacy gap between topical and injectable delivery formats. |
| Geographic Expansion | Tier-2 and tier-3 Indian city clinic penetration bypasses cold-chain infrastructure constraints. |
Research Approach
Cross-validation between FDA filings and EMA submissions anchors the qualitative findings on regulatory pathway timelines. Primary interviews with regulatory affairs leads, formulary directors at integrated delivery networks, hospital procurement managers, and sports medicine clinicians combined with secondary validation against ClinicalTrials.gov, CMS Medicare data, and GPO contracts databases. Bottom-up patient population modeling and top-down pharmaceutical market sizing provided triangulation checks.
Calibration against historical approval-to-launch intervals and documented permeation coefficient studies shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include delivery format, active ingredient chemistry, distribution channel archetype, and end-user population cluster. CAGRs derived from patent expiration timelines, generic entry patterns, and protocol adoption curves in sports medicine settings. Forecast inputs incorporated microneedle platform clinical trial readouts and FDA monograph revision schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light microneedle entrants or unexpected FDA monograph acceleration would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Opioid Withdrawal Management Market
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
Chronic Lower Back Pain Treatment Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Global Morphine Market
Pain Management
Cold Pain Therapy Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market
Pain Management
Neuropathic Pain Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Palliative Care Market
Pain Management
Chronic Pain Treatment Market
Pain Management
Pain Therapeutic Injectables Market
Pain Management
Plantar Fasciitis Treatment Market