
 Ischemic Optic Neuropathy Treatment Market | 2026-2036
Ischemic Optic Neuropathy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ischemic Optic Neuropathy Treatment Market Foresight
CE marking under the EU Medical Device Regulation is reorganizing competitive access for European surgical intervention suppliers. Pfizer Inc. anchors its position through deep corticosteroid manufacturing scale across multiple geographies. Eli Lilly and Company differentiates via monoclonal antibody R&D pipelines targeting vascular endothelial pathways. GlaxoSmithKline competes through established hospital formulary relationships and broad neuro-ophthalmology detailing networks.
Ischemic optic neuropathy treatment encompasses pharmacological and procedural interventions designed to restore or preserve optic nerve perfusion following acute or progressive ischemic insult, typically involving corticosteroid pulse therapy, anti-VEGF intravitreous injection, or optic nerve sheath fenestration with functional goals of stabilizing visual acuity and visual field parameters. Corticosteroids dominate current prescribing patterns due to established reimbursement codes and clinician familiarity, while monoclonal antibodies represent the fastest-expanding segment driven by targeted mechanism validation in anterior ischemic optic neuropathy subtypes. Neuroprotective agents command premium positioning in long-term treatment protocols where margin pools concentrate around neurotrophic factor delivery systems.
The FDA oversees clinical trial endpoints and orphan drug exclusivity timelines for ischemic optic neuropathy indications, while the EMA's MDR framework governs surgical device market access across European member states, collectively elevating evidence thresholds for new entrants. Japan's PMDA accelerates review pathways for designated orphan diseases, reshaping regional launch sequencing for developers. Stakeholders must monitor how evolving neuro-ophthalmology biomarker qualification standards influence payer coverage determinations and prescribing protocol standardization across tertiary care networks.
Market Dynamics
Hospital-based ophthalmology departments are consolidating neuroprotective protocols around corticosteroid pulse therapy, compressing adoption timelines for alternative mechanisms and reshaping formulary negotiations with suppliers.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway accelerates developer incentives for ischemic optic neuropathy indications, reducing regulatory burden and expediting market entry timelines for novel therapeutic candidates.
- Japan's PMDA Accelerated Review:Designated orphan disease status compresses approval cycles, prompting sequential launch strategies that prioritize Japanese tertiary retinal centers.
- Neurotrophic Factor Delivery Systems:Advanced biologics targeting vascular endothelial pathways are expanding prescriber options beyond corticosteroid monotherapy in progressive anterior ischemic optic neuropathy subtypes.
Market Restraints
- Biologics Manufacturing Concentration:Monoclonal antibody production clusters among contract development organizations in Switzerland and Ireland, creating single-source vulnerability for pipeline candidates.
- CE Marking Transition Costs:EU Medical Device Regulation reclassification of optic nerve sheath fenestration instruments imposes substantial clinical evidence requirements on mid-tier surgical suppliers.
- Reimbursement Code Limitations:Established corticosteroid billing codes create formulary inertia that constrains physician willingness to prescribe premium-positioned neuroprotective agents.
Strategic Opportunities
- German Retinal Center Networks:Specialized neuro-ophthalmology clusters in Heidelberg, Tübingen, and Berlin offer concentrated trial recruitment and early-adopter prescribing for mechanism-validated therapies.
- Anti-VEGF Intravitreal Convergence:Combination protocols integrating vascular endothelial growth factor inhibition with perfusion restoration are opening protocol development partnerships between biopharma and surgical device developers.
- Tele-ophthalmology Triage Channels:Remote diagnostic platforms are compressing time-to-treatment intervals for acute anterior ischemic optic neuropathy presentations in United States rural health systems.
Industry Challenges
- Neuro-ophthalmology Fellowship Scarcity:Subspecialty training program bottlenecks in the United States and Germany constrain the clinical workforce capable of diagnosing ischemic optic neuropathy subtypes accurately.
- Biomarker Qualification Timelines:Evolving FDA and EMA standards for optic nerve perfusion surrogate endpoints are prolonging clinical trial design negotiations and protocol amendment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ischemic Optic Neuropathy Treatment Market |
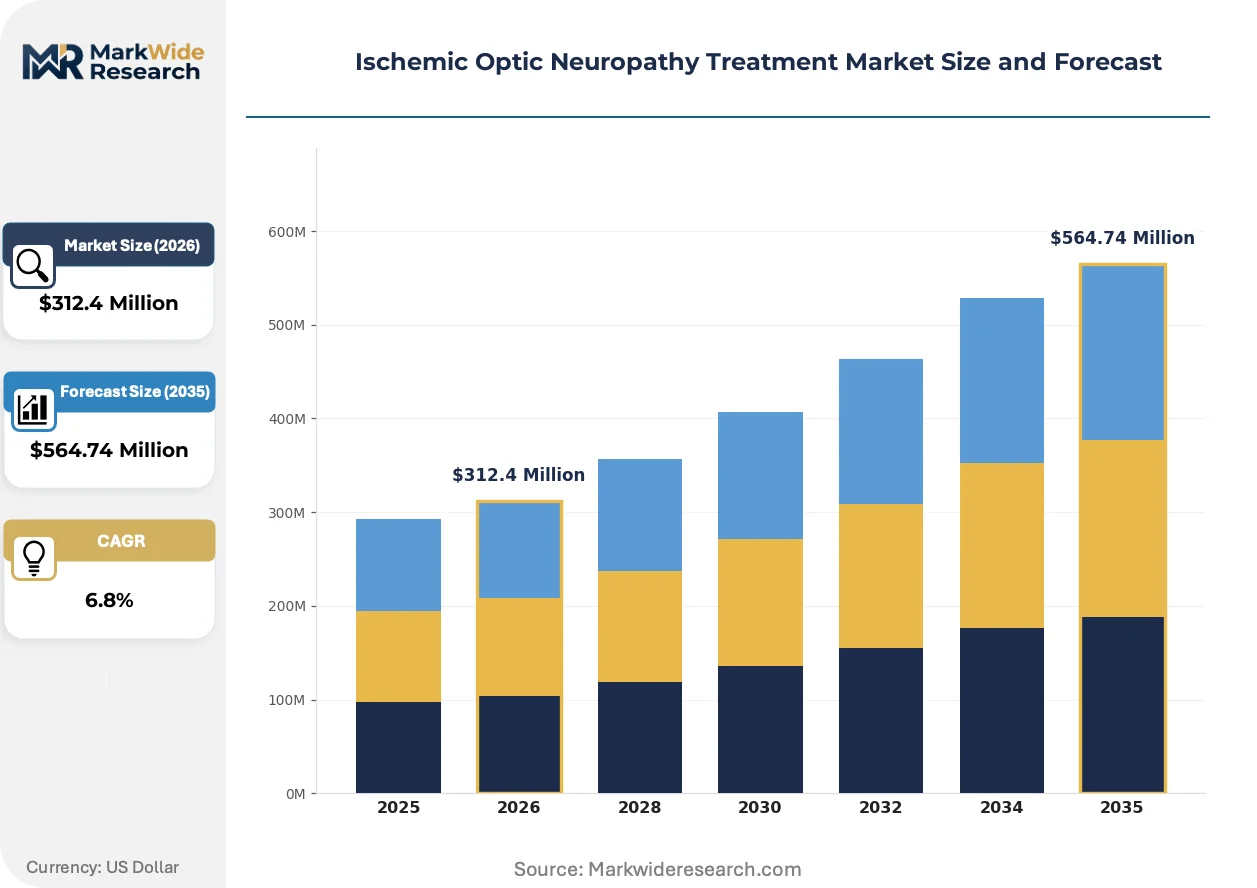
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Corticosteroids, Surgical Interventions, Neuroprotective Agents End User: Ophthalmology Clinics, Hospitals, Research Laboratories, Outpatient Facilities Delivery Mode: Intravitreous Injection, Oral Administration, Topical Application, Intravenous Infusion Stage of Treatment: Acute Management, Long-term Treatment, Follow-up Care, Preventive Strategy |
| Companies Covered | AbbVie Inc., Eli Lilly and Company, GlaxoSmithKline, Pfizer Inc., Teva Pharmaceuticals USA, Inc., Bausch Health Companies Inc., F. Hoffmann-La Roche AG, Bayer AG, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ischemic Optic Neuropathy Treatment Market Shifts & Advancements
Mechanism-driven therapeutic categorization is displacing symptom-based prescribing in neuro-ophthalmology, with vascular pathway targeting and neuroprotection emerging as distinct commercial segments requiring differentiated evidence packages.
Extended-release corticosteroid implants are supplanting systemic pulse therapy in United States academic medical centers, enabling sustained intraocular drug levels without the metabolic complications that limit outpatient compliance. Retinal specialists at tertiary centers in Philadelphia and San Francisco have adopted these depot formulations for recurrent anterior ischemic optic neuropathy cases. The shift is compressing hospital pharmacy budgets while expanding addressable patient populations previously excluded from chronic systemic therapy.
EMA's Medical Device Regulation framework is elevating clinical evidence thresholds for optic nerve sheath fenestration instruments, forcing European surgical suppliers to sponsor prospective registry studies or exit the category. German and French notified bodies are applying divergent interpretation standards, fragmenting market access timelines across member states. Retinal surgery device portfolios are restructuring toward drug-device combination submissions that leverage existing pharmaceutical regulatory pathways.
Retinal center procurement committees are consolidating vendor relationships around full-protocol suppliers capable of delivering corticosteroid, anti-VEGF, and surgical intervention bundles. Standalone pharmaceutical or device manufacturers face exclusion from formulary tiers unless they establish partnership networks or captive supply arrangements. The behavioral shift is most pronounced in United States integrated delivery networks and Japanese university hospital consortia where total cost-of-care contracts dominate purchasing decisions.
Ischemic Optic Neuropathy Treatment Market Segmentation
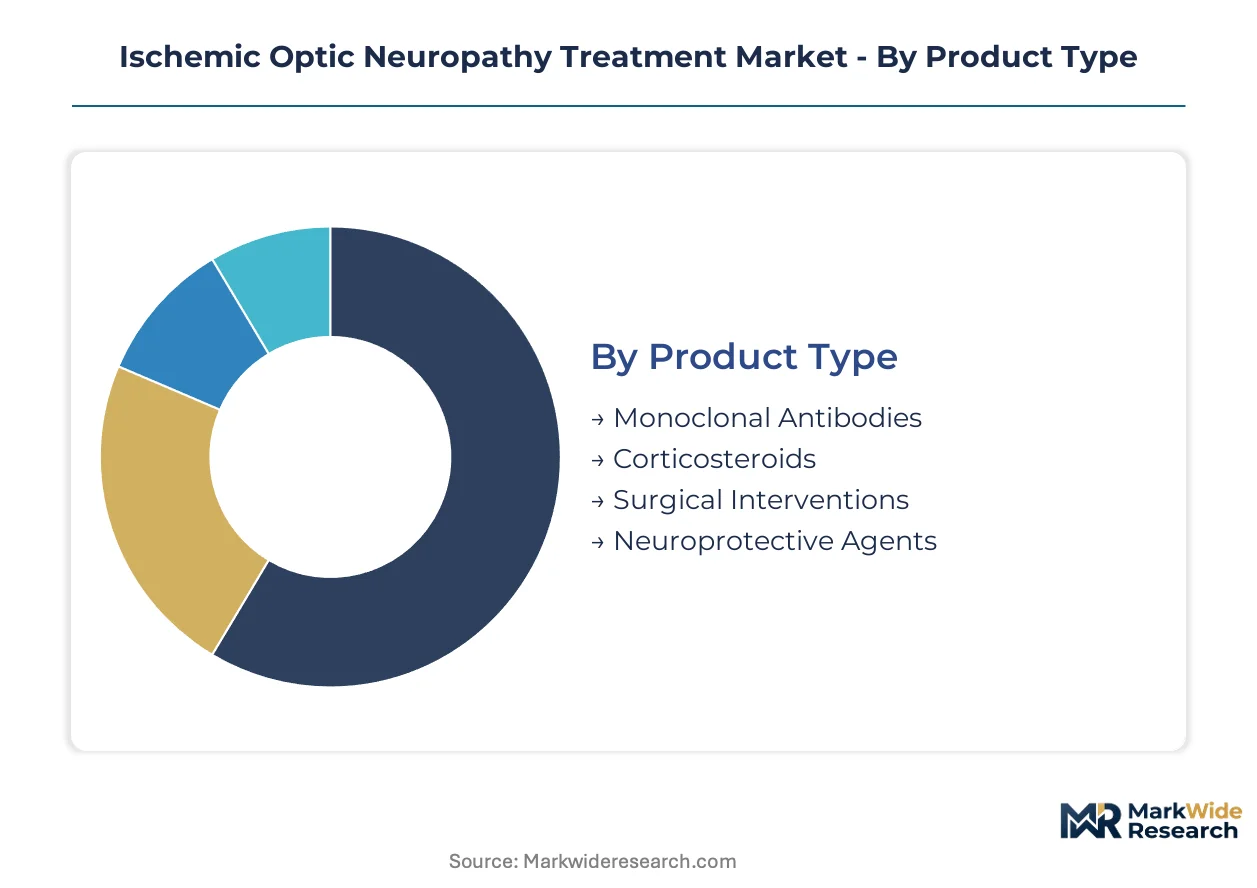
Segmentation in ischemic optic neuropathy treatment reveals how reimbursement pathways and clinical workflows fragment demand across intervention types. Understanding these divisions exposes where formulary consolidation threatens standalone suppliers and where mechanism-driven prescribing creates premium positioning opportunities.
Product Type:
Corticosteroids face the most acute substitution pressure as extended-release implants displace systemic pulse therapy in United States academic centers, while monoclonal antibodies and neuroprotective agents compete for premium-tier adoption.
- Corticosteroids:Systemic pulse therapy and intraocular depot formulations deliver high-dose methylprednisolone or triamcinolone to reduce optic nerve edema. Hospital pharmacy committees in Philadelphia and San Francisco have prioritized implant formulations to eliminate metabolic complications and outpatient compliance failures.
- Monoclonal Antibodies:Engineered proteins targeting vascular endothelial growth factor or inflammatory cytokines require cold-chain distribution and specialty infusion infrastructure. Eli Lilly's pipeline investments signal manufacturer conviction in mechanism-validated approaches for anterior ischemic optic neuropathy subtypes.
- Surgical Interventions:Optic nerve sheath fenestration and decompression procedures address refractory cases with elevated intracranial pressure.
- Neuroprotective Agents:Neurotrophic factor delivery systems and antioxidant protocols target long-term axonal preservation.
Corticosteroids retain volume leadership; monoclonal antibodies hold the steepest expansion curve.
End User:
Procurement authority concentrates differently across settings, with integrated delivery networks centralizing purchasing for hospitals while ophthalmology clinics maintain prescriber autonomy.
- Hospitals:Tertiary retinal centers in Heidelberg, Tübingen, and Berlin command complete protocol control from diagnosis through intervention. Japanese university hospital consortia bundle corticosteroid, anti-VEGF, and surgical vendor relationships into total cost-of-care contracts.
- Ophthalmology Clinics:Private practice retinal specialists in the United States rural health systems leverage tele-ophthalmology triage to compress acute presentation-to-treatment intervals. These settings favor intravitreous injection protocols that minimize facility fee dependencies.
- Outpatient Facilities:Ambulatory surgery centers perform optic nerve sheath fenestration under regional anesthesia protocols.
- Research Laboratories:Academic medical centers conduct biomarker qualification studies and orphan drug trials under FDA and EMA oversight.
Hospitals dominate revenue capture; ophthalmology clinics are gaining share fastest through procedure migration.
Delivery Mode:
Route selection determines reimbursement coding complexity and prescriber training requirements, with invasive methods commanding higher facility fees but facing stricter prior authorization.
- Intravitreous Injection:Direct anti-VEGF or corticosteroid delivery into the vitreous cavity achieves therapeutic concentrations without systemic exposure. Retinal specialists at German centers have standardized anti-VEGF protocols for anterior ischemic optic neuropathy with macular involvement.
- Oral Administration:Systemic corticosteroid protocols require endocrinology co-management for glucose and bone density monitoring.
- Intravenous Infusion:Monoclonal antibody delivery demands infusion center capacity and nursing specialization.
- Topical Application:Limited penetration restricts use to anterior segment adjunctive therapy.
Intravitreous injection retains procedural dominance; intravenous infusion is climbing the fastest as biologics expand.
Stage of Treatment:
Timing of intervention dictates evidence requirements and payer coverage determination, with acute presentations qualifying for emergency authorization while preventive strategies face actuarial skepticism.
- Acute Management:Corticosteroid pulse therapy initiated within hours to days of vision loss presentation aims to salvage perfusion before irreversible axonal injury. United States integrated delivery networks have established 24-hour neuro-ophthalmology consultation protocols.
- Long-term Treatment:Neuroprotective agent protocols for progressive anterior ischemic optic neuropathy require sustained adherence monitoring.
- Follow-up Care:Visual field and optical coherence tomography surveillance tracks treatment response.
- Preventive Strategy:Risk factor modification in contralateral eye protection remains underpenetrated.
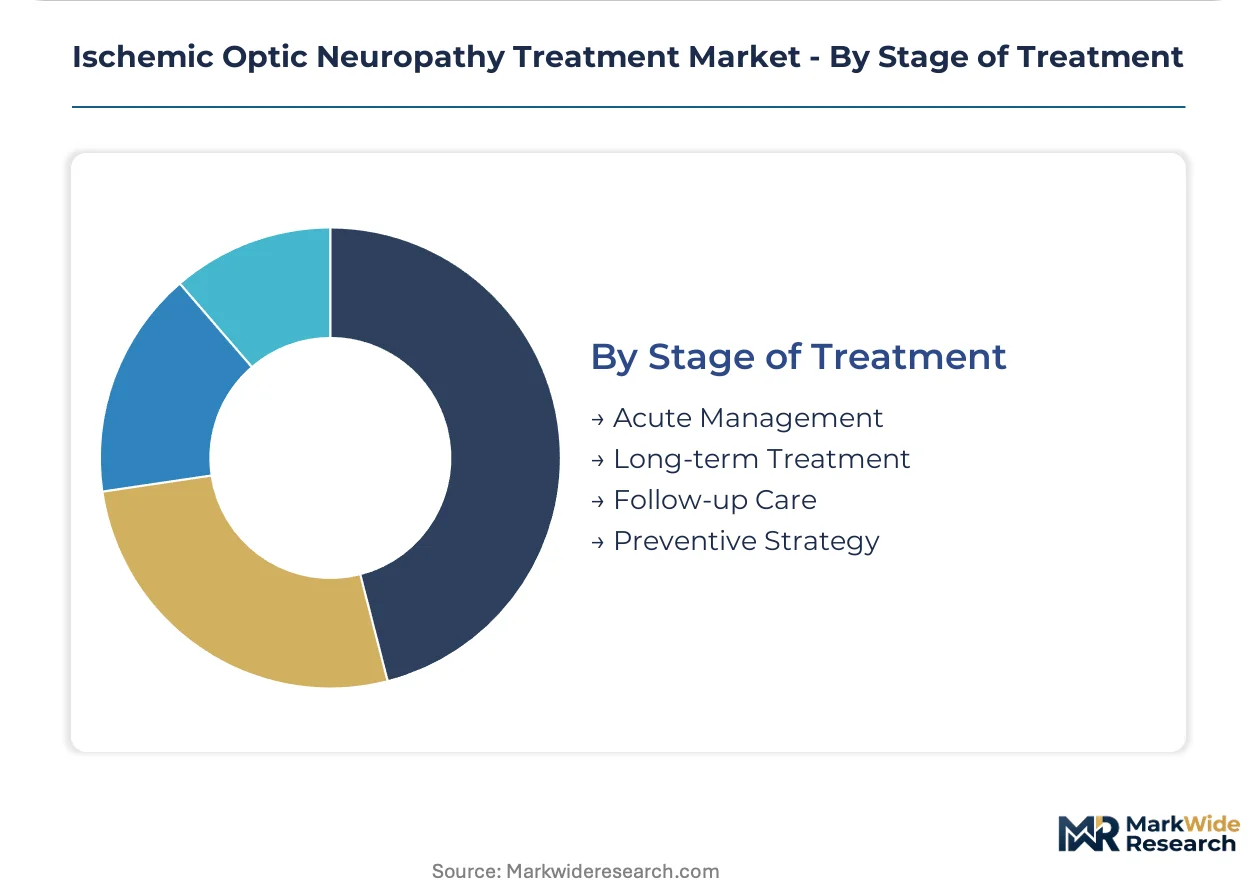
Acute management captures the highest per-episode reimbursement; long-term treatment offers the most durable revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized retinal centers in the United States, Germany, and Japan concentrate the highest-value prescribing for ischemic optic neuropathy interventions. Tertiary hospitals in these markets command protocol authority that shapes regional adoption curves.
United States
Integrated delivery networks in Philadelphia and San Francisco drive extended-release corticosteroid implant uptake. FDA orphan drug designation accelerates developer incentives for novel mechanisms. Academic medical centers in the Northeast Corridor conduct biomarker qualification studies under FDA oversight.
Germany
Specialized neuro-ophthalmology clusters in Heidelberg, Tübingen, and Berlin standardize anti-VEGF protocols for anterior ischemic optic neuropathy. EMA MDR reclassification elevates clinical evidence thresholds for surgical device suppliers. Retinal centers in Baden-Württemberg consolidate vendor relationships around full-protocol bundles.
Japan
PMDA accelerated review pathways compress approval cycles for designated orphan diseases. University hospital consortia bundle corticosteroid, anti-VEGF, and surgical vendor contracts. Tertiary retinal centers in Tokyo and Osaka prioritize mechanism-validated therapies for progressive subtypes.
Switzerland
Contract development organizations cluster monoclonal antibody production for European pipeline candidates. Swissmedic maintains alignment with EMA orphan drug frameworks. Basel-area biologics manufacturing creates single-source vulnerability for active pharmaceutical ingredients.
United Kingdom
NHS specialized commissioning frameworks concentrate ischemic optic neuropathy treatment in London and Southeast retinal centers. MHRA post-Brexit divergence from EMA MDR creates parallel compliance obligations. Academic hospitals in the Midlands participate in EMA biomarker qualification consortia.
Ischemic Optic Neuropathy Treatment Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established neuro-ophthalmology detailing networks. The competitive structure tiers across corticosteroid manufacturers, monoclonal antibody developers, and surgical device suppliers. Dominant archetypes include scale-driven corticosteroid producers, mechanism-focused biologics specialists, and integrated drug-device bundlers. Capacity expansion in biologics manufacturing and strategic partnerships for combination protocols represent the two prevailing competitive moves.
Among US-based pharmaceutical conglomerates, Pfizer Inc., Eli Lilly and Company, and AbbVie Inc. occupy distinct positioning vectors. Pfizer exemplifies the scale-driven corticosteroid archetype through manufacturing breadth across multiple geographies. Eli Lilly represents the mechanism-focused biologics specialist with monoclonal antibody R&D targeting vascular endothelial pathways. AbbVie sits within the integrated bundler tier, leveraging immunology infrastructure for neuro-ophthalmology portfolio extension. European players including F. Hoffmann-La Roche AG and Bayer AG anchor regional market access through established hospital formulary relationships.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline |
| Pfizer Inc. |
| Teva Pharmaceuticals USA, Inc. |
| Bausch Health Companies Inc. |
| F. Hoffmann-La Roche AG |
| Bayer AG |
| Sanofi S.A. |
| Others |
Supply & Pricing Matrix
Extended-release corticosteroid implants displacing systemic pulse therapy in United States academic centers simultaneously redraws manufacturing geography toward Swiss and Irish contract development organizations while compressing reimbursement economics for hospital pharmacy committees.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate monoclonal antibody procurement between biopharma developers and European contract manufacturers. Three-tier pricing structure across premium neuroprotective agents, standard corticosteroid protocols, and economy systemic generics reflects mechanism validation status and cold-chain infrastructure requirements. Pricing pressure stems from integrated delivery network formulary consolidation around bundled protocol suppliers. Ophthalmology clinics in rural United States health systems exhibit highest price sensitivity due to facility fee dependencies, while Japanese university hospital consortia demonstrate lowest sensitivity under total cost-of-care contracting.
Supply Chain Analysis
Inventory lead times for monoclonal antibody production stretch 18-24 months from cell line development to finished drug substance, constraining responsiveness to demand surges in anterior ischemic optic neuropathy indications. Biologics manufacturing concentrates in Switzerland, Ireland, and the United States, with active pharmaceutical ingredient production drawing from Basel-area CMO clusters and Dublin-region fill-finish facilities. Single-source vulnerability pervades neurotrophic factor delivery systems due to specialized bioreactor requirements. Distribution runs through cold-chain logistics networks serving tertiary retinal centers in Heidelberg, Philadelphia, and Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated around integrated delivery networks and Japanese university hospital consortia, fragmenting procurement authority previously held by standalone ophthalmology clinics and forcing supplier restructuring toward full-protocol bundling.
For Market Incumbents: Shield corticosteroid market share through captive manufacturing of extended-release implants in United States-based facilities, reducing exposure to Swiss CMO single-source vulnerability. Deepen hospital formulary relationships via neuro-ophthalmology detailing networks that embed prescribing protocols within academic medical center residency programs. Prioritize reimbursement strategy investment to secure billing code expansion for mechanism-validated alternatives before monoclonal antibodies achieve widespread adoption.
For New Entrants and Emerging Players: FDA orphan drug designation fast-track offers the most penetrable regulatory pathway for novel vascular endothelial targeting mechanisms, compressing approval timelines and accelerating market entry. Target German retinal center networks in Heidelberg and Tübingen for early-adopter clinical validation, leveraging concentrated prescriber influence to drive protocol adoption. Pursue drug-device combination submissions that bypass standalone surgical device CE marking requirements under EMA MDR frameworks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract development organizations holding monoclonal antibody manufacturing capacity in Ireland and Switzerland. Long-term viability hinges on mechanism differentiation beyond corticosteroid substitution, with neuroprotective agent platforms offering durable revenue streams in progressive anterior ischemic optic neuropathy subtypes. Watch biomarker qualification timelines at FDA and EMA as the critical inflection signal for payer coverage expansion and prescribing protocol standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA pathway reduces regulatory burden and accelerates exclusivity timelines for novel mechanisms. |
| CE Marking Pathway Restructuring | EMA MDR reclassification elevates evidence thresholds for optic nerve sheath fenestration instruments. |
| Hospital System Partnership | United States integrated delivery networks consolidate vendor relationships around full-protocol bundles. |
| Manufacturing Scale-Up | Swiss and Irish CMO capacity expansion addresses single-source vulnerability in monoclonal antibody supply. |
| Reimbursement Strategy | Billing code expansion for neuroprotective agents unlocks formulary access beyond corticosteroid inertia. |
Research Methodology
Operator-level perspectives from retinal specialists, hospital pharmacy directors, neuro-ophthalmology fellowship program directors, and payer access specialists anchored the qualitative base for this study. Primary interview data combined with secondary validation from FDA orphan drug filings, EMA MDR submission databases, ClinicalTrials.gov protocol registries, and Japanese PMDA accelerated review announcements. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation cross-verified segment-level estimates across treatment modalities and regional clusters.
Sensitivity analysis tested forecast robustness against biomarker qualification timeline delays, reimbursement code expansion scenarios, and CMO capacity constraint assumptions across the projection horizon. Segmentation dimensions modeled include product type, end user setting, delivery mode, and stage of treatment progression, with regional regulatory clusters capturing FDA, EMA, and PMDA pathway differentiation. CAGRs derived from log-linear trend fitting to historical adoption curves, adjusted for mechanism-validation inflection points in monoclonal antibody pipelines.
Decision-makers should treat outputs as directional under assumptions of sustained orphan drug incentive structures and stable neuro-ophthalmology fellowship training capacity; material deviation in biomarker qualification standards or reimbursement policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Uveal Melanoma Treatment Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Retinoblastoma Treatment Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
United States Dry Eye Syndrome Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Astigmatism Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Diabetic Macular Edema Treatment Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Amblyopia Treatment Market