
 Global Topical Analgesic Market | 2026-2036
Global Topical Analgesic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Topical Analgesic Market Foresight
Software-defined dosing platforms embedded in connected patches is broadening the service layer beyond the physical product. Johnson & Johnson leverages its consumer health infrastructure to sustain pharmacy shelf presence across North America. Hisamitsu Pharmaceutical dominates transdermal patch manufacturing through backward integration into adhesive polymer supply. Sun Pharmaceutical Industries Ltd anchors its position in emerging markets with localized cream formulations.
Topical analgesics comprise active pharmaceutical ingredients such as diclofenac, lidocaine, capsaicin, or menthol formulated in semisolid or transdermal delivery vehicles designed for localized pain modulation without systemic circulation. The segment of patches leads value generation due to extended-release kinetics and premium pricing tied to multi-day wear formulations. Creams and gels compete intensely in retail pharmacy channels where immediate cooling or warming sensations drive impulse purchases. Neuropathic pain management applications represent the fastest-growing clinical indication as diabetic peripheral neuropathy prevalence rises in aging populations.
The FDA OTC monograph reform and EMA's MDR classification for active substance-containing devices are tightening stability testing and clinical evidence requirements for transdermal systems. Health Canada's PMRA and Japan's PMDA enforce divergent labeling standards that fragment packaging strategies for multinational portfolios. Stakeholders must monitor how pharmacovigilance data from connected delivery devices reshapes regulator expectations for real-world efficacy documentation.
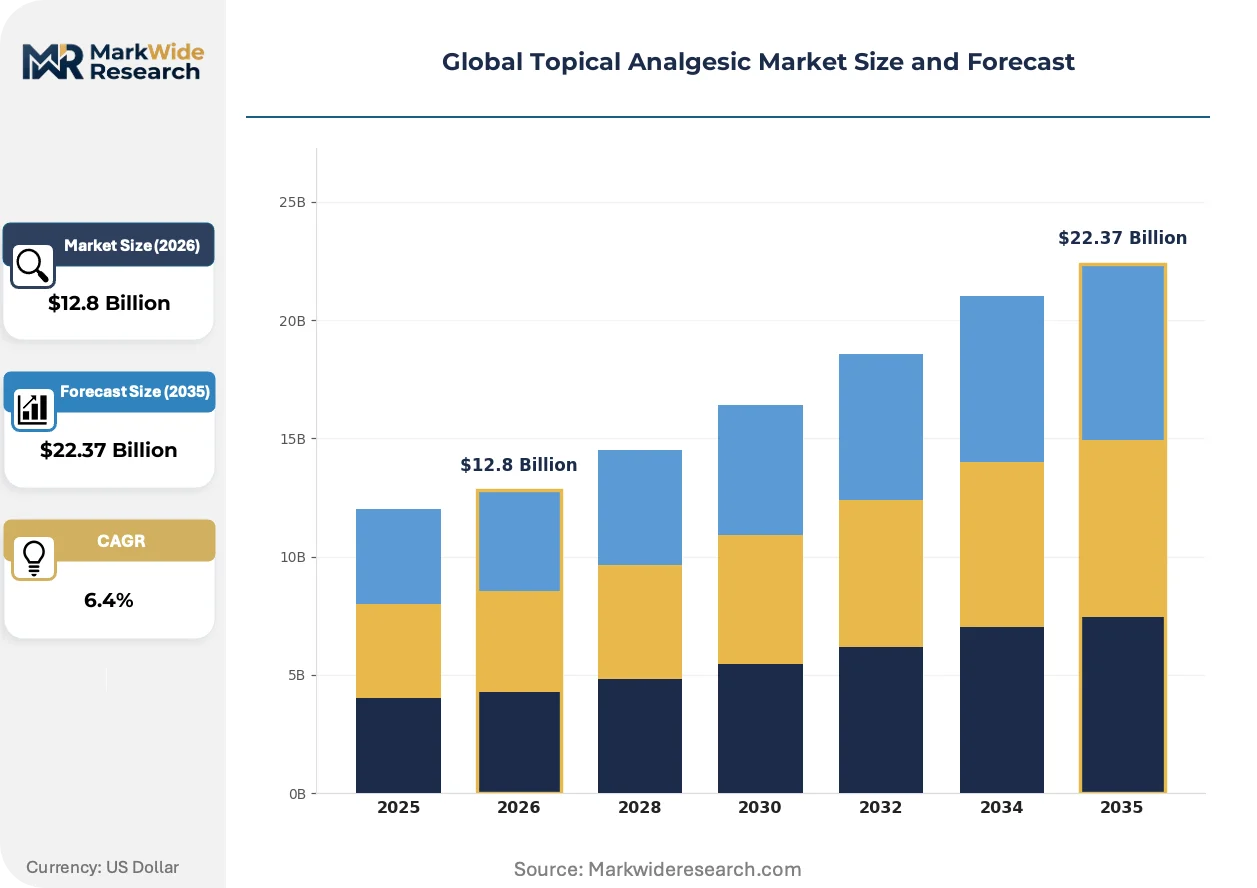
Market Dynamics
The FDA's OTC monograph reform is compressing formulation timelines while forcing manufacturers to rebuild stability datasets for legacy transdermal products. This regulatory pressure is concentrating investment in connected patch platforms that can generate real-world evidence streams.
Growth Catalysts
- Sports rehabilitation procurement:Professional athletic facilities in Germany and Japan are standardizing multi-day patch protocols for acute injury management. Extended-release kinetics reduce dosing frequency for competitive athletes.
- REACH compliance automation:European adhesive polymer suppliers are pre-certifying excipient portfolios for transdermal applications. This streamlines toxicology documentation for patch manufacturers targeting EMA MDR pathways.
- Neuropathic pain protocols:Diabetic peripheral neuropathy screening programs in the United States are expanding capsaicin patch reimbursement. Aging demographics concentrate demand in Medicare-eligible populations.
Market Restraints
- API supply concentration:Lidocaine base production clusters in Indian chemical hubs subject to environmental compliance shutdowns. Formulators face input volatility from concentrated upstream supply.
- Adhesive polymer import dependency:Silicone and acrylic pressure-sensitive adhesives for multi-day wear derive primarily from German and Japanese specialty chemical producers. Geographic concentration creates single-source risk.
- Transdermal permeation limits:Large-molecule biologics cannot achieve therapeutic flux through intact stratum corneum. This technical ceiling restricts pipeline expansion beyond small-molecule actives.
Strategic Opportunities
- Software-defined dosing platforms:Connected patches with embedded microprocessors enable programmable release profiles. Convergence of transdermal delivery and digital therapeutics opens subscription revenue models beyond physical product sales.
- Brazilian regulatory harmonization:ANVISA's alignment with ICH stability guidelines reduces redundant testing for multinational portfolios. Early entrants capture pharmacy shelf space in expanding private insurance markets.
- Veterinary pain management:Equine and companion animal applications remain underpenetrated for lidocaine patches. Species-specific adhesive formulations represent untapped white space.
Industry Challenges
- Biostatistics talent scarcity:Real-world evidence generation from connected devices requires pharmacovigilance specialists capable of interpreting sensor-derived efficacy signals. Training pipelines lag device deployment timelines.
- Legacy system integration:Pharmaceutical quality management systems require retrofitting to ingest continuous data streams from IoT-enabled patches. Validation protocols for automated adverse event detection remain undefined.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Topical Analgesic Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Creams, Patches, Sprays, Oils Application: Muscle Pain Relief, Joint Pain Treatment, Neuropathic Pain Management, Post-Surgical Pain Care End User: Pharmacies, Hospitals, Physiotherapy Clinics, Sports Rehabilitation Centers Distribution Channel: Online Pharmacies, Retail Pharmacies, Direct Sales, Drugstores, Clinics |
| Companies Covered | Johnson & Johnson, Sun Pharmaceutical Industries Ltd, Haleon plc, Sanofi, GlaxoSmithKline, Novartis AG, Pfizer Inc., Reckitt Benckiser Group plc, Hisamitsu Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Topical Analgesic Market Shifts & Advancements
Formulation science and digital connectivity are converging to transform topical analgesics from passive commodities into programmable therapeutic systems. This shift redefines value capture toward data services and adherence monitoring.
Microstructured transdermal arrays are modularizing delivery architecture for high-molecular-weight actives previously excluded from patch formats. Sports medicine clinics in the United States are piloting these systems for ketoprofen delivery. The technology is modularizing competitive positioning around bioavailability enhancement rather than formulation chemistry alone.
EMA's MDR classification for active substance-containing devices is reclassifying combination patches as medical devices rather than pharmaceuticals. Manufacturers must now submit clinical performance data under notified body review. Transdermal systems with integrated sensors face the steepest compliance burden in European markets.
Pharmacy benefit managers are compressing reimbursement cycles for extended-wear formulations. United States payers now require documented adherence metrics before authorizing multi-month supplies. This behavioral shift forces manufacturers to embed connectivity or risk exclusion from preferred drug lists.
Global Topical Analgesic Market Segmentation
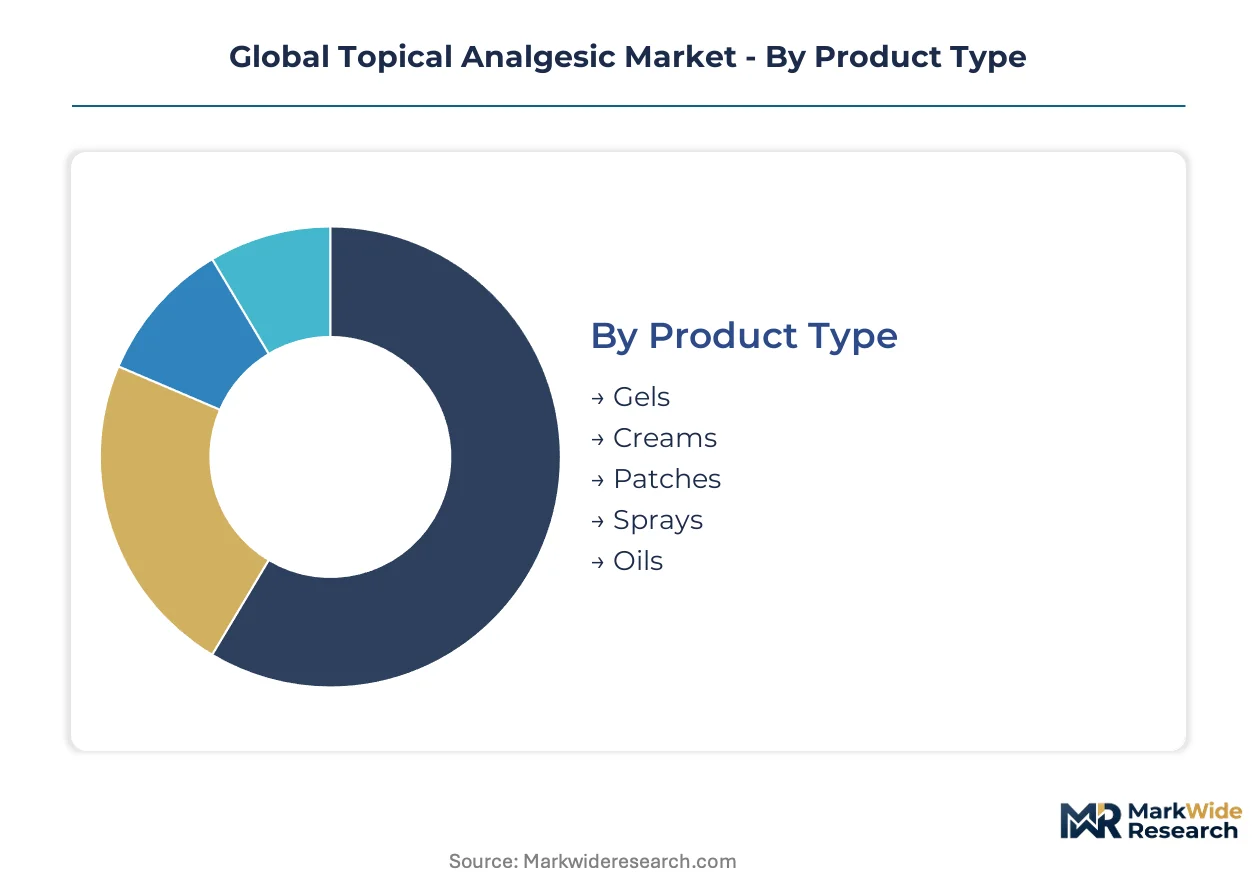
Topical analgesic segmentation reveals how formulation format, clinical indication, and procurement channel each impose distinct regulatory and commercial requirements. Understanding these boundaries helps manufacturers align development spend with the specific compliance burdens and margin structures of each slice.
Product Type:
FDA OTC monograph compliance varies sharply across formats, with transdermal patches facing the steepest stability testing requirements under evolving reform timelines while sprays and oils operate under lighter documentation loads.
- Patches:Multi-day wear systems utilizing silicone or acrylic pressure-sensitive adhesives for extended-release kinetics. Demand concentrates in sports rehabilitation centers across Germany and Japan where competitive athletes require reduced dosing frequency during training cycles.
- Creams:Semisolid emulsions formulated for immediate cooling or warming sensory feedback. Retail pharmacy channels in the United States drive volume through impulse purchase behavior tied to visible shelf placement and tactile packaging.
- Gels:Aqueous-based vehicles with faster skin penetration than creams. Hospital formulary procurement favors gel formats for post-surgical applications requiring rapid onset without occlusive dressing interference.
- Sprays:Metered-dose aerosol or pump systems for hard-to-reach anatomical areas. Direct sales channels target elderly populations with limited manual dexterity for self-application.
- Oils:Lipid-based carriers often combined with herbal actives for massage-integrated therapy. Physiotherapy clinics in Japan incorporate oil formats into manual manipulation protocols.
Patches sit at the top of the volume ranking, with neuropathic pain management applications climbing the fastest.
Application:
Payer reimbursement intensity and clinical evidence requirements diverge across pain etiologies, with neuropathic indications demanding the most extensive real-world efficacy documentation for Medicare authorization.
- Neuropathic Pain Management:Capsaicin and lidocaine formulations targeting diabetic peripheral neuropathy. Medicare-eligible populations in the United States concentrate demand as screening programs expand patch reimbursement coverage.
- Muscle Pain Relief:Counterirritant-based products utilizing menthol or methyl salicylate for acute strain. Sports rehabilitation centers standardize multi-day patch protocols for competitive athletic facilities.
- Joint Pain Treatment:NSAID-based formulations for osteoarthritis symptom modulation. Retail pharmacy chains compete on private-label diclofenac gel pricing.
- Post-Surgical Pain Care:Hospital-controlled distribution of lidocaine patches for incision-site management. EMA MDR classification is reclassifying combination patches as medical devices in European markets.
Neuropathic pain management commands premium pricing tiers, with post-surgical pain care expanding most quickly due to ambulatory surgical center growth.
End User:
Procurement sophistication and connectivity requirements scale with institutional size, from automated inventory systems in hospital networks to manual reorder cycles in independent physiotherapy practices.
- Sports Rehabilitation Centers:Specialized facilities requiring extended-wear formulations for athlete compliance. Germany and Japan lead procurement standardization for acute injury management protocols.
- Hospitals:Formulary-controlled purchasing with emphasis on infection prevention and adverse event tracking. Connected patch platforms generate pharmacovigilance data for quality management system integration.
- Pharmacies:Front-of-store placement drives impulse purchase behavior for immediate-relief formats. Shelf space competition intensifies between private-label and branded offerings.
- Physiotherapy Clinics:Manual therapy integration favors oil and cream formats for provider-applied treatment. Patient education requirements elevate staff training costs.
Pharmacies anchor volume throughput, with sports rehabilitation centers gaining share fastest as professional athletic investment expands.
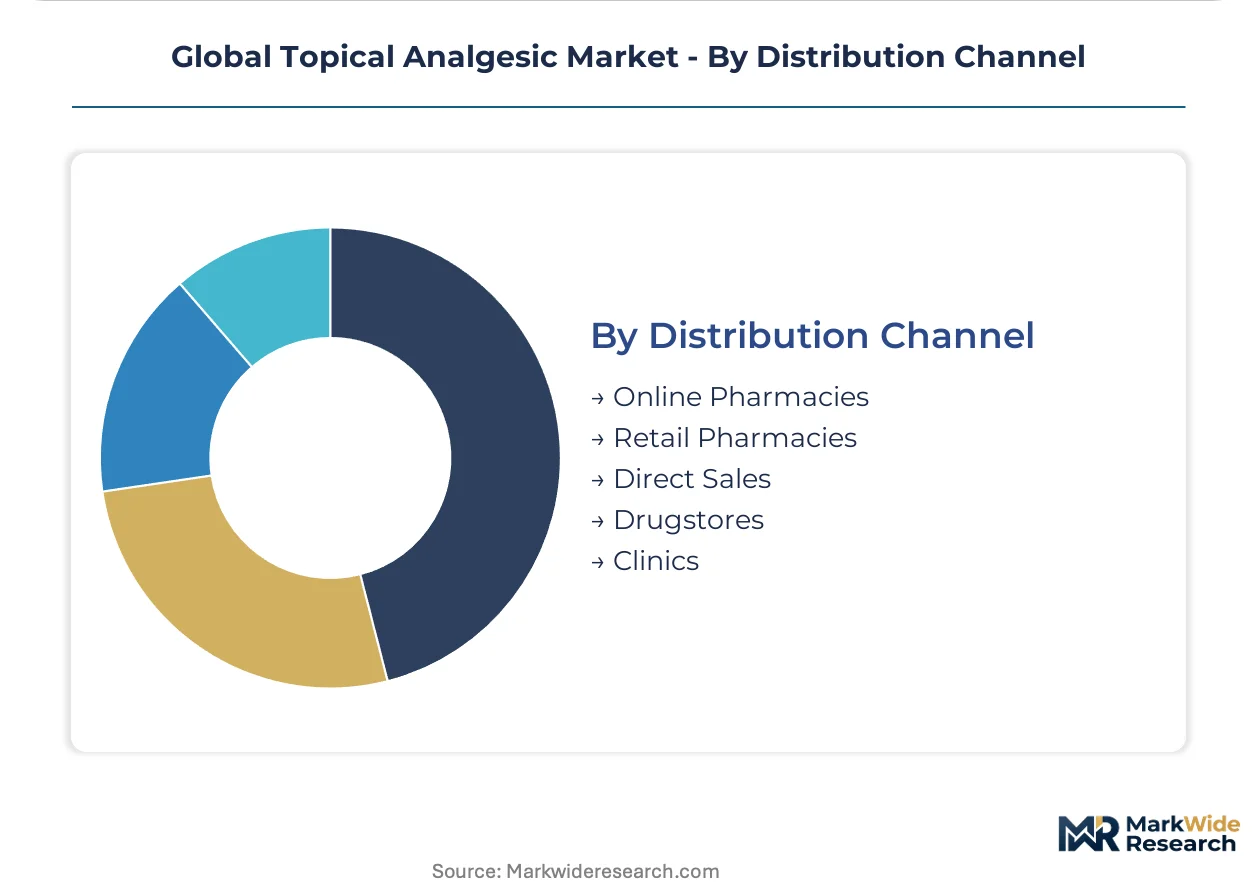
Distribution Channel:
Channel selection determines labeling compliance burden, with online pharmacies facing emerging track-and-trace requirements while clinic-direct distribution operates under practitioner dispensing exemptions.
- Online Pharmacies:E-commerce platforms requiring temperature-controlled logistics for adhesive stability. United States and European markets face tightening serialization mandates for cross-border shipment.
- Retail Pharmacies:Brick-and-mortar networks with planogram-driven shelf placement economics. Johnson & Johnson leverages consumer health infrastructure for North American pharmacy presence.
- Clinics:Provider-dispensed models bypassing retail markup for reimbursed indications. Diabetic peripheral neuropathy screening programs channel volume through specialty care settings.
- Drugstores:Convenience-oriented formats emphasizing travel-size and single-dose packaging. Impulse purchase placement competes with adjacent OTC categories.
- Direct Sales:Manufacturer-to-consumer models for subscription-based connected patch services. Software-defined dosing platforms enable recurring revenue beyond physical product.
Retail pharmacies dominate transaction volume, with online pharmacies showing the steepest expansion trajectory as digital prescription adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan concentrate procurement sophistication for extended-wear formulations, while the United States anchors volume throughput through retail pharmacy networks and Medicare reimbursement expansion.
United States
Diabetic peripheral neuropathy screening programs and Medicare-eligible aging demographics drive capsaicin patch demand. The FDA's evolving OTC monograph reform compresses formulation timelines and forces stability dataset rebuilds for legacy transdermal products. Boston and Minneapolis clusters host pharmacovigilance specialists interpreting sensor-derived efficacy signals from connected patch platforms.
Germany
Professional athletic facilities standardize multi-day patch protocols for acute injury management in competitive sports. REACH compliance automation among adhesive polymer suppliers streamlines toxicology documentation for EMA MDR pathways. The Rhine-Ruhr industrial corridor concentrates silicone and acrylic pressure-sensitive adhesive production for multi-day wear systems.
Japan
Aging populations and physiotherapy clinic integration of oil formats into manual manipulation protocols concentrate chronic pain management demand. PMDA enforces divergent labeling standards that fragment packaging strategies for multinational portfolios. The Kansai region around Osaka anchors Hisamitsu Pharmaceutical's backward integration into adhesive polymer supply chains.
India
Sun Pharmaceutical Industries Ltd anchors emerging market positioning through localized cream formulations and lidocaine base production clustering. Environmental compliance shutdowns in chemical hubs create input volatility for formulators facing concentrated upstream supply. Mumbai and Hyderabad clusters specialize in generic API manufacturing for export-oriented transdermal applications.
Brazil
Expanding private insurance markets and pharmacy shelf space competition attract early entrants following ANVISA's alignment with ICH stability guidelines. Reduced redundant testing requirements lower barriers for multinational portfolio entry. São Paulo's pharmaceutical distribution networks concentrate import logistics for temperature-sensitive adhesive products.
Global Topical Analgesic Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consumer health conglomerates dominating retail pharmacy shelf space while pharmaceutical pure-plays control hospital formulary procurement. The vendor base organizes around three strategic archetypes: diversified consumer health giants with North American pharmacy infrastructure, Japanese and German transdermal specialists with captive adhesive supply, and emerging market generic formulators with localized semisolid portfolios. Competitive moves concentrate on M&A for connected device capabilities and strategic partnerships for real-world evidence generation platforms.
Within the diversified consumer health tier, Johnson & Johnson and Haleon plc occupy positions sustained by front-of-store retail presence and impulse purchase economics. Hisamitsu Pharmaceutical Co., Inc. exemplifies the transdermal specialist archetype through its integration into upstream adhesive polymer production. Sun Pharmaceutical Industries Ltd represents the emerging market generic formulator model with India-based manufacturing and localized cream portfolios.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Sun Pharmaceutical Industries Ltd |
| Haleon plc |
| Sanofi |
| GlaxoSmithKline |
| Novartis AG |
| Pfizer Inc. |
| Reckitt Benckiser Group plc |
| Hisamitsu Pharmaceutical |
| Others |
Supply & Pricing Matrix
Pharmacovigilance specialists concentrated in Boston and Minneapolis clusters command wage premiums that propagate through connected patch development costs, widening spreads between premium software-enabled tiers and economy semisolid formats.
Pricing Analysis
Capacity additions in Indian chemical hubs are reshaping price floors for lidocaine base and generic API inputs, compressing margins for commoditized cream and gel formats. Three-tier pricing structure across premium, standard, and economy levels separates connected patches with embedded microprocessors from multi-day wear transdermal systems and basic counterirritant creams. Price differentiation rests on REACH compliance certification and silicone adhesive grade quality. Cost compression in economy tiers is intensifying because environmental compliance shutdowns in Mumbai and Hyderabad clusters create input volatility. Retail pharmacy chains exhibit highest price sensitivity for private-label diclofenac gels, while hospital formulary procurement absorbs premiums for EMA MDR-compliant combination patches.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty chemical producers dominating silicone and acrylic pressure-sensitive adhesive output for multi-day wear systems. Geographic supply concentration centers on India for lidocaine base and generic API manufacturing, Germany for adhesive polymer production, and Japan for transdermal patch finishing. Raw material dependencies draw from petrochemical feedstocks for acrylic adhesives, botanical extracts for herbal oil actives, and pharmaceutical-grade solvents for gel vehicles. Supply chain risk hinges on tariff exposure for temperature-sensitive adhesive imports into Brazil and the United States. Distribution runs through hospital GPO contracts for post-surgical lidocaine patches, retail pharmacy networks for impulse-purchase creams, and direct-to-consumer channels for subscription-based connected patch services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Topical Analgesic Market functions as a stable compounder anchored by irreversible demographic shifts toward Medicare-eligible chronic pain populations in aging societies.
For Market Incumbents: Deepen backward integration into adhesive polymer supply to insulate margin structures from German and Japanese specialty chemical pricing volatility. Prioritize pharmacovigilance talent acquisition in Boston and Minneapolis clusters to sustain connected patch platform development ahead of FDA real-world evidence requirements. Channel control through front-of-store retail pharmacy presence remains defensible against private-label erosion. For New Entrants and Emerging Players: Specialty veterinary distributors represent the most accessible channel partner type for species-specific lidocaine patch formulations in equine and companion animal applications. Brazilian private insurance markets offer penetrable white space following ANVISA's ICH alignment, with São Paulo distribution networks enabling rapid pharmacy shelf capture. Direct-to-consumer subscription models for software-defined dosing platforms bypass incumbent retail pharmacy gatekeepers. For Investors and Strategic Acquirers: Consumer health conglomerates with North American pharmacy infrastructure are the most active acquirer in this space, seeking connected device capabilities to extend shelf presence into data services. Mid-cap transdermal specialists with captive adhesive supply in Japan or Germany present acquisition target archetypes with durable moats. Monitor FDA OTC monograph reform implementation timelines as the critical inflection signal for legacy product portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Patch Platform Development | Software-defined dosing enables recurring subscription revenue beyond physical product sales. |
| Backward Integration into Adhesive Supply | Hisamitsu Pharmaceutical's Kansai region polymer production insulates margin from input volatility. |
| EMA MDR Compliance Pathway | Notified body clinical performance data requirements reshape European competitive barriers. |
| Veterinary Formulation Extension | Equine and companion animal lidocaine applications remain underpenetrated white space. |
| Real-World Evidence Generation Infrastructure | Sensor-derived efficacy signals from IoT-enabled patches satisfy payer adherence documentation demands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at FDA and EMA, formulary directors at United States hospital systems, procurement managers at German sports rehabilitation centers, and adhesive polymer R&D directors in the Rhine-Ruhr corridor with secondary validation from FDA OTC monograph dockets, EMA MDR classification guidance, ClinicalTrials.gov transdermal study registrations, and CMS Medicare reimbursement databases. Bottom-up patch and cream volume builds triangulated against top-down demographic pain prevalence models.
Segment-weighting approaches distributed value across formulation format, clinical indication, and procurement channel dimensions, with additional weighting for connected device adoption curves and regional regulatory cluster compliance burdens. CAGRs were derived from fitted growth curves across the projection horizon, incorporating diabetic peripheral neuropathy screening expansion rates, sports medicine facility investment cycles, and adhesive polymer capacity utilization trends as industry-specific forecast inputs.
Revisions become necessary when FDA OTC monograph reform implementation accelerates, EMA MDR notified body backlogs extend, or environmental compliance shutdowns in Indian chemical hubs deepen beyond historical patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Analgesics Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Global Hepatitis B Vaccines Market