
 Radiofrequency Ablation Devices for Pain Management Market | 2026-2036
Radiofrequency Ablation Devices for Pain Management Market Size, Share, and Industry Trends Forecast 2026-2036
Radiofrequency Ablation Devices for Pain Management Market Analytics
North American medical device manufacturing is restructuring its capacity allocation toward minimally invasive pain platforms. Medtronic leverages its integrated generator and electrode ecosystem to sustain high switching costs among interventional pain physicians. Boston Scientific Corporation anchors its position through specialized pulsed radiofrequency technology for neuropathic indications. Abbott Laboratories differentiates via navigable catheter systems that compete on procedural precision in outpatient settings.
Radiofrequency ablation devices for pain management generate thermal lesions in nervous tissue through high-frequency alternating current, typically operating at 300 to 500 kHz with tip temperatures reaching 60 to 90 degrees Celsius to achieve neurolysis. These systems serve the primary commercial purpose of providing durable analgesia for patients with chronic spinal, joint, and neuropathic pain who have failed conservative management. Generator systems command the dominant margin pool due to capital intensity and recurring electrode revenue attachment, while single-use devices represent the fastest-expanding consumable category driven by infection control protocols. Pulsed radiofrequency technology is gaining structural share in neuropathic pain applications where conventional thermal ablation carries higher neural injury risk.
The FDA regulates these devices through the 510(k) premarket notification pathway, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa and IIb pain ablation systems. ISO 13485 quality management standards govern manufacturing processes across both jurisdictions, directly influencing supplier qualification and market access timelines. Stakeholders must monitor evolving reimbursement codes for outpatient RFA procedures and prepare for potential FDA guidance updates on temperature-controlled ablation safety profiles.
Market Dynamics
The transition toward outpatient chronic pain management is compressing capital equipment replacement cycles and forcing generator manufacturers to prioritize electrode ecosystem lock-in over hardware margins.
Growth Catalysts
- Opioid-sparing reimbursement policies:CMS and private payers in the United States now favor interventional pain procedures over pharmaceutical management, directing patient volume toward ambulatory surgery centers equipped with radiofrequency ablation systems.
- Pulsed radiofrequency technology:This modality expands treatable indications to neuropathic pain syndromes where thermal ablation risks neuritis, opening addressable patient populations previously excluded from neurolytic intervention.
- India:CDSCO streamlining of Class II medical device registration under the 2017 Medical Device Rules accelerates market entry timelines for international pain device manufacturers targeting tier-1 hospital networks.
Market Restraints
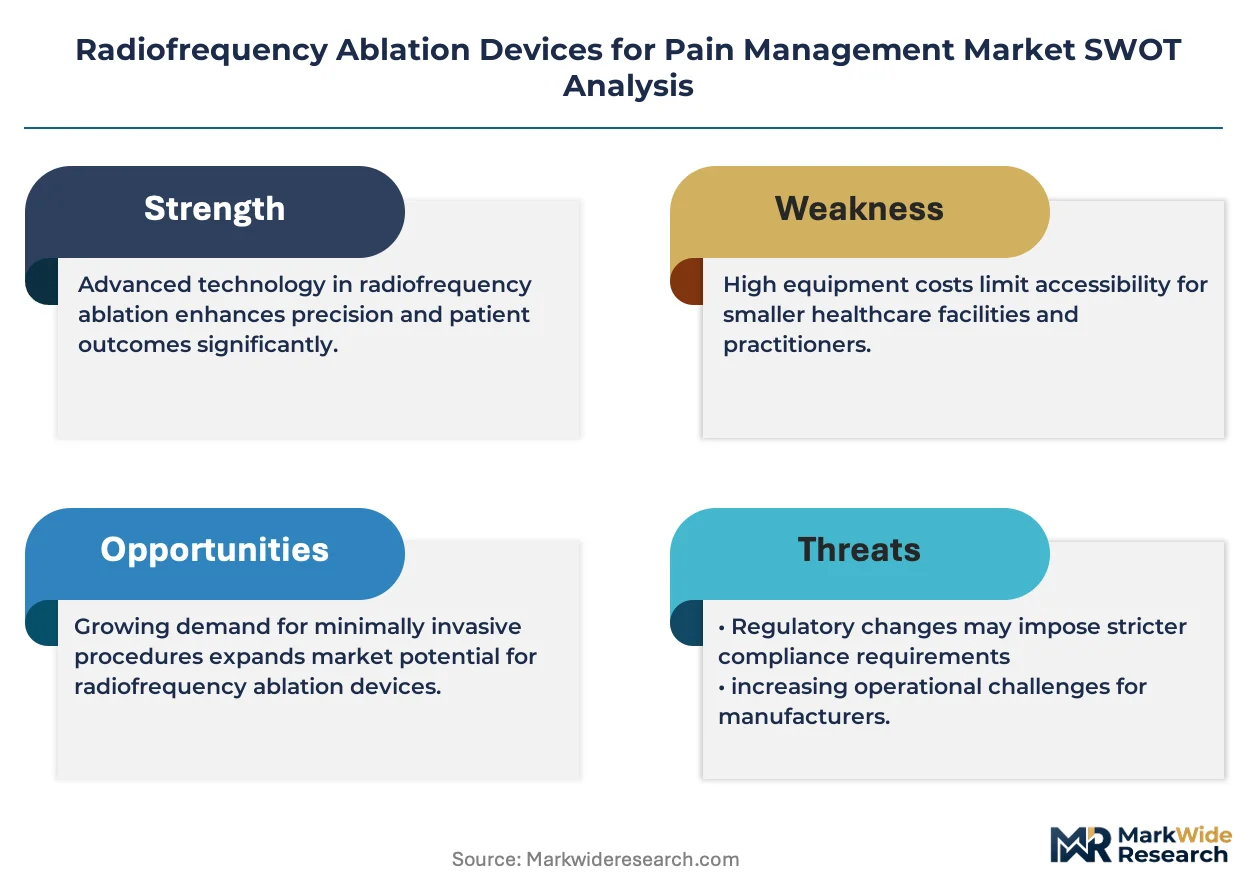
- Generator capital intensity:High upfront equipment costs and extended depreciation schedules constrain ambulatory surgery center purchasing frequency, particularly in markets with limited procedure reimbursement certainty.
- Electrode supply concentration:Single-use consumable manufacturing clusters in specific Asian economies create vulnerability to logistics disruptions and input material allocation constraints.
- Thermal lesion precision limitations:Conventional radiofrequency cannot reliably target small-caliber nerves near critical structures, restricting applicability in cervical spine and craniofacial applications.
Strategic Opportunities
- Brazil:ANVISA's expanding technical competence in pain device evaluation, combined with underpenetrated interventional pain specialist density, offers first-mover positioning for navigable catheter platforms.
- Artificial intelligence-integrated procedural planning:Convergence of imaging analytics with radiofrequency needle guidance enables real-time trajectory optimization, reducing fluoroscopy exposure and technical failure rates.
- Direct-to-ambulatory surgery center distribution:Bypassing traditional hospital supply chain intermediaries allows manufacturers to capture margin previously allocated to group purchasing organization administrative fees.
Industry Challenges
- Interventional pain fellowship training capacity:The pipeline of physicians competent in fluoroscopy-guided radiofrequency cannulation lags procedural demand growth, particularly in ex-urban geographies.
- ISO 13485 certification timeline compression:Accelerated EU MDR transition deadlines strain quality management system documentation resources, delaying product line extensions for smaller device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiofrequency Ablation Devices for Pain Management Market |
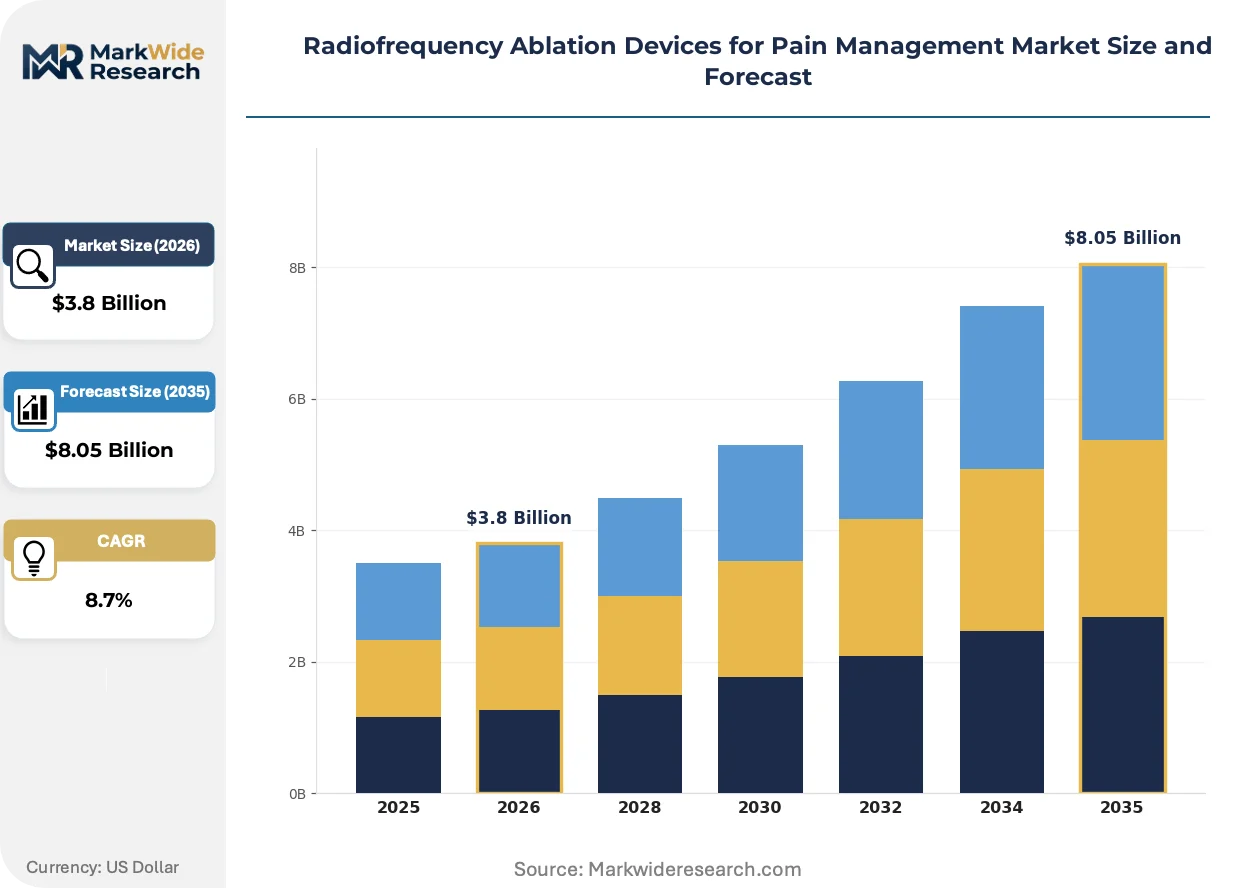
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Devices, Reusable Devices, Electrode Kits, Generator Systems Application: Chronic Pain, Acute Pain, Cancer Pain, Neuropathic Pain End User: Hospitals, Outpatient Clinics, Ambulatory Surgery Centers, Pain Management Clinics Technology: Conventional RFA, Pulsed RFA, Connective Tissue RFA, Cryoablation |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, Johnson & Johnson, Stryker Corporation, Avanos Medical, Smith & Nephew, AtriCure, AngioDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiofrequency Ablation Devices for Pain Management Market Evolving Landscape
Temperature-controlled ablation with closed-loop feedback is displacing fixed-parameter generators, while reimbursement coding evolution and procurement centralization reshape how buying decisions aggregate across health systems.
Cooled radiofrequency technology is overtaking conventional thermal probes in large-joint denervation procedures. Orthopedic ambulatory surgery centers in the United States are adopting these systems at twice the pace of standard radiofrequency platforms. This modality enables larger lesion volumes without exceeding safe tissue temperature thresholds, compressing the addressable market for competing chemical neurolysis approaches.
The EU Medical Device Regulation's clinical evidence requirements for Class IIb pain ablation systems are extending technical documentation preparation timelines. Manufacturers must now compile post-market surveillance data and PMCF study protocols before CE marking authorization. Pain device portfolios with legacy MDD certifications face compressed transition windows, forcing prioritization of highest-revenue generator platforms for MDR recertification.
Health system procurement consolidation is aggregating radiofrequency device purchasing across integrated delivery networks. Interventional pain service lines within these networks now negotiate enterprise-wide electrode supply agreements, displacing individual physician preference purchasing. This concentration is most visible in the United States, where hospital-owned ambulatory surgery centers represent the fastest-expanding channel for capital equipment placement.
Radiofrequency Ablation Devices for Pain Management Market Segmentation
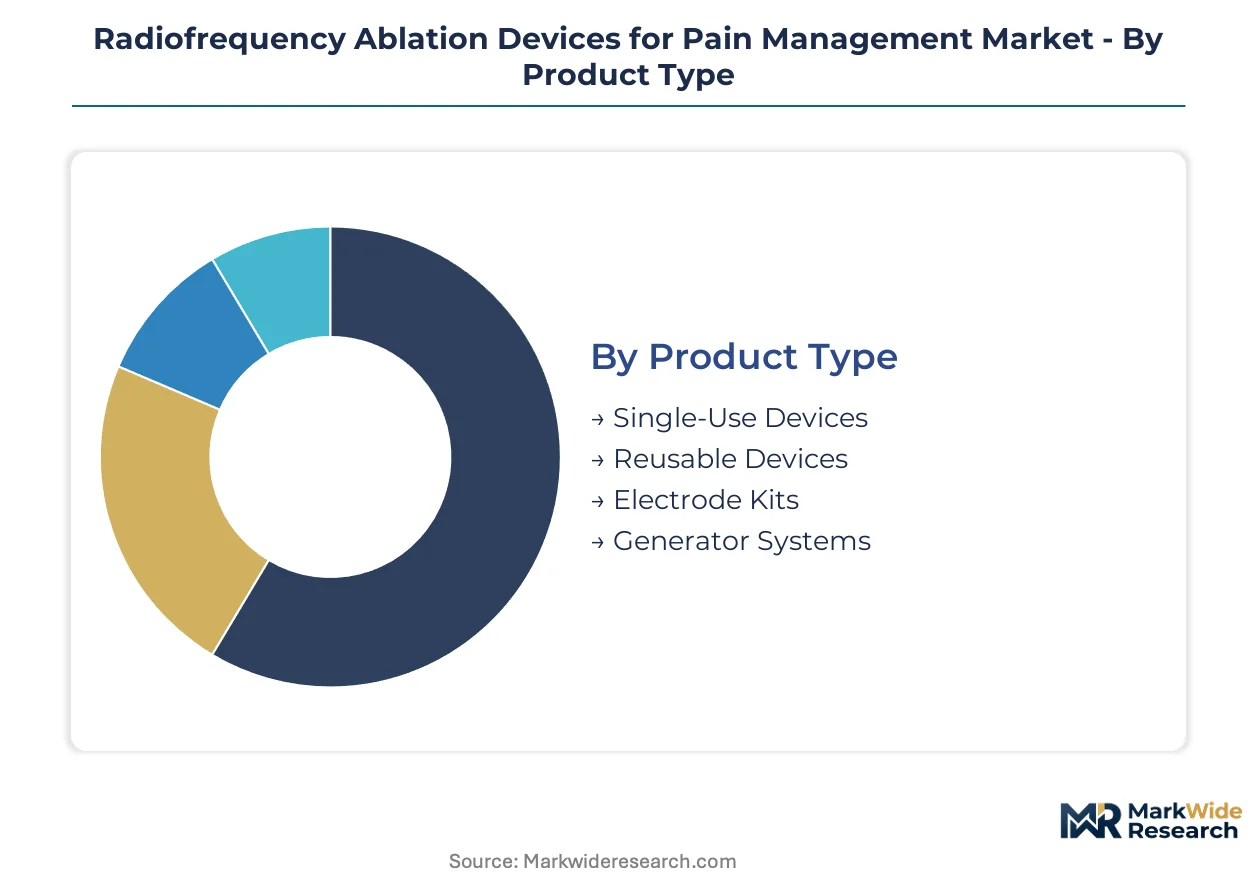
Radiofrequency ablation device purchasing decisions fragment across capital intensity tiers, procedure settings, and regulatory pathways. Manufacturers must align certification strategies with each segment's specific FDA 510(k) or EU MDR classification requirements.
Product Type:
Generator systems and single-use consumables carry distinct regulatory burdens under FDA 510(k) and EU MDR Class IIb frameworks, with reusable devices facing additional sterilization validation requirements.
- Generator Systems:Capital equipment delivering high-frequency alternating current at 300-500 kHz with integrated temperature monitoring. Demand concentrates in United States ambulatory surgery centers where opioid-sparing reimbursement policies accelerate equipment replacement cycles. These systems command extended depreciation schedules that constrain purchasing frequency in markets with reimbursement uncertainty.
- Single-Use Devices:Disposable electrodes and cannulas designed for per-procedure utilization to satisfy infection control protocols. United States hospital networks are expanding procurement of these consumables as integrated delivery networks negotiate enterprise-wide supply agreements. FDA 510(k) clearance timelines for electrode iterations remain shorter than generator platform certifications.
- Reusable Devices:Sterilizable probe components requiring validated reprocessing documentation under ISO 17664 standards.
- Electrode Kits:Procedure-specific configurations bundling multiple cannula geometries with grounding pads.
Generator systems sit at the top of the volume ranking, with single-use devices climbing the fastest.
Application:
Clinical indications span nociceptive and neuropathic mechanisms, with reimbursement coding specificity determining addressable patient populations across Medicare and commercial payer networks.
- Chronic Pain:Persistent spinal and joint pain syndromes failing conservative management. United States interventional pain specialists perform these procedures predominantly in outpatient settings where CMS facility fee schedules favor ambulatory venues. Thermal lesion durability drives repeat procedure economics.
- Neuropathic Pain:Peripheral nerve dysfunction including radiculopathy and complex regional pain syndrome. Pulsed radiofrequency technology is expanding treatable populations in United States academic medical centers where neuritis risk limits conventional thermal ablation. Neuromodulation coding overlaps create reimbursement complexity.
- Acute Pain:Postoperative and trauma-related pain episodes requiring temporary neural blockade.
- Cancer Pain:Tumor-related nociception and metastatic bone pain requiring palliative intervention.
Chronic pain captures the largest procedure volume, while neuropathic pain applications are gaining share fastest.
End User:
Site-of-service economics and capital equipment requirements create distinct purchasing behaviors across institutional settings.
- Ambulatory Surgery Centers:Freestanding surgical facilities specializing in same-day interventional procedures. United States orthopedic and pain-focused ASCs are adopting cooled radiofrequency systems at twice the pace of hospital-based sites. CMS outpatient prospective payment system reimbursement directly shapes equipment acquisition timelines.
- Pain Management Clinics:Physician-owned or hospital-affiliated practices dedicated to interventional techniques. These United States-based clinics prioritize electrode ecosystem compatibility over generator hardware margins. Limited capital budgets favor leasing arrangements and refurbished equipment markets.
- Hospitals:Acute care institutions with inpatient and outpatient procedural capacity.
- Outpatient Clinics:Non-surgical settings providing diagnostic and therapeutic pain services.
Ambulatory surgery centers dominate capital placements, with pain management clinics expanding consumable demand most rapidly.
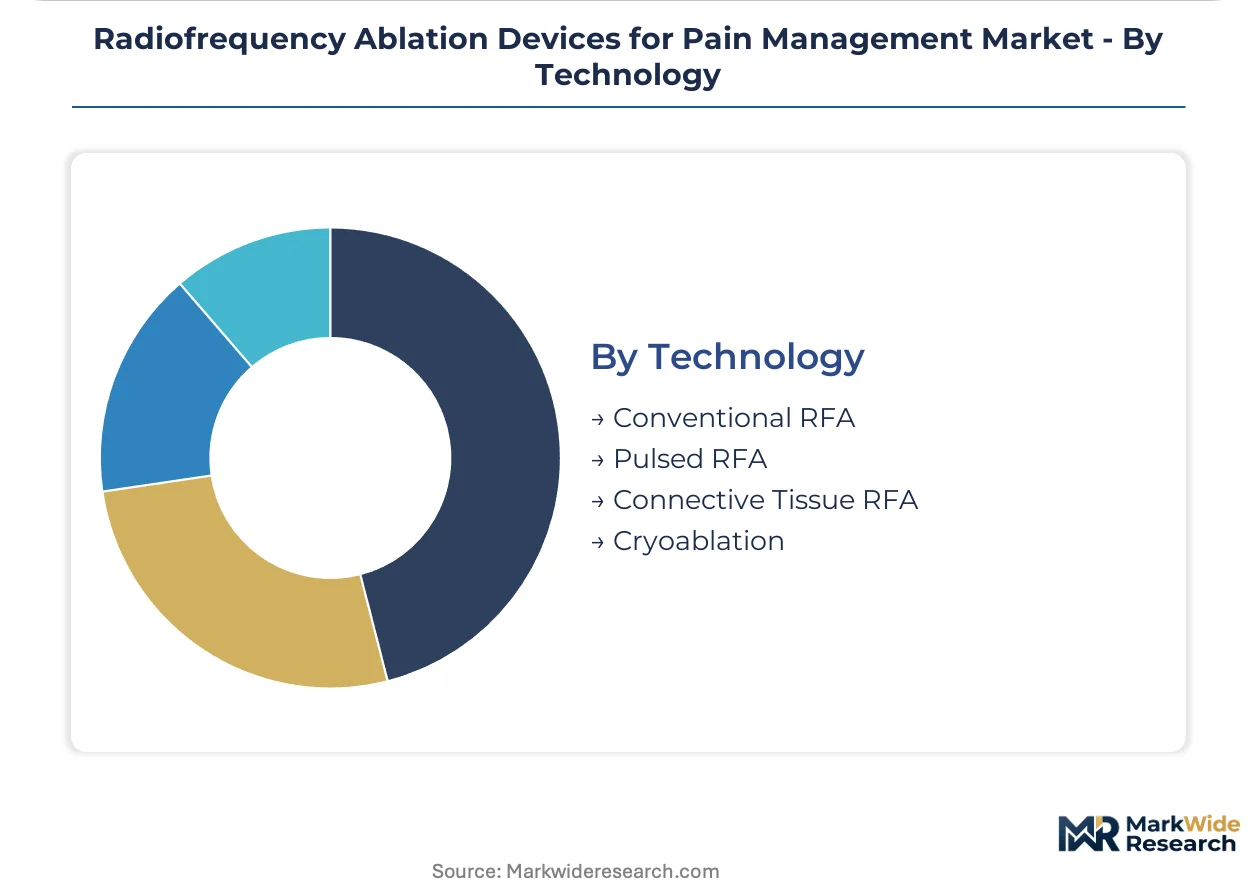
Technology:
Thermal and non-thermal modalities compete on lesion precision, nerve selectivity, and procedural safety profiles.
- Pulsed RFA:Intermittent high-frequency current delivery producing non-thermal neuromodulation. United States academic pain centers are adopting this modality for cervical spine applications where thermal neuritis risk restricts conventional techniques. Temperature-controlled generators with pulsed capability command premium pricing.
- Conventional RFA:Continuous thermal energy delivery creating neurolytic lesions at 60-90 degrees Celsius. United States community hospital systems retain this technology for lumbar medial branch denervation where established CPT coding ensures reimbursement predictability.
- Connective Tissue RFA:Targeted application to ligamentous and tendinous structures.
- Cryoablation:Freezing-based neural destruction using compressed gas systems.
Conventional RFA maintains the largest installed base, with pulsed RFA showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for radiofrequency ablation devices migrates toward jurisdictions with streamlined Class II medical device pathways. The United States retains procedural demand leadership while Asian economies capture electrode consumable production. European regulatory tightening under MDR is extending technical documentation timelines.
United States
CMS facility fee schedules for outpatient RFA procedures direct capital equipment purchases toward ambulatory surgery centers. FDA 510(k) clearance pathways maintain shorter premarket timelines than EU equivalents. Minneapolis and Boston clusters concentrate generator system engineering and electrode kit manufacturing.
Germany
Interventional pain specialist density in Bavaria and North Rhine-Westphalia sustains premium generator demand. EU MDR Class IIb clinical evidence requirements are compressing legacy device recertification windows. Baden-Württemberg medical technology clusters are pivoting toward temperature-controlled ablation platforms.
China
Domestic hospital procurement of pain management devices is accelerating under centralized volume-based purchasing. NMPA streamlined registration for Class II RF devices reduces entry barriers for international manufacturers. Shanghai and Shenzhen manufacturing zones dominate single-use electrode export capacity.
India
Tier-1 hospital networks in Delhi and Mumbai are expanding interventional pain service lines. CDSCO 2017 Medical Device Rules classification of RF ablation systems as Class II devices shortens import registration timelines. Hyderabad medical device manufacturing clusters are developing local electrode kit assembly.
Brazil
Underpenetrated interventional pain specialist density in São Paulo and Rio de Janeiro creates equipment placement opportunities. ANVISA technical competence in pain device evaluation is expanding beyond basic regulatory review. Southeastern hospital networks are adopting cooled radiofrequency systems for large-joint denervation.
Radiofrequency Ablation Devices for Pain Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue navigable catheter and AI-integrated procedural planning segments. The market structures around three tiers: integrated medtech conglomerates with generator-electrode ecosystems, specialized pain device manufacturers, and regional electrode suppliers. Dominant competitive moves include M&A for technology licensing and direct-to-ambulatory surgery center distribution bypassing group purchasing organizations.
Among diversified medtech conglomerates, Medtronic, Boston Scientific Corporation, and Abbott Laboratories exemplify distinct archetype positioning. Medtronic represents the integrated ecosystem model with generator and electrode bundling. Boston Scientific Corporation occupies the specialized technology tier through pulsed radiofrequency differentiation. Abbott Laboratories anchors the navigable catheter segment competing on procedural precision.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Johnson & Johnson |
| Stryker Corporation |
| Avanos Medical |
| Smith & Nephew |
| AtriCure |
| AngioDynamics |
| Others |
Value Network & Pricing Analysis
Generator-electrode ecosystem bifurcation between integrated premium platforms and commodity electrode suppliers manifests in divergent margin structures and procurement concentration patterns across United States ambulatory surgery centers. This tier divergence shapes both capital equipment depreciation schedules and consumable contract terms, with FDA 510(k) certification tiers serving as the primary gating mechanism for supplier qualification.
Pricing Analysis
Distributor margin compression in the hospital supply chain is reshaping contract structures for radiofrequency ablation devices. Three-tier pricing structure across premium temperature-controlled generators, standard thermal platforms, and economy electrode refills reflects ISO 13485 certification grade and after-sales service bundling. Cost compression in the electrode tier is intensifying because group purchasing organization administrative fees consume an expanding share of landed costs. Ambulatory surgery centers exhibit the highest price sensitivity due to fixed CMS reimbursement rates, while academic medical centers prioritize pulsed radiofrequency capability over unit economics.
Supply Chain Analysis
ISO 13485 certification timelines and EU MDR technical documentation requirements are extending supplier qualification periods beyond traditional procurement cycles. Electrode consumable manufacturing concentrates in China, South Korea, and Malaysia, while generator system assembly rests on precision electronics sourced from Germany and the United States. Single-source vulnerability in nitinol cannula wire supply creates exposure to aerospace alloy allocation constraints. Distribution runs through integrated delivery network procurement offices rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in radiofrequency ablation devices hinges on electrode ecosystem lock-in and the shift toward temperature-controlled platforms commanding premium positioning in outpatient settings.
For Market Incumbents: Anticipate reimbursement coding fragmentation as pulsed radiofrequency and cooled radiofrequency modalities compete for distinct CPT classifications. Deepen backward integration into nitinol cannula manufacturing to offset electrode supply concentration risk. Prioritize MDR recertification of highest-revenue generator platforms before legacy MDD certification expiration windows close. For New Entrants and Emerging Players: Direct-to-ambulatory surgery center e-procurement platforms offer the most penetrable route for bypassing established group purchasing organization relationships. Target Brazil's underpenetrated interventional pain specialist networks where ANVISA regulatory competence expansion lags equipment demand growth. Lead with artificial intelligence-integrated procedural planning software as a differentiated entry wedge. For Investors and Strategic Acquirers: Consolidation pressure builds where electrode kit manufacturers lack generator platform bundling capability and face ISO 13485 certification cost barriers. The long-term viability window favors vertically integrated players with captive supply of temperature-controlled generator technology. Watch for FDA guidance updates on temperature-controlled ablation safety profiles as an inflection signal for platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Recertification Acceleration | EU MDR Class IIb clinical evidence requirements compress legacy device transition timelines for manufacturers. |
| Direct-to-ASC Distribution | Bypassing group purchasing organizations captures margin previously allocated to administrative fee layers. |
| Pulsed RFA Platform Launch | Neuropathic pain indications expand addressable populations beyond conventional thermal ablation limits. |
| AI Procedural Planning Integration | Real-time trajectory optimization reduces fluoroscopy exposure and technical failure rates in outpatient settings. |
| Electrode Ecosystem Lock-In | Consumable recurring revenue attachment sustains generator hardware margins across extended depreciation cycles. |
Research Methodology
Bottom-up ambulatory surgery center procedure volume modeling reconciled against top-down generator and electrode shipment tracking forms the analytical core of this study. Primary interviews with interventional pain physicians, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers were validated against secondary sources including FDA 510(k) clearance databases, CMS Medicare claims data, hospital procurement records, and EU MDR notified body technical documentation filings.
Historical trendline analysis of capital equipment replacement cycles and consumable utilization rates informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, application indication, end-user setting, and technology modality. CAGRs were derived from regression analysis of procedure volume growth, reimbursement rate trajectories, and equipment penetration saturation curves. Forecast inputs incorporated pulsed radiofrequency adoption velocity and cooled radiofrequency orthopedic application expansion.
Regulatory pathway delays, reimbursement coding revisions, and electrode supply disruptions are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in FDA guidance on temperature-controlled ablation safety profiles or CMS outpatient prospective payment system rate adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Topical Pain Relief Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Postoperative Pain Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Global Morphine Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Tattoo Numbing Cream Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Global Pain Management Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Neuropathic Pain Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Cancer Pain Management Market