
 Chronic Lower Back Pain Treatment Market | 2026-2036
Chronic Lower Back Pain Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Lower Back Pain Treatment Market Intelligence
Consolidation among large healthcare providers and hospital networks is expanding their purchasing power for chronic lower back pain treatments. Medtronic leverages its extensive portfolio in spinal cord stimulation and surgical solutions to secure large contracts. Stryker Corporation competes on the basis of its innovative interventional spine products. Pfizer Inc. specializes in pharmacological treatments, focusing on non-opioid analgesics to meet evolving clinical guidelines.
Chronic lower back pain treatment encompasses a range of medical interventions designed to manage pain persisting for over 12 weeks. The primary goal is to alleviate discomfort, restore mobility, and improve patient quality of life through pharmacological or device-based approaches. Pharmacological options, particularly non-steroidal anti-inflammatory drugs, form a foundational treatment layer, while surgical interventions represent a high-cost, high-acuity segment. A significant shift is occurring towards outpatient clinics and rehabilitation centers for non-invasive procedures.
Regulatory frameworks established by the US FDA and the European Medicines Agency (EMA) dictate the approval pathways for new drugs and medical devices, emphasizing safety and efficacy data. In Japan, the PMDA imposes stringent requirements for market entry, influencing device design and clinical trial protocols. Stakeholders must now decide whether to invest in developing personalized treatment algorithms or focus on securing reimbursement for novel therapies.
Market Dynamics
The central structural force shaping the market is the migration of care from inpatient hospital settings to outpatient clinics and rehabilitation centers. This shift is driven by payer reimbursement policies favoring lower-cost environments and patient demand for less invasive, more convenient treatment options.
Growth Catalysts
- Advanced Non-Invasive Devices:Innovations in transcutaneous electrical nerve stimulation and wearable therapeutic technologies are enabling effective pain management in home-care settings, expanding the addressable patient population beyond clinical facilities.
- Aging Global Demographics:The rising prevalence of degenerative spine conditions in the geriatric populations of developed nations, particularly Germany and Japan, provides a sustained source of demand for both pharmacological and device-based treatments.
- Policy Shifts Away from Opioids:Clinical guidelines and reimbursement frameworks increasingly favor non-opioid analgesics and interventional procedures, creating a significant tailwind for alternative pain management solutions amid public health concerns over opioid dependency.
Market Restraints
- High Cost of Advanced Therapies:The significant upfront cost associated with surgical interventions like spinal cord stimulation and innovative biologic treatments creates access barriers for patients, especially in markets with limited insurance coverage.
- Stringent Regulatory Hurdles:The US FDA, European Medicines Agency, and Japan's PMDA enforce rigorous and lengthy approval processes for new drugs and high-risk medical devices, delaying market entry and increasing development costs.
- Threat from Alternative Medicine:The widespread availability and patient acceptance of alternative treatments, such as chiropractic care, acupuncture, and physical therapy, represent a persistent source of competition for conventional medical interventions.
Strategic Opportunities
- Personalized Treatment Algorithms:The convergence of artificial intelligence with patient data from wearable sensors offers an opportunity to develop adaptive, personalized therapy regimens that can optimize outcomes and demonstrate value to payers.
- Expansion into Emerging Economies:Markets in Latin America and Southeast Asia with improving healthcare infrastructure and a growing middle class represent underpenetrated regions for advanced chronic lower back pain treatments.
- Direct-to-Consumer Channels:Developing direct-to-consumer sales and support models for certain classes of FDA-cleared, non-invasive therapeutic devices can bypass traditional institutional procurement cycles and capture a wider patient base.
Industry Challenges
- Data Security and Privacy Compliance:Adherence to stringent patient data protection regulations, such as HIPAA in the US and GDPR in Europe, presents a significant operational challenge for connected devices and digital health platforms.
- Clinical Skill Shortages:A lack of specialists trained in the latest minimally invasive spinal procedures and data analytics limits the adoption rate of novel technologies and personalized medicine approaches in many healthcare systems.
- Lack of Outcome Standardization:The absence of universally accepted metrics for comparing the clinical effectiveness of diverse treatments complicates reimbursement negotiations and purchasing decisions for healthcare providers and payers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Lower Back Pain Treatment Market |
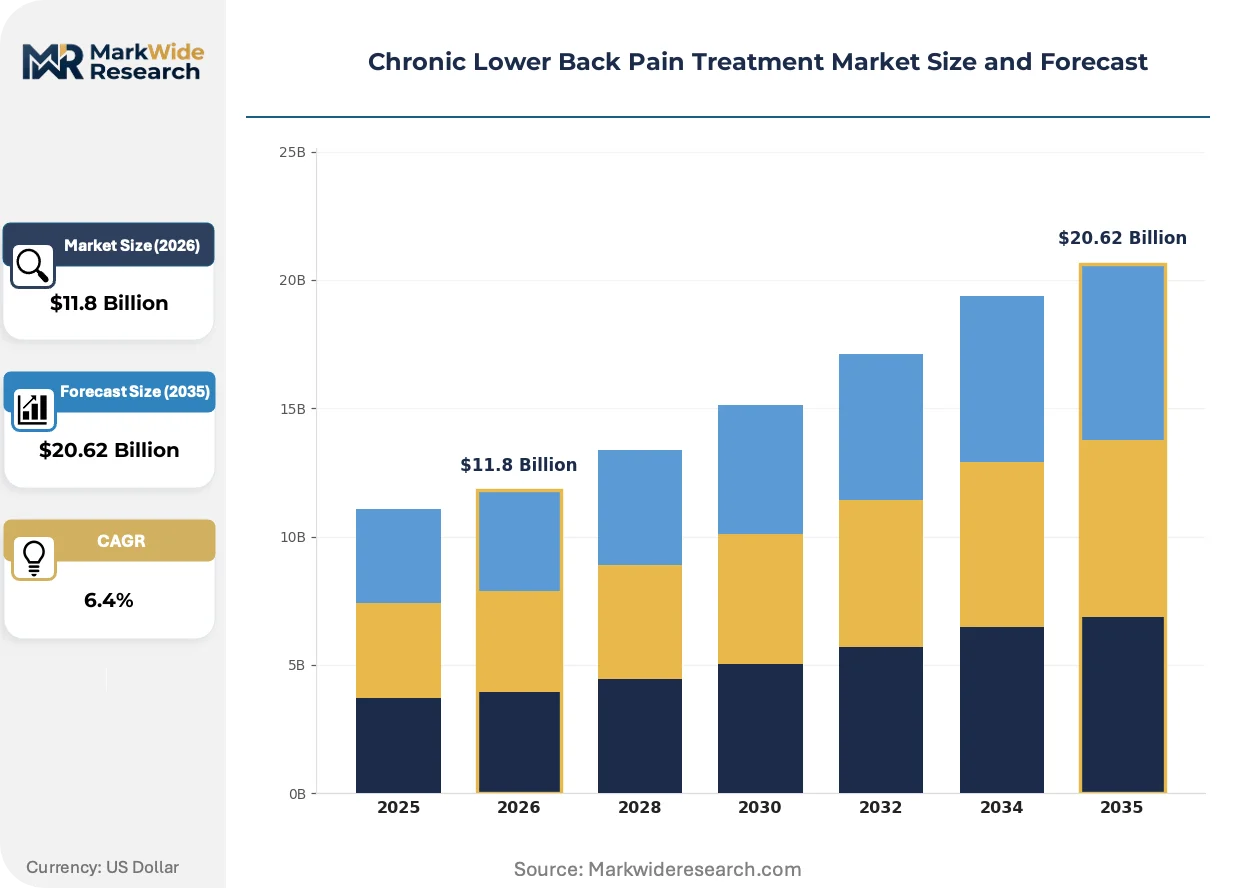
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Pharmacological, Physical Therapy, Surgical, Complementary Therapies Delivery Mode: Oral Medication, Injection, Transcutaneous Electrical Nerve Stimulation, Spinal Cord Stimulation, Epidural Patient Demographics: Adult, Geriatric, Pediatric, Athletes, Office Workers Healthcare Setting: Outpatient Clinics, Rehabilitation Centers, Specialty Hospitals, Primary Care Facilities |
| Companies Covered | Johnson & Johnson Services, Inc., Medtronic, Pfizer Inc., Merck & Co., Inc., Stryker Corporation, Boston Scientific Corporation, GSK plc, Sanofi, Endo Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Lower Back Pain Treatment Market Strategic Shifts & Innovations
Personalization is the defining trend, as data analytics and advanced diagnostics enable a move away from generalized treatment protocols. This evolution toward patient-specific care is reshaping product development, clinical practice, and the very definition of a successful outcome.
Digital health platforms integrated with wearable biosensors are emerging to continuously monitor patient biometrics, movement patterns, and treatment adherence. Rehabilitation centers and specialized pain clinics are the primary adopters, using the technology to track long-term outcomes outside of clinical visits. This technology is unifying disparate data from patient-reported surveys, device usage, and clinical records into a single, actionable patient profile for therapy adjustment.
The European Union's Medical Device Regulation (MDR) imposes significantly stricter post-market surveillance and clinical evidence requirements. This change increases the compliance burden and lifecycle cost for manufacturers of spinal implants, stimulators, and other Class II and III devices. Consequently, companies targeting the European market must now generate more robust real-world evidence and conduct long-term follow-up studies to maintain their CE marking.
A significant demand-side shift is occurring toward procedures performed in ambulatory surgery centers (ASCs) and other outpatient settings. This movement is disrupting the traditional hospital-centric model for many interventional pain treatments, driven by payer incentives and patient preference for faster recovery times. This trend is most visible in the United States, where reimbursement structures increasingly favor care delivery outside of high-cost inpatient facilities.
Chronic Lower Back Pain Treatment Market Segmentation
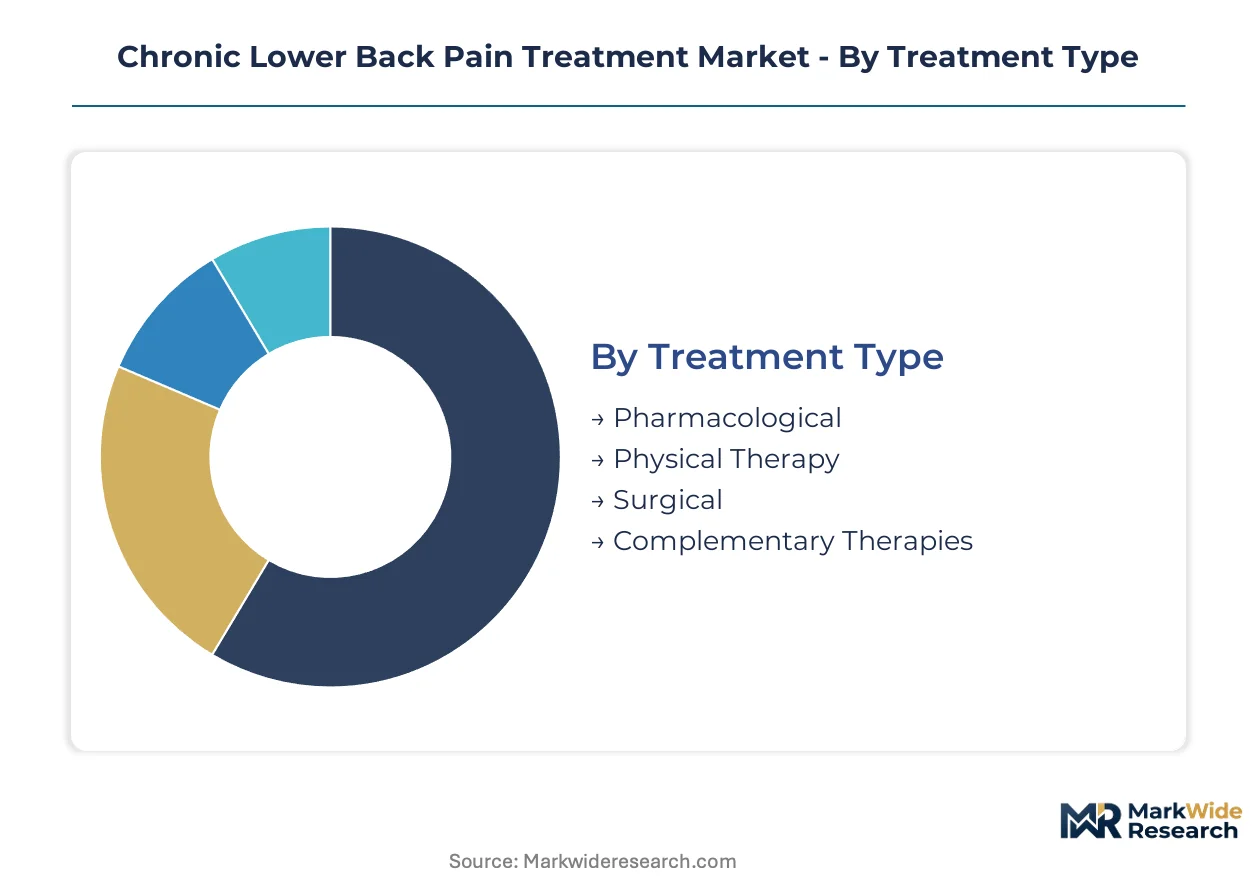
The chronic lower back pain treatment market is diverse, encompassing a wide array of therapeutic approaches and delivery mechanisms. Segmenting this market provides critical insights into the evolving landscape of patient care and technological innovation. This detailed breakdown helps identify areas of concentrated demand and emerging treatment preferences.
Treatment Type:
The integration depth of chronic lower back pain treatments varies, from standalone pharmaceutical regimens to embedded surgical solutions.
- Pharmacological:These treatments encompass a broad spectrum of medications, including NSAIDs, muscle relaxants, and neuropathic pain agents, primarily managed through general practitioners. Demand concentrates in countries like Germany due to established reimbursement frameworks for non-opioid analgesics.
- Physical Therapy:This involves structured exercise programs, manual therapy, and education designed to improve strength and flexibility, often delivered in rehabilitation centers. Patient demand in Japan shows strong preference for non-invasive options, driving significant adoption.
- Surgical:This segment includes invasive procedures like spinal fusion or decompression for severe, refractory cases.
- Complementary Therapies:These alternative approaches, such as acupuncture and chiropractic care, supplement conventional medical treatments.
Volume placements concentrate in Pharmacological treatments; the faster expansion belongs to Physical Therapy.
Delivery Mode:
Delivery modes for chronic lower back pain treatments span a wide cost spectrum, from accessible oral medications to advanced implantable devices.
- Spinal Cord Stimulation:This involves implanting a device that delivers electrical impulses to the spinal cord, modulating pain signals for patients with severe chronic pain. Demand is strong in developed markets where insurance coverage supports high-cost neurostimulation therapies.
- Transcutaneous Electrical Nerve Stimulation:TENS devices deliver low-voltage electrical currents through electrodes placed on the skin, offering non-invasive pain relief for home use. Wearable therapeutic technologies are expanding the addressable patient population.
- Oral Medication:This includes pills and capsules for systemic pain relief, forming a foundational layer of treatment.
- Injection:Localized pain relief is achieved through epidural steroid injections or nerve blocks.
- Epidural:This involves injecting medication into the epidural space to reduce inflammation around spinal nerves.
The highest volume of treatments occurs via Oral Medication; Transcutaneous Electrical Nerve Stimulation is experiencing the fastest expansion.
Patient Demographics:
Patient demographics significantly influence the choice and efficacy of chronic lower back pain treatments, reflecting diverse physiological needs and lifestyle factors.
- Geriatric:This demographic, characterized by age-related degenerative conditions, drives substantial demand for both pharmacological and device-based interventions. Developed nations like Germany and Japan exhibit high prevalence rates within this group.
- Adult:The largest patient segment, adults experience chronic lower back pain from various causes, including occupational stress and injuries, often seeking a balance between efficacy and minimal disruption to daily life. Non-opioid analgesics are gaining preference for this group.
- Pediatric:Chronic lower back pain in children and adolescents often requires specialized, conservative management approaches.
- Athletes:This group experiences pain due to high physical demands and sports-related injuries, often seeking rapid recovery and performance-focused therapies.
- Office Workers:Sedentary lifestyles and poor ergonomics contribute to chronic pain in this demographic, driving demand for ergonomic solutions and physical therapy.
The Adult demographic accounts for the largest patient volume; the Geriatric segment is gaining share most rapidly.
Healthcare Setting:
The healthcare setting for chronic lower back pain treatment reflects evolving care models, driven by payer policies and patient preferences for convenience.
- Outpatient Clinics:These facilities provide a range of non-invasive and minimally invasive procedures, including injections and physical therapy, driven by payer incentives for lower-cost care. The US market shows a strong shift towards these settings.
- Rehabilitation Centers:Focused on restoring function and mobility through structured programs, these centers are increasingly adopting digital health platforms and wearable sensors for long-term patient monitoring. This trend is visible in the European Union.
- Specialty Hospitals:These institutions handle complex surgical cases and advanced interventional pain management procedures.
- Primary Care Facilities:General practitioners serve as the initial point of contact, managing pharmacological treatments and referrals.
Primary Care Facilities manage the initial patient intake; Outpatient Clinics are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for chronic lower back pain treatments concentrates significantly in developed nations with aging populations. Germany and Japan exhibit particularly high prevalence rates for degenerative spine conditions. Reimbursement frameworks in these regions further support market expansion.
United States
Patient preference for outpatient settings drives significant demand for non-invasive procedures in the United States. The US FDA dictates rigorous approval pathways for new medical devices and drugs, emphasizing safety and efficacy. Major healthcare hubs like Boston are seeing increased investment in digital health platforms and personalized treatment algorithms.
Germany
An aging demographic in Germany fuels demand for both pharmacological and device-based treatments, particularly non-opioid analgesics. The European Medicines Agency (EMA) sets stringent regulatory standards for market entry and post-market surveillance. Munich is a center for medical technology innovation, attracting R&D for advanced pain management solutions and neurostimulation devices.
Japan
Strong patient preference for non-invasive options, especially physical therapy, characterizes the Japanese market. Japan's PMDA imposes stringent requirements for medical device design and clinical trial protocols, influencing market access. Tokyo's rehabilitation centers are early adopters of wearable therapeutic technologies for continuous patient monitoring.
United Kingdom
The National Health Service (NHS) in the United Kingdom influences procurement decisions for chronic pain treatments, favoring cost-effective solutions. The UK's Medicines and Healthcare products Regulatory Agency (MHRA) oversees drug and device approvals. London's specialized pain clinics focus on integrating personalized treatment algorithms and advanced diagnostics.
Canada
Canada's universal healthcare system impacts the accessibility and reimbursement of advanced therapies, often prioritizing evidence-based interventions. Health Canada regulates the safety and efficacy of medical devices and pharmaceutical products. Toronto's research institutions contribute to clinical trials for novel non-opioid analgesics and minimally invasive spinal procedures.
Chronic Lower Back Pain Treatment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized niches in digital health and personalized solutions. The market structure exhibits a mix of large, diversified healthcare conglomerates focusing on comprehensive offerings and agile medical device manufacturers innovating in specific interventional segments. Companies are actively engaging in strategic partnerships to expand their product portfolios and geographic reach, alongside targeted acquisitions to integrate novel technologies.
Specialists in device-based solutions and pharmacological treatments include Medtronic, which represents a diversified approach with its extensive portfolio in spinal cord stimulation and surgical solutions. Stryker Corporation exemplifies innovation in interventional spine products, positioning itself on advanced technology and minimally invasive techniques. Pfizer Inc., a major pharmaceutical entity, anchors the non-opioid analgesics segment, aligning its offerings with evolving clinical guidelines and public health concerns over opioid dependency.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Medtronic |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Stryker Corporation |
| Boston Scientific Corporation |
| GSK plc |
| Sanofi |
| Endo Pharmaceuticals Inc. |
| Others |
Cost & Logistics Intelligence
The European Union's Medical Device Regulation (MDR) significantly increases compliance costs, gating access for unqualified suppliers and driving premium pricing for certified advanced therapies. This regulatory stringency impacts both the availability of complex devices and the cost structures for manufacturers.
Pricing Analysis
Volume-based pharmacological treatments contrast sharply with the margin-intensive advanced device solutions. The dominant pricing model for innovative devices is value-based, often negotiated through long-term contracts with large healthcare providers. Price differentiation stems from rigorous regulatory approvals like US FDA clearance and proven clinical efficacy data. Pricing softness runs through the generic non-opioid analgesics segment, driven by intense competition. Patients with limited insurance coverage exhibit the highest price sensitivity for advanced surgical interventions.
Supply Chain Analysis
Reverse logistics for medical devices, particularly for implantable neurostimulators, involves stringent regulatory protocols for refurbishment or secure disposal. Geographic supply concentration for active pharmaceutical ingredients (APIs) often rests on India and China, while specialized medical devices are primarily manufactured in the United States and Germany. The supply chain relies on electronic components and specialized polymers as key inputs. A structural risk involves single-source vulnerability for highly specialized device components. Distribution runs through a fragmented network of pharmaceutical wholesalers and direct sales forces targeting outpatient clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chronic lower back pain treatment market is increasingly defined by its cost-of-compliance narrative, with the European Union's Medical Device Regulation (MDR) creating a significant barrier-to-entry for non-compliant solutions.
For Market Incumbents: Acquire specialized outpatient clinic networks to consolidate care delivery, countering the shift away from traditional inpatient settings. Invest heavily in artificial intelligence and data analytics capabilities to develop personalized treatment algorithms, addressing the threat from generalized therapeutic approaches. Leverage existing channel control and regulatory expertise to maintain market dominance for high-cost interventional devices.
For New Entrants and Emerging Players: Capture underpenetrated markets in Latin America and Southeast Asia by offering cost-effective, non-invasive therapeutic devices. Focus on developing digital health platforms integrated with wearable biosensors, targeting the home-care setting as a highly penetrable segment. A direct-to-consumer sales model for FDA-cleared devices can bypass traditional procurement cycles.
For Investors and Strategic Acquirers: Reimbursement expansion for personalized treatment algorithms is the leading indicator that value-based care models are maturing. The long-term viability favors companies innovating in non-opioid solutions and outpatient care delivery. Target acquisition profiles include firms specializing in AI-driven diagnostics or wearable therapeutic technologies. Investors should monitor payer coverage decisions for digital health platforms for early signals of market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Robust clinical evidence for non-opioid analgesics strengthens market position against traditional pain management. |
| Regulatory Approval Pathway | Navigating US FDA and EMA requirements ensures market access for innovative spinal cord stimulation devices. |
| Hospital System Partnership | Collaborating with large healthcare providers secures procurement contracts for advanced interventional spine products. |
| Software Companion Development | Integrating AI-powered diagnostics with wearable biosensors optimizes patient outcomes and therapy adherence. |
| Reimbursement Strategy | Securing favorable payer coverage for novel therapies is critical for market penetration in developed nations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, which were then validated through extensive primary interviews. Clinicians, hospital purchasing committees, regulatory affairs leads, and medical device engineers provided critical insights into market dynamics. Secondary sources included US FDA filings, EMA submissions, PMDA guidelines, and peer-reviewed academic literature. A robust bottom-up and top-down triangulation approach ensured data accuracy.
Treatment type, delivery mode, patient demographics, healthcare setting, and regional regulatory frameworks were modeled at a granular country level across the analysis window. The compounded annual growth rates were derived from historical trends and projected market dynamics, incorporating qualitative insights from primary research. Key industry-specific forecast inputs included aging demographics and policy shifts away from opioid dependence.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving regulatory landscapes and unforeseen technological advancements. Forecasts reflect assumptions regarding market evolution and technological adoption. Practitioners should monitor payer reimbursement policy changes and shifts in clinical guidelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Topical Pain Relief Cream Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Spine Pain Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Postoperative Pain Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Chronic Pain Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Chronic Pain Treatment Market
Pain Management
Ketorolac Market
Pain Management
Neuralgia Treatment Market
Pain Management
Global Visceral Pain Treatment Market