
 Global Morphine Market | 2026-2036
Global Morphine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Morphine Market Foresight
Controlled-release formulation technology is reshaping how morphine products achieve therapeutic consistency and reduce dosing frequency. Pfizer Inc. leverages its biopharmaceutical manufacturing infrastructure to sustain supply chain reliability for injectable morphine across regulated markets. Teva Pharmaceutical Industries Ltd. anchors its position through generic controlled-release tablet portfolios that compete on cost and bioequivalence standards.
Morphine, an opiate alkaloid derived from Papaver somniferum with the chemical formula C17H19NO3, functions as a potent mu-opioid receptor agonist for moderate-to-severe pain management in clinical and hospice settings. Injection formulations dominate acute care environments where rapid onset is clinically essential, while controlled-release tablets capture chronic pain and palliative care segments where steady plasma levels reduce breakthrough episodes. Oral solutions occupy pediatric and geriatric niches where swallowing difficulties limit solid-dose administration.
The FDA's REMS program for extended-release and long-acting opioids imposes prescriber certification and patient counseling mandates that constrain market access for non-compliant manufacturers. The EMA's pharmacovigilance requirements under the EU MDR and WHO's Access to Controlled Medicines Programme together shape international distribution frameworks for essential opioid analgesics. Stakeholders must monitor evolving DEA production quota allocations and WHO treaty compliance benchmarks to anticipate supply availability and competitive positioning shifts.
Market Dynamics
Controlled-release formulation technology is compressing dosing frequency requirements while WHO Essential Medicines List inclusion expands institutional procurement volumes across hospital systems.
Growth Catalysts
- Palliative care expansion:Hospital-based pain management networks in the United States, China, and Germany are institutionalizing morphine protocols for terminal care. The WHO's Access to Controlled Medicines Programme accelerates regulatory harmonization in low-access regions.
- Controlled-release tablet adoption:Steady plasma level maintenance reduces breakthrough pain episodes in chronic care settings. Bioequivalence standards for generic formulations lower cost barriers to long-term therapy.
- Injectable morphine demand:Acute care environments require rapid-onset delivery for post-surgical and trauma applications. Emergency department protocols standardize intravenous administration for severe pain stabilization.
Market Restraints
- DEA production quota volatility:Annual allocation adjustments for raw opium alkaloid create supply uncertainty for downstream manufacturers. Quota compression in any single year disrupts formulation planning.
- Diversion control infrastructure costs:Tamper-resistant packaging and track-and-trace serialization add per-unit expense. Compliance with the FDA's REMS program demands prescriber certification systems.
- Non-opioid substitution pressure:Multimodal analgesia protocols in perioperative care reduce morphine monotherapy dependence. Regional nerve block techniques and NSAID combinations displace opioid-first approaches in select procedures.
Strategic Opportunities
- Underpenetrated African markets:The WHO Access to Controlled Medicines Programme identifies morphine availability gaps in palliative care systems across Sub-Saharan Africa. National essential medicines list adoption creates procurement pathways.
- Pediatric oral solution expansion:Swallowing difficulties in geriatric and pediatric populations limit solid-dose administration. Liquid formulation development addresses this unmet need with age-appropriate delivery.
- EMA pharmacovigilance alignment:EU MDR compliance creates competitive moats for manufacturers with established European distribution. Convergence with WHO treaty benchmarks simplifies multi-jurisdictional registration.
Industry Challenges
- Specialized manufacturing workforce scarcity:Controlled-substance handling certification requirements limit qualified operator pools. GMP compliance for Schedule II compounds demands training investments that constrain capacity scaling.
- Legacy ERP integration with serialization:Track-and-trace mandates require system overhauls for established manufacturers. Integration timelines extend 18-24 months for facilities with outdated infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Morphine Market |
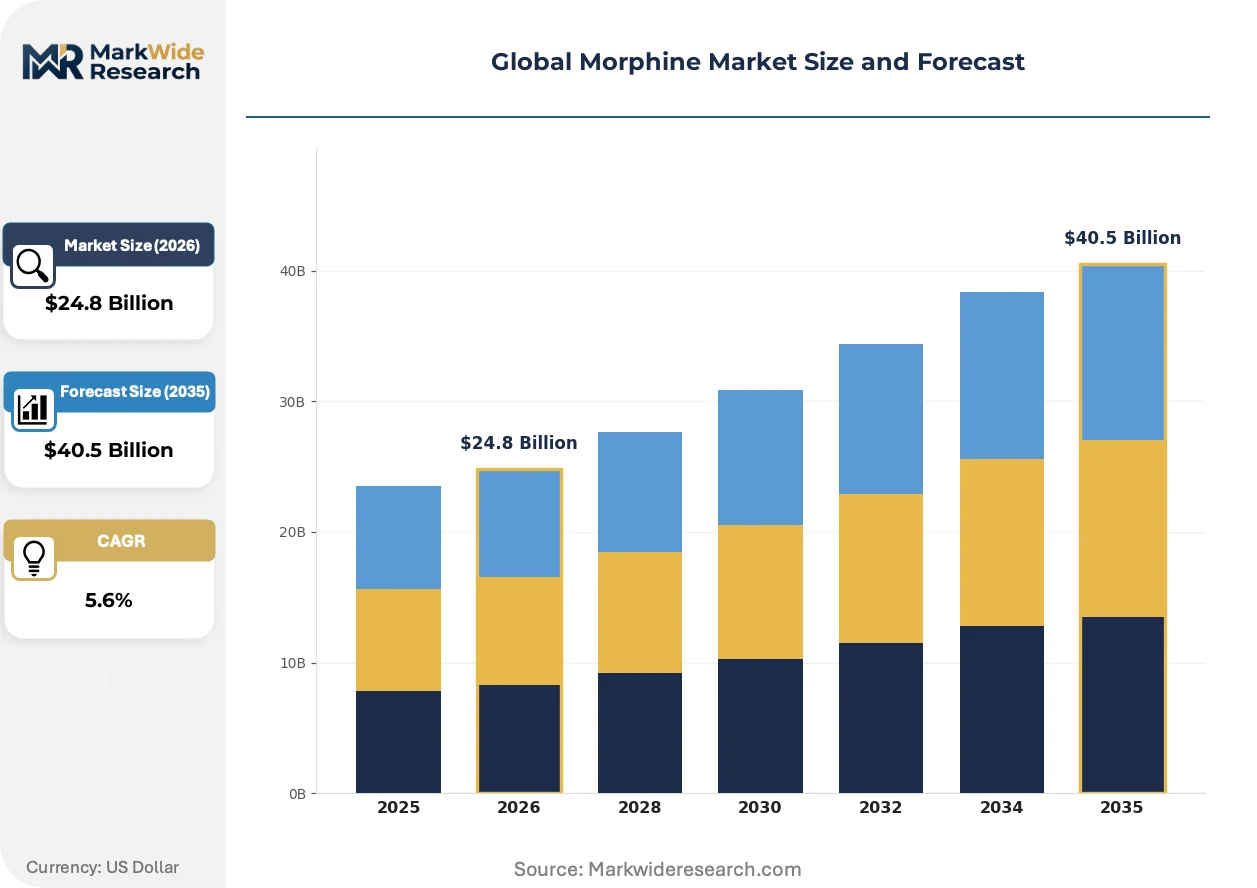
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.5 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Oral Solution, Controlled-Release Tablets, Suppositories, Immediate-Release Tablets Therapy Area: Oncology Pain, Postoperative Pain, Trauma Pain, Chronic Pain, Palliative Care End User: Hospitals, Specialty Clinics, Home Healthcare, Pain Management Centers, Hospice Facilities Delivery Mode: Intravenous, Oral, Subcutaneous, Epidural, Intramuscular |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., Mallinckrodt Pharmaceuticals, Sun Pharmaceutical Industries Ltd., Johnson & Johnson, Viatris Inc., AbbVie Inc., Hikma Pharmaceuticals plc, Endo International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Morphine Market Shifts & Advancements
Formulation science and regulatory technology are converging to reshape product differentiation and compliance architecture across opioid manufacturing.
Polymeric matrix systems for extended-release morphine are hybridizing conventional hydrophilic gel technologies with osmotic pump mechanisms. Chronic pain clinics in Germany and the United States are adopting these dual-mechanism tablets to flatten plasma concentration curves. The technology is compressing competitive differentiation around duration-of-action claims.
REACH compliance under the EU's chemical registration framework is reshaping excipient sourcing for European formulation facilities. Manufacturers must document full supply chain substance volumes above one-tonne thresholds. Controlled-release tablet producers with captive polymer synthesis capabilities are insulating margin structures from third-party supplier audit risks.
Hospital procurement consortia are consolidating purchasing power across integrated delivery networks in the United States. Group purchasing organizations now negotiate multi-year morphine supply agreements with inflation-linked pricing. This concentration is most visible in tertiary care systems where formulary standardization reduces supplier fragmentation.
Global Morphine Market Segmentation
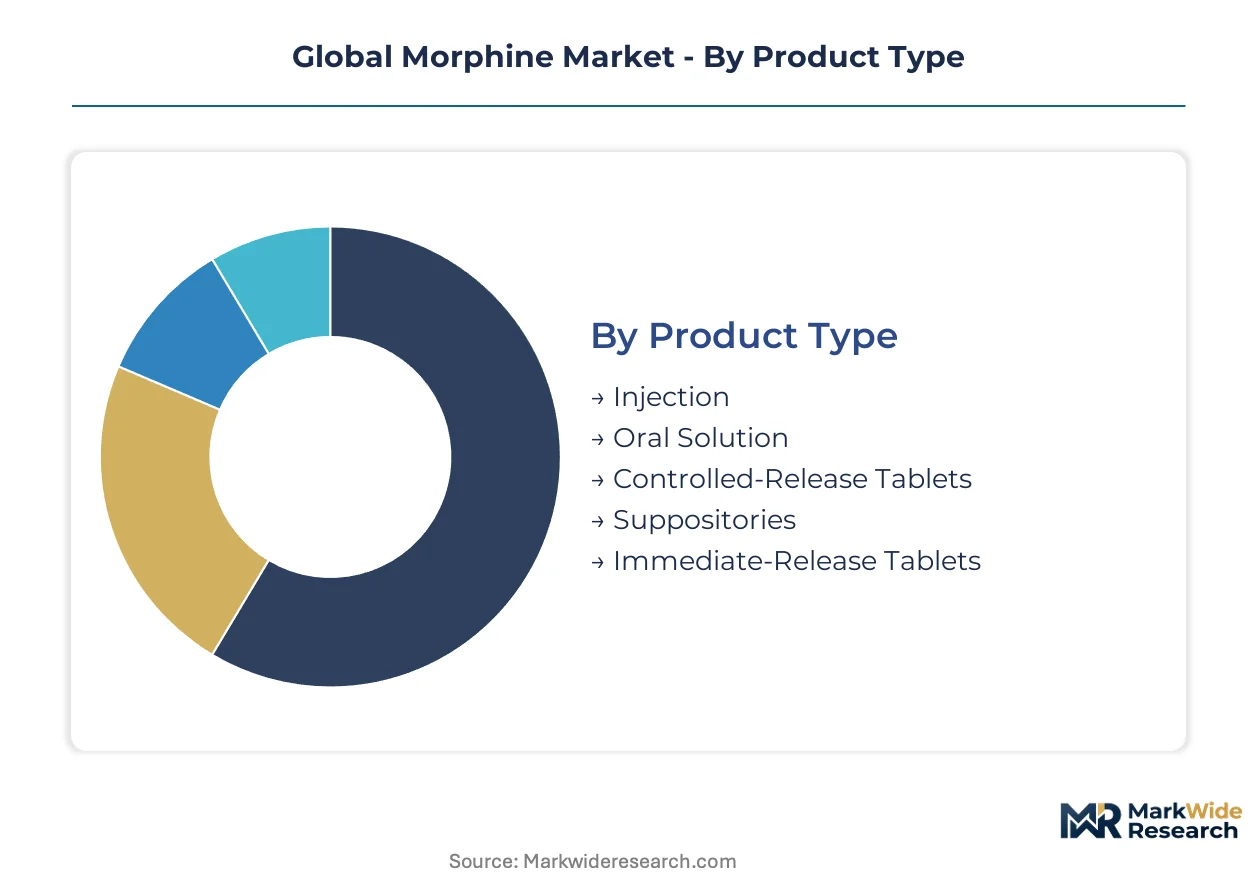
Morphine market segmentation reflects divergent clinical requirements across acute intervention and long-term maintenance settings. Formulation technology, therapy protocols, and care delivery sites each create distinct procurement patterns and margin structures for manufacturers.
Product Type:
Mature injectable formats coexist with emerging controlled-release innovations across hospital formularies.
- Injection:Sterile aqueous solutions of morphine sulfate or hydrochloride enable rapid plasma concentration for acute pain stabilization. Emergency departments in the United States, China, and Germany standardize intravenous protocols for post-surgical and trauma applications where onset speed determines clinical utility.
- Controlled-Release Tablets:Polymeric matrix and osmotic pump technologies sustain therapeutic plasma levels over 12-24 hour intervals. Palliative care programs in hospital systems favor these formulations for chronic cancer pain where breakthrough episode reduction improves quality-of-life metrics.
- Oral Solution:Concentrated liquid morphine formulations address swallowing difficulties in pediatric and geriatric populations.
- Suppositories:Rectal delivery formats serve patients with compromised gastrointestinal absorption or nil-per-os status.
- Immediate-Release Tablets:Rapid-disintegration solid doses bridge rescue dosing between extended-release intervals.
Injection handles the majority of throughput; controlled-release tablets are gaining share fastest on palliative care expansion.
Therapy Area:
Cost tier stratification separates high-acuity intervention from maintenance therapy segments.
- Palliative Care:Terminal illness protocols prioritize pain relief over addiction risk in end-of-life settings. WHO Essential Medicines List inclusion drives procurement standardization across national health systems in Germany and the United States.
- Oncology Pain:Tumor-related nociceptive and neuropathic pain demands escalating opioid titration. Cancer centers in China combine morphine with adjuvant analgesics in multimodal protocols.
- Postoperative Pain:Surgical recovery protocols balance opioid efficacy against ileus and respiratory depression risks.
- Trauma Pain:Emergency stabilization requires rapid-onset delivery for fracture and burn management.
- Chronic Pain:Non-malignant persistent pain conditions face heightened scrutiny under FDA REMS prescriber certification mandates.
Oncology pain absorbs the largest prescription volume; palliative care is expanding most quickly on demographic aging.
End User:
Customer type determines compliance infrastructure requirements and pricing power distribution.
- Hospitals:Integrated delivery networks consolidate purchasing through group purchasing organizations with inflation-linked multi-year agreements. Tertiary care systems in the United States standardize formularies across anesthesia, emergency medicine, and oncology departments.
- Hospice Facilities:Residential end-of-care settings prioritize oral solutions and controlled-release tablets for home-equivalent comfort.
- Specialty Clinics:Pain management and oncology-focused ambulatory centers maintain restricted opioid prescribing licenses.
- Pain Management Centers:Interventional pain practices combine morphine with regional anesthesia techniques.
- Home Healthcare:Visiting nurse services administer oral and subcutaneous formulations for post-acute transitions.
Hospitals command the dominant procurement position; hospice facilities are climbing the fastest on palliative care decentralization.
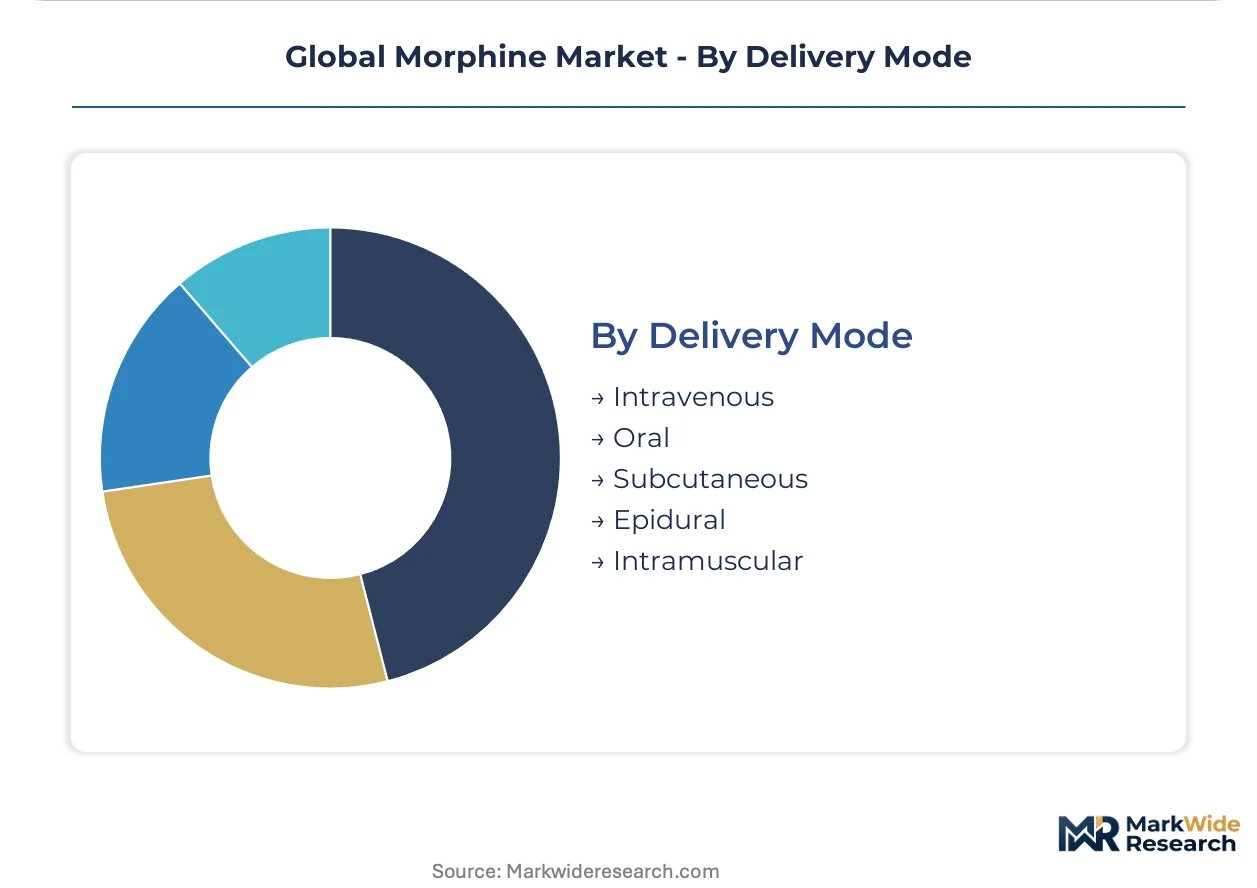
Delivery Mode:
Volume concentration tracks acute care infrastructure density across regulated markets.
- Intravenous:Direct vascular administration achieves peak plasma concentration within minutes for severe pain stabilization. Anesthesia departments in German university hospitals favor patient-controlled analgesia pumps for postoperative titration.
- Oral:Gastrointestinal absorption enables outpatient maintenance with controlled-release and immediate-release tablet options.
- Epidural:Intrathecal delivery targets localized analgesia with reduced systemic exposure for obstetric and lower-extremity procedures.
- Subcutaneous:Intermittent or continuous infusion suits patients lacking venous access.
- Intramuscular:Deep tissue injection persists in resource-constrained settings without intravenous capability.
Intravenous delivery manages the highest acute care throughput; epidural administration shows steepest expansion trajectory on obstetric and surgical anesthesia protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows for morphine concentrate heavily in regulated pharmaceutical corridors, with the United States, Germany, and China maintaining structural surpluses in finished-dose manufacturing while raw opium alkaloid sourcing traces through treaty-controlled supply chains.
United States
Hospital-based integrated delivery networks in the United States consume the largest institutional morphine volumes worldwide, driven by tertiary care expansion and hospice decentralization. The FDA's REMS program for extended-release opioids imposes prescriber certification mandates that constrain formulary access for non-compliant suppliers. Manufacturing clusters in New Jersey and North Carolina host sterile injectable facilities serving anesthesia and emergency medicine departments across the Midwest and Southeast.
Germany
German university hospitals anchor European demand for patient-controlled analgesia pumps and controlled-release tablet protocols, with palliative care networks standardizing morphine in terminal cancer management. The EMA's pharmacovigilance requirements under EU MDR shape excipient sourcing and batch-release documentation for formulation facilities. The Rhine-Ruhr and Bavarian pharmaceutical corridors concentrate polymeric matrix manufacturing for 24-hour extended-release products.
China
China's National Medical Products Administration (NMPA) regulates domestic morphine production through state-controlled alkaloid processing quotas and hospital procurement tender systems. Cancer center expansion in Beijing, Shanghai, and Guangzhou drives demand for multimodal oncology pain protocols combining morphine with adjuvant therapies. The Yangtze River Delta hosts active pharmaceutical ingredient synthesis facilities serving both domestic tablet formulation and regulated export markets.
India
Indian generic manufacturers supply controlled-release morphine tablets to WHO Access to Controlled Medicines Programme procurement channels across Sub-Saharan Africa and Southeast Asia. The Central Drugs Standard Control Organization (CDSCO) aligns export licensing with international narcotics control treaty requirements. Hyderabad and Ahmedabad clusters specialize in cost-competitive oral solution and immediate-release tablet production for pediatric and geriatric export segments.
United Kingdom
National Health Service palliative care pathways in the United Kingdom prioritize oral morphine solutions for home-based terminal care, reducing hospital admission duration. The Medicines and Healthcare products Regulatory Agency (MHRA) maintains post-Brexit regulatory convergence with EMA standards for batch testing and distribution documentation. The Southeast England pharmaceutical corridor, centered on Cambridge and Stevenage, hosts specialist formulation R&D for next-generation extended-release technologies.
Global Morphine Market Competitive Landscape
On the supply side, the industry is consolidated around a tiered structure where multinational pharmaceutical conglomerates with captive alkaloid sourcing capabilities coexist with regional generic specialists and contract manufacturing organizations. Three archetypes dominate: vertically integrated innovators controlling raw material through finished-dose supply chains, cost-optimized generic tablet manufacturers competing on bioequivalence certification, and sterile injectable specialists serving acute care procurement networks. Capacity expansion and strategic licensing partnerships constitute the primary competitive vectors, with manufacturers securing DEA production quota allocations and EMA manufacturing authorization certificates to defend market access.
Within the multinational integrated tier, Pfizer Inc. and Johnson & Johnson occupy positions anchored by biopharmaceutical manufacturing infrastructure spanning regulated markets. Teva Pharmaceutical Industries Ltd. exemplifies the generic-specialist archetype, with portfolio breadth in controlled-release tablet formats competing on cost and regulatory filing speed. Sun Pharmaceutical Industries Ltd. represents the emerging-market challenger model, leveraging Indian manufacturing cost structures to supply WHO procurement channels and price-sensitive institutional buyers across Africa and Southeast Asia.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Mallinckrodt Pharmaceuticals |
| Sun Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| Viatris Inc. |
| AbbVie Inc. |
| Hikma Pharmaceuticals plc |
| Endo International plc |
| Others |
Supply & Pricing Matrix
Raw opium alkaloid sourcing concentrates in treaty-controlled supply chains spanning India, Turkey, and Australia, anchoring margin capture at the cultivation-extraction tier while downstream formulation competes on bioequivalence certification and DEA quota access. Hospital procurement consortia and WHO Access to Controlled Medicines Programme tenders exert countervailing price pressure on finished-dose manufacturers.
Pricing Analysis
Hospital group purchasing organizations anchor contract-based long-term offtake pricing across injectable and controlled-release tablet portfolios. Price differentiation hinges on FDA REMS compliance certification and DEA production quota allocation security, with generic manufacturers competing on volume scale and established bioequivalence standards. Pricing pressure stems from multimodal analgesia protocols displacing opioid-first approaches in perioperative care. Hospice facilities and pediatric oral solution segments demonstrate highest price sensitivity; tertiary care anesthesia departments prioritize supply reliability over unit cost.
Supply Chain Analysis
International narcotics control treaty frameworks limit raw opium alkaloid flows through licensed cultivation and processing quotas. Manufacturing concentrates in the United States, Germany, and China for finished-dose formulation, while India supplies generic oral solutions to WHO procurement channels. Active pharmaceutical ingredient synthesis rests on Papaver somniferum gum opium and concentrated poppy straw dependencies. Single-source vulnerability runs through DEA annual quota allocation volatility for Schedule II controlled substances. Distribution runs through hospital procurement consortia, specialty pharmaceutical distributors with controlled-substance licensing, and direct government tender systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
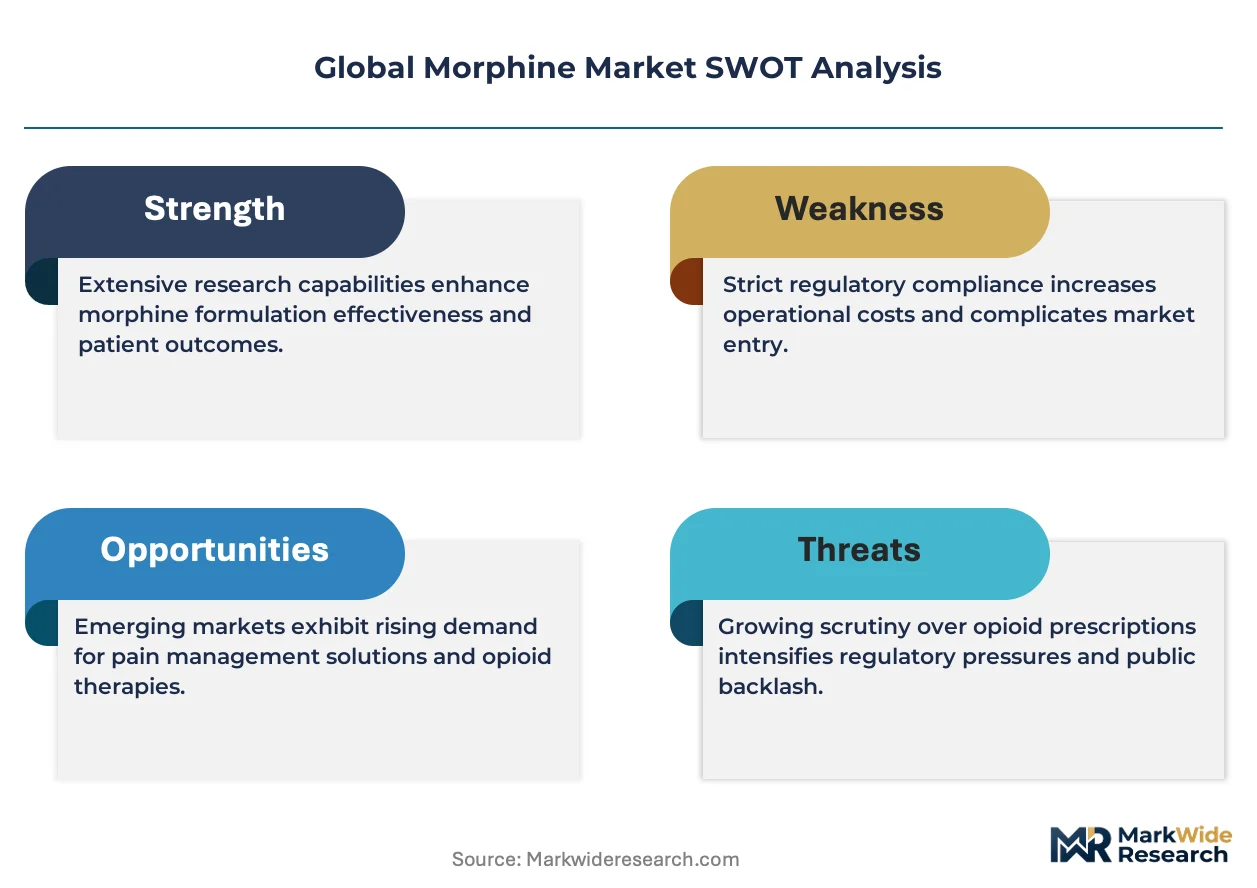
Non-opioid analgesic substitution and regional nerve block diffusion threaten morphine volume expansion, forcing incumbents to defend position through formulation innovation and regulatory compliance moats rather than commodity volume competition.
For Market Incumbents: Harden DEA quota allocation security through backward integration into active pharmaceutical ingredient synthesis or captive alkaloid sourcing partnerships. Deepen controlled-release formulation R&D investments to differentiate duration-of-action claims against immediate-release commoditization. Defend hospital formulary position by embedding patient-controlled analgesia pump protocols and REMS-compliant prescriber certification programs. For New Entrants and Emerging Players: Sub-Saharan African palliative care systems with WHO Access to Controlled Medicines Programme procurement pathways represent the most penetrable entry point for oral solution and immediate-release tablet portfolios. Pediatric liquid formulation development for swallowing-limited populations offers second white-space targeting. Pursue national essential medicines list adoption as the primary go-to-market angle, anchoring tender eligibility before commercial scale. For Investors and Strategic Acquirers: Capital is best deployed toward sterile injectable specialists with established DEA manufacturing authorizations and EMA MDR compliance infrastructure, given decade-long regulatory moat construction timelines. Long-term viability hinges on convergence with multimodal pain management protocols rather than opioid-isolation strategies. Watch FDA REMS program expansion to additional dosage forms as the inflection signal for compliance-cost barriers tightening further.| Strategic Initiative | Industry Significance |
|---|---|
| DEA Quota Security Investment | Captive alkaloid sourcing insulates supply continuity against annual allocation volatility. |
| Controlled-Release Formulation R&D | Dual-mechanism tablet development flattens plasma curves for palliative care differentiation. |
| WHO Procurement Channel Expansion | Essential medicines list alignment unlocks institutional tender access across low-access regions. |
| REMS Compliance Infrastructure | Prescriber certification systems defend formulary access against regulatory exclusion. |
| Pediatric Oral Solution Development | Liquid formulation capabilities address swallowing-limited geriatric and pediatric unmet need. |
Research Methodology
Desk research of FDA REMS program documentation, DEA production quota records, WHO Access to Controlled Medicines Programme assessments, and EMA pharmacovigilance filings preceded structured interviews with hospital formulary directors, palliative care physicians, controlled-substance regulatory affairs leads, and pharmaceutical procurement managers at group purchasing organizations. Secondary validation drew from clinical trial registries, national essential medicines list publications, and import-export trade databases. Bottom-up demand modeling across dosage forms and therapy areas was cross-checked against top-down market sizing from alkaloid processing volumes and finished-dose manufacturing capacity.
Forecast assumptions held FDA REMS prescriber certification mandates, DEA quota allocation methodologies, and WHO treaty compliance frameworks constant across the projection horizon, while varying palliative care program expansion rates and multimodal analgesia protocol diffusion. Segmentation modeling spanned product type, therapy area, end user, and delivery mode dimensions, with regional regulatory cluster differentiation for controlled-substance scheduling. CAGRs were derived from historical volume trends adjusted for demographic aging trajectories and hospital infrastructure buildout patterns in priority markets.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement rates, opioid litigation settlement fund allocations, or national palliative care budget commitments would shift the trajectory. Material shifts in DEA quota policy, FDA REMS expansion scope, or WHO treaty renegotiation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Heat Therapy Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Asia-Pacific Tattoo Numbing Cream Market
Pain Management
OTC Painkiller Market
Pain Management
Neuralgia Treatment Market
Pain Management
Topical Pain Relief Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Cancer Pain Management Market
Pain Management
Spine Pain Market
Pain Management
Global Chiropractic Care Market
Pain Management
Opioid Withdrawal Management Market
Pain Management
Painkillers Market
Pain Management
Ketorolac Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Axial Spondyloarthritis Management Market