
 Opioid Withdrawal Management Market | 2026-2036
Opioid Withdrawal Management Market Size, Share, and Industry Trends Forecast 2026-2036
Opioid Withdrawal Management Market Analytics
The FDA's Risk Evaluation and Mitigation Strategy for buprenorphine-containing products is shifting how manufacturers structure distribution and prescriber education programs. Indivior dominates the branded buprenorphine-naloxone segment through sustained investment in depot formulations and prescriber training networks. Alkermes competes with its extended-release naltrexone platform, leveraging monthly dosing intervals to differentiate from daily agonist therapies. Orexo specializes in sublingual film technologies that optimize bioavailability and patient adherence profiles.
Opioid withdrawal management encompasses pharmacological interventions that mitigate acute and protracted withdrawal symptoms through receptor-targeted agonist, partial agonist, or antagonist mechanisms, typically formulated as sublingual tablets, long-acting injectables, or transdermal patches with defined dissolution rates and plasma half-lives. The primary purpose is to stabilize neurochemical dysregulation and enable continuity in behavioral rehabilitation programs. Buprenorphine formulations anchor the product type landscape due to their ceiling effect on respiratory depression and established office-based prescribing pathways. Medication-Assisted Treatment leads the therapy type dimension as the dominant reimbursed care model, while transdermal delivery modes represent the fastest-growing segment driven by patient compliance advantages and reduced diversion risk.
The Drug Enforcement Administration's production quota system for Schedule III controlled substances directly constrains manufacturing volumes and shapes national availability patterns. State Medicaid programs and the Substance Abuse and Mental Health Services Administration funding mechanisms determine reimbursement thresholds and site-of-care expansion rates. The FDA's evolving standards for abuse-deterrent formulations and the Centers for Medicare & Medicaid Services' bundled payment pilots for opioid use disorder treatment are restructuring provider economics. Stakeholders must monitor how the interplay between DEA scheduling reviews, state-level prescribing limits, and Medicaid expansion decisions will reshape competitive access and formulary positioning across care settings.
Market Dynamics
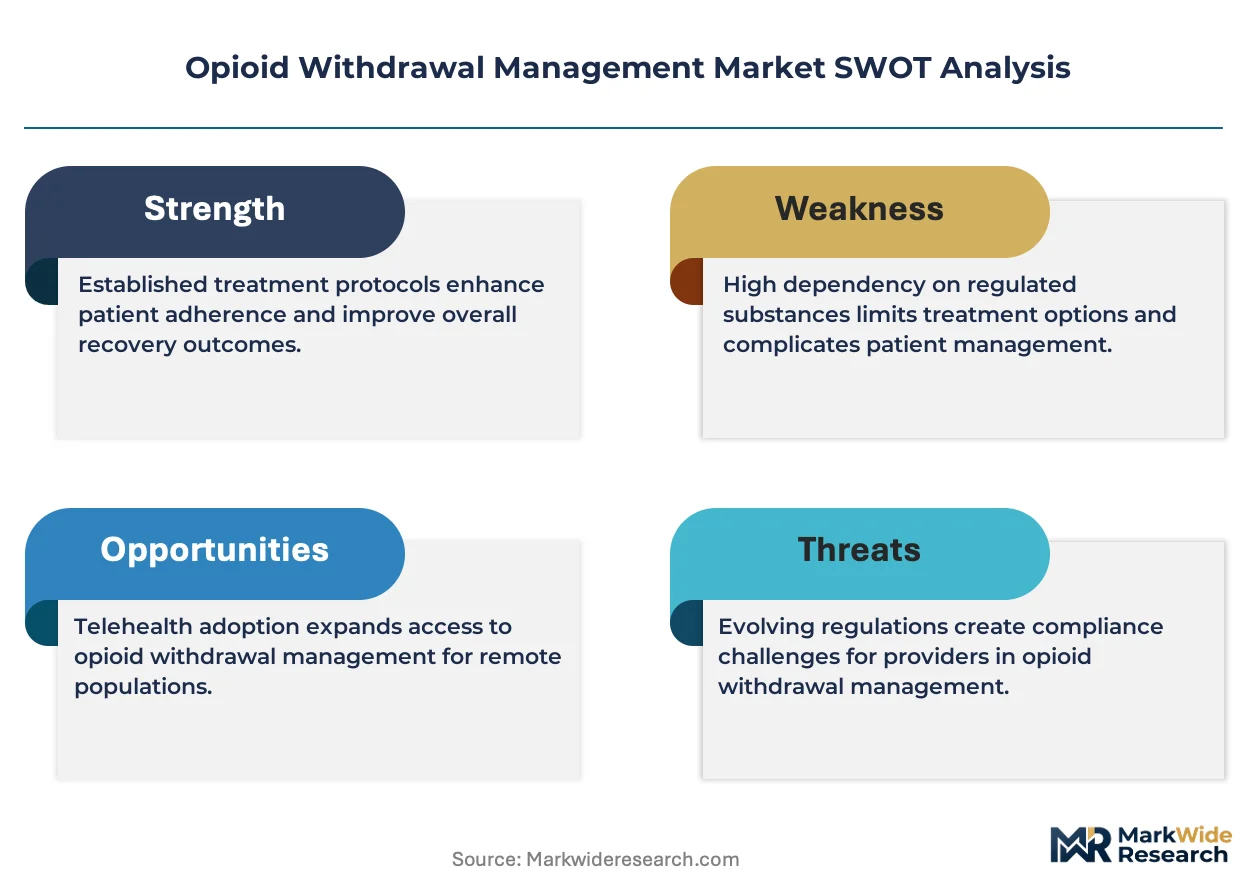
The FDA's Risk Evaluation and Mitigation Strategy for buprenorphine products is compressing prescriber certification timelines while expanding office-based treatment capacity, fundamentally restructuring how withdrawal management services reach patients.
Growth Catalysts
- Medicaid Expansion:State-level Medicaid expansion under the Affordable Care Act has amplified reimbursement coverage for Medication-Assisted Treatment programs, particularly in states that adopted enhanced federal matching rates.
- DEA Scheduling Flexibility:The Drug Enforcement Administration's 2023 rule change permitting telehealth prescribing of buprenorphine without in-person evaluation requirements has accelerated rural and underserved area access.
- Long-Acting Injectable Formulations:Extended-release depot technologies reduce dosing frequency from daily to monthly intervals, improving adherence metrics and reducing diversion risks in criminal justice and housing-first program settings.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for buprenorphine base material concentrates in Indian and Chinese chemical synthesis facilities, creating geopolitical and quality-control vulnerability.
- DEA Production Quotas:The Drug Enforcement Administration's annual aggregate production limits for Schedule III substances cap national buprenorphine tablet and film volumes, constraining manufacturer response to demand surges.
- Prior Authorization Friction:Commercial insurance plans impose multi-step prior authorization protocols for branded formulations, delaying treatment initiation and elevating pharmacy abandonment rates.
Strategic Opportunities
- Correctional Health Systems:State prison systems and county jails represent underpenetrated channels where extended-release naltrexone protocols can bridge the overdose risk period post-release.
- Harm Reduction Integration:Syringe service programs and overdose prevention centers in urban corridors offer novel distribution touchpoints for buprenorphine initiation kits and naloxone co-prescribing.
- SAMHSA State Targeted Response:Substance Abuse and Mental Health Services Administration block grants to states create funding pools for expanding hub-and-spoke model infrastructure linking specialty addiction centers with primary care.
Industry Challenges
- Waivered Prescriber Shortage:The DATA 2000 waiver requirement limits the pool of authorized buprenorphine prescribers, creating access bottlenecks in federally qualified health centers and rural clinics.
- Diversion Monitoring Complexity:State prescription drug monitoring program interoperability gaps complicate real-time tracking of patient pharmacy shopping and prescriber overlap patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opioid Withdrawal Management Market |
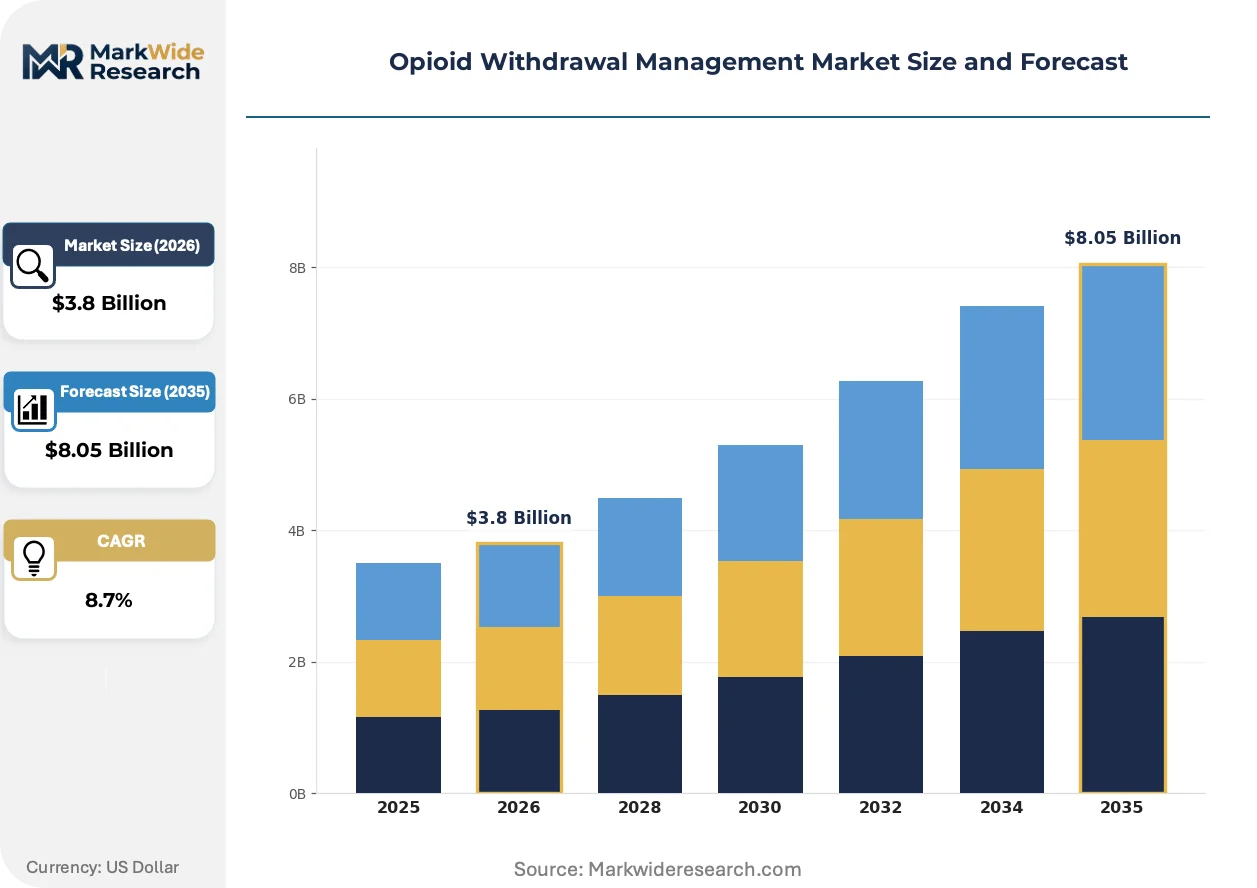
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buprenorphine, Methadone, Naltrexone, Clonidine Therapy Type: Medication-Assisted Treatment, Detoxification, Counseling, Behavioral Therapy End User: Rehabilitation Centers, Hospitals, Outpatient Clinics, Pharmacies Delivery Mode: Oral, Injectable, Transdermal, Inhalation |
| Companies Covered | Indivior, Alkermes, Orexo, Teva Pharmaceutical Industries, Mylan, Sun Pharmaceutical Industries, BioDelivery Sciences International, Mallinckrodt Pharmaceuticals, Hikma Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opioid Withdrawal Management Market Evolving Landscape
Formulation science and regulatory flexibility are converging to reshape how opioid withdrawal management reaches patients outside traditional clinical settings.
Extended-release injectable formulations are unifying pharmacokinetic stability with programmatic adherence requirements. Correctional facilities and housing-first programs have adopted monthly depot injections to eliminate daily dosing logistics. This convergence is compressing the gap between controlled clinical environments and community-based recovery support.
REACH compliance pressures in European pharmaceutical manufacturing are elevating environmental standards for opioid API synthesis and packaging waste streams. EMA guidelines on sustainable manufacturing practices now influence supplier qualification criteria for contract manufacturers serving the withdrawal management market. German and French regulatory authorities have accelerated inspections of Indian API facilities supplying buprenorphine precursors.
Patient preference for discreet medication administration is shifting demand toward sublingual film strips over tablets in retail pharmacy channels. Younger demographics in urban treatment programs increasingly select film formulations that dissolve rapidly without water or chewing. This pattern concentrates in Medicaid-managed care populations where pharmacy benefit design influences product selection at the point of dispensing.
Opioid Withdrawal Management Market Segmentation
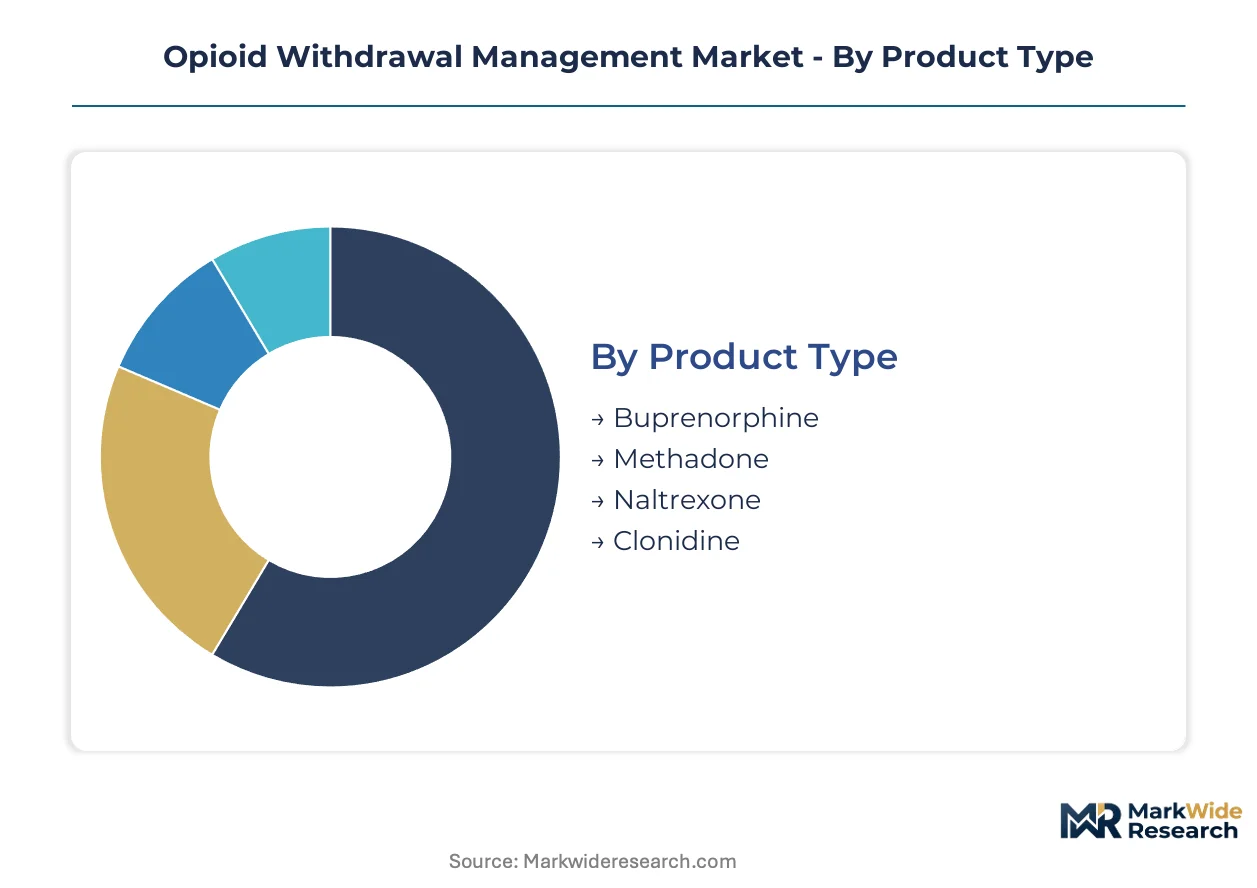
Opioid withdrawal management markets fragment across pharmacological mechanisms, care delivery settings, and administration technologies. Each segmentation axis carries distinct regulatory, reimbursement, and patient adherence implications that reshape competitive positioning.
Product Type:
Standardization dominates at the API level, while formulation differentiation creates tiered value capture across delivery technologies and patent protections.
- Buprenorphine:Partial mu-opioid agonist with ceiling effect on respiratory depression, formulated as sublingual tablets, films, and long-acting depot injections. Demand concentrates in United States outpatient clinics where DEA waiver requirements and Medicaid reimbursement favor office-based prescribing pathways over specialized addiction centers.
- Methadone:Full opioid agonist restricted to federally regulated Opioid Treatment Programs with daily supervised dosing requirements. Patient volume clusters in urban corridors with established clinic infrastructure, constrained by SAMHSA certification burdens and NIMBY opposition to new facility siting.
- Naltrexone:Competitive opioid antagonist available in oral daily and extended-release monthly injectable formats. Prescribing concentrates in criminal justice diversion programs and employer-based recovery initiatives seeking abstinence-verified outcomes.
- Clonidine:Alpha-2 adrenergic agonist managing autonomic withdrawal symptoms without opioid receptor activity. Demand flows from inpatient detoxification protocols seeking non-controlled alternatives amid DEA quota pressures on scheduled medications.
Most installed capacity flows through buprenorphine formulations. Expansion is steepest in long-acting injectable presentations.
Therapy Type:
Reimbursement architecture separates acute episodic care from chronic disease management models with diverging margin profiles.
- Medication-Assisted Treatment:Integrated pharmacotherapy with behavioral counseling delivered through federally qualified health centers and hub-and-spoke networks. Federal block grant funding and state Medicaid expansion decisions determine site-of-care expansion rates.
- Detoxification:Medically supervised withdrawal management in residential or acute care settings with 3-7 day average length of stay. Commercial insurance prior authorization requirements and out-of-network billing restrictions constrain volume growth.
- Counseling:Psychosocial interventions including individual, group, and family modalities delivered by licensed addiction counselors. Licensure portability barriers and workforce shortages limit capacity scaling in rural service areas.
- Behavioral Therapy:Evidence-based modalities including cognitive behavioral therapy and contingency management. Implementation concentrates in Veterans Health Administration systems and large employer health plans with dedicated behavioral health carve-outs.
Most reimbursed encounters flow through Medication-Assisted Treatment. Behavioral Therapy is gaining share fastest among commercial payers.
End User:
Site-of-care economics fragment across institutional cost structures, regulatory oversight intensity, and patient acuity thresholds.
- Rehabilitation Centers:Residential facilities combining pharmacological management with structured therapeutic programming. Length-of-stay compression from managed care utilization review and state licensure requirements reshape operational models.
- Hospitals:Acute care settings managing complicated withdrawal with comorbid medical or psychiatric conditions. Emergency department buprenorphine initiation protocols and observation unit pathways expand capacity without full inpatient admission.
- Outpatient Clinics:Federally qualified health centers and primary care practices with DEA-waivered prescribers. Telehealth flexibilities from DEA rule changes accelerate rural access expansion.
- Pharmacies:Retail dispensing channels with pharmacist-administered depot injection services and medication therapy management. State scope-of-practice expansions enable pharmacist prescribing in select jurisdictions.
Most patient encounters originate in Outpatient Clinics. Pharmacy-based services are expanding most quickly among Medicaid managed care populations.
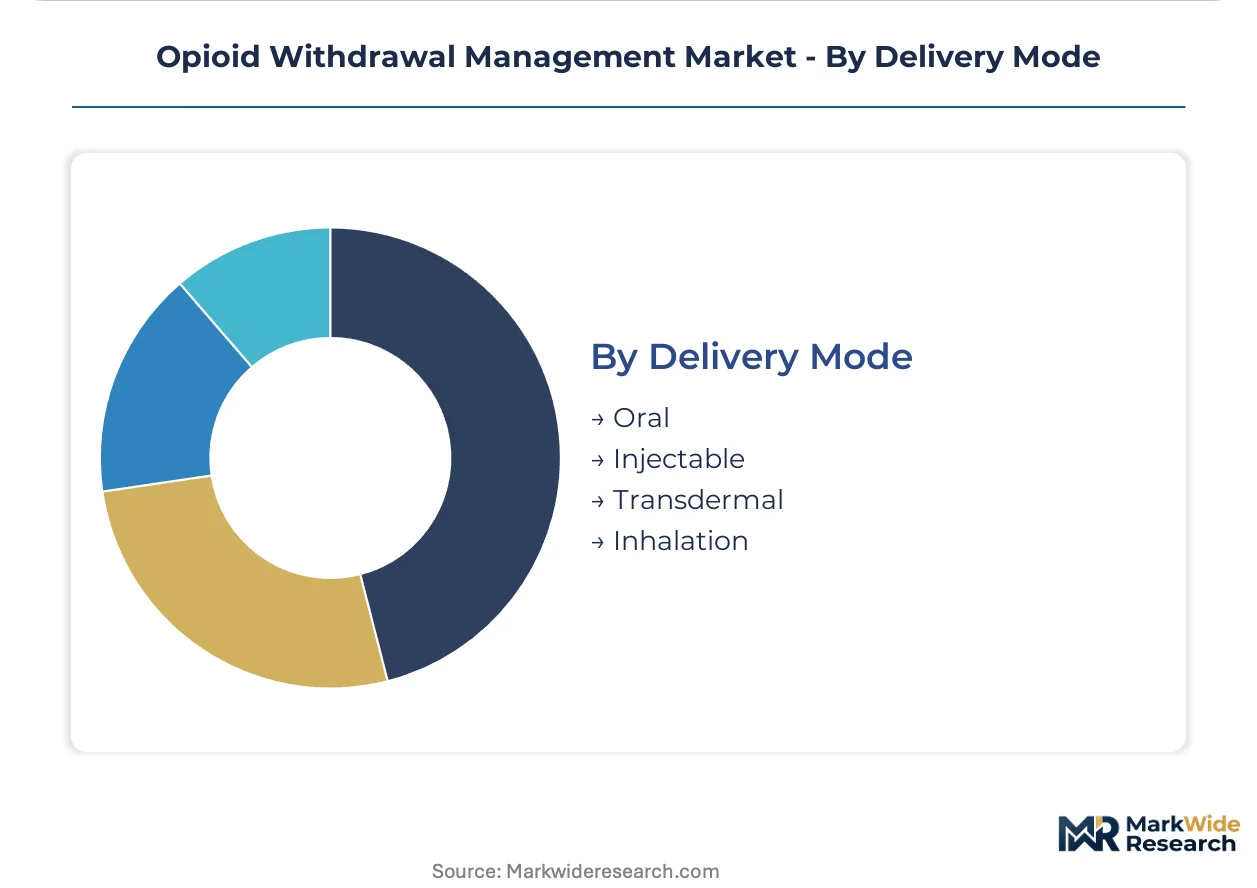
Delivery Mode:
Patient adherence requirements and diversion risk profiles drive technology selection across criminal justice, housing, and community-based settings.
- Oral:Sublingual tablets and films with rapid dissolution and established bioavailability profiles. Patient preference for discreet administration drives film adoption over tablets in urban treatment programs.
- Injectable:Extended-release depot formulations with monthly dosing intervals. Correctional facilities and reentry programs adopt monthly naltrexone and buprenorphine injections to eliminate daily dosing logistics.
- Transdermal:Patch technologies offering continuous drug delivery with reduced peak-trough variability. Manufacturing complexity and skin irritation rates limit current adoption.
- Inhalation:Nasal spray presentations for rapid onset symptom management. Development concentrates on naloxone co-formulations for overdose reversal rather than maintenance therapy.
Most dispensed units flow through Oral formulations. Injectable presentations are climbing the fastest among institutional purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered office-based buprenorphine prescribing through the DATA 2000 legislation, establishing the regulatory template that other jurisdictions now adapt. Federal and state funding mechanisms have since concentrated treatment infrastructure domestically while export-oriented manufacturers serve secondary markets.
United States
Medicaid expansion and SAMHSA block grants drive demand concentration across federally qualified health centers. The DEA's 2023 telehealth flexibility for buprenorphine prescribing without in-person evaluation requirements accelerates rural access expansion. Treatment capacity clusters in California, New York, and Florida, where state-level opioid response funding amplifies hub-and-spoke model infrastructure.
Germany
Substitution therapy demand flows through statutory health insurance reimbursement pathways with established office-based prescribing networks. The country's national pharmaceutical regulator enforces REACH compliance pressures on API sourcing from Indian synthesis facilities. Manufacturing and distribution activity concentrates in North Rhine-Westphalia and Bavaria, where contract manufacturers serve European formulation requirements.
United Kingdom
National Health Service commissioning frameworks prioritize Medication-Assisted Treatment integration with community-based recovery services. NHS England's specialized commissioning for opioid dependence treatment shapes prescriber training and formulary access protocols. Service delivery concentrates in Greater London and the West Midlands, where integrated care systems coordinate addiction treatment with primary care networks.
Canada
Provincial health authority procurement drives demand for extended-release formulations in correctional and housing-first program settings. Health Canada's regulatory standards for abuse-deterrent formulations influence manufacturer submission strategies and labeling requirements. Clinical trial and distribution activity clusters in Ontario and British Columbia, where provincial overdose response strategies expand depot injection access.
France
High-dose buprenorphine substitution protocols anchor the national response to opioid dependence within universal health coverage frameworks. ANSM oversight of controlled substance distribution shapes pharmacy-based dispensing and patient monitoring requirements. Treatment infrastructure concentrates in Île-de-France and Auvergne-Rhône-Alpes, where specialized addiction centers coordinate with general practitioner networks.
Opioid Withdrawal Management Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and delivery technology segments. The market structure consolidates around three to five dominant players with established prescriber networks and regulatory dossiers, while mid-tier manufacturers compete on price in generic tablet and film categories. Two strategic archetypes prevail: vertically integrated API-to-formulation operators controlling supply chain security, and specialized delivery technology developers licensing platform innovations. Competitive dynamics center on depot formulation patent estates and prescriber certification program scale.
Within the branded formulation tier, Indivior and Alkermes occupy positions defined by extended-release platform investments and institutional channel penetration. Orexo exemplifies the specialized delivery technology archetype through sublingual film innovation. Teva Pharmaceutical Industries and Mylan represent the generic manufacturing tier, competing on volume supply and international distribution reach. Sun Pharmaceutical Industries anchors the emerging market supply position with API and formulation integration.
| Leading Market Players |
|---|
| Indivior |
| Alkermes |
| Orexo |
| Teva Pharmaceutical Industries |
| Mylan |
| Sun Pharmaceutical Industries |
| BioDelivery Sciences International |
| Mallinckrodt Pharmaceuticals |
| Hikma Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Buprenorphine API synthesis costs cascade through formulation tiers, with Indian and Chinese chemical manufacturing feeding branded depot injections at premium price points while generic sublingual tablets compete on volume in Medicaid channels. DEA production quotas constrain upstream supply flexibility, amplifying price volatility when demand surges exceed annual aggregate limits.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates extended-release depot formulations from branded sublingual films and generic tablets. Price differentiation hinges on patent-protected delivery technology and DEA waiver prescriber network density. Cost compression in the generic tier intensifies because Teva and Mylan compete on API sourcing scale and international distribution reach. Medicaid-managed care populations exhibit highest price sensitivity, while correctional health systems and employer-based recovery programs accept premium pricing for monthly adherence verification.
Supply Chain Analysis
Domestic-content mandates in pharmaceutical manufacturing reshape sourcing toward qualified contract manufacturers in North Rhine-Westphalia and Bavaria for European formulation requirements. API production concentrates in India and China, with buprenorphine base material synthesis feeding formulation facilities in the United States and Germany. Raw material dependencies span naltrexone hydrochloride, buprenorphine free base, and specialized polymer matrices for depot encapsulation. Single-source vulnerability in Indian API facilities elevates regulatory inspection risk. Distribution runs through DEA-registered wholesale distributors to retail pharmacies, outpatient clinics, and correctional health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in long-acting injectable formulations where patent estates protect pricing power and prescriber certification programs create switching costs. Depot technology investments and hub-and-spoke infrastructure scale drive premium-tier volume capture.
For Market Incumbents: Anticipate generic erosion in sublingual tablet categories by accelerating depot formulation lifecycle management and expanding prescriber training network density. Defensive consolidation moves include backward integration into API sourcing through qualified Indian contract manufacturers and certification investment in abuse-deterrent formulation standards. The DATA 2000 waiver requirement creates prescriber access bottlenecks that channel control can mitigate. For New Entrants and Emerging Players: Telehealth prescribing platforms offer the most penetrable route for buprenorphine initiation services, particularly in rural and underserved areas where DEA rule changes eliminated in-person evaluation requirements. White-space targets include syringe service program partnerships for harm reduction integration and pharmacy-based depot injection services enabled by state scope-of-practice expansions. A direct-to-clinic go-to-market angle bypasses prior authorization friction in commercial insurance channels. For Investors and Strategic Acquirers: Consolidation pressure builds where prescriber certification scale and depot formulation patent estates overlap, favoring acquisition of specialized delivery technology developers over pure-play generic manufacturers. Long-term viability across the analysis window rests on regulatory dossier depth and institutional channel penetration. The signal to watch as inflection indicator is DEA scheduling review outcomes and state Medicaid expansion decisions reshaping addressable patient populations.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Extended-release naltrexone protocols in correctional reentry programs validate monthly dosing adherence models. |
| Regulatory Approval Pathway | FDA abuse-deterrent formulation standards reshape submission strategies for sublingual film innovators. |
| Manufacturing Scale-Up | DEA production quota negotiations determine national buprenorphine tablet and film availability ceilings. |
| Pipeline Diversification | Transdermal patch technologies address patient preference for discreet administration outside clinical settings. |
| Strategic Partnership | SAMHSA block grant alignment with state hub-and-spoke infrastructure expands federally qualified health center capacity. |
Research Methodology
Direct dialogue with formulary directors, DEA-registered prescriber network managers, correctional health pharmacy directors, and Medicaid managed care contracting officers grounded qualitative insights. Secondary validation drew from FDA Orange Book listings, SAMHSA Treatment Episode Data Set, DEA controlled substance production quota records, and state prescription drug monitoring program interoperability reports. Bottom-up patient volume modeling and top-down reimbursement expenditure analysis triangulated market sizing across the projection horizon.
Segmented outputs across product type, therapy modality, end-user setting, and delivery technology dimensions fed into analytical framework construction. CAGRs derived from historical Medicaid expenditure trajectories, Medicare Part D claims patterns, and commercial payer pharmacy benefit design evolution. Forecast inputs incorporated DEA scheduling review timelines, state-level opioid response funding allocations, and extended-release formulation patent expiration sequences.
The model assumes a particular technology adoption path; alternative pathways for transdermal delivery systems or implantable depot technologies would alter the outlook. Forecasts reflect assumptions around telehealth prescribing flexibilities, SAMHSA funding continuity, and DEA quota expansion responsiveness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Cluster Headache Market
Pain Management
Cold Pain Therapy Market
Pain Management
Painkillers Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Dyspareunia Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Postoperative Pain Market
Pain Management
Palliative Care Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Medical Morphine Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Cancer Pain Market
Pain Management
Pain Therapeutic Injectables Market
Pain Management
Pain Relief Oil Market